
 Global Air Charter Services Market | 2026-2036
Global Air Charter Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Air Charter Services Market Analysis
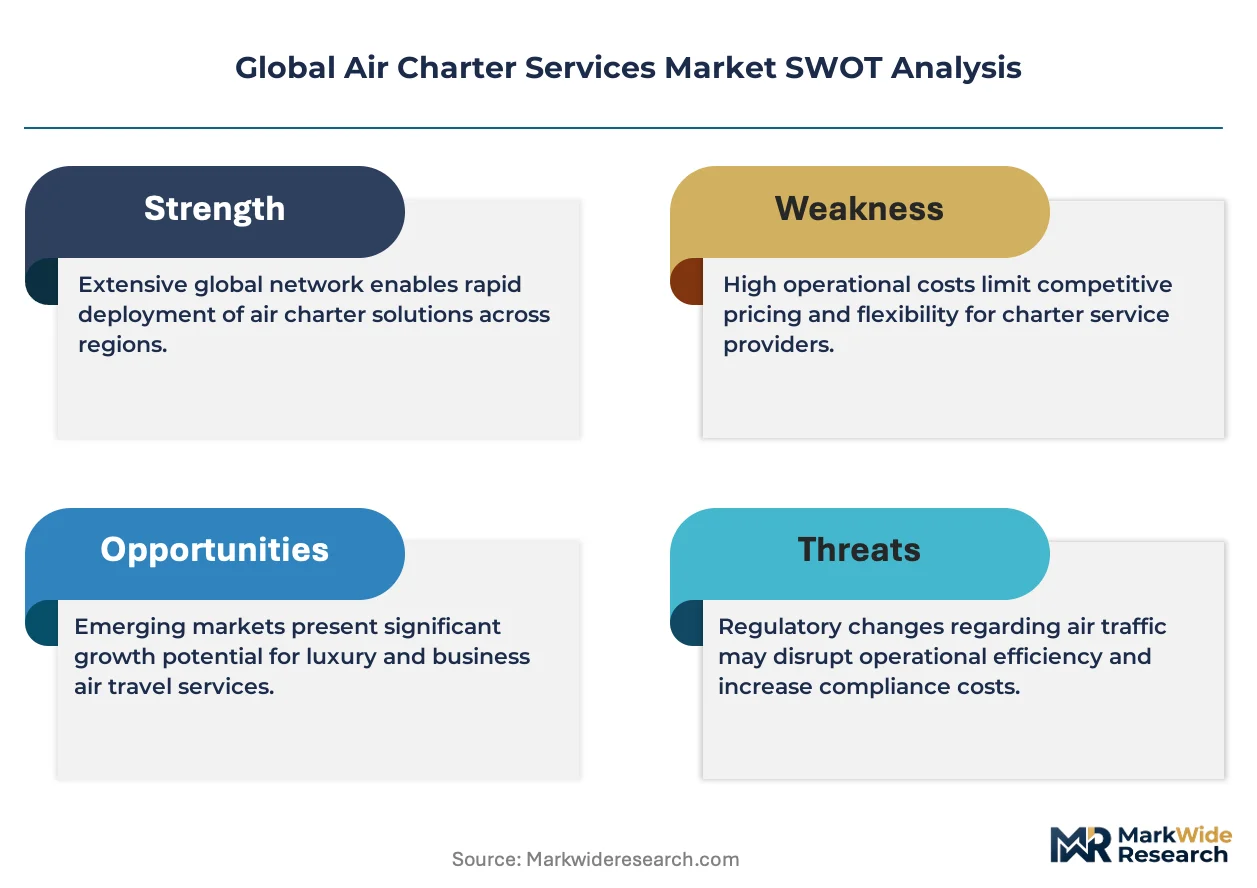
The EU Green Deal is broadening the addressable market for sustainable aviation fuel commitments across European charter operators. NetJets Aviation Inc. leverages its fractional ownership scale to secure long-term SAF offtake agreements. VistaJet Group Holding Ltd. differentiates through global floating fleet coverage and carbon offset integration. Flexjet LLC anchors its competitive position with disciplined aircraft-type specialization in light and mid-cabin segments.
Air charter services denote on-demand aircraft rental without fixed schedule obligations, encompassing crewed flight operations across jet, turboprop, and rotary-wing platforms with payload capacities ranging from under 1,000 kg for light jets to exceeding 10,000 kg for heavy cargo configurations. These services serve time-critical logistics, executive mobility, medical transport, and humanitarian relief missions where scheduled airline networks prove inadequate or unavailable. Private jet charter retains the dominant revenue share among service types, though cargo charter exhibits the fastest expansion trajectory driven by e-commerce fulfillment velocity requirements and pharmaceutical cold-chain integrity demands. Aircraft type segmentation reveals heavy jets commanding premium yield pools on transoceanic routes, while light jets capture frequency advantages in regional point-to-point markets.
FAA Part 135 operating certificate standards govern US charter safety and maintenance protocols, while EASA Air Operator Certificate requirements shape European market access conditions, and ICAO carbon offsetting mechanisms progressively influence fleet renewal decisions. Regulatory compliance costs are diverting smaller operators toward management company affiliations or consolidation pathways. Stakeholders must monitor SAF certification scheme interoperability between jurisdictions as a determinant of future route economics and fleet investment viability.
Market Dynamics
Fractional ownership platforms are compressing traditional charter demand elasticity by converting high-frequency business travelers into asset-sharing participants rather than spot-market buyers.
Growth Catalysts
- Emerging market infrastructure investment:The United Arab Emirates is deploying super-connector airport capacity at Dubai and Abu Dhabi, drawing intercontinental traffic away from traditional European hubs. This geographic pivot concentrates high-yield charter demand in new corridor configurations.
- EU Green Deal SAF mandates:Binding sustainable aviation fuel quotas for European operators are creating certified supply scarcity that rewards early offtake committers with route access privileges. Regulatory compliance is becoming a competitive moat rather than a cost burden.
- Pharmaceutical cold-chain integrity requirements:Temperature-controlled cargo charter is displacing scheduled belly-hold capacity for biologics and vaccine distribution. Manufacturers now specify charter-only protocols for high-value temperature-sensitive payloads.
Market Restraints
- Jet fuel price volatility:Crude derivative exposure remains unhedged for mid-tier operators, compressing margin buffers during supply shocks. Fuel surcharges recover only partial cost escalations.
- Pilot certification scarcity:FAA Part 135 and EASA Air Operator Certificate training pipelines cannot match fleet expansion velocity. Experienced crew availability concentrates at legacy flag carriers.
- Airport slot congestion:Primary business aviation terminals at Teterboro, Farnborough, and Le Bourget face physical capacity ceilings. Ground handling delays erode the time-value proposition that justifies charter premiums.
Strategic Opportunities
- India's underserved corporate aviation base:Mumbai and Bangalore host Fortune 500 regional headquarters with minimal fractional penetration. Local operators can anchor greenfield programs before international platforms establish presence.
- Electrification-ready airfield infrastructure:Battery-electric and hydrogen-electric propulsion certification is converging with ground support equipment upgrades. Early airport adopters in Norway and Sweden are securing first-mover route rights.
- Blockchain-verified carbon credit integration:Smart-contract offset retirement is displacing manual registry reconciliation. Corporate travel departments now mandate real-time emission attribution for ESG disclosure compliance.
Industry Challenges
- Aircraft type rating fragmentation:Light jet, mid-cabin, and heavy jet specializations require distinct crew certifications that cannot cross-qualify. Fleet heterogeneity inflates training budgets and scheduling rigidity.
- SAF certification scheme interoperability gaps:ASTM D7566, CAAC, and DEF STAN 91-91 fuel standards lack mutual recognition. Transcontinental operators face bunkering constraints at non-aligned jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Air Charter Services Market |
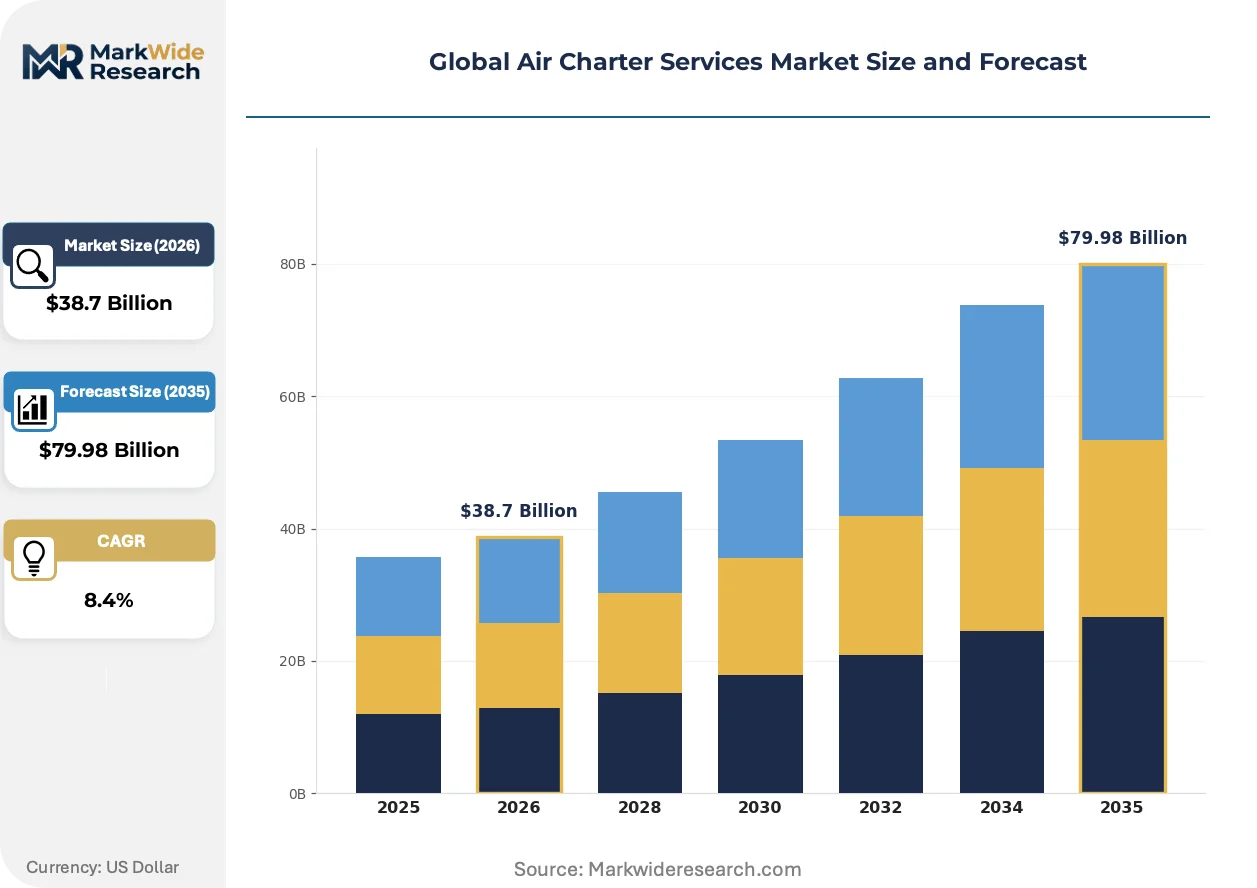
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Private Jet, Cargo, Helicopter, Medical Evacuation End User: Corporates, Government Agencies, Non-Profit Organizations, Individuals Aircraft Type: Light Jets, Medium Jets, Heavy Jets, Turboprops Booking Channel: Direct, Online Platforms, Travel Agents, Brokers |
| Companies Covered | NetJets Aviation Inc., VistaJet Group Holding Ltd., Flexjet LLC, Air Charter Service Group Ltd., Jet Aviation AG, Wheels Up Partners LLC, Gama Aviation, Chapman Freeborn Airchartering, Luxaviation S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Air Charter Services Market Emerging Trajectories
Digital booking platforms are compressing charter procurement cycles from days to hours, while propulsion electrification and carbon accounting automation reshape fleet investment criteria.
Integrated flight management software is unifying dispatch, crew scheduling, and passenger experience modules into single-stack platforms. Regional operators in the United States are adopting these systems fastest, driven by FAA Part 135 audit automation requirements. This technology compression is enabling sub-fleet operators to match network carriers on on-time performance metrics without dedicated operations centers.
The EU Green Deal's ReFuelEU Aviation regulation is mandating progressive SAF blending quotas for flights departing European airports. European charter operators now face fuel procurement constraints that favor long-term offtake contracting over spot market purchasing. Heavy jet segments serving transoceanic routes are most affected, as SAF availability concentrates at hub airports with storage infrastructure.
Corporate travel departments are unbundling charter procurement from traditional travel management company relationships. Direct platform relationships with fractional providers and independent charter brokers are displacing intermediary markup structures. This channel shift is most visible in the United States, where technology sector procurement teams specify API-integrated booking tools for real-time availability and transparent dynamic pricing.
Global Air Charter Services Market Segmentation
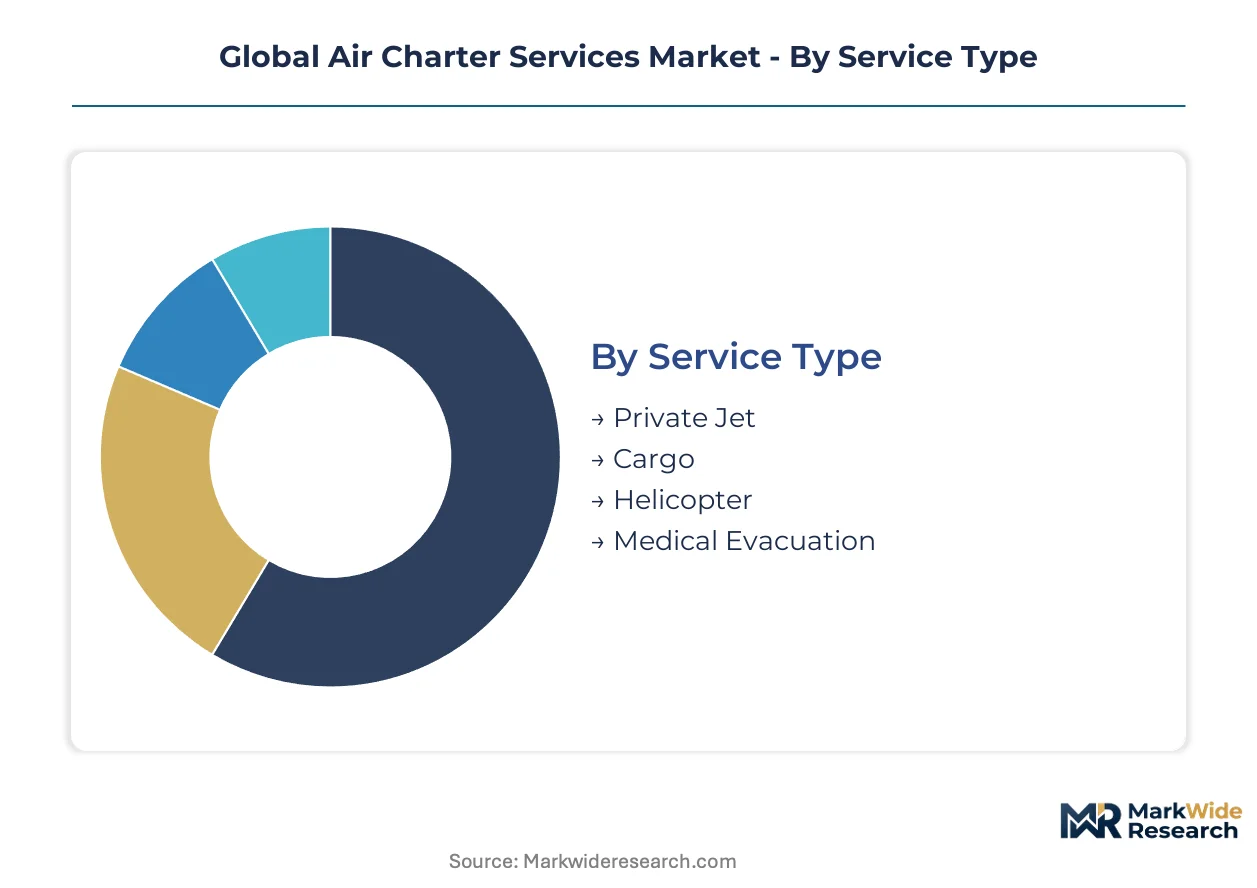
Segmentation in air charter services reveals divergent margin structures and operational requirements across service modalities. Each category maps distinct asset deployment patterns to specific customer value propositions and regulatory compliance burdens.
Service Type:
Volume concentration favors scheduled-adjacent operations while premium yield pools concentrate in bespoke mobility solutions.
- Private Jet:Crewed on-demand aircraft rental for executive mobility without fixed schedule obligations. Demand concentrates in the United Arab Emirates as Dubai and Abu Dhabi super-connector infrastructure draws intercontinental traffic. FAA Part 135 and EASA Air Operator Certificate standards govern safety protocols.
- Cargo:Temperature-controlled and time-critical freight transport across jet, turboprop, and dedicated freighter platforms. Pharmaceutical cold-chain integrity requirements are displacing scheduled belly-hold capacity for biologics distribution. This segment is gaining share fastest among service types.
- Helicopter:Rotary-wing platforms for point-to-point urban mobility and offshore energy logistics. Offshore oil and gas operations in the North Sea and Gulf of Mexico anchor fleet utilization.
- Medical Evacuation:Specialized aircraft configurations with intensive care equipment and medical crew. Remote mining operations and disaster response missions in Australia and Canada drive contract structures.
Mature deployment sits with Private Jet. Newer deployment is concentrated in Cargo.
End User:
Procurement authority determines contract duration, insurance requirements, and aircraft specification complexity.
- Corporates:Fortune 500 travel departments and mid-cap enterprises with recurring mobility needs. Technology sector procurement teams in the United States now mandate API-integrated booking tools for real-time availability.
- Government Agencies:Defense, diplomatic, and emergency response operations with sovereign immunity considerations. Multi-year framework agreements predominate.
- Non-Profit Organizations:Humanitarian relief and medical mission operators with donor-funded budgets. UN and Red Cross certification requirements shape vendor selection.
- Individuals:Ultra-high-net-worth families and celebrity talent with privacy and schedule flexibility priorities. Discretionary spend correlates with asset market performance.
Contract standardization is highest with Government Agencies. Pricing volatility is most acute with Individuals.
Aircraft Type:
Payload-range capability stratifies crew certification requirements and airport access privileges.
- Light Jets:Aircraft with maximum takeoff weight under 10,000 kg serving regional point-to-point markets. Fractional ownership platforms in the United States compress spot-market demand elasticity through asset-sharing participation.
- Medium Jets:Transcontinental range with stand-up cabin configurations for 6-9 passengers. European charter operators face ReFuelEU Aviation SAF blending quotas that favor long-term offtake contracting.
- Heavy Jets:Intercontinental range exceeding 5,000 nautical miles with lie-flat sleeping configurations. Premium yield pools on transoceanic routes concentrate at hub airports with SAF storage infrastructure.
- Turboprops:Short-field performance for unimproved airstrips and regional connectivity. Mining and energy sector contracts in remote geographies anchor utilization.
Fleet renewal investment is concentrating in Medium Jets. Operational complexity is highest with Heavy Jets.
Booking Channel:
Channel selection determines price transparency, cancellation flexibility, and liability allocation.
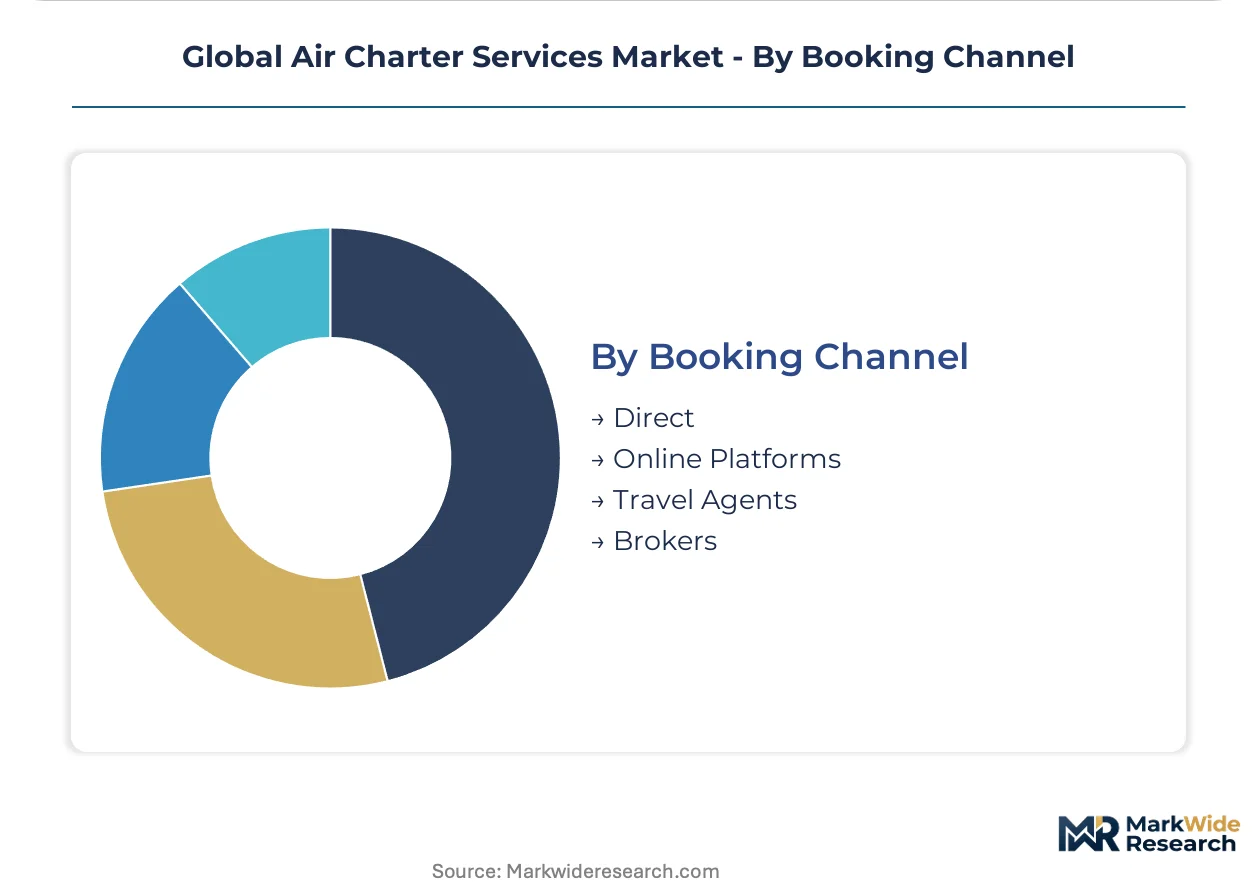
- Direct:Relationships with fractional providers or fleet operators eliminating intermediary markup. Corporate travel departments are unbundling charter procurement from traditional travel management company relationships.
- Online Platforms:Digital booking interfaces compressing procurement cycles from days to hours. Real-time availability and dynamic pricing transparency attract technology sector procurement teams.
- Travel Agents:Full-service intermediaries with duty of care and risk management integration. Legacy corporate travel policies still mandate this channel for compliance documentation.
- Brokers:Independent market access without fleet ownership, aggregating supply across operator networks. API-integrated tools are displacing manual broker relationships in the United States.
Margin compression is most severe with Online Platforms. Relationship durability is strongest with Direct.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Abu Dhabi anchor global air charter services demand through super-connector airport infrastructure that draws intercontinental traffic away from traditional European hubs. The United Arab Emirates concentrates high-yield charter demand in new corridor configurations spanning Asia, Africa, and Europe.
United States
Technology sector procurement teams mandate API-integrated booking tools for real-time availability and transparent dynamic pricing. FAA Part 135 operating certificate standards govern safety and maintenance protocols for crewed flight operations. Teterboro Airport faces physical capacity ceilings where ground handling delays erode the time-value proposition justifying charter premiums.
United Arab Emirates
Super-connector infrastructure at Dubai International and Abu Dhabi Zayed International concentrates intercontinental traffic flows across emerging market corridors. MOHAP aviation regulations align with international safety standards while facilitating rapid fleet registration. Dubai South's business aviation district hosts maintenance facilities serving heavy jet segments on transoceanic routes.
Germany
ReFuelEU Aviation mandates progressive SAF blending quotas for flights departing European airports, creating certified supply scarcity. EASA Air Operator Certificate requirements shape market access conditions for charter operators serving corporate travel departments. Frankfurt and Munich anchor Central European connectivity with dedicated business aviation terminals.
United Kingdom
Farnborough Airport confronts slot congestion that limits frequency expansion for light and mid-cabin segments serving regional point-to-point markets. CAA oversight maintains alignment with EASA standards post-Brexit while preserving UK-registered fleet competitiveness. London's helicopter shuttle networks connect financial districts with satellite business airports.
India
Mumbai and Bangalore host Fortune 500 regional headquarters with minimal fractional ownership penetration, creating greenfield program opportunities. DGFT aviation policy frameworks support non-scheduled operator permit issuance for charter services. Maharashtra's industrial corridors generate demand for mining and energy sector contracts requiring turboprop short-field performance.
Global Air Charter Services Market Vendor Landscape
The competitive structure tilts toward fractional ownership platforms with fleet scale advantages. Consolidation pressures concentrate among mid-tier operators facing regulatory compliance cost escalation. Three archetypes dominate: asset-heavy fractional providers with long-term SAF offtake commitments, technology-integrated booking platforms compressing procurement cycles, and specialized cargo operators serving pharmaceutical cold-chain requirements. Dominant competitive moves include management company affiliations for smaller operators and strategic airport slot acquisitions at capacity-constrained terminals.
Within the fractional ownership tier, NetJets Aviation Inc. and Flexjet LLC represent scale-driven archetypes with disciplined aircraft-type specialization. VistaJet Group Holding Ltd. occupies a position exemplifying global floating fleet coverage with integrated carbon offset programs. These three entities anchor the premium service tier where corporate travel departments unbundle procurement from traditional intermediary relationships.
| Leading Market Players |
|---|
| NetJets Aviation Inc. |
| VistaJet Group Holding Ltd. |
| Flexjet LLC |
| Air Charter Service Group Ltd. |
| Jet Aviation AG |
| Wheels Up Partners LLC |
| Gama Aviation |
| Chapman Freeborn Airchartering |
| Luxaviation S.A. |
| Others |
Supply Flow & Price Mechanics
Jet fuel price benchmarks cascade through air charter supply chains into three-tier pricing structures across premium, standard, and economy levels. Crude derivative volatility compresses margin buffers for mid-tier operators while fractional ownership platforms absorb cost escalations through long-term offtake hedging.
Pricing Analysis
Yield-per-flight-hour anchors value-based pricing for heavy jet transoceanic routes where lie-flat configurations command premium multiples. Price differentiation separates FAA Part 135-certified operators from non-certified competitors, with EASA Air Operator Certificate tiers adding further stratification in European corridors. Cost compression in light jet segments is intensifying because fractional ownership platforms convert high-frequency travelers into asset-sharing participants rather than spot-market buyers. Corporate travel departments exhibit lowest price sensitivity due to ESG disclosure mandates, while individual ultra-high-net-worth clients demonstrate acute elasticity during asset market corrections.
Supply Chain Analysis
Freight forwarding costs for aircraft components concentrate supply chain leverage at Dubai South and Teterboro maintenance hubs. OEM parts provisioning draws from the United States, Germany, and the United Arab Emirates, with avionics systems resting on semiconductor inputs from Taiwan and South Korea. Single-source vulnerability sits with SAF certification scheme interoperability gaps between ASTM D7566 and DEF STAN 91-91 standards. Distribution runs through management company affiliations that aggregate smaller operators under consolidated procurement umbrellas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Air Charter Services Market operates as a cost-of-compliance story where ReFuelEU Aviation SAF mandates erect barrier-to-entry moats rewarding early offtake committers with route access privileges.
For Market Incumbents: Deploy long-term SAF offtake contracting to lock in certified supply scarcity before spot market constraints harden. Consolidate management company affiliations to spread FAA Part 135 and EASA Air Operator Certificate compliance costs across pooled fleet scales. Pilot certification scarcity threatens expansion velocity; anchor crew pipelines through cadet partnerships with legacy flag carriers.
For New Entrants and Emerging Players: API-integrated booking platforms offer technology-first wedge into corporate travel procurement unbundling from traditional intermediary relationships. White-space concentration sits with India's Mumbai-Bangalore corridor where Fortune 500 regional headquarters lack fractional penetration. Greenfield fractional programs anchored before international platforms establish presence capture first-mover contract structures.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier operators with management company affiliation potential in the United States and United Arab Emirates. Long-term viability hinges on electrification-ready airfield infrastructure positioning for battery-electric and hydrogen-electric propulsion certification convergence. Monitor SAF certification scheme interoperability negotiations as inflection indicator for transcontinental operator bunkering economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term SAF Offtake Contracting | ReFuelEU Aviation compliance locks route access privileges for early committers at European hub airports. |
| Management Company Affiliation | Pooled FAA Part 135 audit automation spreads compliance cost burdens across sub-fleet operator networks. |
| API-Integrated Booking Platform Deployment | Technology sector procurement mandates compress charter procurement cycles from days to hours. |
| Electrification-Ready Airfield Investment | Norwegian and Swedish airport first-movers secure route rights for battery-electric propulsion certification. |
| Blockchain Carbon Credit Integration | Smart-contract offset retirement satisfies corporate travel ESG disclosure compliance requirements. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with fleet operations directors, charter procurement managers, aviation regulatory affairs leads, and maintenance facility supervisors combined with FAA Part 135 audit databases, EASA Air Operator Certificate registries, ICAO carbon offsetting mechanism disclosures, and SAF certification scheme documentation. Bottom-up fleet utilization modeling and top-down revenue aggregation triangulated market sizing across the analysis window.
Segment-level granularity modeled service type, aircraft category, end-user procurement authority, and booking channel dynamics throughout the forecast period. CAGRs derived from fitted growth curves against historical fleet deployment patterns, with ReFuelEU Aviation mandate phase-in schedules and super-connector airport capacity expansion timelines informing trajectory assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under SAF supply disruption or pilot certification pipeline collapse scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Canada Airport Operations Market
Airport Operations
France Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
UK Airport Operations Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Terminal Operations Market