
 Composite Winglet and Sharklet Structures Market | 2026-2036
Composite Winglet and Sharklet Structures Market Size, Share, and Industry Trends Forecast 2026-2036
Composite Winglet and Sharklet Structures Market Insights
Commercial aviation's end-use vertical mix is shifting toward narrowbody platforms with factory-integrated wingtip devices. GKN Aerospace sustains technology leadership through advanced carbon fiber layup processes for blended winglets. FACC anchors European supply chains with specialized aerostructures manufacturing for Airbus programs. Korean Air Aerospace Division dominates Asia-Pacific aftermarket retrofits through captive airline fleet relationships.
Composite winglet and sharklet structures are aerodynamic appendages molded from carbon fiber-reinforced polymer laminates, typically fabricated through resin transfer molding or autoclave curing to achieve strength-to-weight ratios exceeding aluminum equivalents by forty percent, with primary purpose of reducing induced drag and lowering fuel burn on fixed-wing aircraft. Blended winglets command mature margin pools from retrofit demand on Boeing 737NG and 757 fleets, while sharklet variants represent the fastest-growing product category driven by Airbus A320neo family production rates. Carbon fiber material segments lead value capture due to qualification barriers and OEM specification lock-in, whereas hybrid composites compete on cost for unmanned aerial vehicle applications where weight thresholds are less stringent.
FAA airworthiness standards under Part 25 and EASA CS-25 certification frameworks govern structural integrity and flutter margins for wingtip modifications, with both agencies mandating updated fatigue life assessments for retrofit installations on aging narrowbody frames. The EU Green Deal's ReFuelEU Aviation mandate binds operators to escalating sustainable aviation fuel blending requirements, indirectly accelerating demand for drag-reducing devices that offset higher SAF costs. Stakeholders must monitor evolving OEM specification changes for next-generation narrowbody platforms and position qualification investments ahead of type certificate amendment cycles.
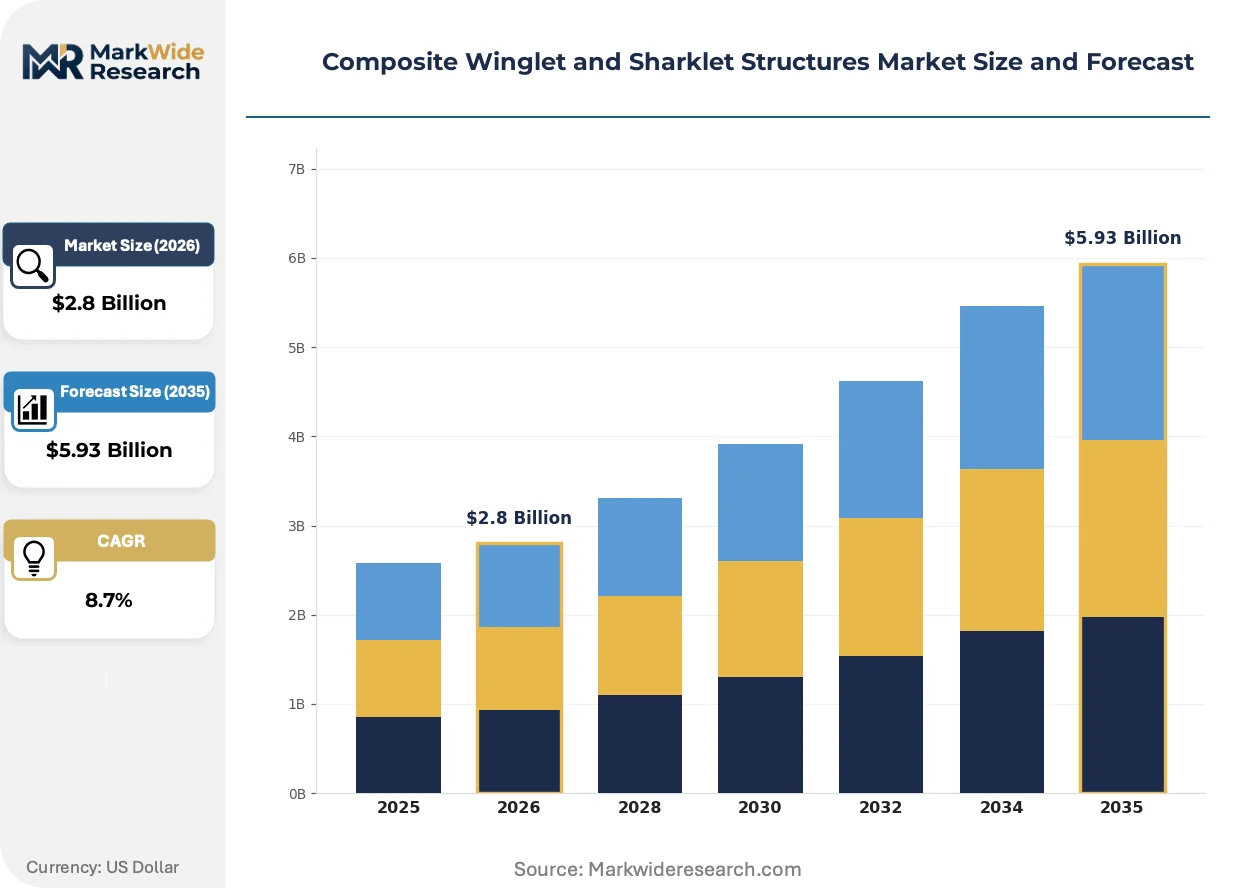
Market Dynamics
Narrowbody fleet renewal across Asia-Pacific airlines is compressing procurement cycles for factory-integrated wingtip devices, while FAA airworthiness directives on fuel efficiency compliance are tightening retrofit timelines for legacy platforms still in service.
Growth Catalysts
- FAA Part 25 Compliance Pressure:Updated fatigue life assessments for wingtip modifications on aging narrowbody frames are accelerating replacement demand. Airlines face mandatory compliance windows that compress procurement decisions.
- Carbon Fiber Layup Automation:Advanced automated fiber placement is reducing unit production costs for complex aerodynamic geometries. OEM specification lock-in around CFRP qualification barriers protects incumbent margin pools.
- China Civil Aviation Manufacturing:Demand concentrates in Shanghai and Tianjin manufacturing corridors where Airbus final assembly lines anchor localized supply chain development. Domestic fleet expansion programs require scaled wingtip device output.
Market Restraints
- Autoclave Capacity Bottlenecks:Curing cycle times for large composite aerostructures constrain throughput at tier-one suppliers. Capital intensity for qualified autoclave infrastructure limits new entrant participation.
- Prepreg Material Concentration:Toray, Hexcel, and Solvay control qualified carbon fiber supply for aerospace-grade winglet applications. Single-source dependencies create input cost volatility during capacity constraints.
- Flutter Margin Certification Complexity:EASA CS-25 structural integrity requirements demand extensive aeroelastic testing for each wingtip variant. Certification timelines extend 18-24 months for new geometries.
Strategic Opportunities
- Urban Air Mobility Integration:Electric vertical take-off and landing platforms require lightweight drag-reducing appendages. Winglet architectures scaled for eVTOL applications represent unaddressed specification territory.
- ReFuelEU Aviation Indirect Demand:Sustainable aviation fuel blending mandates escalate operator fuel costs. Drag-reducing devices that offset SAF premiums gain favorable total-cost-of-ownership positioning.
- Resin Transfer Molding Convergence:Out-of-autoclave processing paired with thermoplastic composites enables faster cycle times. Technology convergence opens cost-competitive positioning for mid-volume aftermarket retrofits.
Industry Challenges
- Composite Repair Technician Scarcity:Specialized skills for carbon fiber damage assessment and restoration outpace training pipeline output. MRO capacity constraints delay fleet return-to-service timelines.
- Type Certificate Amendment Coordination:STC integration with OEM baseline configurations requires synchronized engineering change approvals. Legacy platform documentation gaps complicate retrofit engineering packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Composite Winglet and Sharklet Structures Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Winglets, Sharklets, Wingtip Fences, Raked Wingtips, Blended Winglets Material: Carbon Fiber, Glass Fiber, Aramid Fiber, Hybrid Composites, Resin Matrices Application: Commercial Aircraft, Business Jets, Military Fighters, Cargo Aircraft, Unmanned Aerial Vehicles End User: Airliners, Private Operators, Defense Forces, Freight Carriers, Aerospace Manufacturers |
| Companies Covered | FACC, Korean Air Aerospace Division, RUAG Aerostructures, GKN Aerospace, Winglet Technology, BLR Aerospace, Airbus, The Boeing Company, Spirit AeroSystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Composite Winglet and Sharklet Structures Market Trends and Innovations
Automated fiber placement and out-of-autoclave curing are compressing production economics for complex aerostructures, while regulatory carbon accounting is embedding fuel efficiency hardware into compliance strategies.
Resin transfer molding for thermoplastic composite winglet structures is consolidating process economics for mid-volume production runs. Regional airlines and cargo converters are adopting RTM-fabricated sharklet retrofits as lead times compress from 26 weeks to 14 weeks. The technology is consolidating supplier tiers by enabling tier-two aerostructures houses to qualify for OEM direct contracts previously reserved for autoclave-capable incumbents.
The EU Green Deal's ReFuelEU Aviation mandate binds operators to escalating sustainable aviation fuel blending requirements through 2035. This indirect regulatory pressure accelerates demand for drag-reducing devices that offset higher SAF operating costs. European narrowbody operators are prioritizing factory-integrated sharklet configurations over retrofit alternatives to capture lifetime fuel burn reductions.
Airline procurement departments are unbundling wingtip device contracts from full aerostructures packages and sourcing directly from specialized composite manufacturers. This channel disintermediation disrupts traditional tier-one system integrator relationships. Asia-Pacific narrowbody fleet operators are most visible in this shift, driven by price transparency from Chinese manufacturing corridor alternatives.
Composite Winglet and Sharklet Structures Market Segmentation
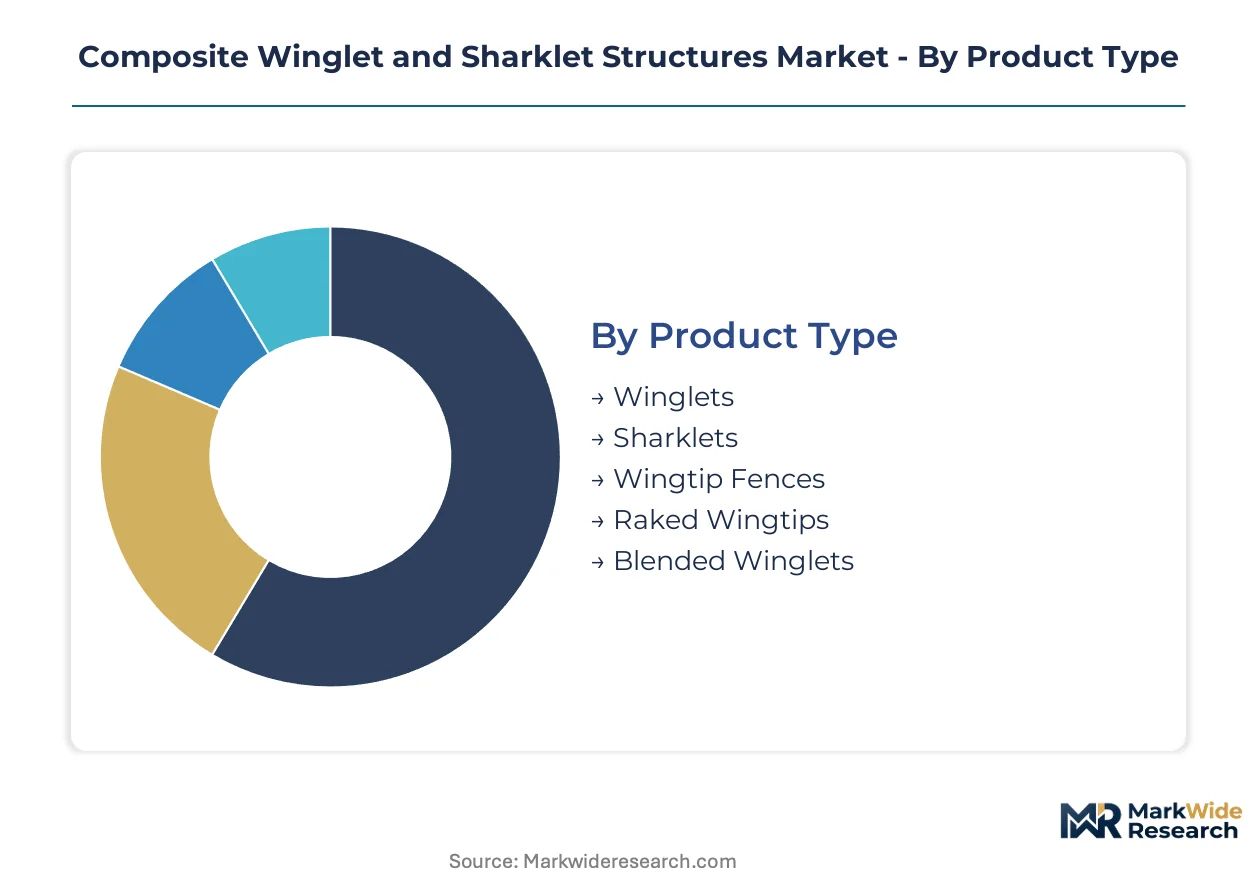
Segmentation in composite winglet and sharklet structures reflects divergent aerodynamic philosophies, material qualification barriers, and platform-specific certification requirements. Each axis shapes procurement patterns, margin pools, and supplier competitive positioning across commercial and defense aviation.
Product Type:
Product architecture determines manufacturing process selection, with autoclave curing dominating legacy geometries and out-of-autoclave methods penetrating newer variants.
- Winglets:Vertical or angled extensions mounted at wingtips to reduce induced drag through vortex disruption. Demand concentrates in North American retrofit programs for Boeing 737NG fleets where FAA compliance windows compress procurement timelines.
- Sharklets:Airbus-proprietary blended geometries integrating smoothly into wing structure for superior span efficiency. Shanghai and Tianjin final assembly lines anchor production scaling for A320neo family output.
- Wingtip Fences:Airbus legacy configuration on A320ceo variants with simpler manufacturing requirements but lower fuel burn reduction. European MRO networks sustain aftermarket demand for fleet retention programs.
- Raked Wingtips:Swept-back extensions optimized for high-Mach cruise efficiency on widebody platforms. Boeing 787 and 777X programs specify these geometries for long-haul route economics.
- Blended Winglets:Curved transitions between wing and tip device minimizing interference drag. Retrofit demand on aging 737-700/800 aircraft drives margin capture for specialized aerostructures houses.
Sharklets lead on scale through Airbus narrowbody production dominance; blended winglets lead on momentum through accelerated FAA-mandated retrofit cycles.
Material:
Material selection governs qualification pathways, with aerospace-grade carbon fiber imposing the steepest barriers to supplier entry.
- Carbon Fiber:Toray T800H and Hexcel IM7 grades dominate primary structural laminates for wingtip devices. OEM specification lock-in protects incumbent margin pools while prepreg concentration with Japanese and US suppliers creates input cost volatility.
- Glass Fiber:E-glass and S-glass reinforcements compete on cost for secondary structures and unmanned platforms. Chinese fiberglass manufacturers penetrate lower-tier aerospace applications where weight thresholds relax.
- Aramid Fiber:Kevlar and Twaron hybrids provide impact resistance and damage tolerance in leading edge applications. Military fighter programs specify aramid-carbon hybrids for field repairability.
- Hybrid Composites:Multi-fiber architectures balancing cost and performance for mid-volume production. Regional airline retrofits adopt hybrid configurations as resin transfer molding compresses lead times.
- Resin Matrices:Epoxy, bismaleimide, and emerging thermoplastic formulations determine cure cycles and service temperature limits. Out-of-autoclave epoxy systems are gaining qualification for aftermarket sharklet retrofits.
Carbon fiber commands revenue concentration; hybrid composites are expanding most quickly through process automation enabling tier-two supplier entry.
Application:
Application scope spans crewed and uncrewed platforms with divergent certification rigor and production volume economics.
- Commercial Aircraft:Narrowbody factory integration and widebody retrofit programs constitute the revenue core. Asia-Pacific fleet renewal concentrates procurement timing for A320neo and 737 MAX wingtip configurations.
- Business Jets:Custom aerodynamic optimization for long-range platforms like Gulfstream and Bombardier families. Low-volume production favors automated fiber placement flexibility over hard tooling amortization.
- Military Fighters:Survivability requirements drive damage-tolerant hybrid laminates with field-repair protocols. US Air Force and NATO procurement cycles synchronize with platform modernization programs.
- Cargo Aircraft:Freighter conversion programs on 767-300 and A330-300 platforms create retrofit demand. E-commerce logistics expansion extends aircraft economic life through drag-reduction modifications.
- Unmanned Aerial Vehicles:Weight-critical endurance platforms adopt thermoplastic composites for rapid fabrication. Defense and commercial drone manufacturers bypass autoclave infrastructure through resin transfer molding adoption.
Commercial aircraft anchors volume; unmanned aerial vehicles show steepest expansion trajectory through defense and logistics platform proliferation.
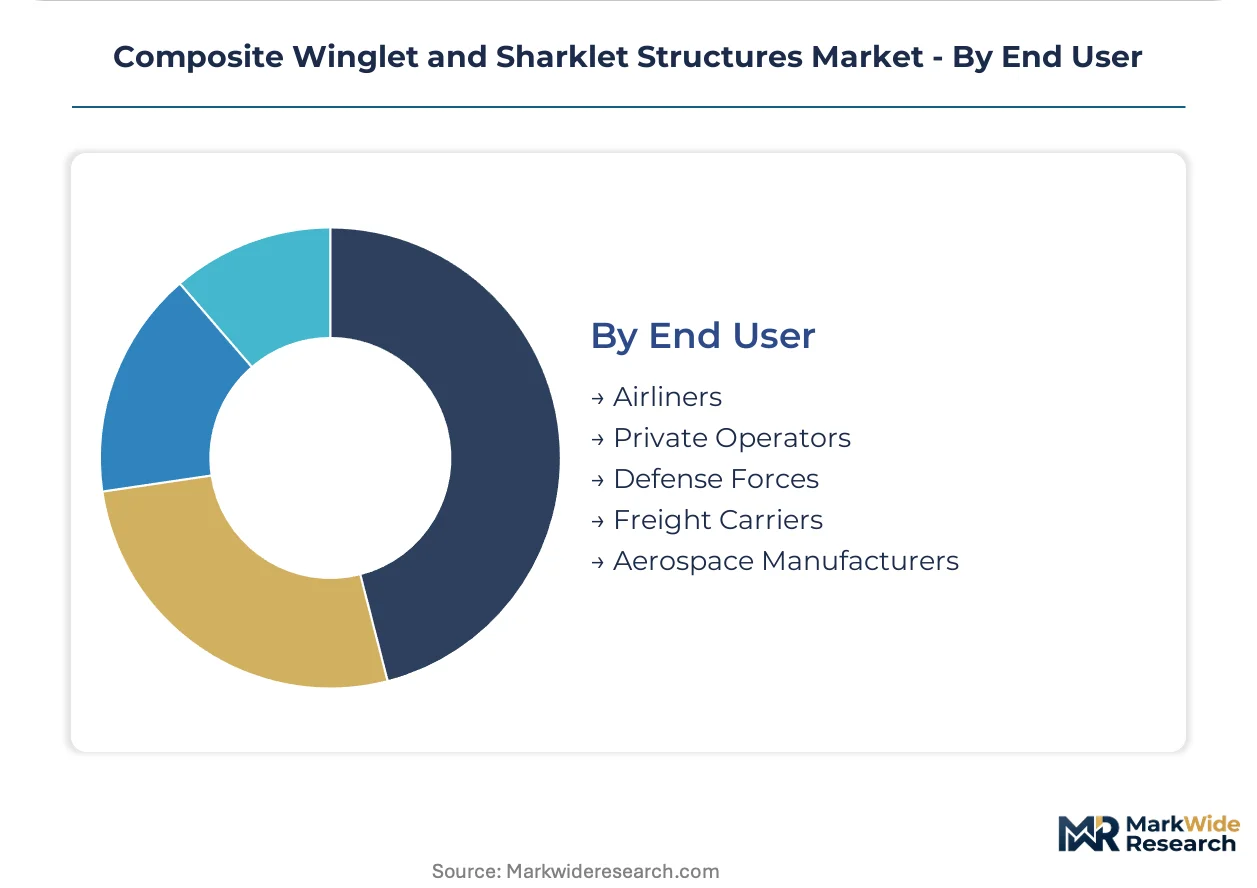
End User:
End user structure determines contract bundling patterns and direct procurement channel development.
- Airliners:Full-service and low-cost carriers unbundle wingtip device contracts from airframe purchases. Chinese operators leverage manufacturing corridor proximity for price transparency.
- Private Operators:Fractional ownership and charter fleets prioritize factory-integrated configurations over retrofit complexity. Business aviation OEMs specify custom geometries for range-performance differentiation.
- Defense Forces:Military procurement emphasizes damage tolerance and rapid field repair over fuel efficiency optimization. US Department of Defense and allied ministries sustain specialized supplier relationships.
- Freight Carriers:Cargo operators maximize payload-range economics through drag reduction on converted narrowbodies. Express carriers time retrofits with heavy maintenance checks to minimize downtime.
- Aerospace Manufacturers:Airbus and Boeing tier-one suppliers capture direct contracts for factory-integrated devices. Channel disintermediation enables specialized composite houses to bypass traditional system integrators.
Airliners dominate procurement volume; aerospace manufacturers are gaining share fastest through OEM direct-sourcing restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as suppliers migrate toward jurisdictions with streamlined aerospace certification pathways and concentrated OEM final assembly capacity. Cost-of-compliance gaps between mature aviation authorities and emerging manufacturing corridors are accelerating facility relocation decisions among tier-one aerostructures houses.
United States
FAA Part 25 certification requirements for wingtip modifications sustain demand for retrofit engineering services across aging narrowbody fleets. The agency's updated fatigue life assessment mandates compress procurement timelines for blended winglet installations on Boeing 737NG platforms. Wichita, Kansas anchors specialized aerostructures manufacturing clusters serving both commercial and business aviation segments.
China
Airbus A320neo family production scaling at Shanghai and Tianjin final assembly lines concentrates procurement for factory-integrated sharklet configurations. The Civil Aviation Administration of China's harmonized type certification procedures with EASA accelerate market access for European aerostructures suppliers. Domestic fleet expansion programs under the 14th Five-Year Plan require scaled composite wingtip device output from localized supply chains.
Germany
EASA CS-25 structural integrity standards govern flutter margin certification for wingtip modifications across European operator fleets. The EU Green Deal's ReFuelEU Aviation mandate indirectly accelerates demand for drag-reducing devices that offset sustainable aviation fuel cost premiums. Hamburg and Bremen manufacturing corridors host specialized composite fabrication facilities serving Airbus narrowbody programs.
South Korea
Korean Air Aerospace Division leverages captive airline fleet relationships to dominate Asia-Pacific aftermarket retrofit demand. The Ministry of Trade, Industry and Energy's aerospace industry development incentives support composite aerostructures capability expansion. Busan-Ulsan industrial clusters concentrate thermoplastic composite processing expertise for mid-volume production runs.
United Kingdom
GKN Aerospace sustains technology leadership through advanced carbon fiber layup processes for blended winglets serving Boeing platforms. The UK Civil Aviation Authority's bilateral certification agreements with FAA streamline cross-Atlantic retrofit program approvals. Bristol and Portsmouth manufacturing sites anchor European supply chain development for resin transfer molding applications.
Composite Winglet and Sharklet Structures Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with autoclave-capable incumbents defending premium positions in factory-integrated OEM supply while out-of-autoclave specialists capture aftermarket retrofit volume. The vendor base concentrates around three strategic archetypes: tier-one system integrators with hard-to-replicate certification assets, regional aerostructures houses leveraging geographic proximity to final assembly lines, and technology licensors monetizing proprietary geometries through royalty-bearing partnerships. Dominant competitive moves include backward integration into carbon fiber prepreg supply and strategic partnerships with emerging urban air mobility platform developers.
Within the tier-one integrator tier, GKN Aerospace and FACC exemplify divergent geographic anchoring strategies that shape their respective OEM relationships. Korean Air Aerospace Division occupies a distinctive position as a vertically integrated airline-affiliated manufacturer with privileged access to Asia-Pacific fleet retrofit cycles. Spirit AeroSystems represents the scale-driven contract manufacturing archetype, positioned to benefit from channel disintermediation trends as procurement departments unbundle wingtip device contracts from full aerostructures packages.
| Leading Market Players |
|---|
| FACC |
| Korean Air Aerospace Division |
| RUAG Aerostructures |
| GKN Aerospace |
| Winglet Technology |
| BLR Aerospace |
| Airbus |
| The Boeing Company |
| Spirit AeroSystems |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber prepreg costs cascade through three distinct pricing tiers as aerospace-grade Toray T800H and Hexcel IM7 laminates move from Japanese and US supplier mills to tier-one autoclave operators, then to factory-integrated OEM contracts versus aftermarket retrofit channels. FAA and EASA certification lock-in at each tier creates margin capture asymmetry that favors incumbent suppliers with qualified part histories.
Pricing Analysis
Distributor margins on qualified prepreg supply separate premium-tier factory-integrated contracts from standard-tier aftermarket retrofits and economy-tier unmanned aerial vehicle applications. Price differentiation hinges on EASA CS-25 certification grade and volume scale, with single-aisle OEM direct contracts commanding premium positioning over multi-source MRO procurement. Cost compression in aftermarket channels intensifies as resin transfer molding enables tier-two suppliers to bypass traditional autoclave incumbents. Cargo converters and regional airlines exhibit highest price sensitivity due to total-cost-of-ownership scrutiny, while full-service carriers prioritize fuel burn reduction over unit cost.
Supply Chain Analysis
Refurbishment flows for damaged wingtip devices create reverse-logistics complexity that specialized MRO networks in Wichita, Hamburg, and Busan-Ulsan industrial clusters manage through proprietary repair protocols. Geographic supply concentration centers on Japan, the United States, and China for carbon fiber feedstock, with Germany and South Korea anchoring finished aerostructures fabrication. Raw material dependencies rest on epoxy resin systems, thermoplastic formulations, and automated fiber placement equipment. Single-source vulnerability around qualified prepreg supply from Toray, Hexcel, and Solvay creates input cost volatility during capacity constraints. Distribution runs through OEM direct channels for factory-integrated devices and specialized aerostructures houses for aftermarket retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
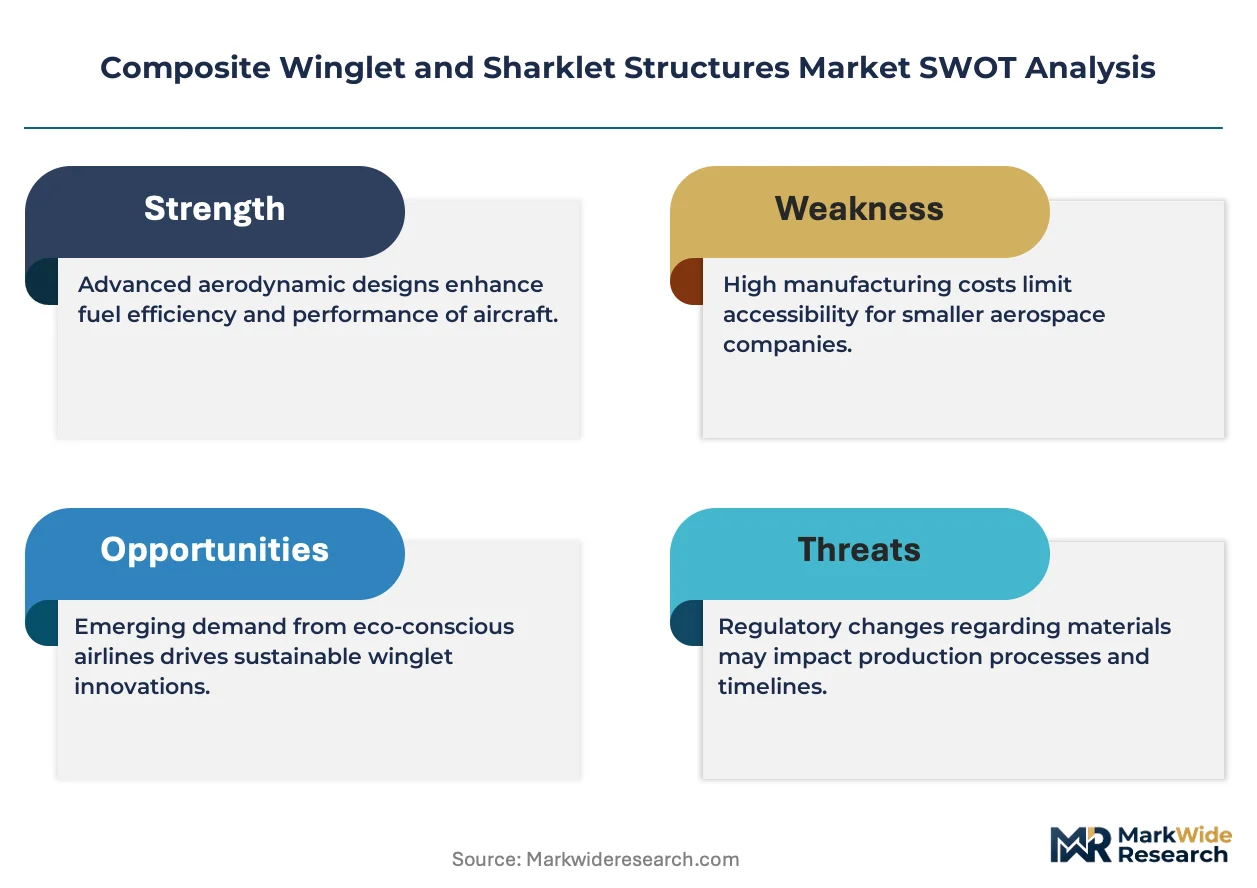
Analyst Recommendations
Margin expansion in composite winglet and sharklet structures rests on out-of-autoclave process economics compressing production costs while ReFuelEU Aviation compliance premiums sustain pricing power for drag-reduction hardware.
For Market Incumbents: Anchor certification assets against resin transfer molding disruption by accelerating thermoplastic composite qualification ahead of type certificate amendment cycles. Defend OEM specification lock-in through backward integration into carbon fiber prepreg supply. Prioritize capacity addition in China's Shanghai-Tianjin manufacturing corridor to capture Airbus A320neo family scaling. Channel control through direct airline relationships protects against procurement disintermediation. For New Entrants and Emerging Players: Urban air mobility platform developers represent an underserved buyer archetype with unaddressed specification territory for scaled winglet architectures. Regional airline retrofit programs offer the most penetrable segment as lead time compression from 26 weeks to 14 weeks disrupts incumbent relationships. Cargo converter heavy maintenance check windows provide synchronized fleet access points. A go-to-market angle centered on out-of-autoclave epoxy qualification for aftermarket sharklet retrofits bypasses autoclave infrastructure barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where autoclave capacity scarcity constrains tier-one supplier throughput and creates acquisition premiums for qualified facilities. Long-term viability favors targets with EASA CS-25 and FAA Part 25 certification portfolios spanning multiple narrowbody platforms. Acquisition target archetype: specialized aerostructures houses with resin transfer molding capability and OEM direct-sourcing relationships. The signal to watch is type certificate amendment timing for next-generation narrowbody platforms, which triggers qualification investment cycles and determines competitive positioning windows.| Strategic Initiative | Industry Significance |
|---|---|
| Out-of-Autoclave Process Qualification | Enables tier-two suppliers to capture OEM direct contracts previously reserved for autoclave incumbents. |
| Backward Integration into Prepreg Supply | Reduces single-source dependency on Toray, Hexcel, and Solvay for aerospace-grade carbon fiber. |
| Urban Air Mobility Platform Partnership | Positions winglet architectures for eVTOL applications in unaddressed specification territory. |
| China Manufacturing Corridor Expansion | Captures localized demand from Airbus Shanghai and Tianjin final assembly line scaling. |
| Thermoplastic Composite R&D Investment | Accelerates cycle times for mid-volume aftermarket retrofit production economics. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with aerostructures procurement managers, composite manufacturing engineers, airline fleet planning executives, and MRO operations directors with secondary validation against FAA airworthiness directives, EASA certification databases, SEC filings from tier-one suppliers, and customs trade data for carbon fiber prepreg flows. Bottom-up build-ups across product type, material grade, application, and end user segments triangulated against top-down market sizing from OEM production rate disclosures.
Comparable-period anchoring to historical narrowbody delivery cycles and retrofit program timing established the forecast window baseline across the projection horizon. Segmentation dimensions modeled include product architecture, material qualification tier, platform application, and procurement channel structure. CAGRs derived from production rate trajectories, fleet age distributions, and regulatory compliance timeline analysis. Industry-specific forecast inputs encompass Airbus and Boeing narrowbody output schedules, ReFuelEU Aviation mandate implementation phasing, and autoclave capacity expansion announcements.
Underlying measurement precision varies by segment; factory-integrated OEM contracts carry tighter precision than aftermarket retrofit estimates due to production visibility gaps. Forecasts reflect assumptions around certification timeline continuity, prepreg supply availability, and regulatory harmonization between FAA Part 25 and EASA CS-25 frameworks. Practitioners should monitor type certificate amendment announcements, SAF blending mandate acceleration, and thermoplastic composite qualification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Global Aircraft Nacelle and Thrust Reverser Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Latch Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Aerospace Parts Manufacturing Market
Aircraft and Aerospace Components
Aerospace Nuts Market
Aircraft and Aerospace Components
United Kingdom Rotor Blade Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Asia Pacific Commercial Aircraft Aerostructures Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Altimeter Market
Aircraft and Aerospace Components
Europe Passive Electronic Components in Aerospace and Defense Market
Aircraft and Aerospace Components
Aerospace Pressure Bulkheads Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market