
 South Korea Airport Operations Market | 2026-2036
South Korea Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Airport Operations Market Insights
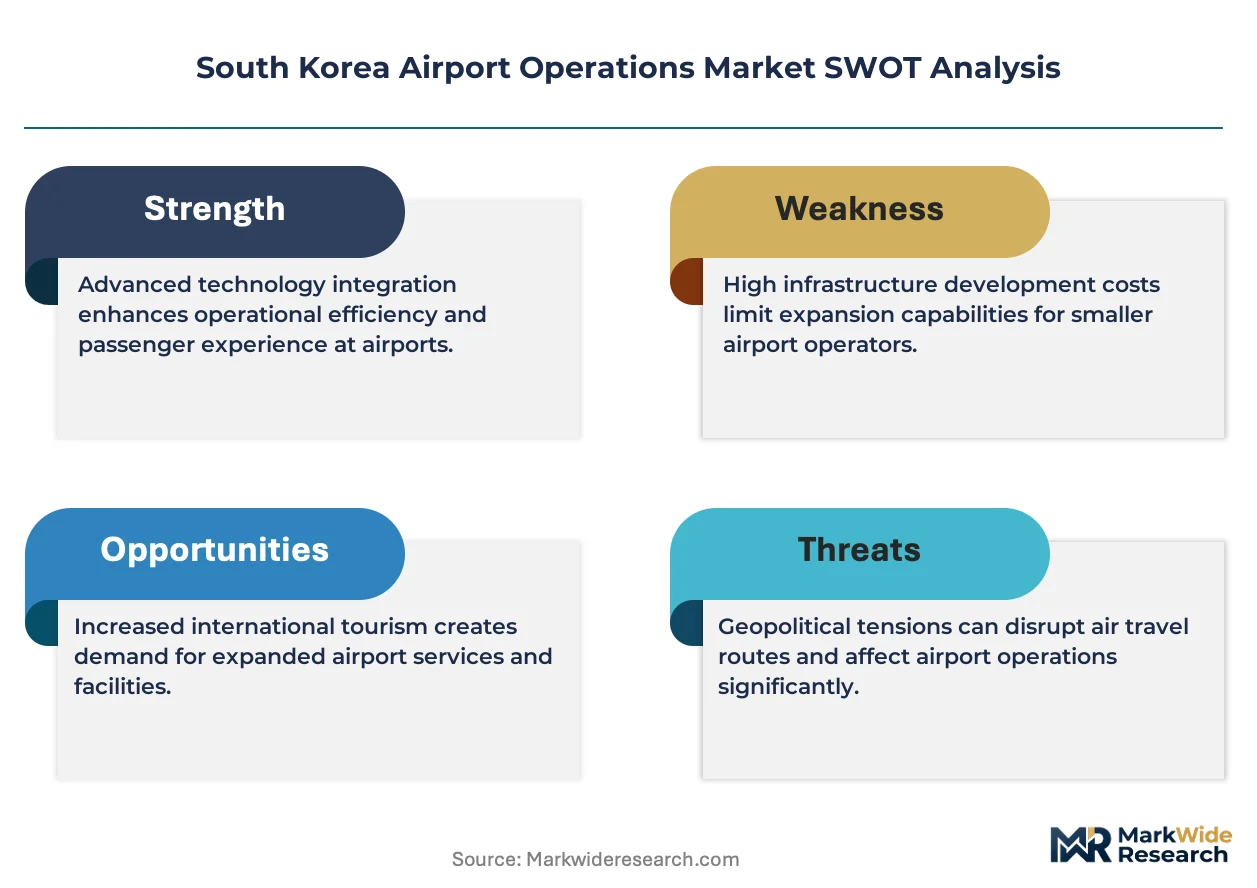
Software-defined passenger flow management is hardening into a recurring revenue layer across South Korean hub airports. Incheon International Airport Corporation leverages real-time gate allocation algorithms to sustain transfer efficiency rankings. Korea Airports Corporation anchors regional connectivity through consolidated control of provincial facilities. Busan Gimhae International Airport Corporation differentiates via cruise-air multimodal integration.
Airport operations encompass the coordinated execution of ground handling, passenger processing, cargo logistics, and airside maintenance within aviation infrastructure. Terminal throughput depends on baggage handling system capacity exceeding 15,000 items per hour at peak design loads. Ground handling services dominate direct revenue contribution due to aircraft turnaround time penalties and specialized equipment requirements. Biometric screening technology captures disproportionate capital allocation as facial recognition gates replace manual document checks at immigration checkpoints.
MFDS aviation health protocols, Ministry of Land Infrastructure and Transport airport certification standards, and KISO cybersecurity frameworks govern operational compliance. MFDS pandemic-era contagion controls permanently altered passenger processing layouts and ventilation specifications. Stakeholders must weigh franchise model transitions against retained public control as the government evaluates Gimhae and Cheongju privatization pathways.
Market Dynamics
Slot coordination algorithms at Incheon and Gimpo are compressing turnaround windows below 45 minutes for narrow-body aircraft, forcing ground handlers to retool equipment fleets and retrain crews for synchronized operations.
Growth Catalysts
- MFDS Aviation Health Protocols:Permanent pandemic-era ventilation and passenger flow specifications are mandating terminal infrastructure upgrades across all Ministry of Land, Infrastructure and Transport-certified facilities.
- Low-cost carrier fleet expansion:Secondary hub commitments at Gimhae and Daegu are tightening slot scarcity and driving demand for automated gate allocation systems.
- Biometric screening deployment:Facial recognition gates replacing manual document checks at immigration checkpoints are accelerating passenger throughput capacity.
Market Restraints
- Labor cost rigidity:Ground handling unions at Incheon resist flexible staffing models despite seasonal demand swings, inflating per-turnaround labor costs.
- Equipment import dependency:Baggage handling system components and specialized GSE fleets concentrate sourcing from German and Japanese suppliers, exposing operators to currency volatility.
- Land scarcity at Seoul corridor:Incheon fourth-phase expansion faces wetland protection disputes and Gimpo is physically constrained by urban encroachment.
Strategic Opportunities
- Jeju Island cruise-air integration:Untapped multimodal passenger flows between seaborne tourism and domestic aviation create white space for unified ticketing platforms.
- KISO cybersecurity framework compliance:Mandated airport IT security audits are opening recurring revenue streams for threat monitoring and incident response services.
- Drone-based airside inspection:Converging computer vision and autonomous flight systems enable runway and lighting assessments without operational shutdowns.
Industry Challenges
- Certified aircraft marshaller shortages:Korea Airports Corporation training pipelines cannot match attrition rates at regional facilities, delaying peak-season capacity ramps.
- Legacy BHS integration complexity:Retrofitting 1990s-era baggage handling architectures with real-time tracking APIs requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Airport Operations Market |
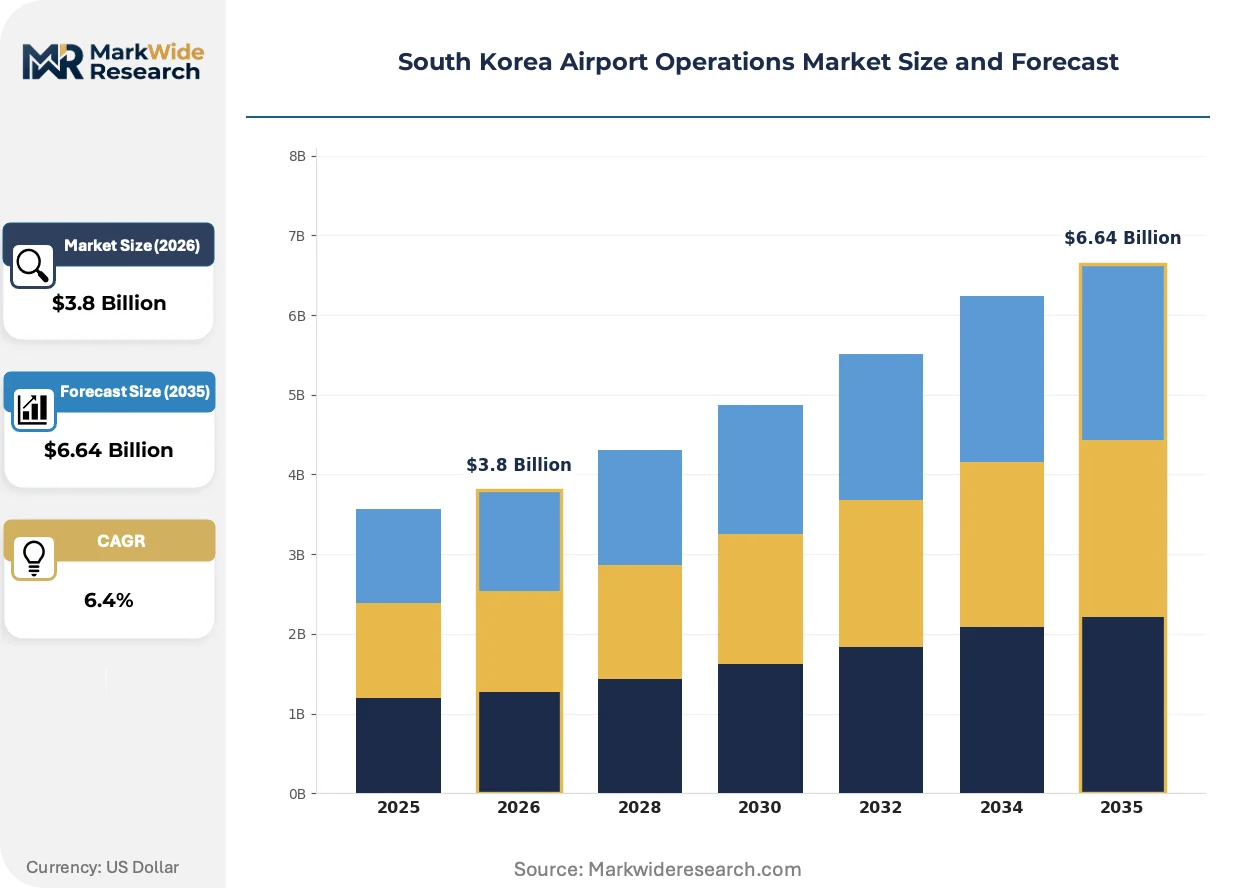
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Passenger Services, Cargo Operations, Maintenance Technology: Automated Check-in, Baggage Tracking, Biometric Screening, Mobile Applications End User: Airlines, Airport Authorities, Ground Service Providers, Logistics Companies Operation Model: Public-Private Partnership, Fully Privatized, Fully Public, Franchised |
| Companies Covered | Jeju International Airport Corporation, Busan Gimhae International Airport Corporation, Incheon International Airport Corporation, Cheongju International Airport Corporation, Yeosu Airport Corporation, Korea Airports Corporation, Daegu International Airport Corporation, Yangyang International Airport Corporation, Gimpo International Airport Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Airport Operations Market Trends and Innovations
Software-defined operational layers are supplanting hardware-centric airport management, with real-time data streams now governing everything from gate assignments to predictive maintenance scheduling.
Digital twin simulation is decentralizing capacity planning authority from central engineering offices to individual terminal operations centers. Incheon International Airport Corporation deploys physics-based modeling to test passenger flow scenarios without physical prototyping. This capability compresses renovation design cycles and enables rapid reconfiguration during disruption events.
Ministry of Land, Infrastructure and Transport airport certification standards now mandate cybersecurity risk assessments as a condition of operating license renewal. KISO frameworks require quarterly penetration testing and incident reporting protocols. Regional airports lacking dedicated security operations centers are outsourcing compliance to specialized aviation IT vendors, creating a managed services market segment.
Transfer passenger behavior is fragmenting hub loyalty as low-cost carriers undercut full-service alliance pricing on intra-Asia routes. Seoul-Incheon historically captured 70 percent of Korea-China-Japan triangle transfer volume; this concentration is eroding as Gimhae and Qingdao airports improve connectivity. Airlines are responding with unbundled fare products and paid lounge access to recover ancillary revenue from price-sensitive transit passengers.
South Korea Airport Operations Market Segmentation
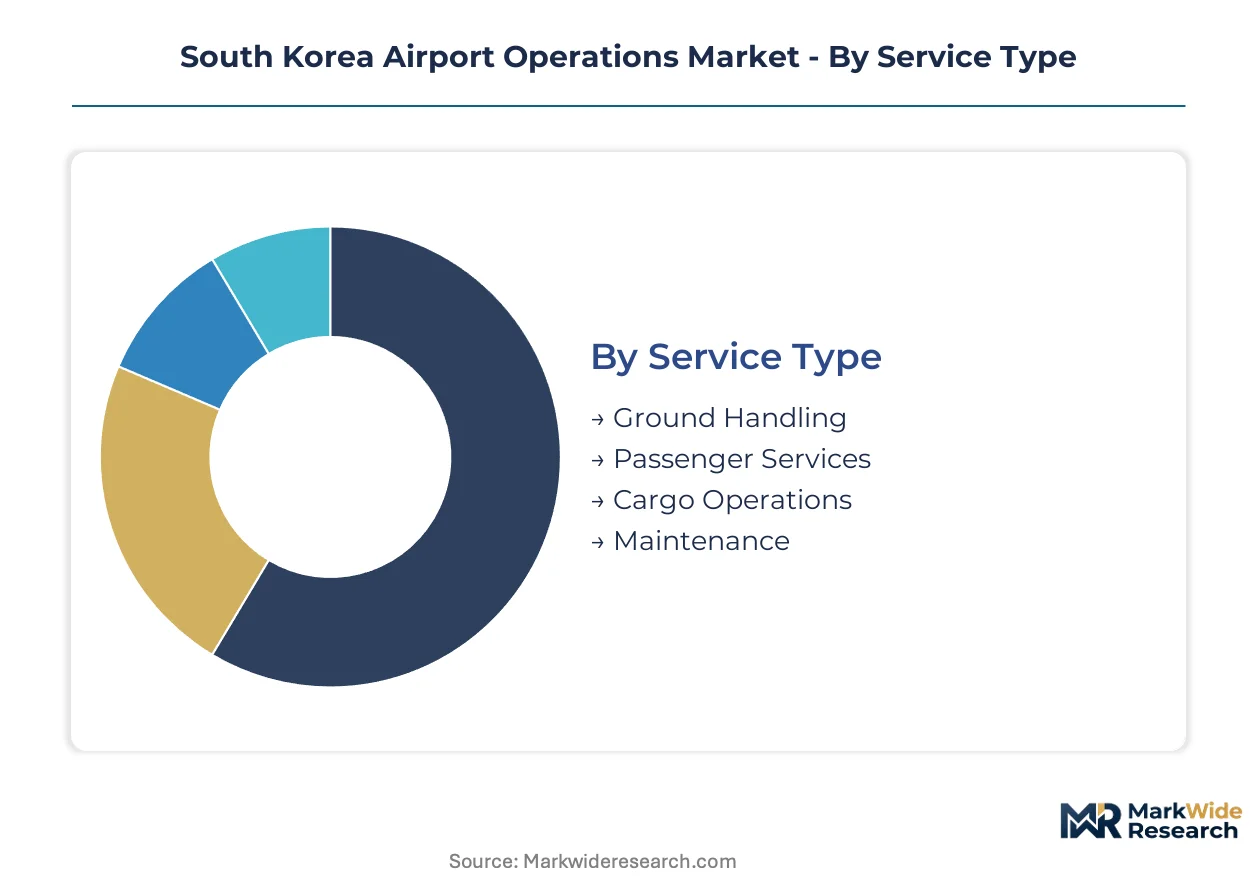
Airport operations in South Korea fragment across service delivery modes, technology maturity tiers, and governance structures that determine capital access and operational flexibility. Each segmentation axis reveals distinct buyer priorities: Incheon International Airport Corporation demands throughput-maximizing automation, while Korea Airports Corporation facilities prioritize cost-controlled reliability.
Service Type:
Buyers differentiate by aircraft turnaround time penalties and labor specialization requirements, with premium handlers commanding rates for narrow-body synchronization below 45-minute windows.
- Ground Handling:Aircraft turnaround services encompassing pushback, fueling, and catering coordination dominate direct revenue contribution due to specialized GSE fleet requirements and union-negotiated labor rates at Incheon. Demand concentrates at Seoul corridor hubs where slot compression below 45 minutes for narrow-body aircraft forces equipment retooling and crew retraining investments.
- Passenger Services:Terminal processing including check-in, boarding, and lounge management generates recurring revenue through airline service agreements. Growth tilts toward biometric-integrated flows as facial recognition gates replace manual document checks at immigration checkpoints across Ministry of Land, Infrastructure and Transport-certified facilities.
- Cargo Operations:Freight handling and cold chain logistics serving pharmaceutical and electronics exports.
- Maintenance:Airside infrastructure upkeep including runway resurfacing and lighting system replacement.
Volume sits with Ground Handling; growth tilts toward Passenger Services.
Technology:
Procurement patterns split between legacy system retrofits at 1990s-era regional terminals and greenfield automation deployments at expansion phases.
- Automated Check-in:Self-service kiosks and mobile-enabled boarding pass issuance reduce counter staffing requirements. Korea Airports Corporation provincial facilities deploy these systems to offset certified aircraft marshaller shortages.
- Baggage Tracking:Real-time item location systems requiring API integration with legacy BHS architectures. Retrofitting complexity concentrates demand at Incheon and Gimpo where 1990s-era infrastructure demands custom middleware development.
- Biometric Screening:Facial recognition gates capture disproportionate capital allocation as permanent pandemic-era specifications reshape passenger processing layouts.
- Mobile Applications:Unified platforms for flight information, wayfinding, and retail integration.
Capital deployment clusters on Biometric Screening; operational expansion favors Mobile Applications.
End User:
Contract structures range from long-term franchise agreements to spot-market ground handling procurement, with pricing power varying by slot scarcity and alternative supplier availability.
- Airlines:Full-service carriers and low-cost operators purchasing turnaround services and terminal access. Low-cost carrier fleet expansion at Gimhae and Daegu tightens slot coordination requirements and drives automated gate allocation demand.
- Airport Authorities:Incheon International Airport Corporation and Korea Airports Corporation directly operating select functions. These entities anchor software-defined passenger flow management investments to sustain transfer efficiency rankings.
- Ground Service Providers:Third-party handlers competing for airline contracts through equipment specialization.
- Logistics Companies:Freight forwarders and integrators securing warehouse and tarmac access.
Procurement volume concentrates with Airlines; contract innovation emerges through Airport Authorities.
Operation Model:
Governance selection determines infrastructure financing access and regulatory compliance burden, with the Ministry of Land, Infrastructure and Transport evaluating privatization pathways for Gimhae and Cheongju.
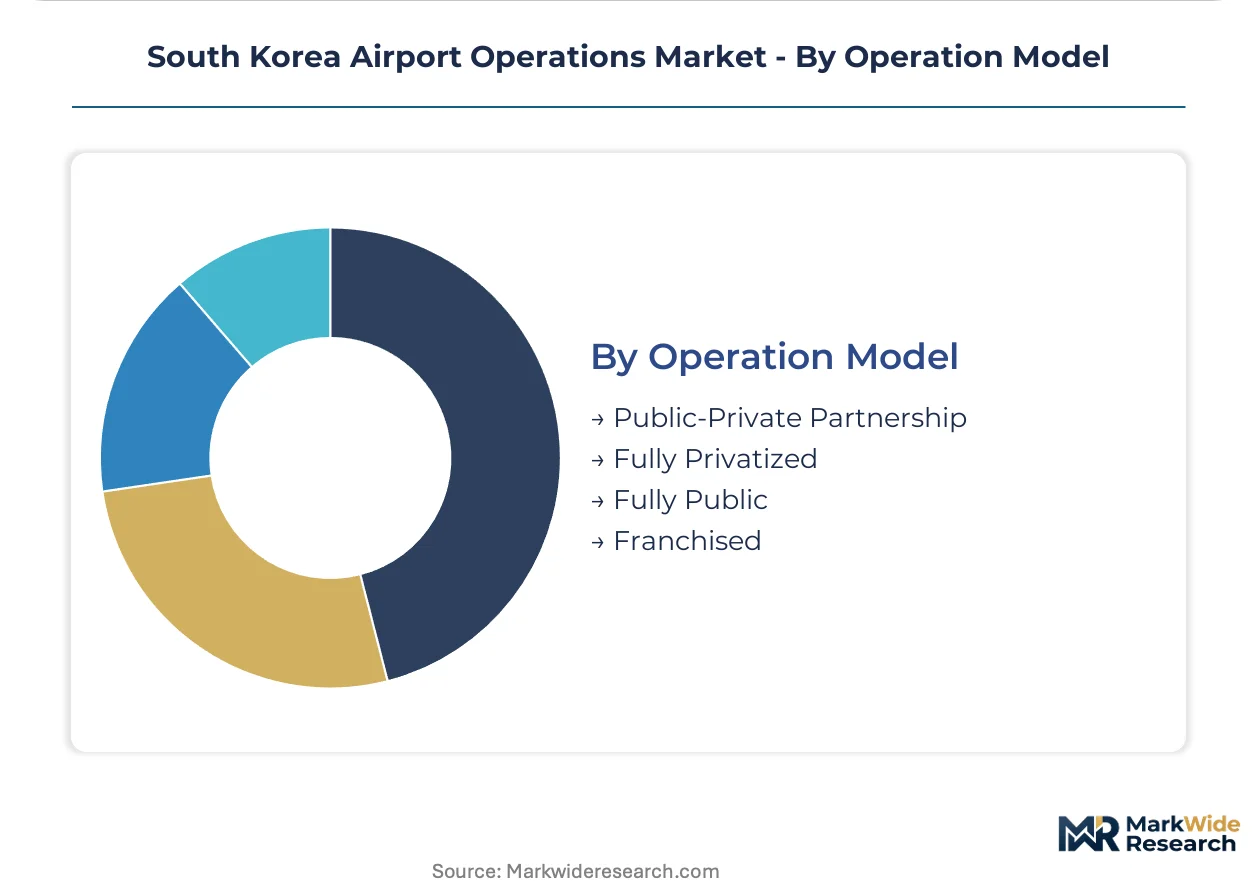
- Public-Private Partnership:Shared capital structures combining government land assets with private operational expertise. Incheon operates under this model, leveraging real-time gate allocation algorithms to maintain transfer passenger capture.
- Fully Privatized:Complete private ownership with profit-maximizing fee structures. No major South Korean airport currently employs this model, though government evaluations of Gimhae and Cheongju pathways signal potential transitions.
- Fully Public:State-operated facilities with budget-constrained capital programs. Korea Airports Corporation provincial network operates here, facing certified aircraft marshaller training pipeline shortfalls.
- Franchised:Concession-based service contracts for specific terminal functions or retail operations.
Operational scale rests with Public-Private Partnership; structural reform momentum points toward Franchised arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Operations concentrate in the Seoul Capital Area while provincial hubs absorb overflow capacity. Consumption patterns split between international transfer traffic at Incheon and domestic leisure flows to Jeju. Regional disparities in automation investment are widening throughput gaps.
Seoul Capital Area
Incheon International Airport Corporation processes the majority of international transfer volume through its automated gate allocation systems. MFDS aviation health protocols mandate biometric screening deployments at both Incheon and Gimpo facilities. Gimpo International Airport Corporation faces physical constraints from urban encroachment while handling disproportionate domestic business traffic.
Busan-Ulsan
Busan Gimhae International Airport Corporation differentiates through cruise-air multimodal integration serving seaborne tourism flows. Ministry of Land, Infrastructure and Transport slot coordination requirements are tightening as low-cost carriers expand fleet commitments. The Busan metropolitan corridor anchors southeastern connectivity to Japan and Southeast Asian destinations.
Daegu-Gyeongbuk
Daegu International Airport Corporation is absorbing secondary hub traffic as budget airlines diversify beyond Seoul corridor saturation. Korea Airports Corporation training pipelines struggle to match certified aircraft marshaller attrition rates at this facility. The Daegu technology manufacturing cluster generates cargo demand for electronics exports.
Jeju Island
Jeju International Airport Corporation manages the nation's busiest domestic route from Seoul with persistent slot scarcity. Untapped cruise-air multimodal integration creates white space for unified ticketing platforms between seaborne tourism and aviation. The island's resort economy drives seasonal demand swings that strain ground handling labor flexibility.
Daejeon-Sejong
Cheongju International Airport Corporation operates under evaluation for potential privatization pathway transitions by the Ministry of Land, Infrastructure and Transport. The Sejong administrative city proximity generates government-related passenger flows distinct from leisure or business segments. This facility represents the franchised operational model under active structural reform consideration.
South Korea Airport Operations Market Competitive Landscape
Top-tier vendors anchor the public-private partnership tier, while fully public operators manage provincial networks with budget-constrained capital programs. The market structure consolidates around three strategic archetypes: international hub specialists with software-defined passenger flow management, regional connectivity operators prioritizing cost-controlled reliability, and multimodal integrators exploiting cruise-air synergies. Competitive moves center on automation procurement partnerships and franchise model transitions as privatization evaluations proceed.
Among the public-corporation tier, Incheon International Airport Corporation, Korea Airports Corporation, and Busan Gimhae International Airport Corporation exemplify distinct operational archetypes. Incheon International Airport Corporation occupies the premium automation position with real-time gate allocation investments. Korea Airports Corporation anchors provincial network consolidation across multiple secondary facilities. Busan Gimhae International Airport Corporation represents the multimodal differentiation strategy through cruise-air integration capabilities.
| Leading Market Players |
|---|
| Jeju International Airport Corporation |
| Busan Gimhae International Airport Corporation |
| Incheon International Airport Corporation |
| Cheongju International Airport Corporation |
| Yeosu Airport Corporation |
| Korea Airports Corporation |
| Daegu International Airport Corporation |
| Yangyang International Airport Corporation |
| Gimpo International Airport Corporation |
| Others |
Pricing and Supply Chain Analysis
Airline procurement concentration at Incheon International Airport Corporation anchors contract-based long-term service agreements, with ground handling fees negotiated through multi-year franchise arrangements that bundle equipment, labor, and slot coordination into unitized turnaround charges.
Pricing Analysis
Margin tightening in ground handling services reflects union-negotiated labor rates at Seoul corridor hubs resisting flexible staffing models despite seasonal demand swings. Three-tier pricing structure across premium, standard, and economy levels separates full-service carrier synchronization packages from low-cost carrier basic turnaround and cargo-only handling. Price differentiation traces to equipment specialization grade and KISO cybersecurity certification tier. Low-cost carriers exhibit highest price sensitivity, while full-service alliance members prioritize transfer efficiency over per-turnaround cost.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers for baggage handling system components and specialized GSE fleets. Equipment sourcing draws from Germany, Japan, and domestic Korean fabrication for terminal infrastructure. Raw material dependencies include precision-engineered conveyor systems, autonomous guided vehicle fleets, and biometric sensor arrays. Tariff exposure on imported automation hardware creates cost volatility. Distribution runs through Ministry of Land, Infrastructure and Transport-certified vendor lists with direct procurement to airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MFDS aviation health protocols permanently altered passenger processing specifications, erecting compliance barriers that favor incumbent operators with certified infrastructure and established regulatory relationships.
For Market Incumbents: To counter low-cost carrier fleet expansion eroding Seoul corridor slot premiums, deepen automation procurement partnerships for biometric-integrated passenger flows and secure exclusive ground handling franchises at Gimhae and Daegu before privatization pathways open. KISO cybersecurity framework compliance investments create switching-cost moats against regional competitors. For New Entrants and Emerging Players: A mid-market pricing gap between Incheon premium automation and Korea Airports Corporation budget-constrained reliability opens white space at Jeju Island for unified cruise-air ticketing platforms and drone-based airside inspection services. Target provincial facilities facing certified aircraft marshaller shortages with outsourced training and equipment leasing models. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional connectivity operators in Busan-Ulsan and Daegu-Gyeongbuk corridors with underutilized slot capacity and multimodal integration potential. Watch Ministry of Land, Infrastructure and Transport privatization evaluation announcements as inflection signals for franchise model transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Screening Deployment | Facial recognition gates at immigration checkpoints accelerate passenger throughput capacity at MFDS-certified facilities. |
| Drone-Based Airside Inspection | Autonomous flight systems enable runway assessments without operational shutdowns at Incheon and Gimpo. |
| Ground Handling Franchise Acquisition | Consolidated control of provincial facilities strengthens Korea Airports Corporation network economies. |
| Cybersecurity Compliance Outsourcing | Regional airports lacking security operations centers create recurring revenue for aviation IT vendors. |
| Cruise-Air Multimodal Integration | Unified ticketing platforms between seaborne tourism and aviation unlock Jeju Island passenger flows. |
Research Methodology
Multi-period observation of slot utilization rates, turnaround time performance, and biometric deployment timelines anchored the trend analysis, supplemented by interviews with Incheon International Airport Corporation operations directors, Korea Airports Corporation regional facility managers, ground handling union representatives, Ministry of Land, Infrastructure and Transport certification officials, and biometric system integration specialists. Secondary validation drew from MFDS aviation health protocol filings, KISO cybersecurity framework documentation, airport authority annual reports, and customs records for GSE equipment imports. Bottom-up service segment sizing and top-down infrastructure investment flows were triangulated.
Input-output matrices modeled passenger throughput volumes against automation capital deployment across service type, technology tier, and governance structure dimensions over the projection horizon. CAGRs were derived from regression analysis of historical slot compression trends and fleet commitment pipelines. Industry-specific forecast inputs included low-cost carrier expansion schedules at secondary hubs and Ministry of Land, Infrastructure and Transport privatization evaluation timelines.
Inputs from airport authority disclosure filings and regulatory certification databases were available through the study window; gaps in proprietary airline ground handling contract terms introduce uncertainty bands around revenue concentration estimates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Global Airside Services Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Canada Airport Operations Market
Airport Operations
UK Airport Operations Market