
 General Aviation Engines Market | 2026-2036
General Aviation Engines Market Size, Share, and Industry Trends Forecast 2026-2036
General Aviation Engines Market Intelligence
Market Context
Modular engine-airframe bundling is rebalancing procurement economics across the general aviation value chain. Pratt & Whitney Canada leverages its turboprop integration expertise to anchor long-term fleet agreements with regional OEMs. Continental Aerospace Technologies competes through backward integration into piston engine component manufacturing. Lycoming Engines dominates the flight training segment with certified powerplants purpose-built for high-cycle operations.
Technical Definition and Segments
General aviation engines are air-breathing propulsion systems rated below 4,000 shaft horsepower, encompassing reciprocating, turbine, and emerging electric architectures designed for non-commercial aircraft operations under 19 passenger seats. Piston engines sustain the largest installed base through simplicity and lower operating costs, while turboprop engines capture expanding margin pools in utility and regional transport roles. Jet engines lead the personal aircraft and air taxi services categories where speed and altitude performance command premium positioning. Electric engines represent the fastest-growing technology segment as battery energy density improves and airframe electrification architectures mature.
Regulatory Environment
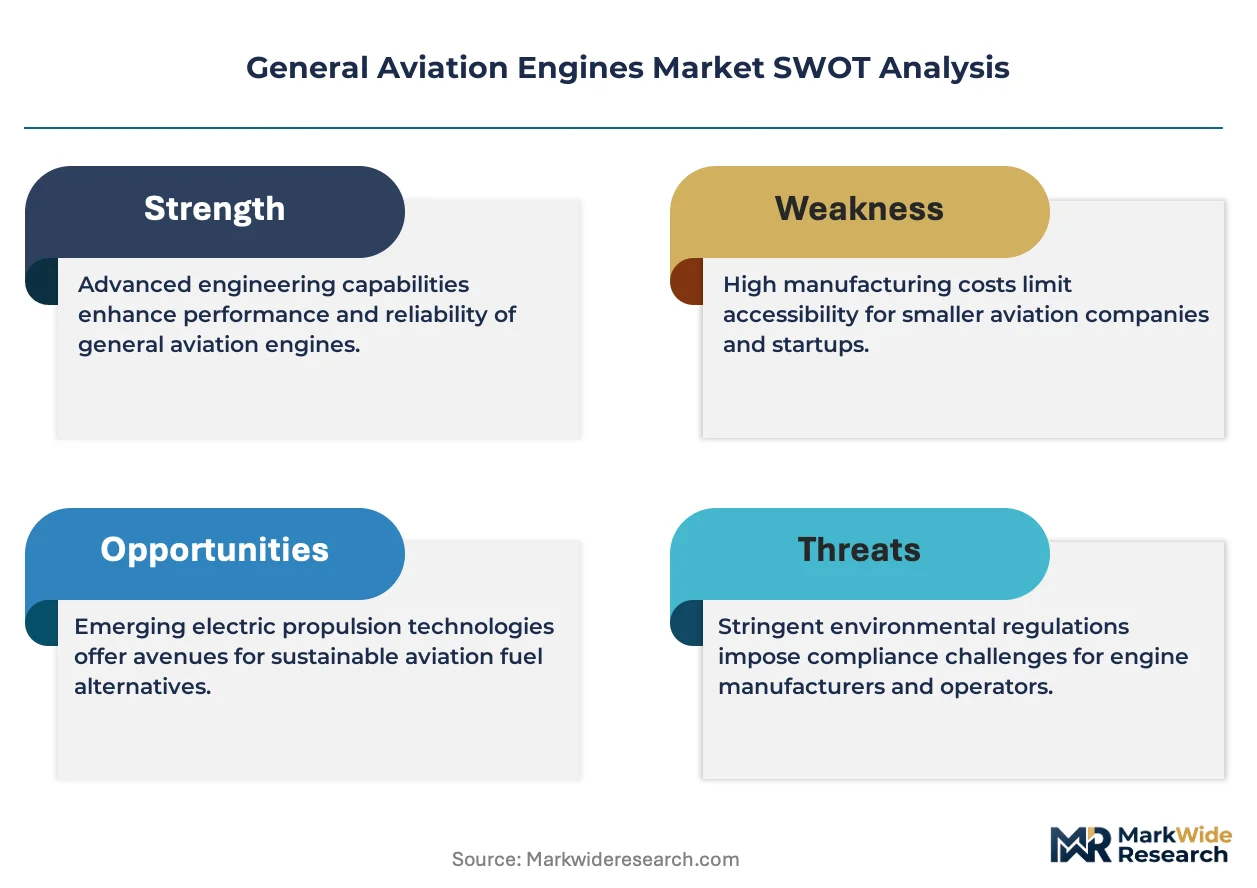
FAA Part 23 reforms and EASA CS-23 standards are reshaping certification pathways, reducing development timelines for innovative propulsion concepts. EPA aircraft emissions guidelines and ICAO carbon offset requirements are forcing fuel efficiency improvements across turbine and piston portfolios. Stakeholders must monitor evolving ASTM standards for sustainable aviation fuels compatibility and electric propulsion system airworthiness criteria.
Market Dynamics
Propulsion electrification is fragmenting the traditional engine-airframe bundling model that has governed general aviation procurement for decades, forcing incumbents to defend installed bases while new entrants capture experimental and training segments.
Growth Catalysts
- FAA Part 23 Certification Streamlining:The reformed airworthiness standards compress approval timelines for novel propulsion architectures, enabling faster market entry for hybrid-electric systems targeting the light sport aircraft category.
- Flight Training Fleet Renewal:University aviation programs and Part 141 schools in the United States are replacing aging piston powerplants with modern fuel-injected alternatives to reduce maintenance downtime and improve dispatch reliability.
- Sustainable Aviation Fuel Mandates:ASTM D7566 certification pathways for synthetic fuels are expanding turbine engine addressable markets as charter operators seek emissions compliance without airframe replacement.
Market Restraints
- Turbine Forging Capacity Concentration:Single-source dependency for nickel-based superalloy castings in the United States and United Kingdom creates supply vulnerability for turboprop hot section components.
- Battery Energy Density Ceiling:Lithium-ion cell performance below 300 Wh/kg restricts electric propulsion to sub-1,000 lb airframes, excluding the utility and regional transport segments that drive turbine margins.
- ICAO Carbon Offset Compliance Costs:CORSIA baseline adjustments impose incremental operating expenses on business jet fleets, compressing discretionary upgrade budgets for engine retrofits.
Strategic Opportunities
- Urban Air Mobility Infrastructure:Vertiport development in the United Arab Emirates and Saudi Arabia is creating demand for distributed electric propulsion systems rated under 500 kW.
- Remanufactured Powerplant Programs:Zero-time overhaul certification pathways offer margin expansion for independent engine shops serving the owner-flown piston market in Brazil and Australia.
- Hybrid-Electric Range Extenders:Series-hybrid architectures combining piston generators with electric motors are penetrating the European light aircraft segment where noise restrictions limit pure internal combustion operations.
Industry Challenges
- Powerplant-Airframe Integration Complexity:Electric propulsion thermal management requires coordination between battery OEMs, motor suppliers, and legacy airframe manufacturers lacking systems engineering heritage.
- Certificated Mechanic Shortage:FAA A&P schools are producing insufficient graduates trained in high-voltage electrical systems and composite propeller repair to support emerging fleet mixes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | General Aviation Engines Market |
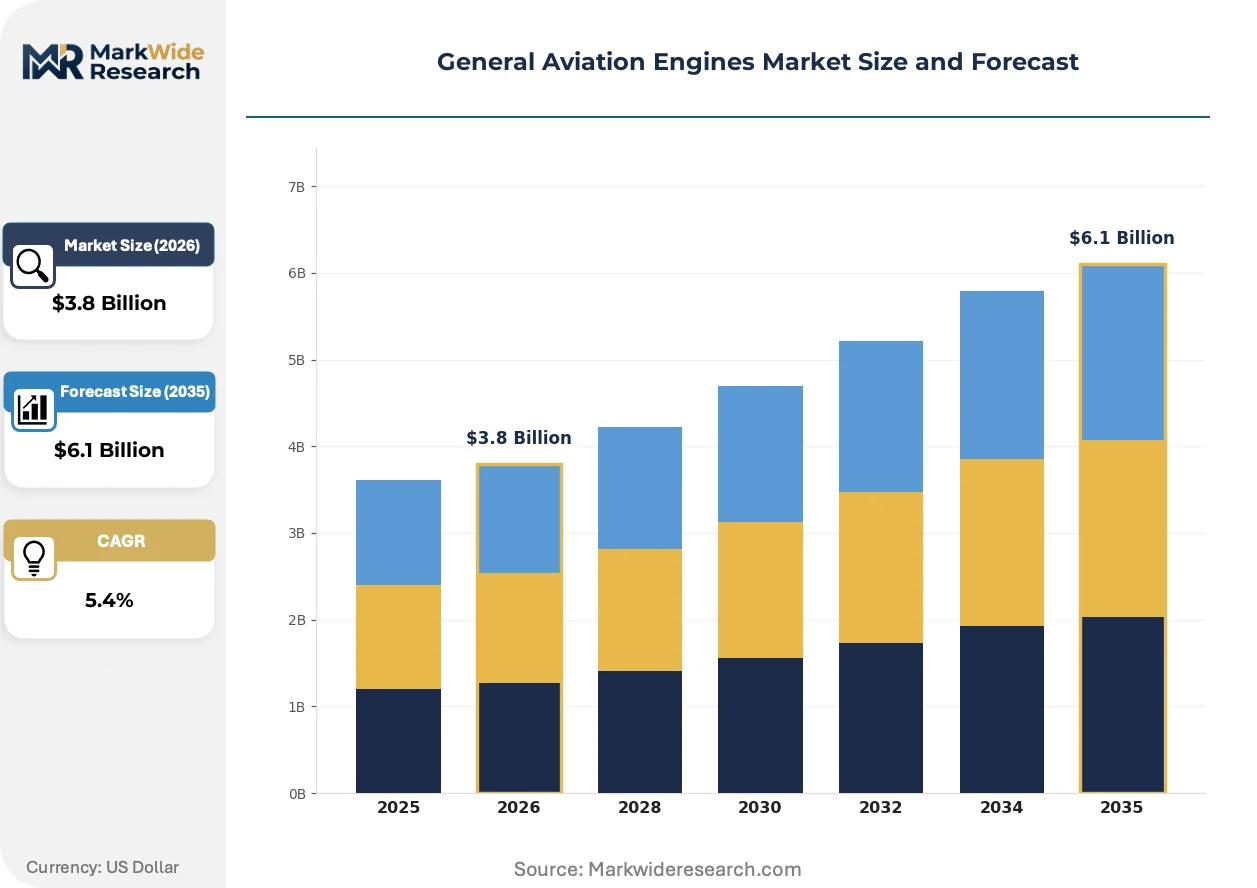
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Piston Engines, Turboprop Engines, Turboshaft Engines, Jet Engines, Electric Engines Technology: Fuel Injection, Turbocharging, Direct Drive, Reduction Gearbox, Hybrid Propulsion Application: Personal Aircraft, Flight Training, Air Taxi Services, Agricultural Aviation, Aerial Surveying End User: Flight Schools, Corporate Operators, Charter Services, Government Agencies, Private Owners |
| Companies Covered | Lycoming Engines, Continental Aerospace Technologies, Rotax Aircraft Engines, Pratt & Whitney Canada, Williams International, GE Honda Aero Engines, Safran Helicopter Engines, Honeywell Aerospace, MTU Aero Engines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
General Aviation Engines Market Strategic Shifts & Innovations
Distributed propulsion architectures and digital engine monitoring are compressing the traditional overhaul cycle while creating new aftermarket revenue pools for data-enabled service providers.
Hybrid-electric powertrains combining piston engines with electric boost motors is modularizing the propulsion supply chain, allowing airframe OEMs to source motors, controllers, and batteries from separate tier-one suppliers rather than single-source engine manufacturers. Flight schools in Germany and the Netherlands are piloting these systems for pattern work and circuit training where short-duration electric-only operation reduces fuel costs. This architecture is modularizing the traditional engine OEM monopoly over propulsion system design.
EASA CS-23 amendments aligning with FAA Part 23 reforms are creating harmonized certification pathways for electric and hybrid systems across European member states, reducing duplicate testing burdens for powerplant developers. The industrial consequence is accelerated technology transfer from automotive battery suppliers into aviation-qualified systems. Light sport and microlight categories in France and Italy are seeing the earliest adoption as national regulators exercise delegated authority for simplified approval.
Charter operators are unbundling engine maintenance from airframe management contracts, creating standalone power-by-the-hour offerings from independent MRO providers. This disintermediation threatens OEM service networks in the United States Part 135 segment where Texan and Floridian operators prioritize cost transparency over brand-authorized coverage. The shift is most visible among mid-size turboprop fleets where third-party prognostic systems now match factory diagnostic capability.
General Aviation Engines Market Segmentation
Segmentation in general aviation engines reveals how certification requirements, operational economics, and airframe integration demands fragment procurement decisions across customer types. Each dimension exposes different margin structures and technology adoption barriers that shape competitive positioning.
Product Type:
Piston engines carry the lightest certification burden under FAA Part 33 and EASA CS-E for reciprocating powerplants, while electric architectures face evolving airworthiness criteria still being harmonized across regulators.
- Piston Engines:Air-cooled and liquid-cooled reciprocating designs dominate the sub-400 horsepower category with proven reliability. Demand concentrates in United States flight schools replacing aging Lycoming and Continental fleets to reduce unscheduled maintenance and improve dispatch rates.
- Turboprop Engines:Free-turbine and fixed-shaft configurations deliver 500-2,000 shaft horsepower for utility and regional transport roles. Charter operators in Texas and Florida are expanding turboprop fleets for Part 135 operations where payload-range flexibility commands premium positioning.
- Turboshaft Engines:Optimized for helicopter applications with high torque density and rapid power response. Military and emergency medical services drive procurement through dedicated airframe programs.
- Jet Engines:Turbofan architectures rated under 4,000 pounds thrust serve personal aircraft and air taxi categories. FAA Part 33 certification timelines and hot-section inspection intervals constrain adoption economics.
- Electric Engines:Battery-electric and hydrogen fuel cell systems are penetrating light sport and experimental categories ahead of full Part 23 certification. ASTM standards for propulsion system airworthiness remain under development.
Leading the category by volume: Piston Engines. Growing fastest: Electric Engines.
Technology:
Technology segmentation tracks how propulsion architecture choices distribute manufacturing complexity, maintenance burden, and fuel efficiency gains across operator profiles.
- Fuel Injection:Electronic and mechanical fuel metering systems replace carbureted induction in modern piston engines. European training fleets in Germany and the Netherlands favor port fuel injection for reduced cold-start emissions and altitude compensation.
- Turbocharging:Exhaust-driven compressors restore sea-level power at altitude for high-elevation operations. Mountain flying schools and Rocky Mountain charter bases specify turbocharged powerplants for density altitude performance.
- Direct Drive:Crankshaft-connected propeller systems eliminate gearbox weight and failure modes in low-power applications. Owner-flown piston aircraft in Brazil and Australia prioritize mechanical simplicity for remote-area operations.
- Reduction Gearbox:Speed-reducing transmissions enable optimal propeller efficiency from high-rpm turbine and piston outputs. Turboprop integration programs specify gearbox architectures to match airframe noise certification requirements.
- Hybrid Propulsion:Series and parallel configurations combining thermal engines with electric motors are modularizing supply chains. EASA CS-23 alignment with FAA reforms is accelerating European light aircraft adoption where noise restrictions limit pure combustion operations.
Widest installed base: Direct Drive. Steepest expansion trajectory: Hybrid Propulsion.
Application:
Application segmentation maps how mission profiles dictate power-to-weight requirements, duty cycles, and regulatory operating environments.
- Personal Aircraft:Owner-flown piston singles and light twins prioritize acquisition cost and simplicity over speed. United States private owners in Texas and Florida dominate volume through recreational and business travel missions.
- Flight Training:High-cycle operations demand durable powerplants with predictable maintenance intervals. University aviation programs and Part 141 schools are modernizing fleets with fuel-injected alternatives to reduce downtime.
- Air Taxi Services:On-demand regional transport requires turbine reliability and weather capability. Urban air mobility developers are specifying distributed electric propulsion for vertiport operations in the United Arab Emirates and Saudi Arabia.
- Agricultural Aviation:Low-altitude, high-power operations stress cooling systems and air filtration. Brazilian aerial application fleets drive demand for robust piston and turboprop configurations.
- Aerial Surveying:Long-endurance, stable-platform missions favor fuel efficiency and low vibration. Geospatial contractors specify turbine powerplants for multi-sensor payload integration.
Highest cycle accumulation: Flight Training. Gaining share fastest: Air Taxi Services.
End User:
End user segmentation exposes how procurement authority, financing structures, and technical sophistication shape engine selection criteria and aftermarket engagement.
- Flight Schools:Institutional buyers with fleet-standardization mandates negotiate volume pricing and training support. United States university programs are consolidating around single-engine manufacturers to simplify parts logistics.
- Corporate Operators:Flight departments prioritize dispatch reliability and residual value protection. Business jet fleet renewal programs are expanding addressable markets for modern turbofan and turboprop offerings.
- Charter Services:Part 135 operators unbundle maintenance from airframe management, creating standalone power-by-the-hour demand. Texan and Floridian operators are driving third-party prognostic system adoption.
- Government Agencies:Federal, state, and local procurement follows sealed-bid processes with domestic content preferences. Law enforcement and firefighting missions specify turbine reliability for extended loiter operations.
- Private Owners:Individual purchasers balance acquisition cost against direct operating expense predictions. Owner-flown markets in Brazil and Australia sustain demand for remanufactured powerplant programs with zero-time overhaul certification.
Largest fleet aggregation: Flight Schools. Fastest procurement modernization: Charter Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engine manufacturing concentrates in North American and European industrial clusters while consumption spreads across flight training centers and charter bases worldwide. Foundry capacity for turbine hot-section components remains concentrated in legacy aerospace regions. Demand aggregation follows Part 135 operator density and university aviation program locations.
United States
Part 135 charter operators in Texas and Florida are expanding turboprop fleet renewals for payload-range flexibility. FAA Part 23 reforms compress certification timelines for hybrid-electric architectures targeting light sport categories. Wichita, Kansas hosts airframe-engine integration programs while Phoenix-area flight schools modernize piston fleets.
Germany
Flight training centers in Bavaria and Baden-Württemberg favor fuel-injected piston powerplants for reduced cold-start emissions compliance. EASA CS-23 alignment with FAA standards accelerates electric propulsion certification pathways. Stuttgart industrial clusters supply precision gearbox components for reduction-drive turboprop systems.
Brazil
Aerial application operators in São Paulo and Minas Gerais sustain demand for rugged piston and turboprop configurations. ANVISA-equivalent aviation regulatory frameworks govern agricultural aircraft type certification. Owner-flown markets drive remanufactured powerplant programs with zero-time overhaul certification pathways.
United Arab Emirates
Urban air mobility infrastructure investment in Dubai and Abu Dhabi creates demand for distributed electric propulsion under 500 kW. GCAA vertiport development guidelines shape airworthiness criteria for battery-electric systems. Emirates Flight Training Academy modernizes fleets with fuel-efficient turbine alternatives.
United Kingdom
Specialized turbine forging capacity for nickel-based superalloy castings supports global turboprop hot-section supply. CAA certification reciprocity with EASA maintains market access for European powerplant manufacturers. Cranfield aerospace clusters conduct hybrid-electric integration research for light aircraft applications.
General Aviation Engines Market Key Industry Players
The competitive structure tilts toward vertically integrated turbine specialists and modular piston engine suppliers. Foundry-dependent turboprop manufacturers defend positions through captive superalloy casting relationships. Three archetypes dominate: legacy airframe-integrated engine OEMs, independent powerplant specialists, and emerging electric propulsion developers. Consolidation activity concentrates in aftermarket service networks while technology licensing agreements proliferate for hybrid-electric architectures.
Among North American turbine and piston specialists, Lycoming Engines, Continental Aerospace Technologies, and Pratt & Whitney Canada exemplify contrasting strategic positions. Lycoming occupies a position anchored in flight training segment standardization. Continental represents backward integration into component manufacturing. Pratt & Whitney Canada sits within the turboprop integration tier serving regional OEM fleet agreements.
| Leading Market Players |
|---|
| Lycoming Engines |
| Continental Aerospace Technologies |
| Rotax Aircraft Engines |
| Pratt & Whitney Canada |
| Williams International |
| GE Honda Aero Engines |
| Safran Helicopter Engines |
| Honeywell Aerospace |
| MTU Aero Engines |
| Others |
Cost & Logistics Intelligence
Hybrid-electric propulsion development is fragmenting traditional engine-airframe bundling economics while concentrating battery cell sourcing decisions among automotive-qualified suppliers. This technology shift simultaneously compresses margins on legacy piston overhauls and creates new pricing power for electric motor integrators who control thermal management system design.
Pricing Analysis
Margin tightening in turboprop hot-section services reflects single-source dependency on nickel-based superalloy castings from United States and United Kingdom foundries. Three-tier pricing structure across certified new-production, factory-remanufactured, and independent overhaul segments tracks FAA certification pedigree and warranty coverage depth. Cost-down pressure on piston engine spare parts accelerates as flight schools consolidate fleet-standardization contracts around volume-discounted power-by-the-hour arrangements. Charter operators in Texas and Florida exhibit highest price sensitivity due to unbundled maintenance procurement, while corporate flight departments prioritize dispatch reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Wichita, Phoenix, and Stuttgart coordinate hub-and-spoke patterns for turbine hot-section components and precision gearbox subassemblies. Manufacturing gravity centers on United States, United Kingdom, and Germany for superalloy forgings, reduction drive systems, and fuel injection components. Raw material dependencies draw from cobalt-chrome alloys for turbine blades, lithium-ion cathode materials for electric architectures, and aviation-grade aluminum forgings for crankcase castings. Single-source vulnerability in nickel-based superalloy casting capacity creates supply risk for turboprop OEMs. Distribution runs through authorized service centers, independent MRO networks, and direct-to-operator parts programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
General aviation propulsion is transitioning from reciprocating dominance toward electrified architectures, with battery-electric and hybrid-electric systems displacing legacy piston engines in training and light sport categories.
For Market Incumbents: Acquire electric motor and power electronics design capabilities to defend installed base against automotive-tier suppliers entering aviation-qualified systems. Secure captive forging capacity for turbine hot-section components to mitigate single-source exposure in United States and United Kingdom superalloy castings. Deepen backward integration into battery management system software to maintain propulsion system integration authority. For New Entrants and Emerging Players: Enter via EASA CS-23 aligned certification pathways in Germany and the Netherlands where delegated authority accelerates electric propulsion approval for light sport categories. Target flight training segment replacement cycles at United States university aviation programs consolidating around fuel-injected alternatives. Pursue vertiport infrastructure partnerships in United Arab Emirates and Saudi Arabia for distributed electric propulsion under 500 kW. For Investors and Strategic Acquirers: Exit pathways concentrate in aftermarket service network roll-ups and hybrid-electric technology licensing to legacy airframe OEMs. Long-term viability favors vertically integrated powerplant specialists with captive superalloy supply and certificated mechanic training infrastructure. Watch FAA Part 33 certification timeline compression for electric propulsion as inflection signal for technology transfer velocity from automotive suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Certification Investment | FAA Part 23 reform alignment reduces approval timelines for hybrid-electric architectures targeting light sport categories. |
| Superalloy Forging Capacity Expansion | Captive nickel-based casting supply insulates turboprop OEMs from United States and United Kingdom foundry concentration risk. |
| Power-by-the-Hour Service Unbundling | Independent MRO prognostic systems match factory diagnostic capability for Texan and Floridian Part 135 operators. |
| Flight School Fleet Standardization Contracts | Volume pricing negotiations with university aviation programs consolidate parts logistics around single-engine manufacturers. |
| Vertiport Infrastructure Partnership | GCAA development guidelines in Dubai and Abu Dhabi shape airworthiness criteria for battery-electric distributed propulsion. |
Research Approach
Independent corroboration across OEM product development executives, Part 135 charter operations managers, FAA certification specialists, and independent MRO service directors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation through FAA type certificate databases, EASA CS-23 amendment tracking, ASTM propulsion standards development records, and university aviation program fleet procurement disclosures. Bottom-up triangulation across installed base estimates and top-down validation through powerplant production records ensure segmentation integrity.
Rate-of-change decomposition across the analysis window separates volume growth from mix-shift effects as electric architectures penetrate light sport categories ahead of full Part 23 certification. Segmentation dimensions modeled include product type, technology architecture, application mission profile, and end-user procurement authority. CAGRs derive from airframe delivery forecasts, engine replacement cycle analysis, and regulatory adoption curve assumptions for sustainable aviation fuel compatibility and electric propulsion certification.
Revisions become necessary when FAA Part 33 certification timeline assumptions shift, battery energy density trajectories deviate from projected improvement curves, or superalloy foundry capacity constraints intensify beyond current single-source dependency levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Engine Systems and Services
Global Aircraft Filter Market
Aircraft Engine Systems and Services
Turboprop Engine Market
Aircraft Engine Systems and Services
Aeroengine Accessory Drive Train Market
Aircraft Engine Systems and Services
Commercial Aircraft Engines Market
Aircraft Engine Systems and Services
Commercial Aircraft Gas Turbine Engine Market
Aircraft Engine Systems and Services
Aerospace Engine Mounts Market
Aircraft Engine Systems and Services
Global Aircraft Engine Fuel Systems Market
Aircraft Engine Systems and Services
Global Aircraft Engine Testbed Market
Aircraft Engine Systems and Services
Aviation Gas Turbine Market
Aircraft Engine Systems and Services
Middle-East and Africa Aircraft Engine Market
Aircraft Engine Systems and Services
Turbofan Engines Market
Aircraft Engine Systems and Services
Rocket Propulsion Systems Market
Aircraft Engine Systems and Services
Asia-Pacific Aircraft Engine Market
Aircraft Engine Systems and Services
Aircraft Engine Blade Market
Aircraft Engine Systems and Services
Aero Engine Coatings Market
Aircraft Engine Systems and Services
Helicopter Engine Market