
 Airport Operations Market | 2026-2036
Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Operations Market Analysis
Middle Eastern airport infrastructure expansion is rewriting competitive benchmarks for throughput capacity and passenger experience. Aéroports de Paris leverages its integrated hub model to sustain premium retail and transfer traffic dominance at Charles de Gaulle. Fraport AG Frankfurt Airport Services Worldwide anchors German aviation connectivity through its balanced cargo-passenger mix and extensive ground handling specialization.
Airport operations encompass the coordinated management of aircraft movements, passenger processing, baggage systems, and ground support activities governed by ICAO standards and national aviation regulations, with core performance measured by aircraft turnaround times and slot utilization rates. The primary purpose is ensuring safe, efficient, and commercially viable air transport throughput. Ground handling services generate the most labor-intensive revenue pools, while automated check-in systems represent the fastest technology upgrade cycle as airports reduce counter staffing. Baggage handling systems command concentrated capital investment due to their direct impact on passenger satisfaction metrics and operational delay reduction.
The FAA enforces NextGen avionics and surface management mandates that reshape US airport technology procurement timelines and interoperability requirements. EASA's safety management system regulations and the EU Green Deal aviation emissions framework jointly pressure European operators toward electrified ground fleets and carbon reporting infrastructure. Stakeholders must weigh regulatory compliance timelines against technology vendor lock-in risks as digitalization accelerates across operational functions.
Market Dynamics
Airport operators face intensifying pressure from the FAA's NextGen modernization mandates, which compress procurement timelines while forcing interoperability upgrades across incompatible legacy systems. This regulatory acceleration is restructuring vendor relationships and capital allocation priorities throughout the sector.
Growth Catalysts
- NextGen Surface Management Mandates:The FAA's trajectory-based operations requirements are forcing synchronized investments in collaborative decision-making platforms across US hub airports.
- Biometric Passenger Processing:Facial recognition boarding gates are cutting passenger touchpoints by eliminating document checks, driving terminal redesigns at high-volume facilities.
- India:The country's PLI scheme for airport infrastructure is channeling capital toward greenfield developments and brownfield automation retrofits.
Market Restraints
- Copper and Semiconductor Supply Volatility:Baggage handling system manufacturers face input cost spikes from constrained chip foundry capacity and electrified motor winding materials.
- Ground Handling Labor Pool Concentration:Germany's KBA-certified training bottlenecks limit licensed personnel availability, capping service expansion at Frankfurt and Munich hubs.
- ICAO Annex 14 Compliance Burden:Runway safety area extensions require land acquisition that encounters municipal opposition, freezing expansion timelines at constrained urban airports.
Strategic Opportunities
- Saudi Arabia:The Kingdom's giga-project airport developments are specifying fully automated baggage systems and AI-powered predictive maintenance from greenfield construction phases.
- Hydrogen Ground Fleet Conversion:The EU Green Deal aviation emissions framework is creating first-mover advantages for operators electrifying pushback tugs and belt loaders ahead of mandate deadlines.
- Digital Twin Convergence:Integration of IoT sensor networks with building information modeling is enabling real-time capacity optimization that static master plans cannot match.
Industry Challenges
- Certified Aviation Cybersecurity Personnel Scarcity:The FAA's emerging cybersecurity directives for critical airport systems outpace qualified workforce availability, delaying system hardening programs.
- Legacy ASR-11 Radar Integration:Surface surveillance systems must interface with decades-old primary radar infrastructure, creating data latency and false-alarm management burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Operations Market |
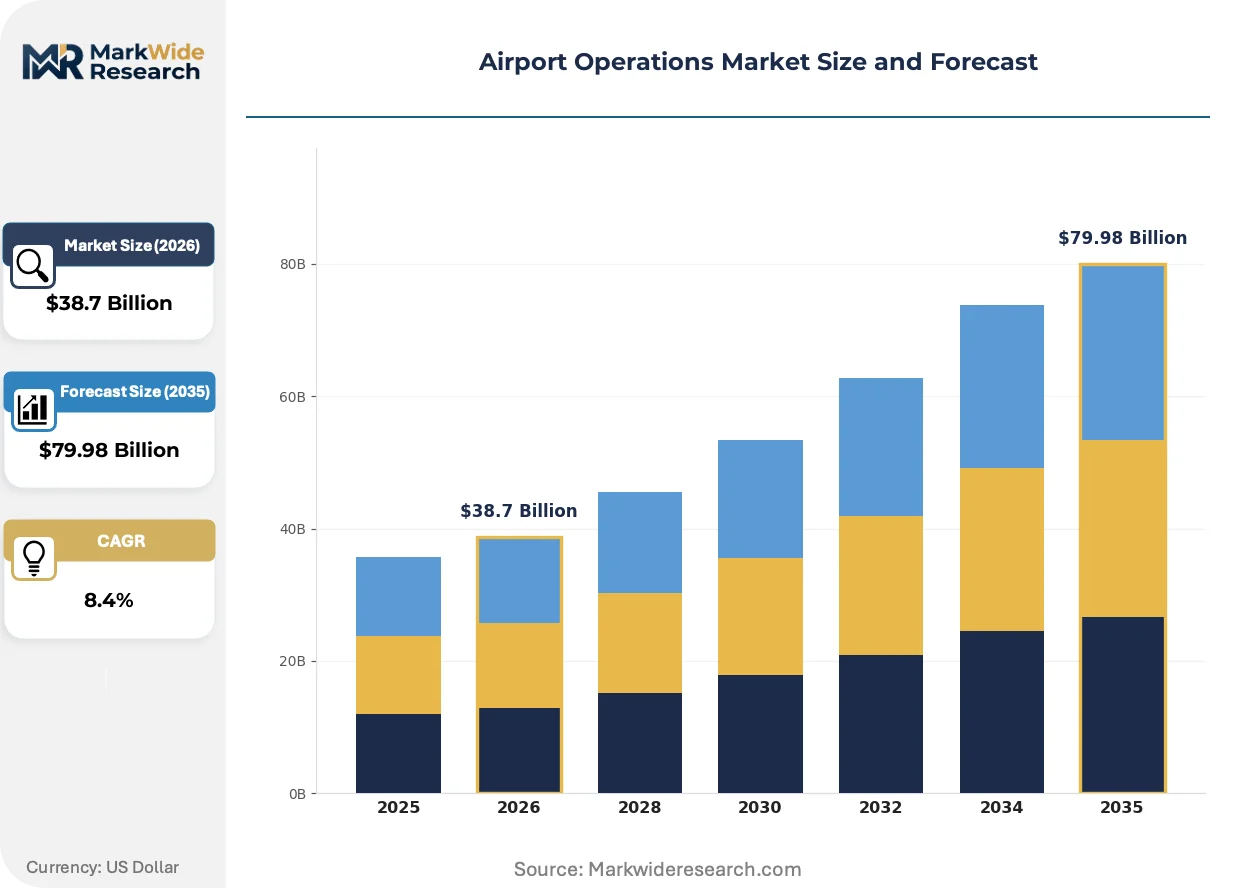
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Air Traffic Control, Security Services, Maintenance Services Technology: Automated Check-in Systems, Baggage Handling Systems, Runway Safety Systems, Surveillance Technologies End User: Airlines, Airports, Ground Handling Companies, Security Agencies Operational Function: Passenger Services, Cargo Services, Maintenance Operations, Security Operations |
| Companies Covered | Airports of Thailand Public Company Ltd, Aéroports de Paris, The Port Authority Of New York & New Jersey, Manchester Airport Group, Fraport AG Frankfurt Airport Services Worldwide, Aena S.M.E., SA, Grupo Aeroportuario del Pacífico, S.A.B. de C.V., Airport Corporation City of Taoyuan, AerCap Holdings N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Operations Market Emerging Trajectories
Digitalization is compressing traditional airport operational hierarchies, flattening decision-making structures while embedding predictive capabilities directly into frontline equipment. This structural reorganization is redistributing value capture from centralized command centers to distributed intelligent nodes.
Computer vision-based apron monitoring is collapsing the distinction between human traffic control and automated safety systems. Dallas-Fort Worth International and Denver International are deploying AI-enabled foreign object debris detection across active movement areas, eliminating dedicated visual inspection patrols. The technology is collapsing incident response times from minutes to seconds while reducing ground control staffing ratios.
The EU Green Deal aviation emissions framework is mandating carbon reporting infrastructure that extends to ground support equipment fleets. European hub operators must install telematics and fuel consumption tracking on every diesel-powered vehicle by 2027. German and French airports are responding fastest, integrating charging infrastructure planning into five-year capital programs.
Airlines are unbundling ground handling contracts from long-term exclusive agreements, fragmenting procurement across specialized providers. This disintermediation favors niche operators with single-service excellence over integrated incumbents. The Middle East is exhibiting the most aggressive contract restructuring, with Dubai and Abu Dhabi airports segmenting baggage, cargo, and passenger services into separate competitive tenders.
Airport Operations Market Segmentation
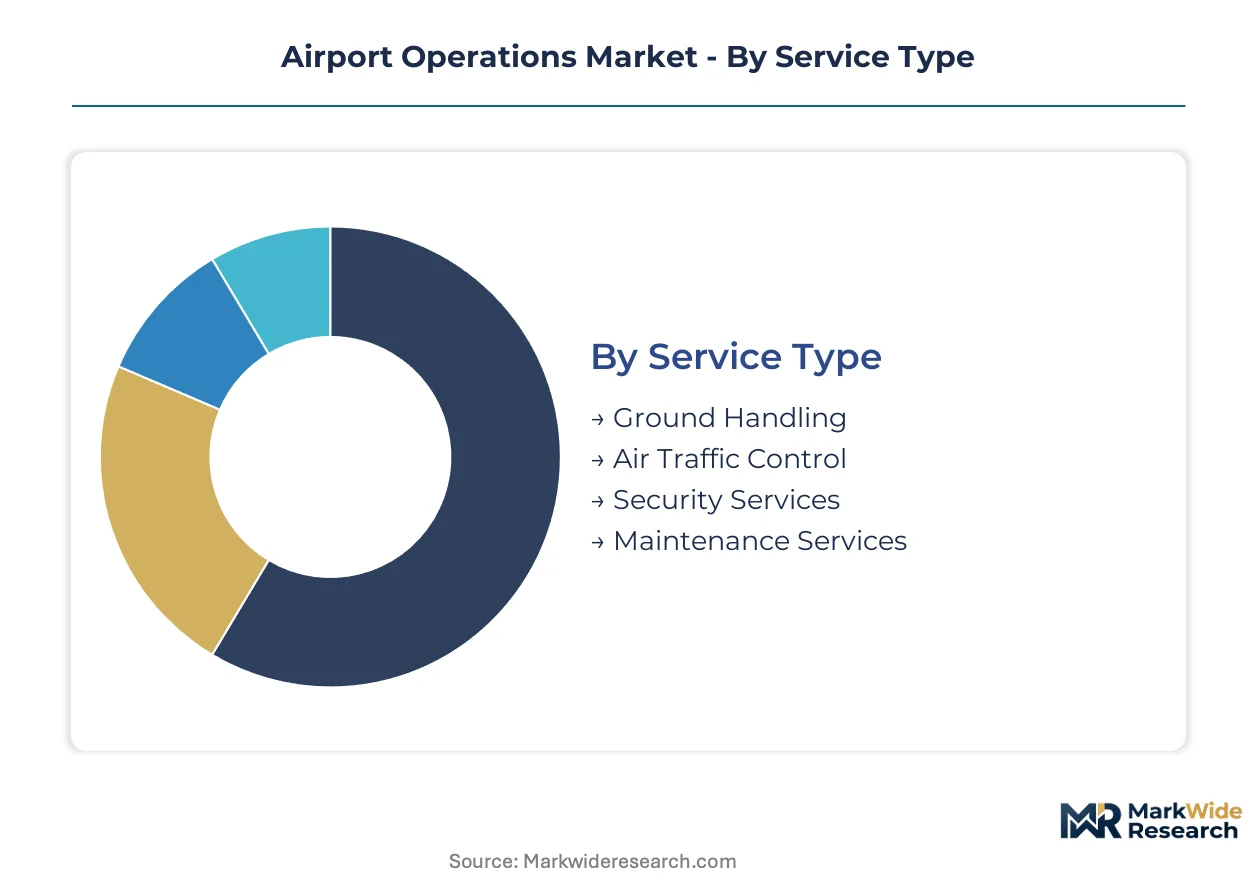
Airport operations segmentation reveals distinct capital intensity patterns across service delivery modes. Each category carries unique regulatory burdens and technology refresh cycles that determine vendor profitability and contract duration.
Service Type:
After-sales service intensity varies sharply across operational functions, with maintenance contracts extending decades while ground handling relies on continuous labor redeployment.
- Ground Handling:Aircraft servicing, baggage transport, and passenger boarding coordination executed through labor-intensive crews and specialized equipment fleets. Demand concentrates at Frankfurt and Dubai hubs where KBA-certified training bottlenecks constrain licensed personnel availability, capping service expansion.
- Air Traffic Control:Tower-based separation management and approach sequencing governed by FAA NextGen trajectory mandates and EASA safety management regulations. United States hub airports are synchronizing investments in collaborative decision-making platforms to meet surface management deadlines, compressing procurement timelines.
- Security Services:Passenger and cargo screening, access control, and perimeter monitoring.
- Maintenance Services:Infrastructure upkeep, equipment calibration, and facility lifecycle management.
Ground Handling holds the largest share; momentum sits with Air Traffic Control as modernization mandates accelerate.
Technology:
Capital deployment patterns divide between front-end passenger touchpoint automation and back-end safety-critical infrastructure requiring regulatory certification.
- Automated Check-in Systems:Self-service kiosks, mobile boarding pass validation, and biometric facial recognition gates eliminating document checks. Dallas-Fort Worth and Denver International are deploying these systems to cut passenger processing touchpoints, driving terminal redesigns at high-volume facilities.
- Baggage Handling Systems:Conveyor networks, automated sorting, and RFID tracking infrastructure commanding concentrated capital investment. Manufacturers face input cost spikes from constrained semiconductor foundry capacity and copper winding material volatility.
- Runway Safety Systems:Surface surveillance, incursion prevention, and lighting control.
- Surveillance Technologies:Video analytics, perimeter detection, and AI-enabled foreign object debris monitoring.
Baggage Handling Systems absorb the heaviest capital allocation; Automated Check-in Systems are expanding most quickly as airports reduce counter staffing.
End User:
Procurement authority fragmentation creates divergent vendor relationships across direct operators, contracted service providers, and regulatory agencies.
- Airlines:Direct purchasers of ground handling and passenger processing services, increasingly unbundling long-term exclusive contracts into segmented competitive tenders.
- Airports:Infrastructure owners specifying integrated operations platforms and master technology systems.
- Ground Handling Companies:Specialized operators competing on single-service excellence rather than bundled offerings.
- Security Agencies:Government-directed screening mandates with standardized equipment procurement protocols.
Airports retain capital deployment authority; Ground Handling Companies are gaining procurement influence through contract restructuring.
Operational Function:
Revenue stability differs between passenger-facing services with demand volatility and cargo operations with contract-backed throughput guarantees.
- Passenger Services:Terminal operations, check-in processing, and gate management with direct correlation to flight schedule reliability.
- Cargo Services:Freight handling, cold chain logistics, and warehouse coordination anchored by long-term airline contracts.
- Maintenance Operations:Scheduled infrastructure upkeep and emergency repair dispatch.
- Security Operations:Continuous screening deployment with regulatory compliance reporting obligations.
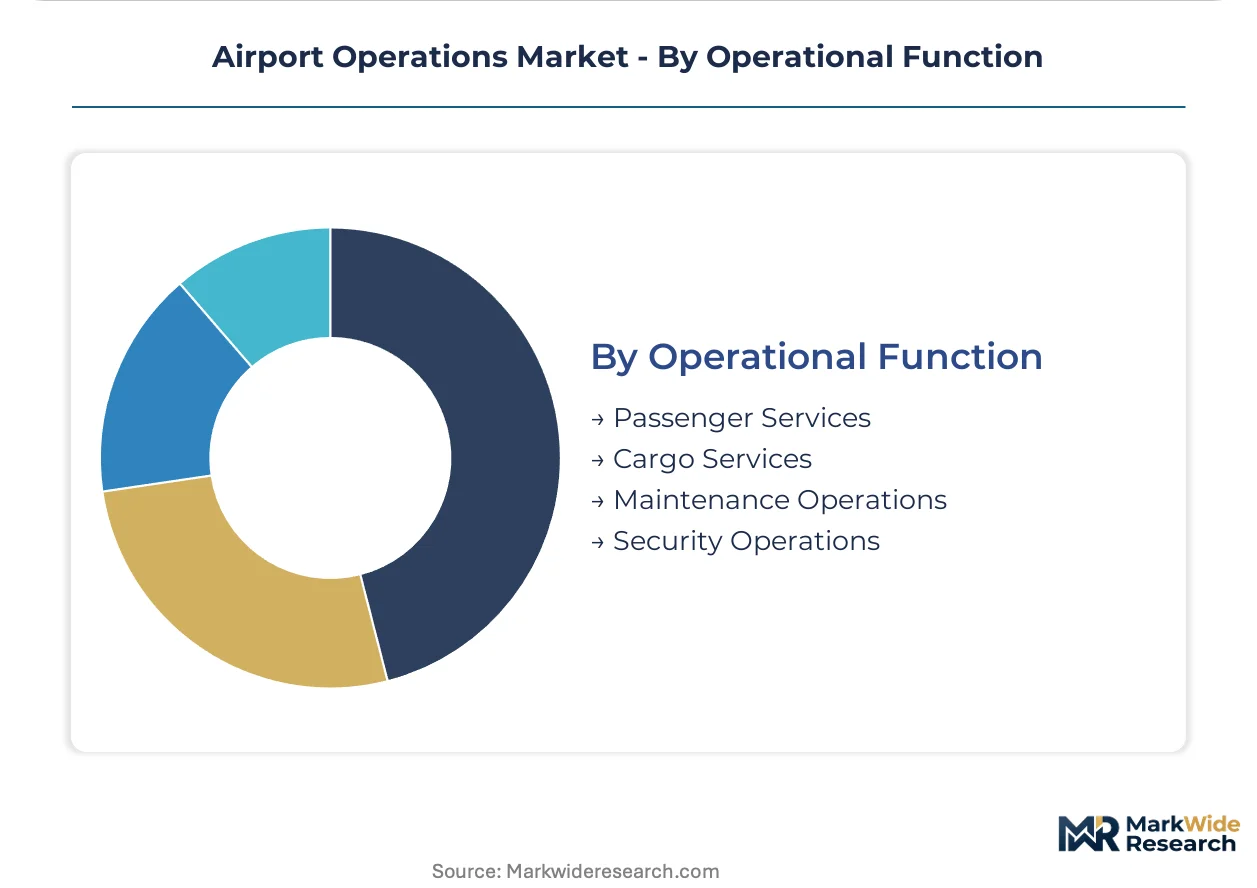
Passenger Services generates the highest revenue volume; Cargo Services demonstrates the steadiest expansion trajectory as e-commerce freight volumes climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FAA's NextGen modernization program anchors technology deployment timelines across the United States, while EASA's safety management regulations and the EU Green Deal reshape European capital allocation priorities.
United States
Hub airports in Dallas-Fort Worth and Denver are deploying AI-enabled foreign object debris detection across active movement areas. The FAA enforces trajectory-based operations requirements that compress procurement timelines for collaborative decision-making platforms. Surface surveillance system upgrades at Chicago O'Hare and Atlanta Hartsfield-Jackson are synchronizing investments to meet NextGen surface management mandates.
Germany
Frankfurt and Munich hubs face licensed personnel constraints from KBA-certified training bottlenecks that cap ground handling service expansion. EASA safety management system regulations pressure operators toward electrified ground fleets and carbon reporting infrastructure. The balanced cargo-passenger mix at Frankfurt anchors German aviation connectivity through extensive ground handling specialization.
Saudi Arabia
The Kingdom's giga-project airport developments are specifying fully automated baggage systems and AI-powered predictive maintenance from greenfield construction phases. National aviation expansion programs channel capital toward throughput capacity benchmarks that rewrite regional competitive standards. Riyadh and Jeddah developments concentrate demand for integrated operations platforms.
India
The country's PLI scheme for airport infrastructure is channeling capital toward greenfield developments and brownfield automation retrofits. Greenfield airports in Noida and expansions at Delhi and Mumbai drive demand for passenger processing efficiency technologies. The national regulator's infrastructure incentives are accelerating digital adoption timelines.
France
Aéroports de Paris leverages its integrated hub model to sustain premium retail and transfer traffic dominance at Charles de Gaulle. The EU Green Deal aviation emissions framework mandates carbon reporting infrastructure extending to ground support equipment fleets by 2027. Paris-Charles de Gaulle and Orly concentrate investment in terminal redesigns for biometric passenger processing.
Airport Operations Market Vendor Landscape
Integrated hub operators and specialized ground handling providers split the market across distinct value capture models. The competitive structure tiers between premium hub managers with retail-anchored revenue streams and scale-driven handlers competing on throughput efficiency. Two archetypes dominate: integrated airport groups bundling property, retail, and operations; and specialized service contractors unbundling functions into competitive tenders. Dominant competitive moves include contract restructuring to fragment procurement across single-service providers and greenfield automation specification from construction phases.
Within the integrated hub tier, Aéroports de Paris and Fraport AG Frankfurt Airport Services Worldwide exemplify the balanced cargo-passenger mix and extensive ground handling specialization model. Among Asia-Pacific operators, Airports of Thailand Public Company Ltd and Airport Corporation City of Taoyuan occupy positions within high-growth corridor development. The Port Authority Of New York & New Jersey represents the multi-jurisdictional hub governance structure prevalent in major US metropolitan markets.
| Leading Market Players |
|---|
| Airports of Thailand Public Company Ltd |
| Aéroports de Paris |
| The Port Authority Of New York & New Jersey |
| Manchester Airport Group |
| Fraport AG Frankfurt Airport Services Worldwide |
| Aena S.M.E., SA |
| Grupo Aeroportuario del Pacífico, S.A.B. de C.V. |
| Airport Corporation City of Taoyuan |
| AerCap Holdings N.V. |
| Others |
Supply Flow & Price Mechanics
The Frankfurt-Dubai air freight corridor's cost volatility exposes how concentrated semiconductor sourcing compresses margins for baggage handling OEMs while forcing three-tier pricing stratification across premium automation, standard conveyor, and economy retrofit tiers.
Pricing Analysis
Geographic price spreads between German and Indian procurement markets exceed forty percent for equivalent baggage handling modules. Contract-based long-term offtake dominates, with price differentiation hinging on FAA NextGen certification tier and after-sales service bundling. Cost compression in economy retrofits is intensifying because copper and semiconductor input volatility forces manufacturers to absorb margin erosion. Regional airport authorities exhibit highest price sensitivity; Middle Eastern greenfield developers show least sensitivity due to sovereign-backed capital allocation.
Supply Chain Analysis
Contract manufacturing for automated check-in kiosks concentrates in Taiwan, South Korea, and Mexico, with Foxconn and Jabil holding dominant EMS capacity for biometric terminal hardware. Raw material dependencies span silicon wafers, rare-earth magnets for drive motors, and aviation-grade aluminum extrusions. Single-source vulnerability in semiconductor foundry capacity poses structural risk given TSMC's concentration of automotive-grade chip production. Distribution runs through direct OEM-airport procurement relationships and tier-1 systems integrators like Siemens and Vanderlande.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Middle Eastern sovereign wealth vehicles consolidate greenfield airport procurement into multi-billion dollar integrated platform tenders, fragmenting vendor access and forcing specialization.
For Market Incumbents: Build regulatory certification moats by accelerating FAA NextGen surface management compliance ahead of mandate deadlines. Incumbents must secure exclusive maintenance contracts for automated baggage systems to lock out emerging robotics specialists, while adding captive semiconductor inventory buffers to offset foundry allocation volatility. For New Entrants and Emerging Players: India's brownfield automation retrofit market offers the most penetrable entry point given PLI scheme subsidies and fragmented municipal airport governance. New entrants should lead with AI-powered predictive maintenance software rather than hardware, licensing through local ground handling joint ventures to bypass capital-intensive equipment manufacturing. For Investors and Strategic Acquirers: Niche cybersecurity specialists for aviation-critical systems represent the priority acquisition archetype given FAA's emerging directives and certified personnel scarcity. Long-term viability hinges on exposure to regulatory-mandated upgrade cycles rather than discretionary capital expenditure. Watch for NextGen surface management deadline acceleration as the inflection signal indicating procurement timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| NextGen Compliance Acceleration | FAA trajectory mandates force synchronized hub investments in collaborative decision-making platforms. |
| Biometric Platform Integration | Dallas-Fort Worth and Denver deployments validate facial recognition boarding at high-volume terminals. |
| Backward Integration into Semiconductors | Baggage OEMs secure automotive-grade chip allocation through direct foundry partnerships. |
| Hydrogen Ground Fleet Conversion | EU Green Deal deadlines create first-mover advantage for electrified pushback equipment at Frankfurt. |
| Predictive Maintenance Software Licensing | Saudi giga-projects specify AI-powered systems from greenfield construction phases. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airport operations directors, ground handling fleet managers, FAA NextGen implementation leads, and biometric systems procurement officers at major US and Middle Eastern hubs. Secondary validation drew from FAA NextGen implementation reports, EASA safety management system filings, EU Green Deal aviation emissions tracking disclosures, and airport authority capital expenditure budgets. Bottom-up equipment shipment data and top-down infrastructure investment flows were triangulated to reconcile market sizing.
Calibration against historical procurement cycles and regulatory mandate timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, technology tier, operational function, and end-user procurement authority, with additional granularity on regulatory compliance cluster. CAGRs were derived from equipment replacement cycle analysis and infrastructure investment elasticity to passenger throughput growth. Forecast inputs incorporated semiconductor lead time volatility and certified aviation cybersecurity personnel availability constraints.
Practitioners should monitor FAA NextGen deadline acceleration, EU Green Deal enforcement tightening, and Middle Eastern sovereign liquidity shifts for early signals of procurement timeline compression or capital allocation redirection. Forecasts reflect assumptions on regulatory schedule adherence and input cost stabilization. Quarterly review of foundry capacity allocation announcements and airport authority budget revision filings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Europe Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
France Airport Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Aircraft Ground Handling System Market