
 Canada Airport Operations Market | 2026-2036
Canada Airport Operations Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Airport Operations Market Insights
Low-cost carriers is rotating toward larger gate allocations and longer-term use agreements at secondary terminals, displacing legacy network carriers that previously held preferential lease structures. Toronto Pearson Airport Authority leverages its slot coordination dominance to sustain premium landing fee structures during peak hours. Vancouver International Airport Authority anchors trans-Pacific cargo flows through specialized cold-chain facilities. Calgary Airport Authority differentiates with dedicated general aviation terminals that compete directly with Edmonton International Airport for energy-sector charter demand.
Canada airport operations encompass the integrated management of airside and landside functions including runway utilization scheduling, terminal passenger processing, baggage handling throughput, and ground support equipment deployment, all governed by Transport Canada aerodrome standards and ICAO Annex 14 specifications for pavement classification numbers and obstacle limitation surfaces. The primary commercial purpose centers on maximizing aircraft movement efficiency while maintaining CAT III precision approach minima for all-weather operations. Passenger services generates the largest revenue pool across service type categories, though cargo handling exhibits the fastest structural expansion driven by e-commerce fulfillment networks. Biometric systems within the technology dimension attracts disproportionate capital allocation as airports replace legacy document verification checkpoints with facial recognition corridors.
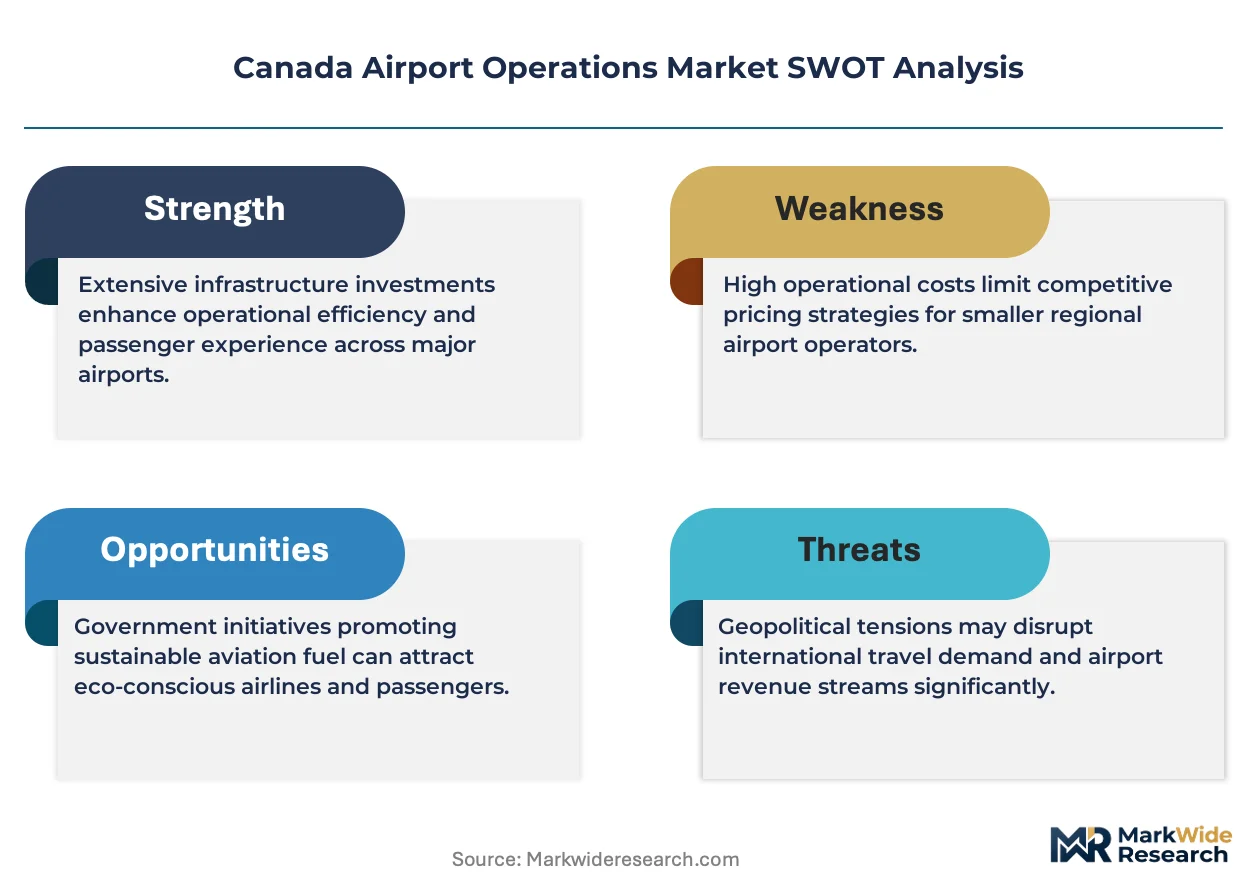
Transport Canada enforces aerodrome certification under Canadian Aviation Regulations, while Nav Canada manages instrument flight procedure design and airspace classification that directly determines runway capacity ceilings. The Canadian Air Transport Security Authority mandates screening technology refresh cycles that reshape procurement priorities for terminal operators. Stakeholders must monitor pending amendments to CARs Part III that could impose new wildlife hazard management obligations with significant grassland remediation costs.
Market Dynamics
Nav Canada modernization mandates are compressing technology procurement timelines across Canadian airport authorities, forcing simultaneous upgrades to air traffic management systems and terminal security infrastructure.
Growth Catalysts
- CAT III Precision Approach Mandates:Transport Canada aerodrome standards are requiring enhanced all-weather landing capabilities at primary hubs, driving runway lighting and instrument landing system investments.
- E-commerce Fulfillment Networks:Specialized cold-chain cargo facilities at Vancouver International and Toronto Pearson are expanding dedicated freighter apron capacity for temperature-sensitive pharmaceutical and perishable goods.
- Biometric Corridor Deployment:Canadian Air Transport Security Authority screening technology refresh cycles are accelerating facial recognition checkpoint installations at CATSA-designated airports.
Market Restraints
- Wildlife Hazard Management Costs:Pending amendments to Canadian Aviation Regulations Part III could impose grassland remediation obligations with significant ongoing maintenance expenditures.
- Slot Coordination Concentration:Toronto Pearson Airport Authority's dominance in peak-hour landing fee structures limits competitive pricing flexibility for secondary carriers.
- Ground Support Equipment Electrification:Battery-powered GSE conversion requires substantial capital outlay with limited domestic supplier availability for heavy-duty electric tugs.
Strategic Opportunities
- Secondary Terminal Gate Reallocation:Low-cost carriers are negotiating longer-term use agreements at Billy Bishop and Calgary terminals previously held by legacy network carriers.
- General Aviation Terminal Differentiation:Calgary Airport Authority's dedicated energy-sector charter facilities create a template for capturing corporate aviation demand across Alberta's oil sands corridor.
- Trans-Pacific Cargo Hub Expansion:Vancouver International's specialized cold-chain infrastructure positions it for additional Asia-North America pharmaceutical routing.
Industry Challenges
- Air Traffic Controller Training Pipeline:Nav Canada instrument flight procedure design capacity is constrained by certified specialist availability, limiting runway throughput expansion.
- Legacy Baggage Handling Integration:Terminal operators face complex retrofit requirements when connecting new automated sortation systems to existing mechanical infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Airport Operations Market |
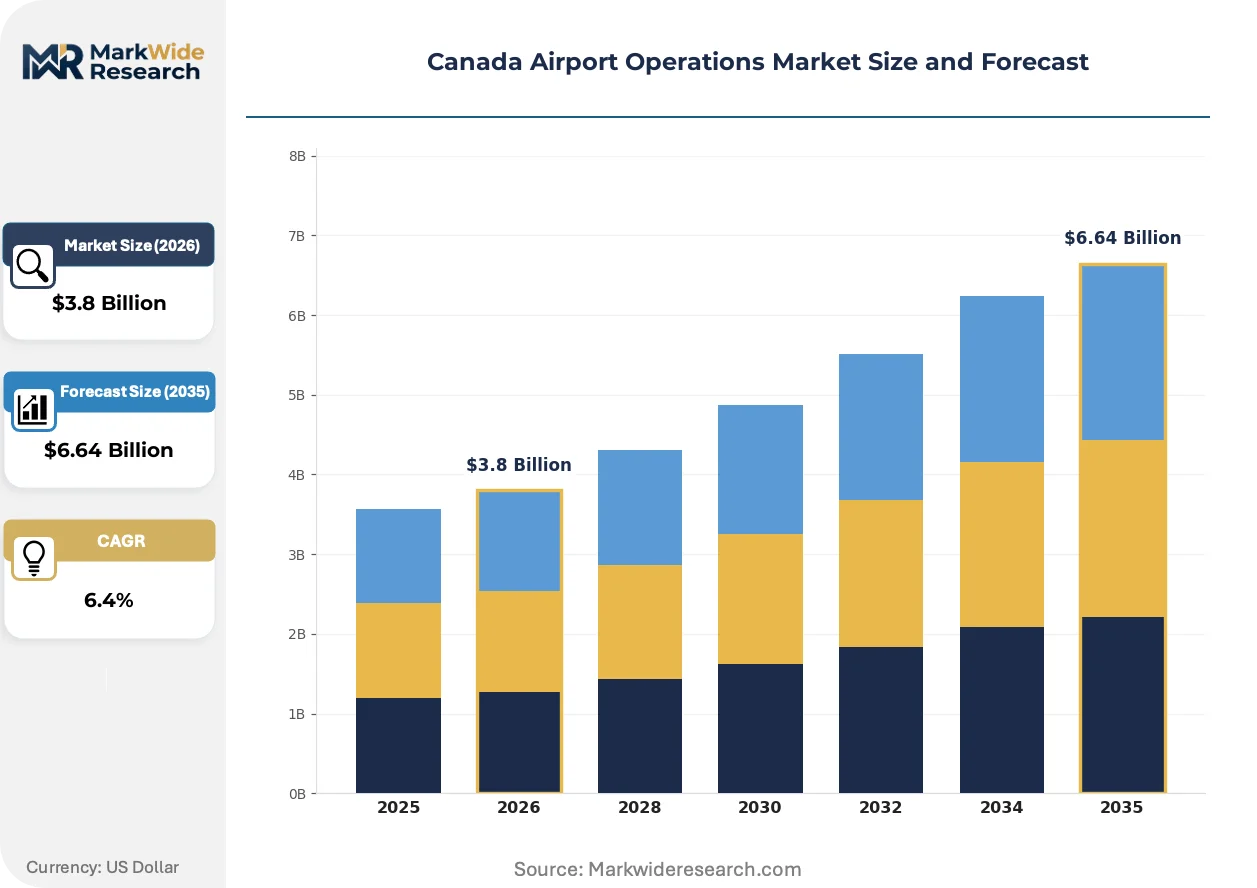
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Services, Cargo Handling, Ground Services, Maintenance Services Technology: Biometric Systems, Baggage Tracking, Self-Check-in Kiosks, Flight Information Displays End User: Airlines, Government Agencies, Ground Handlers, Travelers Application: Commercial Aviation, Military Operations, General Aviation, Freight Transport |
| Companies Covered | Calgary Airport Authority, Winnipeg James Armstrong Richardson International Airport, Toronto Pearson Airport Authority, Halifax Stanfield International Airport Authority, Ottawa Macdonald–Cartier International Airport Authority, Vancouver International Airport Authority, Edmonton International Airport, Greater Toronto Airports Authority, Montréal-Trudeau Airport Authority, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Airport Operations Market Trends and Innovations
Canadian airport operations are experiencing concentrated technology turnover as regulatory mandates and passenger processing demands converge on biometric and automation systems.
Facial recognition corridors are bifurcating passenger processing architecture at Canadian hubs. CATSA-mandated screening technology refresh cycles are accelerating adoption at Toronto Pearson and Vancouver International. This biometric infrastructure is bifurcating terminal design between legacy document-verification checkpoints and streamlined recognition-enabled pathways.
Transport Canada aerodrome certification under Canadian Aviation Regulations is tightening wildlife hazard management protocols. The industrial consequence is mandatory grassland remediation and perimeter fencing upgrades at airports with significant bird strike risk. Secondary hubs in the Prairie provinces face the steepest compliance cost exposure as they retrofit older airfield layouts.
Energy-sector charter demand patterns are rotating toward dedicated general aviation terminals. Calgary Airport Authority's specialized facilities are displacing traditional FBO models for oil sands corporate travel. This behavioral shift concentrates most visibly in Alberta, where flight departments prioritize apron proximity and customs pre-clearance over main terminal amenities.
Canada Airport Operations Market Segmentation
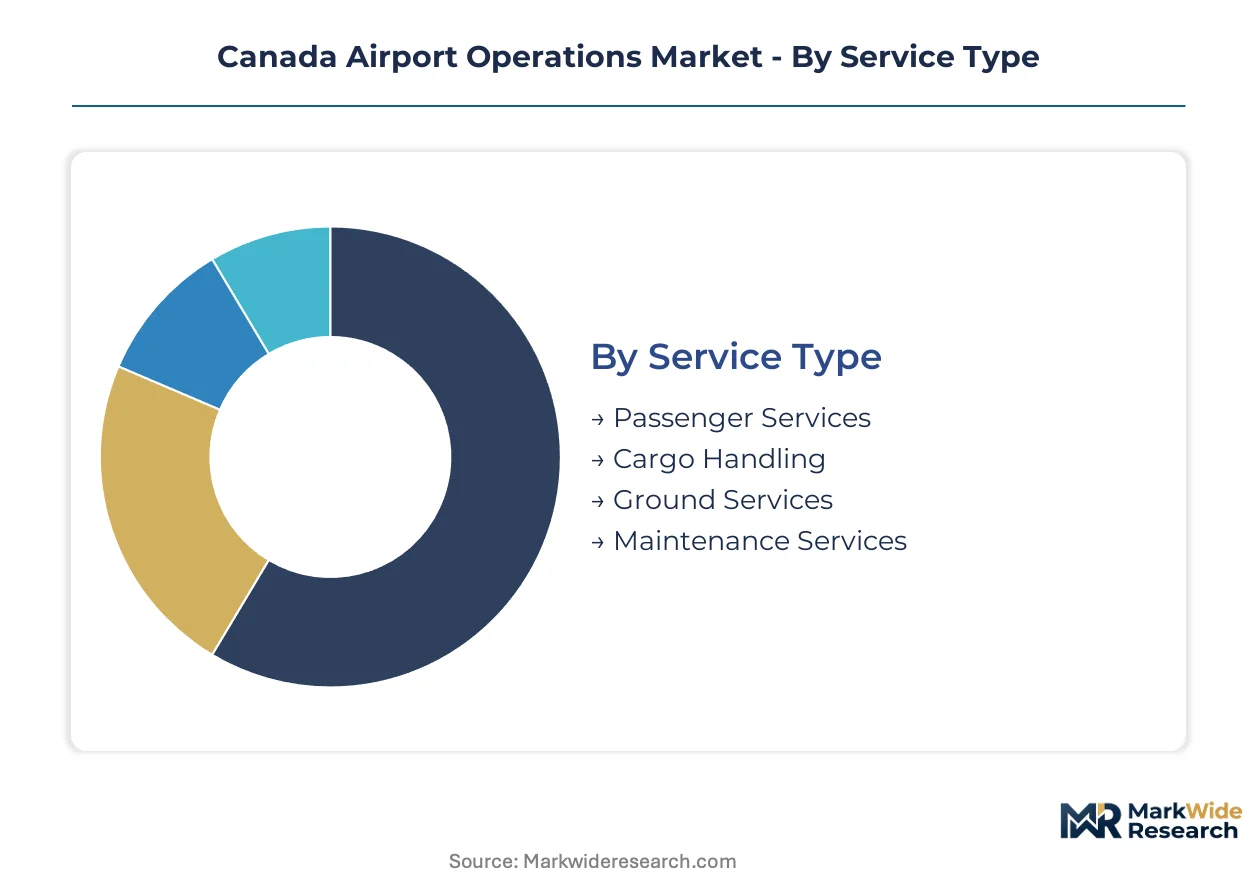
Segmentation in Canadian airport operations reveals distinct procurement patterns across service tiers and technology layers. Transport Canada certification requirements and Nav Canada airspace mandates create divergent investment priorities between passenger-facing and cargo-focused facilities.
Service Type:
Domestic demand concentrates at Toronto Pearson and Vancouver International for full-service contracts, while secondary hubs in Alberta and the Prairie provinces drive specialized cargo and maintenance procurement.
- Passenger Services:Terminal processing functions including check-in, security screening, and gate management dominate revenue composition at CATSA-designated facilities. Toronto Pearson and Billy Bishop anchor demand for premium passenger experience upgrades, pressured by low-cost carrier expansion into formerly legacy-held terminal space.
- Cargo Handling:Cold-chain infrastructure for pharmaceutical and perishable goods drives specialized apron investments at Vancouver International. Trans-Pacific e-commerce fulfillment networks are compressing turnaround time requirements for dedicated freighter operations.
- Ground Services:Aircraft marshalling, fueling, and de-icing operations serve all carrier categories with seasonal volatility in Prairie provinces.
- Maintenance Services:Runway pavement classification assessments and instrument landing system calibration follow Transport Canada aerodrome certification cycles.
Passenger Services commands the established base. The steepest expansion runs through Cargo Handling.
Technology:
Capital allocation splits between regulatory-mandated security infrastructure and carrier-driven efficiency systems, with biometric deployment receiving disproportionate funding at primary hubs.
- Biometric Systems:Facial recognition corridors replace document-verification checkpoints under CATSA screening technology refresh mandates. Toronto Pearson and Vancouver International lead deployment, creating bifurcated terminal architectures between legacy and streamlined pathways.
- Baggage Tracking:Automated sortation integration with legacy mechanical infrastructure creates complex retrofit requirements at older terminals. Calgary and Edmonton face the steepest system replacement challenges.
- Self-Check-in Kiosks:Common-use terminal equipment reduces airline-specific counter requirements at secondary facilities.
- Flight Information Displays:Digital signage networks integrate with Nav Canada air traffic management data feeds for real-time gate assignment updates.
Biometric Systems captures the dominant capital share. Baggage Tracking faces the most complex integration pathway.
End User:
Procurement authority fragments between airport authorities owning infrastructure and carriers or government agencies specifying operational standards.
- Airlines:Network carriers and low-cost operators negotiate terminal use and landing fee structures, with the latter displacing legacy preferential lease agreements at Billy Bishop and Calgary.
- Government Agencies:Transport Canada aerodrome certification, CATSA security mandates, and Nav Canada airspace design collectively determine technology procurement timelines and compliance costs.
- Ground Handlers:Third-party service providers compete for contracts at facilities lacking in-house capabilities, particularly at secondary Prairie hubs.
- Travelers:Passenger experience expectations indirectly drive biometric corridor and self-service technology adoption through carrier competitive positioning.
Government Agencies sets the compliance boundary. Airlines generate the most volatile contract flow.
Application:
Facility specialization separates commercial passenger hubs from cargo-dominant and general aviation operations, with military requirements concentrated at specific installations.
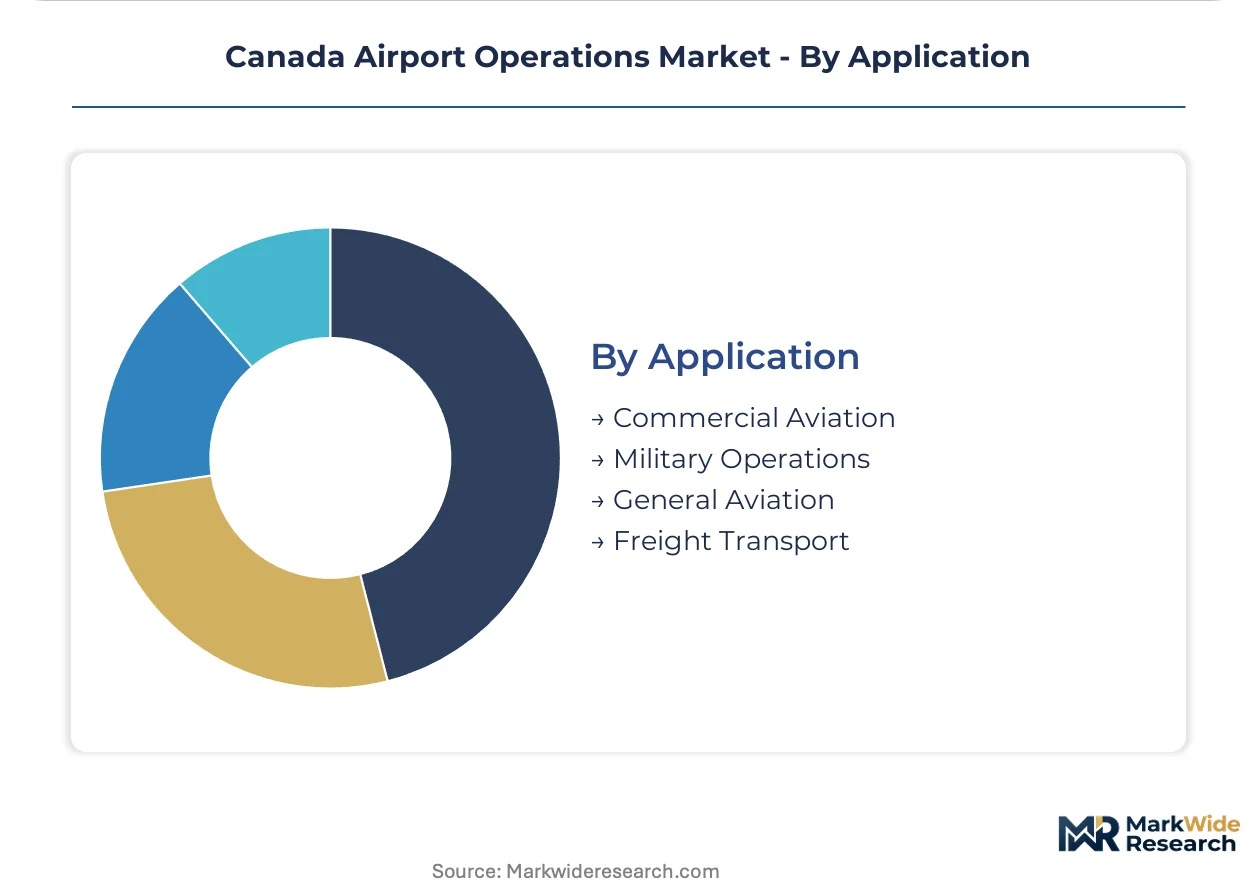
- Commercial Aviation:Scheduled passenger and cargo operations at Transport Canada-certified aerodromes generate the core revenue base. Toronto Pearson's slot coordination dominance sustains premium pricing during peak hours.
- General Aviation:Corporate charter and energy-sector travel concentrates at Calgary's dedicated terminals, competing directly with Edmonton International for Alberta oil sands corridor demand.
- Military Operations:Royal Canadian Air Force facility requirements follow Department of National Defence specifications separate from civilian certification.
- Freight Transport:Dedicated freighter apron capacity expands at Vancouver International for Asia-North America pharmaceutical routing.
Commercial Aviation anchors the revenue foundation. General Aviation is climbing the fastest on energy-sector demand rotation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada exports airport operations expertise and infrastructure services primarily to the United States, where cross-border charter demand and integrated cargo networks sustain bilateral traffic flows through Toronto Pearson and Vancouver International corridors.
Ontario
Toronto Pearson Airport Authority manages the dominant share of international passenger volume through Greater Toronto, where slot coordination dominance sustains premium landing fee structures during peak hours. Transport Canada aerodrome certification requirements and Nav Canada airspace mandates compress technology procurement timelines across the province's primary hub.
British Columbia
Vancouver International Airport Authority anchors trans-Pacific cargo flows through specialized cold-chain facilities serving pharmaceutical and perishable goods routing. CATSA-mandated screening technology refresh cycles accelerate biometric corridor deployment at the province's primary gateway.
Alberta
Calgary Airport Authority differentiates with dedicated general aviation terminals competing directly with Edmonton International for energy-sector charter demand across the oil sands corridor. Pending amendments to Canadian Aviation Regulations Part III could impose wildlife hazard management obligations with significant grassland remediation costs.
Quebec
Montréal-Trudeau Airport Authority processes transatlantic passenger flows while navigating bilingual service requirements and federal procurement standards. The province's aerospace manufacturing cluster generates corporate aviation demand that feeds general aviation terminal utilization.
Atlantic Canada
Halifax Stanfield International Airport Authority manages seasonal volatility in passenger traffic while serving as the eastern gateway for transatlantic cargo. Transport Canada security directives reshape terminal infrastructure investment priorities across the region's secondary hubs.
Canada Airport Operations Market Competitive Landscape
Listed airport authorities compete with private ground handlers across service contract allocation, creating a tiered structure where infrastructure owners retain premium revenue streams while outsourcing operational functions. The market consolidates around three strategic archetypes: large-hub authorities with slot coordination dominance, mid-tier regional operators with cargo specialization, and general aviation terminal specialists capturing corporate charter demand. Competitive moves center on terminal gate reallocation negotiations and biometric infrastructure partnerships with security technology vendors.
Among Canadian airport authorities, Calgary Airport Authority and Vancouver International Airport Authority exemplify the specialization archetype through dedicated facility strategies, while Toronto Pearson Airport Authority anchors the scale-driven tier with dominant international passenger volume.
| Leading Market Players |
|---|
| Calgary Airport Authority |
| Winnipeg James Armstrong Richardson International Airport |
| Toronto Pearson Airport Authority |
| Halifax Stanfield International Airport Authority |
| Ottawa Macdonald–Cartier International Airport Authority |
| Vancouver International Airport Authority |
| Edmonton International Airport |
| Greater Toronto Airports Authority |
| Montréal-Trudeau Airport Authority |
| Others |
Pricing and Supply Chain Analysis
Ninety-day procurement cycles for biometric screening hardware compress supplier negotiation windows while amplifying Toronto Pearson's volume-based purchasing leverage against secondary Prairie hubs. This lead-time compression concentrates pricing power with Nav Canada-certified systems integrators who control facial recognition corridor deployments across CATSA-mandated facilities.
Pricing Analysis
Next-generation biometric corridor systems command substantial premiums over legacy document-verification checkpoints, while prior-generation mechanical baggage sortation trades at distressed valuations amid retrofit obsolescence. Contract-based long-term service agreements dominate, with price differentiation driven by Transport Canada certification tier and after-sales maintenance bundling. Cost compression in standard-tier ground support equipment intensifies as battery-electric conversion mandates strain limited domestic supplier capacity. Low-cost carriers exhibit acute price sensitivity on terminal use agreements, whereas full-service network carriers absorb premium gate allocations at Billy Bishop and Pearson.
Supply Chain Analysis
Inventory buffers for instrument landing system components stretch to 120 days given single-source dependencies on specialized Nav Canada-approved manufacturers. Supply concentrates in the United States, Germany, and Japan for precision approach lighting and air traffic management hardware, with raw material dependencies spanning rare-earth phosphors, aviation-grade aluminum alloys, and specialized optical sensors. Tariff exposure on Chinese-sourced LED modules creates procurement vulnerability for runway lighting retrofits. Distribution runs through authorized Nav Canada systems integrators with exclusive territorial servicing rights.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified air traffic controller shortages and biometric systems engineering gaps constrain expansion velocity across Canadian hubs, creating asymmetric returns for stakeholders who secure scarce technical capabilities before regulatory mandates tighten further.
For Market Incumbents: Fortify slot coordination dominance at Toronto Pearson through preemptive gate lease renegotiations before low-cost carriers consolidate secondary terminal positions. Deepen backward integration into ground support equipment electrification by acquiring Alberta-based battery systems specialists, insulating against supplier concentration risk as Transport Canada emissions directives harden. For New Entrants and Emerging Players: Lead with specialized wildlife hazard management services targeting Prairie province airports facing Canadian Aviation Regulations Part III remediation mandates. The most penetrable white-space sits in automated grassland monitoring systems for secondary hubs outside CATSA-designated facilities. Pursue direct contracting relationships with Calgary and Edmonton airport authorities bypassing established environmental services incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Transport Canada certification requirements and Nav Canada airspace design authority create structural moats around incumbent technology providers. Acquisition targets should display dual competencies in biometric integration and legacy mechanical system retrofitting. Watch Nav Canada training pipeline graduation rates as the inflection signal for runway throughput expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Corridor Deployment | CATSA-mandated screening refresh cycles accelerate facial recognition adoption at Toronto Pearson and Vancouver International terminals. |
| Cold-Chain Cargo Expansion | Vancouver International's specialized pharmaceutical facilities anchor trans-Pacific e-commerce fulfillment network growth. |
| General Aviation Terminal Differentiation | Calgary Airport Authority's energy-sector charter facilities capture corporate travel demand across Alberta's oil sands corridor. |
| Wildlife Hazard Management Compliance | Pending CARs Part III amendments force grassland remediation investments at Prairie province secondary hubs. |
| Ground Support Equipment Electrification | Battery-powered conversion mandates strain domestic supplier capacity for heavy-duty electric tugs at Canadian airports. |
Research Methodology
The analysis maps passenger services, cargo handling, ground services, and maintenance procurement patterns, each validated through airport authority procurement directors, CATSA technology implementation leads, Nav Canada airspace design specialists, and ground handling contract managers. Primary intelligence combined with Transport Canada regulatory filings, Nav Canada instrument procedure databases, CATSA screening technology refresh schedules, and airport authority financial disclosures. Bottom-up contract flow analysis triangulated against top-down infrastructure investment tracking.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type tier, technology generation, end-user procurement authority, and application facility specialization. CAGRs derived from infrastructure investment pipeline analysis and regulatory mandate implementation timelines, incorporating Nav Canada modernization spending forecasts and Transport Canada aerodrome certification cycle data.
The analysis sits within stated boundaries; outcomes outside sustained Nav Canada funding authorization or Transport Canada regulatory enforcement intensity would require recalibration. Forecasts reflect documented assumptions regarding low-cost carrier terminal share expansion and biometric technology adoption curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
UK Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
Middle East Airport Ground and Cargo Handling Services Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Business Jet Ground Handling Services Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Global Air Charter Services Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
France Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Airport Operations Market