
 Middle East Airport Ground and Cargo Handling Services Market | 2026-2036
Middle East Airport Ground and Cargo Handling Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Airport Ground and Cargo Handling Services Market Insights
Freight forwarder demand is shifting toward integrated cargo-to-gate solutions as e-commerce volumes surge through Dubai and Jeddah hubs. Dnata leverages its multi-airport network across the UAE to sustain dominance in perishable and pharmaceutical cargo handling. Menzies Aviation anchors its position through long-term contracts with full-service carriers at expanding Saudi gateways. Çelebi Aviation competes by specializing in narrow-body turnaround efficiency at secondary Turkish-influenced markets.
Middle East airport ground and cargo handling services encompass the physical processing, documentation, and technical support functions required for aircraft turnarounds, passenger boarding, baggage flow, and freight movement on airport ramps and in terminals. These operations rely on specialized equipment including aircraft ground power units, cargo loaders with 35-tonne lift capacity, and belt loaders engineered for containerized unit load devices. Passenger handling and cargo handling segments lead revenue contribution as pilgrimage traffic and pharmaceutical cold-chain exports expand across the region. Ramp services represent the fastest-growing category as Saudi Arabia's airport privatization program introduces competition at previously single-handler facilities. The technology dimension, particularly RFID baggage tracking and automation in sortation systems, sits at the center of margin improvement efforts as labor costs rise.
The UAE's General Civil Aviation Authority enforces aerodrome safety standards that mandate equipment certification and handler training protocols, directly shaping operator compliance costs and market entry barriers. Saudi Arabia's General Authority of Civil Aviation implements privatization frameworks that restructure ground handling concessions and open historically protected routes to competitive bidding. Stakeholders must monitor how GACA's concession re-tendering schedule and GCAA's advancing automation mandates reshape partnership structures between airlines, handlers, and technology providers.
Market Dynamics
Saudi Arabia's airport privatization program is dismantling single-handler monopolies at Riyadh and Jeddah, injecting competitive tendering into ground handling concessions previously shielded from rivalry.
Growth Catalysts
- Pharmaceutical cold-chain exports:Temperature-sensitive cargo volumes from UAE and Saudi Arabia are expanding as regional biologics manufacturing scales up, requiring specialized handling infrastructure.
- GCAA aerodrome safety mandates:The UAE's stricter equipment certification protocols are forcing handler consolidation, raising barriers that favor established operators with capital reserves.
- E-commerce logistics integration:Freight forwarders across the Gulf Cooperation Council are adopting cargo-to-gate solutions to manage surging parcel volumes through Dubai and Jeddah hubs.
Market Restraints
- Specialized equipment import dependency:35-tonne cargo loaders and aircraft ground power units rely on European and East Asian manufacturers, exposing handlers to currency volatility and extended lead times.
- Labor cost inflation:Ramp services and passenger handling face wage pressure as Saudi Arabia's Saudization policies and UAE residency reforms tighten workforce availability.
- Single-airport revenue concentration:Secondary market handlers in Oman and Bahrain remain dependent on one facility, limiting diversification against traffic fluctuations.
Strategic Opportunities
- NEOM Air infrastructure greenfield:Saudi Arabia's new carrier at the Red Sea megaproject offers first-mover ground handling contracts without incumbent displacement costs.
- RFID baggage tracking mandates:GCAA's advancing automation requirements create technology upgrade cycles where handlers can bundle hardware and service contracts.
- Perishable agriculture exports:Egypt and Jordan are expanding fresh produce air freight, opening cargo handling specialization beyond oil-state dominance.
Industry Challenges
- Certified aircraft dispatcher scarcity:Saudi Arabia's GACA-licensed personnel pool lags behind concession expansion timelines, delaying operational readiness at privatized airports.
- Legacy system integration friction:New automated sortation systems must interface with airline-specific departure control systems, extending deployment cycles and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Airport Ground and Cargo Handling Services Market |
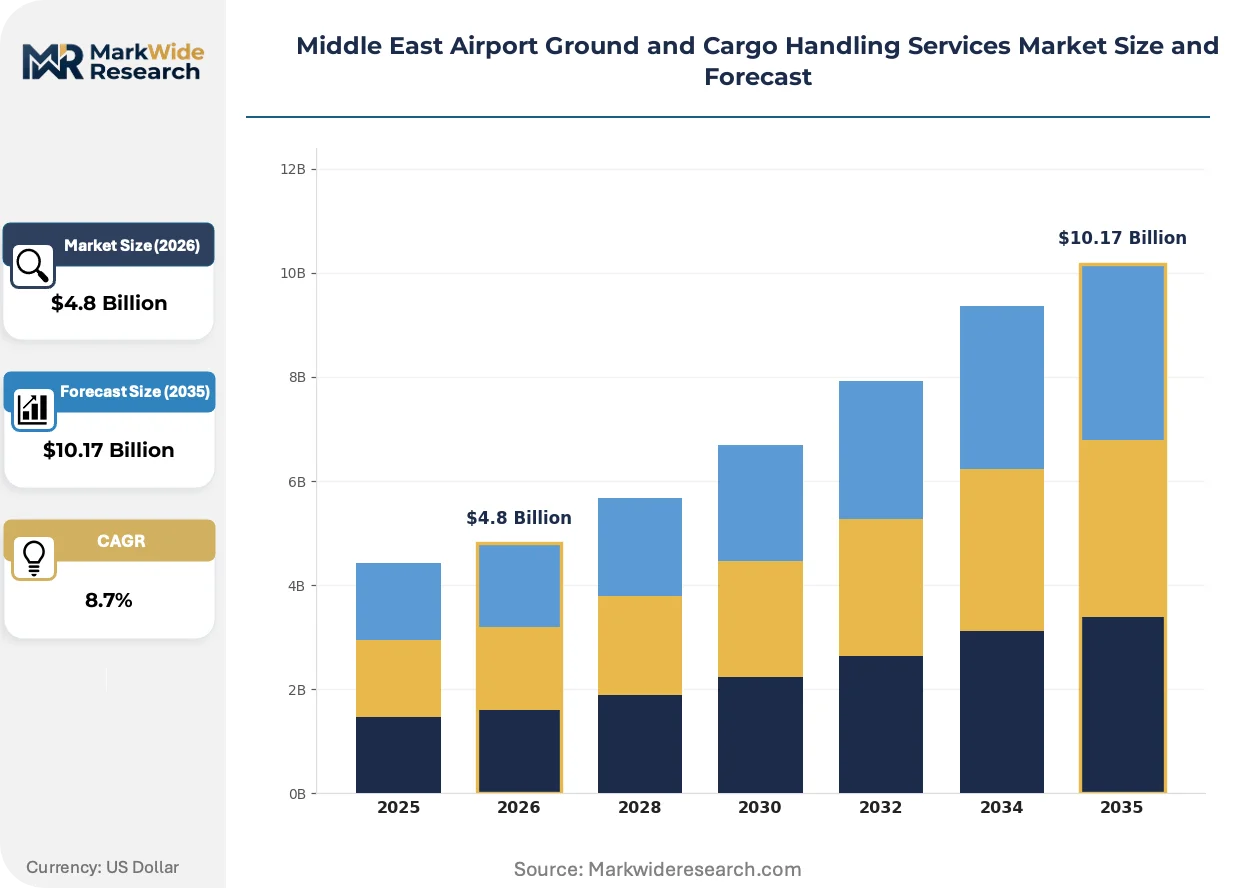
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Handling, Baggage Handling, Cargo Handling, Ramp Services End User: Airlines, Ground Handlers, Freight Forwarders, Government Agencies Technology: AIS, RFID, Automation, Mobile Apps Capacity: Small Airports, Medium Airports, Large Airports, International Airports |
| Companies Covered | Dnata, Havas Ground Handling Co., Çelebi Aviation, Menzies Aviation, Aviapartner, Worldwide Flight Services, Siemens AG, Cavotec SA, Alvest SAS, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Airport Ground and Cargo Handling Services Market Trends and Innovations
Automation and regulatory digitization are compressing turnaround times while raising capital thresholds for market participation. Three developments are reshaping competitive requirements.
Autonomous guided vehicles for baggage and cargo transport are consolidating material flow operations across major Gulf hubs. Dnata and Menzies Aviation are deploying these systems at Dubai International and King Abdulaziz International to reduce tarmac congestion. The technology is consolidating handler market share by requiring multi-million dollar capital commitments that exclude smaller regional competitors.
Saudi Arabia's General Authority of Civil Aviation is restructuring ground handling concessions through competitive re-tendering frameworks that break historical monopolies. The policy is fragmenting incumbent revenue streams while opening slots for specialized narrow-body operators. Secondary Saudi gateways like Taif and Hail are experiencing the most aggressive concession rotation as GACA tests auction mechanisms.
Airline procurement teams are bundling ground handling with cargo warehousing under multi-year integrated contracts. Full-service carriers at expanding Saudi hubs are displacing spot-rate spot purchasing with performance-guaranteed agreements. This consolidation is most visible in Riyadh, where Riyadh Air's launch specifications demand single-accountability handlers across passenger, ramp, and cargo functions.
Middle East Airport Ground and Cargo Handling Services Market Segmentation
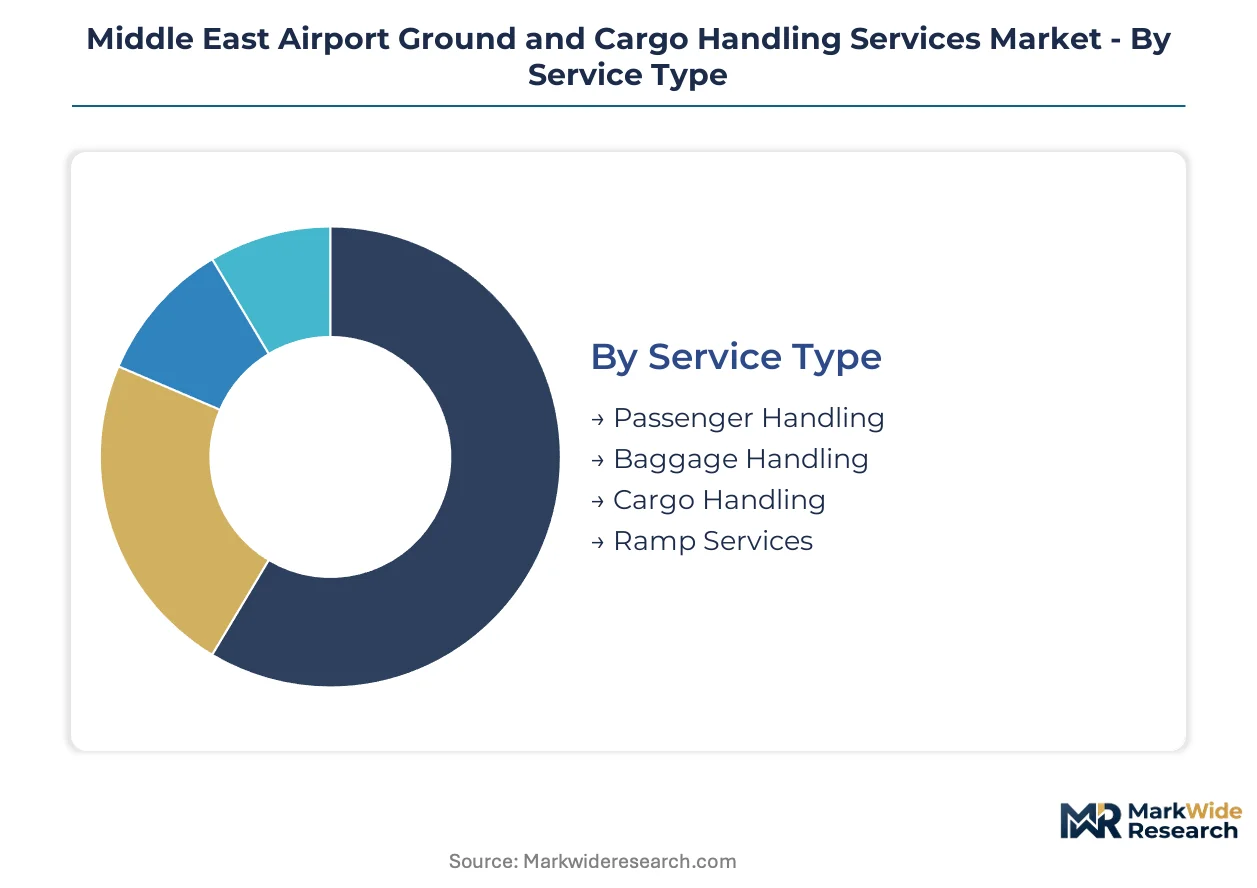
Segmentation in Middle East airport ground and cargo handling services reveals how service specialization, technology maturity, and airport scale create distinct operational and investment profiles. Handler procurement strategies diverge sharply across these dimensions, with integrated contracts favoring multi-service providers while technology mandates fragment vendor selection.
Service Type:
Standalone passenger and baggage functions operate independently at legacy facilities, while cargo and ramp services increasingly embed within unified terminal management systems.
- Passenger Handling:Encompasses check-in, boarding gate operations, and lounge management using departure control system interfaces. Demand concentrates at Saudi Arabia's expanding hubs as Riyadh Air and NEOM Air require full-service handlers capable of processing 12 million annual passengers per terminal. Labor intensity and Saudization compliance costs dominate margin structures.
- Cargo Handling:Covers freight acceptance, build-up/break-down, and cold-chain storage for temperature-sensitive pharmaceuticals. UAE biologics manufacturing expansion drives specialized infrastructure investment at Dubai International and Al Maktoum International, where handlers compete on IATA CEIV Pharma certification coverage.
- Baggage Handling:Sortation, transfer, and claim operations using conveyor networks and RFID tracking infrastructure. GCAA mandates for baggage tracking automation are accelerating system replacement cycles across Emirates and Etihad hub operations.
- Ramp Services:Aircraft marshalling, ground power provision, and pushback operations requiring GACA-licensed dispatchers. Saudi Arabia's airport privatization program is opening previously protected ramp concessions to competitive tender at King Abdulaziz International and King Khalid International.
Passenger handling leads volumes today; ramp services is gaining share fastest.
End User:
Cost tier differentiation separates price-sensitive government procurement from performance-guaranteed airline contracts with penalty clauses.
- Airlines:Full-service and low-cost carriers purchasing ground handling under multi-year agreements with service level agreements covering on-time performance and baggage mishandling rates. Saudi Arabia's new airline launches are consolidating procurement under single-accountability handlers.
- Ground Handlers:Subcontractors and specialized operators purchasing equipment, training, and technology licenses from upstream providers. Dnata and Menzies Aviation anchor this segment through vertical integration into equipment leasing and workforce certification programs.
- Freight Forwarders:Logistics intermediaries contracting cargo terminal services and last-mile connectivity. E-commerce volume surges through Dubai and Jeddah are shifting forwarder demand toward integrated cargo-to-gate solutions with real-time visibility.
- Government Agencies:Military, postal, and emergency services requiring dedicated handling protocols. UAE and Saudi government aviation departments maintain separate procurement frameworks with domestic preference requirements.
Airlines dominate contract value; freight forwarders are expanding procurement fastest.
Technology:
Application maturity varies from established AIS deployment to emerging mobile platforms still in pilot phases.
- AIS:Airport information systems integrating flight data, resource allocation, and passenger processing. Legacy installations at major Gulf hubs require continuous upgrade to interface with airline-specific departure control systems.
- RFID:Baggage and cargo tracking using passive and active radio-frequency identification tags. GCAA regulatory pressure is mandating airport-wide RFID infrastructure deployment, creating hardware and integration contract opportunities.
- Automation:Autonomous guided vehicles, automated sortation, and robotic cargo handling. Capital thresholds of multi-million dollar commitments are consolidating handler market share at Dubai International and King Abdulaziz International.
- Mobile Apps:Workforce dispatch, equipment status monitoring, and customer-facing tracking interfaces. Pilot deployments at secondary Saudi gateways are testing integration with legacy terminal operating systems.
AIS anchors installed base; automation is climbing the fastest.
Capacity:
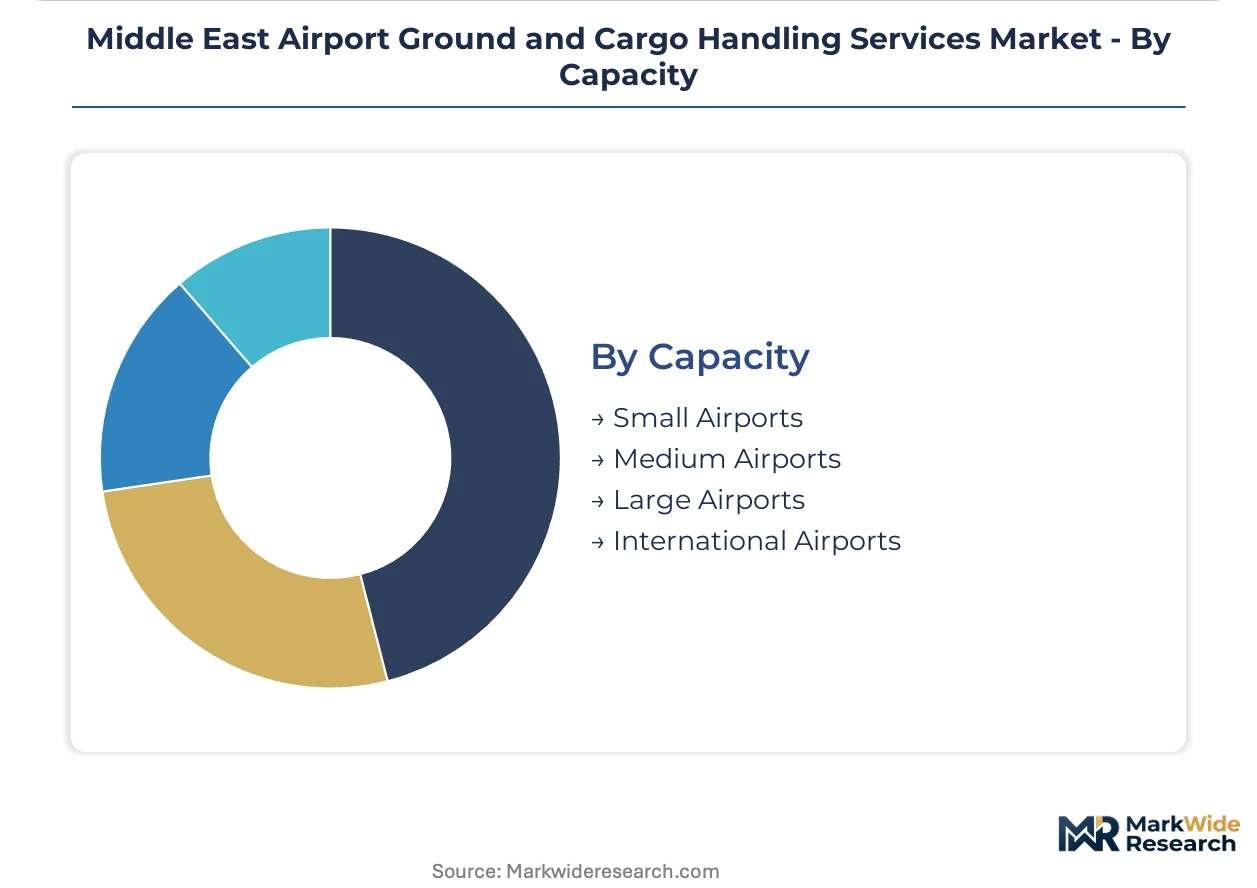
Volume scale determines equipment specification tiers, with international airports requiring 35-tonne cargo loaders unavailable at smaller facilities.
- Large Airports:Facilities processing over 25 million annual passengers with multi-terminal operations and dedicated cargo cities. Dubai International and King Abdulaziz International require handlers with network-scale resource deployment capabilities.
- International Airports:Cross-border hubs with customs integration, immigration processing, and wide-body aircraft stands. Saudi Arabia's privatization program is re-tendering ground handling concessions at this tier with competitive bidding replacing historical monopolies.
- Medium Airports:Secondary gateways handling 5-15 million passengers with mixed narrow-body and wide-body traffic. Taif and Hail in Saudi Arabia are experiencing aggressive concession rotation as GACA tests auction mechanisms.
- Small Airports:Regional and general aviation facilities with limited equipment pools and single-handler dependence. Oman and Bahrain secondary markets remain vulnerable to traffic fluctuation without diversification options.
Large airports command revenue concentration; international airports are expanding capacity fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai International Airport anchors the Middle East ground handling ecosystem, with its cargo throughput and passenger volumes dictating equipment specification tiers across the Gulf Cooperation Council.
United Arab Emirates
Dubai International and Al Maktoum International drive demand for 35-tonne cargo loaders and autonomous guided vehicle fleets. The General Civil Aviation Authority enforces aerodrome safety standards mandating equipment certification and RFID baggage tracking infrastructure. Abu Dhabi's Zayed International Airport is consolidating ground handling concessions under performance-guaranteed contracts with single-accountability providers.
Saudi Arabia
Riyadh Air and NEOM Air are commissioning full-service handlers capable of processing 12 million annual passengers per terminal. The General Authority of Civil Aviation is dismantling single-handler monopolies at King Abdulaziz International and King Khalid International through competitive re-tendering frameworks. Jeddah's King Abdulaziz International is experiencing the most aggressive concession rotation as GACA tests auction mechanisms.
Turkey
Istanbul Airport's expansion is generating demand for narrow-body turnaround efficiency specialists at secondary Turkish-influenced markets. The country's civil aviation authority is implementing stricter dispatcher licensing protocols that raise workforce certification barriers. Çelebi Aviation anchors operations at Istanbul and regional gateways through specialization in quick-turnaround narrow-body operations.
Egypt
Cairo International Airport is expanding perishable agriculture export handling capacity for fresh produce air freight to European markets. The national civil aviation regulator is introducing cold-chain certification requirements for pharmaceutical cargo transit. Alexandria and Luxor secondary airports remain dependent on single-handler arrangements without competitive tendering frameworks.
Qatar
Hamad International Airport sustains demand for premium passenger handling and pharmaceutical cold-chain infrastructure. The Qatar Civil Aviation Authority is aligning equipment certification standards with GCAA protocols to facilitate cross-border handler operations. Doha's cargo city is attracting specialized biologics handling investment as regional pharmaceutical manufacturing scales up.
Middle East Airport Ground and Cargo Handling Services Market Competitive Landscape
Concession re-tendering dominates the current landscape as Saudi Arabia's privatization program dismantles historical monopolies. The market structure is consolidating around three tiers: network-scale operators with multi-airport presence, specialized narrow-body turnaround providers, and equipment-integrated technology vendors. Strategic archetypes include integrated service bundlers, automation-focused capital deployers, and regional niche specialists. Competitive intensity centers on long-term contract capture and multi-million dollar automation commitments that exclude smaller regional competitors.
Among UAE-based integrated handlers, Dnata occupies a position exemplifying network-scale resource deployment across Dubai International and Al Maktoum International. Menzies Aviation represents the long-term contract anchor model at expanding Saudi gateways through full-service carrier relationships. Çelebi Aviation sits within the narrow-body specialization tier, serving Turkish-influenced secondary markets with turnaround efficiency focus. These three anchors illustrate how geographic coverage breadth, contract duration, and aircraft-type specialization define competitive positioning in the current concession rotation environment.
| Leading Market Players |
|---|
| Dnata |
| Havas Ground Handling Co. |
| Çelebi Aviation |
| Menzies Aviation |
| Aviapartner |
| Worldwide Flight Services |
| Siemens AG |
| Cavotec SA |
| Alvest SAS |
| Others |
Pricing and Supply Chain Analysis
Captive equipment leasing networks anchor handler pricing power across the Middle East, as Dnata and Menzies Aviation control 35-tonne cargo loader fleets that secondary operators cannot replicate without multi-million dollar capital commitments. This vertical integration into specialized ground support equipment creates tiered supplier relationships where network-scale handlers extract premium pricing from full-service carriers while spot-rate competition dominates fragmented ramp services.
Pricing Analysis
Input-cost pass-through from European and East Asian equipment manufacturers drives contract escalation clauses in multi-year ground handling agreements. Three-tier pricing structure across premium, standard, and economy levels separates CEIV Pharma-certified cold-chain handlers from general cargo operators and basic ramp service providers. Pricing pressure stems from Saudi Arabia's competitive re-tendering frameworks that fragment historical monopolies. Freight forwarders exhibit highest price sensitivity as e-commerce volumes compress margins, while full-service carriers prioritize performance guarantees over unit cost.
Supply Chain Analysis
GCAA and GACA equipment certification mandates gate supplier participation, restricting 35-tonne cargo loader and autonomous guided vehicle procurement to vendors meeting aerodrome safety protocols. Manufacturing concentrates in Germany, Japan, and South Korea for specialized ground power units and containerized loading systems. Supply chains rest on aviation-grade steel alloys and precision hydraulics vulnerable to extended lead times. Single-source vulnerability runs through OEM-exclusive service contracts. Distribution runs through handler-led equipment leasing consortia at Dubai International and King Abdulaziz International.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Middle East ground handling services hinges on automation-driven labor substitution as RFID baggage tracking mandates and autonomous vehicle deployment compress unit costs per turnaround. Premium-tier shifts toward integrated cargo-to-gate contracts reward handlers bundling passenger, ramp, and cargo functions under single-accountability structures.
For Market Incumbents: Lock in long-term concession renewals at Saudi Arabia's privatizing airports before GACA's auction mechanisms mature. Secure exclusive equipment leasing arrangements with European OEMs to raise capital barriers against emerging competitors. Vertical integration into GACA-licensed dispatcher training programs addresses certified personnel scarcity threatening operational readiness. For New Entrants and Emerging Players: Digital-channel route partnerships with e-commerce platforms offer white-space entry without incumbent displacement costs. Target perishable agriculture export corridors at Egypt's secondary airports where cold-chain specialization remains underdeveloped. Pursue narrow-body turnaround efficiency contracts at Taif and Hail as GACA tests competitive bidding frameworks. For Investors and Strategic Acquirers: Consolidation pressure builds where single-airport handlers in Oman and Bahrain face traffic fluctuation without diversification options. Five-to-ten year viability favors network-scale operators with multi-airport presence and automation capital deployment capability. Watch GACA's concession re-tendering schedule as inflection indicator for market structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Capital Deployment | Autonomous guided vehicle fleets at Dubai International consolidate handler market share through multi-million dollar barriers. |
| Concession Renewal Capture | Long-term contracts at Saudi Arabia's privatizing airports secure revenue visibility before competitive auction mechanisms expand. |
| Cold-Chain Certification Investment | IATA CEIV Pharma coverage at UAE biologics hubs differentiates pricing tiers for temperature-sensitive cargo handling. |
| Integrated Service Bundling | Single-accountability contracts across passenger, ramp, and cargo functions align with Riyadh Air procurement specifications. |
| Workforce Certification Programs | GACA-licensed dispatcher pipelines address personnel scarcity delaying operational readiness at privatized Saudi gateways. |
Research Methodology
Direct dialogue with ground handling operations directors, airline procurement executives, GACA concession managers, and freight forwarder logistics heads grounded qualitative findings in operational reality. Secondary validation drew from GCAA aerodrome safety directives, GACA privatization framework documents, IATA cargo handling guidelines, and customs trade data for specialized ground support equipment. Bottom-up handler revenue aggregation and top-down airport throughput modeling provided cross-verification.
Segment-level projections across service type, end user, technology, and airport capacity tiers structured the analytical framework throughout the forecast period. CAGRs derived from historical concession contract values, equipment deployment cycles, and regulatory mandate implementation timelines. RFID automation adoption curves and Saudization policy compliance costs informed technology and labor segment trajectories.
GACA auction mechanism expansion, GCAA equipment certification protocol revisions, and biologics manufacturing investment cycles are the dominant revision risks warranting model reassessment. Forecasts reflect documented assumptions regarding concession re-tendering velocity and automation capital commitment thresholds. A model refresh is warranted upon material change in Saudi Arabia's airport privatization timeline or UAE regulatory automation mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Operations
France Airport Operations Market
Airport Operations
South Korea Airport Operations Market
Airport Operations
Airport Terminal Operations Market
Airport Operations
Europe Offshore Helicopter Services Market
Airport Operations
Aircraft Ground Handling System Market
Airport Operations
Airport Ground Handling Market
Airport Operations
Canada Airport Operations Market
Airport Operations
Africa Airport Operations Market
Airport Operations
Global Airside Services Market
Airport Operations
Europe Airport Operations Market
Airport Operations
Airport Ground and Cargo Handling Services Market
Airport Operations
UK Airport Operations Market
Airport Operations
Middle East Airport Operations Market
Airport Operations
Airport Operations Market
Airport Operations
Global Non-Aeronautical Market
Airport Operations
Global Air Charter Services Market