
 Airless Packaging Market | 2026-2036
Airless Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Airless Packaging Market Intelligence
The substitution of virgin polymers with post-consumer recycled (PCR) plastics is realigning product economics and supply chain priorities. AptarGroup Inc. leverages its global manufacturing footprint and R&D in dispensing systems to integrate these sustainable materials. Albéa Group competes through its specialization in tube and pump solutions that meet recyclability criteria. Meanwhile, LUMSON S.p.A. differentiates with high-end glass and decorated plastic options for the luxury cosmetics segment, where aesthetics are critical.
Airless packaging is a dispensing system designed to prevent product contact with external air. It utilizes a non-pressurized mechanism, often a piston or a collapsing inner bag, to evacuate the contents with near-total dispensation, thereby protecting sensitive formulations from oxidation. Airless bottles and pumps for cosmetics and personal care applications constitute the largest segment by volume. Airless jars and tubes, however, represent the fastest-growing product types, driven by their suitability for high-viscosity creams and pharmaceutical formulations.
In Europe, the Packaging and Packaging Waste Regulation (PPWR) pressures manufacturers to improve recyclability and use recycled content. In parallel, the U.S. Food and Drug Administration (FDA) has stringent requirements for packaging that ensures the stability and integrity of topical pharmaceutical products. These regulations collectively favor the protective attributes inherent in airless designs. Navigating the material science challenge of creating mono-material systems that are both functional and compliant is the central task for suppliers.
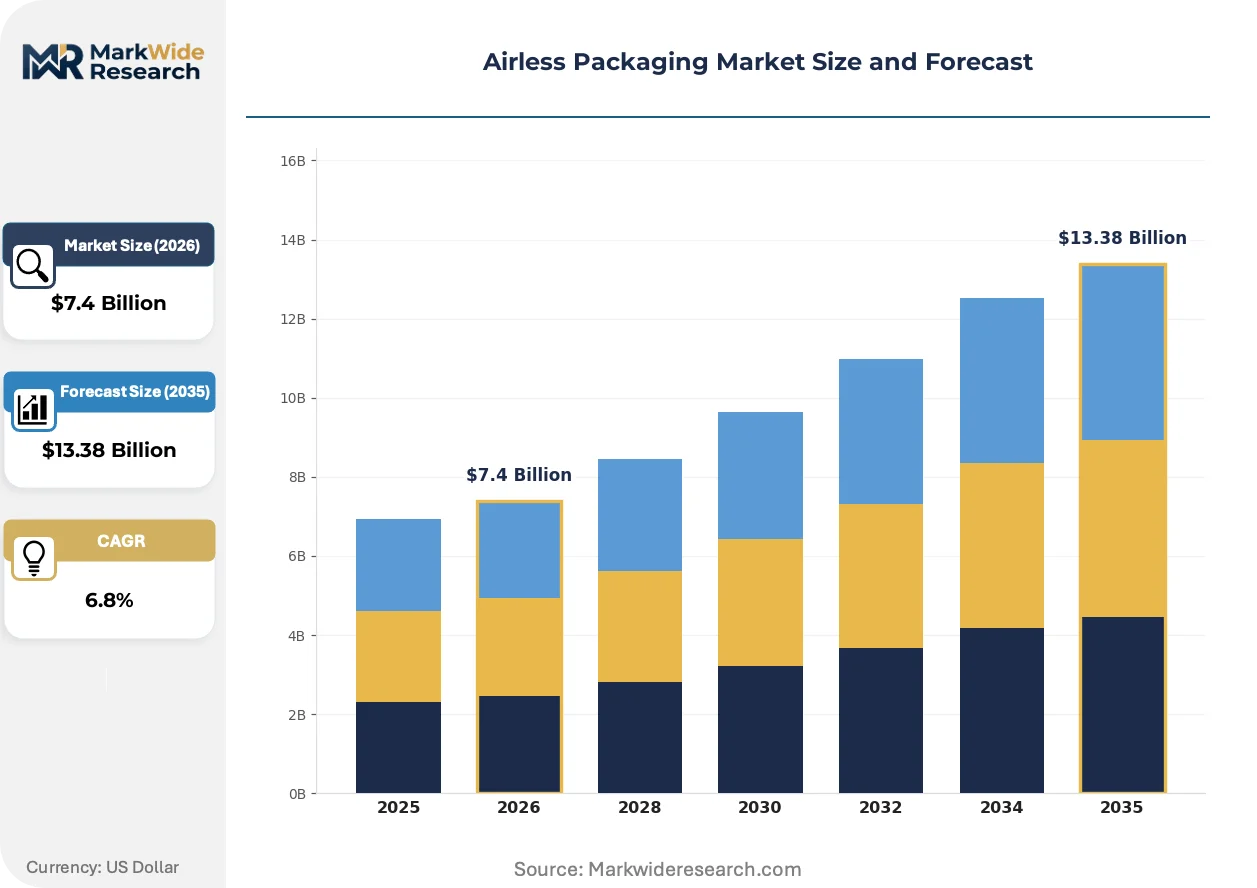
Market Dynamics
The central tension shaping the airless packaging market is the collision between sustainability mandates demanding circular materials and the inherent technical complexity of high-performance dispensing systems. This dynamic forces innovation in material science to create functional, recyclable mono-material pumps.
Growth Catalysts
- Regulatory Mandates:Europe's Packaging and Packaging Waste Regulation (PPWR) is compelling brands to adopt packaging that is recyclable and incorporates recycled content, directly benefiting airless systems designed for circularity.
- Formulation Protection:The premium cosmetics industry, especially in export-focused hubs like South Korea, requires advanced packaging to protect sensitive, high-value active ingredients from oxidation, driving adoption of airless technology.
- Mono-Material Innovation:Technical advances in creating all-polyolefin (PE or PP) pump engines without metal springs enable the entire package to be processed in a single recycling stream, aligning with brand sustainability goals.
Market Restraints
- Cost Structure:The premium price of high-quality, cosmetic-grade post-consumer recycled (PCR) resins over virgin polymers creates economic barriers for brands, particularly in mass-market segments.
- Technical Performance:Mono-material pump designs can present performance trade-offs, including challenges in achieving the same precise dosage and smooth actuation as traditional mixed-material pumps.
- Supply Chain Limitations:A constrained supply of certified, food-grade or cosmetic-grade PCR plastics creates procurement bottlenecks and price volatility for packaging manufacturers globally.
Strategic Opportunities
- Pharmaceutical Applications:Expansion into the topical and transdermal drug delivery market offers a significant opportunity, as airless systems meet stringent requirements for dosage accuracy and protection of sensitive APIs.
- Refillable Systems:Designing airless packages with replaceable inner cartridges or pods creates a new market for refills, appealing to environmentally conscious consumers and building brand loyalty.
- High-Viscosity Formulations:Developing innovative airless jars and tubes for dense creams, masks, and color cosmetics addresses an unmet need for hygienic, efficient dispensing of non-liquid products.
Industry Challenges
- Regulatory Divergence:Manufacturers face complexity in designing products that comply with differing requirements for material safety and recycled content between jurisdictions, such as the EU's PPWR and the FDA's standards in the United States.
- Capital Investment:The transition to mono-material pumps requires significant capital expenditure on precision injection molding tools and assembly automation to produce the intricate, multi-part components.
- Recycling Infrastructure Gaps:The effectiveness of "design for recycling" is limited by the real-world capabilities of municipal recycling facilities, many of which lack the optical sorting technology to identify and separate cosmetic packaging correctly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airless Packaging Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Airless Bottles, Airless Jars, Airless Pumps, Airless Tubes, Airless Bags Material: Plastic, Glass, Aluminum, Multi-layer Laminates, Composite Materials Application: Cosmetics, Personal Care, Food & Beverage, Pharmaceuticals, Industrial Lubricants End User: Beauty Brands, Nutraceutical Manufacturers, Drug Manufacturers, Chemical Producers |
| Companies Covered | AptarGroup Inc., Silgan Holdings Inc., Albéa Group, LUMSON S.p.A, HCP Packaging, Quadpack, Berry Global, Gerresheimer, APackaging Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airless Packaging Market Strategic Shifts & Innovations
The market's evolution is defined by the convergence of material science and circular economy principles. This movement is forcing a fundamental redesign of packaging, prioritizing end-of-life management and resource efficiency alongside traditional requirements for product protection and user experience.
Mono-material airless pumps, constructed entirely from a single polymer family like polypropylene, provide a clear path to recyclability. Prestige skincare and cosmetic brands are rapidly adopting these systems to meet corporate sustainability pledges and retailer mandates. This material simplification is automating the sorting process at material recovery facilities, which previously could not effectively separate the mixed plastics and metal springs of conventional pumps.
Europe's Packaging and Packaging Waste Regulation (PPWR) is a significant policy driver, establishing firm targets for recycled content and recyclability performance. This directive effectively renders many legacy airless pump designs obsolete by penalizing the use of non-recyclable components like metal springs. The luxury cosmetics sector, especially brands based in France and Italy, is accelerating investment in compliant mono-material systems to ensure continued access to the EU market.
A notable shift in consumption patterns is the rise of refillable airless packaging. This model, which pairs a durable, premium outer container with a replaceable inner cartridge, disrupts the single-use-and-dispose cycle. Brand owners are leveraging this system to foster repeat purchases and reduce their overall plastic footprint. This trend is most prominent in the high-end skincare segment in markets like Germany, Scandinavia, and Japan, where consumer demand for sustainable options is strong.
Airless Packaging Market Segmentation
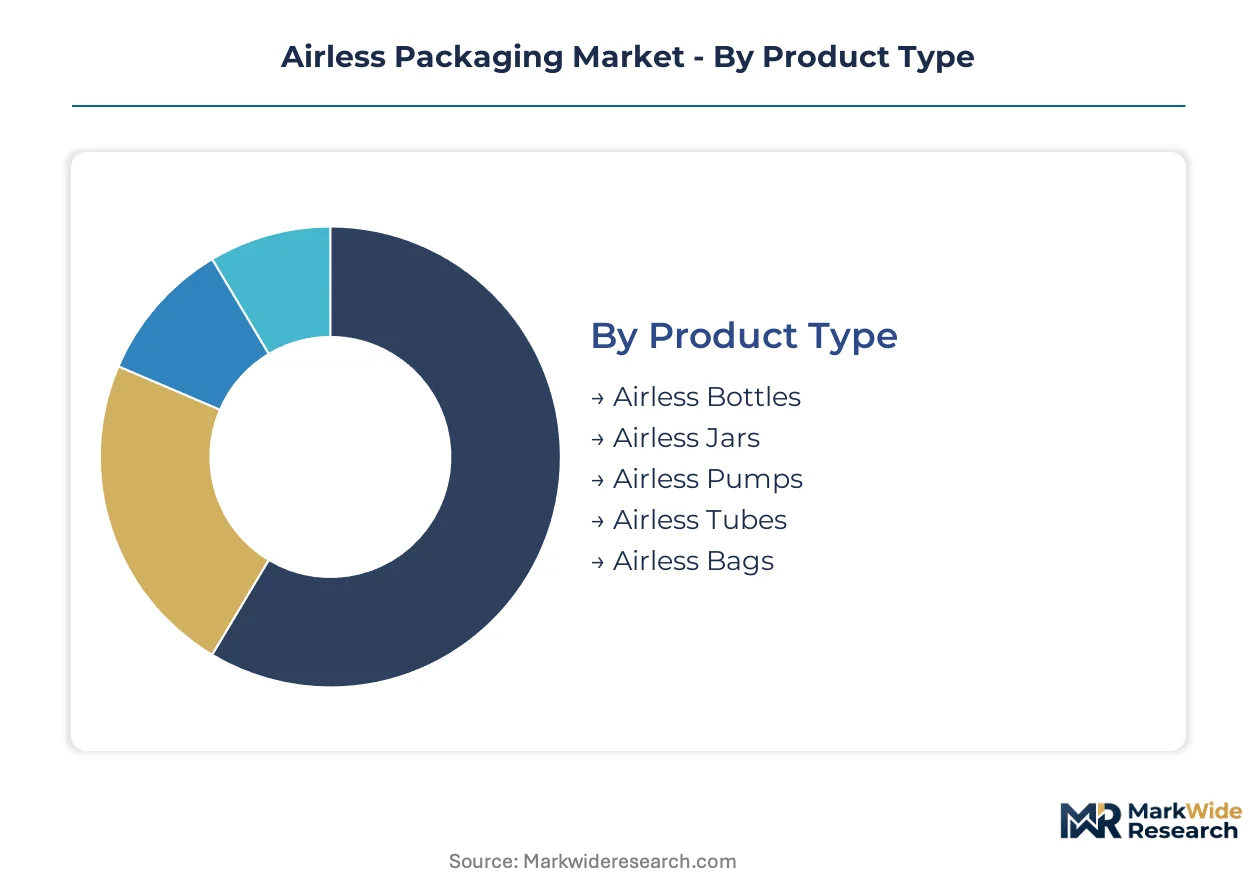
Understanding the airless packaging market through its constituent segments reveals the varied demands placed on dispensing technologies. Each category reflects distinct functional requirements, material preferences, and end-user expectations. This granular view helps identify areas of concentrated investment and emerging growth across the packaging ecosystem.
Product Type:
The product type segmentation highlights the balance between highly standardized components and custom-engineered solutions for specific product viscosities and aesthetic demands.
- Airless Bottles:These systems typically employ a piston mechanism or an internal pouch to dispense product without air exposure, widely used for liquid and serum formulations. Demand concentrates heavily in the premium skincare sector in France and South Korea, where formulation integrity is critical for high-value active ingredients.
- Airless Jars:Designed for thicker creams and balms, airless jars utilize a rising plate or diaphragm to push product upwards, preventing oxidation and contamination. This product type is expanding most quickly for high-viscosity pharmaceutical creams and luxury cosmetic masks, requiring hygienic dispensing.
- Airless Pumps:Standalone dispensing mechanisms integrated into various containers, often featuring mono-material designs for enhanced recyclability.
- Airless Tubes:Flexible packaging solutions that collapse as product is dispensed, suitable for a range of cosmetic and personal care formulations.
- Airless Bags:Inner bags within a rigid outer container, offering excellent product protection and near-total evacuation, particularly for larger volume applications.
Leading the category by volume: Airless Bottles. Growing fastest: Airless Jars.
Material:
Material choices in airless packaging are increasingly influenced by regulatory pressures for sustainability and the need for chemical compatibility with diverse formulations.
- Plastic:Dominant material due to its versatility, cost-effectiveness, and the development of mono-material polyolefin solutions that support recycling initiatives. Brands in the European Union prioritize plastic options compliant with PPWR recycled content targets.
- Glass:Favored by the luxury cosmetics segment for its premium aesthetic, inertness, and perceived recyclability, often paired with airless pump mechanisms. LUMSON S.p.A. offers high-end glass options, catering to brands seeking aesthetic differentiation.
- Aluminum:Provides excellent barrier properties and a sleek, modern appearance, used for certain high-end cosmetic and pharmaceutical products requiring robust protection.
- Multi-layer Laminates:Engineered structures combining different materials to achieve specific barrier, aesthetic, or functional properties, particularly for sensitive formulations.
- Composite Materials:Innovative combinations of materials designed to optimize performance, recyclability, or reduce material usage, often targeting niche applications.
Plastic materials dominate consumption in this segment. Glass options are gaining share in the high-end market.
Application:
The application landscape for airless packaging demonstrates a clear shift towards sectors prioritizing product protection, dosage accuracy, and hygienic dispensing.
- Cosmetics:The largest application area, driven by the need to protect sensitive active ingredients in premium skincare, makeup, and hair care formulations from oxidation. South Korean and French beauty brands rely on airless systems for export-oriented products.
- Pharmaceuticals:A high-growth segment where airless technology ensures sterile dispensing and precise dosing for topical medications, creams, and transdermal patches. The U.S. FDA regulations for product stability and integrity directly benefit airless designs in this sector.
- Personal Care:Includes products like lotions, sunscreens, and deodorants, benefiting from airless systems for extended shelf life and hygienic use.
- Food & Beverage:Niche applications for oxygen-sensitive products like sauces, oils, or specialized food supplements, preserving freshness and preventing spoilage.
- Industrial Lubricants:Specialized use cases where precise application and protection from contamination are critical for high-performance industrial fluids.
Cosmetics applications account for the largest share of airless packaging. Pharmaceutical applications show the steepest expansion trajectory.
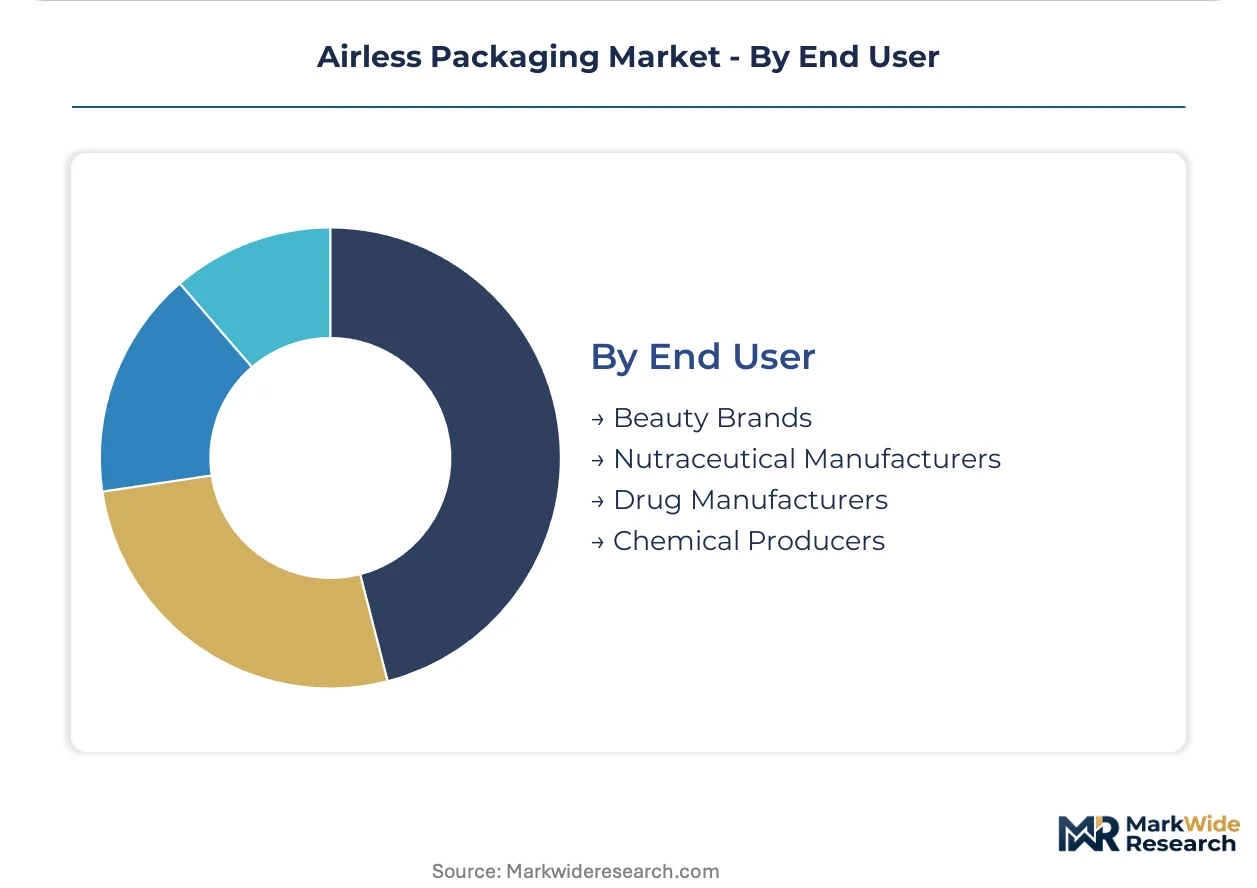
End User:
The end-user segmentation reflects the primary industries adopting airless packaging, each with unique regulatory and consumer-driven demands.
- Beauty Brands:Major consumers of airless packaging for their premium and mass-market cosmetic and skincare lines, driven by product integrity and consumer experience. AptarGroup Inc. supplies many beauty brands with advanced dispensing systems.
- Drug Manufacturers:Utilize airless systems for pharmaceutical products, ensuring dosage accuracy, sterility, and compliance with stringent regulatory standards like those from the U.S. FDA.
- Nutraceutical Manufacturers:Adopt airless packaging for dietary supplements and health products to protect sensitive ingredients from degradation.
- Chemical Producers:Employ airless solutions for specialized chemical formulations requiring precise dispensing and protection from environmental exposure.
Beauty Brands represent the largest consumer segment. Drug Manufacturers are rapidly increasing their adoption of airless packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for airless packaging concentrates in beauty and personal care manufacturing hubs, particularly in South Korea and France, for export-oriented brands. This geographical focus reflects the specific needs of premium cosmetics for formulation protection and aesthetic presentation. Regulatory frameworks in major markets also heavily influence regional adoption rates and material science innovations.
South Korea
South Korea exhibits significant demand for airless packaging in its booming K-beauty industry, driven by sensitive active ingredients in premium skincare. The Ministry of Food and Drug Safety (MFDS) sets stringent requirements for cosmetic product stability and packaging safety. Seoul and Gyeonggi Province serve as central hubs for advanced cosmetic manufacturing and packaging innovation.
France
France, a global leader in luxury cosmetics, shows substantial adoption of airless systems for high-value formulations and aesthetic appeal. The EU's Packaging and Packaging Waste Regulation (PPWR) compels French manufacturers to prioritize recyclable and recycled content. Cosmetic Valley, centered around Chartres and Orléans, drives research and production of sophisticated beauty packaging solutions.
United States
The United States market requires airless packaging for topical pharmaceutical products and high-end personal care formulations, emphasizing dosage accuracy and product integrity. The U.S. Food and Drug Administration (FDA) mandates strict packaging standards to ensure drug stability and patient safety. The Northeast Corridor remains a key region for pharmaceutical R&D and advanced packaging development.
Germany
German manufacturers adopt airless packaging, particularly for refillable systems and high-end skincare, aligning with strong consumer demand for sustainability. Europe's PPWR directly impacts German brands, pushing for mono-material designs and increased recycled content. Bavaria and North Rhine-Westphalia are significant centers for chemical, pharmaceutical, and cosmetic industries.
Japan
Japan's high-end skincare segment increasingly utilizes airless packaging, driven by consumer preferences for sustainable options and precise product dispensing. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees product safety and quality for cosmetic and pharmaceutical packaging. Tokyo and Osaka lead in the development and manufacturing of innovative cosmetic and personal care products.
Airless Packaging Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, defining the airless packaging market's competitive structure. The market sees a tiered landscape with global dispensing system providers, specialized component manufacturers, and luxury packaging differentiators. Companies frequently engage in R&D for sustainable materials and expand their global manufacturing footprints to capture market share.
Global dispensing system providers like AptarGroup Inc. anchor the market, leveraging extensive manufacturing capabilities and ongoing research into advanced dispensing solutions. Albéa Group occupies a position among specialized component manufacturers, focusing on tube and pump solutions that meet evolving recyclability criteria. LUMSON S.p.A. represents luxury packaging differentiators, offering high-end glass and decorated plastic options for the prestige cosmetics segment.
| Leading Market Players |
|---|
| AptarGroup Inc. |
| Silgan Holdings Inc. |
| Albéa Group |
| LUMSON S.p.A |
| HCP Packaging |
| Quadpack |
| Berry Global |
| Gerresheimer |
| APackaging Group |
| Others |
Cost & Logistics Intelligence
Polypropylene (PP) resin price fluctuations directly influence the manufacturing cost of airless packaging, creating distinct pricing tiers for virgin versus post-consumer recycled (PCR) material. This volatility cascades through the supply chain, impacting profitability across segments.
Pricing Analysis
Volume-driven segments operate on tight margins, contrasting sharply with the premium pricing commanded by specialized solutions. Pricing stratifies across luxury, standard, and mass-market tiers, driven by material quality, compliance with regulations like the EU's PPWR, and brand reputation. Pricing softness stems from the higher cost of cosmetic-grade PCR resins compared to virgin polymers, especially for mass-market brands. Luxury cosmetic brands exhibit lower price sensitivity, prioritizing formulation protection and aesthetic differentiation.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risks in a supply chain concentrated in key manufacturing hubs. Production gravity centers on South Korea, France, and China for plastic components, while glass is sourced globally. The supply chain relies on consistent access to cosmetic-grade PCR plastics and precision-engineered mono-material pump engines, creating procurement bottlenecks. Distribution runs through direct sales channels to beauty and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
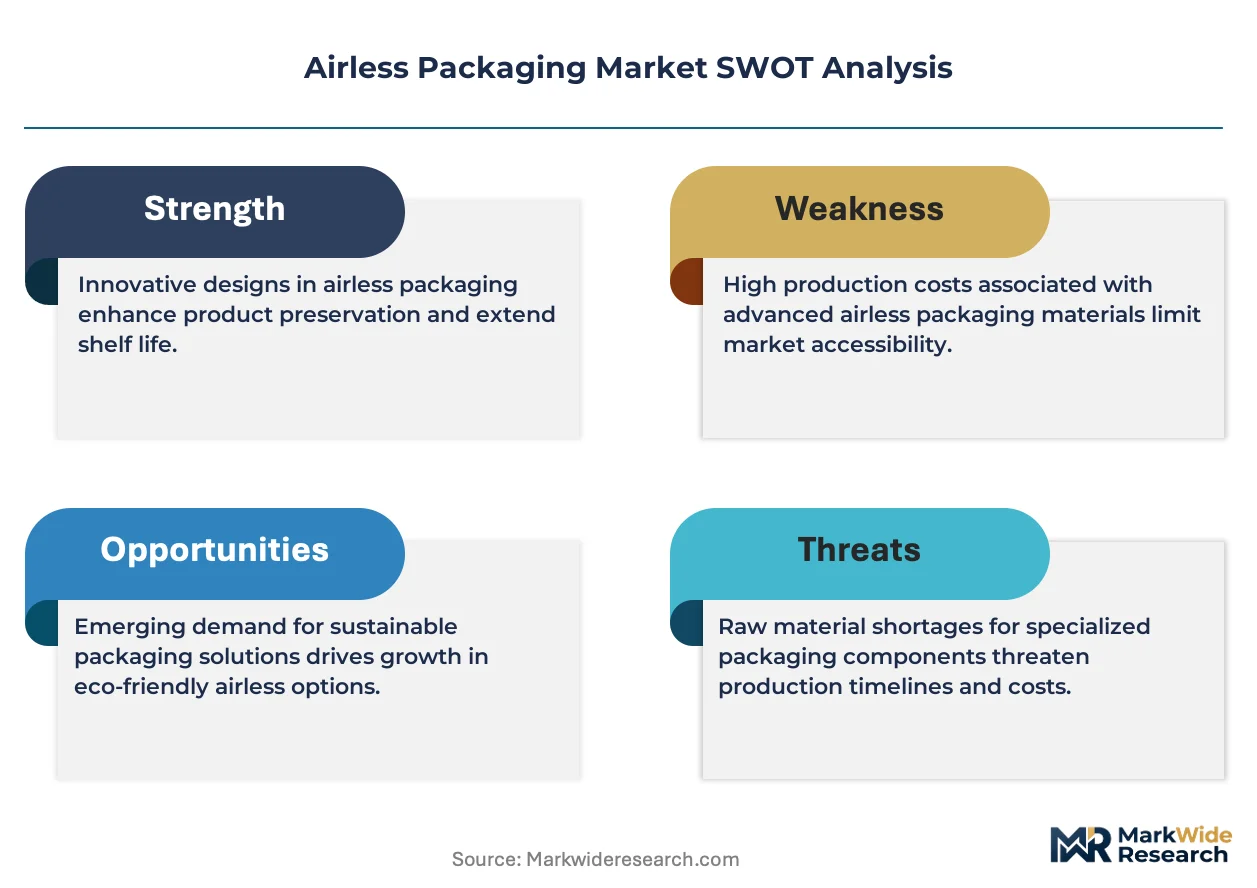
Analyst Recommendations
The airless packaging market is witnessing a vertical-integration race, with players aggressively pursuing in-house production of mono-material pump components. This strategy aims to control material quality and secure supply amidst rising sustainability mandates.
For Market Incumbents: Anchor existing market share by accelerating investment in mono-material pump R&D and securing long-term contracts for cosmetic-grade PCR supply. Expand global manufacturing footprints to serve regional demand and navigate regulatory divergence, such as between EU PPWR and FDA standards. This proactive approach counters the threat of regulatory obsolescence for legacy mixed-material designs.
For New Entrants and Emerging Players: Europe's Packaging and Packaging Waste Regulation (PPWR) in the EU opens a window for specialized mono-material packaging providers. Target the high-growth pharmaceutical applications requiring stringent protection and precise dosing, and the expanding refillable systems market in Germany and Japan. Offer highly customized solutions for high-viscosity formulations as a go-to-market strategy.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized mono-material innovators in Europe, particularly those with strong intellectual property in pump engines. The long-term viability of airless packaging is secured by its essential product protection and role as a sustainability enabler for premium cosmetics and pharmaceuticals. Acquire companies with established supply chains for cosmetic-grade PCR plastics. A signal to watch is the expansion of national PCR content mandates beyond current EU directives.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Mono-Material Pump Platforms | Enables full recyclability, aligning with EU PPWR and brand sustainability goals for cosmetic products. |
| Secure Long-Term PCR Supply Contracts | Mitigates procurement bottlenecks and price volatility for cosmetic-grade recycled plastics used in production. |
| Expand Global Manufacturing Footprint | Facilitates localized production, reducing logistics costs and improving responsiveness for South Korean and French brands. |
| Invest in Refillable Packaging Solutions | Addresses growing consumer demand for sustainable options and fosters brand loyalty in high-end skincare. |
| Pursue Pharmaceutical Packaging Certifications | Unlocks access to the high-growth pharmaceutical market, meeting stringent U.S. FDA requirements for topical drugs. |
Research Approach
Multi-period observation of material consumption and product launch indicators anchored the trend analysis, supplemented by interviews with R&D directors, procurement leads, and regulatory affairs specialists. Primary insights were validated against secondary sources including customs data, packaging industry reports, and regulatory filings from the EU and U.S. FDA. This approach ensured comprehensive bottom-up and top-down triangulation of market dynamics.
An input-output matrix structured the quantitative model, projecting market evolution across the analysis window. Segmentation dimensions included product type, material, application, end user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical data analysis and expert consensus. Key industry-specific forecast inputs included post-consumer recycled plastic availability and mono-material pump adoption rates.
The model assumes a particular technology adoption path; alternative pathways for advanced mono-material polymers would alter the outlook. Forecasts reflect documented assumptions regarding regulatory enforcement and recycling infrastructure development. Deviation in global PCR supply chain stability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market