
 Transport Packaging Market | 2026-2036
Transport Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Transport Packaging Market Outlook
Consolidation among third-party logistics providers is restructuring procurement patterns for bulk transport containers. Smurfit Kappa Group leverages its European recycled paperboard network to serve consolidated grocery distribution chains. Sealed Air Corporation sustains technology leadership in inflatable protective systems for fragile electronics shipments. Mondi Group anchors its position through kraft paper specialization for industrial pallet wrapping across centralized buying groups.
Transport packaging encompasses engineered containers, dunnage, and unit-load platforms designed to protect goods during intermodal transit, typically constructed from corrugated fiberboard with burst strengths exceeding 200 psi or high-density polyethylene with 20-30% recycled content. Its primary purpose is to prevent mechanical damage, moisture ingress, and contamination from manufacturing origin through final delivery. Corrugated boxes dominate volume across food and beverage distribution due to cost efficiency and printability for retail-ready formats. Plastic pallets represent the fastest-expanding product category as pooled rental programs replace wood in pharmaceutical cold chains. Smart packaging technologies embed RFID and temperature loggers that command premium positioning in high-value electronics and pharmaceutical lanes.
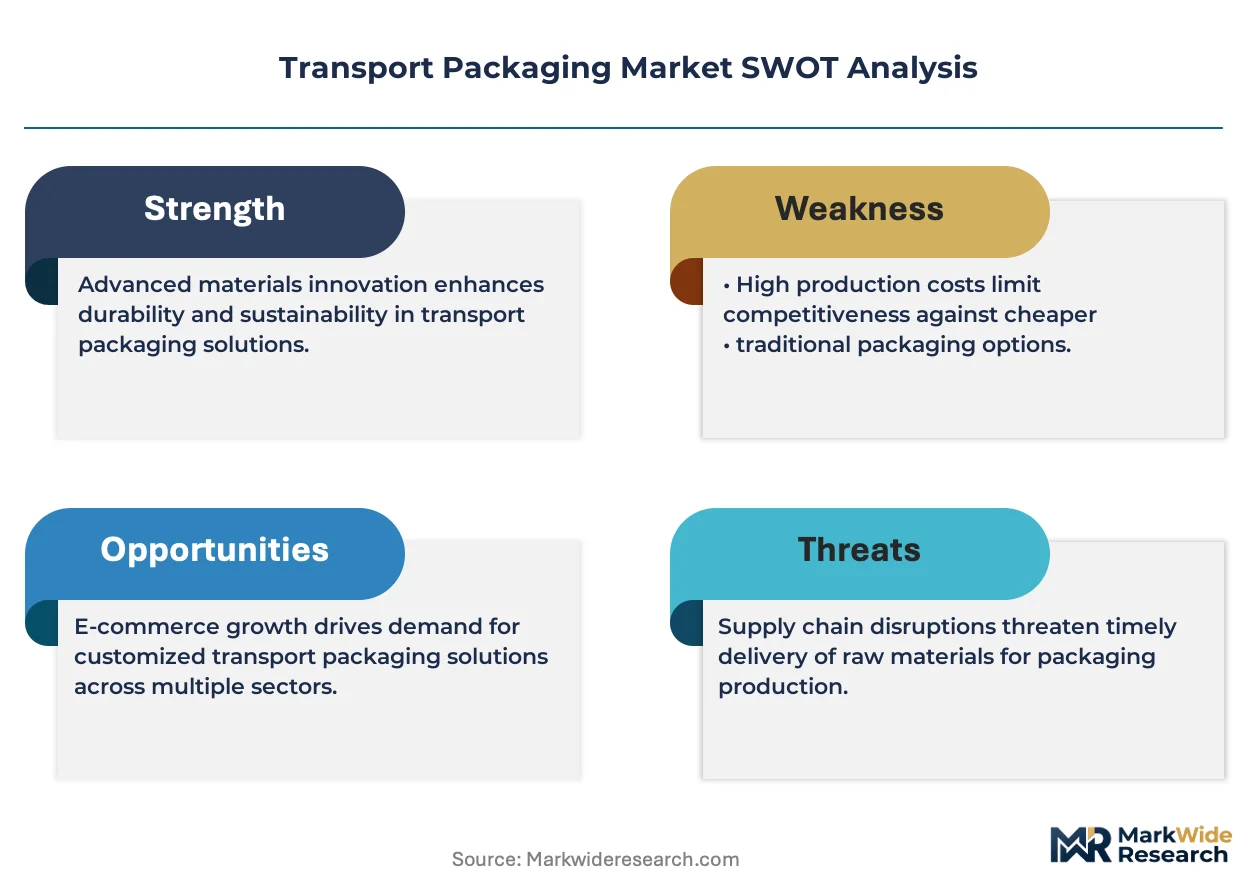
The EPA guides sustainable materials management for packaging recovery in the United States, while the EU Packaging and Packaging Waste Regulation mandates extended producer responsibility schemes that alter material selection across export-bound production. ISO 18600 series standards define reusable transport item performance benchmarks that gate market access for pooled container suppliers. Stakeholders must weigh recycled content compliance against total cost of ownership as regulatory thresholds tighten and customer scorecards embed circularity metrics into supplier qualification.
Market Dynamics
The EU Packaging and Packaging Waste Regulation's recycled content mandates are compressing material substitution timelines across export-bound production networks. This regulatory pressure is forcing corrugated converters to requalify supply chains faster than capital cycles permit.
Growth Catalysts
- E-commerce fulfillment densification:Automated sortation hubs in Germany and the Netherlands are specifying standardized reusable tote dimensions that lock in container suppliers for decade-long contracts.
- REACH chemical compliance:The EU's restricted substance lists are accelerating migration from solvent-based inks to water-based alternatives in food-contact corrugated, opening retrofit demand for printing equipment.
- Pharmaceutical cold chain expansion:Temperature-validated shippers with integrated phase-change materials are capturing lane volume from traditional expanded polystyrene as biologics distribution multiplies.
Market Restraints
- Old corrugated container price volatility:OCC index swings of 40% within single quarters compress converter margins and destabilize long-term contract pricing.
- China kraft pulp concentration:Three state-owned enterprises control 60% of Asian bleached kraft supply, creating single-source vulnerability for European linerboard producers.
- Plastic pallet substitution ceiling:Wood pallet pools retain cost advantage below 50-unit annual circulation thresholds, blocking penetration in fragmented retail receiving networks.
Strategic Opportunities
- India pharmaceutical export corridors:CDSCO serialization mandates are creating demand for track-and-trace-enabled secondary packaging that integrates RFID with tamper-evident features.
- Pool rental model expansion:Pallet and crate pooling networks are penetrating fresh produce distribution in Spain and Italy, displacing single-use corrugated at field packing stations.
- Battery cell logistics:UN 38.3 lithium transport regulations are mandating fire-resistant fiberboard and flame-retardant dunnage for electric vehicle component supply chains.
Industry Challenges
- Automation integration complexity:Warehouse robotic systems require dimensional tolerances tighter than legacy corrugated production lines achieve, forcing capital-intensive press upgrades.
- ISO 18600 certification timelines:Reusable container performance testing protocols extend product development cycles by 8-14 months, delaying market entry for pooled packaging innovators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transport Packaging Market |
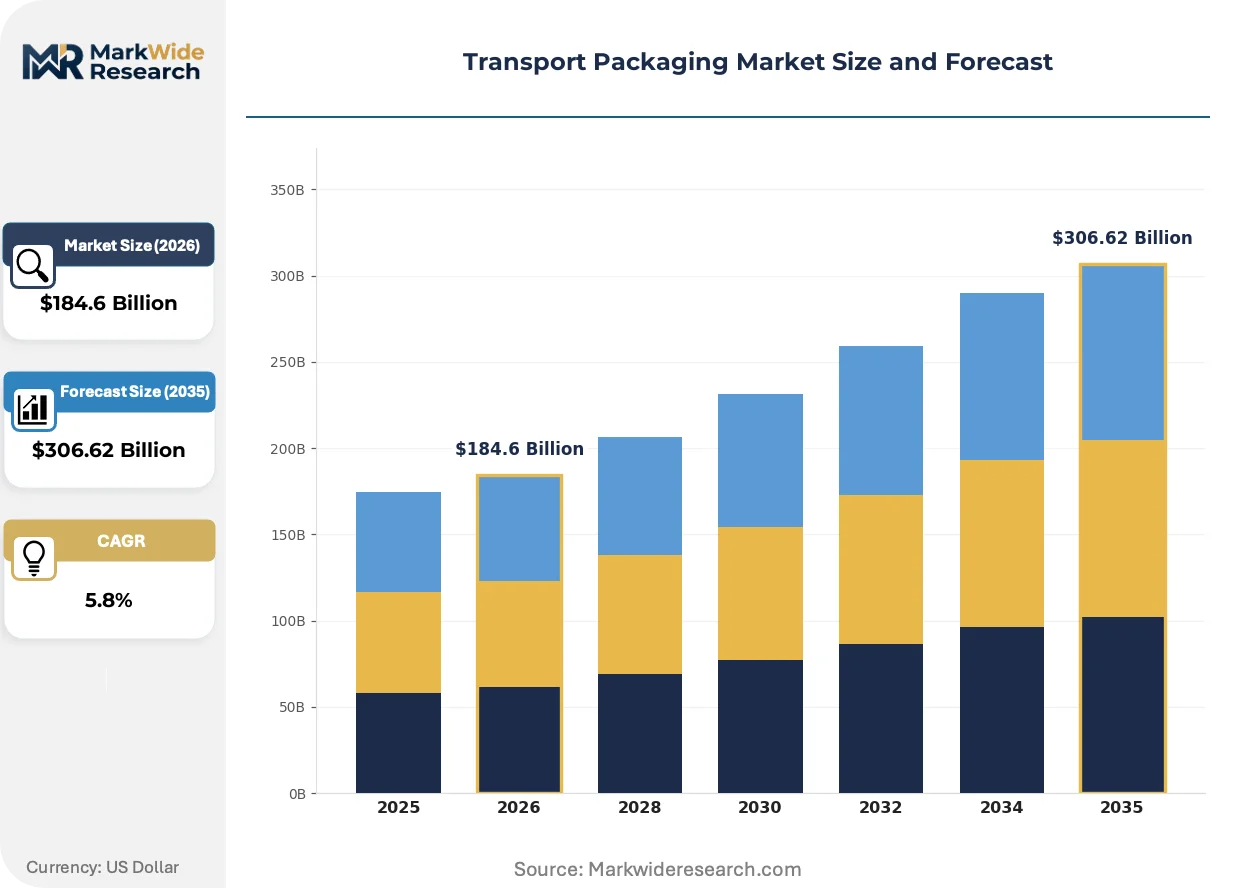
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $306.62 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Metal, Wood Product Type: Boxes, Pallets, Crates, Bags End User: Food & Beverage, Electronics, Pharmaceuticals, Consumer Goods Packaging Technology: Active Packaging, Modified Atmosphere, Smart Packaging, Vacuum Packaging |
| Companies Covered | Smurfit Kappa Group, International Paper, WestRock, Mondi Group, DS Smith Plc, Berry Global, Sealed Air Corporation, Amcor plc, Greif, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transport Packaging Market Strategic Shifts
Active and intelligent packaging systems are migrating from high-value electronics into mid-tier consumer goods as sensor costs decline. This diffusion is compressing the technology premium and reshaping competitive positioning across protective packaging tiers.
RFID-enabled returnable containers are integrating real-time location tracking with automated inventory reconciliation in automotive component supply chains. Tier-1 suppliers in Germany's Baden-Württemberg corridor are mandating these systems for just-in-sequence delivery compliance. The technology is integrating supplier quality data directly into OEM production planning systems, eliminating manual receiving inspection steps.
The EU Green Deal's packaging waste reduction targets are accelerating Extended Producer Responsibility fee structures that penalize non-recyclable formats. Corrugated producers are responding with fiber-based alternatives to plastic stretch film for pallet unitization. France's national environmental agency has published draft criteria that would disqualify multi-material laminates from preferred procurement status in public sector logistics.
Consolidated buying groups in grocery distribution are unbundling packaging procurement from third-party logistics contracts, creating direct supplier relationships that bypass traditional 3PL specification control. This disintermediation is most visible in the Netherlands' centralized retail distribution infrastructure, where supermarket cooperatives now negotiate corrugated specifications independently from transport providers. The shift is compressing supplier margins while demanding faster design iteration cycles.
Transport Packaging Market Segmentation
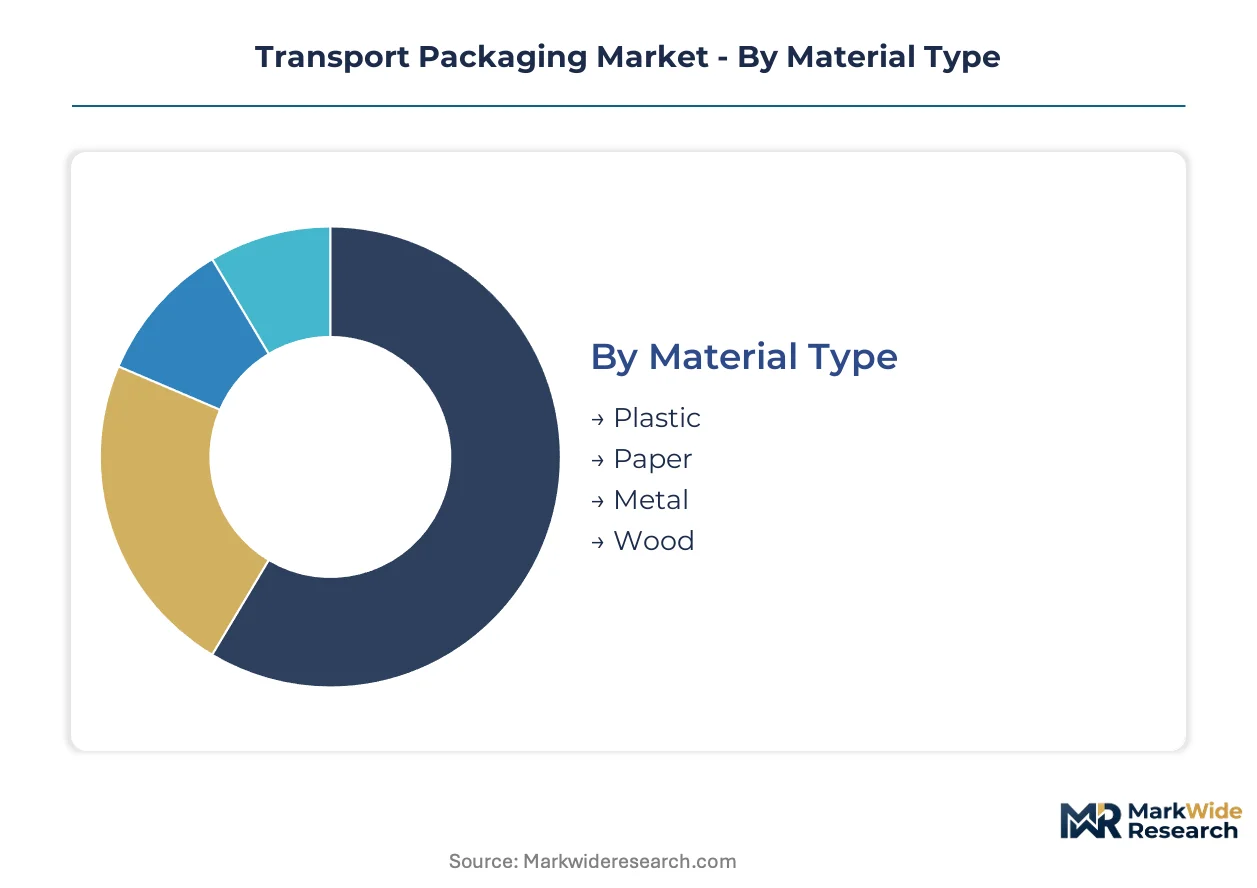
Transport packaging segmentation reveals how material science, product form, and end-use requirements create distinct competitive arenas with diverging margin profiles and capital intensity. Understanding these boundaries helps suppliers align R&D investment with structural growth vectors.
Material Type:
Standalone materials dominate high-volume applications, while hybrid and embedded material systems serve specialized protective functions requiring multi-layer performance.
- Plastic:High-density polyethylene and polypropylene formulations deliver moisture barriers and impact resistance for pharmaceutical cold chains. REACH chemical compliance is accelerating migration from virgin to post-consumer recycled grades in EU export-bound production.
- Paper:Corrugated fiberboard with burst strengths exceeding 200 psi anchors food and beverage distribution through cost efficiency and retail-ready printability. Germany's automotive component logistics corridor is specifying heavier-duty triple-wall grades for just-in-sequence delivery.
- Metal:Steel and aluminum containers serve hazardous material transport and reusable industrial liquid handling. Drum specifications for chemical logistics remain concentrated in Rotterdam-Antwerp port industrial zones.
- Wood:Softwood pallets retain dominance in fragmented retail receiving networks below 50-unit annual circulation thresholds. Heat-treated ISPM-15 compliance adds certification cost layers for cross-border agricultural shipments.
Paper leads volumes today; plastic is gaining share fastest.
Product Type:
Product form segmentation tracks the shift from single-use disposable units toward pooled rental assets with embedded tracking capabilities.
- Pallets:Plastic pallet pools are displacing wood in pharmaceutical cold chains through dimensional consistency for automated handling. Pooled rental programs now penetrate fresh produce distribution in Spain and Italy.
- Boxes:Corrugated containers dominate volume across grocery distribution due to printability for retail-ready formats. Automated sortation hubs in Germany and the Netherlands specify standardized reusable tote dimensions.
- Crates:Returnable plastic crate systems lock in suppliers for decade-long contracts at e-commerce fulfillment densification sites. ISO 18600 performance testing protocols extend product development cycles significantly.
- Bags:Flexible intermediate bulk containers serve agricultural and chemical powder logistics. UN certification requirements for hazardous material transport create specification barriers for new entrants.
Boxes lead volumes today; pallets are expanding most quickly.
End User:
End-use segmentation reflects diverging regulatory intensity, with pharmaceutical and food contact applications imposing stricter material qualification protocols than industrial segments.
- Food & Beverage:Temperature-validated shippers with phase-change materials are capturing lane volume from expanded polystyrene as fresh distribution networks multiply. Water-based ink migration from solvent systems opens retrofit demand for printing equipment.
- Pharmaceuticals:CDSCO serialization mandates in India pharmaceutical export corridors create demand for track-and-trace-enabled secondary packaging integrating RFID with tamper-evident features. Biologics distribution expansion drives cold chain packaging investment.
- Electronics:Inflatable protective systems and anti-static dunnage serve high-value fragile shipments. Active and intelligent packaging systems are migrating from high-value electronics into mid-tier consumer goods as sensor costs decline.
- Consumer Goods:Consolidated buying groups in grocery distribution are unbundling packaging procurement from third-party logistics contracts. This disintermediation compresses supplier margins while demanding faster design iteration cycles.
Food & Beverage leads volumes today; Pharmaceuticals is climbing the fastest.
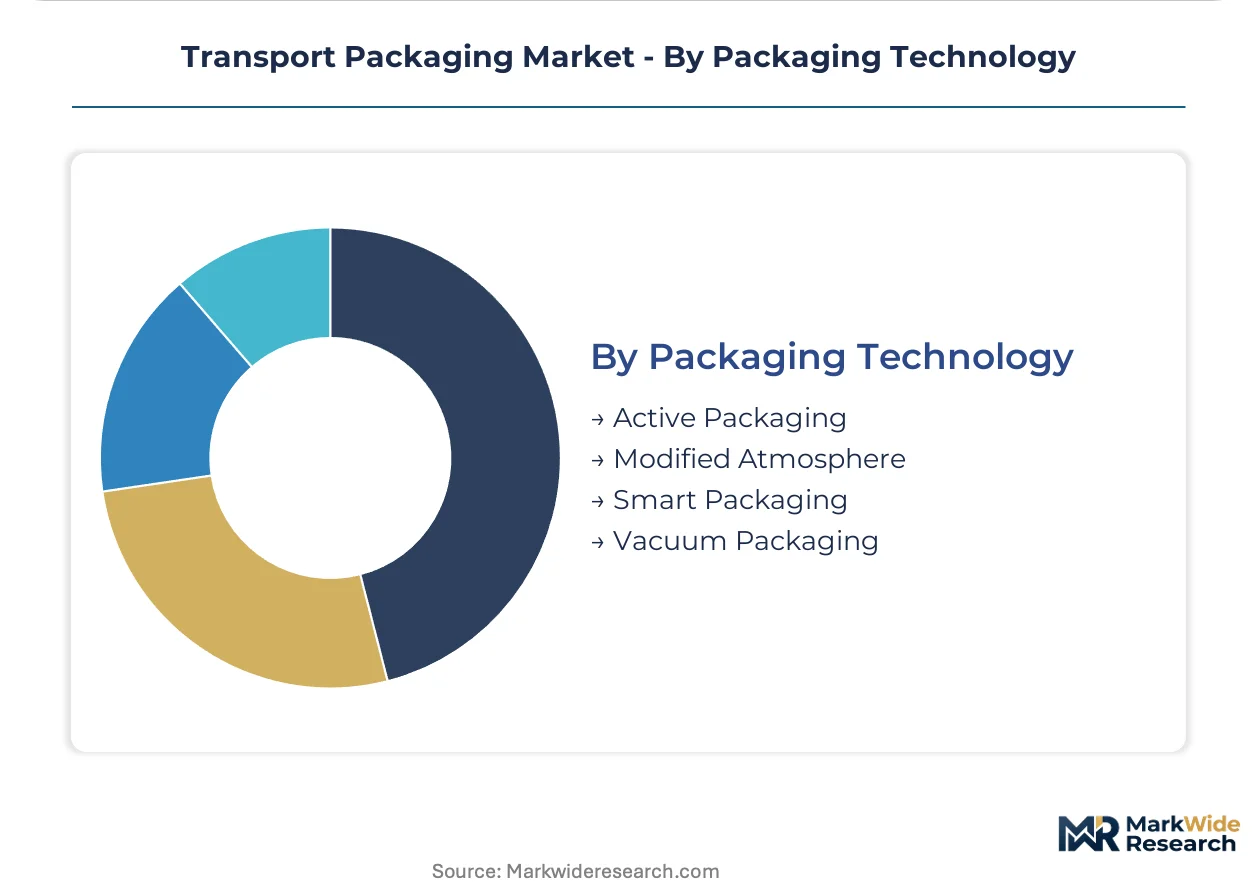
Packaging Technology:
Technology segmentation distinguishes between passive containment functions and active intervention systems that monitor or modify the internal environment.
- Smart Packaging:RFID-enabled returnable containers integrate real-time location tracking with automated inventory reconciliation in automotive supply chains. Tier-1 suppliers in Germany's Baden-Württemberg corridor mandate these systems for just-in-sequence compliance.
- Active Packaging:Oxygen scavengers and moisture absorbers extend shelf life for sensitive food and pharmaceutical products. EU Green Deal packaging waste reduction targets accelerate Extended Producer Responsibility fee structures that penalize non-recyclable formats.
- Modified Atmosphere:Gas-flushed barrier films preserve fresh produce quality through controlled oxygen and carbon dioxide levels. Field packing stations in Mediterranean agriculture are adopting these systems for export-grade shipments.
- Vacuum Packaging:Barrier film evacuation extends protein shelf life in food distribution networks. Capital-intensive thermoforming equipment creates scale advantages for integrated converters.
Vacuum Packaging leads volumes today; Smart Packaging is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive logistics corridor generates denser demand for reusable transport packaging than India's pharmaceutical export hubs, though both markets face tightening recycled content mandates from distinct regulatory frameworks.
Germany
Automotive component manufacturers in Baden-Württemberg specify RFID-enabled returnable containers for just-in-sequence delivery compliance. The EU Packaging and Packaging Waste Regulation's extended producer responsibility schemes alter material selection across export-bound production networks. Stuttgart's tier-1 supplier cluster now mandates ISO 18600-certified crate systems that integrate real-time location tracking.
United States
E-commerce fulfillment densification drives automated sortation hub investment across the Midwest and Southeast logistics corridors. EPA sustainable materials management guidance shapes packaging recovery protocols for domestic distribution networks. Chicago's consolidated retail distribution infrastructure unbundles packaging procurement from third-party logistics contracts.
India
Pharmaceutical cold chain expansion creates demand for temperature-validated shippers with integrated phase-change materials. CDSCO serialization mandates generate track-and-trace-enabled secondary packaging requirements for export corridors. Mumbai-Pune's biologics distribution cluster integrates RFID with tamper-evident features for EU-bound shipments.
China
Battery cell logistics for electric vehicle supply chains mandate fire-resistant fiberboard under UN 38.3 lithium transport regulations. MIIT dual carbon goals accelerate migration toward post-consumer recycled grades in export-bound production. Yangtze River Delta converters face capital-intensive press upgrades to meet warehouse robotic dimensional tolerances.
Netherlands
Centralized retail distribution infrastructure enables supermarket cooperatives to negotiate corrugated specifications independently from transport providers. REACH chemical compliance accelerates water-based ink migration from solvent systems in food-contact applications. Rotterdam-Antwerp port zones concentrate drum specifications for chemical logistics.
Transport Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across material and technology boundaries. The vendor base organizes around three strategic archetypes: integrated paperboard networks serving grocery distribution chains, protective systems specialists targeting pharmaceutical and electronics lanes, and pooled rental operators embedding tracking capabilities in returnable assets. Competitive moves concentrate on strategic partnerships with automated warehouse providers and geographic expansion into pharmaceutical export corridors.
Among European paperboard specialists, Smurfit Kappa Group and Mondi Group exemplify the integrated network archetype. Sealed Air Corporation occupies a position within the protective systems tier. These three companies represent distinct competitive vectors—fiber-based supply chain integration, kraft paper specialization for industrial applications, and technology leadership in inflatable protective systems—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| International Paper |
| WestRock |
| Mondi Group |
| DS Smith Plc |
| Berry Global |
| Sealed Air Corporation |
| Amcor plc |
| Greif, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU recycled content mandates for corrugated materials are compressing converter margins and forcing rapid supply chain requalification that outpaces capital replacement cycles. This regulatory pressure cascades through procurement negotiations as buyers demand certified post-consumer grades at contract prices indexed to volatile recovered paper markets.
Pricing Analysis
Capacity additions in Southeast Asia are reshaping price floors for kraft linerboard as integrated pulp-to-boxboard complexes achieve scale economies. Three-tier pricing structure across premium, standard, and economy levels separates ISO 18600-certified reusable systems from commodity corrugated and unbranded plastic pallets. Pricing pressure stems from OCC index volatility that compresses converter margins during quarterly price swings. Fragmented retail receiving networks below 50-unit annual circulation thresholds exhibit highest price sensitivity, while pharmaceutical cold chain operators absorb premiums for temperature-validated systems.
Supply Chain Analysis
Return flows of pooled plastic pallets and RFID-enabled crates from automotive tier-1 suppliers create reverse-logistics infrastructure that lowers total cost of ownership versus single-use alternatives. Manufacturing concentration in Germany, China, and the United States anchors global supply for engineered transport packaging systems. Raw material flows draw from bleached kraft pulp concentrated among Chinese state-owned enterprises, post-consumer recycled resin streams, and European recovered paper networks. Single-source vulnerability in Asian pulp supply creates structural risk for European linerboard producers. Distribution runs through consolidated grocery buying groups, third-party logistics networks, and direct OEM procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Transport packaging functions as a stable compounder anchored by regulatory mandates that tighten recycled content thresholds and extend producer responsibility schemes across major economies.
For Market Incumbents: Anticipate margin compression from unbundled procurement as supermarket cooperatives negotiate corrugated specifications directly, bypassing 3PL intermediaries. Defend position by deepening captive supply of post-consumer recycled fiber through backward integration into recovered paper sorting infrastructure. Prioritize ISO 18600 certification investment to lock in decade-long automotive contracts. For New Entrants and Emerging Players: Direct-to-manufacturer digital platforms serving fragmented field packing stations in Mediterranean agriculture offer lowest barrier to entry. Target fresh produce distribution in Spain and Italy where pooled rental models displace single-use corrugated at sub-scale operations. Lead with track-and-trace integration for pharmaceutical export corridors facing CDSCO serialization mandates. For Investors and Strategic Acquirers: Asymmetric upside sits with protective systems specialists possessing temperature-validation IP and pharmaceutical lane relationships. Five-to-ten year viability hinges on regulatory compliance capabilities rather than commodity scale. Monitor EU Packaging and Packaging Waste Regulation enforcement timelines as inflection signal for recycled content premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Fiber | Captive OCC supply insulates margins from quarterly index volatility. |
| ISO 18600 Certification Investment | Performance testing protocols gate automotive just-in-sequence contract access. |
| RFID-Enabled Returnable Container Launch | Real-time tracking integrates Tier-1 suppliers into OEM planning systems. |
| Water-Based Ink Retrofit | REACH compliance opens food-contact corrugated retrofit demand. |
| Phase-Change Material Shipper Development | Temperature validation captures biologics distribution lane expansion. |
Study Parameters
Direct dialogue with corrugated converter operations managers, pharmaceutical packaging engineers, automotive procurement leads, and pooled rental network operators grounded the qualitative assessment. Secondary validation drew from EPA sustainable materials management guidance, EU Packaging and Packaging Waste Regulation draft criteria, CDSCO serialization advisories, and customs trade data for containerized packaging flows. Bottom-up volume modeling triangulated against top-down macroeconomic drivers.
Segment-level projections across material type, product form, end-use application, and packaging technology dimensioned the analytical framework over the projection horizon. CAGRs derived from regression analysis of historical volume trends against regulatory implementation schedules and e-commerce fulfillment densification trajectories. Modeled inputs incorporated OCC price elasticity, automotive production forecasts, and pharmaceutical cold chain lane expansion.
Regulatory delay, pulp supply disruption, and automation adoption speed are the dominant revision risks to the outlook. Practitioners should monitor EU enforcement timelines, Chinese state-owned enterprise capacity announcements, and warehouse robotics deployment rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Europe Contract Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market