
 Supplements and Nutrition Packaging Market | 2026-2036
Supplements and Nutrition Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Supplements and Nutrition Packaging Market Intelligence
Post-consumer recycled PET is consolidating share from virgin plastics in supplement bottles as EPR fees widen cost spreads. Amcor Plc leverages global resin procurement networks to stabilize PCR supply across continents. Gerresheimer AG anchors pharmaceutical-grade glass capacity for premium probiotic and omega-3 formats. Glenroy, Inc. specializes in high-barrier flexible films that extend shelf life for moisture-sensitive powders.
Supplements and Nutrition Packaging encompasses primary and secondary containment systems engineered to protect bioactive compounds from oxidation, moisture ingress, and UV degradation through controlled barrier properties, child-resistant mechanisms, and tamper-evident seals. Blister packs with cold-form aluminum laminates dominate pharmaceutical-adjacent vitamin segments where unit-dose compliance drives preference. Pouches capture fastest growth in protein supplements as fitness brands prioritize shelf presence and e-commerce shipability. Glass bottles retain margin concentration in herbal products where amber tinting and inert surfaces justify premium positioning.
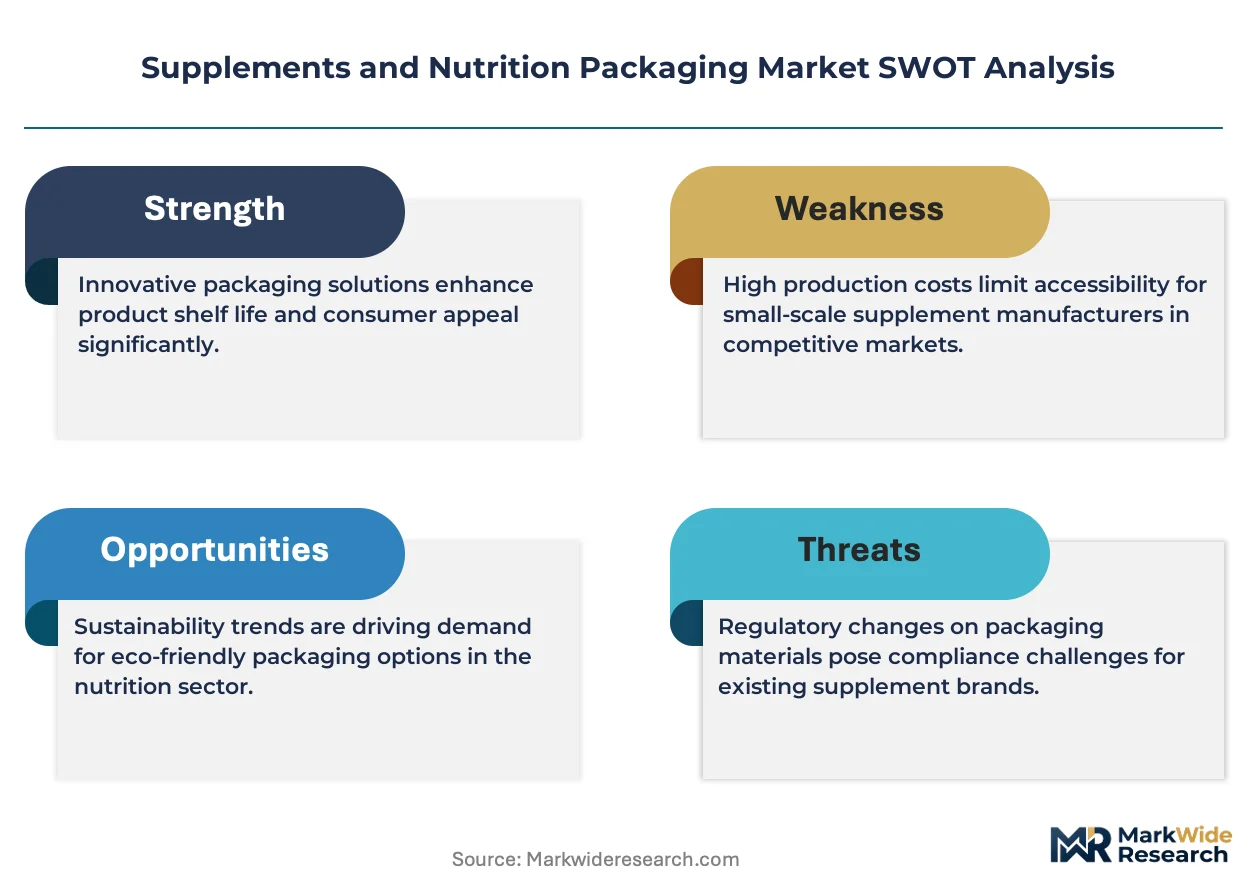
FDA 21 CFR Part 111 cGMP mandates container closure integrity testing for dietary supplement packaging, while EU REACH restricts phthalate plasticizers in vinyl closures destined for European markets. The EU Green Deal's packaging reuse targets force reformulation of multi-layer pouches previously optimized for single-stream recyclability. Stakeholders must decide whether to absorb compliance costs or pass them through in a category where private-label price points already compress branded packaging budgets.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing design cycles for multi-layer flexible formats, forcing converters to choose between compliance investment and portfolio rationalization ahead of 2030 reuse targets.
Growth Catalysts
- EPR fee differentials:Post-consumer recycled PET now carries lower extended producer responsibility levies than virgin resin in Germany, France, and Italy. Brand owners accelerate PCR adoption to hedge regulatory cost escalation.
- Sports nutrition pouch demand:Fitness brands in North America and Western Europe prioritize stand-up pouches with resealable zippers for e-commerce shipability and retail shelf differentiation.
- Pharmaceutical-grade glass anchoring:Premium probiotic and omega-3 formats require amber borosilicate containers with inert surfaces. Gerresheimer AG and Schott AG expand capacity to capture margin concentration in this segment.
Market Restraints
- PCR resin supply fragmentation:Food-grade recycled PET availability concentrates with a limited set of European and North American reprocessors. Amcor Plc and Berry Global compete for contracted volumes.
- Multi-layer pouch recyclability:High-barrier films combining polyethylene, aluminum oxide, and oriented polyamide lack single-stream recycling pathways. Mechanical separation infrastructure remains underdeveloped.
- REACH plasticizer restrictions:ECHA limitations on phthalates in vinyl closures force reformulation of child-resistant caps. Suppliers absorb R&D costs or risk European market exclusion.
Strategic Opportunities
- Indian contract manufacturing expansion:CDSCO regulatory harmonization and FSSAI packaging standards alignment position Mumbai and Hyderabad as export hubs for European and North American supplement brands.
- Refill station infrastructure:EU Green Deal reuse targets incentivize bulk powder dispensing systems. Retailers in Denmark and the Netherlands pilot in-store refill for protein and collagen products.
- Digital printing convergence:HP Indigo and Xeikon technologies enable short-run variable data for personalized nutrition. Brands test SKU proliferation without plate-changeover penalties.
Industry Challenges
- Cold-chain validation for live cultures:Probiotic packaging requires thermal stability testing across distribution networks. FDA 21 CFR Part 111 cGMP mandates container closure integrity documentation that extends qualification timelines.
- Barrier film talent scarcity:Coextrusion die design and aluminum oxide deposition expertise concentrates with aging technical workforces in Germany and Japan. Knowledge transfer to emerging facilities lags capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supplements and Nutrition Packaging Market |
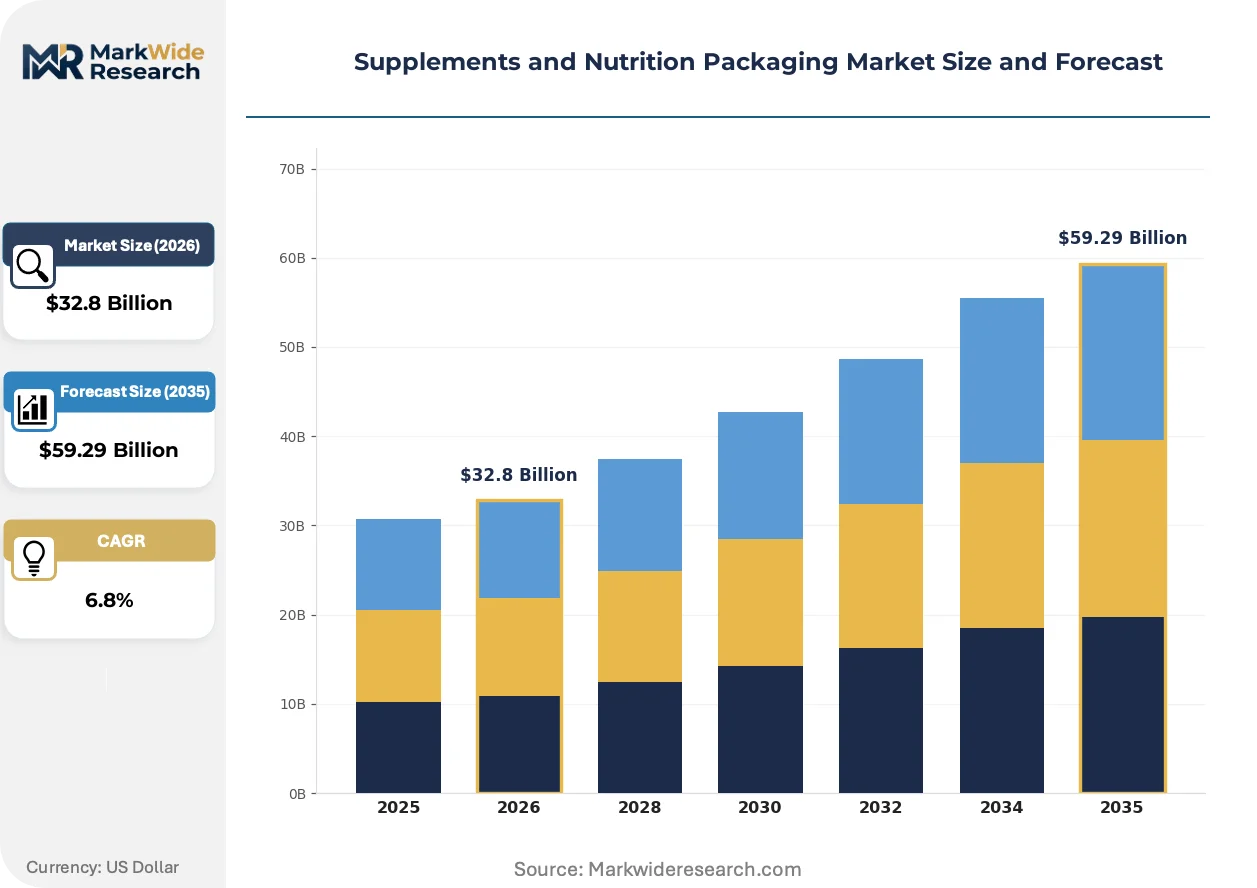
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $59.29 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Blisters, Jars Material: Plastic, Glass, Metal, Paper Closure Type: Screw Cap, Flip Top, Snap On, Tamper Evident End Use: Vitamins, Protein Supplements, Herbal Products, Pre-workout |
| Companies Covered | SGD Pharma, Stoelzle Glass Group, Amcor Plc, Comar, LLC, ePac Holdings, LLC, Tetra Pak, Glenroy, Inc., Graham Packaging Company, Gerresheimer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supplements and Nutrition Packaging Market Strategic Shifts & Innovations
Digital manufacturing workflows and material science breakthroughs are collapsing development cycles for moisture-sensitive formats, compressing the gap between laboratory validation and commercial scale-up.
Mono-material polyethylene pouches with enhanced ethylene vinyl alcohol barrier layers are decentralizing supply chain risk for protein powder brands. Nestlé Health Science and Glanbia PLC specify these formats for European distribution to preempt EPR complexity. The shift enables regional sourcing of resin and film conversion, reducing transoceanic shipping exposure.
REACH authorization requirements for bisphenol A in epoxy can linings are accelerating migration to polyester and oleoresinous coatings for omega-3 liquid supplements. German and Dutch brand owners reformulate fill processes to accommodate modified surface chemistries. The transition compresses supplier qualification windows ahead of 2025 sunset dates.
Direct-to-consumer subscription models are fragmenting order profiles for contract packagers. Brands like Ritual and Care/of specify lot sizes below 5,000 units with weekly replenishment cycles. This pattern concentrates in North American urban corridors where last-mile logistics infrastructure supports cold-chain delivery of refrigerated probiotics.
Supplements and Nutrition Packaging Market Segmentation
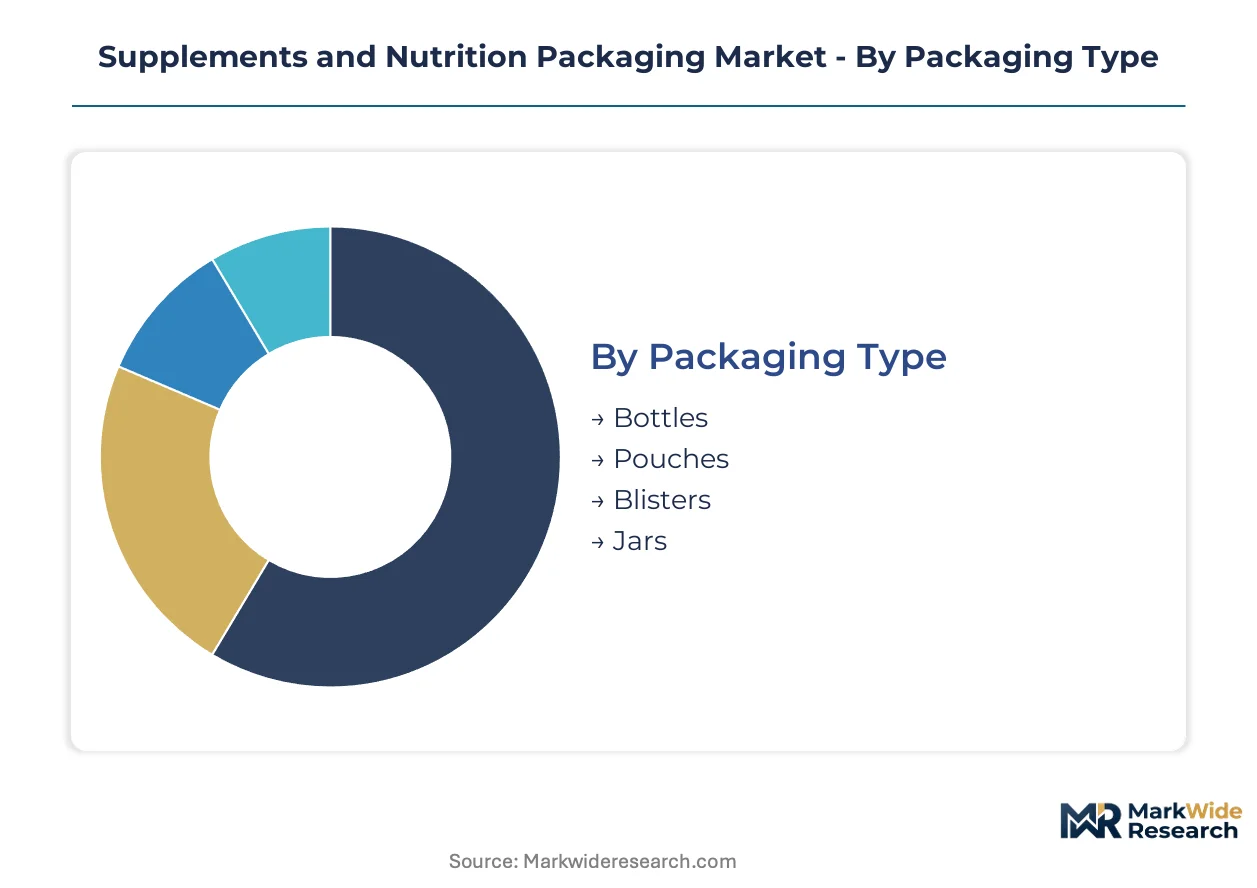
Packaging format selection in supplements and nutrition hinges on barrier requirements against moisture and oxidation, child-resistance mandates, and e-commerce shipability. Segmentation reveals how material science and regulatory compliance fragment procurement strategies across brand tiers.
Packaging Type:
Volume concentrates in formats optimized for powder flow and tablet protection, while premium positioning favors formats with tactile differentiation and shelf presence.
- Bottles:HDPE and PET containers with desiccant-lined closures dominate vitamin and mineral segments. Demand clusters in North American mass-market channels where cGMP compliance documentation simplifies FDA inspections.
- Pouches:Stand-up flexible formats with resealable zippers capture protein supplement distribution. Fitness brands in Germany and the Netherlands specify high-barrier laminates for e-commerce resilience against puncture and moisture ingress.
- Blisters:Cold-form aluminum laminates serve unit-dose compliance packaging for pharmaceutical-adjacent vitamin segments.
- Jars:Wide-mouth containers accommodate scoop access for pre-workout powders and collagen peptides.
Today's leader: Bottles. Tomorrow's challenger: Pouches.
Material:
Cost tier stratification separates virgin resin dependence from sustainability premiums, with regulatory fee structures accelerating material migration.
- Plastic:Post-consumer recycled PET bottles displace virgin resin as EPR fee differentials widen in Germany, France, and Italy. Amcor Plc and Berry Global compete for contracted food-grade reprocessor volumes.
- Glass:Amber borosilicate containers anchor premium probiotic and omega-3 formats where inert surfaces prevent oxidation. Gerresheimer AG expands pharmaceutical-grade capacity to capture margin concentration.
- Metal:Aluminum canisters serve effervescent tablet formats requiring complete light and moisture exclusion.
- Paper:Fiber-based cartons and secondary packaging gain traction in European markets facing EU Green Deal reuse targets.
Plastic retains volume dominance. Glass commands margin premiums.
Closure Type:
Child-resistance certification and tamper evidence separate regulatory-compliant formats from commodity alternatives in retail and direct-to-consumer channels.
- Screw Cap:Standard threaded closures with induction seals dominate vitamin bottles. Cost efficiency drives specification in private-label contracts.
- Flip Top:Hinged lids with audible closure feedback serve sports nutrition pouches and on-the-go formats. Fitness brands prioritize single-handed operation.
- Snap On:Press-fit closures accommodate jar formats for powder supplements where reseal integrity matters less than access speed.
- Tamper Evident:Breakaway bands and shrink sleeves satisfy FDA 21 CFR Part 111 requirements for dietary supplement container integrity documentation.
Screw caps anchor baseline compliance. Tamper-evident features expand fastest.
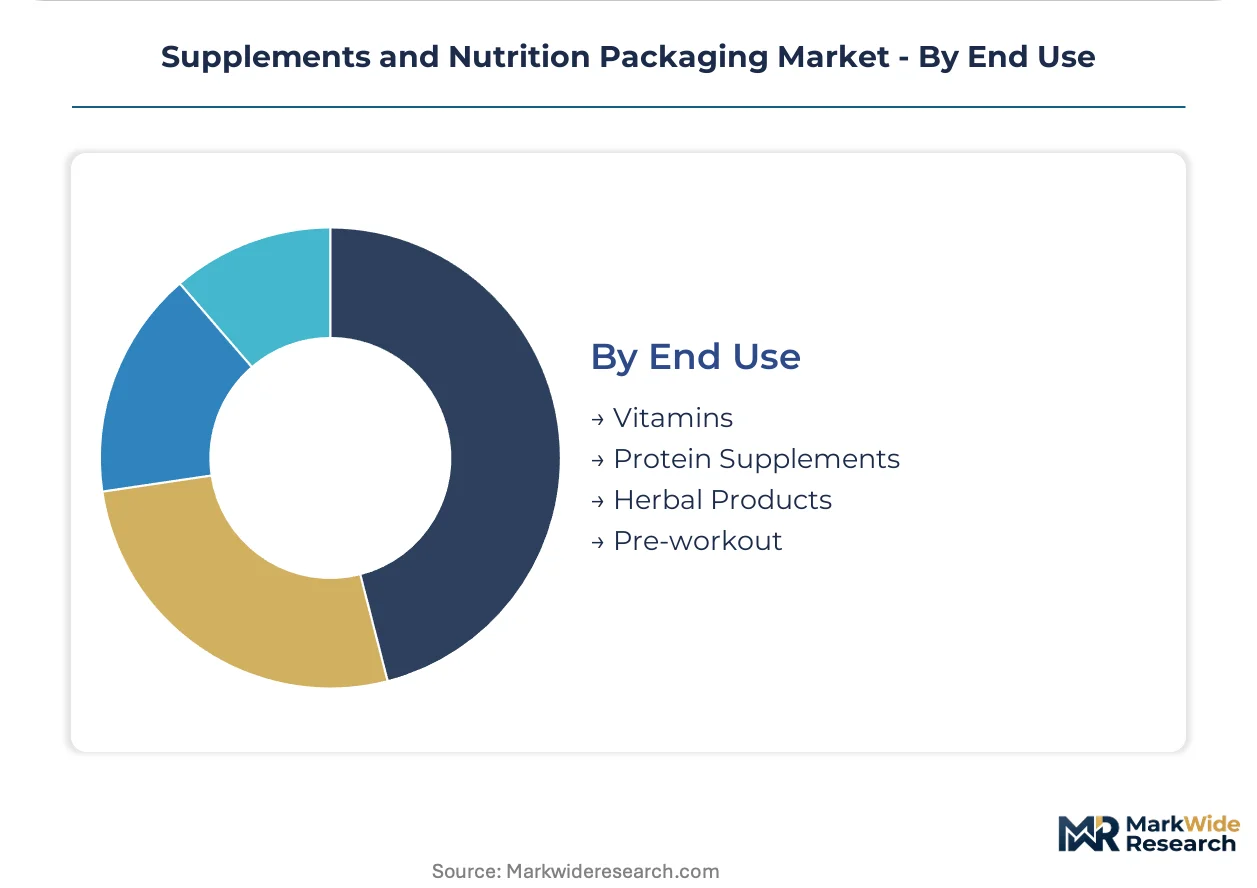
End Use:
Application-driven packaging requirements split between moisture-sensitive powders, oxidation-prone oils, and compliance-critical tablets.
- Vitamins:Multi-tablet and gummy formats demand bottles with desiccant integration and UV-opaque walls. Unit-dose blisters serve pharmaceutical-adjacent segments.
- Protein Supplements:Whey and plant-based powders specify high-barrier pouches with resealable zippers. Nestlé Health Science and Glanbia PLC drive mono-material polyethylene adoption in Europe.
- Herbal Products:Amber glass bottles with inert surfaces preserve volatile compounds. Premium positioning justifies higher packaging costs.
- Pre-workout:Hygroscopic powder formulations require moisture-barrier jars or pouches with silica gel integration.
Protein supplements drive pouch innovation. Herbal products sustain glass demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's contract packaging corridor anchors continental supply for Central European supplement brands, with EPR fee structures accelerating material transitions across member states.
United States
FDA 21 CFR Part 111 cGMP inspections drive container closure integrity documentation for domestic vitamin manufacturers. Sports nutrition brands in Utah and California specify high-barrier pouches for direct-to-consumer subscription models. The Mountain West corridor concentrates powder packaging capacity serving protein supplement distribution.
Germany
EPR fee differentials between post-consumer recycled PET and virgin resin compress procurement timelines for contract packagers. The EU Packaging and Packaging Waste Regulation forces multi-layer pouch reformulation ahead of 2030 reuse targets. North Rhine-Westphalia hosts flexible film converters supplying amber borosilicate alternatives for omega-3 formats.
India
CDSCO regulatory harmonization and FSSAI packaging standards alignment position Mumbai and Hyderabad as export fabrication hubs. Domestic Ayurvedic supplement brands drive amber glass demand for volatile compound preservation. Maharashtra's pharmaceutical packaging cluster extends capacity into dietary supplement containment systems.
China
NMPA alignment with international cGMP standards accelerates qualification timelines for export-oriented contract manufacturers. Dual carbon goals compress virgin resin dependence in favor of mechanically recycled alternatives. The Yangtze River Delta concentrates flexible film conversion for moisture-sensitive powder formats.
Netherlands
EU Green Deal reuse targets incentivize bulk powder refill station pilots in Amsterdam and Rotterdam retail networks. REACH authorization timelines for bisphenol A accelerate coating transitions in omega-3 liquid supplement packaging. The Randstad corridor anchors sustainable pouch innovation for European protein brands.
Supplements and Nutrition Packaging Market Key Industry Players
Capacity expansion dominates the current landscape as converters race to install pharmaceutical-grade glass furnaces and mono-material film extrusion lines ahead of regulatory deadlines. The vendor base stratifies across three tiers: multinational resin-integrated conglomerates, regional flexible film specialists, and pharmaceutical-grade glass fabricators. Strategic archetypes include EPR-optimized recyclers, barrier film innovators, and cGMP-certified containment providers. M&A activity concentrates in European PCR reprocessor networks, while technology licensing spreads mono-material pouch formulations across Asian manufacturing bases.
Within the pharmaceutical-grade glass tier, SGD Pharma and Stoelzle Glass Group exemplify capacity-led positioning for premium probiotic and omega-3 formats. Among resin-integrated multinationals, Amcor Plc occupies a position reflecting global procurement network scale for post-consumer recycled PET stabilization. Glenroy, Inc. anchors the high-barrier flexible film specialist archetype, representing expertise in moisture-sensitive powder containment.
| Leading Market Players |
|---|
| SGD Pharma |
| Stoelzle Glass Group |
| Amcor Plc |
| Comar, LLC |
| ePac Holdings, LLC |
| Tetra Pak |
| Glenroy, Inc. |
| Graham Packaging Company |
| Gerresheimer AG |
| Others |
Cost & Logistics Intelligence
EPR fee differentials in Germany, France, and Italy now force brand owners toward post-consumer recycled PET procurement, compelling converters to absorb resin qualification costs or surrender margin to virgin-resin competitors. This demand-side mandate reshapes supplier pricing power across European contract packaging corridors.
Pricing Analysis
Input-cost pass-through from food-grade recycled PET scarcity now governs contract negotiations between Amcor Plc and Berry Global. Three-tier pricing structure across pharmaceutical-grade glass, high-barrier flexible films, and commodity virgin resin separates margin tiers. Cost compression in multi-layer pouch segments intensifies because REACH plasticizer restrictions force cap reformulation. Private-label vitamin manufacturers exhibit highest price sensitivity; premium probiotic brands anchored by Gerresheimer AG glass contracts show lowest.
Supply Chain Analysis
Direct-to-brand channels handle hyperscale fitness nutrition demand through North American and Western European pouch converters. Raw material supply concentrates in Germany, China, and India for flexible film substrates, desiccant components, and amber borosilicate glass respectively. Converter networks draw from European and North American PCR reprocessors, Japanese aluminum oxide deposition equipment, and Indian pharmaceutical-grade glass furnaces. Single-source vulnerability in food-grade recycled PET reprocessing threatens supply continuity. Distribution runs through contract packager intermediaries serving Central European supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Demand is migrating toward pharmaceutical-grade containment specifications as live-culture probiotic formats capture margin concentration from commodity vitamin segments.
For Market Incumbents: Hedge PCR resin supply fragmentation by locking multi-year offtake agreements with European reprocessors before competitor bidding intensifies. Defend against emerging mono-material pouch specialists by accelerating EPR-optimized format certification in Germany and the Netherlands. Capacity addition in pharmaceutical-grade glass furnaces represents the critical lever for margin preservation. For New Entrants and Emerging Players: Direct-to-consumer subscription brands with sub-5,000 unit lot sizes present the most penetrable buyer archetype. Digital printing convergence enables personalized nutrition packaging without plate-changeover penalties. White-space exists in Indian contract manufacturing for export-oriented European brands. Go-to-market should emphasize short-run flexibility and cold-chain validation documentation. For Investors and Strategic Acquirers: Asymmetric upside sits with high-barrier flexible film specialists possessing aluminum oxide deposition expertise. Long-term viability favors converters with backward integration into resin reprocessing or captive glass furnace capacity. Acquisition targets should demonstrate EPR compliance roadmaps and cGMP certification depth. The signal to watch is EU Packaging and Packaging Waste Regulation enforcement velocity ahead of reuse targets.| Strategic Initiative | Industry Significance |
|---|---|
| PCR Resin Supply Lock-in | Multi-year offtake agreements with European reprocessors stabilize input costs against EPR fee escalation. |
| Pharmaceutical-Grade Glass Expansion | Gerresheimer AG and SGD Pharma furnace additions capture margin concentration in premium probiotic formats. |
| Mono-Material Pouch Reformulation | Nestlé Health Science and Glanbia PLC specifications preempt EU Green Deal recyclability complexity. |
| Digital Printing Convergence | HP Indigo and Xeikon installations enable subscription-brand SKU proliferation without plate penalties. |
| Indian Contract Manufacturing Scale-Up | CDSCO harmonization positions Mumbai and Hyderabad as export fabrication hubs for European brands. |
Research Approach
Multiple input streams — primary interviews with packaging procurement directors, regulatory affairs leads at supplement brands, and flexible film converter operations heads; secondary validation against FDA 21 CFR Part 111 guidance documents, ECHA REACH authorization databases, and EU Packaging and Packaging Waste Regulation impact assessments — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across packaging format demand, material migration patterns, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include primary containment format, barrier technology tier, closure certification level, and end-use application. CAGRs were derived from volume trajectory analysis incorporating EPR fee differential impacts and pharmaceutical-grade glass capacity expansion schedules.
Inputs from converter capacity announcements, regulatory filing databases, and brand owner sustainability disclosures were available through the study window; gaps in real-time PCR resin spot pricing and private-label contract terms introduce uncertainty bands. Forecasts reflect documented assumptions regarding EU Green Deal enforcement velocity and REACH sunset date adherence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
FMCG Packaging Market