
 Insulated Food Containers Market | 2026-2036
Insulated Food Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Food Containers Market Outlook
Specialized polymer engineers and thermal-design technicians is redrawing how manufacturers compete in insulated food containers. Thermos leverages decades of vacuum-insulation expertise to sustain premium positioning across Asian and North American retail channels. Igloo anchors mass-market volume through dominant placement in big-box wholesale and outdoor recreation distribution. Zojirushi differentiates through precision temperature-retention engineering that commands loyalty in household and commercial catering segments.
Insulated food containers are engineered thermal vessels employing double-wall vacuum construction, foam-injection barriers, or phase-change gel linings to maintain safe food temperatures for four to twelve hours in ambient conditions. Their primary commercial purpose centers on hazard-analysis compliance for mobile food service, meal-delivery logistics, and outdoor consumption where active heating or refrigeration remains unavailable. Stainless steel thermal jars capture the dominant margin pool due to durability premiums and food-grade certification requirements, while food carriers designed for catering services represent the fastest-expanding application segment as event-based and ghost-kitchen delivery formats multiply. Plastic lunch boxes retain volume leadership in household channels where cost sensitivity and lightweight portability outweigh longevity demands.
The FDA's Food Code provisions on time-temperature control, combined with OSHA workplace meal-storage guidelines and California's CalRecycle rigid-plastic recycling mandates, collectively elevate material traceability and thermal-performance testing requirements for market access. These frameworks push manufacturers toward stainless steel substitution and certified insulation testing documentation. Stakeholders must monitor how state-level extended-producer-responsibility legislation and emerging federal food-delivery safety standards reshape material choices and channel compliance costs.
Market Dynamics
Vacuum-insulation engineering is fragmenting competitive advantage across the insulated food container landscape, as proprietary thermal-retention protocols migrate from household brands toward contract manufacturers serving food-service logistics.
Growth Catalysts
- Food truck fleet expansion:Mobile food service operators in Texas and California urban corridors are standardizing vacuum-insulated carrier procurement to maintain FDA Food Code time-temperature compliance during extended service windows.
- Phase-change gel integration:Advanced thermal liners incorporating proprietary gel formulations are extending safe-hold duration from four hours toward twelve-hour thresholds for ghost-kitchen delivery routes.
- CalRecycle rigid-plastic mandates:California's extended producer responsibility frameworks are accelerating stainless steel substitution across food-service channels, elevating certified thermal-performance documentation requirements.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost fluctuations are compressing margin structures for vacuum-insulation fabricators dependent on food-grade 304 and 316 substrates.
- Asian supply concentration:Vacuum-panel manufacturing capacity clusters in specific Chinese industrial zones, creating exposure to regional logistics disruptions and export-control friction.
- Foam-injection technical ceiling:Polyurethane barrier systems face hard limits on thermal conductivity reduction, blocking further efficiency gains without material substitution.
Strategic Opportunities
- German commercial catering penetration:Event-based food logistics in Bavaria and North Rhine-Westphalia remain underpenetrated by precision-engineered thermal carriers, presenting white-space entry for certified suppliers.
- India railway meal logistics:IRCTC contract modernization and FSSAI cold-chain mandates are opening institutional procurement channels for validated four-hour retention containers.
- EU Green Deal material incentives:REACH-compliant recycled stainless steel sourcing subsidies are lowering compliance costs for manufacturers achieving ECHA-registered circularity certification.
Industry Challenges
- Thermal-design technician scarcity:Specialized polymer engineers capable of optimizing vacuum-panel geometry against food-safety validation protocols command premium compensation, constraining R&D throughput.
- FDA 510(k) parallel pathway complexity:Dual-use containers crossing into medical meal delivery trigger extended premarket notification timelines, delaying commercial launch schedules.
- Legacy ERP integration friction:Temperature-logger IoT telemetry systems require substantial middleware development to interface with established food-service distributor inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Food Containers Market |
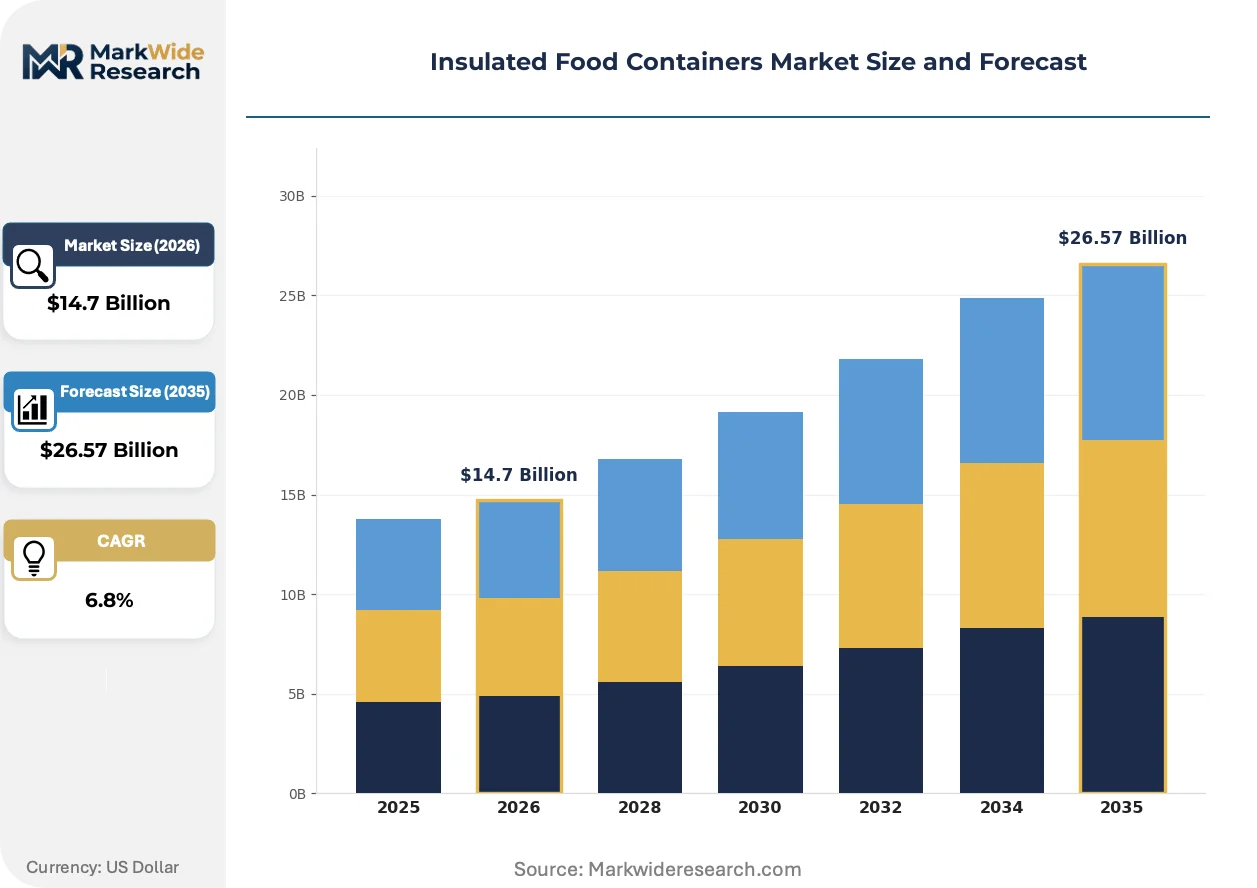
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Jars, Food Carriers, Lunch Boxes, Vacuum Flasks Material: Stainless Steel, Plastic, Glass, Silicone End User: Households, Restaurants, Catering Services, Food Trucks Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Stanley, Igloo, Thermos, Klean Kanteen, Rubbermaid, Zojirushi, CamelBak, FoodSaver, Contigo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Food Containers Market Strategic Shifts
Aerogel composite liners and solid-state phase-change materials are redrawing thermal-performance benchmarks, while regulatory pressure on material traceability accelerates substitution away from conventional polymer barriers.
Aerogel-infused vacuum panels are decomposing the traditional cost-performance tradeoff that confined super-insulation to premium household segments. Ghost-kitchen operators in London and Singapore are piloting these carriers for sub-zero delivery routes previously requiring active refrigeration. The technology is decomposing the boundary between passive and active cold-chain economics, compressing addressable market definitions across food-logistics procurement.
REACH SVHC disclosure requirements and EU F-Gas Regulation amendments are tightening material traceability for polyurethane foam blowing agents. Manufacturers serving European food-service channels must now document full supply-chain substance inventories through SCIP database registration. German and French catering distributors are responding by consolidating supplier bases toward ECHA-registered partners with pre-validated circularity protocols.
Food-service buyers are unbundling container procurement from temperature-logger service contracts, treating IoT telemetry as a separate vendor category. This fragmentation is disrupting the bundled-hardware-software model that dominated ghost-kitchen equipment leasing. The pattern is most visible in California and Texas, where third-party logistics platforms now specify open-protocol data standards independent of container manufacturer ecosystems.
Insulated Food Containers Market Segmentation
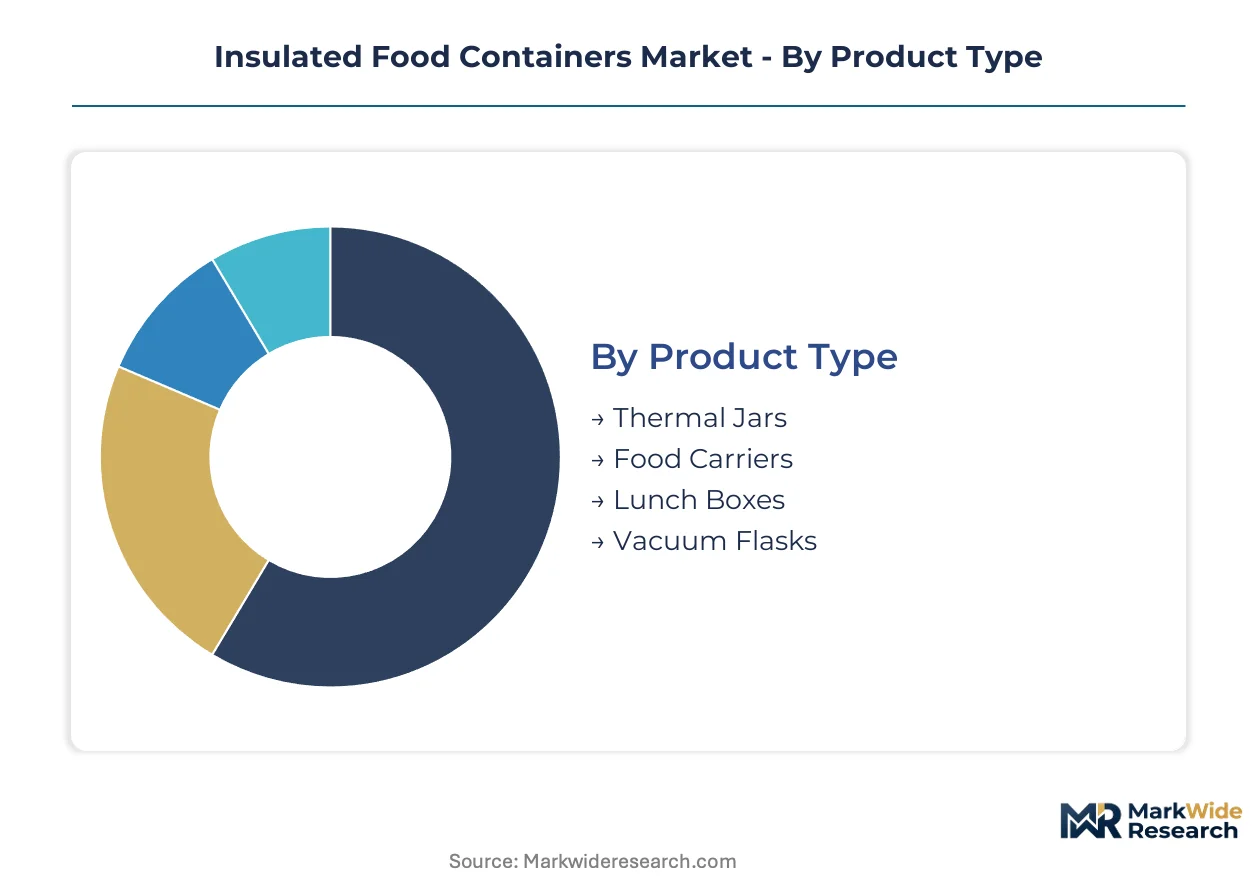
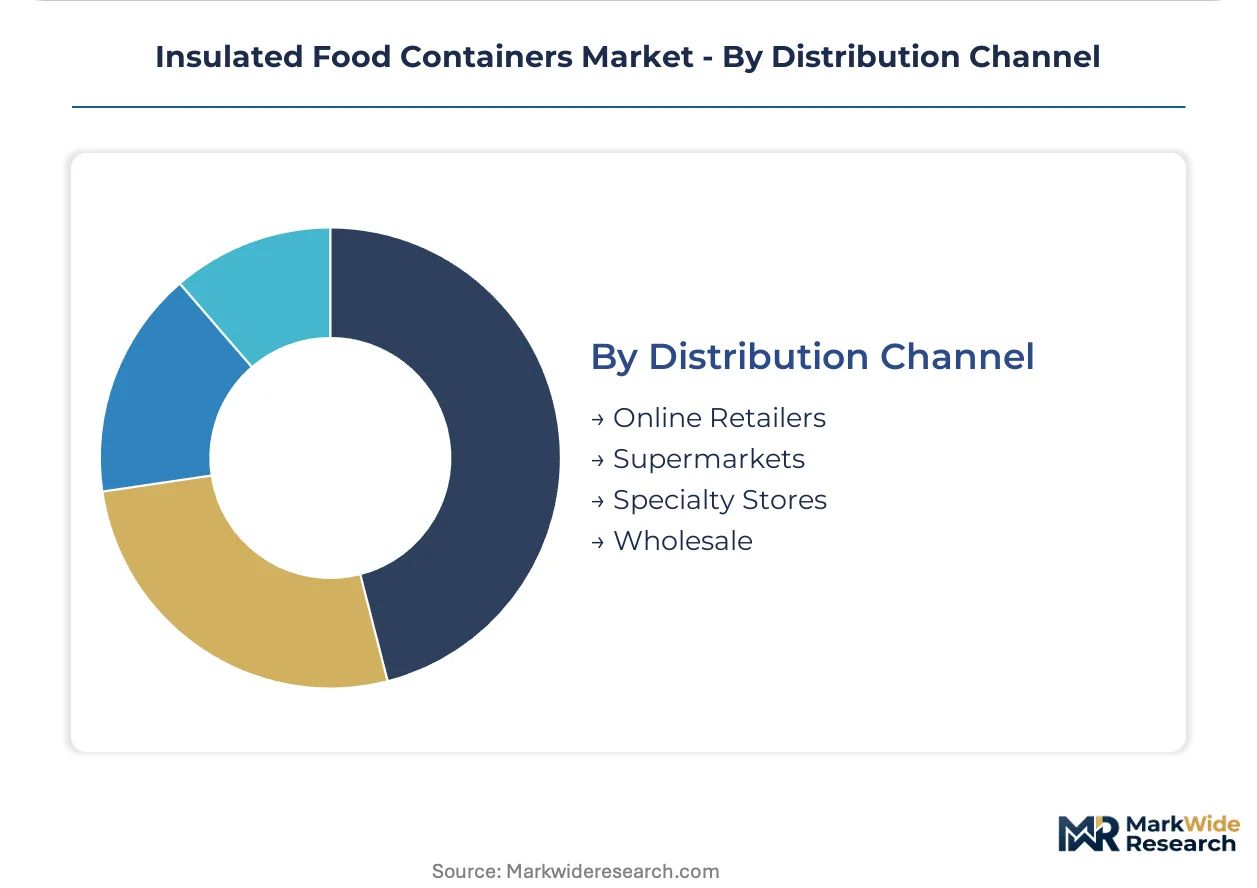
Insulated food container procurement channels fragment sharply by performance certification requirements and volume scale. Food-service buyers prioritize thermal-validation documentation while household purchasers trade retention duration against unit cost.
Product Type:
Channel-mix patterns diverge: food-service logistics channels concentrate around certified carriers, while retail channels fragment across convenience-oriented formats.
- Thermal Jars:Double-wall vacuum construction with food-grade 304 stainless steel inner chambers dominates commercial catering procurement. California and Texas food truck operators are standardizing these units for FDA Food Code time-temperature compliance during extended service windows.
- Food Carriers:Multi-compartment thermal vessels with phase-change gel integration are displacing passive foam systems in ghost-kitchen delivery fleets. Bavaria and North Rhine-Westphalia event-catering logistics show underpenetration, presenting white-space entry for certified suppliers.
- Lunch Boxes:Lightweight polymer shells with polyurethane barriers retain household channel volume leadership where portability outweighs longevity demands.
- Vacuum Flasks:Narrow-neck liquid-focused designs capture beverage-service niches in railway and institutional meal programs.
By volume, Lunch Boxes leads. By growth pace, Food Carriers is ahead.
Material:
Cost tiers stratify sharply: premium substrates command food-service certification premiums while commodity polymers retain mass-market penetration.
- Stainless Steel:Food-grade 304 and 316 substrates capture the dominant margin pool through durability premiums and FDA-compliant surface finishes. CalRecycle mandates are accelerating substitution across California food-service channels.
- Plastic:Polypropylene and copolyester formulations dominate household retail through cost sensitivity alignment. REACH SVHC disclosure requirements and EU F-Gas Regulation amendments are tightening traceability for polyurethane foam blowing agents.
- Glass:Borosilicate double-wall construction retains niche positioning in health-conscious consumer segments.
- Silicone:Flexible collapse designs address space-constrained outdoor recreation and travel applications.
By margin capture, Stainless Steel leads. By unit volume, Plastic is ahead.
End User:
Application requirements dictate specification divergence: commercial buyers demand validated retention protocols while household users prioritize convenience attributes.
- Households:Individual and family units drive replacement-cycle demand through aesthetic refresh and portability upgrades. Cost sensitivity and lightweight design outweigh longevity demands in channel procurement.
- Restaurants:Full-service and quick-service operators are unbundling container procurement from temperature-logger service contracts. California and Texas third-party logistics platforms now specify open-protocol data standards independent of manufacturer ecosystems.
- Catering Services:Event-based food logistics in Germany remain underpenetrated by precision-engineered thermal carriers.
- Food Trucks:Mobile operators in California and Texas urban corridors are standardizing vacuum-insulated carrier procurement for extended service window compliance.
By absolute volume, Households leads. By specification intensity, Food Trucks is ahead.
Distribution Channel:
Customer type determines channel routing: institutional buyers consolidate through wholesale while fragmented household demand disperses across retail formats.
- Online Retailers:Direct-to-consumer platforms enable specification comparison and thermal-performance documentation access. Ghost-kitchen equipment leasing fragmentation is disrupting bundled-hardware-software models.
- Supermarkets:Mass-market placement anchors volume for polymer lunch box categories. Big-box wholesale placement sustains outdoor recreation distribution.
- Specialty Stores:Premium vacuum-insulation expertise sustains positioning across Asian and North American retail channels.
- Wholesale:Food-service distributor inventory platforms require substantial middleware development for temperature-logger IoT telemetry integration.
By household penetration, Supermarkets leads. By growth pace, Online Retailers is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA food safety protocols anchor demand concentration in the United States, where mobile food service expansion and ghost-kitchen logistics are reshaping procurement patterns across multiple state-level markets.
United States
California and Texas urban corridors are standardizing vacuum-insulated carrier procurement for food truck FDA compliance. CalRecycle rigid-plastic mandates accelerate stainless steel substitution across Los Angeles and Houston food-service channels. FDA Food Code time-temperature control requirements elevate certified thermal-performance documentation for interstate logistics.
Germany
Bavaria and North Rhine-Westphalia event-catering logistics show underpenetration by precision-engineered thermal carriers. REACH SVHC disclosure requirements and EU F-Gas Regulation amendments tighten material traceability for polyurethane foam systems. ECHA-registered circularity certification is consolidating supplier bases toward pre-validated partners in Frankfurt-Rhine-Main industrial clusters.
China
Vacuum-panel manufacturing capacity clusters in specific industrial zones serving export markets for food-grade 304 and 316 substrates. GB standards and SAMR quality frameworks govern domestic food-contact material certification. Yangtze River Delta fabrication hubs face exposure to regional logistics disruptions and export-control friction.
India
IRCTC contract modernization and FSSAI cold-chain mandates open institutional procurement channels for validated retention containers. Maharashtra and Karnataka urban corridors drive household replacement-cycle demand through portability upgrades. National railway meal logistics represent emerging volume anchors for four-hour certified thermal systems.
United Kingdom
Ghost-kitchen operators in London are piloting aerogel-infused vacuum panels for sub-zero delivery routes. GDPR-compliant IoT telemetry fragmentation disrupts bundled hardware-software procurement models. REACH-aligned material traceability requirements are elevating documentation burdens for polyurethane barrier systems across Southeast distribution channels.
Insulated Food Containers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with household-name brands commanding premium positioning through decades of vacuum-insulation expertise while contract manufacturers capture food-service logistics volume. The market structure stratifies across three archetypes: heritage thermal-engineering houses, mass-market outdoor recreation suppliers, and precision-catering specialists. Consolidation pressure is elevating through strategic partnerships for IoT telemetry integration and geographic licensing arrangements for aerogel composite technologies.
Within the heritage-engineering tier, Thermos and Zojirushi exemplify precision temperature-retention positioning that commands loyalty across household and commercial catering segments. Stanley occupies a position bridging outdoor recreation durability with food-service compliance documentation. Among mass-market fabricators, Igloo anchors volume through dominant wholesale placement. These named entities represent archetype anchors rather than exhaustive market coverage, with each sitting within distinct competitive vectors defined by certification intensity, channel access, and thermal-performance tiering.
| Leading Market Players |
|---|
| Stanley |
| Igloo |
| Thermos |
| Klean Kanteen |
| Rubbermaid |
| Zojirushi |
| CamelBak |
| FoodSaver |
| Contigo |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day raw material lead times for food-grade 304 stainless steel coil concentrate procurement leverage in Yangtze River Delta fabrication hubs, compressing margin structures for vacuum-insulation fabricators while elevating pricing power for certified thermal-performance documentation holders serving California food-service channels.
Pricing Analysis
California-to-Texas price spreads for certified vacuum-insulated carriers run three-tier pricing structure across premium, standard, and economy levels, with FDA Food Code compliance tier and volume scale as primary differentiation drivers. Cost compression in standard-grade polymer lunch boxes is intensifying because REACH SVHC disclosure requirements elevate traceability burdens. Household retail channels exhibit highest price sensitivity, while ghost-kitchen logistics buyers prioritize thermal-validation documentation over unit cost.
Supply Chain Analysis
Port congestion on Shanghai-to-Long Beach trade lanes elevates inbound logistics costs for vacuum-panel assemblies, with supply concentration in China, South Korea, and Japan for food-grade 304 and 316 substrates. Raw material dependencies rest on nickel, chromium, and proprietary phase-change gel formulations. Single-source vulnerability clusters in specific Chinese industrial zones for vacuum-panel manufacturing capacity. Distribution runs through food-service wholesale distributors requiring middleware development for IoT telemetry integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where FDA Food Code compliance documentation and ECHA-registered circularity certification create switching costs that lock in institutional procurement relationships.
For Market Incumbents: Secure thermal-design technician talent pools through captive training partnerships with polymer engineering programs, insulating R&D throughput from capability scarcity. Deepen backward integration into food-grade stainless steel finishing capacity in Yangtze River Delta clusters to defend against nickel price volatility and Asian supply concentration risks.
For New Entrants and Emerging Players: FDA 510(k) parallel pathway fast-track for dual-use containers crossing into medical meal delivery opens white-space entry with extended premarket notification timelines that deter rapid competitive response. Target Bavaria and North Rhine-Westphalia event-catering logistics through ECHA-registered circularity certification as the most penetrable geography, deploying direct technical sales to institutional procurement committees.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because IoT telemetry fragmentation and aerogel composite technology licensing arrangements are elevating strategic partnership premiums for integrated hardware-software capabilities. Acquisition target archetype: mid-cap specialists with validated four-hour retention protocols and pre-installed temperature-logger middleware. Signal to watch: CalRecycle mandate expansion into neighboring states as inflection indicator for stainless steel substitution acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Telemetry Middleware Development | Open-protocol integration with third-party logistics platforms unbundles bundled-hardware-software procurement models in California and Texas. |
| ECHA-Registered Circularity Certification | Pre-validated supply-chain substance inventories through SCIP database registration consolidate supplier bases in German and French catering distribution. |
| Aerogel Composite Technology Licensing | Geographic licensing arrangements for sub-zero delivery routes compress addressable market definitions across London and Singapore ghost-kitchen procurement. |
| Thermal-Design Technician Training Partnerships | Captive polymer engineering program pipelines constrain R&D throughput bottlenecks from specialized talent scarcity. |
| Backward Integration into Stainless Steel Finishing | In-house food-grade 304 and 316 substrate capacity insulates margin structures from nickel and chromium input cost fluctuations. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA Food Code guidance documents, ECHA SCIP database registrations, and customs trade data for vacuum-panel assemblies, combining interviews with thermal-design technicians, food-service procurement managers, ghost-kitchen logistics operators, and polymer engineering directors with bottom-up and top-down triangulation.
Segmentation dimensions modeled span product type, material substrate, end-user application, and distribution channel across the analysis window, with CAGRs derived from volume trajectory reconciliation against price-band stratification. Forecast inputs incorporate food truck fleet expansion rates in California and Texas urban corridors and IRCTC contract modernization timelines for railway meal logistics.
Decision-makers should treat outputs as directional under sustained FDA Food Code enforcement intensity and stable nickel-chromium price corridors; material deviation in regulatory expansion velocity or commodity input volatility would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Europe Punnet Trays Market
Packaging Containers
Logistics Packaging Market
Packaging Containers
Food Grade Bottles Market
Packaging Containers
Foldable Mailer Box Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Portion Packs Market
Packaging Containers
Thermoform Cups Market
Packaging Containers
Wrist Watch Packaging Market
Packaging Containers
Gable Top Liquid Cartons Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Euro Box Market
Packaging Containers
Tamper Evident Pots and Tubs Market
Packaging Containers
Dosage Cups Market
Packaging Containers
VCI Bags Market
Packaging Containers
Insulated Storage Vessel Market
Packaging Containers
Custom Boxes Market