
 Shelf Stable Packaging Market | 2026-2036
Shelf Stable Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Shelf Stable Packaging Market Analytics
Multi-source procurement for barrier films and substrates is expanding as brand owners reduce dependency on single converters. Amcor plc leverages its global extrusion network to sustain supply security across aseptic carton and flexible pouch lines. Mondi Group anchors European kraft paper supply for shelf-stable formats, while Sonoco Products Company competes through rigid paperboard canister specialization in North American retail channels.
Shelf stable packaging denotes systems engineered to preserve product integrity without refrigeration through controlled barrier properties, thermal treatment integration, and oxygen/moisture exclusion. Aseptic packaging employs hydrogen peroxide sterilization of paperboard-laminate reels paired with ultra-high-temperature product filling to achieve commercial sterility at ambient distribution. Pouches lead growth in lightweight convenience segments where material efficiency and logistics optimization concentrate margin pools, while cans retain dominance in protein-rich categories where oxygen impermeability and mechanical durability remain non-negotiable. Modified atmosphere packaging technology is displacing conventional vacuum methods in premium ready-meal applications as nitrogen-flushing precision improves residual oxygen control.
The FDA enforces 21 CFR Part 113 and 114 for low-acid and acidified foods, directly governing thermal process validation and container integrity standards for shelf-stable formats in the United States. EFSA and the EU Packaging and Packaging Waste Regulation collectively shape migration limits and recyclability quotas across European supply chains, while China's SAMR implements GB standards for composite food contact materials that constrain laminate layer specifications. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material recyclability mandates to anticipate converter qualification requirements and packaging redesign cycles.
Market Dynamics
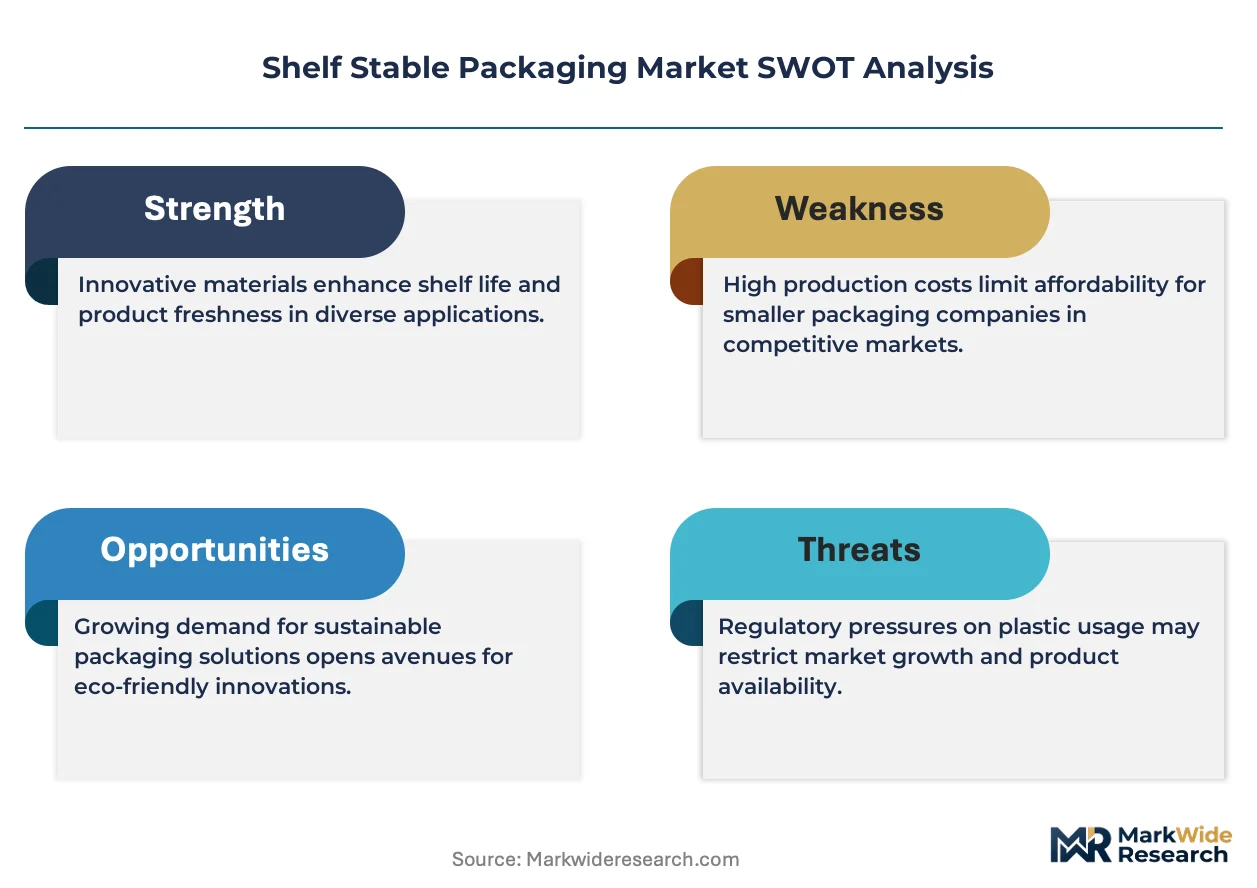
The EU Packaging and Packaging Waste Regulation is forcing converters to abandon multi-layer laminates in favor of mono-material structures, triggering a wholesale redesign of barrier film architectures across ambient food supply chains.
Growth Catalysts
- Urbanization in emerging economies:Cold-chain infrastructure gaps in India and Brazil sustain demand for aseptic cartons and retort pouches as primary distribution formats for dairy and prepared meals.
- 21 CFR Part 113:FDA thermal process validation requirements for low-acid foods institutionalize rigid container standards, locking in specialized converter relationships with protein processors.
- Retort pouch technology:Lightweight format adoption accelerates in military and expeditionary food supply where logistics weight penalties dominate procurement criteria.
Market Restraints
- Ethylene-vinyl alcohol supply concentration:Barrier resin production clusters in Northeast Asia expose converters to feedstock disruption risk and volatile input pricing.
- Recyclability mandates:The EU Green Deal's 2030 packaging recyclability targets impose technical friction on oxygen barrier integration in mono-material designs.
- Metal can substitution ceiling:Oxygen impermeability requirements in fish and meat categories constrain flexible format penetration regardless of cost advantages.
Strategic Opportunities
- Sub-Saharan Africa:Ambient distribution dominance in Nigeria and Kenya creates white space for aseptic carton localization as dairy consumption formalizes.
- High-pressure processing convergence:HPP cold-pasteurization paired with modified atmosphere packaging opens premium chilled-adjacent segments without full cold-chain dependency.
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law create first-mover advantage for converters with established closed-loop collection infrastructure.
Industry Challenges
- Migration testing capacity:Laboratory backlog for EU 10/2011 compliance validation extends product qualification timelines by 4-8 months for novel laminate structures.
- Legacy retort line incompatibility:Mono-material pouch formats require pressure-temperature profile recalibration that idle existing capital equipment across co-packer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shelf Stable Packaging Market |
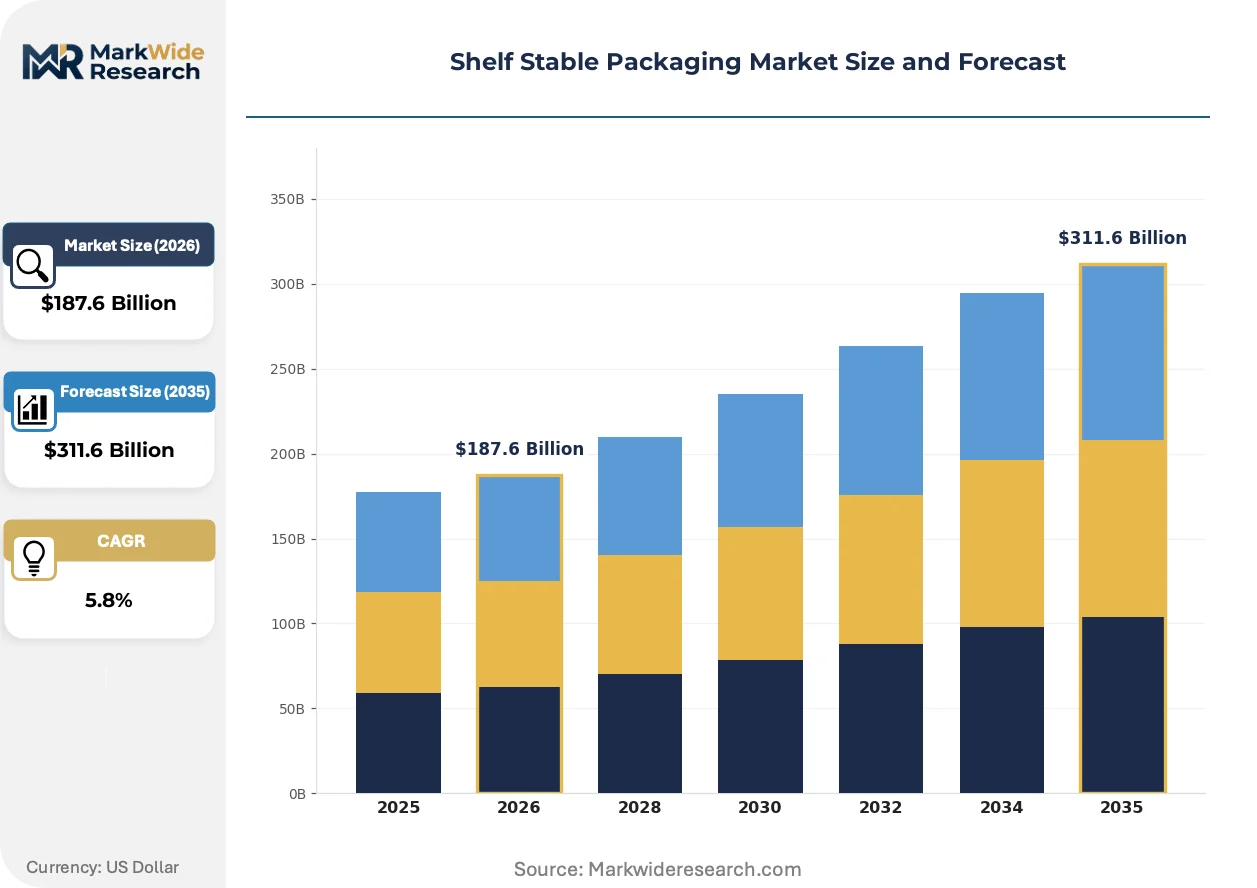
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $311.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aseptic Packaging, Cans, Pouches, Bottles Material: Plastic, Aluminum, Paperboard, Glass End User: Food Industry, Beverage Industry, Pharmaceuticals, Retail Technology: Thermal Processing, Dehydration, Modified Atmosphere Packaging, Vacuum Packaging |
| Companies Covered | Amcor plc, Sealed Air Corporation, Tetra Pak, Mondi Group, Berry Global, Sonoco Products Company, International Paper, WestRock, Crown Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shelf Stable Packaging Market Evolving Landscape
Active and intelligent packaging integration is shifting from premium positioning to operational necessity as real-time shelf-life monitoring becomes critical for reducing food waste liability across extended distribution networks.
Digital printing of barrier substrates is decentralizing short-run customization economics for private-label ready-meal launches. Regional brand owners in Poland and Mexico adopt the technology to compress SKU introduction cycles from months to weeks. The shift is compressing minimum order thresholds and enabling micro-segmentation without plate inventory carrying costs.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings from paperboard supply chains. Converters in the Netherlands and Belgium accelerate mineral-oil-free and bio-based barrier alternatives to maintain quick-service restaurant qualification. The regulatory pressure is most acute in fried and baked goods segments where fat migration resistance remains non-negotiable.
Direct-to-retailer procurement consolidation among European grocery chains is compressing converter margin pools. Buyers in Germany and the United Kingdom now specify performance guarantees spanning shelf-life extension rather than accepting material specifications alone. The behavioral shift is visible in private-label soup and sauce categories where annual contract renegotiation cycles have shortened from three years to eighteen months.
Shelf Stable Packaging Market Segmentation
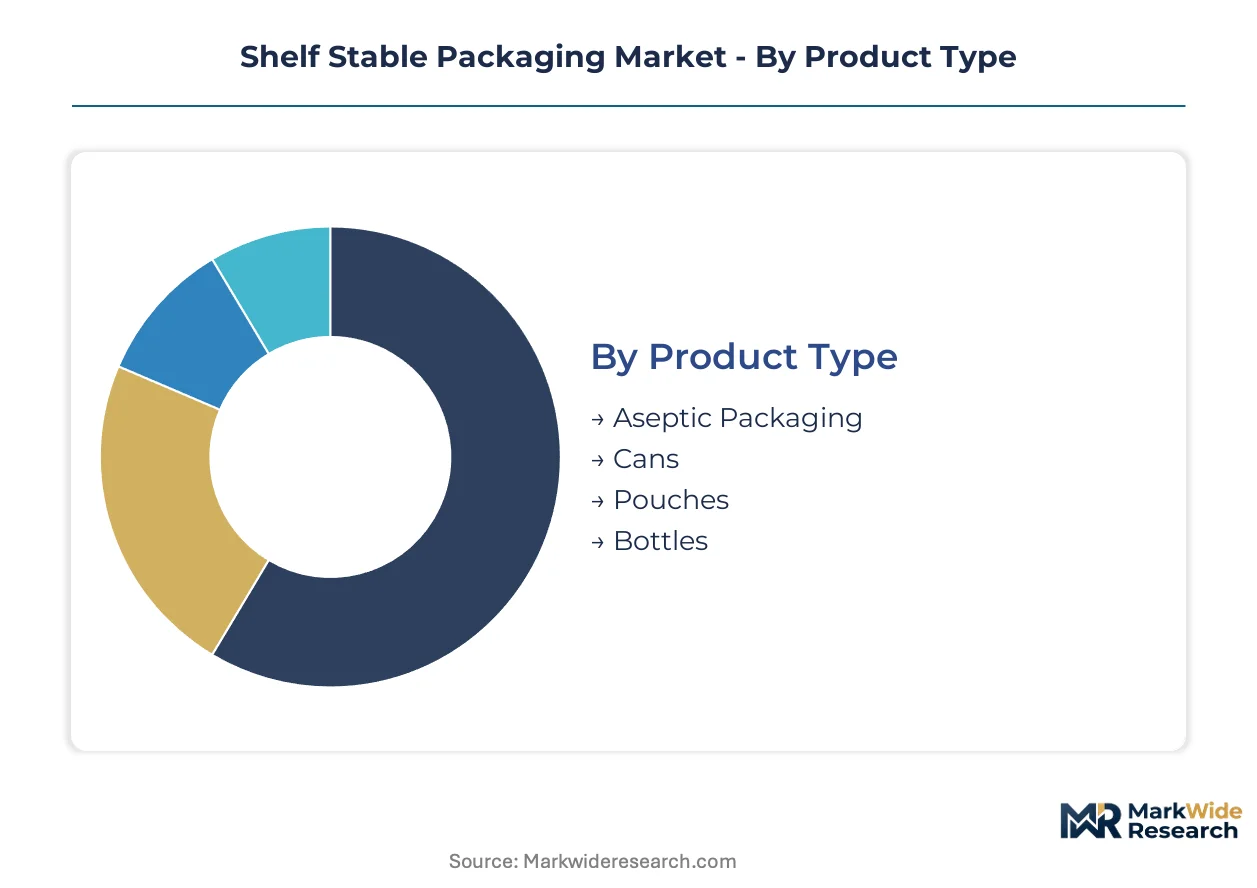
Segmentation in shelf-stable packaging reveals how technical specifications, regulatory constraints, and distribution economics fragment procurement decisions across buyer categories. Material selection and sterilization technology choices cascade through compliance costs, recyclability positioning, and cold-chain independence.
Product Type:
Buyers prioritize oxygen barrier performance against logistics weight penalties when selecting formats for ambient distribution networks.
- Aseptic Packaging:Paperboard-laminate reels sterilized with hydrogen peroxide enable ultra-high-temperature filling without refrigeration. Dairy and ready-to-drink beverage processors in India and Brazil deploy this format where cold-chain gaps persist.
- Cans:Aluminum and steel containers deliver absolute oxygen impermeability for protein-rich categories. Fish and meat processors accept higher logistics costs to guarantee shelf stability across extended distribution cycles.
- Pouches:Flexible multi-layer films reduce material intensity and shipping weight. Military and expeditionary procurement specifications favor retort-compatible variants where payload optimization dominates.
- Bottles:Glass and high-barrier plastic formats serve premium positioning and visibility requirements in retail environments.
Pouches lead on scale; aseptic packaging leads on momentum.
Material:
Recyclability mandates and migration compliance costs now outweigh unit economics in material qualification decisions.
- Plastic:Polypropylene and polyethylene terephthalate structures dominate flexible and rigid formats. EU mono-material recyclability targets are forcing converters toward single-polymer barrier architectures.
- Aluminum:Rolled sheet and foil provide impermeable barriers in cans and laminate layers. Beverage can stock supply concentrates among Northeast Asian smelters.
- Paperboard:Kraft and bleached substrates form the structural core of aseptic cartons. REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant coatings.
- Glass:Inert barrier properties serve acidic and premium applications where chemical migration risk must approach zero.
Plastic leads on scale; paperboard leads on momentum.
End User:
Regulatory stringency and shelf-life liability exposure vary dramatically across buyer verticals.
- Food Industry:Ready-to-eat meals, soups, and sauces drive volume demand. FDA 21 CFR Part 113 thermal process validation requirements lock protein processors into specialized converter relationships.
- Beverage Industry:Dairy alternatives and juice products concentrate aseptic carton demand. Urbanization in China and Nigeria sustains ambient distribution format growth.
- Pharmaceuticals:Sterile barrier requirements for parenteral nutrition and oral solid doses impose USP and EU GMP compliance burdens.
- Retail:Private-label procurement consolidation in Germany and the United Kingdom compresses converter margins through performance-based contracting.
Food industry leads on scale; beverage industry leads on momentum.
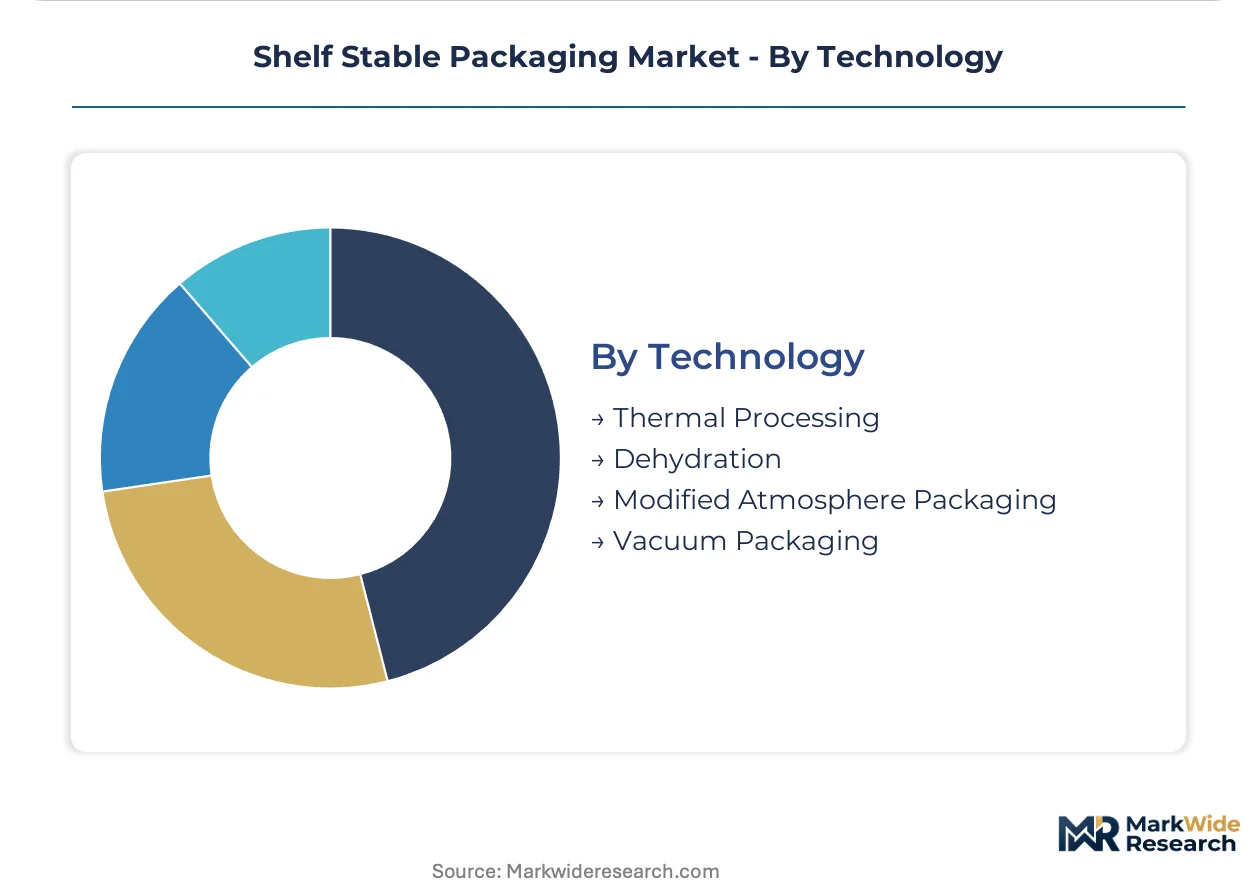
Technology:
Capital equipment compatibility and energy intensity separate adoption economics across sterilization methods.
- Thermal Processing:Retort and aseptic systems achieve commercial sterility through temperature-time profiles. Legacy equipment across co-packer networks requires recalibration for mono-material pouch formats.
- Dehydration:Moisture reduction extends stability without barrier packaging complexity. Snack and ingredient applications favor spray-drying and freeze-drying economics.
- Modified Atmosphere Packaging:Nitrogen flushing precision improves residual oxygen control. Premium ready-meal applications displace conventional vacuum methods.
- Vacuum Packaging:Oxygen exclusion through mechanical evacuation persists in cost-sensitive segments.
Thermal processing leads on scale; modified atmosphere packaging leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Düsseldorf-Ruhr industrial corridor anchors European converter capacity for barrier film extrusion and aseptic carton manufacturing. Cold-chain infrastructure gaps across emerging economies sustain demand for ambient-stable formats. Regulatory fragmentation between FDA thermal process rules and EU recyclability mandates forces multinational brand owners to maintain parallel packaging specifications.
United States
Protein processors and ready-to-eat meal manufacturers drive rigid container demand. FDA 21 CFR Part 113 thermal process validation requirements lock food manufacturers into specialized converter relationships with documented sterilization protocols. Chicago and Wisconsin host concentrated co-packer networks serving national retail distribution.
Germany
Private-label procurement consolidation among grocery chains compresses converter margins through performance-based contracting cycles. VerpackG extended producer responsibility frameworks create first-mover advantage for converters with closed-loop collection infrastructure. The Hamburg-Bremen port cluster facilitates laminate film import and aseptic filling equipment distribution.
China
Urban dairy consumption formalization sustains aseptic carton demand despite cold-chain expansion. SAMR implements GB standards for composite food contact materials that constrain laminate layer specifications. The Yangtze River Delta concentrates domestic converter capacity for retort pouch and flexible barrier film production.
Brazil
Cold-chain infrastructure gaps in interior states preserve ambient distribution dominance for dairy and prepared meals. ANVISA pharmaceutical packaging regulations extend to parenteral nutrition formats with shelf-stable requirements. São Paulo state anchors South American converter investment for mono-material flexible packaging transitions.
India
Urbanization and formal retail expansion concentrate demand for aseptic cartons in dairy and beverage segments. FSSAI food contact material regulations tighten migration testing requirements for multi-layer laminates. Gujarat and Maharashtra host emerging domestic converter capacity serving quick-service restaurant and retail private-label supply chains.
Shelf Stable Packaging Market Competitive Landscape
Global majors compete with regional champions across converter networks and substrate supply security. The market structure consolidates around integrated material suppliers with captive resin or paperboard production, while specialized pouch and canister fabricators occupy niche positions. Three archetypes dominate: integrated multinational converters with global extrusion networks, regional paperboard specialists with kraft supply control, and rigid format specialists serving protein-processor relationships. Competitive moves concentrate on mono-material barrier R&D partnerships and co-packer network qualification for redesigned pouch formats.
Within the integrated multinational tier, Amcor plc and Sealed Air Corporation exemplify global extrusion network operators. Tetra Pak occupies a position as the dominant aseptic carton system licensor. Mondi Group and Sonoco Products Company represent regional substrate specialists with European kraft paper and North American rigid paperboard positioning respectively. Berry Global anchors flexible film converter scale across multiple substrate technologies.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Tetra Pak |
| Mondi Group |
| Berry Global |
| Sonoco Products Company |
| International Paper |
| WestRock |
| Crown Holdings |
| Others |
Value Network & Pricing Analysis
Barrier certification tiers separate premium mono-material laminates from commodity multi-layer films, with that divergence mapping directly onto converter margin structures and raw material procurement strategies across European and North American supply chains.
Pricing Analysis
Ethylene-vinyl alcohol resin pricing passes through to converter quotations within one quarter, tethering flexible film costs to Northeast Asian petrochemical feedstock volatility. Three-tier pricing structure across premium, standard, and economy levels reflects oxygen transmission rate performance and EU 10/2011 migration compliance status. Pricing pressure stems from private-label procurement consolidation among German grocery chains compressing annual contract values. Small regional brand owners in Poland and Mexico exhibit highest price sensitivity, while protein processors locked into FDA 21 CFR Part 113 validation relationships accept premium rigid container pricing.
Supply Chain Analysis
Regional distribution centers in the Hamburg-Bremen and Rotterdam-Antwerp corridors consolidate laminate film imports before hub-and-spoke dispatch to Central European converters. Barrier resin production clusters in Japan, South Korea, and China; kraft paperboard supply anchors in Nordic forests and Southeastern US mills. Supply chain risk concentrates in single-source EVOH feedstock dependencies exposed to maritime logistics chokepoints. Distribution runs through co-packer networks requiring thermal process equipment recalibration for mono-material pouch formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shelf stable packaging functions as a stable compounder, with urbanization-driven cold-chain gaps in emerging economies providing durable demand tailwinds for ambient distribution formats.
For Market Incumbents: Deploy mono-material barrier R&D partnerships to preempt EU Packaging and Packaging Waste Regulation qualification requirements. Consolidate co-packer network relationships through equipment upgrade financing, locking in capacity for redesigned pouch formats. Counter rigid can substitution threats in protein categories by demonstrating total cost of ownership advantages across extended distribution cycles.
For New Entrants and Emerging Players: Enter via Sub-Saharan African dairy formalization, where Nigerian and Kenyan ambient distribution dominance outpaces local converter capacity. Target aseptic carton localization partnerships with Tetra Pak system licensees seeking regional substrate suppliers. Pursue quick-service restaurant qualification in India, where FSSAI migration testing backlogs delay incumbent product introductions.
For Investors and Strategic Acquirers: Asymmetric upside sits with European kraft paper specialists possessing closed-loop collection infrastructure under Germany's VerpackG framework. Five-to-ten year viability hinges on converter qualification timelines for redesigned mono-material structures. Monitor EU 10/2011 laboratory backlog durations as inflection indicator for novel laminate competitive entry windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier R&D Partnership | Amcor and Mondi co-development accelerates EU recyclability mandate compliance ahead of 2030 deadlines. |
| Co-Packer Network Equipment Upgrade Financing | Sonoco's capital deployment locks in retort pouch capacity recalibration for military procurement specifications. |
| Sub-Saharan African Aseptic Carton Localization | Tetra Pak system expansion into Nigeria addresses dairy consumption formalization without cold-chain infrastructure investment. |
| High-Pressure Processing Convergence | Modified atmosphere packaging integration opens premium ready-meal segments adjacent to chilled distribution. |
| Closed-Loop Collection Infrastructure Buildout | Germany's VerpackG compliance creates first-mover margin protection for Mondi's European kraft supply control. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market informing cross-regional pattern identification. The research combines interviews with packaging converters, procurement directors at protein processors, regulatory affairs specialists, and co-packer operations managers with secondary validation through FDA 21 CFR filings, EFSA scientific opinions, SAMR GB standard publications, and trade customs data. Bottom-up segment sizing and top-down macroeconomic triangulation anchor volume and value estimates.
Granularity extends to product type, material substrate, end-use vertical, and sterilization technology dimensions across the projection horizon. CAGRs derive from modeled segment growth trajectories weighted by regional cold-chain infrastructure maturity and regulatory implementation schedules. Forecast inputs incorporate urbanization rates, dairy consumption formalization indices, and extended producer responsibility framework adoption curves.
Inputs from converter capacity databases and regulatory filing repositories were available through the study window; gaps in real-time co-packer equipment utilization rates introduce uncertainty bands around retort pouch adoption timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Mexico Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Anti-Counterfeit Clothing Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market