
 Interior Packaging Market | 2026-2036
Interior Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Interior Packaging Market Foresight
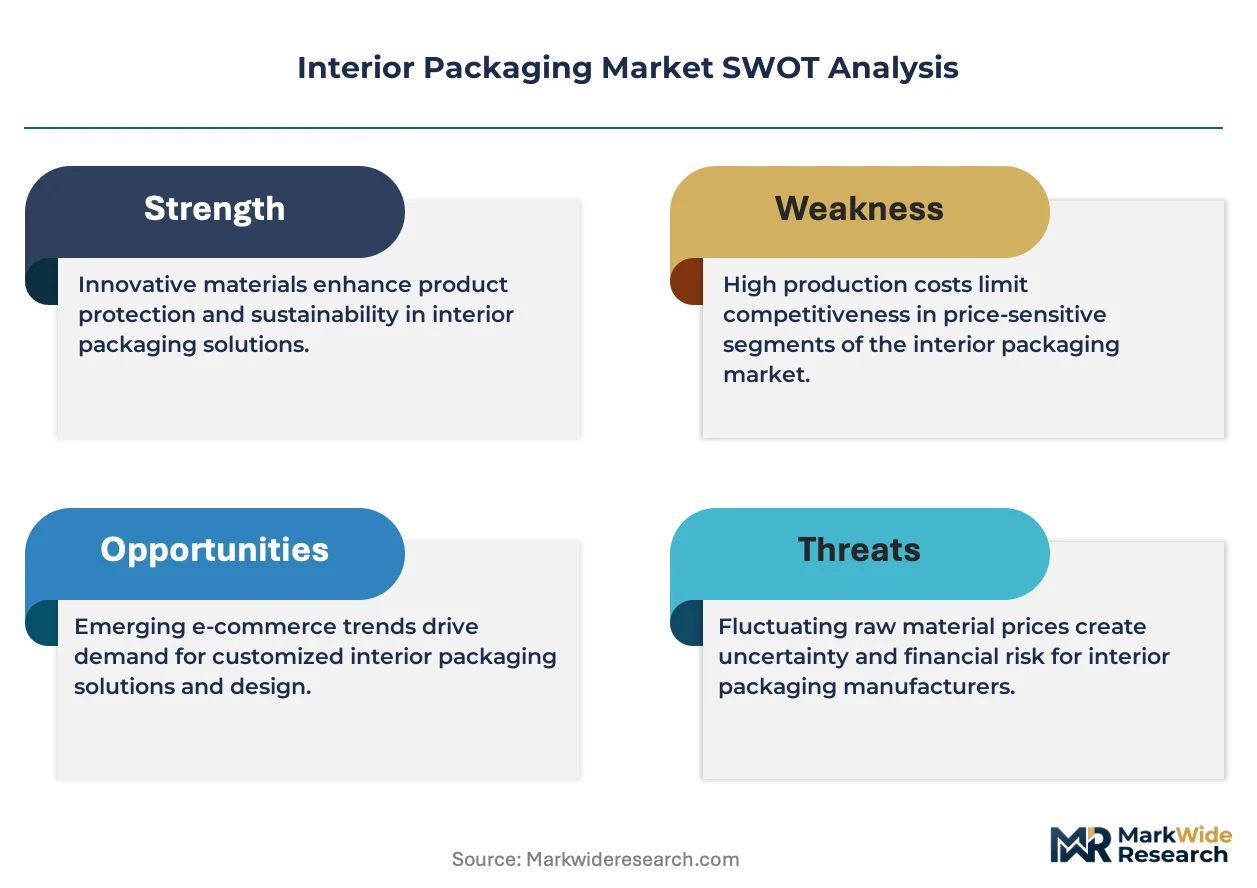
E-commerce fulfillment centers is redrawing procurement priorities away from traditional retail distribution. Smurfit Kappa leverages recycled paper-based dunnage systems to anchor sustainable supply contracts with European retailers. Sealed Air Corporation sustains technology leadership in inflatable void-fill automation for high-velocity warehouses. Pregis differentiates through foam-in-place systems that protect electronics during last-mile transit.
Interior packaging encompasses protective materials engineered to immobilize, cushion, and separate products within outer shipping containers, typically specified by compression strength, drop-test performance, and dimensional stability metrics. Its primary purpose is preventing damage from vibration, impact, and environmental exposure during handling and distribution. Flexible bags and wraps capture volume share in apparel and soft-goods fulfillment where conformability reduces material usage. Rigid containers command margin pools in healthcare and electronics segments requiring sterility maintenance and electrostatic discharge protection. Biodegradable grades within the material dimension are expanding fastest as brand owners face Scope 3 emissions reporting obligations.
EPA guidelines on sustainable materials management and the EU Packaging and Packaging Waste Regulation are elevating post-consumer recycled content minimums across North America and Europe. FDA food-contact material standards and EU REACH chemical restrictions shape barrier-grade film formulations for food and pharmaceutical applications. Stakeholders must monitor evolving extended producer responsibility frameworks and decide between retrofitting existing lines or investing in novel bio-based barrier technologies.
Market Dynamics
E-commerce fulfillment velocity is compressing packaging specification cycles from quarterly to monthly reviews, forcing converters to hold modular die inventory and deploy rapid-changeover converting lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content floors for transport packaging are pulling fiber-based dunnage into German automotive supply chains ahead of compliance deadlines.
- Automotive EV battery logistics:Cell-to-pack architectures require precision-engineered cushioning with thermal runaway containment, opening specification windows for engineered foam systems.
- Automated void-fill robotics:High-velocity warehouses in the Netherlands and Belgium are retrofitting pack stations with real-time dimensional scanning to cut material overuse.
Market Restraints
- Recycled pulp supply concentration:Nordic containerboard mills control 40% of European testliner supply, exposing converters to force majeure risk during winter energy curtailments.
- Biodegradable polymer cost premium:PLA and PBAT resins trade at 2.5-3x virgin PE levels, constraining adoption in price-sensitive apparel fulfillment.
- REACH chemical restriction complexity:Substance of Very High Concern listings for certain flame retardants are forcing reformulation of electronics-grade foam-in-place systems with 18-month validation timelines.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-controlled biologics distribution is creating demand for insulated box liners with phase-change material integration in Mumbai and Hyderabad corridors.
- Reusable dunnage pooling:Automotive tier-one suppliers in Stuttgart and Wolfsburg are piloting closed-loop container programs with RFID-tracked return logistics.
- Carbon accounting integration:Scope 3 reporting mandates under CSRD are enabling packaging-as-a-service models where converters assume end-of-life recovery liability.
Industry Challenges
- Multi-material separation infrastructure:Laminated barrier films bonded to corrugated substrates lack commercial recycling pathways, creating stranded asset risk for converters.
- Food-contact migration testing backlog:Novel bio-based barrier coatings face 14-month FDA notification queues, delaying market entry for compostable meat tray liners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interior Packaging Market |
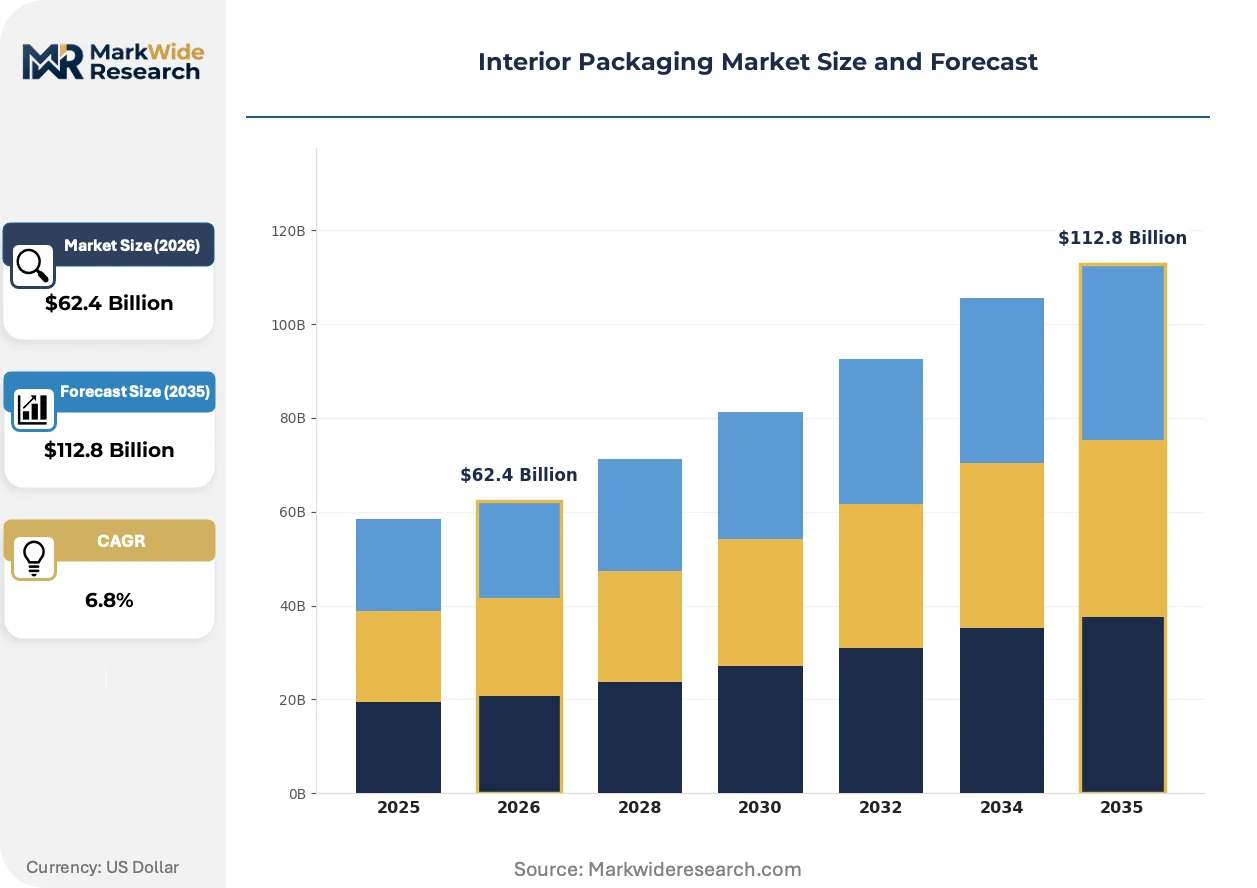
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Bags, Blister Packs, Rigid Containers, Wraps Material: Plastic, Paper, Foam, Metal End User: Food & Beverage, Healthcare, Personal Care, Electronics Grade: Standard, Biodegradable, Barrier, Custom |
| Companies Covered | Sealed Air Corporation, Smurfit Kappa, Pregis, Storopack, Ranpak, Polyair, Pro-Pac Packaging, Veritiv, FP International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interior Packaging Market Shifts & Advancements
Active and intelligent packaging layers are merging with protective functions, creating value pools beyond physical damage prevention into supply chain visibility and condition monitoring.
Paper-based inflatable dunnage is bifurcating the void-fill category between commodity polyethylene pillows and premium fiber systems. German appliance manufacturers are specifying kraft-based air cushions for white-goods delivery to meet retailer sustainability scorecards. This technology is bifurcating procurement teams into cost-focused and brand-alignment camps with incompatible vendor qualification criteria.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating oil-grease resistance from conventional molded fiber food service trays. Danish and Swedish converters are accelerating plasma-deposited silicone oxide barrier trials for ready-meal applications. Electronics manufacturers in the Czech Republic and Poland are switching to fluorine-free anti-static films ahead of anticipated ECHA additions.
Direct-to-consumer appliance brands are unbundling installation services from delivery, compressing last-mile packaging requirements into single-person lift specifications. This pattern favors corner-protector and edge-board systems over full foam encapsulation in French and Italian urban logistics networks. Urban density constraints in Barcelona and Milan are driving specification of collapsible returnable frames for large-format electronics.
Interior Packaging Market Segmentation
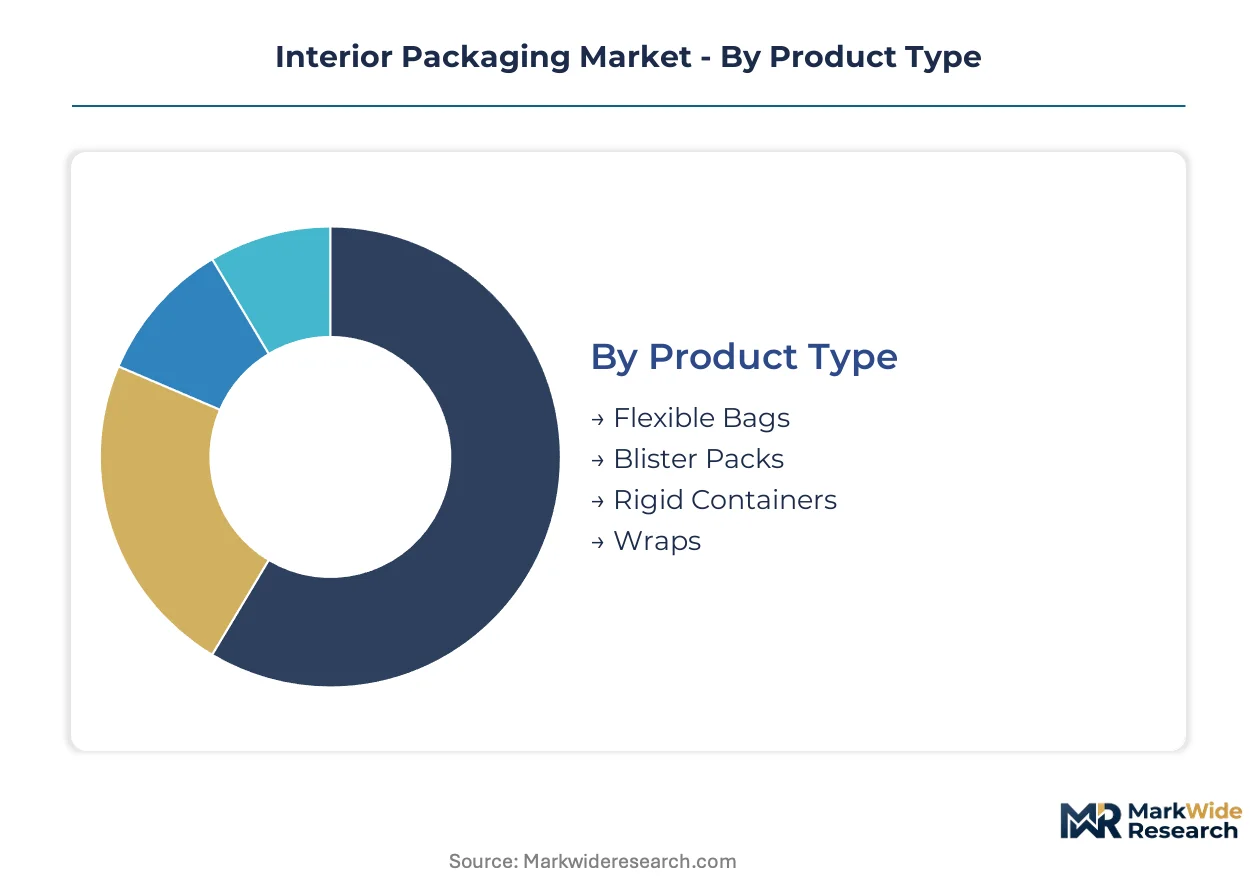
Interior packaging procurement teams segment specifications by damage mode, material compliance, and automation compatibility. Each dimension carries distinct margin structures and supplier qualification barriers that reshape competitive positioning across automotive, pharmaceutical, and e-commerce verticals.
Product Type:
Margin pools concentrate in precision-engineered systems that integrate with automated fulfillment lines, while commodity void-fill competes on throughput cost.
- Flexible Bags:Polyethylene and polypropylene films with heat-sealed closures dominate apparel and soft-goods fulfillment. German e-commerce hubs specify gusseted designs with printed return instructions to cut reverse-logistics friction.
- Blister Packs:Thermoformed PVC or PET cavities bonded to printed card stock deliver tamper-evidence for pharmaceuticals and electronics accessories. Healthcare serialization mandates in Italy and Spain are pulling cold-form foil alternatives into high-value oncology packaging.
- Rigid Containers:Injection-molded PP or HDPE tubs with snap-fit lids protect automotive components through multi-modal transport. Stuttgart suppliers specify ESD-grade formulations for circuit board delivery.
- Wraps:Stretch film and bubble sheeting secure palletized loads and individual items. Netherlands fulfillment centers deploy pre-stretched films to reduce material consumption per pallet.
The dominant share belongs to Flexible Bags, while Blister Packs is closing the gap fastest.
Material:
Cost tiers separate virgin petrochemical feedstocks from recycled and bio-based alternatives, with compliance premiums widening spreads in food-contact and medical applications.
- Plastic:PE, PP, and PET films offer moisture barriers and heat-sealability for perishables. EU Packaging and Packaging Waste Regulation recycled content floors are forcing converters toward post-consumer rPET in French retail ready-meal trays.
- Paper:Kraft liners, corrugated inserts, and molded fiber cushions provide fiber-based protection with established recycling streams. Smurfit Kappa supplies German appliance manufacturers with paper-based inflatable dunnage to meet retailer sustainability scorecards.
- Foam:Expanded polystyrene, polyurethane, and polyethylene foams absorb impact energy for electronics and automotive components. REACH Annex XVII restrictions on legacy flame retardants are extending validation timelines for Czech electronics-grade formulations.
- Metal:Aluminum laminates and steel containers deliver barrier performance for pharmaceuticals and premium cosmetics. Swissmedic-registered facilities in Basel specify aluminum cold-form foil for moisture-sensitive tablet stability.
Plastic maintains volume leadership, though Paper is expanding most quickly under regulatory pressure.
End User:
Application-specific performance requirements create specification silos with incompatible testing protocols and supplier audit criteria.
- Food & Beverage:Barrier films, modified atmosphere trays, and temperature-stable liners prevent spoilage across distribution. FDA food-contact migration testing backlogs are delaying market entry for novel bio-based meat tray liners.
- Healthcare:Sterile barrier systems, cold-chain insulation, and tamper-evident features protect biologics and devices. Temperature-controlled distribution in Mumbai and Hyderabad corridors is creating demand for insulated box liners with phase-change material integration.
- Personal Care:Premium unboxing experiences and fragrance retention drive specification of metallized films and molded pulp inserts. Direct-to-consumer brands in Milan compress last-mile requirements into single-person lift specifications favoring corner-protector systems.
- Electronics:Electrostatic discharge protection, vibration damping, and humidity control safeguard semiconductors and displays. Cell-to-pack EV battery architectures require precision-engineered cushioning with thermal runaway containment.
Food & Beverage holds the largest specification base, while Healthcare is climbing the fastest on cold-chain infrastructure buildout.
Grade:
Certification tiers separate commodity supply from premium segments where converters assume compliance liability and end-of-life recovery obligations.
- Standard:Virgin petrochemical or fiber-based materials meeting baseline mechanical specifications without sustainability certification. Price-sensitive apparel fulfillment in Poland and Romania constrains adoption of higher-cost alternatives.
- Biodegradable:PLA, PBAT, and cellulose-based formulations certified to industrial composting standards. PLA and PBAT resins trade at 2.5-3x virgin PE levels, limiting penetration in mass-market channels.
- Barrier:Multi-layer laminates, metallized films, and coated papers blocking oxygen, moisture, or UV transmission. Plasma-deposited silicone oxide trials are accelerating in Denmark and Sweden as fluorine-free alternatives.
- Custom:Engineer-to-order solutions with embedded RFID, color-matched branding, or dimensional precision for automated handling. Automotive tier-one suppliers in Wolfsburg pilot RFID-tracked returnable dunnage pooling programs.
Standard grade dominates shipment volume, though Custom specifications are gaining share fastest on automation integration requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive component exports to assembly plants across Central Europe are pulling fiber-based dunnage into cross-border supply corridors. The EU Packaging and Packaging Waste Regulation is synchronizing compliance timelines across member states.
Germany
Stuttgart and Wolfsburg automotive clusters specify ESD-grade rigid containers for circuit board delivery to EV assembly lines. The EU Packaging and Packaging Waste Regulation mandates recycled content floors for transport packaging by 2030. Bavarian converters are retrofitting lines to supply paper-based inflatable dunnage for appliance manufacturers.
United States
E-commerce fulfillment velocity in Dallas-Fort Worth and Chicago is compressing packaging specification cycles to monthly reviews. EPA sustainable materials management guidelines elevate post-consumer recycled content minimums. Midwestern converters hold modular die inventory to serve rapid-changeover demands from high-velocity warehouses.
China
Cell-to-pack EV battery architectures in the Yangtze River Delta require precision-engineered cushioning with thermal runaway containment. GB standards and dual carbon goals are accelerating bio-based barrier coating development. Shenzhen electronics manufacturers are switching to fluorine-free anti-static films ahead of anticipated regulatory additions.
India
Temperature-controlled biologics distribution in Mumbai and Hyderabad corridors is creating demand for insulated box liners with phase-change material integration. CDSCO cold-chain regulations shape pharmaceutical packaging specifications. Gujarat pharmaceutical exporters are qualifying compostable barrier films for EU-bound shipments.
Netherlands
Rotterdam and Venlo fulfillment hubs deploy automated void-fill robotics with real-time dimensional scanning to cut material overuse. REACH chemical restrictions force reformulation of electronics-grade foam systems. Dutch converters pilot RFID-tracked returnable dunnage pooling with automotive tier-one suppliers.
Interior Packaging Market Competitive Landscape
Player mix skews toward integrated paper-based converters and specialized protective materials engineers. The vendor base separates into three functional tiers: multinational integrated converters with captive fiber supply, mid-cap automation specialists, and regional foam-in-place system fabricators. Consolidation pressure concentrates in the void-fill automation segment where pack-station integration creates switching costs. Capacity expansion and strategic partnerships represent the dominant competitive moves as converters secure recycled pulp supply and robotics integration capabilities.
Within the integrated converter tier, Smurfit Kappa and Sealed Air Corporation occupy positions that exemplify divergent strategic anchors. Smurfit Kappa represents the fiber-based sustainability vector, leveraging recycled paper systems to anchor supply contracts with European retailers. Sealed Air Corporation sits within the automation-technology tier, sustaining leadership in inflatable void-fill systems for high-velocity warehouse environments. Pregis exemplifies the precision-engineering archetype through foam-in-place specialization for electronics protection during last-mile transit.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Smurfit Kappa |
| Pregis |
| Storopack |
| Ranpak |
| Polyair |
| Pro-Pac Packaging |
| Veritiv |
| FP International |
| Others |
Supply & Pricing Matrix
Recycled paper-based dunnage displacing virgin polyethylene void-fill is redrawing procurement geography toward Nordic fiber mills and compressing margin pools for petrochemical converters serving German automotive corridors.
Pricing Analysis
Next-generation paper-based inflatable systems command 40-60% premiums over legacy polyethylene pillows, while prior-generation molded EPS trays face price erosion from REACH-driven reformulation costs. Three-tier pricing structure across premium fiber-based automation-compatible, standard recycled-content corrugated, and economy virgin plastic void-fill segments stratifies buyer segments. Cost compression in the economy tier is intensifying because apparel fulfillment buyers in Poland and Romania prioritize unit economics over sustainability credentials. Healthcare and electronics verticals show lowest price sensitivity, absorbing ESD-grade and barrier-certified premiums.
Supply Chain Analysis
Nordic containerboard mill concentration along the Gulf of Bothnia underwrites European testliner availability, exposing converters to winter energy curtailment risks. Raw material flows draw from Swedish and Finnish pulp operations, German recycled fiber collection networks, and Chinese bio-based resin pilot plants. Single-source vulnerability concentrates in specialty foam-in-place chemical precursors subject to ECHA Substance of Very High Concern listings. Distribution runs through automotive tier-one supplier hubs in Stuttgart and Wolfsburg, e-commerce fulfillment nodes in Venlo and Dallas-Fort Worth, and pharmaceutical cold-chain corridors in Mumbai and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across automation compatibility, material certification, and regional compliance creates specialist niches as e-commerce velocity splits procurement teams into cost-focused and brand-alignment camps.
For Market Incumbents: Fortify fiber supply security through backward integration into Nordic pulp assets or long-term offtake contracts with Swedish and Finnish mills. Deepen automation integration capabilities to lock in pack-station switching costs at high-velocity warehouses in the Netherlands and Belgium. Counter biodegradable polymer cost premiums by scaling paper-based inflatable dunnage production for German appliance manufacturers facing retailer sustainability scorecards. For New Entrants and Emerging Players: Differentiate on fluorine-free barrier coatings for ready-meal applications as Danish and Swedish converters accelerate plasma-deposited silicone oxide trials ahead of anticipated ECHA per- and polyfluoroalkyl substance restrictions. Target the Indian pharmaceutical cold chain with insulated box liners integrating phase-change materials for Mumbai and Hyderabad biologics distribution. Pursue packaging-as-a-service models assuming end-of-life recovery liability under CSRD Scope 3 mandates. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap automation specialists with robotics integration capabilities and captive recycled pulp supply in the Nordic region. Long-term viability over the next decade hinges on converters' ability to serve monthly specification cycles while managing compliance-driven reformulation timelines. Watch for inflection signals in EU Packaging and Packaging Waste Regulation enforcement actions against German automotive suppliers missing recycled content floors.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Pulp Supply Security | Long-term offtake contracts with Nordic mills insulate converters from winter energy curtailment disruptions. |
| Automation Integration Investment | Real-time dimensional scanning capabilities at pack stations create switching costs with high-velocity e-commerce fulfillment centers. |
| Fluorine-Free Barrier Development | Plasma-deposited silicone oxide coatings capture ready-meal specification windows as REACH eliminates legacy oil-grease resistance. |
| Pharmaceutical Cold-Chain Expansion | Phase-change material integration for insulated box liners addresses CDSCO-regulated biologics distribution in Indian corridors. |
| Packaging-as-a-Service Models | Converters assuming end-of-life recovery liability align with CSRD Scope 3 reporting mandates and generate recurring revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with packaging procurement directors, converting line engineers, sustainability compliance officers, and e-commerce fulfillment operations managers; and secondary validation through EU Packaging and Packaging Waste Regulation filings, EPA sustainable materials management guidelines, REACH Annex XVII restriction updates, and customs trade data on pulp and resin flows. Bottom-up capacity assessments at Nordic containerboard mills and top-down demand modeling across automotive, pharmaceutical, and e-commerce verticals were cross-referenced for triangulation.
Across the analysis window, projections integrate product type segmentation by automation compatibility, material grade by certification tier, end-use vertical by damage mode sensitivity, and regional regulatory cluster by compliance timeline. CAGRs were derived from weighted average growth across these dimensions, with specific inputs including German automotive export volumes, Netherlands fulfillment center automation adoption rates, and Indian pharmaceutical cold-chain infrastructure buildout.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement, stable Nordic energy supply, and continued e-commerce velocity expansion would require recalibration. Forecasts reflect documented assumptions on recycled content floor implementation timelines and biodegradable polymer cost convergence trajectories. Practitioners should keep alternative scenarios live as REACH chemical restriction expansions and automotive EV battery architecture shifts evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Hermetic Packaging Market