
 Global Peel and Reseal Packaging Market | 2026-2036
Global Peel and Reseal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Peel and Reseal Packaging Market Intelligence
The development of high-barrier laminated films with enhanced resealability is reorganizing the competitive landscape for consumer packaged goods. Amcor PLC leverages its extensive global manufacturing network to supply multinational food and pharmaceutical clients. Mondi Group competes through its focus on sustainable paper-based and flexible plastic packaging options. Berry Global Inc. specializes in non-woven materials and engineered films for personal care applications.
Peel and reseal packaging defines containers with an adhesive layer for multiple openings and closings. Performance hinges on the adhesive maintaining tack over numerous cycles without leaving residue. This design extends product freshness and enhances convenience for multi-use goods. Laminated films made from polypropylene and polyester command the material segment, while the food and beverage application represents the largest market.
Food contact safety rules from the U.S. FDA and the European Food Safety Authority (EFSA) govern material composition. Concurrently, sustainability mandates like the EU's Packaging and Packaging Waste Regulation steer design towards recyclability. Stakeholder investment must now balance the development of compliant, cost-effective barrier materials with circular economy goals.
Market Dynamics
The central tension shaping the market is the simultaneous pursuit of enhanced barrier properties for product preservation and the industry-wide shift towards mono-material structures mandated by circular economy regulations like the EU Green Deal.
Growth Catalysts
- Consumer Convenience:Demand for portion control and extended freshness in multi-use food products, particularly in the cheese, deli meat, and snack segments, drives adoption of resealable formats.
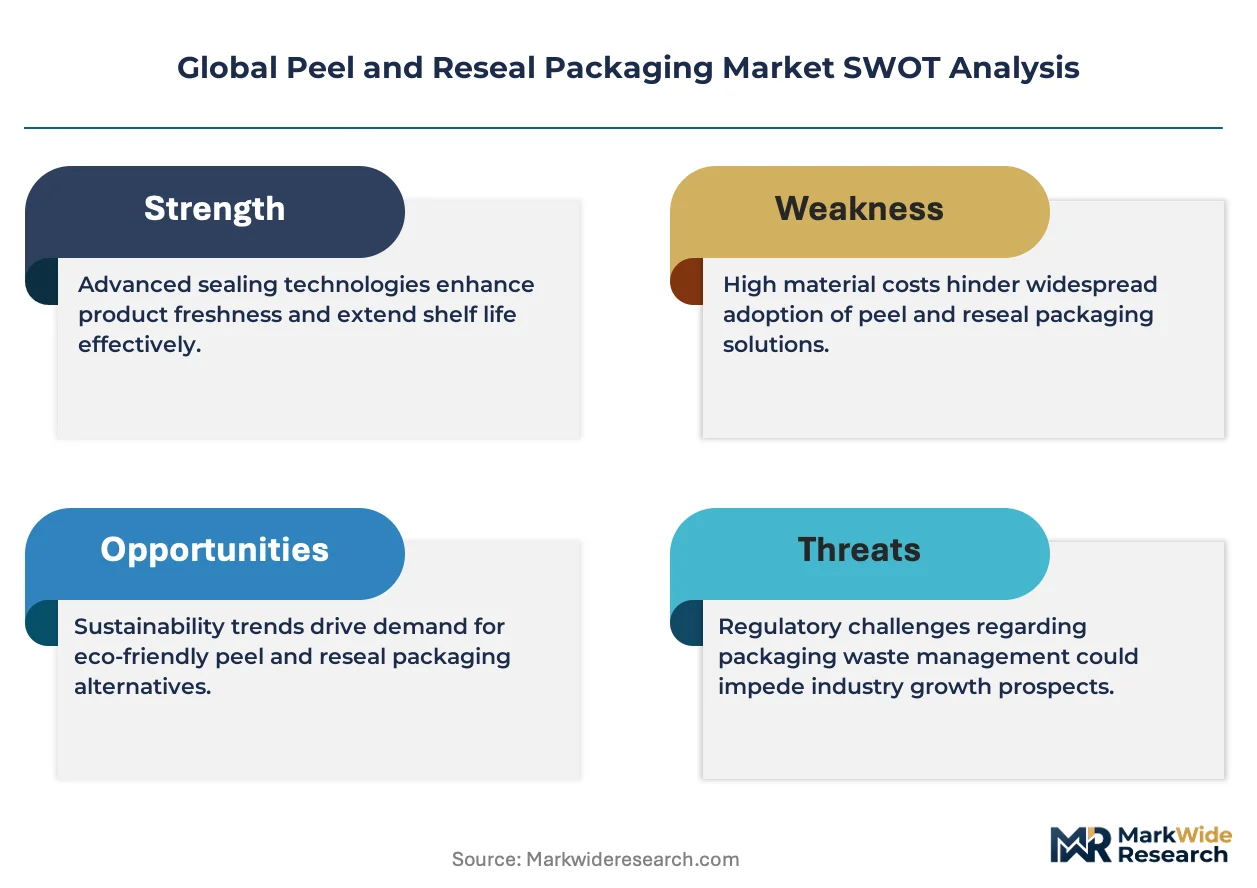
- Regulatory Mandates for Recyclability:Frameworks such as the EU's Packaging and Packaging Waste Regulation incentivize the development and adoption of mono-material films that are compatible with existing recycling streams.
- Emerging Market Consumption:China's expanding middle class and its increasing consumption of packaged consumer goods create a large and concentrated demand center for convenient packaging solutions.
Market Restraints
- Material and Adhesive Costs:High-performance barrier films and specialized pressure-sensitive adhesives that maintain tack over multiple cycles represent a significant cost component, limiting adoption in price-sensitive product categories.
- Performance Trade-offs:Achieving a perfect seal that is easy to peel yet reliably reseals without contamination or loss of adhesion remains a technical barrier for certain applications and substrates.
- Food Safety Compliance:Stringent regulations from bodies like the U.S. FDA and EFSA on food contact materials add complexity, cost, and time to the product development and approval process.
- Pharmaceutical Applications:Untapped potential exists in packaging for multi-dose medications, transdermal patches, and medical devices where resealability can improve safety, compliance, and product integrity.
- Smart Packaging Integration:Combining peel and reseal functionality with printed electronics like NFC or QR codes can provide consumers with enhanced product information, authentication, and re-ordering capabilities.
- Geographic Expansion:Rising disposable incomes and the growth of organized retail in Latin American and Southeast Asian countries present new market opportunities for packaged foods featuring convenient closures.
- Supply Chain Reconfiguration:The transition from traditional multi-material laminates to recyclable mono-material films requires significant investment in new extrusion technology, supplier qualification, and production line adjustments.
- Lack of Standardization:Ambiguity and regional variations in definitions and testing protocols for "recyclable" flexible packaging create uncertainty for material suppliers and brand owners investing in new solutions.
- Film Pouches:These flexible containers, often made from multi-layer films, provide excellent barrier properties for food and pharmaceutical products. Demand concentrates in the snack and confectionery segments, driven by consumer preference for convenient, portion-controlled packaging.
- Stand-Up Pouches:Featuring a flat base for upright display, these pouches enhance shelf appeal and offer resealable functionality for products like pet food and dried fruits. Their adoption in the food and beverage sector is accelerating due to their reduced material usage compared to rigid containers.
- Blister Packs:These rigid thermoformed plastic cavities sealed with a lidding material primarily serve pharmaceutical and medical device applications, ensuring product integrity.
- Sachets:Small, single-use flexible packets provide convenient, unit-dose packaging for condiments, cosmetics, and nutraceuticals.
- Foil Bags:Constructed from aluminum foil laminates, these bags offer superior barrier protection against moisture, oxygen, and light, critical for coffee and sensitive food items.
- Laminated Films:These multi-layer structures combine different polymers like PET, PE, or PP to achieve enhanced barrier properties against oxygen and moisture. The food and beverage sector heavily utilizes laminated films for extended shelf life of deli meats and cheese.
- Polypropylene:A versatile thermoplastic polymer, polypropylene offers good moisture barrier properties and can be engineered into mono-material films compatible with recycling streams. Its use is expanding in snack and bakery packaging due to its heat resistance and clarity.
- Polyethylene:This widely used polymer provides flexibility and good sealing characteristics, frequently appearing in the form of lidding films for dairy and fresh produce.
- Aluminum Foil:Aluminum foil provides an absolute barrier to gases, moisture, and light, making it indispensable for products requiring maximum protection.
- Polyester:Polyester films offer high tensile strength, clarity, and temperature resistance, commonly used as an outer layer in multi-layer laminates.
- Food & Beverage:This sector represents the largest application for peel and reseal packaging, encompassing categories like cheese, deli meats, snacks, and ready meals. Consumer demand for extended freshness and portion control directly drives adoption in this segment.
- Pharmaceuticals:Peel and reseal features improve medication adherence and product safety for multi-dose drugs, transdermal patches, and medical devices. Stringent regulatory compliance from bodies like the U.S. FDA and European Medicines Agency (EMA) influences material choices.
- Personal Care:Resealable packaging enhances convenience for wet wipes, cosmetic samples, and travel-sized toiletries.
- Household Products:Products such as cleaning wipes, pet treats, and garden supplies benefit from the extended usability offered by resealable closures.
- Pet Supplies:Resealable bags for pet food and treats maintain freshness and prevent spoilage, catering to pet owners' convenience.
- Retail Chains:Large retail chains procure vast quantities of peel and reseal packaging for their private label brands and branded products, emphasizing cost-effectiveness and shelf appeal. Their procurement decisions often dictate industry trends for packaging design.
- Online Retailers:E-commerce platforms require packaging that withstands transit, offers tamper evidence, and provides consumer convenience upon delivery. They increasingly influence demand for durable, yet easy-to-open and resealable formats.
- Contract Manufacturers:These companies produce goods for various brands, requiring flexible packaging solutions that can be adapted to diverse product specifications.
- Private Label Brands:Brands owned by retailers or distributors leverage peel and reseal packaging to offer competitive products with enhanced consumer features.
- Specialty Stores:Boutique retailers and niche market players seek customized, often premium, peel and reseal packaging that reflects their brand identity.
Strategic Opportunities
Industry Challenges
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Peel and Reseal Packaging Market |
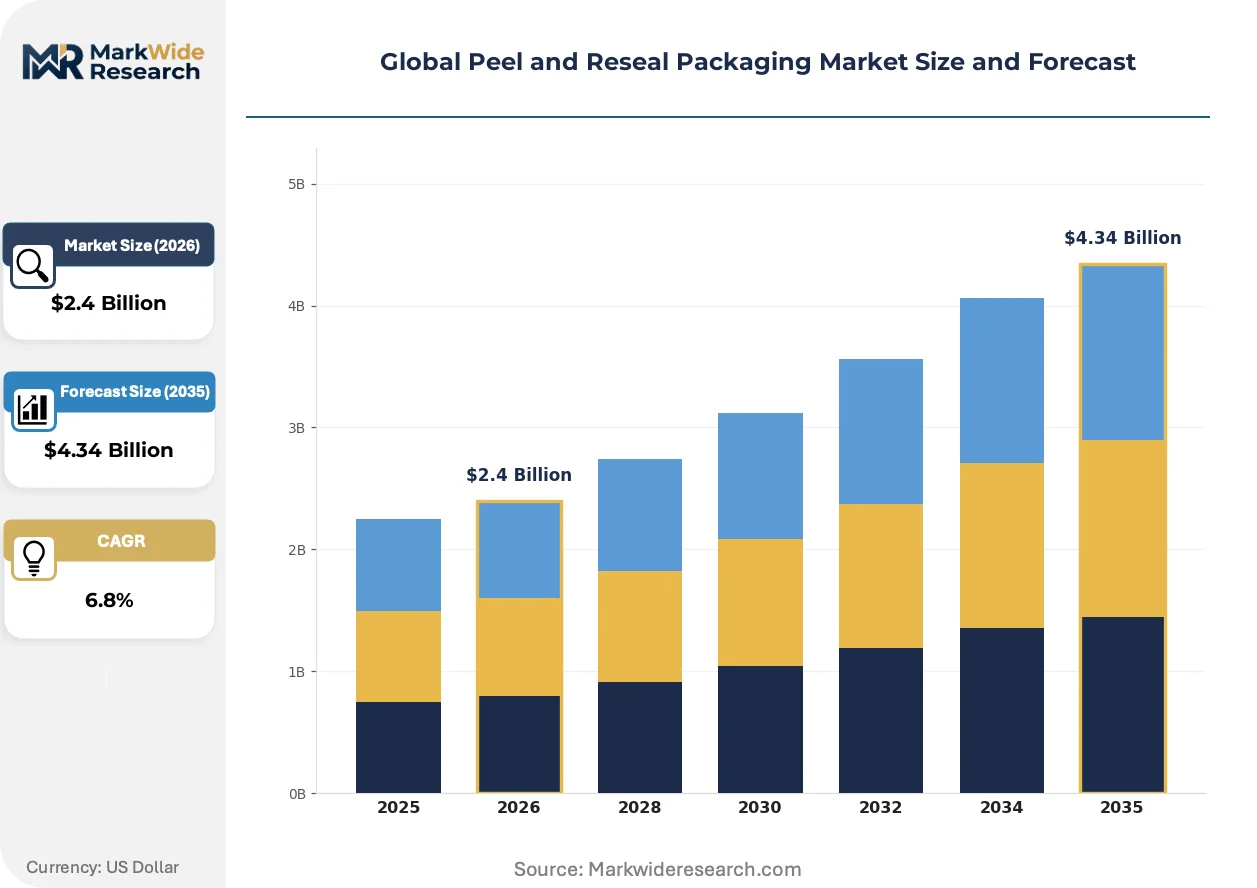
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film Pouches, Blister Packs, Stand-Up Pouches, Sachets, Foil Bags Material: Polyethylene, Polypropylene, Aluminum Foil, Polyester, Laminated Films Application: Pharmaceuticals, Food & Beverage, Personal Care, Household Products, Pet Supplies End User: Contract Manufacturers, Private Label Brands, Retail Chains, Online Retailers, Specialty Stores |
| Companies Covered | Mondi Group, Sonoco Products Company, Amcor PLC, Huhtamaki Oyj, UFlex Ltd., Berry Global Inc., Constantia Flexibles, Coveris Holdings, Sealed Air Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Peel and Reseal Packaging Market Strategic Shifts & Innovations
The market's innovation trajectory is defined by the pursuit of circularity. Material science advancements are focused on developing packaging that meets stringent recycling criteria without compromising the convenience and barrier protection that consumers expect from resealable formats.
Mono-material films, typically based on polyethylene or polypropylene, are engineered for compatibility with mechanical recycling streams. Consumer packaged goods companies are accelerating adoption to meet public sustainability commitments and regulatory targets. This trend is bifurcating the market, creating a divide between these emerging recyclable solutions and legacy multi-material laminates that offer higher barrier performance but face disposal challenges.
Europe's Packaging and Packaging Waste Regulation (PPWR) establishes ambitious targets for recyclable packaging and minimum recycled content. This legislation directly compels a design overhaul for many flexible packaging formats, including those with resealable features. Converters and film producers serving the EU market are now prioritizing investment in mono-material film technologies to ensure future compliance and market access.
Consumer preference is shifting towards brands that demonstrate tangible sustainability credentials, often communicated via on-pack labeling. This behavioral change disrupts brand loyalty based solely on price or quality, creating an advantage for products in verifiably recyclable peel and reseal packaging. The shift is most pronounced within the organic and health-conscious food segments in North America and Western Europe.
Global Peel and Reseal Packaging Market Segmentation
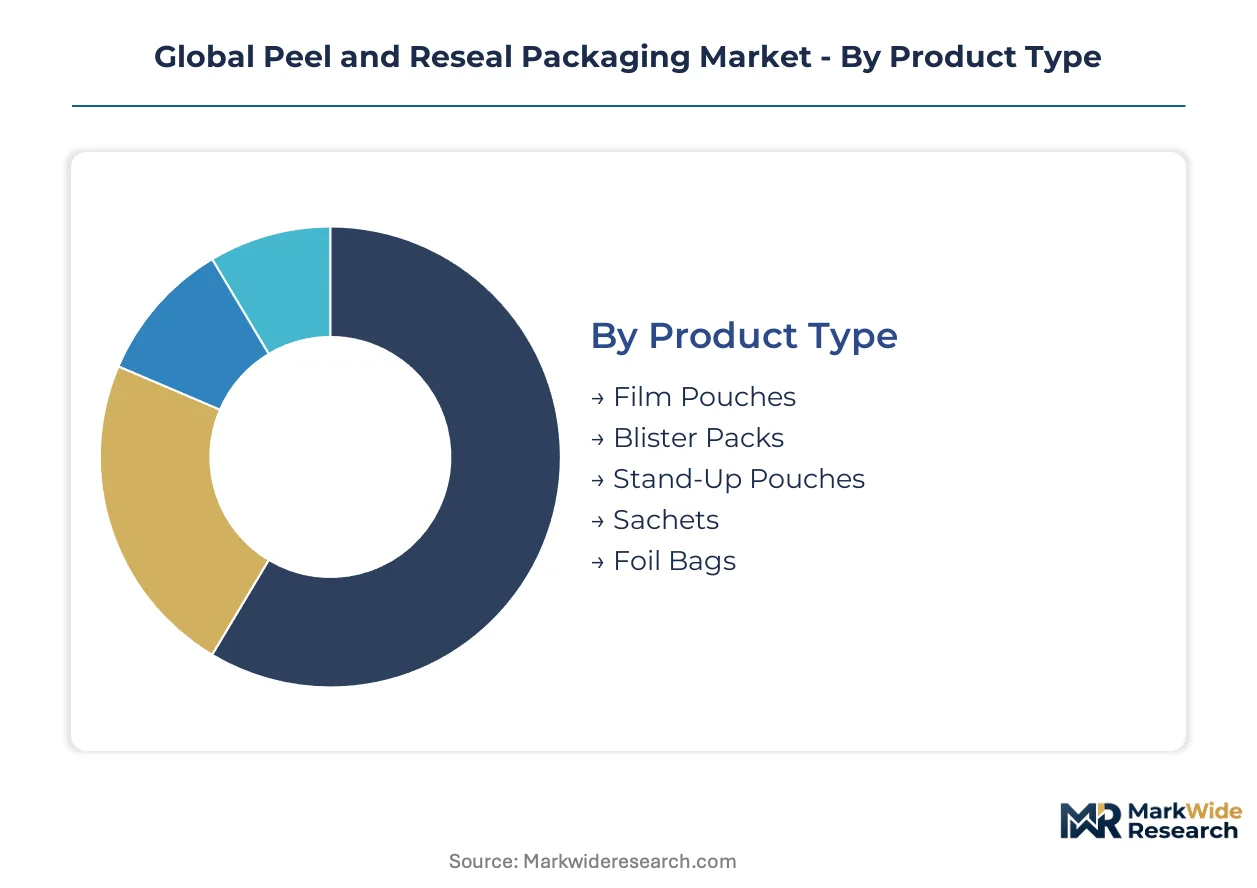
The Global Peel and Reseal Packaging Market segmentation provides a granular view of product formats, material compositions, and end-use sectors. This detailed breakdown helps stakeholders understand specific demand drivers and regulatory influences across diverse consumer goods categories. It illuminates where innovation and investment are most concentrated.
Product Type:
Regulatory frameworks, particularly those addressing packaging waste, significantly differentiate the market for peel and reseal product types.
Film Pouches handle the majority of throughput; Stand-Up Pouches are the fastest mover on share.
Material:
Material selection for peel and reseal packaging is primarily driven by the specific application's barrier requirements and increasingly by recyclability mandates.
Laminated Films secure the largest volume; Polypropylene materials exhibit the steepest expansion trajectory.
Application:
The volume of peel and reseal packaging consumed varies significantly across different application sectors, reflecting diverse product lifecycles and consumer usage patterns.
Food & Beverage applications command the dominant share; Pharmaceutical applications are gaining share fastest.
End User:
The customer type influences the scale and customization requirements for peel and reseal packaging solutions.
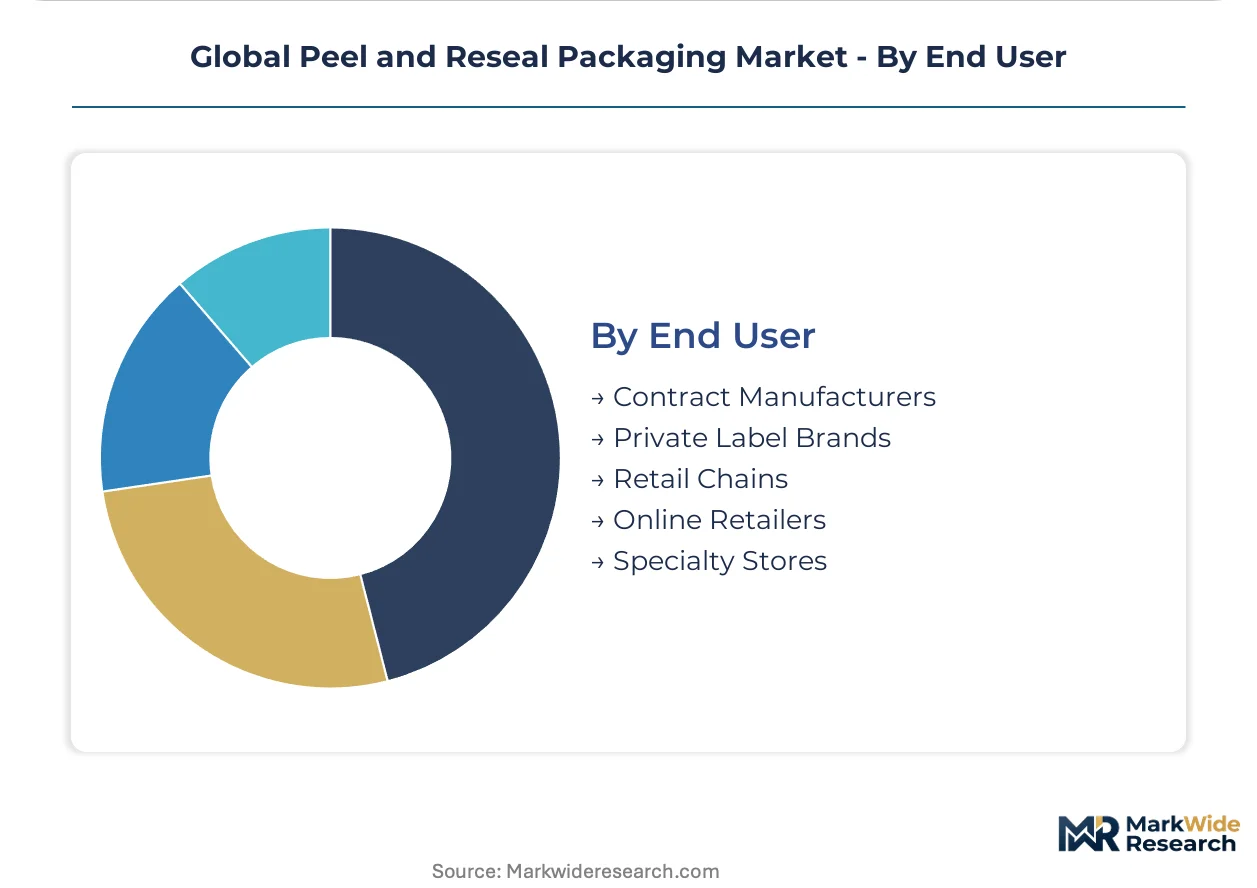
Retail Chains represent the primary purchasing power; Online Retailers are rapidly expanding their market influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for peel and reseal packaging concentrates significantly within China's expansive consumer goods market, driven by its growing middle class. This concentration also reflects the country's extensive manufacturing capabilities for flexible packaging solutions. Other major economies contribute to global market expansion.
China
Demand for convenient packaged foods, particularly snacks and ready meals, propels peel and reseal adoption in China. The country's GB standards for food contact materials ensure product safety and quality. Packaging innovation clusters in the Yangtze River Delta, developing advanced mono-material films for fast-moving consumer goods.
United States
Consumer preference for extended freshness in deli meats and cheese drives peel and reseal packaging demand across the United States. The U.S. FDA regulations stringently govern food contact materials, influencing material composition choices. Packaging manufacturers in the Midwest, particularly around Chicago, focus on high-barrier film production.
Germany
Germany's robust food and beverage sector, coupled with strong sustainability mandates, fuels demand for recyclable peel and reseal formats. The EU's Packaging and Packaging Waste Regulation directly impacts design choices, favoring mono-material solutions. North Rhine-Westphalia hosts numerous packaging converters, specializing in advanced flexible packaging technologies.
India
Rising disposable incomes and the expansion of organized retail channels increase the uptake of packaged snacks and personal care items in India. The FSSAI mandates specific standards for food packaging, ensuring consumer safety. Production hubs in Maharashtra, especially around Mumbai, are expanding capacity for flexible packaging films.
Brazil
Brazil's large domestic market and growing middle class stimulate demand for convenient, multi-use food packaging for items like coffee and dried fruits. ANVISA, the national health surveillance agency, regulates food contact packaging materials. Manufacturers in São Paulo are investing in new extrusion lines for sustainable resealable solutions.
Global Peel and Reseal Packaging Market Key Industry Players
Concentration sits with large, integrated packaging conglomerates leveraging extensive global manufacturing networks. The market exhibits a tiered structure, from multinational giants offering comprehensive solutions to specialized regional players focusing on niche applications and material science innovators. Strategic archetypes include diversified packaging solution providers, sustainable packaging specialists, and engineered film manufacturers. Companies frequently engage in capacity expansion and strategic partnerships, alongside portfolio diversification, to broaden their product offerings and market reach.
Global packaging powerhouses, including Amcor PLC, exemplify the extensive manufacturing and distribution capabilities required to serve diverse multinational clients. Mondi Group occupies a position among innovators focusing on sustainable solutions, offering both paper-based and flexible plastic packaging options. Berry Global Inc. represents a key player specializing in engineered films and non-woven materials, particularly catering to personal care and industrial applications. These companies leverage their broad portfolios to address evolving market demands and regulatory pressures for both performance and sustainability.
| Leading Market Players |
|---|
| Mondi Group |
| Sonoco Products Company |
| Amcor PLC |
| Huhtamaki Oyj |
| UFlex Ltd. |
| Berry Global Inc. |
| Constantia Flexibles |
| Coveris Holdings |
| Sealed Air Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between packaging converters and consumer packaged goods companies lock in both material supply access and price visibility for high-volume peel and reseal formats. These contracts stabilize costs for specialized barrier films and adhesives.
Pricing Analysis
EU's Packaging and Packaging Waste Regulation dictates the pricing tier structure for recyclable peel and reseal solutions in Europe. Contract-based long-term offtake agreements dominate for high-volume applications. Price differentiation stems from recyclability certification for mono-material films and the level of customization required for specific product applications. Pricing softness reflects the high material and adhesive costs for performance films, particularly in price-sensitive food and beverage segments. Pharmaceutical applications exhibit lower price sensitivity due to stringent regulatory compliance.
Supply Chain Analysis
Specialized film production for peel and reseal packaging often necessitates longer lead times dueating to custom material formulations. Global supply concentrates across manufacturing hubs in China, Germany, and the United States. The industry relies heavily on polypropylene and polyethylene resins, alongside specialized pressure-sensitive adhesives. Commodity price volatility for petrochemical feedstocks represents a significant structural risk for film producers. Downstream distribution typically involves direct supply channels from packaging converters to large consumer packaged goods manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The peel and reseal packaging market presents a fragmentation opportunity, driven by consumer demand for portion control and extended freshness across diverse product categories. This shift creates niches for specialized, application-specific packaging solutions.
For Market Incumbents: Fortify existing market positions by accelerating investment in mono-material film research and development. Expand global manufacturing capacity for compliant, recyclable solutions to counter the threat of stringent regulatory mandates like the EU's Packaging and Packaging Waste Regulation. Leverage certification investment to validate new recyclable formats, maintaining competitive advantage against emerging sustainable alternatives. Consolidate supply chains for key raw materials to mitigate cost volatility.
For New Entrants and Emerging Players: Lead with innovative, integrated smart packaging solutions combining resealability with digital functionalities. Target underpenetrated pharmaceutical applications, improving medication safety and compliance. The most penetrable segments include emerging markets in Latin America and Southeast Asia, driven by rising disposable incomes. A go-to-market angle emphasizing enhanced product integrity and consumer engagement can differentiate offerings.
For Investors and Strategic Acquirers: Capital is best deployed toward specialized film producers demonstrating proven expertise in mono-material and high-barrier technologies. The market shows strong long-term viability over the next decade, driven by sustainability mandates and consumer convenience. Acquisition targets should include innovators with strong intellectual property in advanced adhesive formulations. The signal to watch for market inflection is the widespread adoption of standardized recycling infrastructure for flexible plastic packaging.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Mono-Material Extrusion Lines | Enables compliance with EU's Packaging and Packaging Waste Regulation, expanding market access for converters. |
| Develop Advanced Pressure-Sensitive Adhesives | Improves resealability performance for multi-use food products, enhancing consumer convenience and freshness. |
| Expand Pharmaceutical Packaging Portfolio | Captures untapped potential in multi-dose medications, addressing safety and compliance needs for patients. |
| Certify Recyclable Packaging Formats | Provides tangible sustainability credentials for consumer brands, meeting shifting consumer preference in North America. |
| Establish Production Hubs in Southeast Asia | Addresses rising disposable incomes and organized retail growth in emerging markets, expanding geographic reach. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. We engaged packaging engineers, CPG procurement managers, regulatory affairs specialists, and material scientists. Secondary sources included U.S. FDA guidelines, EFSA reports, trade association publications, and relevant company financial filings. Bottom-up market sizing and top-down validation were employed to ensure data accuracy.
The market forecast spans the projection horizon, employing a robust analytical framework. Segmentation dimensions modeled included product type, material, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical growth trends and projected market dynamics. Key forecast inputs incorporated consumer convenience demand and the anticipated impact of global sustainability regulations.
Forecasts assume regulatory continuity in U.S. FDA and EU's Packaging and Packaging Waste Regulation frameworks; material policy shifts would require re-modeling. The analysis reflects current market dynamics, but unforeseen shifts in material science or global economic downturns could alter trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market