
 Halal Packaging Market | 2026-2036
Halal Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Halal Packaging Market Outlook
Smart active packaging with embedded halal traceability layers is reconfiguring supply chain verification from batch testing to continuous digital authentication. Tetra Pak leverages its aseptic carton platform to anchor shelf-stable dairy and beverage segments across Muslim-majority markets. Amcor plc sustains multi-region production flexibility through its global converting network, while Huhtamaki Group specializes in fiber-based molded packaging for quick-service halal food applications.
Halal packaging comprises materials, containers, and sealing systems manufactured under Islamic dietary law compliance, requiring absence of pork derivatives, alcohol-based adhesives, and cross-contamination risks; specifications include migration-tested polyethylene films and titanium dioxide-free paperboard coatings to preserve product integrity. Flexible packaging leads volume deployment due to cost efficiency in snack and confectionery wrapping, though biodegradable plastics within the material matrix represent the fastest-expanding segment as JAKIM and EMA-aligned frameworks tighten substrate purity rules. Paperboard occupies stable demand in dry goods cartons where brand owners prioritize recyclability alongside religious compliance.
JAKIM in Malaysia, Indonesia's BPJPH, and the UAE's ESMA collectively enforce divergent certification protocols that fragment market access and elevate compliance costs for multi-country suppliers. ISO 17065 accreditation requirements from these bodies now extend beyond finished goods to raw material provenance and facility sanitation audits. Stakeholders must monitor certification reciprocity negotiations between Southeast Asian and Gulf regulators to anticipate harmonization windows that could reshape competitive entry barriers.
Market Dynamics
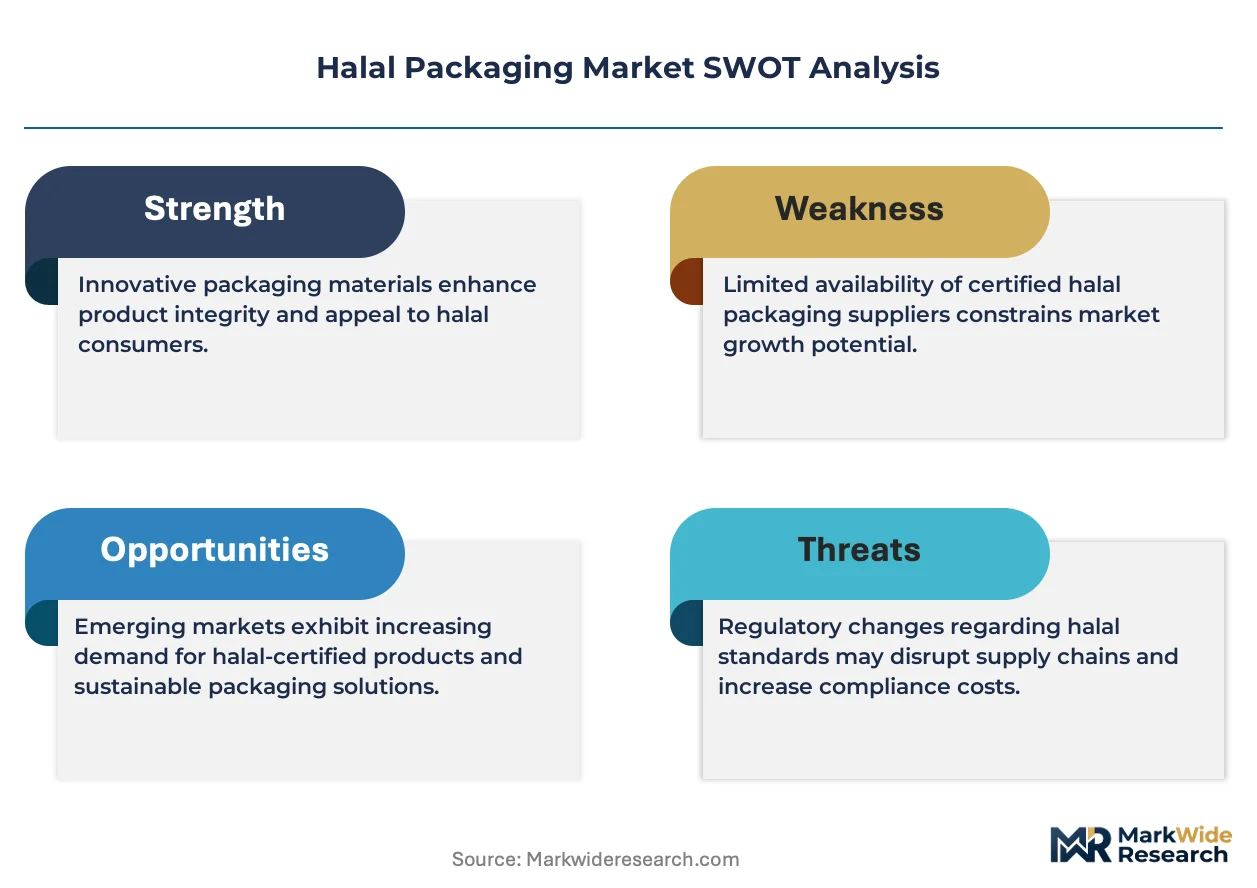
Certification protocol fragmentation across Southeast Asian and Gulf regulators is forcing suppliers to maintain parallel compliance tracks, elevating fixed costs and compressing margins for converters serving multi-jurisdictional food brands.
Growth Catalysts
- BPJPH Mandate Expansion:Indonesia's halal certification body now requires packaging substrate provenance documentation for all processed food exports, creating audit-ready demand for traceable supply chains.
- Smart Layer Integration:Embedded NFC and blockchain authentication layers in flexible films enable real-time halal status verification, reducing batch recall risk for dairy and meat exporters.
- UAE Hub Positioning:Dubai's logistics free zones attract regional food brand headquarters, concentrating procurement decision-making and packaging specification authority in Gulf-based supply chain teams.
Market Restraints
- Titanium Dioxide Substitution Costs:EFSA's 2022 reclassification of TiO2 as a prohibited food-contact additive forces reformulation of paperboard coatings, raising raw material expenses for carton producers.
- Reciprocity Gaps:JAKIM and ESMA maintain non-mutually-recognized audit standards, compelling Malaysian suppliers to undergo duplicate facility inspections for Gulf market access.
- Biodegradable Performance Limits:PLA and PHA films exhibit inferior moisture barrier properties versus conventional polyethylene, restricting deployment in high-humidity Southeast Asian distribution channels.
Strategic Opportunities
- African Market Underpenetration:Nigeria and Egypt lack domestic halal packaging certification infrastructure, creating first-mover advantage for converters establishing local converting partnerships.
- Quick-Service Restaurant Expansion:Middle Eastern fast-casual chains entering European cities require certified fiber-based takeaway containers, opening molded pulp applications beyond traditional Asian markets.
- EU Green Deal Alignment:CSRD disclosure requirements on packaging circularity intersect with halal purity rules, allowing certified suppliers to capture dual-compliant premium positioning in continental retail.
Industry Challenges
- Halal Auditor Scarcity:JAKIM and BPJPH-accredited inspectors remain concentrated in Kuala Lumpur and Jakarta, creating 90-120 day certification backlogs for facilities in secondary cities.
- Legacy Adhesive Migration:Alcohol-based solvent adhesives persist in existing converting equipment, requiring capital-intensive line retrofits to achieve full substrate compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halal Packaging Market |
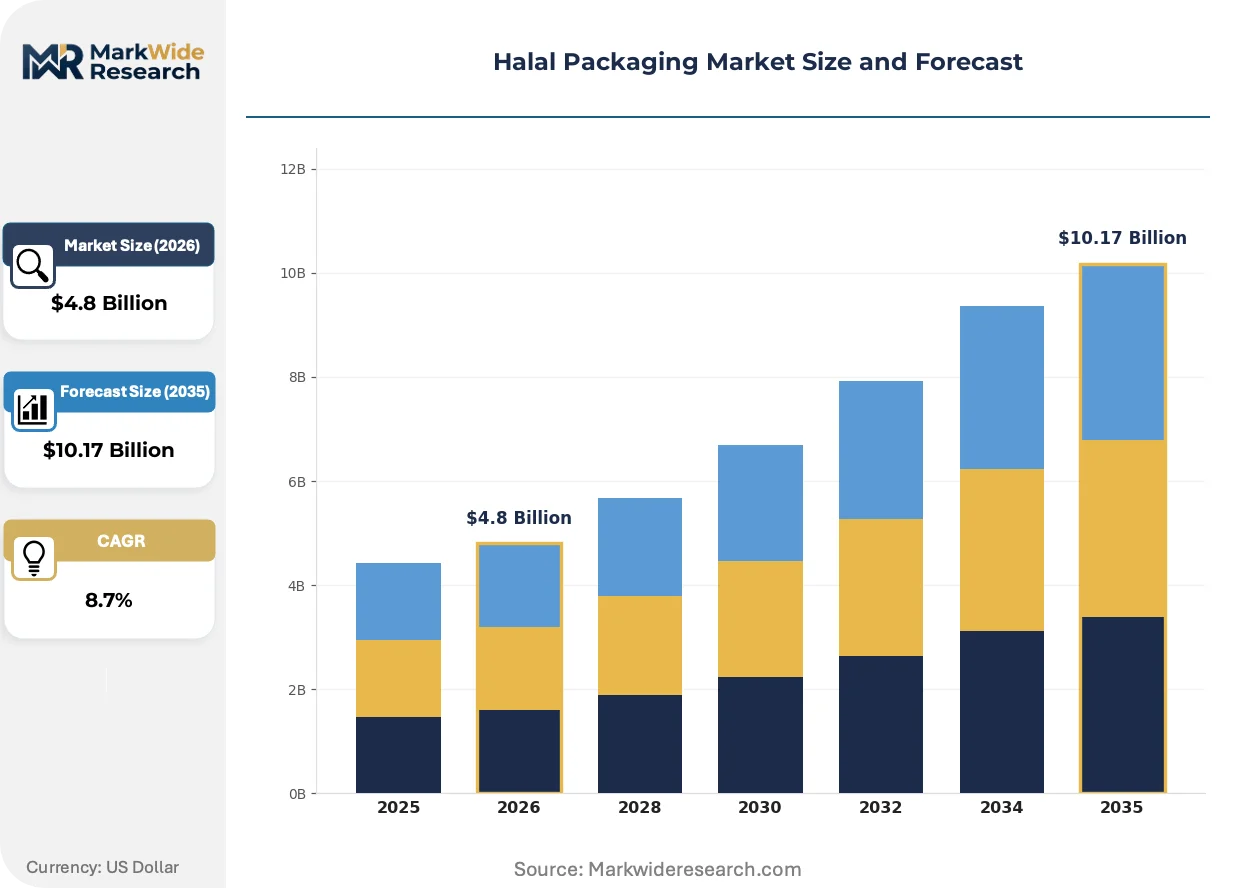
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paper Packaging, Glass Packaging Material: Biodegradable Plastics, Polyethylene, Paperboard, Aluminum End User: Food Industry, Cosmetics, Pharmaceuticals, Health Supplements Certification: Halal Certified, ISO Certified, Non-Toxic Certified, Organic Certified |
| Companies Covered | DuPont, Clondalkin Group, Tetra Pak, Huhtamaki Group, Sealed Air Corporation, Amcor plc, DS Smith, Coveris Holdings S.A., Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halal Packaging Market Strategic Shifts
Digital authentication infrastructure is displacing paper-based certificate verification, while material science advances enable simultaneous compliance with religious purity standards and circular economy mandates.
Active intelligent packaging incorporating time-temperature indicators and halal integrity sensors is hybridizing with aseptic carton platforms. Indonesian processed seafood exporters are piloting these systems for EU-bound shipments. This convergence is compressing the traditional separation between food safety monitoring and religious compliance verification, forcing converters to integrate electronics assembly capabilities.
Malaysia's JAKIM revised its Halal Certification Procedure in 2023 to mandate blockchain-anchored supply chain documentation for all packaging substrates. The regulation requires immutable provenance records from raw material extraction through final conversion. Medium-sized Malaysian converters are responding by subscribing to third-party verification platforms rather than building proprietary systems, altering competitive economics toward platform-dependent scale players.
Certification-driven supplier consolidation is reshaping procurement patterns among Southeast Asian food brands. Buyers are narrowing approved vendor lists to converters holding dual JAKIM-BPJPH accreditation, eliminating single-certified competitors from tender processes. This concentration is most pronounced in Indonesia's instant noodle and confectionery segments, where export-grade compliance has become a non-negotiable procurement filter.
Halal Packaging Market Segmentation
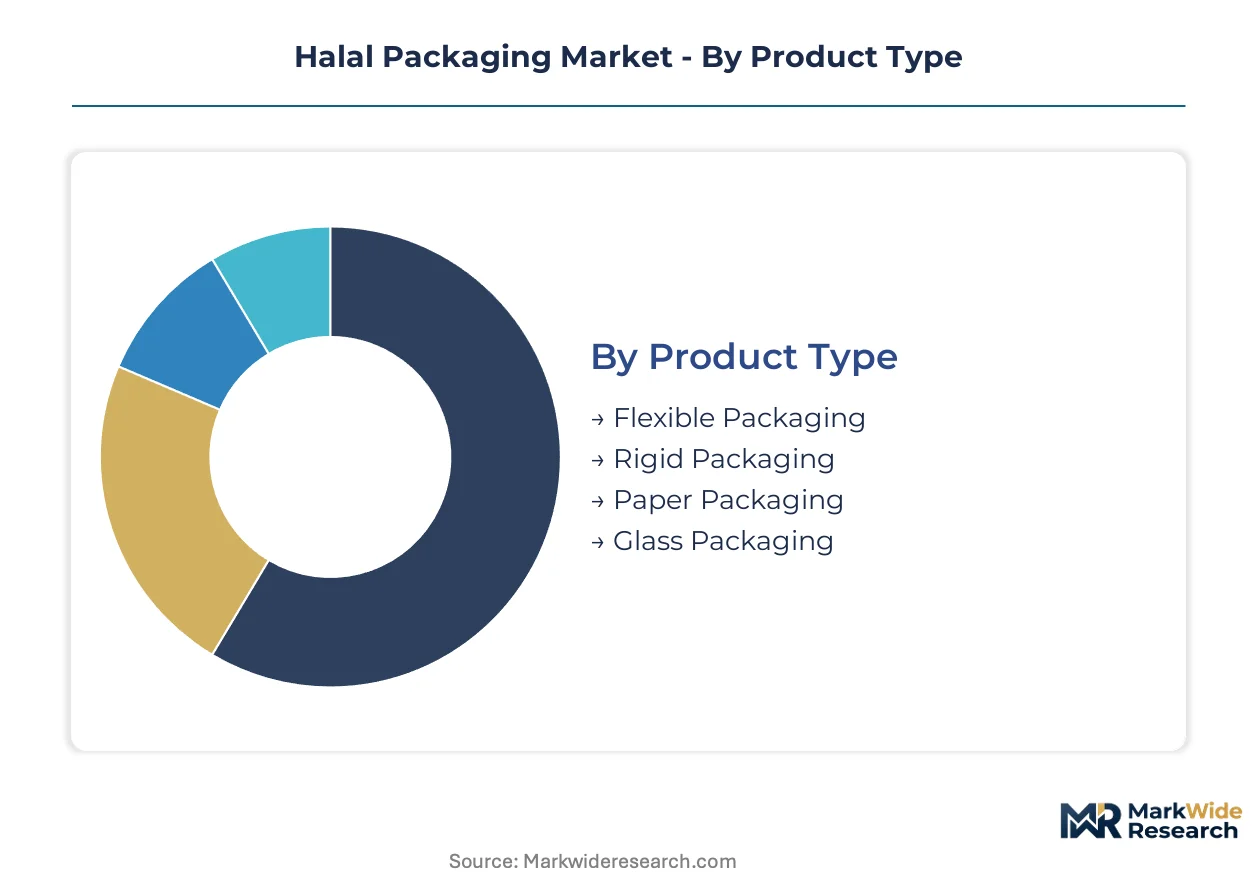
Halal packaging segmentation reveals divergent compliance burdens and margin structures across substrate categories. Certification requirements cascade differently through flexible films versus rigid containers, reshaping procurement priorities for multi-jurisdictional food brands.
Product Type:
Flexible packaging turns inventory fastest through snack and confectionery channels, while glass packaging cycles slowest due to extended sterilization protocols and return logistics.
- Flexible Packaging:Multi-layer polyethylene and polypropylene films dominate high-volume wrapping applications. Indonesian instant noodle manufacturers drive specification intensity here, demanding migration-tested substrates that satisfy both JAKIM and BPJPH documentation requirements.
- Paper Packaging:Fiber-based cartons and molded pulp containers serve dry goods and quick-service takeaway segments. Malaysian dry goods brands prioritize these formats for recyclability alignment with EU Green Deal disclosure mandates.
- Rigid Packaging:Thermoformed trays and injection-molded containers protect processed meat and dairy products through cold chain distribution.
- Glass Packaging:Aseptic bottles and jars preserve premium sauces and beverages, though weight and fragility limit Southeast Asian distribution economics.
Flexible packaging dominates installed base. Paper packaging is where expansion concentrates.
Material:
Cost tiers separate commodity substrates from certified specialty grades, with biodegradables commanding 40-60% premiums over conventional polyethylene.
- Biodegradable Plastics:PLA and PHA films offer compostability compliance but exhibit moisture barrier limitations. Indonesian exporters pilot these for EU-bound shipments where circularity rules intersect with halal purity standards.
- Polyethylene:Low-density and linear-low-density films remain the workhorse for moisture-sensitive applications. Malaysian converters maintain multi-layer extrusion lines certified under tightened JAKIM substrate protocols.
- Paperboard:Titanium dioxide-free coatings are reformulating following EFSA reclassification, raising coating costs for carton producers.
- Aluminum:Foil laminates provide oxygen and light barriers for extended shelf-life dairy and infant nutrition products.
Polyethylene anchors volume throughput. Biodegradable plastics are climbing the fastest.
End User:
Application maturity varies sharply, with food sector compliance infrastructure far ahead of nascent pharmaceutical halal requirements.
- Food Industry:Processed meat, dairy, and confectionery segments generate the bulk of certified packaging procurement. Indonesian domestic brands seeking export-grade compliance are tightening substrate traceability requirements.
- Cosmetics:Alcohol-free formulation packaging is expanding as Muslim-majority market consumers demand sharia-compliant personal care products.
- Pharmaceuticals:Gelatin-free capsule and alcohol-free syrup packaging represents an emerging compliance frontier with limited certified supplier infrastructure.
- Health Supplements:Probiotic and vitamin formats require substrate purity documentation to prevent cross-contamination with non-halal processing aids.
Food Industry commands procurement scale. Cosmetics is gaining share fastest.
Certification:
Customer type stratification shows halal certification as table stakes, with dual and triple certifications becoming competitive differentiators for premium positioning.
- Halal Certified:JAKIM, BPJPH, and ESMA accreditation now extends to raw material provenance and facility sanitation audits. Malaysian converters face 90-120 day inspection backlogs.
- ISO Certified:Quality management and food safety standards provide baseline operational credibility for multi-regional suppliers.
- Non-Toxic Certified:Migration testing and heavy metal screening addresses consumer safety concerns beyond religious compliance.
- Organic Certified:EU and USDA organic alignment allows simultaneous capture of sustainability-premium and halal-premium positioning.
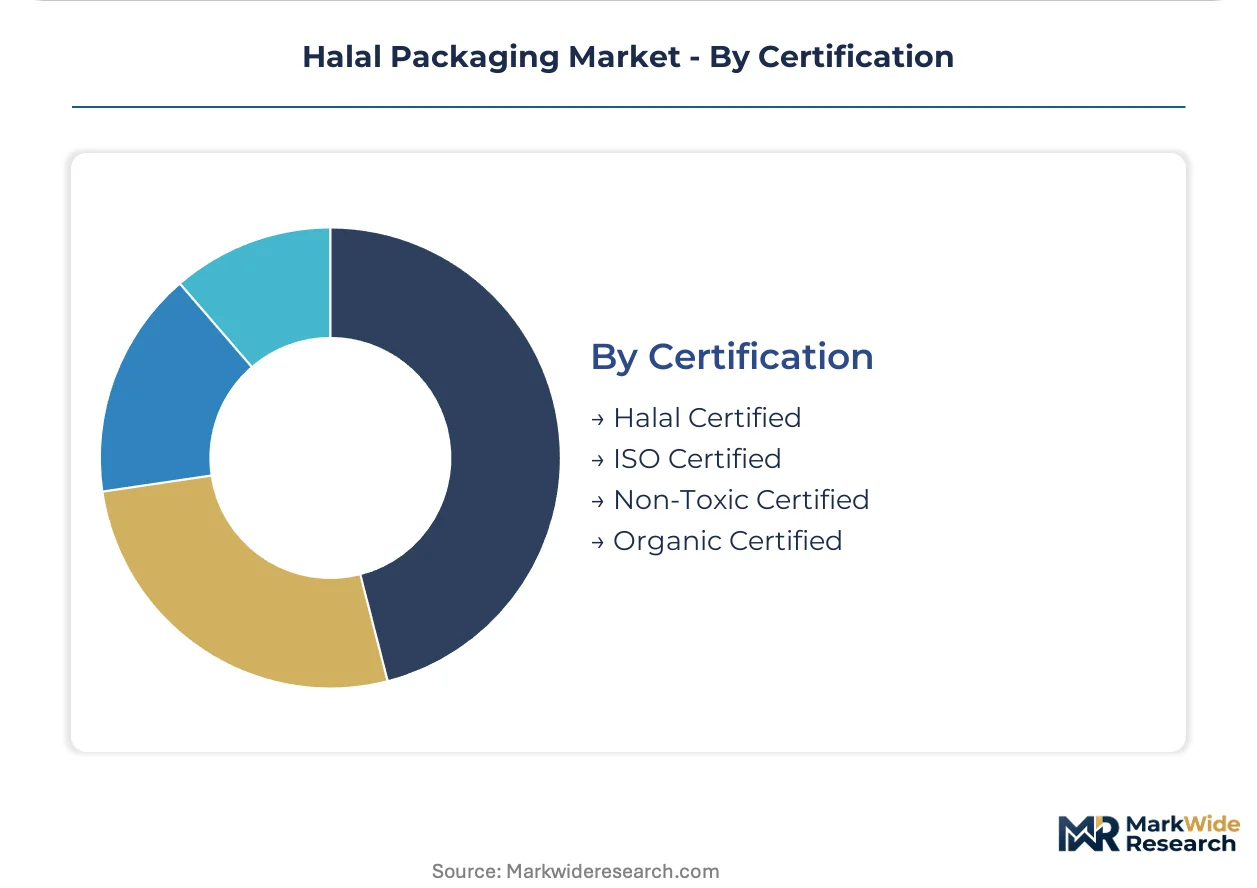
Halal Certified dominates tender requirements. ISO Certified is where supplier consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesian processed food exporters supply certified packaging-compliant goods to Gulf retail chains, while Malaysian converters serve Southeast Asian brands seeking dual JAKIM-BPJPH accreditation. This trade corridor shapes procurement specifications across both origin and destination markets.
Indonesia
Domestic instant noodle and confectionery manufacturers drive substrate traceability intensity as BPJPH mandates packaging provenance documentation for all processed food exports. The national halal certification body tightened audit protocols in 2024, extending facility sanitation requirements to raw material suppliers. Jakarta and Surabaya house the densest converter clusters, where medium-sized firms subscribe to third-party blockchain verification platforms to satisfy documentation burdens.
Malaysia
JAKIM's 2023 Halal Certification Procedure revision forced blockchain-anchored supply chain records for all packaging substrates, creating 90-120 day inspection backlogs for facilities outside Kuala Lumpur. The Department of Islamic Development Malaysia now requires migration-tested polyethylene films and titanium dioxide-free paperboard coatings. Penang and Selangor concentrate certified converting capacity, with exporters serving Indonesian brands seeking dual-accredited suppliers.
Saudi Arabia
The Saudi Food and Drug Authority enforces halal packaging standards for imported processed foods, with SFDA alignment to Gulf Cooperation Council technical regulations creating regional certification reciprocity. Domestic dairy and meat processors anchor rigid packaging demand for cold chain distribution. Jeddah Islamic Port and Riyadh industrial zones attract logistics headquarters positioning procurement authority for regional food brand supply chains.
United Arab Emirates
Dubai's logistics free zones concentrate procurement decision-making for Middle Eastern fast-casual chains expanding into European cities, generating demand for certified fiber-based takeaway containers. The Emirates Authority for Standardization and Metrology maintains non-mutually-recognized audit standards with JAKIM, compelling Malaysian suppliers to undergo duplicate facility inspections. Abu Dhabi and Dubai house the Gulf's densest halal-certified converter representation.
Egypt
Domestic processed food brands lack local halal packaging certification infrastructure, creating first-mover positioning for converters establishing Egyptian partnerships. The country's national food safety regulator has begun drafting substrate purity guidelines aligned to broader African market harmonization efforts. Cairo and Alexandria industrial corridors concentrate import-dependent packaging procurement, with Gulf-accredited suppliers capturing premium positioning.
Halal Packaging Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven multinational converters hold procurement relationships with pan-regional food brands, while mid-sized accredited specialists capture single-country tender processes. The market fragments across certification jurisdiction lines rather than product lines, with JAKIM-only, BPJPH-only, and dual-accredited suppliers occupying distinct competitive tiers. Three archetypes dominate: aseptic carton platform operators, flexible film converters with multi-layer extrusion certification, and fiber-based molded packaging specialists. Consolidation pressure operates through certification-driven supplier narrowing, while geographic expansion and strategic partnerships represent the primary competitive moves for capacity-constrained players.
Among diversified packaging conglomerates, Tetra Pak and Amcor plc occupy positions exemplifying scale-driven platform strategies, while Huhtamaki Group represents the fiber-based specialist archetype. Tetra Pak anchors shelf-stable dairy and beverage segments through aseptic carton deployment across Muslim-majority markets. Amcor plc sustains multi-region production flexibility through global converting network configuration. Huhtamaki Group concentrates molded fiber applications for quick-service halal food takeaway formats.
| Leading Market Players |
|---|
| DuPont |
| Clondalkin Group |
| Tetra Pak |
| Huhtamaki Group |
| Sealed Air Corporation |
| Amcor plc |
| DS Smith |
| Coveris Holdings S.A. |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
Malaysian polyethylene resin converters anchor upstream substrate supply, concentrating margin capture with JAKIM-accredited facilities in Penang and Selangor while Indonesian buyers absorb certification premiums for dual-accredited sourcing.
Pricing Analysis
Conventional polyethylene films, next-generation biodegradable PLA/PHA substrates, and legacy titanium dioxide-coated paperboard occupy distinct price bands. Three-tier pricing structure across premium certified, standard single-accredited, and economy non-certified levels separates JAKIM-BPJPH dual-accredited suppliers from single-certified competitors. Certification documentation burdens and EFSA-driven coating reformulations are intensifying cost compression in paperboard segments. Indonesian instant noodle manufacturers exhibit highest price sensitivity due to export compliance mandates, while Gulf dairy processors show lowest sensitivity given cold-chain performance requirements.
Supply Chain Analysis
Contract manufacturing concentrates with Tetra Pak's aseptic carton foundries, Amcor's multi-region converting network, and Huhtamaki's fiber molding facilities. Raw material supply draws from Malaysian polyethylene extrusion hubs, Indonesian pulp processing clusters, and Thai aluminum foil laminators. Single-source vulnerability persists in blockchain-anchored verification platform subscriptions required by JAKIM's 2023 protocol revision. Distribution runs through Dubai's logistics free zones for Gulf procurement authority and Jakarta-Surabaya converter corridors for Indonesian domestic brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from certification backlog cyclicality as JAKIM and BPJPH inspector scarcity created 90-120 day approval delays that suppressed converter capacity utilization.
For Market Incumbents: Insulate margin pools by deepening backward integration into titanium dioxide-free coating formulation and captive polyethylene resin sourcing. Threat substitution from biodegradable film performance limitations in high-humidity Southeast Asian channels demands moisture-barrier R&D investment. Certification investment lever: secure dual JAKIM-BPJPH accreditation before supplier consolidation eliminates single-certified competitors from Indonesian instant noodle tenders. For New Entrants and Emerging Players: Pursue white-space positioning in Egypt and Nigeria where domestic halal packaging certification infrastructure remains underdeveloped. Most penetrable target: Egyptian processed food brands seeking Gulf-accredited suppliers for import substitution. Go-to-market angle: partner with local industrial zone developers in Cairo-Alexandria corridors to establish converting presence ahead of national regulator substrate purity guideline finalization. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale Malaysian converters holding JAKIM accreditation with latent capacity for BPJPH dual-certification. Long-term viability across 5-10 year windows rests on certification reciprocity harmonization between Southeast Asian and Gulf regulators reducing duplicate audit burdens. Signal to watch: JAKIM-ESMA mutual recognition agreement negotiations as inflection indicator for margin expansion in multi-jurisdictional supplier portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | JAKIM-BPJPH dual accreditation unlocks Indonesian export-grade procurement from consolidated buyer lists. |
| Blockchain Platform Subscription | Third-party verification platforms satisfy JAKIM's immutable provenance documentation mandates without proprietary buildout. |
| Titanium Dioxide-Free Coating Reformulation | EFSA reclassification compliance preserves paperboard carton access to EU-bound processed food shipments. |
| African Partnership Establishment | Egyptian and Nigerian first-mover positioning captures premium pricing before local certification infrastructure matures. |
| Smart Layer Integration | NFC and blockchain authentication layers enable real-time halal verification reducing dairy and meat exporter recall risk. |
Study Parameters
Operator-level perspectives from packaging procurement managers at Indonesian processed food exporters, JAKIM-accredited facility auditors, Malaysian converter operations directors, and Gulf retail chain supply chain heads anchored the qualitative base. Primary interview insights combined with secondary validation from BPJPH regulatory filings, JAKIM Halal Certification Procedure documentation, EFSA food-contact additive reclassification records, and Dubai Multi Commodities Centre trade statistics. Bottom-up substrate demand modeling and top-down packaging value chain sizing were triangulated for consistency.
Scenario-bracketing framed volume and value outputs across the projection horizon. Segmentation dimensions modeled include packaging substrate type, certification tier, end-use application, and regional regulatory cluster alignment. CAGRs were derived from certified packaging procurement intensity trends and export compliance adoption curves. Industry-specific forecast inputs incorporated BPJPH mandate expansion timelines and JAKIM inspector capacity constraints.
Sensitivities concentrate around certification reciprocity negotiation outcomes, biodegradable film moisture-barrier performance breakthroughs, and African regulator guideline harmonization progress. Forecasts reflect documented assumptions on audit standard convergence and substrate purity rule alignment. Quarterly review of JAKIM-BPJPH inspection backlog durations and ESMA mutual recognition dialogue status is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Secondary Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
Interior Packaging Market