
 South Korea Container Glass Market | 2026-2036
South Korea Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Container Glass Market Insights
Buyer concentration in South Korea's beverage sector is consolidating as leading soju and makgeolli producers centralize procurement under fewer contract bottlers. Samkwang Glass leverages its Gwangju-Jeolla manufacturing complex to anchor supply for domestic spirits brands. Kumbi Corporation sustains long-term furnace operations through captive energy partnerships. Gerresheimer competes on pharmaceutical-grade borosilicate vial output for Seoul-based biotech customers.
Container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, typically containing 70-74% silica with thermal shock resistance between 40-60°C for filled product integrity. Bottles occupy the dominant volume position across alcoholic and non-alcoholic beverage filling lines, while vials command premium margins under MFDS sterilization-grade specifications. Jars segment growth concentrates in fermented food packaging where oxygen barrier properties outperform plastic alternatives.
MFDS enforces pharmacopeial glass standards for injectable drug containers, while Korea's Ministry of Environment administers extended producer responsibility schemes affecting post-consumer cullet recovery rates. K-Bottle deposit legislation and municipal recycling quotas shape raw material sourcing strategies for furnace operators. Stakeholders must monitor carbon border adjustment developments and cullet quality premiums as Seoul tightens industrial emissions benchmarks.
Market Dynamics
Buyer consolidation among soju and makgeolli producers is compressing supplier margins while MFDS sterilization-grade mandates raise technical barriers for pharmaceutical glass entrants. Furnace operators face simultaneous pressure from carbon border adjustments and cullet quality premiums under Seoul's tightening emissions benchmarks.
Growth Catalysts
- Premium cosmetics packaging migration:Luxury beauty brands are expanding glass adoption for shelf differentiation and perceived quality elevation, pulling demand from Seoul-based contract manufacturers.
- K-Bottle deposit-return expansion:Korea's Ministry of Environment schemes tighten material traceability requirements, creating captive cullet supply advantages for integrated furnace operators.
- Craft spirits bottling contracts:Small-batch soju and whiskey producers are fragmenting procurement across specialized container glass suppliers in the Seoul-Incheon corridor.
Market Restraints
- Natural gas price volatility:Furnace operations depend on imported LNG feedstock, exposing operators to energy cost swings that compress margin buffers during heating seasons.
- Pharmaceutical-grade technical barriers:MFDS borosilicate vial specifications require capital-intensive furnace modifications that exclude mid-scale competitors from high-margin segments.
- Aluminum can substitution:Beer and RTD beverage producers are accelerating metal packaging adoption for logistics efficiency, displacing glass volume in mainstream alcoholic segments.
Strategic Opportunities
- Fermented food jar expansion:Kimchi and jeotgal producers are migrating from plastic to oxygen-barrier glass containers, opening premium positioning for Jeolla-region manufacturers.
- Biotech vial demand:Seoul-based cell therapy developers are creating pull for pharmaceutical-grade borosilicate capacity as MFDS fast-track approvals expand.
- Carbon-neutral furnace retrofits:Green hydrogen pilot programs under Korea's national hydrogen roadmap offer first-mover positioning for emissions-compliant glass production.
Industry Challenges
- Skilled furnace engineer scarcity:Specialized glass technology programs at Korean universities are producing insufficient graduates to replace retiring plant operators.
- Extended MFDS certification timelines:Injectable drug container approvals now require eighteen-month stability testing cycles that delay revenue recognition for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Container Glass Market |
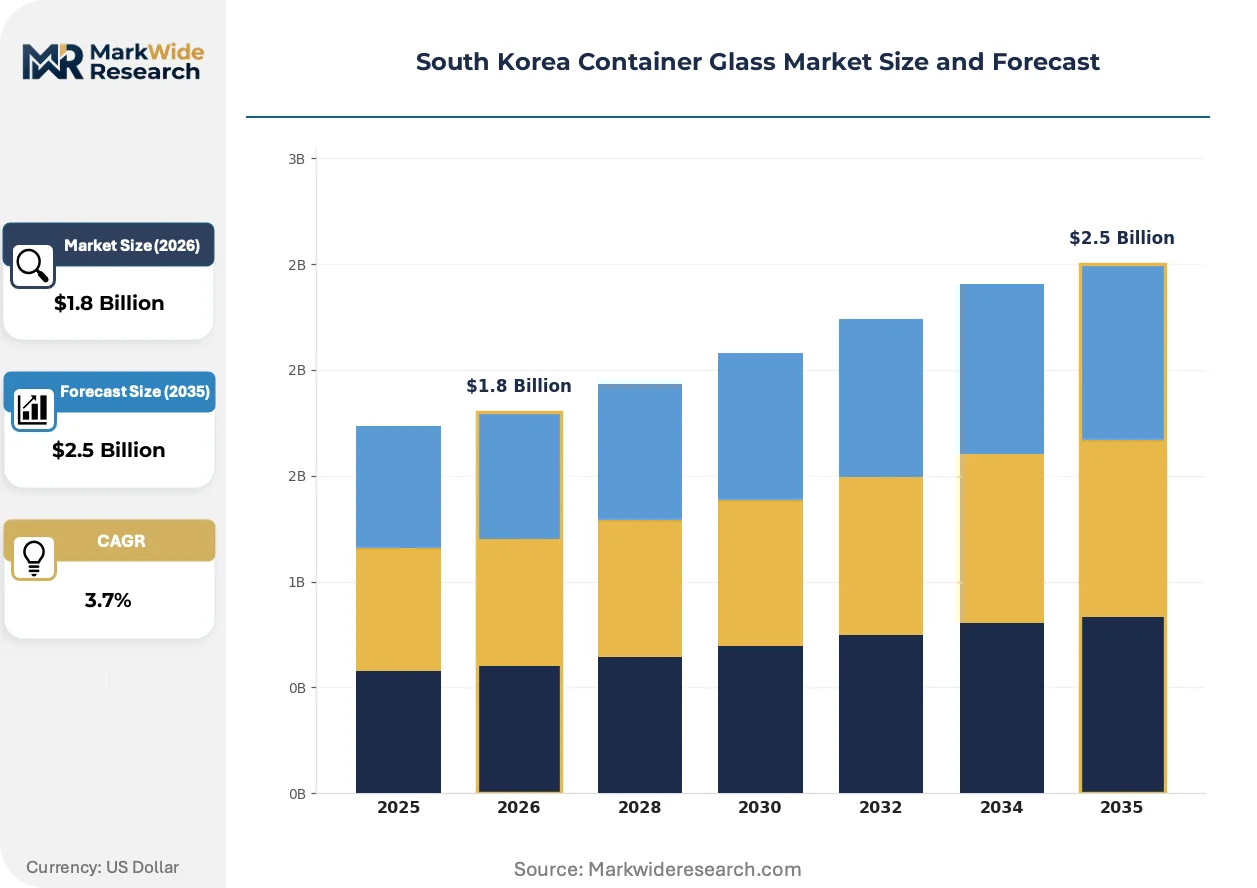
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Tumblers End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Closure Type: Caps, Corks, Pumps, Sprayers Shape: Round, Square, Rectangular, Custom |
| Companies Covered | Kumbi Corporation, Samkwang Glass, Somang Glass Co., Ltd, SGC Solutions Co., Ltd, Verescence Pacific, Inc, Pacific Glas, Gerresheimer, Stoelzle Glass Group, Vidrala, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Container Glass Market Trends and Innovations
Digital manufacturing integration and sustainability-driven material science are reshaping competitive positioning across Korea's container glass sector. Furnace operators are deploying sensor networks and predictive analytics to optimize thermal efficiency while regulatory pressure accelerates low-carbon production transitions.
Electrified melting technology is converging with renewable energy procurement strategies to enable fossil-fuel-free glass production. Samkwang Glass and Kumbi Corporation are piloting hybrid furnace architectures at Gwangju-Jeolla complexes. This convergence is compressing the cost gap between conventional natural gas melting and carbon-neutral alternatives for premium contract segments.
MFDS is tightening pharmacopeial glass standards for injectable drug containers through enhanced particulate matter testing protocols. The regulator's sterilization-grade specifications now mandate automated visual inspection systems. Biotech vial manufacturers in the Seoul metropolitan area are responding by retrofitting production lines with AI-defect detection equipment.
Direct procurement relationships between spirits brands and furnace operators are displacing traditional distributor intermediaries. Major soju producers are negotiating multi-year volume commitments with specific manufacturing complexes. This pattern is most visible in the Seoul-Incheon corridor where logistics proximity enables just-in-time bottling line integration.
South Korea Container Glass Market Segmentation
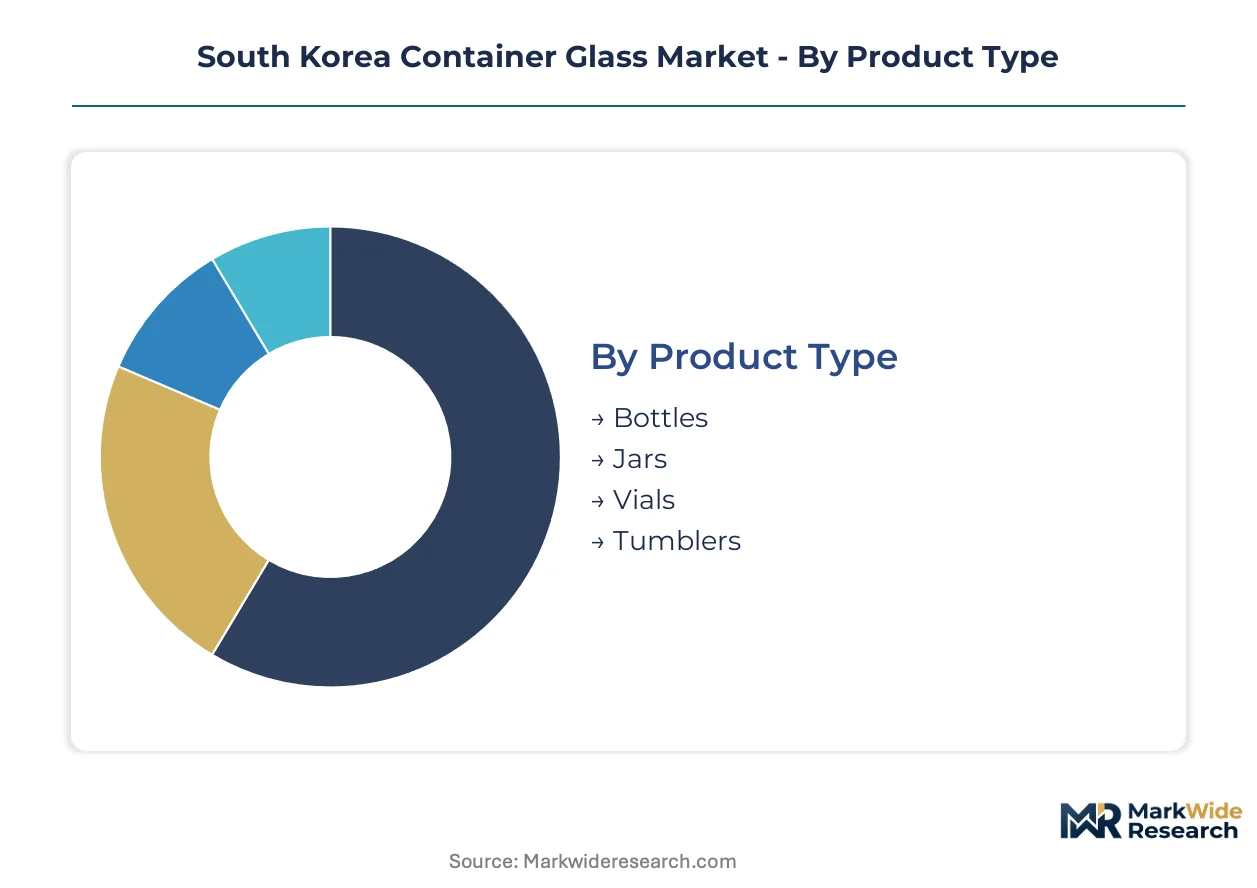
South Korea's container glass market fragments across product specifications that align with distinct regulatory and performance requirements. MFDS sterilization mandates, K-Bottle deposit traceability rules, and premium cosmetics shelf differentiation each create specialized procurement patterns among domestic buyers.
Product Type:
Buyers differentiate primarily by thermal shock tolerance and oxygen barrier needs rather than price alone.
- Bottles:Soda-lime silica vessels containing 70-74% silica with 40-60°C thermal shock resistance for filled product integrity. Soju and craft spirits producers in the Seoul-Incheon corridor are consolidating procurement under direct furnace contracts, compressing distributor margins while pulling volume toward specialized blow-and-blow production lines.
- Jars:Press-and-blow formed containers optimized for oxygen barrier performance in fermented food packaging. Kimchi and jeotgal producers across Jeolla province are migrating from plastic alternatives, opening premium positioning for Gwangju-region manufacturers with captive cullet recovery systems.
- Vials:MFDS pharmacopeial-grade borosilicate containers for injectable drugs requiring eighteen-month stability testing cycles.
- Tumblers:Direct-melt soda-lime drinkware serving hospitality and retail channels with lower technical barriers.
Bottles lead volumes today; jars are gaining share fastest.
End User:
Application-specific certification requirements create divergent margin structures across customer categories.
- Food & Beverage:Alcoholic and non-alcoholic filling lines dominate unit economics, with soju producers centralizing procurement under fewer contract bottlers. K-Bottle deposit-return schemes tighten material traceability, favoring integrated furnace operators with captive cullet supply.
- Pharmaceuticals:MFDS enforces enhanced particulate matter testing and automated visual inspection mandates for sterilization-grade containers. Seoul-based biotech developers are creating pull for borosilicate capacity as fast-track approvals expand.
- Cosmetics:Premium beauty brands prioritize shelf differentiation through glass adoption, contracting Seoul metropolitan area manufacturers for luxury packaging runs.
- Household Products:Cleaning and personal care applications face aluminum can substitution pressure in logistics-sensitive segments.
Food and beverage anchors volume; pharmaceuticals shows the steepest expansion trajectory.
Closure Type:
Sealing mechanism selection tracks end-use shelf life requirements and consumer convenience expectations.
- Caps:Screw-top and lug finishes for mainstream beverage and food applications, with soju producers specifying tamper-evident designs for retail compliance.
- Corks:Natural and synthetic sealing for premium spirits and wine positioning, concentrated among craft whiskey and small-batch soju brands.
- Pumps:Dispensing mechanisms for cosmetics and household products, requiring thread standardization with Seoul-based contract fillers.
- Sprayers:Aerosol and trigger systems for personal care and cleaning applications, facing technical compatibility constraints with borosilicate vial specifications.
Caps dominate unit shipments; pumps are climbing the fastest on cosmetics demand.
Shape:
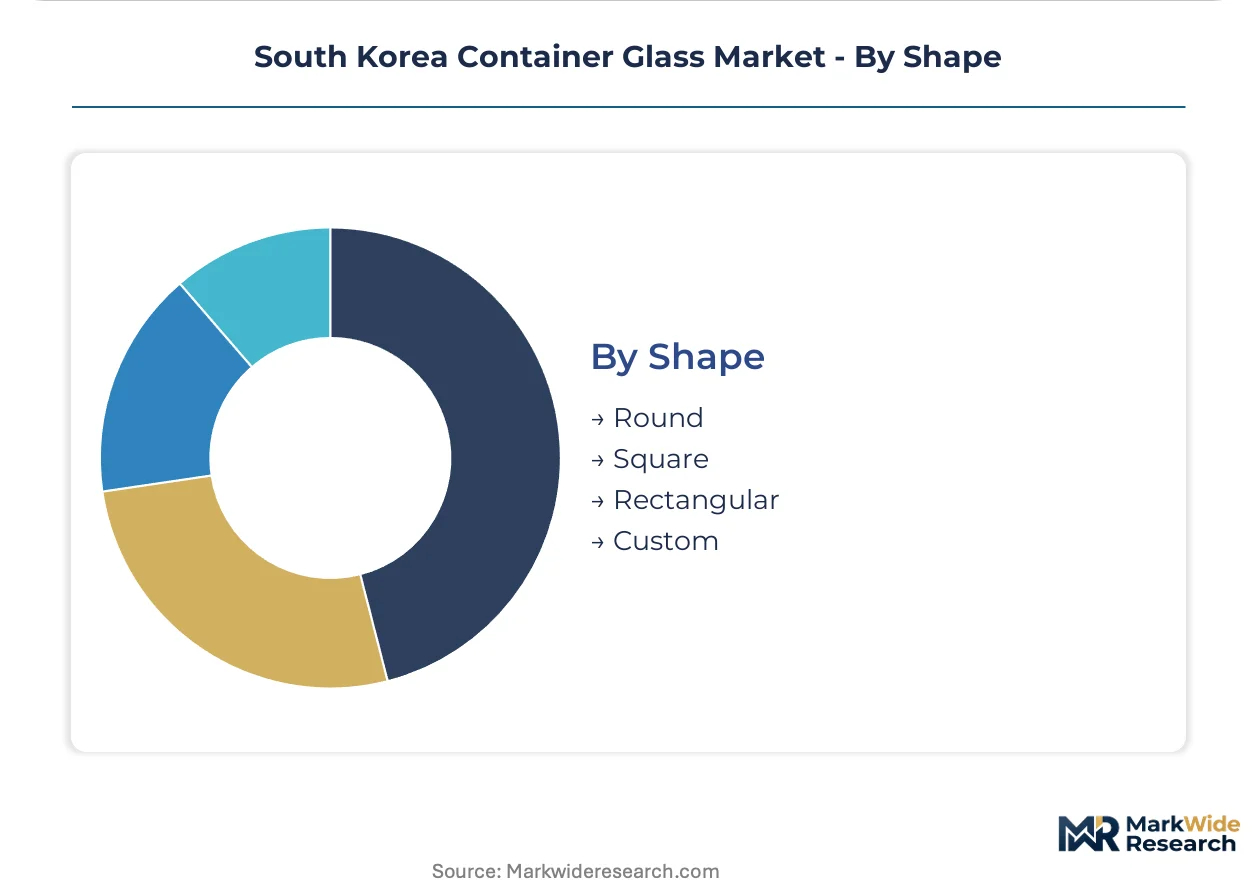
Geometry decisions reflect logistics efficiency trade-offs against brand differentiation requirements.
- Round:Standard cylindrical profiles optimizing pallet density and label adhesion for high-volume soju and makgeolli bottling lines.
- Square:Shelf-space-efficient designs for premium spirits and cosmetics, enabling rectangular packing configurations that reduce transport void space.
- Rectangular:Flat-panel constructions for fermented food jars, maximizing refrigeration storage density in Korean retail formats.
- Custom:Proprietary molds for luxury cosmetics and limited-edition spirits releases, carrying higher tooling amortization across shorter production runs.
Round shapes command volume leadership; custom geometries are expanding most quickly in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's container glass output concentrates in distinct industrial corridors, while neighboring economies pursue divergent packaging strategies shaped by local regulatory frameworks and end-use demand patterns.
Seoul Capital Area
Biotech vial demand from Seoul-based cell therapy developers is pulling pharmaceutical-grade borosilicate capacity toward the metropolitan core. MFDS fast-track approval pathways are accelerating sterilization-grade container procurement cycles. Incheon corridor manufacturers are capturing direct furnace contracts from major soju producers seeking just-in-time bottling line integration.
Busan-Ulsan
Southeastern port infrastructure supports export-oriented glass packaging for cosmetics brands targeting Asian luxury markets. Korea's Ministry of Environment K-Bottle deposit schemes are tightening material traceability requirements for regional furnace operators. Ulsan industrial complexes are piloting green hydrogen furnace retrofits under the national hydrogen roadmap.
Gwangju-Honam
Jeolla province kimchi and jeotgal producers are migrating from plastic to oxygen-barrier glass containers, opening premium positioning for regional manufacturers. Captive cullet recovery systems at Gwangju-area complexes are creating supply advantages under extended producer responsibility mandates. Samkwang Glass anchors domestic spirits supply from its Jeolla manufacturing base.
Daegu-Gyeongbuk
Traditional soju and makgeolli bottling operations maintain procurement relationships with mid-scale furnace operators in the southeastern interior. Buyer consolidation among alcoholic beverage producers is compressing supplier margins across the sub-region. Gyeongbuk industrial zones face skilled furnace engineer scarcity as university programs produce insufficient replacement graduates.
Daejeon-Sejong
Central government administrative proximity shapes regulatory compliance infrastructure for pharmaceutical glass entrants. MFDS eighteen-month stability testing cycles for injectable drug containers delay revenue recognition for new manufacturing investments. Sejong special autonomous city development plans are attracting logistics-focused packaging distributors serving national beverage networks.
South Korea Container Glass Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South Korea's container glass sector, creating a tiered structure where scale advantages clash with technical specialization. The market consolidates around furnace operators with captive energy partnerships and integrated cullet recovery systems. Three archetypes dominate: domestic conglomerates with multi-site manufacturing networks, foreign multinationals with pharmaceutical-grade certification, and regional specialists serving fermented food and craft spirits niches. Capacity expansion and direct procurement relationships represent the dominant competitive moves as soju producers bypass traditional distributor intermediaries.
Among domestic furnace operators, Kumbi Corporation and Samkwang Glass exemplify the integrated conglomerate archetype through multi-site manufacturing presence and captive supply chain control. Foreign multinationals including Gerresheimer occupy positions in pharmaceutical-grade segments where MFDS sterilization mandates create technical barriers. These named entities represent strategic positioning patterns rather than specific market share claims, with each archetype responding differently to carbon border adjustment pressures and green hydrogen transition timelines.
| Leading Market Players |
|---|
| Kumbi Corporation |
| Samkwang Glass |
| Somang Glass Co., Ltd |
| SGC Solutions Co., Ltd |
| Verescence Pacific, Inc |
| Pacific Glas |
| Gerresheimer |
| Stoelzle Glass Group |
| Vidrala |
| Others |
Pricing and Supply Chain Analysis
Electrified melting technology pilots at Gwangju-Jeolla complexes are compressing the cost gap between natural gas furnaces and carbon-neutral alternatives, simultaneously redistributing pricing power toward integrated operators with captive renewable energy partnerships and tightening supply concentration around multi-site conglomerates.
Pricing Analysis
Capacity additions in the Seoul-Incheon corridor are reshaping price floors for standard soda-lime bottles as direct furnace contracts displace distributor intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates MFDS-certified pharmaceutical vials from food-grade containers and commodity tumblers. Cost compression in mainstream beverage glass is intensifying because aluminum can substitution erodes volume commitments. Mass-market soju producers exhibit highest price sensitivity, while biotech developers accept premium positioning for sterilization-grade borosilicate.
Supply Chain Analysis
Silica sand supply rests on domestic coastal deposits and Australian high-purity imports, while soda ash draws from Chinese synthetic production and Turkish natural reserves. Furnace operations hinge on Qatari and Australian LNG feedstock, creating exposure to heating season price spikes. Single-source vulnerability concentrates in specialty borosilicate cullet recovery systems. Distribution runs through direct procurement relationships between spirits brands and furnace operators, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's container glass market functions as a geographic-arbitrage play where Seoul-based biotech vial premiums exceed Jeolla-region fermented food jar economics by a certification-grade margin, rewarding operators who bridge this cost-regulatory gap through multi-site manufacturing networks.
For Market Incumbents: Anchor defensive positioning through backward integration into captive cullet recovery systems under K-Bottle deposit mandates, while securing green hydrogen furnace retrofit partnerships before carbon border adjustments tighten. Aluminum can substitution in beer and RTD segments threatens volume buffers; counter through direct multi-year contracts with consolidating soju producers. For New Entrants and Emerging Players: Digital direct-procurement platforms for craft spirits brands offer the lowest barrier to initial revenue, bypassing entrenched distributor relationships in the Seoul-Incheon corridor. Target oxygen-barrier jar demand from Jeolla kimchi producers migrating from plastic. Pursue MFDS fast-track certification services as a service-based entry wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale furnace operators facing skilled engineer scarcity and extended MFDS certification timelines. Five-to-ten year viability favors integrated conglomerates with renewable energy partnerships and pharmaceutical-grade certification. Watch green hydrogen pilot conversion rates as the inflection signal for emissions-compliant capacity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Neutral Furnace Retrofit | Green hydrogen pilots under Korea's national hydrogen roadmap secure first-mover positioning for MFDS and carbon border compliance. |
| Direct Procurement Relationship | Soju producers negotiating multi-year volume commitments with Seoul-Incheon manufacturers displace traditional distributor intermediaries. |
| Pharmaceutical-Grade Certification Investment | MFDS sterilization-grade borosilicate mandates create technical barriers excluding mid-scale competitors from biotech vial premiums. |
| Captive Cullet Recovery System | Integrated furnace operators gain supply advantages under K-Bottle deposit-return schemes administered by Korea's Ministry of Environment. |
| AI-Defect Detection Line Retrofit | Automated visual inspection systems respond to MFDS enhanced particulate matter testing protocols for injectable drug containers. |
Research Methodology
Direct dialogue with furnace operations managers, pharmaceutical packaging procurement leads at Seoul-based biotech developers, cosmetics brand supply chain directors, and Korea Ministry of Environment regulatory officers grounded qualitative assessments. Secondary validation drew from MFDS pharmacopeial filings, K-Bottle scheme administrative data, Korea Energy Agency hydrogen roadmap disclosures, and Korean customs glass trade statistics. Bottom-up production capacity tallies across Gwangju-Jeolla and Seoul-Incheon manufacturing complexes were triangulated against top-down end-use demand segmentation.
Segment-level value and volume trajectories across the analysis window reflect product-type splits by thermal shock specification, end-user differentiation by MFDS certification requirements, and regional clustering by logistics proximity to bottling lines. CAGRs were derived from furnace utilization rate projections, cullet recovery rate assumptions under extended producer responsibility, and premium segment share shifts toward pharmaceutical and cosmetics applications. Model inputs incorporated natural gas price volatility scenarios and green hydrogen pilot adoption curves.
The model assumes a particular technology adoption path; alternative pathways for electrified melting or green hydrogen furnace conversion would alter the outlook for carbon border adjustment exposure and premium contract capture. Forecasts embed assumptions regarding K-Bottle deposit scheme expansion rates and MFDS stability testing timeline compression. A small set of triggers—green hydrogen subsidy allocation rates, aluminum can substitution velocity in RTD segments, and biotech vial fast-track approval volumes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Ecuador Container Glass Market
Glass Packaging
Sri Lanka Container Glass Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Slovakia Container Glass Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Glass Liquor Bottles Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Packaging Jars Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Cameroon Container Glass Market
Glass Packaging
United Kingdom (UK) Glass Bottles and Containers Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Glass Packaging Market
Glass Packaging
Angola Container Glass Market