
 CBD Product Packaging Market | 2026-2036
CBD Product Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Product Packaging Market Outlook
Shortage of skilled flexographic press operators is unwinding production schedules at mid-tier converters serving the cannabis sector. WestRock Company anchors North American corrugated supply for CBD subscription boxes through integrated containerboard mills. Amcor plc leverages pharmaceutical-grade blister tooling expertise to serve European CBD oil brands with barrier-compliant formats. LuxLeaf Packaging specializes in child-certified glass jars with integrated desiccant closures, dominating California's craft extract segment.
CBD product packaging encompasses primary and secondary containment systems engineered with specific barrier properties—oxygen transmission rates below 0.1 cc/m²/day and light-blocking opacity exceeding 99%—to preserve cannabinoid stability and prevent degradation of active compounds during shelf storage. Glass bottles with dropper tops occupy the premium tincture segment where UV-amber formulations justify higher unit economics, while flexible pouches compete aggressively in gummy and edible formats where shipping cube efficiency determines distributor preference. Child-resistant design features command disproportionate margin pools as state-level testing requirements tighten certification burdens on smaller brands.
FDA labeling guidance for hemp-derived products intersects with state cannabis regulatory frameworks—California's Department of Cannabis Control mandates opaque, resealable, child-resistant primary containers—to create a dual-compliance architecture that packaging procurement teams must navigate. ASTM D3475 child-resistant testing protocols and ISO 8317 certification requirements add third-party validation costs that favor suppliers with captive laboratory capacity. Stakeholders must monitor how federal rescheduling deliberations reshape interstate shipping rules and corresponding packaging traceability requirements.
Market Dynamics
Certification bottlenecks for child-resistant closures are compressing supplier capacity and forcing brands into longer lead-time commitments with qualified converters. ASTM D3475 testing backlogs at third-party laboratories now stretch sixteen weeks in California's regulated supply chain.
Growth Catalysts
- California's Department of Cannabis Control mandates:Opaque, resealable, child-resistant primary containers for all retail extracts. This regulatory floor creates baseline demand for certified packaging formats.
- Barrier film laminates with sub-0.1 cc/m²/day oxygen transmission:Preserve cannabinoid stability in oil and edible formats. Pharmaceutical-grade specifications migrate into wellness tincture packaging.
- European CBD oil brands:Demand blister and bottle formats meeting pharmaceutical barrier standards. This end-use segment pulls converter investment toward ISO 15378 compliant cleanroom production.
Market Restraints
- Aluminum and glass input cost volatility:Amber glass bottle supply concentrates in China and Mexico, exposing converters to freight rate swings and energy cost pass-throughs.
- FDA labeling guidance ambiguity for hemp-derived products:Overlaps with state cannabis frameworks to create dual-compliance architecture. Brands delay procurement decisions pending federal clarity.
- Skilled flexographic press operator shortage:Mid-tier converters serving the cannabis sector face unwinding production schedules. Talent scarcity limits capacity expansion regardless of equipment availability.
Strategic Opportunities
- German pharmaceutical retail channel:Underpenetrated for CBD isolate products. Pharmacy-dispensed formats require distinct barrier and labeling specifications versus wellness retail.
- Integrated desiccant closure systems:Converge moisture control with child-resistant functionality. Glass jar suppliers capture premium positioning in craft extract segments.
- Subscription box distribution models:Require corrugated secondary packaging with specific cube efficiency and branding surface. E-commerce fulfillment specifications diverge from dispensary wholesale.
Industry Challenges
- ISO 8317 certification timeline compression:State-level testing requirements tighten validation burdens. Smaller brands lack resources to navigate third-party laboratory queues.
- Legacy inventory management systems:Struggle to track batch-specific packaging traceability requirements. Dispensary supply chain software lacks integration with converter ERP platforms.
- Interstate shipping rule uncertainty:Federal rescheduling deliberations create packaging procurement paralysis. Brands defer volume commitments pending clarity on traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Product Packaging Market |
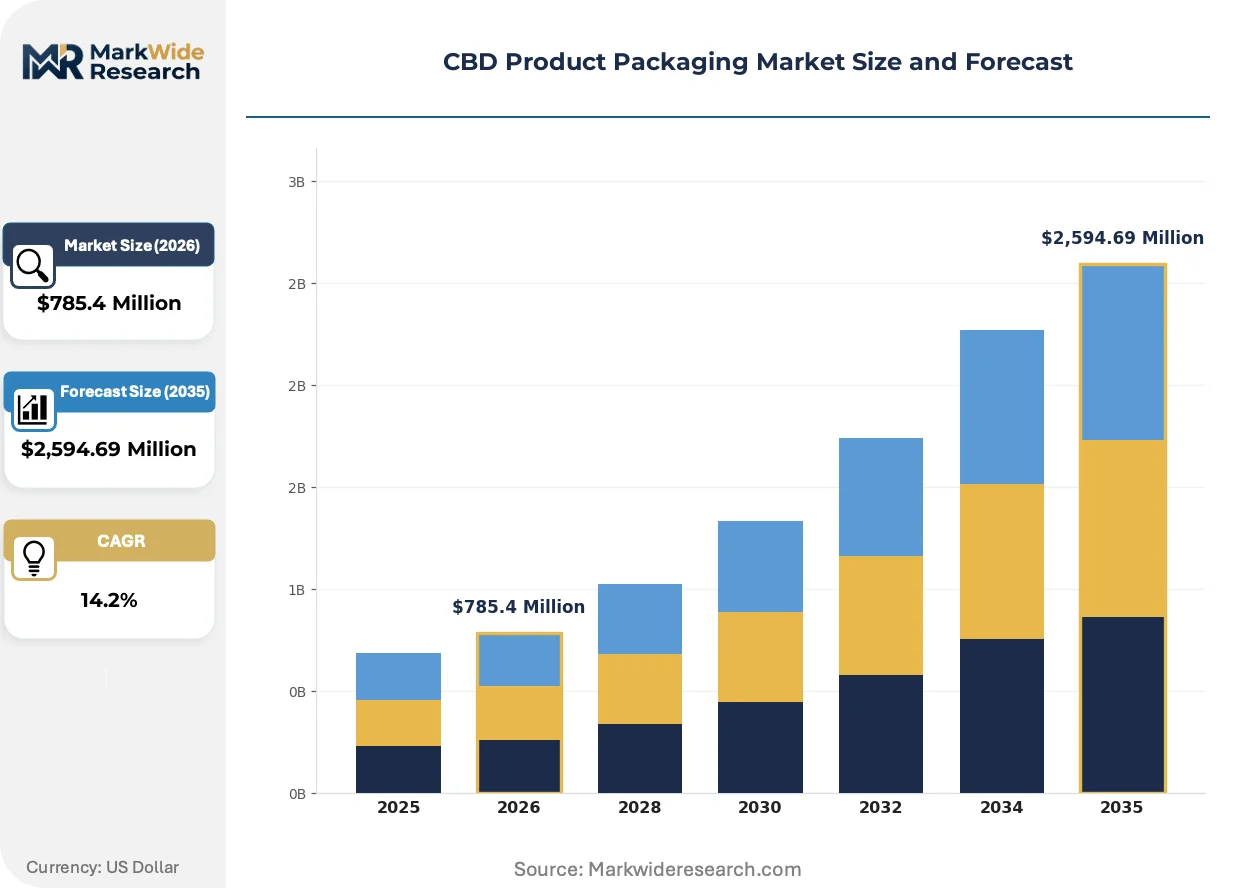
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $2,594.69 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Jars, Pouches, Tubes Material: Glass, Plastic, Metal, Paper Closure Type: Screw Caps, Snap Caps, Dropper Tops, Pump Dispensers Design Features: Child-Resistant, Tamper-Evident, Eco-Friendly, Custom Branding |
| Companies Covered | Sonoco Products Company, N2 Packaging Systems, WestRock Company, Pro CBD Packaging, LuxLeaf Packaging, Berry Global Group, Inc., HiStandards, Seed & Seal, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Product Packaging Market Strategic Shifts
Active and intelligent packaging technologies are penetrating CBD formats as shelf-life extension and authenticity verification become procurement priorities. Material science advances and regulatory precision are reshaping converter R&D allocation.
Molded fiber pulp trays with integrated humidity indicators are fragmenting traditional plastic clamshell dominance in edible and topical CBD formats. Premium wellness brands in California and Colorado adopt these formats for sustainability positioning. The technology is fragmenting supplier tiers as pulp molding equipment requires capital commitments unavailable to smaller converters.
REACH compliance for printing inks and adhesives tightens formulation specifications across European CBD packaging supply chains. ECHA substance restrictions limit certain photoinitiators in UV-cured coatings. Brands exporting to Germany and Netherlands now require full material disclosure documentation, compressing acceptable supplier pools.
Direct-to-consumer subscription models now specify secondary packaging optimized for residential mailbox dimensions and return logistics. California-based wellness brands negotiate corrugated specifications prioritizing shipping cube efficiency over retail shelf presence. This channel-specific procurement compresses traditional distributor markup structures and rewards converters with integrated structural design capabilities.
CBD Product Packaging Market Segmentation
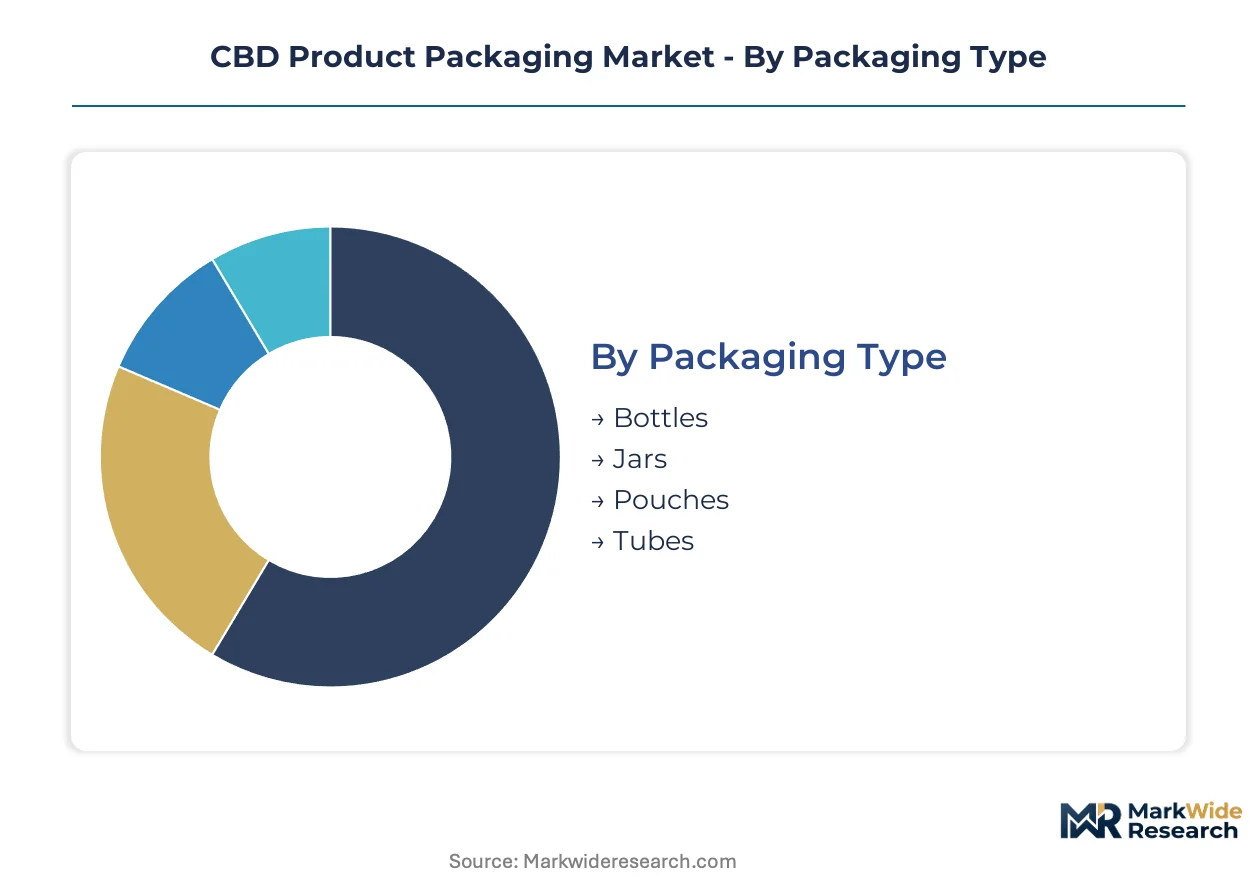
Packaging specification divergence across CBD formats creates distinct procurement clusters. Tincture brands prioritize barrier performance while edible manufacturers optimize shipping economics. Child-resistant certification requirements fragment supplier capabilities by segment.
Packaging Type:
Flexible formats are displacing rigid containers in subscription and travel-size categories, pressuring glass and plastic bottle incumbents.
- Bottles:Amber and cobalt glass constructions with 18-400 neck finishes dominate oil tincture applications. California's Department of Cannabis Control mandates opaque formulations for retail extracts, locking in UV-protective specifications.
- Jars:Wide-mouth configurations with 53-400 or 70-400 neck diameters serve concentrated extracts and topicals. Integrated desiccant closures from LuxLeaf Packaging capture premium positioning in California's craft segment.
- Pouches:Stand-up and lay-flat flexible formats with resealable zipper closures compete aggressively in gummy and edible categories. Shipping cube efficiency drives distributor preference over shelf presence.
- Tubes:Squeeze and pump configurations occupy topical and serum applications where controlled dispensing matters.
Bottles retain volume leadership; pouches hold the steepest expansion curve.
Material:
Cost tier stratification separates pharmaceutical-grade specifications from mass-market wellness positioning.
- Glass:Type III soda-lime and Type I borosilicate formulations provide oxygen transmission rates below 0.1 cc/m²/day. Amber glass supply concentrates in China and Mexico, exposing converters to freight rate volatility.
- Plastic:PET, HDPE, and PP resins compete in edibles and topicals where barrier requirements relax. REACH compliance for printing inks tightens formulation specifications across European supply chains.
- Metal:Aluminum bottles and tins occupy niche segments where lightweight durability matters.
- Paper:Molded fiber pulp trays with humidity indicators fragment traditional plastic clamshell dominance in California and Colorado wellness brands.
Plastic commands unit volume leadership; paper formats gain share fastest in sustainability-positioned segments.
Closure Type:
Certification bottlenecks concentrate margin pools in validated child-resistant mechanisms.
- Screw Caps:Continuous thread and child-resistant certified variants serve jars and bottles. ASTM D3475 testing backlogs stretch sixteen weeks in California's regulated supply chain.
- Snap Caps:Hinged and push-turn configurations compete in single-serve edible formats.
- Dropper Tops:Glass pipette assemblies with bulb squeezers occupy premium tincture segments where dosing precision justifies higher unit economics.
- Pump Dispensers:Treatment pumps and airless systems serve serum and lotion applications in European pharmaceutical retail channels.
Screw caps retain volume leadership; pump dispensers climb the fastest in pharmacy-dispensed formats.
Design Features:
Regulatory compliance requirements now outweigh aesthetic differentiation in procurement priority.
- Child-Resistant:Push-and-turn, squeeze-and-turn, and line-up mechanisms must pass ISO 8317 and ASTM D3475 protocols. Third-party validation costs favor suppliers with captive laboratory capacity.
- Tamper-Evident:Shrink bands, induction seals, and breakaway rings satisfy FDA labeling guidance for hemp-derived products.
- Eco-Friendly:Post-consumer recycled content and biodegradable substrates respond to ECHA substance restrictions and California environmental mandates.
- Custom Branding:Flexographic and digital printing capabilities enable short-run personalization for craft extract brands.
Child-resistant features retain volume leadership; eco-friendly specifications gain share fastest in European and California markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium packaging specifications in California command unit economics that undercut equivalent formats in German pharmacy channels by thirty to forty percent. This pricing-power asymmetry reflects divergent regulatory burdens and certification backlogs rather than input cost differentials. State-level mandates in the United States create captive demand pools that European wellness brands cannot replicate without pharmaceutical-grade capital commitments.
United States
California's Department of Cannabis Control mandates opaque, resealable, child-resistant primary containers for all retail extracts, locking in ASTM D3475 certification demand. The FDA's evolving labeling guidance for hemp-derived products overlaps with state frameworks to create dual-compliance procurement complexity. Los Angeles and Oakland industrial zones concentrate converter capacity serving craft extract brands with integrated desiccant closure systems.
Germany
Pharmacy-dispensed CBD isolate products pull converter investment toward ISO 15378 compliant cleanroom production in Baden-Württemberg. REACH compliance for printing inks and adhesives tightens formulation specifications under ECHA substance restrictions. Stuttgart-based packaging specialists capture premium positioning by meeting full material disclosure documentation requirements for Netherlands and Belgium export channels.
Canada
Health Canada and PMRA traceability mandates for cannabis-derived products drive batch-specific packaging serialization investments. Ontario and British Columbia cultivation clusters require child-resistant formats that satisfy both domestic retail and cross-border wellness export specifications. Toronto-area converters specialize in barrier film laminates with sub-0.1 cc/m²/day oxygen transmission rates for oil stability.
United Kingdom
Post-Brexit regulatory divergence from EU REACH frameworks creates formulation uncertainty for CBD topical and edible packaging. London and Southeast England wellness brands prioritize molded fiber pulp trays with humidity indicators for sustainability positioning. Midlands-based converters face compressed lead times as brands defer procurement decisions pending clarity on retained EU substance restrictions.
Australia
TGA scheduling changes for low-dose CBD products expand pharmacy channel access and corresponding barrier specification requirements. New South Wales and Victoria host the dominant domestic cultivation and processing infrastructure. Sydney-based packaging procurement teams negotiate corrugated secondary specifications optimized for direct-to-consumer subscription fulfillment rather than retail shelf presence.
CBD Product Packaging Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the CBD packaging value chain. The supplier base fragments across three tiers: multinational converters with captive laboratory certification capacity, mid-tier specialists with state-level regulatory expertise, and regional fabricators competing on minimum order quantities and lead-time flexibility. Two dominant competitive moves define current positioning: backward integration into containerboard and glass primary production to secure input cost control, and geographic expansion through acquisition of state-certified converters to capture regulatory moats.
Within the multinational tier, Amcor plc and WestRock Company exemplify divergent strategic positions. Amcor leverages pharmaceutical-grade blister tooling expertise developed across European healthcare channels. WestRock anchors North American corrugated supply for subscription box distribution through integrated containerboard mill networks. Among mid-tier specialists, LuxLeaf Packaging occupies a position concentrated in California's craft extract segment with child-certified glass jar formats.
| Leading Market Players |
|---|
| Sonoco Products Company |
| N2 Packaging Systems |
| WestRock Company |
| Pro CBD Packaging |
| LuxLeaf Packaging |
| Berry Global Group, Inc. |
| HiStandards |
| Seed & Seal |
| Amcor plc |
| Others |
Value Chain & Pricing Dynamics
ASTM D3475 certification requirements gate both supplier qualification and price differentiation simultaneously, compressing converter margins as brands absorb sixteen-week laboratory backlogs through premium placement fees. Child-resistant validation costs concentrate pricing power with captive-laboratory multinationals while mid-tier specialists compete on minimum-order flexibility.
Pricing Analysis
Configured-to-order pricing for custom barrier specifications commands spreads of forty to sixty percent above standard catalog formats. Pharmaceutical-grade certification tiers separate premium positioning from mass-market wellness tiers, with ISO 15378 cleanroom production justifying the upper price band. Cost compression in standard-grade pouches intensifies as flexible-format converters add capacity for gummy and edible segments. Craft extract brands show least price sensitivity; subscription-box distributors prioritize shipping-cube efficiency over unit cost.
Supply Chain Analysis
China and Mexico anchor amber glass bottle supply for tincture applications, with Type III soda-lime formulations dominating volume. Converter operations draw from aluminum coil, barrier film laminates, and pharmaceutical-grade resin feedstocks. Single-source vulnerability concentrates in third-party ASTM testing capacity, where California laboratory queues extend procurement cycles. Distribution runs through dispensary wholesale channels in regulated states and direct-to-consumer fulfillment for wellness subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated child-resistant closure engineering represents the critical capability gap separating qualified suppliers from commodity competitors. Scarce flexographic press talent compounds production bottlenecks regardless of capital availability.
For Market Incumbents: Compound laboratory certification capacity to capture ASTM D3475 backlog premiums before mid-tier converters resolve talent scarcity. Backward integration into amber glass primary production secures input cost control against China-Mexico freight volatility. Prioritize integrated desiccant closure R&D to defend margin position against pulp-molding sustainability entrants. For New Entrants and Emerging Players: Differentiate on pharmacy-channel barrier specifications in Germany's underpenetrated CBD isolate segment. Target ISO 15378 cleanroom production gaps that multinational converters have deprioritized for wellness volumes. Pursue white-label partnerships with Stuttgart-based pharmaceutical packaging specialists lacking CBD regulatory familiarity. For Investors and Strategic Acquirers: Federal rescheduling deliberations reshape the acquisition landscape by compressing valuation windows for state-certified converters ahead of interstate shipping rule clarity. Long-term viability favors targets with captive laboratory capacity and multi-state regulatory footprints. Watch DEA scheduling determinations as the definitive inflection signal for packaging traceability mandate expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Laboratory Expansion | Captive ASTM D3475 capacity captures sixteen-week backlog premiums in California's regulated supply chain. |
| Barrier Film Laminate Investment | Sub-0.1 cc/m²/day oxygen transmission specifications preserve cannabinoid stability for oil tincture brands. |
| Integrated Desiccant Closure Development | Converged moisture control and child-resistant functionality commands premium positioning in craft extract segments. |
| Pulp Molding Equipment Acquisition | Molded fiber trays with humidity indicators fragment plastic clamshell dominance in California wellness markets. |
| Pharmaceutical Cleanroom Certification | ISO 15378 compliance opens German pharmacy channels requiring distinct barrier and labeling specifications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and converter capacity disclosures. Interviews with packaging procurement managers at California dispensary brands, flexographic press operators at mid-tier converters, pharmaceutical regulatory consultants, and corrugated supply planners informed demand-side validation. Secondary sources include FDA labeling guidance documents, California Department of Cannabis Control mandates, ASTM certification records, and ECHA REACH substance restriction updates. Bottom-up segment sizing triangulates against top-down value chain analysis.
Segmentation dimensions modeled span packaging type, material substrate, closure mechanism, design feature compliance tier, and regional regulatory cluster across the analysis window. CAGRs derive from regression against historical certification adoption curves and state-level dispensary expansion trajectories. Forecast inputs incorporate flexographic labor supply elasticity and amber glass freight rate pass-through assumptions.
Decision-makers should treat outputs as directional under stable federal scheduling assumptions; material deviation would warrant model refresh. Specific risks include DEA rescheduling acceleration, ECHA substance restriction expansion, and China energy cost volatility affecting glass primary supply. Recalibration cycles align with material shifts in regulatory clarity and laboratory certification capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
India Packaging Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
United Kingdom Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Global E-Commerce Packaging Market