
 Patisserie Packaging Market | 2026-2036
Patisserie Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Patisserie Packaging Market Analytics
European molded fiber producers is repositioning capacity toward grease-resistant patisserie trays as artisan bakeries demand plastic alternatives. Amcor Plc leverages multilayer barrier films to extend shelf appeal for premium éclair and macaron lines. Mondi Plc anchors its position through kraft paper innovations that sustain moisture control in cold-chain distribution. Huhtamaki Oyj specializes in molded pulp technologies that dominate Nordic bakery supply chains.
Patisserie packaging encompasses rigid and flexible containment systems engineered from paperboard, plastic films, biodegradable polymers, or coated cellulose, typically incorporating grease barriers, vapor transmission controls, and optical windows to preserve organoleptic quality and visual presentation of delicate baked goods. Boxes and trays command the largest material volume as bakery shops prioritize structural integrity for layered cakes and fragile pastries. Biodegradable materials represent the fastest-expanding category as regulatory deadlines in the EU and select Asian markets force reformulation away conventional plastic laminates. Windowed design features capture premium margin pools where consumer purchase decisions hinge on product visibility.
FDA food contact substance notifications govern barrier coatings in the United States, while EFSA and EU Packaging and Packaging Waste Regulation set recyclability mandates that reshape material selection across European supply chains. Japan's METI circular economy guidelines and Container Packaging Recycling Law impose extended producer responsibility that compels domestic and imported packaging to meet strict sorting compatibility standards. Stakeholders must monitor how diverging biodegradability certification schemes between EU EN 13432 and ASTM D6400 in North America fragment compliance requirements and influence cross-border sourcing strategies.
Market Dynamics
EU Single-Use Plastics Directive revisions are forcing material reformulation across bakery supply chains, while cellulose barrier coating breakthroughs simultaneously unlock plastic-free alternatives for grease-sensitive applications.
Growth Catalysts
- Biodegradable polymer R&D:PLA and PHA formulations with enhanced heat resistance are capturing shelf space previously reserved for petroleum-based films.
- France's artisan bakery expansion:Premium patisserie chains in Paris and Lyon are mandating compostable packaging for all takeaway formats.
- Cellulose nanofiber coatings:Laboratory-scale barrier improvements are transitioning to pilot production lines at Nordic pulp processors.
Market Restraints
- Raw material concentration:Bleached kraft pulp supply clusters in Scandinavian mills create vulnerability to Nordic energy price shocks.
- Barrier performance gaps:Current molded fiber technologies fail moisture-vapor transmission standards for multi-day éclair distribution.
- Recyclability sorting friction:EU Packaging and Packaging Waste Regulation mandates are misaligned with municipal composting infrastructure capacity in Southern Europe.
Strategic Opportunities
- Japan's depachika channel:Tokyo basement food halls present underexploited demand for single-serve patisserie formats with premium presentation.
- Digital printing integration:Combination of flexographic decoration and QR traceability enables batch-level customization for boutique bakeries.
- Extended producer responsibility incentives:METI circular economy guidelines reward packaging designs that simplify post-consumer material recovery.
Industry Challenges
- Coating chemist scarcity:Formulation expertise for water-based grease barriers remains concentrated at a handful of European research institutes.
- Legacy equipment retrofit costs:Converting thermoforming lines to handle fiber-based feedstocks demands capital outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patisserie Packaging Market |
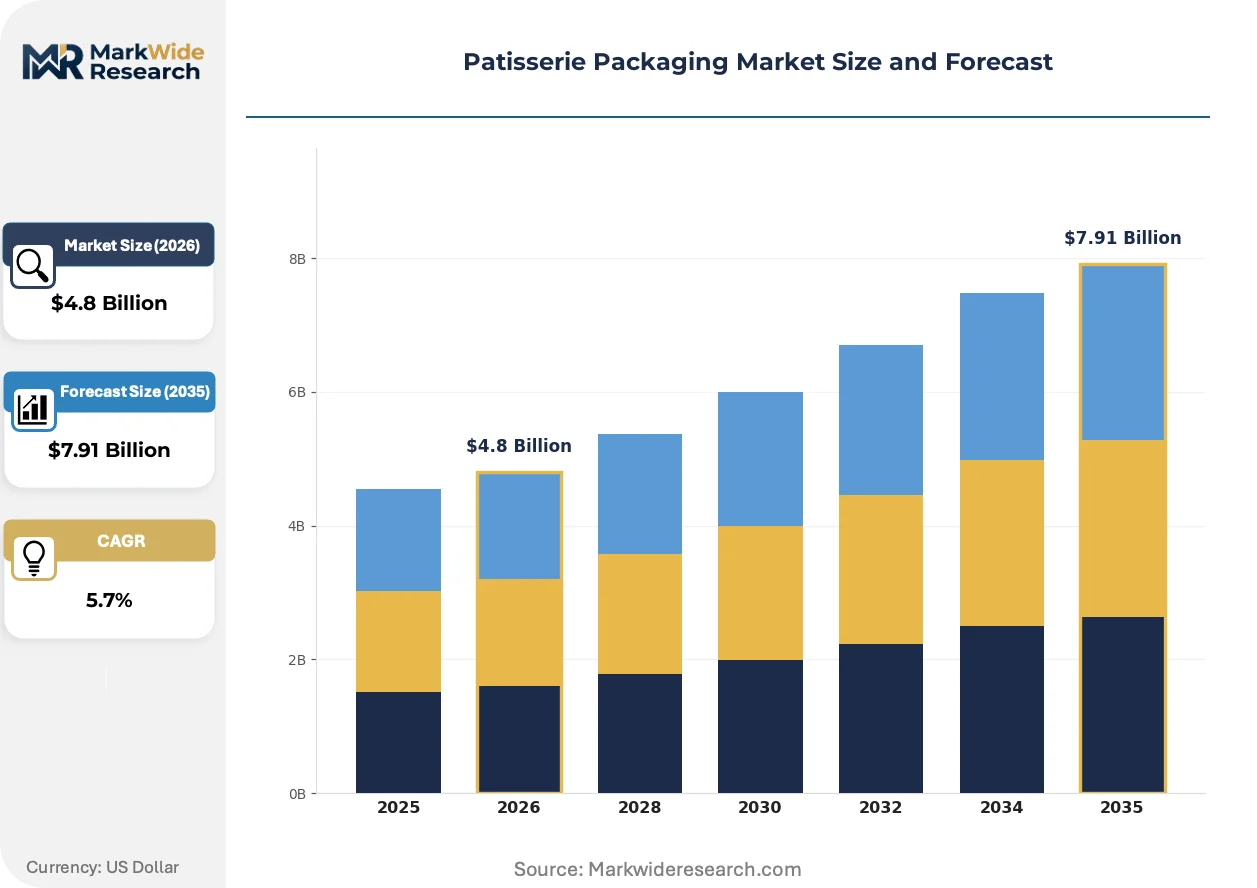
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Boxes, Trays, Wrappers, Bags Material: Paper, Plastic, Cardboard, Biodegradable End User: Bakery Shops, Supermarkets, Online Retailers, Food Service Design Feature: Windowed, Custom Printed, Eco-Friendly, Insulated |
| Companies Covered | Amcor Plc, Mondi Plc, Huhtamaki Oyj, Smurfit Kappa, Berry Global Inc., Sealed Air, WestRock Company, Ball Corporation, Stora Enso, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patisserie Packaging Market Evolving Landscape
Material science breakthroughs and regulatory deadlines are compressing development cycles for barrier-coated fiber alternatives, while digital decoration technologies are collapsing minimum order quantities for customized bakery packaging.
Water-based barrier coatings derived from alginate and chitosan are overtaking conventional polyethylene laminates in cold-chain pastry applications. Nordic bakery cooperatives are piloting these formulations for cinnamon roll and cardamom bun distribution. The shift is overtaking established supply relationships between European converters and petrochemical film suppliers.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy greaseproofing chemistries from EU-sourced packaging. Bakery chains operating across Germany and the Netherlands are accelerating qualification of fluorine-free alternatives. Premium macaron and petit four lines face the steepest reformulation timelines due to stringent oil-resistance requirements.
Direct-to-bakery digital procurement platforms are fragmenting volume concentration previously held by distributor intermediaries. Independent patisseries in Melbourne and São Paulo now specify custom window placements and seasonal motifs through browser-based configurators. This disintermediation is most pronounced in urban markets where same-day delivery logistics have matured.
Patisserie Packaging Market Segmentation
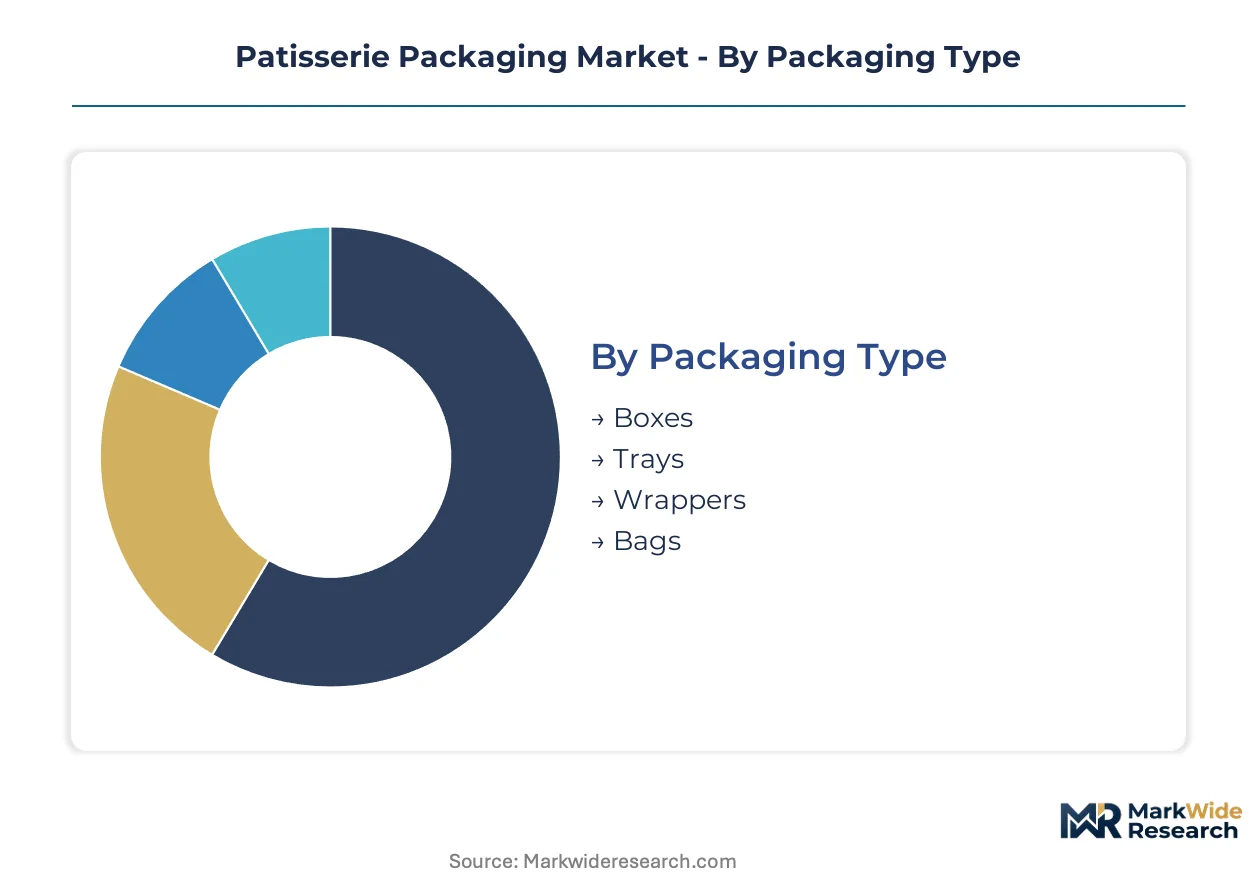
Patisserie packaging procurement decisions hinge on balancing structural protection for fragile products against regulatory mandates for material recyclability. Buyers evaluate barrier performance, visual presentation, and compliance costs across multiple segment dimensions simultaneously.
Packaging Type:
Structural requirements for specific pastry formats drive format selection more than unit cost considerations.
- Boxes:Rigid paperboard constructions with integrated grease barriers dominate layered cake and fragile pastry distribution. German Rhineland bakery clusters specify these for multi-day retail shelf life.
- Trays:Molded fiber and pressed pulp formats engineered for single-serve éclairs and tarts are displacing plastic alternatives in Nordic markets. EU Single-Use Plastics Directive deadlines accelerate this substitution.
- Wrappers:Flexible cellulose films with vapor transmission control serve individual croissants and danishes in grab-and-go channels.
- Bags:Gusseted kraft constructions with pinch-bottom closures handle bulk pastry assortments for catering and institutional food service.
Volume sits with Boxes; growth tilts toward Trays.
Material:
Regulatory deadlines in major markets are collapsing the traditional cost-performance tradeoff that favored petroleum-based substrates.
- Paper:Bleached and unbleached kraft grades with proprietary barrier coatings command premium positioning in Japanese depachika food halls. METI circular economy guidelines reward these designs with simplified sorting compliance.
- Plastic:Multilayer barrier films with optical clarity sustain macaron and petit four presentation in legacy supply chains. EFSA scrutiny of food contact substances intensifies qualification burdens for these formulations.
- Cardboard:Corrugated and solid fiber boards with moisture-resistant liners anchor e-commerce pastry fulfillment where stacking strength matters.
- Biodegradable:PLA, PHA, and coated cellulose alternatives are climbing the fastest as France's artisan bakery chains mandate compostable takeaway formats nationwide.
Plastic still holds volume share; biodegradable materials are gaining share fastest.
End User:
Channel-specific handling protocols and branding requirements fragment procurement specifications.
- Bakery Shops:Independent and chain patisseries prioritize windowed presentation and custom decoration to differentiate counter displays. Paris and Lyon operators now require compostable certification for all procurement tenders.
- Supermarkets:Central bakery operations demand cold-chain compatible formats with extended moisture control for distribution to multiple retail points.
- Online Retailers:Direct-to-consumer pastry subscription services specify insulated and crush-resistant designs that survive last-mile logistics.
- Food Service:Hotels, cafés, and catering operations prioritize cost-efficient bulk formats with minimal decoration for behind-the-scenes preparation.
Bakery shops generate the highest margin per unit; online retailers represent the steepest expansion trajectory.
Design Feature:
Consumer-facing differentiation and regulatory compliance compete as primary design drivers.
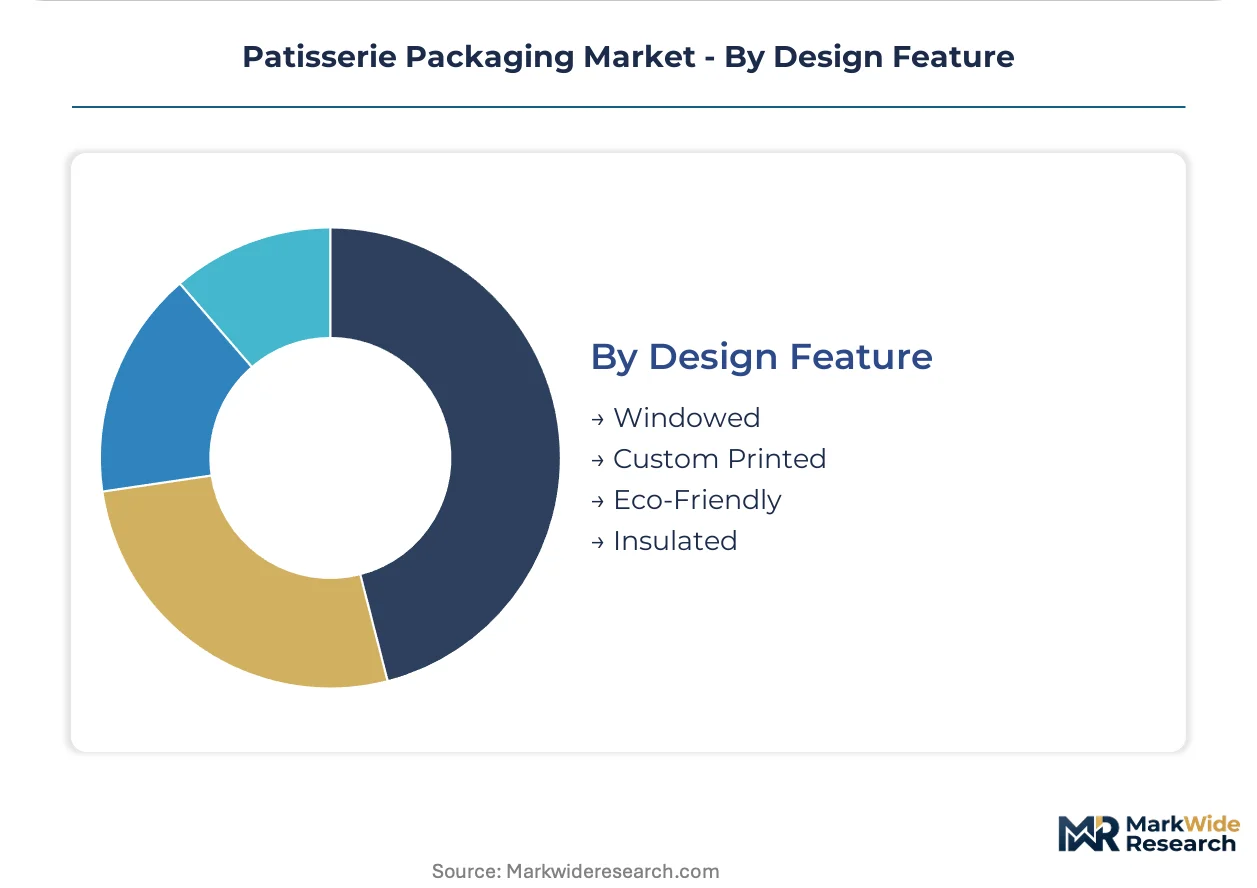
- Windowed:Die-cut apertures with anti-fog films or open cellulose windows enable visual product assessment without package opening. Premium macaron lines in Tokyo depachika halls mandate this feature.
- Custom Printed:Digital flexographic decoration with batch-level QR traceability supports boutique bakery brand building. Melbourne and São Paulo independents now specify seasonal motifs through browser-based configurators.
- Eco-Friendly:Unbleached substrates, soy-based inks, and minimal glue constructions align with EU Packaging and Packaging Waste Regulation recyclability mandates.
- Insulated:Multi-wall constructions with trapped air layers or reflective barriers protect temperature-sensitive cream fillings during summer distribution.
Windowed designs command premium pricing; eco-friendly specifications are expanding most quickly as compliance deadlines tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bleached kraft pulp from Scandinavian mills anchors material supply for patisserie packaging across Northern Europe, while artisan bakery demand clusters in Western European capitals and Japanese metropolitan food halls drive format innovation.
Germany
Rhineland bakery cooperatives procure rigid paperboard boxes with integrated grease barriers for multi-day retail shelf life. EFSA food contact substance regulations and EU Packaging and Packaging Waste Regulation recyclability mandates reshape procurement specifications for layered cake distribution. Düsseldorf and Cologne anchor converter capacity serving artisan chains across North Rhine-Westphalia.
France
Paris and Lyon patisserie chains now mandate compostable certification for all takeaway packaging tenders, accelerating biodegradable material adoption. ANSM and CNIL oversight of consumer-facing claims intersects with EU Single-Use Plastics Directive enforcement timelines. The Île-de-France cluster dominates premium macaron and éclair packaging specification setting for export markets.
Japan
Tokyo depachika basement food halls generate concentrated demand for single-serve formats with premium windowed presentation. METI circular economy guidelines and Container Packaging Recycling Law extended producer responsibility rules reward designs with simplified sorting compatibility. Kanto region converters specialize in kraft paper innovations for moisture control in cold-chain distribution.
United States
Artisan bakery expansion in Brooklyn and Los Angeles drives specification for custom-printed, digitally configured packaging with batch-level traceability. FDA food contact substance notifications govern barrier coating approvals, while state-level composting infrastructure gaps create compliance friction for biodegradable formats. Pacific Northwest molded fiber producers pilot cellulose nanofiber coatings for grease-resistant applications.
United Kingdom
London independent patisseries leverage browser-based configurators for seasonal motif customization, fragmenting volume concentration from distributor intermediaries. EFSA-aligned post-Brexit food contact regulations and evolving Extended Producer Responsibility frameworks reshape material selection. Midlands converters develop corrugated solutions for e-commerce pastry subscription services requiring crush-resistant last-mile performance.
Patisserie Packaging Market Competitive Landscape
Global majors compete with regional champions across barrier technology and sustainability certification dimensions, producing a tiered structure where scale-driven multinationals anchor premium film supply while specialized fiber converters capture plastic substitution mandates. Three archetypes dominate: integrated pulp-to-package operators controlling Nordic supply chains, diversified packaging conglomerates leveraging cross-category R&D spillovers, and boutique converters specializing in digital-print customization for independent bakeries. Competitive moves concentrate on capacity repositioning toward grease-resistant fiber formats and strategic partnerships with artisan bakery chains seeking compostable supply security.
Within the integrated pulp-to-package tier, Stora Enso and Smurfit Kappa exemplify Nordic-based operators with captive kraft pulp access. Among diversified multinationals, Mondi Plc and WestRock Company occupy positions spanning paperboard and corrugated formats. Amcor Plc represents the barrier film specialist archetype despite accelerating fiber-based portfolio diversification. These named entities anchor industry-level commentary without implying specific strategic actions or market share claims beyond their visible positioning in raw material and format supply.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Plc |
| Huhtamaki Oyj |
| Smurfit Kappa |
| Berry Global Inc. |
| Sealed Air |
| WestRock Company |
| Ball Corporation |
| Stora Enso |
| Others |
Value Network & Pricing Analysis
France's nationwide compostable packaging mandates for artisan bakery chains are compressing procurement timelines and forcing converters to absorb certification costs that reshape contract pricing structures across European supply chains.
Pricing Analysis
After-sales technical support and barrier performance warranties are increasingly unbundled from base material contracts, with Nordic pulp suppliers charging premiums for grease-resistance guarantees. Pricing stratifies across premium, standard, and economy tiers based on certification tier (EU EN 13432 compostable grade) and customization depth. Cost compression in molded fiber segments is intensifying because legacy thermoforming equipment retrofits drain converter liquidity. Mid-tier bakery cooperatives exhibit highest price sensitivity; Tokyo depachika premium channels show least.
Supply Chain Analysis
Single-source vulnerability sits with bleached kraft pulp supply from Scandinavian mills, where Nordic energy price shocks transmit directly to material costs. Production draws from Sweden, Finland, and Germany for pulp refining and barrier coating formulation. Raw material dependencies center on cellulose nanofiber inputs, alginate derivatives, and chitosan feedstocks. Tariff exposure on imported biopolymer additives from Southeast Asian processors threatens margin stability. Distribution runs through regional converter hubs serving Rhineland bakery clusters and Paris-Lyon procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU regulatory deadlines on single-use plastics are accelerating consolidation as undercapitalized converters face equipment retrofit burdens that larger players can absorb through captive financing.
For Market Incumbents: Deepen backward integration into cellulose nanofiber coating production to secure barrier technology supply against coating chemist scarcity at European research institutes. Expand pilot-line capacity in Finland and Sweden to capture Nordic bakery cooperative demand before specialty fiber competitors qualify alternative grease-resistant formulations.
For New Entrants and Emerging Players: Begin with digital-print customization services for independent patisseries in Melbourne and São Paulo, where browser-based configurators have fragmented distributor concentration. Target single-serve tray formats for Japan's depachika channel, where premium presentation requirements and METI sorting compatibility rules create qualification barriers that favor agile specialists.
For Investors and Strategic Acquirers: The window for entry favors integrated pulp-to-package operators with captive Nordic kraft supply and existing barrier R&D partnerships. Long-term viability hinges on exposure to biodegradable material conversion mandates rather than legacy plastic film positions. Watch for cellulose coating qualification announcements from major French bakery chains as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Secures fluorine-free greaseproofing chemistry ahead of REACH enforcement deadlines. |
| Pilot Production Scale-Up | Transitions cellulose nanofiber formulations from laboratory to commercial throughput. |
| Digital Print Platform Integration | Enables batch-level QR traceability for boutique bakery brand differentiation. |
| Compostable Certification Investment | Unlocks tender eligibility for France's artisan bakery chain procurement mandates. |
| Regional Converter Acquisition | Captures established relationships with Rhineland bakery cooperatives and Tokyo depachika suppliers. |
Research Methodology
Multi-period observation of barrier coating patent filings, EU regulatory comment periods, and artisan bakery chain procurement tenders anchored the trend analysis, supplemented by interviews with converter operations managers, bakery chain procurement directors, pulp mill technical sales leads, and food packaging R&D directors. Secondary validation drew from EFSA food contact substance notifications, EU Packaging and Packaging Waste Regulation implementation guidance, METI circular economy policy documents, and trade customs data for kraft pulp and biopolymer flows. Bottom-up volume estimates from individual converter capacity announcements were triangulated against top-down material consumption projections.
Input-output matrices mapped packaging format demand against raw material supply elasticities across the projection horizon, with segmentation dimensions spanning packaging type, material substrate, end-user channel, and design feature category. CAGRs were derived from regression analysis of historical procurement patterns and regulatory deadline impacts. Industry-specific forecast inputs included EU Single-Use Plastics Directive phase-out timelines and cellulose barrier coating pilot-line commissioning schedules.
Underlying measurement precision varies by segment; biodegradable material adoption rates carry tighter precision than legacy plastic film projections due to regulatory certainty. Forecasts reflect documented assumptions about enforcement consistency and infrastructure buildout pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Transport Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Package Drop Box Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Global Peel and Reseal Packaging Market