
 Cohesive Packaging Solutions Market | 2026-2036
Cohesive Packaging Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Cohesive Packaging Solutions Market Outlook
ASTM D3330 peel adhesion testing is unwinding competitive access for suppliers lacking certified laboratory infrastructure. Sealed Air Corporation leverages its global manufacturing footprint to sustain multi-regional supply contracts. 3M Company anchors its position through captive resin synthesis and proprietary hot-melt adhesive chemistry. Mondi Group Plc differentiates via integrated paper-based cohesive substrates that bypass petroleum-derived feedstocks entirely.
Cohesive packaging solutions employ pressure-sensitive adhesives, cohesive coatings, and self-sealing films that bond to themselves without residue transfer, typically formulated from synthetic rubber elastomers, acrylic polymers, or water-based dispersions applied at 15-40 grams per square meter coat weights. The primary commercial purpose centers on temporary closure, unitization, and surface protection across automated and manual packing lines where resealability and clean removal preserve product integrity. Adhesive tapes occupy the dominant value position due to universal deployment across carton sealing and pallet stabilization workflows. Protective packaging represents the fastest-expanding application segment as e-commerce fulfillment networks scale fragile-goods throughput. Plastic substrates retain volume leadership though paper-based alternatives are capturing share in regulatory-sensitive European markets.
EPA guidelines on volatile organic compound emissions constrain solvent-based adhesive formulations in US manufacturing facilities. REACH registration requirements and the EU Green Deal circular economy mandates are accelerating waterborne and bio-based cohesive material development across European supply chains. FDA food contact substance notifications govern direct-adhesive exposure limits in US food packaging applications. Stakeholders must monitor evolving extended producer responsibility frameworks that will recalibrate material recovery obligations and adhesive recyclability specifications.
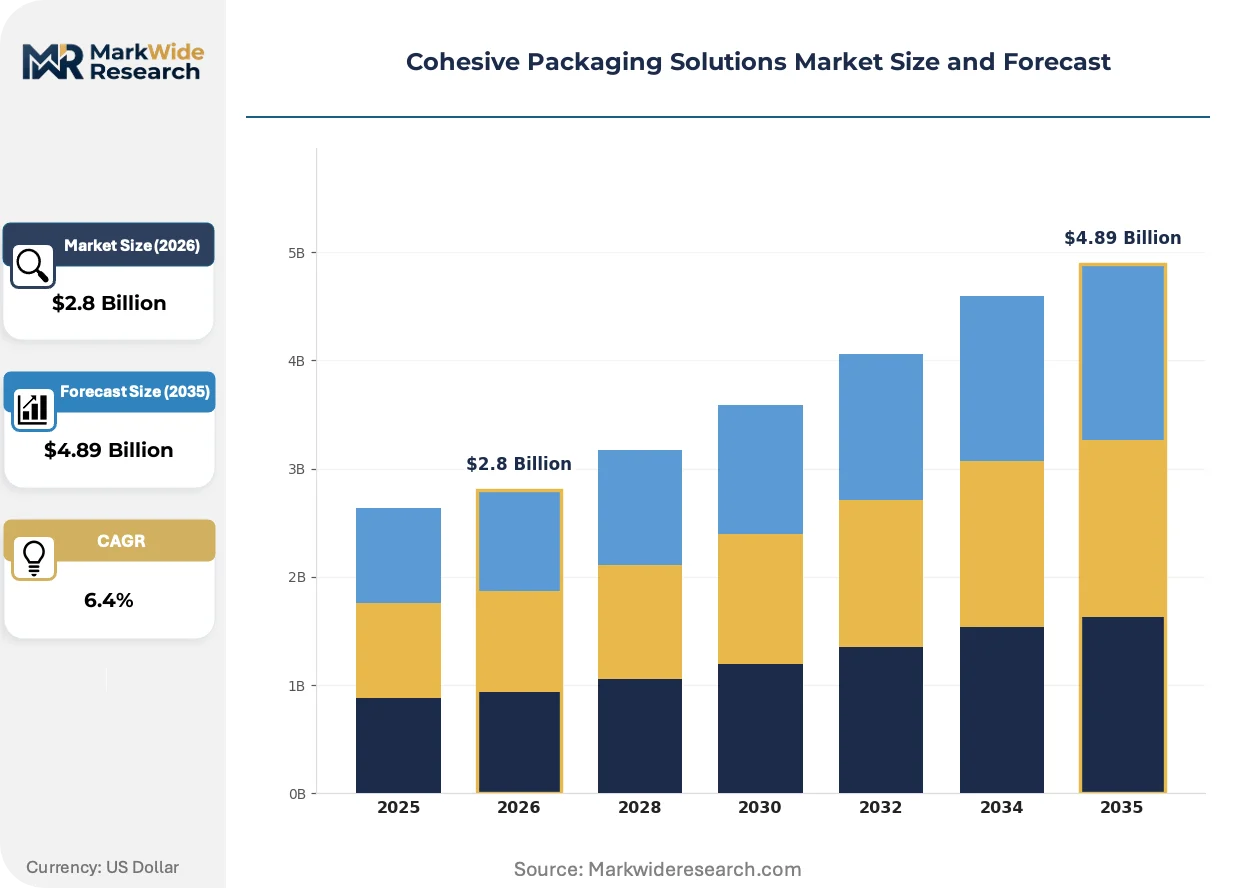
Market Dynamics
REACH registration requirements and the EU Green Deal circular economy mandates are accelerating waterborne and bio-based cohesive material development across European supply chains, forcing reformulation of legacy adhesive portfolios.
Growth Catalysts
- E-commerce fulfillment networks:Fragile-goods throughput expansion drives protective packaging demand across automated sortation hubs in Germany and the Netherlands.
- REACH compliance tightening:Material specification pressures in Europe favor suppliers with certified laboratory infrastructure for ASTM D3330 peel adhesion testing.
- Automotive component suppliers:Precision protective packaging systems concentrate demand in German manufacturing clusters for just-in-time component delivery.
Market Restraints
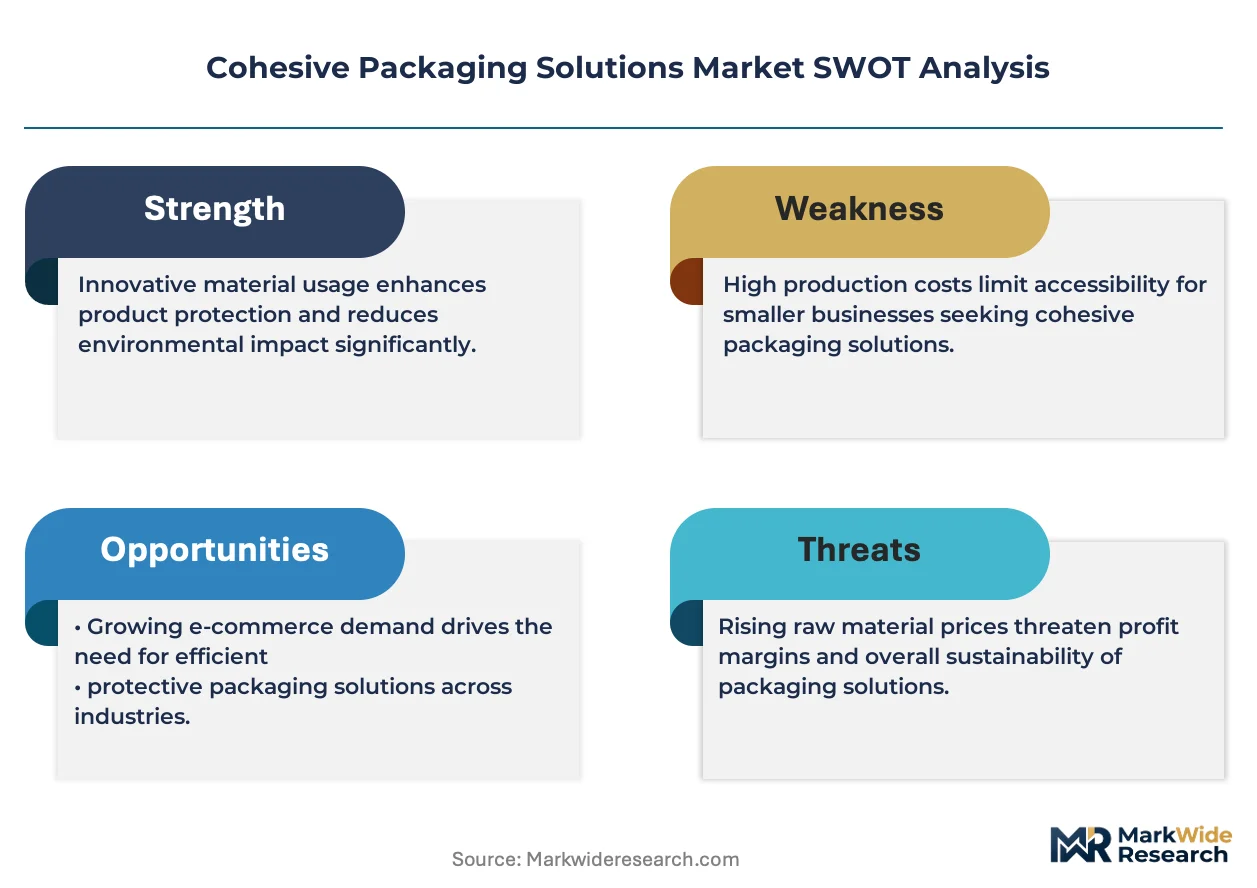
- Petroleum-derived feedstock volatility:Synthetic rubber elastomers and acrylic polymers face input cost swings tied to crude oil price movements.
- Solvent-based formulation constraints:EPA volatile organic compound emission guidelines limit manufacturing flexibility at US production facilities.
- Recyclability specification gaps:Extended producer responsibility frameworks lack harmonized adhesive recovery protocols across EU member states.
Strategic Opportunities
- Integrated paper-based substrates:Water-based dispersions and bio-based coatings bypass petroleum dependency entirely, aligning with EU Green Deal procurement criteria.
- Shelf-ready display formats:Food and beverage manufacturers expand cohesive adoption for retail-ready secondary packaging in automated stocking environments.
- Resin synthesis captive supply:Proprietary hot-melt adhesive chemistry investments secure formulation control against raw material supply interruptions.
Industry Challenges
- Certification timeline compression:FDA food contact substance notification pathways delay product launch schedules for direct-adhesive food packaging applications.
- Legacy equipment retrofit costs:Waterborne adhesive transitions require capital-intensive line modifications at coat weights of 15-40 grams per square meter.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cohesive Packaging Solutions Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesive Tapes, Labels, Stretch Film, Shrink Film End User: Food & Beverage, Pharmaceuticals, Cosmetics, Consumer Electronics Material: Plastic, Paper, Metal, Glass Application: Retail Packaging, Industrial Packaging, Protective Packaging, Specialty Packaging |
| Companies Covered | Pregis LLC, Sealed Air Corporation, 3M Company, Mondi Group Plc, Smurfit Kappa Group, Polypak Packaging, Intertape Polymer Group, DS Smith Plc, LAMATEK, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cohesive Packaging Solutions Market Strategic Shifts
Material science advances and regulatory chemistry mandates are restructuring competitive advantage around feedstock independence and clean-label adhesive portfolios.
Waterborne acrylic dispersions formulated at reduced coat weights are decomposing the volume dominance of solvent-based synthetic rubber systems. Food packaging converters in France and Italy accelerate qualification timelines for direct-contact applications. The shift compresses margins for suppliers lacking in-house dispersion synthesis capabilities.
REACH registration requirements and the EU Green Deal circular economy mandates are accelerating waterborne and bio-based cohesive material development across European supply chains. Formulators must document substance volume thresholds and hazard classifications for continued market access. German automotive suppliers now specify recyclable adhesive systems in component packaging tenders.
Automated procurement platforms for packaging materials are consolidating supplier relationships around certified performance data. Third-party logistics providers in the Netherlands and Belgium aggregate demand through digital tendering systems. Small and mid-sized converters face margin compression as buyer concentration intensifies specification compliance burdens.
Cohesive Packaging Solutions Market Segmentation
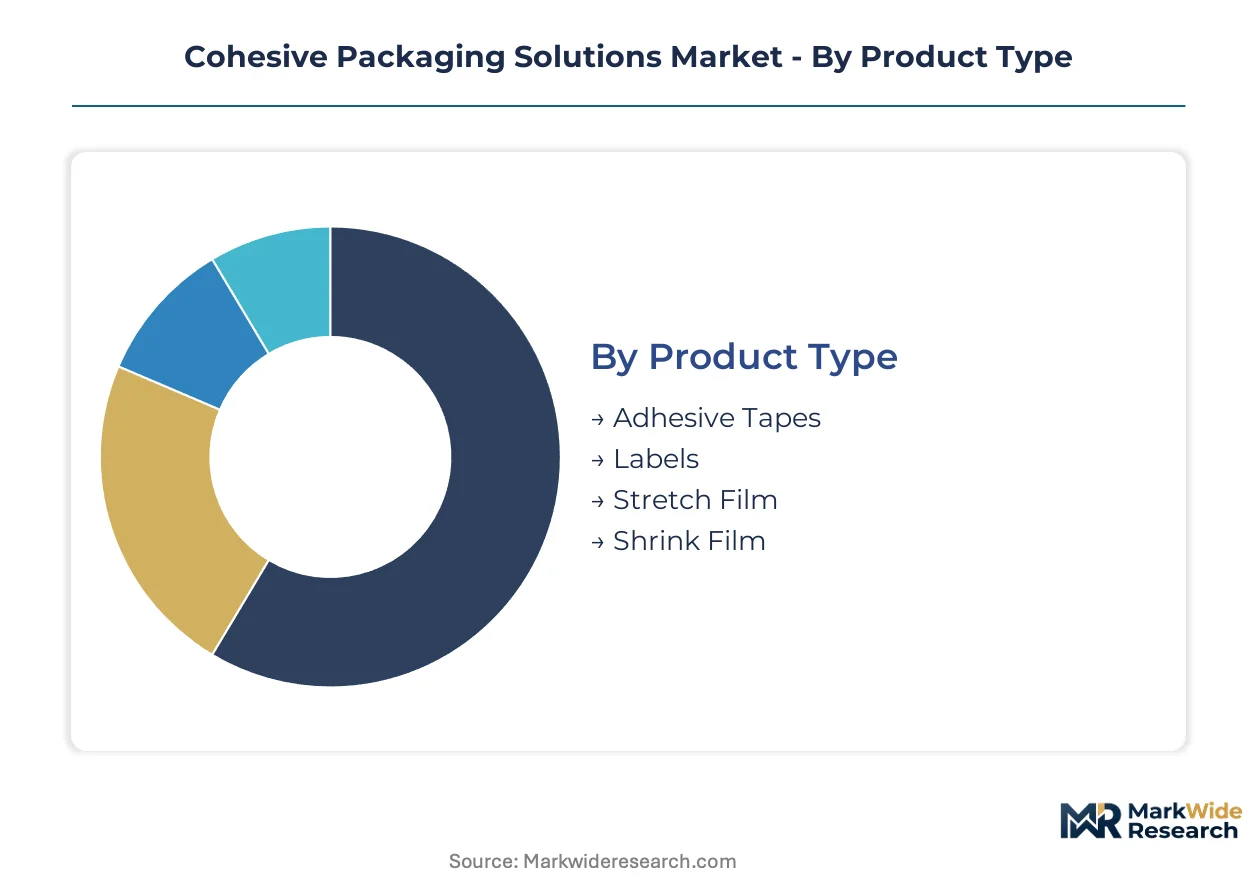
Cohesive packaging solutions fragment across four critical dimensions where material chemistry, end-use performance requirements, and regulatory exposure create divergent margin profiles. Suppliers must align formulation capabilities against specific segment demands rather than pursuing undifferentiated coverage.
Product Type:
Stretch film and shrink film face the most acute substitution pressure from paper-based banding and fiber-based unitization systems, particularly in European markets where REACH compliance tightens polymer specifications.
- Adhesive Tapes:Pressure-sensitive synthetic rubber or acrylic formulations applied to polypropylene or PVC backings dominate carton sealing and pallet stabilization workflows. Food and beverage manufacturers in Germany specify hot-melt adhesive chemistry for automated case sealing lines where resealability preserves product integrity.
- Stretch Film:Linear low-density polyethylene cast films with cling additives enable manual and machine-wrap unitization. E-commerce fulfillment networks in the Netherlands drive demand for pre-stretched variants that reduce material consumption per pallet load.
- Labels:Cohesive-coated paper or film substrates bond to themselves without residue transfer, serving temporary closure applications in pharmaceutical serialization.
- Shrink Film:Polyolefin or PVC formulations require heat activation for tight-fitting product bundling, common in multi-pack consumer goods retail configurations.
Adhesive tapes retain volume leadership; stretch film holds the steepest expansion curve.
End User:
Cost tier segmentation separates premium validated systems for pharmaceuticals from commodity-grade formats serving mass-market consumer goods.
- Food & Beverage:FDA food contact substance notifications govern direct-adhesive exposure limits, forcing reformulation of legacy hot-melt portfolios toward waterborne alternatives. Automated stocking environments in France and Italy accelerate shelf-ready display adoption.
- Pharmaceuticals:Serialization mandates and tamper-evidence requirements specify cohesive labels with clean removal properties for secondary packaging. German contract packaging organizations demand documented ASTM D3330 peel adhesion certification.
- Cosmetics:Premium unboxing experiences drive specification of clear film overwraps with optical clarity and silent unwind characteristics.
- Consumer Electronics:Anti-static cohesive films protect sensitive components during automated assembly line transit in precision manufacturing clusters.
Food and beverage commands the largest revenue pool; pharmaceuticals posts the most rapid qualification timeline compression.
Material:
Supply concentration in petroleum-derived feedstocks creates margin volatility that favors integrated producers with captive resin synthesis capabilities.
- Plastic:Polyethylene, polypropylene, and PVC substrates retain cost advantages for high-volume stretch and shrink applications despite circular economy headwinds.
- Paper:Kraft and glassine papers with water-based cohesive coatings bypass petroleum dependency entirely, aligning with EU Green Deal procurement criteria in regulated European markets.
- Metal:Aluminum foil laminates with heat-seal cohesive layers serve pharmaceutical blister packaging requiring moisture and oxygen barrier properties.
- Glass:Silicone-based cohesive systems enable temporary surface protection for optical and display glass during precision manufacturing and transit.
Plastic substrates dominate unit volumes; paper alternatives gain share fastest in regulatory-sensitive segments.
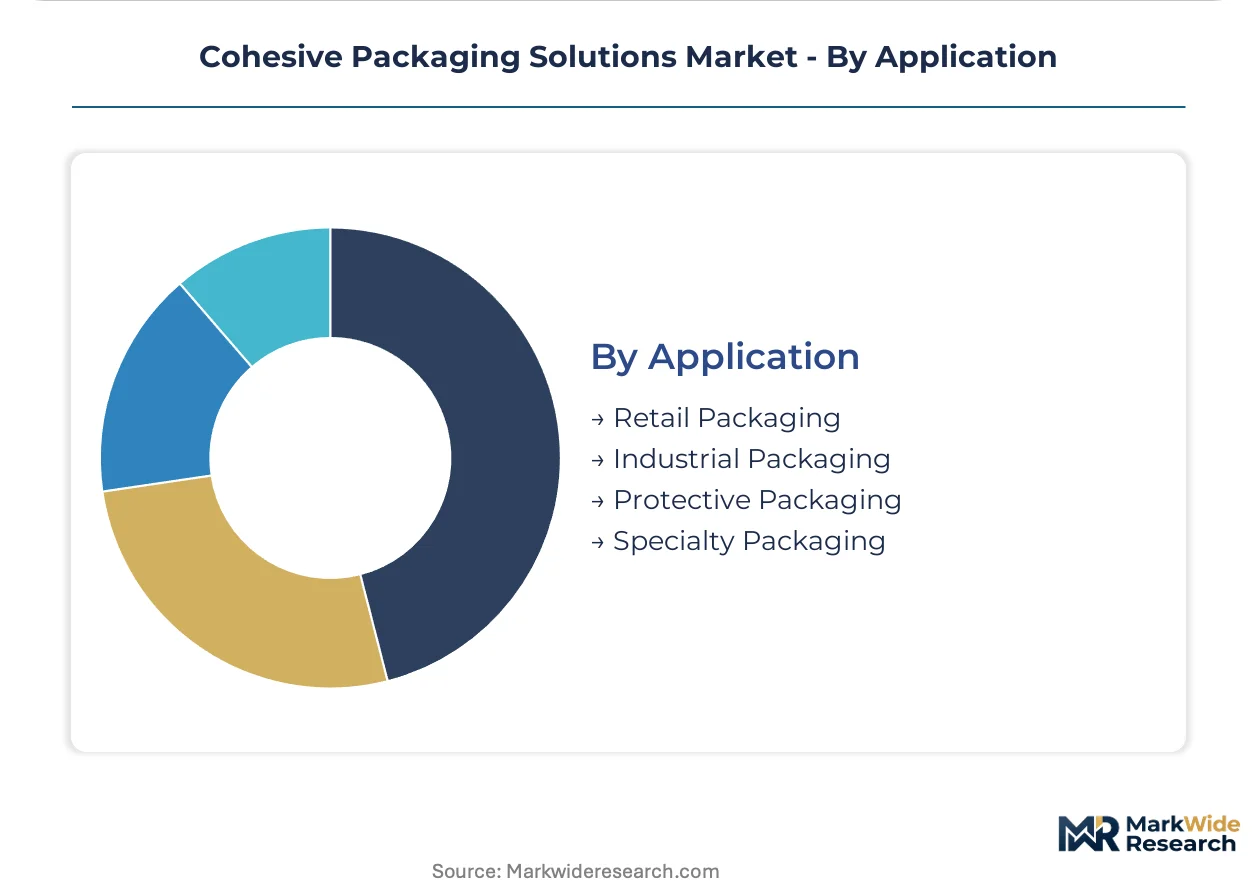
Application:
Customer type segmentation distinguishes automated line integration requirements from manual packing station flexibility needs.
- Protective Packaging:Bubble wrap, foam-in-place, and surface protection films with cohesive coatings prevent abrasion during e-commerce sortation hub throughput expansion. Fragile-goods networks in Belgium specify recyclable adhesive recovery protocols.
- Retail Packaging:Shelf-ready secondary formats with cohesive closure enable automated stocking and consumer resealability in grocery and mass-merchandise channels.
- Industrial Packaging:Heavy-duty pallet unitization and steel strapping replacement applications prioritize tensile strength and load containment over aesthetics.
- Specialty Packaging:Temperature-sensitive adhesives and clean-room validated formats serve semiconductor and aerospace component protection requirements.
Industrial packaging anchors revenue stability; protective packaging climbs the fastest on e-commerce fulfillment scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal circular economy mandates and REACH registration requirements are restructuring material specifications across European supply chains, while e-commerce fulfillment scaling drives protective packaging demand in concentrated logistics corridors.
Germany
Automotive component suppliers in Baden-Württemberg and Bavaria specify precision protective packaging systems for just-in-time delivery networks. ECHA enforcement of REACH substance volume thresholds forces adhesive formulators to document hazard classifications for continued market access. Stuttgart's manufacturing cluster demands recyclable adhesive systems in component packaging tenders.
United States
EPA volatile organic compound emission guidelines constrain solvent-based adhesive formulations at manufacturing facilities in the Midwest and Southeast. FDA food contact substance notifications govern direct-adhesive exposure limits for food packaging applications. Chicago and Atlanta logistics hubs scale automated sortation infrastructure for fragile-goods protective packaging throughput.
Netherlands
Third-party logistics providers aggregate demand through digital tendering systems concentrated in Rotterdam and Venlo distribution corridors. REACH compliance tightening favors suppliers with certified laboratory infrastructure for ASTM D3330 peel adhesion testing. Eindhoven's high-tech manufacturing cluster drives anti-static cohesive film specifications for electronics component protection.
France
Food packaging converters in Île-de-France and Auvergne-Rhône-Alpes accelerate qualification timelines for direct-contact waterborne adhesive applications. ANSM pharmaceutical serialization mandates specify cohesive labels with clean removal properties for secondary packaging. Paris-region contract packaging organizations demand documented peel adhesion certification for supplier qualification.
China
Dual carbon goals and MEE environmental enforcement accelerate waterborne adhesive transitions at manufacturing facilities in the Yangtze River Delta. SAMR standardization initiatives tighten food contact material specifications for cohesive packaging applications. Shanghai and Suzhou industrial clusters scale automated packaging lines for export-oriented consumer electronics protection.
Cohesive Packaging Solutions Market Competitive Environment
Player mix skews toward integrated materials conglomerates with captive resin synthesis capabilities and specialized adhesive formulators serving regulated end-use segments. Market structure exhibits moderate concentration where scale advantages in global manufacturing footprints separate tier-one suppliers from regional converters. Strategic archetypes include petroleum-independent substrate integrators, certified laboratory infrastructure holders, and proprietary hot-melt chemistry developers. Dominant competitive moves center on backward integration into resin supply and geographic expansion through multi-regional supply contracts.
Among integrated packaging conglomerates, Sealed Air Corporation, Mondi Group Plc, and 3M Company occupy positions that exemplify divergent strategic vectors. Sealed Air represents the global manufacturing footprint archetype sustaining multi-regional supply relationships. Mondi exemplifies petroleum-independent substrate integration through paper-based cohesive systems. 3M anchors the proprietary chemistry tier through captive resin synthesis capabilities. These three entities collectively illustrate how feedstock control, certification infrastructure, and formulation intellectual property define competitive positioning in regulatory-sensitive markets.
| Leading Market Players |
|---|
| Pregis LLC |
| Sealed Air Corporation |
| 3M Company |
| Mondi Group Plc |
| Smurfit Kappa Group |
| Polypak Packaging |
| Intertape Polymer Group |
| DS Smith Plc |
| LAMATEK, Inc. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization rates above 85 percent at German and Dutch adhesive manufacturing clusters compress price floors for mid-tier converters while amplifying margin capture for integrated producers with captive resin synthesis. REACH compliance certification costs function as a scale-dependent barrier that concentrates pricing power among ASTM D3330-certified laboratory holders.
Pricing Analysis
Certification level (REACH-registered versus non-registered) creates the primary spread between premium and commodity tiers in European procurement. Contract-based long-term offtake agreements dominate volume transactions, with price differentiation driven by formulation intellectual property and geographic delivery cost to automotive clusters in Baden-Württemberg. Cost compression in waterborne adhesive tiers is intensifying because legacy equipment retrofit requirements strand capital at smaller converters. Food and beverage manufacturers demonstrate lowest price sensitivity due to FDA food contact substance notification compliance burdens, while industrial pallet unitization buyers negotiate aggressively on per-kilogram basis.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for synthetic rubber elastomer feedstocks sourced from South Korea and Thailand. Manufacturing concentration in Germany, the Netherlands, and China draws from petroleum-derived acrylic monomers, water-based dispersion chemicals, and kraft paper substrates. Single-source vulnerability in certified laboratory infrastructure for peel adhesion testing concentrates supply risk among three dominant holders. Distribution runs through third-party logistics aggregators in Venlo and Rotterdam corridors serving just-in-time automotive component networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cohesive packaging solutions increasingly attach recurring revenue through certified laboratory service contracts and formulation customization retainers that expand faster than substrate hardware sales. After-sales compliance documentation and REACH registration renewal services represent the fastest-growing margin layer.
For Market Incumbents: Fortify captive resin synthesis positions against petroleum feedstock volatility by securing long-term offtake agreements with water-based dispersion chemical suppliers. Expand ASTM D3330 certification infrastructure into French and Italian food packaging corridors before regulatory timeline compression accelerates. Capacity addition in Eindhoven's high-tech manufacturing cluster addresses anti-static film demand from semiconductor component suppliers. For New Entrants and Emerging Players: FDA food contact substance notification fast-track services for direct-adhesive food packaging applications open white-space in French and Italian converter markets. Target pharmaceutical serialization mandates in Germany where documented peel adhesion certification creates supplier qualification bottlenecks. White-label certified laboratory partnerships offer lowest-capital go-to-market angle against integrated incumbents. For Investors and Strategic Acquirers: Paper-based substrate integrators with waterborne coating capabilities present acquisition archetypes aligned with EU Green Deal procurement criteria. Long-term viability over the coming decade hinges on feedstock independence from petroleum-derived synthetic rubber. Watch for ECHA enforcement acceleration on REACH substance volume thresholds as inflection indicator for certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Synthesis | Captive supply of hot-melt adhesive chemistry insulates Sealed Air and 3M from crude oil price swings. |
| Certified Laboratory Infrastructure Expansion | ASTM D3330 peel adhesion testing capacity in Stuttgart and Rotterdam locks in automotive supplier contracts. |
| Waterborne Formulation Transition | EU Green Deal alignment at Mondi Group bypasses REACH registration constraints on solvent-based systems. |
| Shelf-Ready Display Format Development | Automated stocking environments in French grocery channels expand cohesive closure adoption beyond industrial applications. |
| Digital Tendering Platform Integration | Third-party logistics aggregators in the Netherlands consolidate supplier relationships around performance data transparency. |
Study Parameters
Desk research of customs trade data, ECHA REACH registration databases, and SEC manufacturing disclosures preceded structured interviews with adhesive formulators, automotive procurement directors, food packaging converters, and third-party logistics operators. Primary fieldwork across German automotive clusters and Dutch distribution corridors combined with secondary validation against EPA emission guidelines and FDA food contact notifications. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Variance decomposition across product type, material substrate, end-use industry, and regional regulatory cluster shaped the analytical framework over the projection horizon. Modeled dimensions included adhesive chemistry class, coat weight tier, certification status, and automated versus manual line integration. CAGRs derived from historical trajectory analysis adjusted for REACH compliance timeline acceleration and e-commerce fulfillment network scaling. Forecast inputs incorporated petroleum feedstock price elasticity and waterborne formulation transition capital requirements.
Decision-makers should treat outputs as directional under sustained REACH enforcement and e-commerce growth assumptions; material deviation in regulatory timeline compression or crude oil price regimes would warrant model refresh. Forecasts reflect documented base-case parameters without contingency for trade policy disruption or adhesive recyclability protocol harmonization failure. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
CBD Product Packaging Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Global Shelf Ready Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
India E-Commerce Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
Korea E-Commerce Packaging Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Promotional Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Halal Packaging Market