
 Single Dose Packaging Market | 2026-2036
Single Dose Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Single Dose Packaging Market Outlook
European contract packaging capacity is rebalancing toward high-barrier single-dose formats as pharmaceutical outsourcing deepens. Amcor plc leverages its integrated film and converting footprint to sustain leadership in blister lidding applications. Berry Global competes through specialized multi-layer barrier structures for moisture-sensitive oral solids. Mondi plc anchors European supply with kraft-based sustainable alternatives gaining traction among ESG-focused buyers.
Single dose packaging denotes individually sealed primary containers designed to dispense one measured unit of product, typically employing cold-form or thermoform aluminum-PVC laminates, cyclo-olefin polymer syringes, or multilayer coextruded pouches with oxygen transmission rates below 0.1 cc/m²/day to ensure stability and patient safety. Blister packs dominate pharmaceutical dispensing due to established tooling ecosystems and child-resistance compliance, while pouches capture fastest growth in food service and travel retail portions where material efficiency matters. Plastic remains the volume leader across all end users though aluminum and cardboard combinations are displacing conventional formats in cosmetics sampling and veterinary bolus applications where premium unboxing drives brand differentiation.
FDA unit-dose labeling requirements, EU F-Gas Regulation phasing down fluorinated barrier films, and REACH restrictions on certain plasticizers are collectively forcing material transitions and compliance investments across the supply base. The EU Green Deal packaging waste directives and emerging state-level extended producer responsibility frameworks in the US are reshaping design-for-recycling specifications before they become mandatory market access conditions. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and redundant qualification cycles.
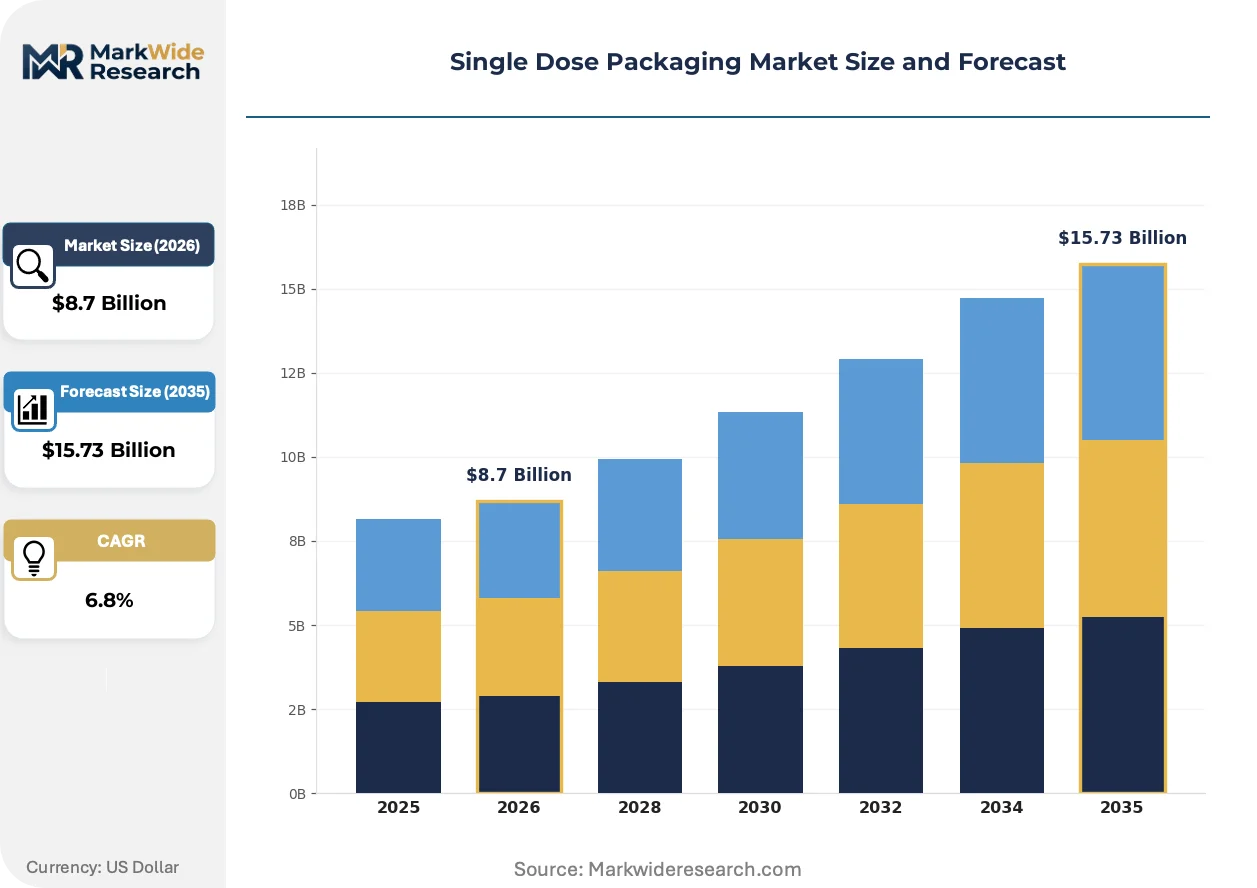
Market Dynamics
EU MDR serialization mandates and FDA unit-dose labeling requirements are forcing pharmaceutical manufacturers to reconfigure primary packaging lines for individual-dose traceability, compressing supplier qualification timelines and concentrating procurement among converters with integrated serialization capabilities.
Growth Catalysts
- Hospital-acquired infection protocols:US acute care facilities are mandating unit-dose dispensing to eliminate multi-dose vial contamination risks, driving blister and pouch demand in pharmacy automation systems.
- EU F-Gas Regulation:The phasedown of fluorinated barrier films is accelerating material transitions toward high-performance polyolefin alternatives with equivalent oxygen barrier properties.
- Aseptic filling capacity:Germany, the United States, and Japan are scaling specialized lines for biologics and vaccines, creating dedicated demand for cyclo-olefin polymer syringes and nested container formats.
Market Restraints
- Aluminum-PVC laminate cost volatility:Cold-form blister substrates depend on pharmaceutical-grade aluminum foil supply concentrated among European and Asian rolling mills, exposing converters to input price swings.
- High-barrier film supply concentration:Multi-layer coextruded structures with sub-0.1 cc/m²/day oxygen transmission rely on specialized resin grades from limited polymer compounders.
- REACH plasticizer restrictions:Phthalate-based plasticizers in PVC lidding face progressive substitution mandates, requiring reformulation of established tooling and sealing parameters.
Strategic Opportunities
- Veterinary bolus applications:Premium unboxing requirements in companion animal therapeutics are displacing conventional strip packaging with aluminum-cardboard hybrid formats.
- Extended producer responsibility frameworks:Emerging state-level EPR legislation in the US is creating first-mover advantage for converters with design-for-recycling certification.
- Cosmetics sampling convergence:Mono-material pouches with tear-notch precision are capturing travel retail and direct-to-consumer trial formats from multi-component sachets.
Industry Challenges
- Aseptic validation timelines:FDA and EMA qualification cycles for new filling lines extend 18-24 months, straining capacity planning for contract packaging organizations.
- Serialization integration:Legacy blister lines require substantial mechanical and software retrofit to accommodate aggregation and verification hardware for track-and-trace compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Dose Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Blister Packs, Pouches, Syringes Material: Plastic, Glass, Aluminum, Cardboard End User: Pharmaceuticals, Food & Beverage, Cosmetics, Veterinary Packaging Type: Rigid, Flexible, Semi-Rigid, Eco-Friendly |
| Companies Covered | Amcor plc, Berry Global Inc., WestRock Company, Sealed Air Corporation, Sonoco Products Company, Mondi plc, Huhtamaki Oyj, Gerresheimer AG, Constantia Flexibles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Dose Packaging Market Strategic Shifts
Material science advances and regulatory tightening are converging to redefine barrier performance standards and manufacturing economics across single-dose formats.
Monolayer and multilayer coextruded films with tuned crystallinity are absorbing moisture-sensitive oral solid volumes previously held by aluminum-cold form blisters. Generic pharmaceutical manufacturers in India and Eastern Europe are adopting these structures to reduce unit costs while meeting ICH stability guidelines. The shift is absorbing capital from traditional thermoform tooling toward cast film extrusion and pouch converting lines.
The EU Green Deal packaging waste directives are mandating recyclability-by-design specifications that will become market access conditions by 2030. Pharmaceutical and food service buyers are now requiring recyclability certifications from converters before contract award. German and French packaging producers are responding with paper-based barrier laminates and mono-material polyolefin structures that maintain child-resistance compliance.
Direct contracting between pharmaceutical manufacturers and specialized single-dose converters is compressing traditional distribution tiers. Hospital pharmacy chains and retail consolidators in the United States are consolidating supplier panels to three preferred converters with integrated serialization and aseptic capabilities. This concentration is visible in long-term supply agreements with penalty clauses for traceability failures, displacing spot-market procurement for high-value biologics.
Single Dose Packaging Market Segmentation
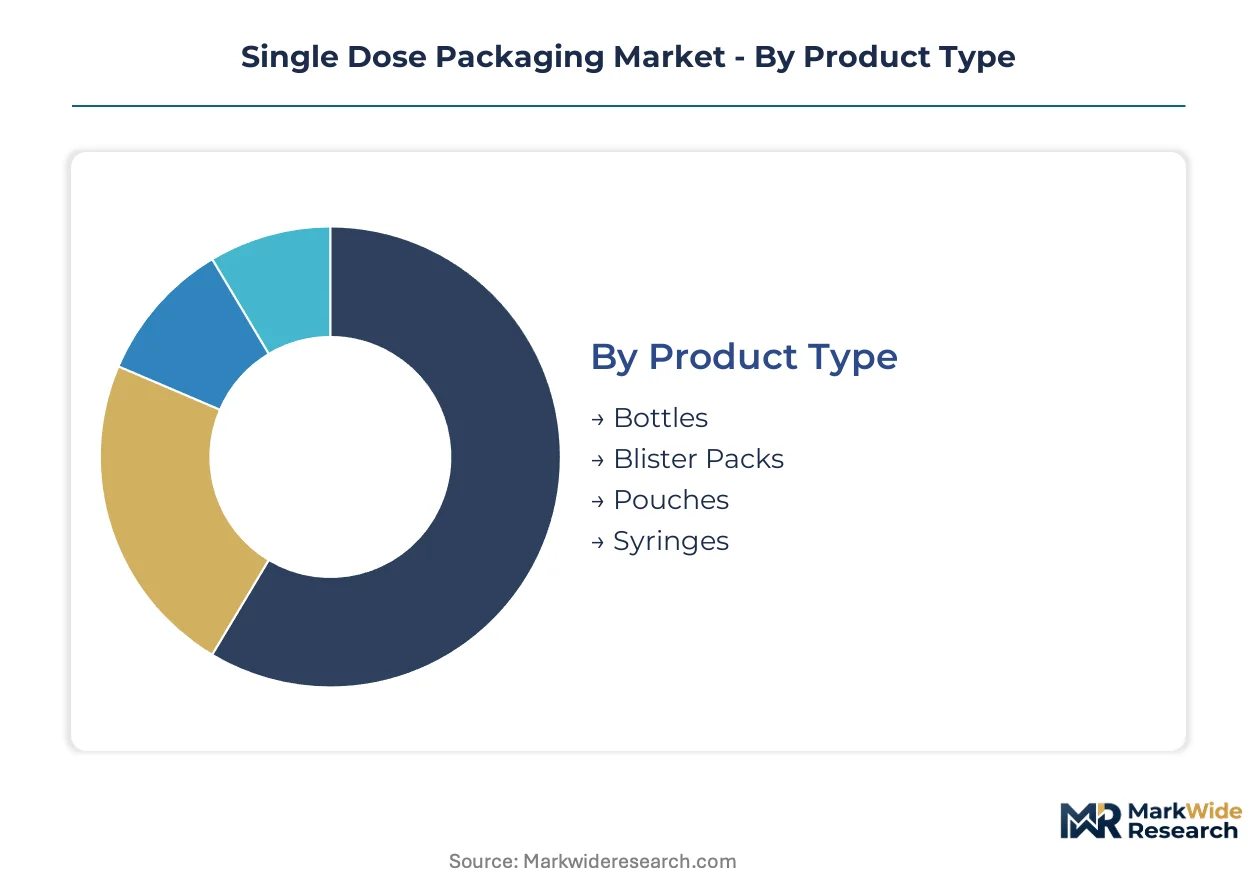
Single dose packaging configurations diverge sharply across end-use requirements, with pharmaceutical traceability mandates and food service portion economics driving incompatible specification sets. Material selection and structural format together determine barrier performance, automation compatibility, and compliance pathway.
Product Type:
Blister packs dominate pharmaceutical dispensing volumes while pouches capture the steepest expansion trajectory in food service and travel retail applications.
- Blister Packs:Cold-form and thermoform aluminum-PVC laminates deliver child-resistance compliance and established tooling ecosystems for oral solids. US hospital pharmacy chains and German retail consolidators are standardizing on unit-dose blisters to meet FDA serialization mandates and EU MDR traceability requirements, compressing supplier qualification timelines among converters with integrated aggregation capabilities.
- Pouches:Multilayer coextruded structures with sub-0.1 cc/m²/day oxygen transmission rates are displacing conventional formats in moisture-sensitive applications. Material efficiency advantages are accelerating adoption across travel retail food portions and cosmetics sampling, with German and French converters leading mono-material recyclability certifications.
- Bottles:HDPE and PET containers retain share in liquid pharmaceutical and veterinary bolus applications where resealability matters.
- Syringes:Cyclo-olefin polymer prefilled formats serve biologics and vaccines from specialized aseptic filling lines in Germany, the United States, and Japan.
Today's leader: Blister Packs. Tomorrow's challenger: Pouches.
Material:
Plastic maintains volume leadership across all end-use categories though regulatory pressure on fluorinated barriers and plasticizer content is fragmenting the supply base.
- Plastic:Multi-layer coextruded polyolefins and PVC dominate blister lidding and pouch substrates. The EU F-Gas Regulation phasedown is forcing transitions toward high-performance polyolefin alternatives, with REACH plasticizer restrictions requiring reformulation of established sealing parameters.
- Aluminum:Pharmaceutical-grade foil in cold-form laminates provides absolute moisture and light barrier for oral solids. European and Asian rolling mill concentration exposes converters to input price volatility, driving qualification of alternative barrier structures.
- Glass:Borosilicate and treated soda-lime formats serve parenteral and high-value cosmetic applications requiring inert contact surfaces.
- Cardboard:Kraft-based laminates and hybrid aluminum-cardboard structures are gaining traction among ESG-focused buyers in cosmetics sampling and premium veterinary therapeutics.
Plastic holds the installed base. Aluminum faces substitution pressure. Cardboard is climbing the fastest.
End User:
Pharmaceutical traceability mandates and infection control protocols are concentrating procurement among qualified converters, while food service and cosmetics buyers prioritize material efficiency and unboxing experience.
- Pharmaceuticals:Unit-dose dispensing mandates from US acute care facilities and EU serialization requirements are driving blister and pouch demand in pharmacy automation systems. Direct contracting between manufacturers and specialized converters is compressing traditional distribution tiers.
- Food & Beverage:Portion control and travel retail applications favor material-efficient pouch formats over rigid alternatives.
- Cosmetics:Direct-to-consumer trial formats and travel retail sampling are shifting from multi-component sachets toward mono-material pouches with tear-notch precision.
- Veterinary:Companion animal therapeutics are displacing conventional strip packaging with aluminum-cardboard hybrid formats where premium unboxing drives brand differentiation.
Pharmaceuticals command the premium tier. Veterinary and cosmetics are gaining share fastest.
Packaging Type:
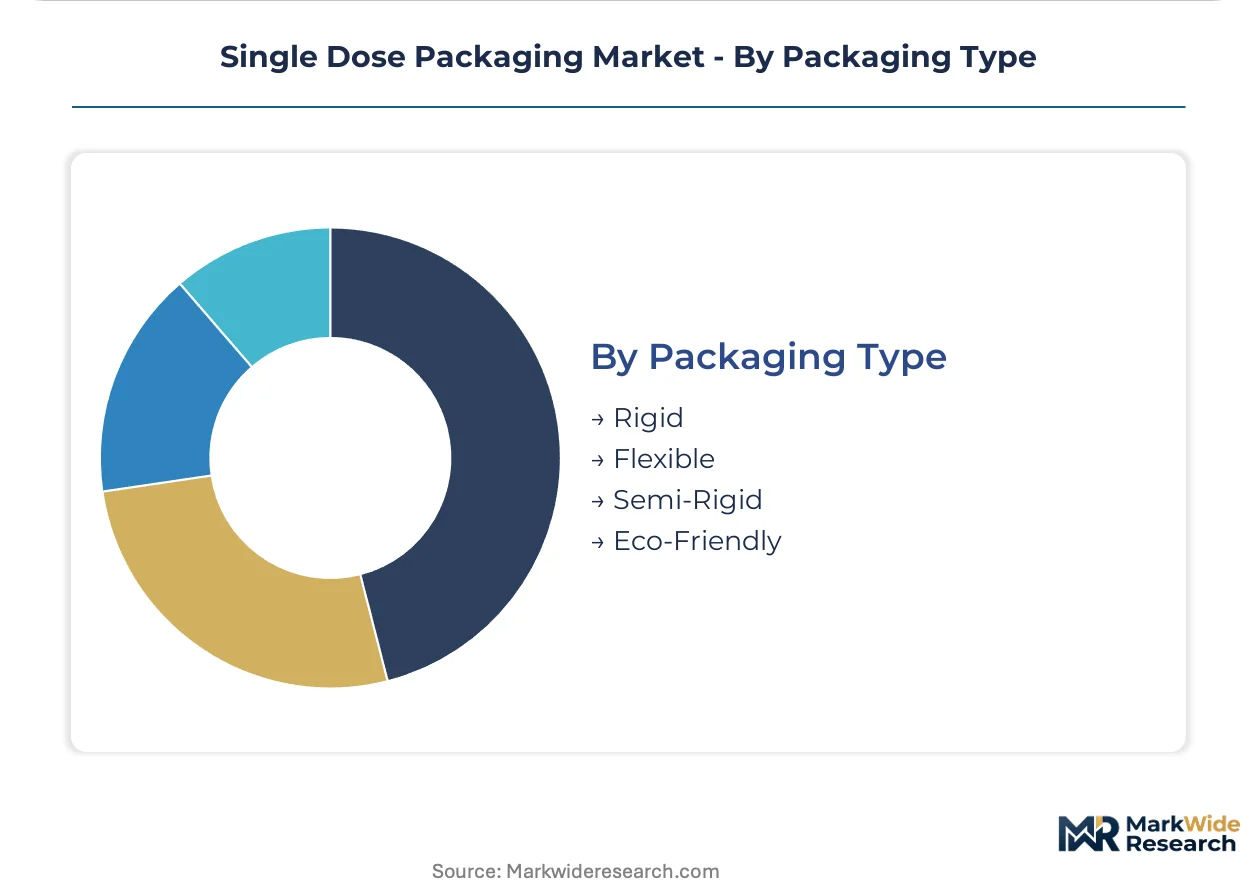
Structural rigidity determinations reflect automation compatibility, product protection requirements, and emerging recyclability mandates across jurisdictions.
- Flexible:Pouches and strip formats offer lowest material intensity and highest converting speeds. The EU Green Deal packaging waste directives are mandating recyclability-by-design specifications that favor mono-material flexible structures.
- Rigid:Blister packs and bottles provide dimensional stability for high-speed pharmaceutical filling lines and child-resistance compliance.
- Semi-Rigid:Thermoformed trays and shallow blisters bridge protection and material efficiency in veterinary and cosmetic applications.
- Eco-Friendly:Paper-based barrier laminates and certified recyclable mono-materials are becoming pre-qualification requirements for contract awards from German and French buyers.
Flexible leads on material efficiency. Eco-Friendly is expanding most quickly on regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as converters seek jurisdictions with streamlined qualification pathways and aligned serialization mandates. Manufacturing investment flows toward clusters where FDA and EMA requirements overlap, reducing redundant compliance costs for multinational pharmaceutical clients.
United States
Hospital-acquired infection protocols in US acute care facilities mandate unit-dose dispensing, driving blister and pouch demand in pharmacy automation systems. FDA unit-dose labeling requirements and track-and-trace mandates compress supplier qualification timelines. The New Jersey-Pennsylvania corridor concentrates contract packaging capacity with integrated serialization capabilities.
Germany
Specialized aseptic filling lines for biologics and vaccines create dedicated demand for cyclo-olefin polymer syringes and nested container formats. EU MDR serialization mandates and EU F-Gas Regulation phasedown force material transitions toward high-performance polyolefin alternatives. The Rhine-Main region anchors European supply with kraft-based sustainable alternatives gaining traction among ESG-focused buyers.
Japan
PMDA qualification cycles for prefilled syringes and nested containers support domestic biologics manufacturing. METI industrial standards and pharmaceutical traceability requirements align with EU MDR frameworks, enabling cross-qualification efficiency. The Kanto region around Tokyo hosts concentrated aseptic filling capacity serving regional vaccine production.
India
Generic pharmaceutical manufacturers adopt multilayer coextruded films to reduce unit costs while meeting ICH stability guidelines. CDSCO serialization requirements and expanding contract packaging capacity attract outsourcing from European and North American sponsors. The Gujarat-Maharashtra corridor scales pouch converting lines and cast film extrusion capacity.
France
Paper-based barrier laminates and mono-material polyolefin structures advance under EU Green Deal packaging waste directives. ANSM pharmaceutical regulations and emerging recyclability-by-design specifications reshape converter R&D priorities. The Auvergne-Rhône-Alpes region develops certified recyclable mono-materials for contract awards from German and French buyers.
Single Dose Packaging Market Competitive Environment
North American producers anchor one tier with integrated serialization and aseptic capabilities; European specialists hold another with sustainable material certifications and regulatory alignment. The market structure concentrates procurement among three preferred converters per major pharmaceutical client, displacing spot-market relationships. Two strategic archetypes dominate: diversified packaging conglomerates with film-to-converting integration, and specialized single-dose converters with dedicated aseptic validation. Competitive moves center on M&A to acquire serialization capabilities and capacity expansion in high-barrier film extrusion.
Among diversified packaging conglomerates, Amcor plc and Berry Global exemplify the integrated-film archetype with control over resin compounding through converting. Mondi plc occupies a position within the European specialist tier, anchoring kraft-based sustainable alternatives. These three names represent the procurement consolidation pattern visible across hospital pharmacy chains and retail consolidators, where long-term supply agreements with penalty clauses for traceability failures have replaced fragmented supplier panels.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| WestRock Company |
| Sealed Air Corporation |
| Sonoco Products Company |
| Mondi plc |
| Huhtamaki Oyj |
| Gerresheimer AG |
| Constantia Flexibles |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade aluminum foil price indices cascade through cold-form blister substrate costs into three distinct procurement tiers, with converters passing input volatility to hospital pharmacy chains through indexed contract clauses while absorbing margin compression in spot-market generic pharmaceutical sales.
Pricing Analysis
Distributor markups on serialized blister lidding vary by certification tier, with FDA-validated formats commanding premium positioning over standard EU MDR-compliant alternatives. Three-tier pricing structure across premium, standard, and economy levels separates aseptic-validated cyclo-olefin polymer syringes from thermoform blisters and basic PVC-polyolefin pouches. Cost compression in generic oral solid formats is intensifying because Indian and Eastern European manufacturers are adopting multilayer coextruded films to undercut aluminum-cold form alternatives. Hospital pharmacy chains exhibit lowest price sensitivity due to infection-control mandates, while travel retail food service buyers drive hardest bargain on pouch volumes.
Supply Chain Analysis
Dual-sourcing requirements from US hospital pharmacy chains and German retail consolidators mandate qualification of secondary film extruders and foil rolling mills to mitigate disruption risk. Pharmaceutical-grade aluminum supply draws from Germany, Japan, and South Korea, while specialized cyclo-olefin polymer resin production centers on Japan and the United States. High-barrier multi-layer coextruded structures depend on limited polymer compounders in Germany and Japan, creating single-source vulnerability for sub-0.1 cc/m²/day oxygen transmission specifications. Distribution runs through direct contracting between pharmaceutical manufacturers and specialized converters, compressing traditional distribution tiers and eliminating spot-market intermediation for biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU MDR-aligned European production and lower-cost Indian contract packaging capacity, with regulatory compliance cost differentials of 15-25 percent driving outsourcing decisions from North American sponsors.
For Market Incumbents: To counter qualification timeline compression from FDA and EMA serialization mandates, Amcor plc and Berry Global should deepen backward integration into high-barrier resin compounding while adding aseptic filling capacity in the New Jersey-Pennsylvania corridor. Certification investment in EU Green Deal recyclability-by-design specifications will defend position against Mondi plc's kraft-based sustainable alternatives.
For New Entrants and Emerging Players: Begin with veterinary bolus applications and cosmetics sampling formats where premium unboxing requirements tolerate higher unit costs and brand differentiation matters more than regulatory qualification depth. Target the aluminum-cardboard hybrid segment in companion animal therapeutics, then leverage mono-material pouch expertise to capture direct-to-consumer trial format demand from multi-component sachets.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized single-dose converters possessing dedicated aseptic validation and integrated serialization hardware rather than diversified packaging conglomerates. Over the next decade, acquisition candidates with FDA and EMA dual-qualification cycles already completed will outperform film producers lacking filling-line validation. Watch for EU F-Gas Regulation enforcement intensity as inflection indicator for polyolefin substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Barrier Resin Compounding | Captive supply of specialized polyolefin grades reduces exposure to limited compounder concentration in Germany and Japan. |
| Aseptic Filling Capacity Expansion | New Jersey-Pennsylvania corridor investment aligns with US hospital pharmacy chain consolidation toward preferred converter panels. |
| EU Green Deal Recyclability Certification | Pre-qualification requirement from German and French buyers before contract award becomes mandatory by 2030. |
| Serialization Hardware Retrofit | FDA unit-dose labeling mandates force legacy blister line upgrades for aggregation and verification compliance. |
| Direct-to-Consumer Trial Format Development | Mono-material pouches with tear-notch precision capture cosmetics sampling volumes from multi-component sachets in travel retail. |
Study Parameters
Coverage spans the United States, Germany, Japan, India, and France, with primary inputs from each market through structured interviews with contract packaging executives, pharmaceutical regulatory affairs leads, hospital procurement managers, and film extrusion plant managers. Secondary validation draws from FDA filings, EMA submissions, EU Green Deal directive texts, and customs trade data for pharmaceutical-grade aluminum foil and cyclo-olefin polymer resin flows. Bottom-up and top-down triangulation reconciles converter capacity announcements with pharmaceutical manufacturer outsourcing disclosures.
Granularity-level modeling extends to product type, material composition, end-user segment, and packaging rigidity classification, with additional dimensioning by regional regulatory cluster alignment. CAGRs across the analysis window derive from weighted capacity expansion schedules, regulatory mandate implementation timelines, and substitution elasticity estimates for aluminum-PVC laminates versus polyolefin alternatives. Forecast inputs incorporate aseptic filling line qualification cycle durations and EU F-Gas Regulation phasedown compliance cost curves.
Caveats apply where EU MDR enforcement intensity or FDA serialization mandate delays could materially shift the outlook, alongside aluminum foil price volatility from European and Asian rolling mill supply disruptions. Deviation in REACH plasticizer restriction timelines or EU Green Deal packaging waste directive implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Void Fill Packaging Systems Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Service Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
North America E-Commerce Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Recycled Materials Packaging Solutions Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Cohesive Packaging Solutions Market