
 Stretch Sleeves and Shrink Sleeves Market | 2026-2036
Stretch Sleeves and Shrink Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Sleeves and Shrink Sleeves Market Intelligence
Aftermarket sleeve recycling services is reshaping margin distribution across the value chain. Amcor PLC leverages its global manufacturing footprint to control substrate supply for high-volume beverage contracts. Berry Global Inc. anchors North American demand through specialized polyethylene formulations for dairy and juice applications. Huhtamaki Oyj differentiates via digital printing integration that reduces minimum order thresholds for craft beverage brands.
Stretch sleeves and shrink sleeves are polymer-based label substrates engineered to conform to container contours through elastic recovery or thermal contraction, typically manufactured from oriented polyethylene or polypropylene films with thicknesses ranging from 40 to 70 microns to provide 360-degree decorative coverage and tamper-evident sealing. Their primary commercial purpose centers on brand differentiation, regulatory compliance labeling, and product protection across rigid packaging formats. Shrink sleeves currently dominate high-contour applications in personal care and beverages where full-body graphics justify higher material costs, while stretch sleeves gain ground in logistics-heavy supply chains where heat-application infrastructure remains absent. Digital printing technology within the segment attracts short-run custom work as brands reduce SKU proliferation risks.
The US Food and Drug Administration governs indirect food contact materials for sleeve substrates used in beverage and food applications, while the EU REACH framework restricts phthalate plasticizers in PVC-based shrink films and the EU Packaging and Packaging Waste Regulation mandates recyclability-by-design standards that favor mono-material PET and PE constructions. These regulatory layers compel material substitution investments and restrict market access for non-compliant imports. Stakeholders must monitor evolving extended producer responsibility schemes and substrate certification requirements to anticipate compliance-driven procurement shifts.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing substrate substitution investments across European sleeve converters, compressing margins for PVC-dependent suppliers while rewarding mono-material PET and PE construction capabilities.
Growth Catalysts
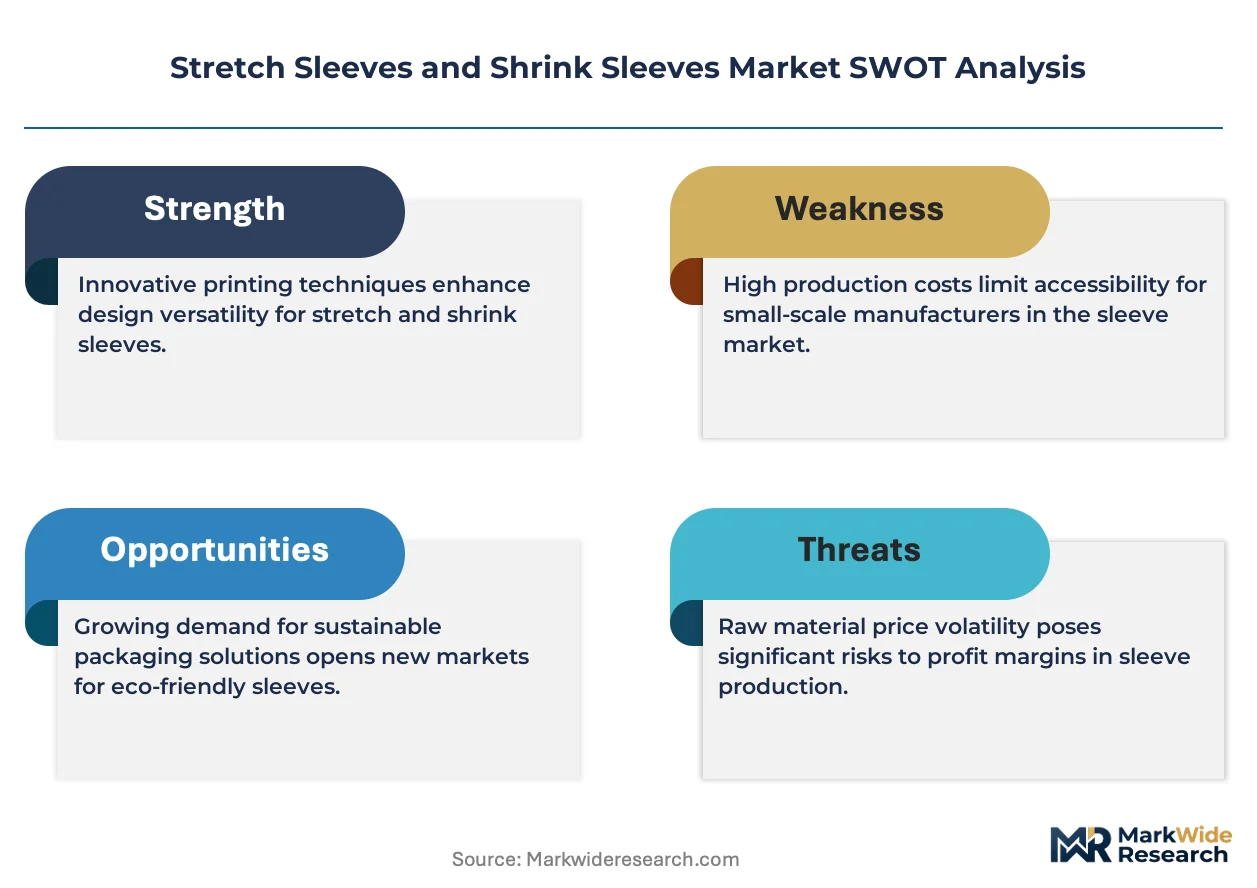
- REACH plasticizer restrictions:The EU REACH framework's phthalate limitations in PVC-based shrink films accelerate demand for compliant polyethylene alternatives in beverage packaging applications.
- Digital printing integration:Short-run customization capabilities reduce minimum order thresholds, enabling craft beverage brands to access 360-degree label coverage previously reserved for mass-market volumes.
- German manufacturing clusters:Concentrated food and beverage production in Bavaria and Baden-Württemberg generate procurement pull for tamper-evident sleeve solutions at scale.
Market Restraints
- Ethylene feedstock volatility:Oriented polyethylene film production remains exposed to naphtha-cracking economics, squeezing converter margins during upstream petrochemical price spikes.
- Heat-application infrastructure gaps:Stretch sleeve adoption plateaus in logistics-heavy supply chains lacking steam tunnel or radiant heat installation capital.
- Mechanical recycling contamination:Multi-layer sleeve constructions with adhesive-sealed seams complicate post-consumer PET bottle flake purity requirements under EU recyclability-by-design standards.
Strategic Opportunities
- Extended producer responsibility expansion:Germany's Verpackungsgesetz amendments create certified recycling service revenue streams for sleeve converters with closed-loop collection infrastructure.
- Pharmaceutical serialization convergence:Track-and-trace mandates under the EU Falsified Medicines Directive position shrink sleeves as dual-function tamper-evident and authentication substrates.
- Aftermarket sleeve recovery services:Beverage bottlers in the Netherlands and Belgium pilot deposit-return scheme integration for separated label collection, opening circular material supply contracts.
Industry Challenges
- Digital print operator scarcity:Narrow-web flexographic and inkjet technicians with sleeve-specific color management expertise command premium wages, constraining converter expansion timelines.
- Substrate certification lag:FDA indirect food contact notifications and EU EFSA positive lists require 18-24 month validation cycles for novel coextruded barrier films, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Sleeves and Shrink Sleeves Market |
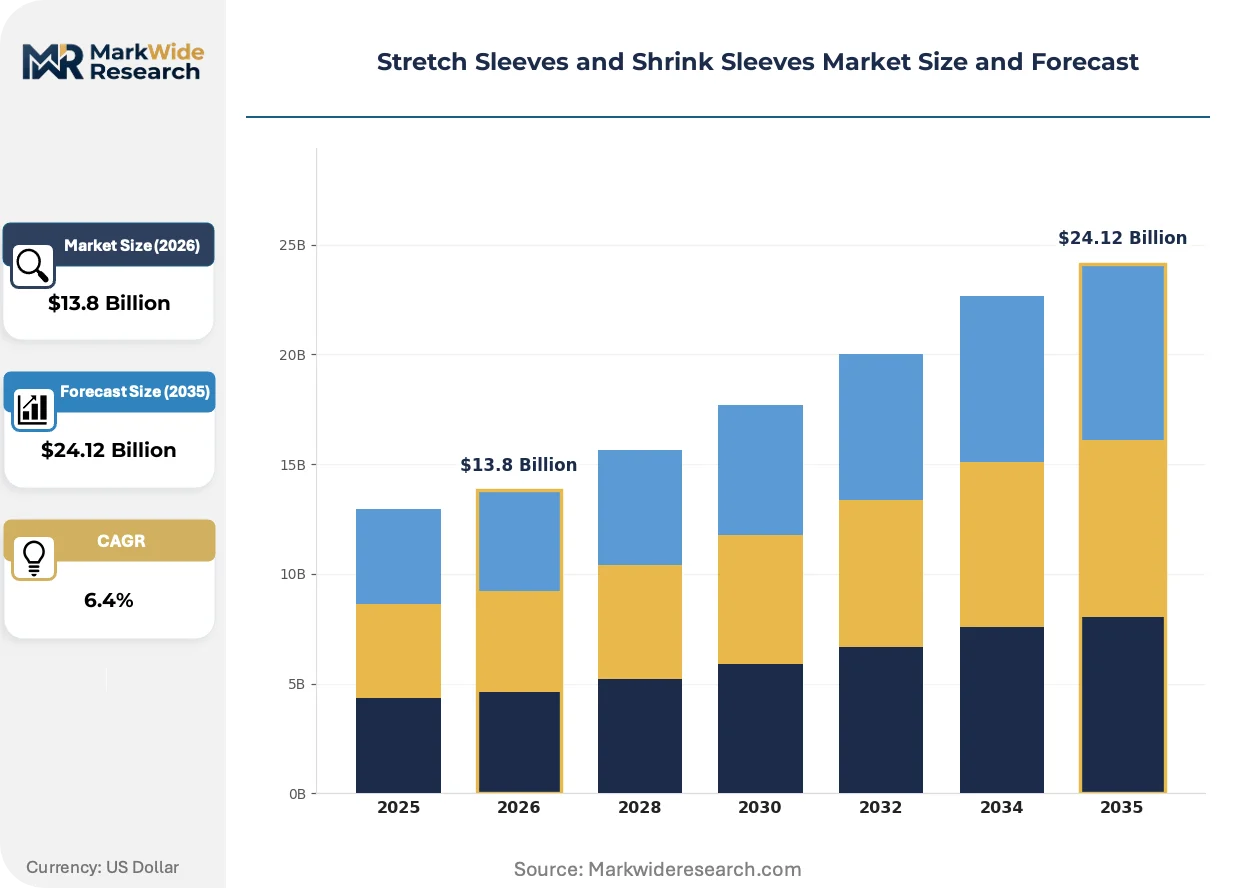
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Sleeves, Shrink Sleeves, Printed Sleeves, Custom Sleeves Material: Polyethylene, Polypropylene, PVC, PET, Others End User: Food & Beverage, Consumer Goods, Pharmaceutical, Automotive Technology: Flexographic Printing, Digital Printing, Gravure Printing, Offset Printing |
| Companies Covered | Amcor PLC, Berry Global Inc., CCL Industries Inc., Fuji Seal International, Huhtamaki Oyj, Klockner Pentaplast, Westrock Company, Clondalkin Group Holdings BV, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Sleeves and Shrink Sleeves Market Strategic Shifts & Innovations
Material science advances and regulatory compliance automation are compressing traditional sleeve production cycles while fragmenting order patterns toward micro-batch customization.
Water-based ink systems with near-infrared drying modules are hybridizing conventional solvent-based gravure workflows, allowing mid-volume converters to serve beverage clients with shorter lead times without sacrificing graphic density. Premium spirits and functional water brands in France and Italy adopt these hybrid lines to test limited-edition packaging without committing to 50,000-unit minimums. The technology is hybridizing equipment utilization rates, forcing asset-heavy competitors to defend position through volume discounts rather than capability differentiation.
The EU Green Deal's packaging recyclability targets are tightening material passport requirements, compelling sleeve suppliers to document polymer chain-of-custody from resin pellet to finished label. Industrial consequence includes accelerated R&D spending on detectable black pigments compatible with near-infrared sorting infrastructure. Personal care and home care brands with pan-European distribution face the steepest compliance ramps, with Unilever and Henkel procurement teams now mandating Design for Recycling certification from all label vendors.
Brand procurement teams are consolidating sleeve specifications across SKU portfolios to reduce substrate variety and simplify recycling claims, reversing a decade of customization proliferation. Beverage category managers at retailers like Carrefour and Ahold Delhaize now require mono-material construction as a listing prerequisite, compressing converter product development pipelines toward standardized PE and PET constructions. This consolidation is most visible in German discount retail channels, where private-label water and juice volumes concentrate purchasing power among three national sleeve suppliers.
Stretch Sleeves and Shrink Sleeves Market Segmentation
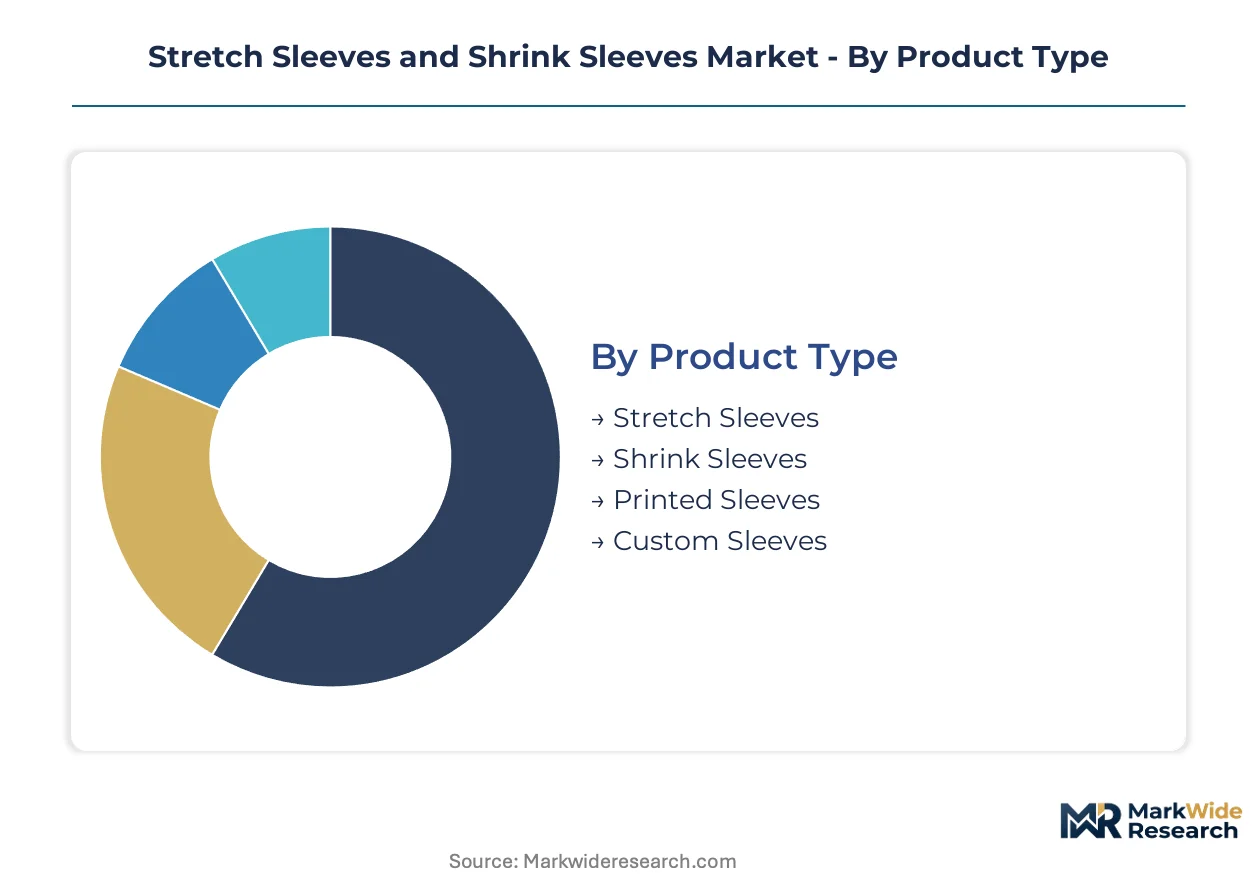
Sleeve converters configure production assets around substrate-technology pairings that align with end-use regulatory requirements and volume thresholds. Segmentation clarity enables procurement teams to match application demands with converter capability matrices.
Product Type:
Application heat requirements and contour complexity separate these formats across beverage, pharmaceutical, and logistics end-uses.
- Stretch Sleeves:Elastic recovery properties allow manual or semi-automated application without heat tunnels. Logistics-heavy supply chains in Germany and Belgium adopt these for palletized beverage distribution where steam infrastructure remains absent.
- Shrink Sleeves:Thermal contraction delivers 360-degree contour conformity for complex bottle geometries. Premium spirits and functional water brands in France and Italy specify these for tamper-evident sealing and full-body graphic coverage.
- Printed Sleeves:Pre-decorated substrates eliminate secondary labeling steps. Mid-volume converters stock these for craft beverage clients with SKU proliferation constraints.
- Custom Sleeves:Bespoke dimensions and barrier specifications serve pharmaceutical serialization mandates under the EU Falsified Medicines Directive.
Shrink sleeves hold installed capacity. Stretch sleeves is rotating up the share rankings.
Material:
Regulatory compliance trajectories and recyclability certification requirements concentrate procurement decisions across polymer categories.
- Polyethylene:Mono-material PE constructions satisfy EU Packaging and Packaging Waste Regulation recyclability-by-design standards. Beverage bottlers at Carrefour and Ahold Delhaize now mandate PE specifications for private-label water and juice portfolios.
- PVC:Phthalate plasticizer restrictions under EU REACH framework constrain beverage applications. Legacy personal care contracts in Southern Europe sustain residual demand despite substitution pressure.
- Polypropylene:High-temperature stability suits hot-fill beverage applications. German dairy processors specify oriented PP for pasteurized juice containers.
- PET:Detectable near-infrared sorting compatibility aligns with EU Green Deal packaging recyclability targets. Unilever and Henkel procurement teams mandate Design for Recycling certification for PET sleeve vendors.
- Others:Bio-based and recycled-content substrates address emerging extended producer responsibility schemes in the Netherlands and Belgium.
Polyethylene dominates current procurement volumes. PET is climbing the fastest as recyclability mandates tighten.
End User:
Volume concentration and regulatory exposure separate these verticals across sleeve converter sales pipelines.
- Food & Beverage:German manufacturing clusters in Bavaria and Baden-Württemberg generate procurement pull at scale. Tamper-evident requirements and 360-degree brand coverage drive specification complexity.
- Pharmaceutical:EU Falsified Medicines Directive track-and-trace mandates position shrink sleeves as dual-function authentication substrates. Serialization convergence accelerates demand for high-integrity barrier films.
- Consumer Goods:Personal care and home care brands face steep EU Green Deal compliance ramps. Design for Recycling certification now gates vendor qualification.
- Automotive:Chemical resistance specifications for lubricant and coolant containers sustain niche demand. Lower volume intensity limits converter specialization.
Food & Beverage commands capacity allocation. Pharmaceutical is expanding most quickly on regulatory tailwinds.
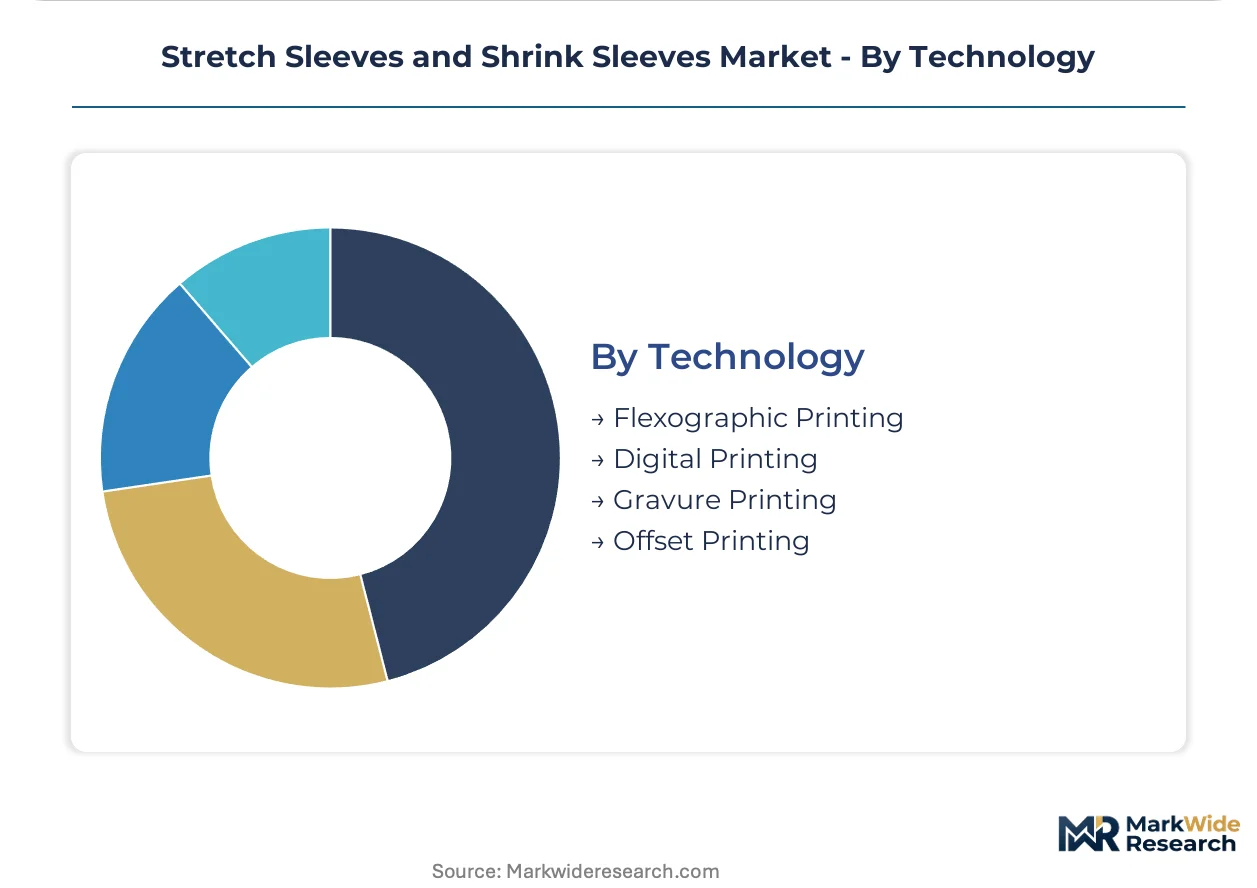
Technology:
Run-length economics and graphic density requirements determine converter equipment investment cycles.
- Digital Printing:Inkjet and toner systems reduce minimum order thresholds for craft beverage brands. Short-run customization capabilities attract limited-edition packaging contracts from premium spirits producers in France and Italy.
- Flexographic Printing:High-speed rotary operation serves mass-market beverage volumes. Water-based ink systems with near-infrared drying modules hybridize conventional solvent workflows for mid-volume flexibility.
- Gravure Printing:Cylinder-engraved reproduction delivers graphic density for premium cosmetic applications. Long setup times constrain suitability for SKU-proliferated portfolios.
- Offset Printing:Planographic transfer suits flat-sleeve applications with lower contour complexity. Limited penetration in full-body shrink sleeve segments.
Flexographic lines anchor installed base. Digital printing is gaining share fastest on order fragmentation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German beverage bottlers prioritize tamper-evident 360-degree coverage for premium private-label portfolios. US converters emphasize logistics efficiency through stretch sleeve formats that bypass heat-tunnel infrastructure.
Germany
Bavarian and Baden-Württemberg manufacturing clusters generate concentrated procurement pull for food and beverage sleeve applications. The Verpackungsgesetz amendments mandate certified recycling service integration, compelling converters to build closed-loop collection infrastructure. Stuttgart-based converters now supply mono-material PE constructions to discount retail channels under Carrefour and Ahold Delhaize listing requirements.
United States
Midwestern dairy and juice processors anchor demand for specialized polyethylene formulations. FDA indirect food contact notifications govern substrate approvals, with 18-24 month validation cycles delaying novel coextruded barrier launches. Chicago-area logistics hubs favor stretch sleeve adoption for palletized distribution where steam tunnel capital remains absent.
France
Premium spirits and functional water brands in the Île-de-France and Provence-Alpes-Côte d'Azur regions specify shrink sleeves for full-body graphic coverage. ECHA REACH phthalate restrictions accelerate PVC substitution toward compliant polyethylene alternatives. Lyon-based converters pilot hybrid water-based ink systems with near-infrared drying for limited-edition packaging runs.
Netherlands
Beverage bottlers in Rotterdam and Amsterdam pilot deposit-return scheme integration for separated label collection. Extended producer responsibility expansion under EU Green Deal packaging recyclability targets creates circular material supply contract opportunities. Dutch converters lead detectable black pigment R&D compatible with near-infrared sorting infrastructure.
Italy
Lombard and Emilia-Romagna personal care manufacturers sustain residual PVC demand despite substitution pressure. EU Packaging and Packaging Waste Regulation recyclability-by-design standards favor mono-material PET constructions for pan-European distribution. Milan-based converters consolidate sleeve specifications across SKU portfolios to simplify recycling claims for Unilever and Henkel procurement teams.
Stretch Sleeves and Shrink Sleeves Market Key Industry Players
Capability concentration sits with specialized substrate innovators; scale advantage sits with diversified packaging conglomerates. The vendor base organizes around three tiers: global film suppliers with captive resin access, regional converters with digital print integration, and niche specialists in pharmaceutical serialization. Consolidation pressure intensifies as beverage brands reduce approved vendor lists. Competitive moves center on backward integration into oriented film extrusion and geographic expansion through distributor partnerships.
Among diversified packaging conglomerates, Amcor PLC and Berry Global Inc. exemplify scale-driven positioning. Amcor leverages global manufacturing footprints to control substrate supply for high-volume beverage contracts. Berry anchors North American demand through specialized polyethylene formulations. Huhtamaki Oyj occupies a distinct tier, differentiating via digital printing integration that reduces minimum order thresholds for craft beverage brands.
| Leading Market Players |
|---|
| Amcor PLC |
| Berry Global Inc. |
| CCL Industries Inc. |
| Fuji Seal International |
| Huhtamaki Oyj |
| Klockner Pentaplast |
| Westrock Company |
| Clondalkin Group Holdings BV |
| Avery Dennison Corporation |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp barge corridors carry oriented polyethylene resin from petrochemical clusters to sleeve converters, with freight cost volatility transmitting directly into converter margin compression and downstream tiered pricing separation between mass-market beverage contracts and premium spirits applications.
Pricing Analysis
Long-term offtake agreements dominate procurement between German beverage bottlers and major converters, locking in polyethylene substrate volumes across 24-36 month horizons while spot purchasing persists for craft brands with irregular demand patterns. Price differentiation separates FDA-validated food-contact grades from industrial labeling tiers, with certification investment acting as the primary margin defense. Cost compression in standard PE constructions is intensifying because discount retail channels at Carrefour and Ahold Delhaize consolidate purchasing power among three national suppliers. Mass-market dairy processors exhibit highest price sensitivity, while premium spirits brands in France absorb graphic density premiums without volume negotiation.
Supply Chain Analysis
EU REACH plasticizer restrictions function as de facto export controls on PVC-based shrink film formulations, limiting legacy substrate flows into member states and accelerating substitution toward compliant polyethylene alternatives. Manufacturing gravity centers on Germany, Belgium, and the Netherlands, with Bavarian extrusion facilities feeding oriented film to regional converters. Raw material sourcing draws from naphtha-cracking economics in Rotterdam and Antwerp, with ethylene feedstock tethered to volatile upstream petrochemical pricing. Single-source vulnerability concentrates in specialized digital print ink formulations, where narrow-web technician scarcity constrains converter expansion timelines. Distribution runs through converter-direct relationships with beverage bottlers, bypassing distributor markups for high-volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized color management expertise for sleeve-specific digital workflows has become the binding constraint on converter expansion, with technician wage premiums now exceeding 40% above standard flexographic operator rates and compressing timelines for new capacity deployment.
For Market Incumbents: Entrench position through backward integration into oriented film extrusion, capturing substrate margin that currently leaks to petrochemical suppliers. Lock in exclusive digital print technician training pipelines with technical institutes in Stuttgart and Lyon before competitor hiring drains the limited talent pool. Defend against emerging regional converters by mandating Design for Recycling certification as a non-negotiable vendor qualification threshold for multinational beverage contracts. For New Entrants and Emerging Players: Build out pharmaceutical serialization capabilities as the most penetrable white-space segment, where EU Falsified Medicines Directive mandates create guaranteed demand for high-integrity barrier films with limited incumbent specialization. Target mid-volume craft beverage brands in France and Italy with hybrid water-based ink systems that enable limited-edition packaging without 50,000-unit minimums. Lead with short-run customization expertise as the primary go-to-market angle, exploiting order fragmentation that asset-heavy competitors cannot serve profitably. For Investors and Strategic Acquirers: Regional converters with captive digital print integration and established technician training programs represent the highest-probability acquisition archetype for capability consolidation plays. Long-term viability hinges on exposure to regulatory-driven material substitution cycles rather than commodity volume exposure. Monitor EFSA positive list approvals for novel coextruded barrier films as the critical inflection signal, with 18-24 month validation cycles creating temporary supply windows for early movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oriented Film Extrusion | Captures substrate margin and insulates converters from naphtha-cracking price volatility at Rotterdam-Antwerp hubs. |
| Digital Print Technician Training Pipeline | Addresses binding color management expertise scarcity that currently constrains converter expansion timelines across Europe. |
| Design for Recycling Certification Investment | Meets Unilever and Henkel procurement mandates that now gate vendor qualification for pan-European distribution contracts. |
| Pharmaceutical Serialization Capability Buildout | Positions sleeve substrates as dual-function tamper-evident and authentication solutions under EU Falsified Medicines Directive mandates. |
| Closed-Loop Collection Infrastructure Deployment | Captures certified recycling service revenue streams under Germany's Verpackungsgesetz amendments and Dutch deposit-return pilots. |
Research Approach
The analysis maps stretch sleeve, shrink sleeve, printed sleeve, and custom sleeve sub-sectors, each validated through sleeve converter operations directors, beverage brand procurement managers, pharmaceutical packaging engineers, and digital print technicians. Primary fieldwork combined structured interviews with secondary triangulation against EU Packaging and Packaging Waste Regulation compliance databases, ECHA REACH restriction updates, FDA indirect food contact notification filings, and German Verpackungsgesetz amendment tracking. Bottom-up volume estimates from converter capacity utilization rates were cross-checked against top-down polyethylene film consumption data from petrochemical trade associations.
Assumptions held fixed include current EU regulatory trajectories for recyclability-by-design standards and extended producer responsibility expansion rates, while variables included digital print adoption curves and pharmaceutical serialization mandate implementation timing. Segmentation modeling incorporated product type, material construction, end-use vertical, and print technology dimensions across the projection horizon. CAGRs were derived from trend-line extrapolation of historical procurement volumes adjusted for regulatory-driven substitution elasticities, with ethylene feedstock pricing and technician wage inflation as key industry-specific inputs.
Practitioners should monitor EFSA positive list approval timelines, EU Green Deal packaging recyclability target acceleration, and deposit-return scheme expansion signals for early indicators of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
FMCG Packaging Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Contract Packaging and Fulfillment Service Market
Packaging Solutions
Contract Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Consumer Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Recycled Materials Packaging Solutions Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Suspension and Retention Packaging Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Global Packaging Market