
 Airless Pumps Market | 2026-2036
Airless Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Airless Pumps Market Analysis
Refillable cartridge subscription programs is recalibrating how airless pump value gets captured across the packaging value chain. AptarGroup, Inc. leverages precision molding capabilities to dominate high-volume pharmaceutical contracts. Silgan Holdings Inc. anchors North American supply through backward integration into resin compounding. Albéa Group specializes in sustainable material formulations that meet emerging recyclability mandates.
An airless pump is a sealed dispensing system that uses a rising diaphragm or piston mechanism to evacuate product without air intake, typically engineered to deliver doses within 0.10–2.0 mL per actuation with vacuum integrity below 0.5 bar differential. This architecture protects oxygen-sensitive formulations across cosmetics, pharmaceuticals, and personal care applications where oxidation degrades active compounds. Plastic material configurations currently lead volume shipments due to cost scalability, though glass-silicone hybrids command premium positioning in dermocosmetic segments where chemical inertness justifies higher unit economics. Dispensing pumps occupy the largest share of product-type demand, while dosage pumps represent the fastest-growing configuration as pharmaceutical brands adopt metered-delivery standards for topical therapies.
REACH restrictions on cyclic silicone compounds and the EU Green Deal packaging sustainability targets are forcing material substitutions across European supply chains, with ECHA substance evaluations now driving reformulation timelines. FDA stability testing requirements for over-the-counter topical products reinforce airless designs as the preferred primary packaging format for preservative-free claims. Stakeholders must monitor evolving extended producer responsibility schemes and polymer traceability mandates to align capital allocation with compliance trajectories.
Market Dynamics
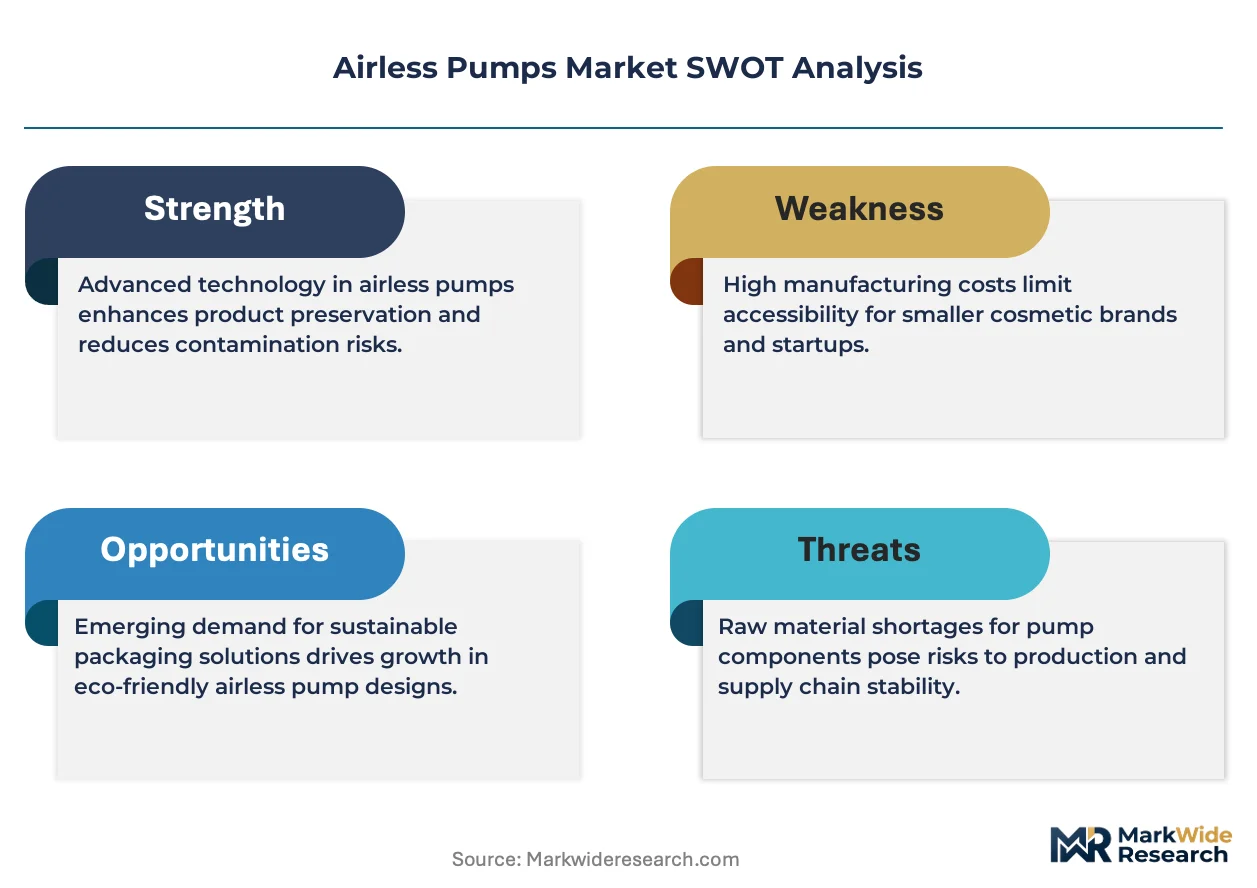
REACH restrictions on cyclic silicones and EU Green Deal packaging mandates are forcing rapid material substitutions across European supply chains, compressing reformulation timelines while elevating mono-material recyclable designs to competitive necessities.
Growth Catalysts
- Pharmaceutical metered-delivery standards:FDA stability testing requirements for over-the-counter topical products designate airless systems as the preferred primary packaging format for preservative-free formulations. Dermatology and wound-care brands are migrating dosage pump configurations into clinical protocols.
- EU extended producer responsibility schemes:Packaging sustainability targets under the EU Green Deal are accelerating capital flows toward recyclable mono-material pump architectures. Compliance deadlines are pulling forward adoption curves across cosmetics manufacturing corridors in Germany, France, and Italy.
- Active ingredient protection imperatives:Oxygen-sensitive retinoids, vitamin C derivatives, and peptide complexes in premium skincare require vacuum integrity below 0.5 bar differential. Formulation chemists specify airless dispensers as standard equipment for stability-critical SKUs.
Market Restraints
- Specialized resin cost volatility:Engineering-grade polypropylene and cyclic olefin copolymer prices fluctuate with propylene feedstock markets. Converter margins compress when polymer indices spike without corresponding pass-through mechanisms in cosmetics contracts.
- Precision molding capability concentration:High-tolerance piston and diaphragm production clusters in southern Germany and northern Italy create geographic supply risk. Tooling lead times extend to 16-20 weeks during capacity crunches.
- Glass-silicone hybrid substitution ceilings:Premium dermocosmetic segments accept 3-4x unit cost premiums for chemical inertness, but mass-market skincare remains locked in plastic configurations. Price elasticity limits addressable market expansion for upgraded materials.
Strategic Opportunities
- Refillable cartridge subscription channels:Direct-to-consumer beauty brands are piloting pump-compatible refill pods that lock into reusable outer shells. This model captures recurring revenue streams while satisfying circular economy mandates in France and Germany.
- Pharmaceutical topical therapy expansion:Metered-dosage pumps for corticosteroid creams, immunomodulators, and hormone therapies are penetrating clinical dermatology. FDA approval pathways for generic topical drugs specify airless primary packaging as bioequivalence safeguards.
- Post-consumer recycled content integration:ECHA substance evaluations and EU Green Deal traceability requirements are creating first-mover advantages for converters mastering food-contact-grade rPP compounding. Early certification unlocks preferred supplier status with multinational cosmetics houses.
Industry Challenges
- Multi-material separation complexity:Legacy pump assemblies combine polypropylene, stainless steel springs, and silicone gaskets that resist mechanical recycling streams. Redesigning for mono-material compatibility without sacrificing vacuum performance demands polymer science expertise that remains scarce.
- Validation timeline compression:ECHA substance evaluations and REACH restriction proposals are accelerating with 18-month implementation windows. Stability testing, migration studies, and supplier qualification cycles must compress without compromising documentation integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airless Pumps Market |
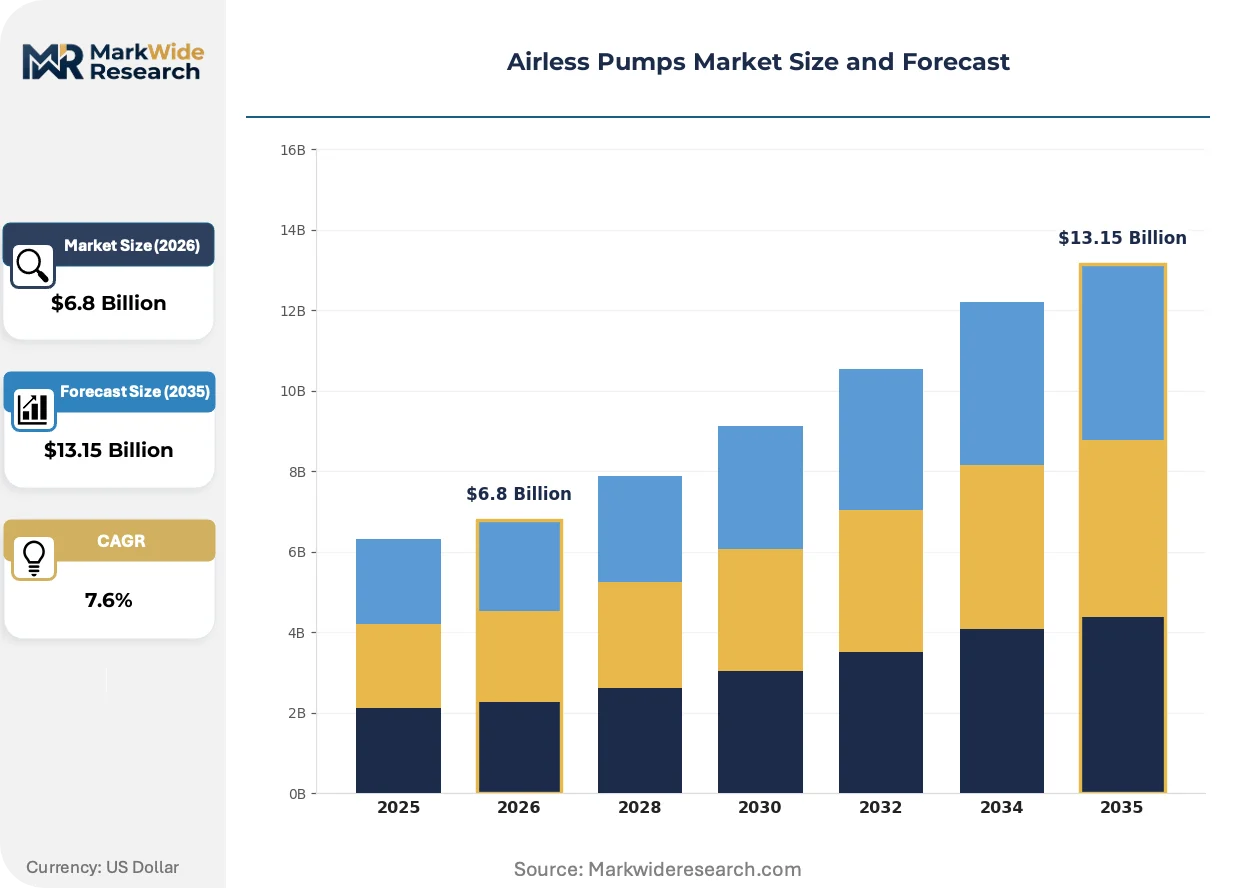
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dispensing Pumps, Spray Pumps, Squeeze Pumps, Dosage Pumps Material: Plastic, Metal, Glass, Silicone Application: Cosmetics, Pharmaceuticals, Food & Beverage, Household Products End User: Manufacturers, Distributors, Retailers, Consumers |
| Companies Covered | AptarGroup, Inc., Silgan Holdings Inc., Albéa Group, Lumson S.p.A., Quadpack Industries SA, Yonwoo Co., Ltd., HCP Packaging, Raepak Ltd., Frapak Packaging B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airless Pumps Market Emerging Trajectories
Material science breakthroughs and regulatory compliance architectures are converging to redefine competitive positioning in airless pump manufacturing, with sustainability credentials now functioning as order-qualifying rather than order-winning attributes.
Biobased polypropylene derived from renewable feedstocks is absorbing capital allocation from conventional petroleum-based resins as cosmetics brands face Scope 3 emissions disclosure requirements under the EU Green Deal. Premium skincare houses in France and Germany are specifying certified biobased content thresholds in supplier scorecards, compressing pricing power for conventional material converters while elevating specialized compounders.
REACH restrictions on D4, D5, and D6 cyclic siloxanes are forcing gasket and diaphragm reformulations across European supply chains. Silicone replacement candidates including thermoplastic elastomers and nitrile rubber compounds are undergoing migration testing and compatibility validation with active pharmaceutical ingredients. German cosmetics manufacturers are advancing fastest in qualifying alternative elastomer formulations due to proximity to ECHA guidance and testing infrastructure.
Refill pod compatibility is reshaping procurement specifications as direct-to-consumer brands unbundle primary packaging from consumable cartridges. Beauty subscription services in France and the United Kingdom are requiring pump architectures that accept standardized refill interfaces, displacing single-use disposable configurations in premium segments. This pattern concentrates most visibly among digitally native brands targeting millennial and Gen-Z demographics with sustainability-forward positioning.
Airless Pumps Market Segmentation
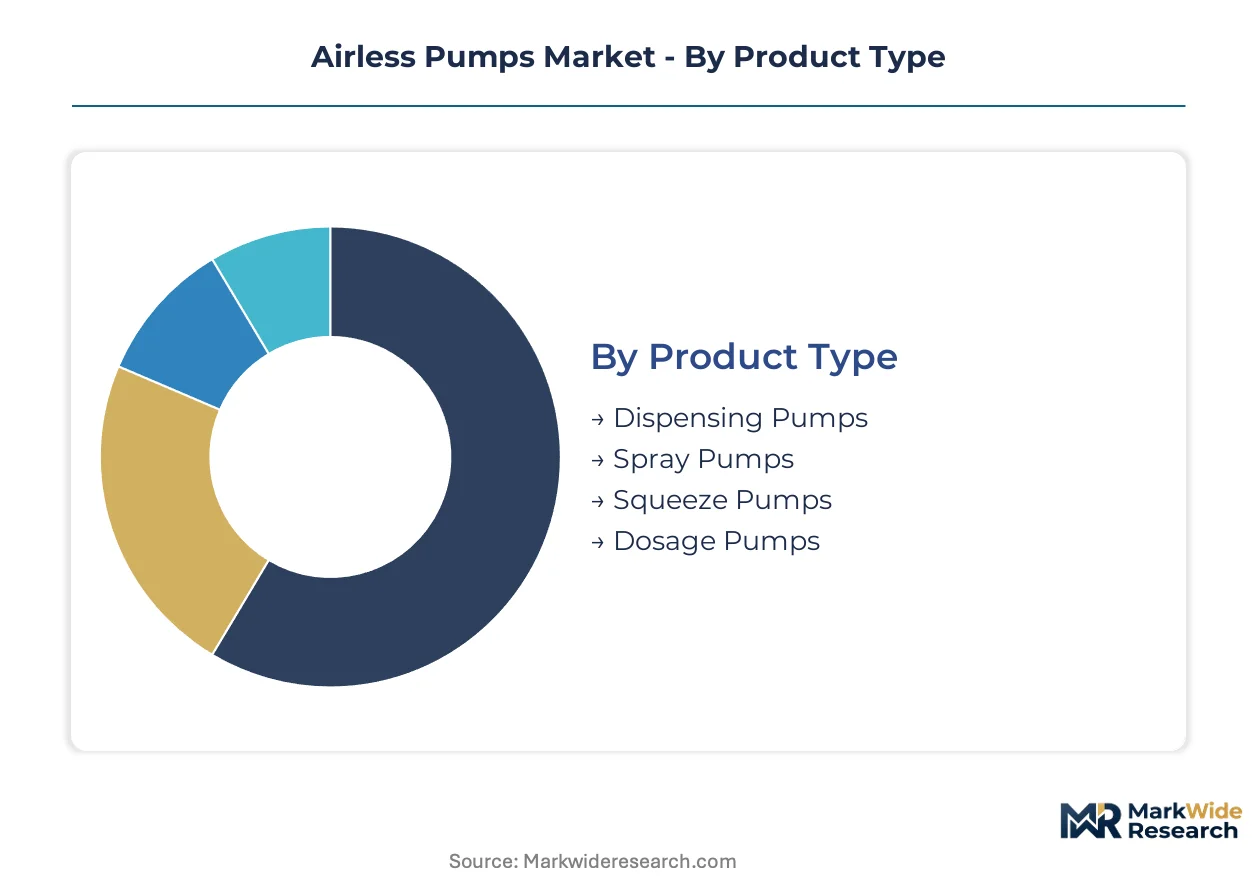
Airless pump procurement specifications diverge sharply across end-use verticals, with pharmaceutical metered-delivery tolerances demanding precision molding capabilities that cosmetics volume contracts rarely justify. Material selection and actuation mechanism choices cascade through regulatory compliance pathways, recyclability mandates, and stability testing requirements that reshape supplier qualification criteria.
Product Type:
Customization intensity spans from commodity dispensing mechanisms to pharmaceutical-grade dosage precision, with each configuration demanding distinct tooling investments and validation protocols.
- Dispensing Pumps:Rising diaphragm or piston mechanisms evacuate product through 0.10–2.0 mL actuations with vacuum integrity below 0.5 bar differential. Premium skincare brands in France and Germany specify these for oxygen-sensitive retinoid and vitamin C formulations where oxidation degradation threatens shelf stability.
- Dosage Pumps:Metered-delivery architectures enforce volumetric precision for topical corticosteroids and immunomodulator therapies. FDA stability testing requirements for over-the-counter products designate these as preferred primary packaging for preservative-free claims, with dermatology brands migrating configurations into clinical protocols.
- Spray Pumps:Atomization mechanisms deliver fine-mist distribution for facial toners and thermal water applications. Cosmetic manufacturers favor these for aqueous formulations requiring even coverage without manual spreading.
- Squeeze Pumps:Manual compression systems offer cost-optimized dispensing for mass-market personal care. Asian contract manufacturers deploy these for body lotion and hair care volumes where unit economics dominate specification criteria.
Leading the category by volume: Dispensing Pumps. Growing fastest: Dosage Pumps.
Material:
Cost tier stratification separates commodity resin formulations from premium inert substrates, with regulatory pressure on cyclic silicones forcing accelerated substitution timelines across European supply chains.
- Plastic:Engineering-grade polypropylene and cyclic olefin copolymer configurations dominate shipment volumes due to cost scalability and moldability. REACH restrictions on petroleum-derived feedstocks are compressing margins when polymer indices spike without contract pass-through mechanisms.
- Glass:Borosilicate and soda-lime architectures command 3-4x unit cost premiums in dermocosmetic segments where chemical inertness prevents active ingredient interaction. German and Italian premium houses specify these for peptide complex formulations.
- Silicone:Elastomer gaskets and diaphragms face ECHA substance evaluations on D4, D5, and D6 cyclic siloxanes that force reformulation toward thermoplastic elastomer replacements.
- Metal:Stainless steel springs and piston components provide mechanical durability in high-actuation pharmaceutical applications. Precision stamping capabilities concentrate in southern German supply clusters.
Dominating procurement volumes: Plastic. Steepest expansion trajectory: Glass-silicone hybrids for premium dermocosmetics.
Application:
End-use maturity varies from established cosmetics packaging norms to emerging pharmaceutical delivery standards that reshape regulatory validation requirements.
- Cosmetics:Skincare, color cosmetics, and fragrance applications generate baseline demand for oxygen-sensitive formulation protection. Refillable cartridge subscription programs in France and the United Kingdom are unbundling primary packaging from consumable pods.
- Pharmaceuticals:Topical therapy expansion into corticosteroid creams and hormone treatments penetrates clinical dermatology. FDA approval pathways for generic topical drugs specify airless primary packaging as bioequivalence safeguards.
- Food & Beverage:Condiment and sauce dispensing applications leverage vacuum integrity for preservative reduction. Migration testing requirements limit material selections to food-contact-grade certified compounds.
- Household Products:Cleaning and care formulations prioritize cost-optimized plastic configurations. Extended producer responsibility schemes under the EU Green Deal are accelerating mono-material recyclable design adoption.
Capturing largest share: Cosmetics. Expanding most quickly: Pharmaceuticals.
End User:
Customer type determines specification authority, with brand-owner manufacturers holding formulation compatibility requirements that distributors and retailers rarely influence.
- Manufacturers:Cosmetic and pharmaceutical brand owners define technical specifications including vacuum integrity thresholds and material certifications. German, French, and Italian manufacturing corridors concentrate procurement decision-making.
- Distributors:Wholesale and logistics intermediaries manage inventory positioning for regional fulfillment. These stakeholders prioritize supply security and tooling lead time reliability over design innovation.
- Retailers:Pharmacy chains and beauty specialty stores influence packaging aesthetics and shelf differentiation. Sustainability-forward positioning drives specification of post-consumer recycled content and biobased materials.
- Consumers:Direct-to-beauty subscription subscribers interact with refill pod architectures that lock into reusable outer shells. Digital-native brands target millennial and Gen-Z demographics with circular economy value propositions.
Holding procurement authority: Manufacturers. Gaining influence fastest: Consumers through subscription channel disruption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Neckar corridor in southern Germany anchors European airless pump manufacturing, with precision molding clusters in Stuttgart and Mannheim supplying pharmaceutical-grade dosage mechanisms to dermatology brands across the continent.
Germany
Baden-Württemberg and Hesse concentrate tooling expertise for high-tolerance piston production serving Bayer and Beiersdorf formulations. ECHA substance evaluations on D4-D6 cyclic siloxanes are accelerating silicone replacement programs in Frankfurt-Rhine-Main chemical testing facilities. Mannheim-based converters are qualifying thermoplastic elastomer gaskets for REACH-compliant pump architectures.
France
L'Oréal and LVMH beauty houses in Île-de-France are specifying biobased polypropylene thresholds in supplier scorecards for premium skincare airless dispensers. ANSM migration testing requirements for dermocosmetic packaging are compressing validation timelines to 18-month windows. Lyon-based Albéa Group facilities are advancing mono-material recyclable pump designs under EU Green Deal extended producer responsibility schemes.
Italy
Lombardy and Emilia-Romagna cosmetics manufacturers in Milan and Bologna corridors are adopting refillable cartridge architectures for direct-to-consumer beauty subscriptions. REACH restriction proposals on petroleum-derived feedstocks are elevating post-consumer recycled content specifications. Quadpack Industries SA anchors southern European supply from its Barcelona-adjacent operations serving Italian premium brands.
United States
New Jersey and California pharmaceutical corridors are integrating FDA stability testing requirements into airless primary packaging specifications for generic topical drug approvals. Silgan Holdings Inc. maintains backward integration into resin compounding across North American operations. EPA and FDA joint guidance on preservative-free claims is pulling dosage pump adoption into dermatology clinical protocols.
South Korea
Seoul Capital Area beauty manufacturers are exporting K-beauty airless packaging configurations to Southeast Asian markets. MFDS bioequivalence standards for topical pharmaceuticals are mirroring FDA metered-delivery specifications. Yonwoo Co., Ltd. exemplifies specialized molding capabilities serving Amorepacific and LG Household formulations with vacuum integrity below 0.5 bar differential.
Airless Pumps Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier base where precision molding capabilities concentrate in southern German and northern Italian industrial clusters. The market structure fragments between high-volume pharmaceutical contract specialists and flexible cosmetics packaging converters. Three archetypes dominate: integrated resin compounders with captive material supply, precision tooling houses with pharmaceutical validation expertise, and sustainable material innovators qualifying biobased and recycled content streams. Competitive dynamics center on M&A activity consolidating regional molding assets and strategic partnerships locking in biobased resin offtake agreements.
Among North American-integrated packaging conglomerates, AptarGroup, Inc. and Silgan Holdings Inc. exemplify divergent scale strategies—AptarGroup anchoring pharmaceutical-grade precision molding while Silgan leverages backward integration into resin compounding. Albéa Group represents the sustainability-forward archetype, with French and Italian facilities specializing in mono-material recyclable formulations that satisfy emerging ECHA substance evaluations. These three companies illustrate how geographic proximity to regulatory guidance in Strasbourg and Helsinki accelerates compliance-first product development.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| Albéa Group |
| Lumson S.p.A. |
| Quadpack Industries SA |
| Yonwoo Co., Ltd. |
| HCP Packaging |
| Raepak Ltd. |
| Frapak Packaging B.V. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal packaging sustainability targets gate qualified supply and premium-tier pricing access, compressing reformulation timelines while elevating mono-material recyclable designs to competitive necessities. REACH restriction proposals on cyclic silicone compounds are forcing gasket and diaphragm substitutions that bifurcate converter margins between compliant and legacy material streams.
Pricing Analysis
Vacuum integrity below 0.5 bar differential anchors value-based pricing premiums for pharmaceutical-grade dosage pumps serving FDA stability testing requirements. Three-tier pricing structure across premium, standard, and economy levels separates glass-silicone hybrids for dermocosmetics from engineering-grade polypropylene configurations and mass-market squeeze pump alternatives. Price differentiation rests on certification grade and volume scale, with pharmaceutical metered-delivery contracts commanding 3-4x unit premiums over cosmetics dispensing mechanisms. Cost compression in plastic configurations is intensifying because propylene feedstock volatility lacks pass-through mechanisms in long-term cosmetics contracts. Mass-market personal care manufacturers exhibit highest price sensitivity, while clinical dermatology brands prioritize vacuum performance over unit economics.
Supply Chain Analysis
France's ANSM migration testing requirements and Germany's ECHA substance evaluation protocols are reshaping sourcing toward domestic-content-qualified compounders with certified biobased polypropylene capabilities. Precision molding clusters concentrate in Germany, Italy, and South Korea, drawing from engineering-grade polypropylene, cyclic olefin copolymer, and thermoplastic elastomer feedstocks. Single-source vulnerability concentrates in southern German tooling houses where 16-20 week lead times extend during capacity crunches. Distribution runs through cosmetics manufacturing corridors in Germany, France, and Italy, with pharmaceutical contracts bypassing wholesale intermediaries for direct manufacturer-to-brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic elastomer replacement of silicone gaskets marks a technology-transition phase displacing legacy D4-D6 cyclic siloxane formulations across European supply chains.
For Market Incumbents: Anchor precision molding capabilities in southern Germany and northern Italy against emerging Asian competition by qualifying thermoplastic elastomer gaskets for REACH-compliant architectures. Defend position by securing biobased polypropylene offtake agreements with renewable feedstock suppliers before capacity constraints elevate resin premiums. Certification investment in food-contact-grade rPP compounding creates preferred supplier lock-in with multinational cosmetics houses facing EU Green Deal traceability mandates. For New Entrants and Emerging Players: Enter via pharmaceutical topical therapy expansion where FDA stability testing requirements designate airless primary packaging as bioequivalence safeguards for generic drug approvals. Target metered-dosage pump configurations for corticosteroid and immunomodulator therapies in clinical dermatology, the most penetrable segment given validation expertise scarcity. Pursue direct-to-consumer refill pod compatibility as the go-to-market angle, locking standardized interfaces into beauty subscription services in France and the United Kingdom. For Investors and Strategic Acquirers: ECHA restriction proposal announcements on D4-D6 cyclic siloxanes are the leading indicator that silicone replacement program acceleration will consolidate compounder margins toward early movers. Long-term viability over the next decade hinges on mastering mono-material recyclable pump architectures without sacrificing vacuum performance. Acquisition target archetype: specialized molders with captive thermoplastic elastomer formulation capabilities and existing pharmaceutical validation protocols. Watch for ANSM migration testing requirement expansions as the signal that French regulatory stringency is pulling ahead of EU harmonization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Recyclable Design Certification | EU Green Deal extended producer responsibility schemes in France and Germany mandate compliant packaging for market access. |
| Thermoplastic Elastomer Gasket Qualification | REACH restrictions on D4-D6 cyclic siloxanes force reformulation toward ECHA-compliant pump architectures. |
| Pharmaceutical Metered-Dosage Validation | FDA stability testing requirements designate airless systems as preferred primary packaging for preservative-free topical therapies. |
| Biobased Polypropylene Compounding Scale-Up | Premium skincare houses in France specify certified renewable content thresholds in supplier scorecards. |
| Refill Pod Interface Standardization | Direct-to-consumer beauty subscriptions in the United Kingdom require pump-compatible reusable outer shells. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews involving packaging engineers at cosmetics manufacturers, procurement leads at pharmaceutical brand owners, regulatory affairs specialists, and precision molding plant managers. ECHA substance evaluation databases, FDA stability testing guidance documents, EU Green Deal implementation trackers, and SEC 10-K disclosures from packaging conglomerates provided validation anchors. Bottom-up shipment tallies by product type and material configuration triangulated against top-down market sizing from end-use demand modeling.
Granularity-level modeling deployed product type, material composition, application vertical, and end-user channel as core segmentation dimensions across the analysis window. CAGRs derived from regression analysis of historical shipment patterns and forward projection of regulatory compliance deadlines. Pharmaceutical metered-delivery adoption curves and cosmetics refill subscription penetration rates served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH restriction timelines or propylene feedstock price spikes. Forecasts reflect documented assumptions regarding ECHA substance evaluation implementation schedules and EU Green Deal extended producer responsibility scheme adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Shrink Sleeve Labeling Equipment Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Bag Re-Sealer Market
Packaging Equipment
Bagging Equipment Market
Packaging Equipment
Can Seamers Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Food Packaging Equipment Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Strapping Devices Market
Packaging Equipment
Blow Molding Tools Market
Packaging Equipment
Ancillary Packaging Equipment Market
Packaging Equipment
Flow Wrap Packaging Market
Packaging Equipment
Global Cap Applicators Market
Packaging Equipment
PET Preform Machine Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Automatic Liquid Filling Market