
 North America E-Commerce Packaging Market | 2026-2036
North America E-Commerce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America E-Commerce Packaging Market Analytics
The capital-intensity divergence between automated corrugated converters and legacy folding-carton operators is reorganizing competitive tiers in North America. WestRock leverages integrated pulp-to-box manufacturing across the US Southeast to sustain margin control on high-volume e-commerce grades. Sealed Air differentiates through proprietary inflatable and foam-in-place systems that protect electronics and health products during parcel transit. Smurfit Kappa anchors North American capacity with recycled-containerboard specialization and regional sheet-feeder networks.
North America e-commerce packaging encompasses protective and containment systems engineered from corrugated fiberboard, polyethylene films, molded pulp, and biodegradable polymers, typically specified by burst strength, edge crush test ratings, and dimensional tolerance to survive automated sortation and last-mile handling. The primary commercial purpose is to reduce product damage rates while minimizing dimensional weight charges imposed by parcel carriers. Corrugated box and envelope formats lead volume, though bubble mailer demand is accelerating fastest among apparel and accessory e-tailers seeking to cut outbound postage. Biodegradable material grades remain niche but command premium positioning among direct-to-consumer brands targeting sustainability-conscious subscribers.
The US EPA, state-level extended producer responsibility frameworks, and the FTC's Green Guides collectively shape material disclosure requirements and recyclability claims across North American e-commerce packaging. The FTC monitors environmental marketing to prevent deceptive biodegradability assertions, while California and New York statutes advance post-consumer recycled-content mandates that filter into national procurement specifications. Stakeholders must monitor how pending state legislation alters compliance costs and whether fiber-based alternatives achieve performance parity with polyethylene in humid distribution corridors.
Market Dynamics
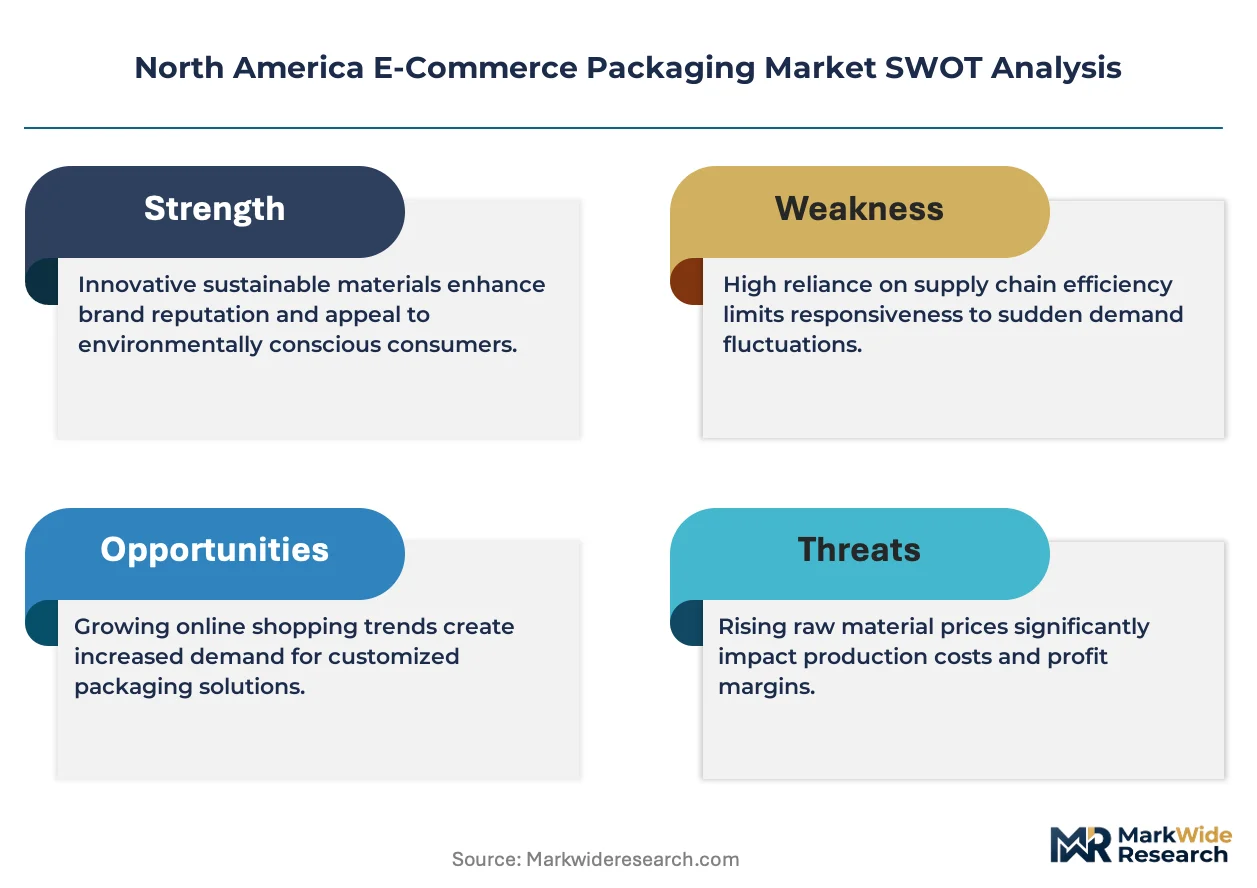
The US EPA's sustainable materials management priorities and state-level extended producer responsibility statutes are redirecting capital toward recycled-content fiberboard and biodegradable polymer alternatives, compressing virgin polyethylene demand while elevating compliance costs for legacy converters.
Growth Catalysts
- State EPR mandates:California and New York post-consumer recycled-content laws are filtering into national procurement specifications, forcing brand owners to specify certified fiber-based alternatives.
- Corrugated manufacturing clusters:Concentrated capacity near Atlanta and Charlotte reduces lead times for Southeast distribution hubs serving same-day and next-day fulfillment networks.
- Automated sortation infrastructure:Parcel carriers' dimensional weight algorithms and handling robotics demand packaging engineered to precise edge crush test and burst strength tolerances.
Market Restraints
- Old corrugated container price volatility:OCC feedstock costs swing with Chinese import policy shifts, compressing margin stability for recycled-containerboard specialists.
- Resin supply concentration:Gulf Coast petrochemical complexes dominate polyethylene supply, exposing bubble mailer producers to hurricane-related production interruptions.
- Performance gap in humid corridors:Fiber-based alternatives absorb moisture during summer transit through Florida and Gulf Coast distribution lanes, elevating damage rates versus polyethylene.
Strategic Opportunities
- Canadian provincial EPR expansion:British Columbia and Ontario extended producer responsibility frameworks outpace US federal action, creating first-mover positioning for compliant packaging suppliers.
- Reusable container pooling:Apparel and accessory e-tailers are piloting returnable polypropylene tote systems to eliminate single-use corrugated from reverse logistics.
- FTC Green Guide enforcement:Stricter biodegradability claim substantiation is advantaging suppliers with third-party certified compostable film portfolios.
Industry Challenges
- Converting equipment automation:Legacy folding-carton operators face eight-figure capital requirements to match corrugated competitors' high-speed flexo folder-gluer throughput.
- Multi-state compliance architecture:Divergent California SB 54, New York EPR, and pending Illinois packaging fee statutes force redundant SKU certification and labeling systems.
- Recyclability testing protocols:How2Recycle and APR screening standards for store drop-off compatibility extend new product development cycles by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America E-Commerce Packaging Market |
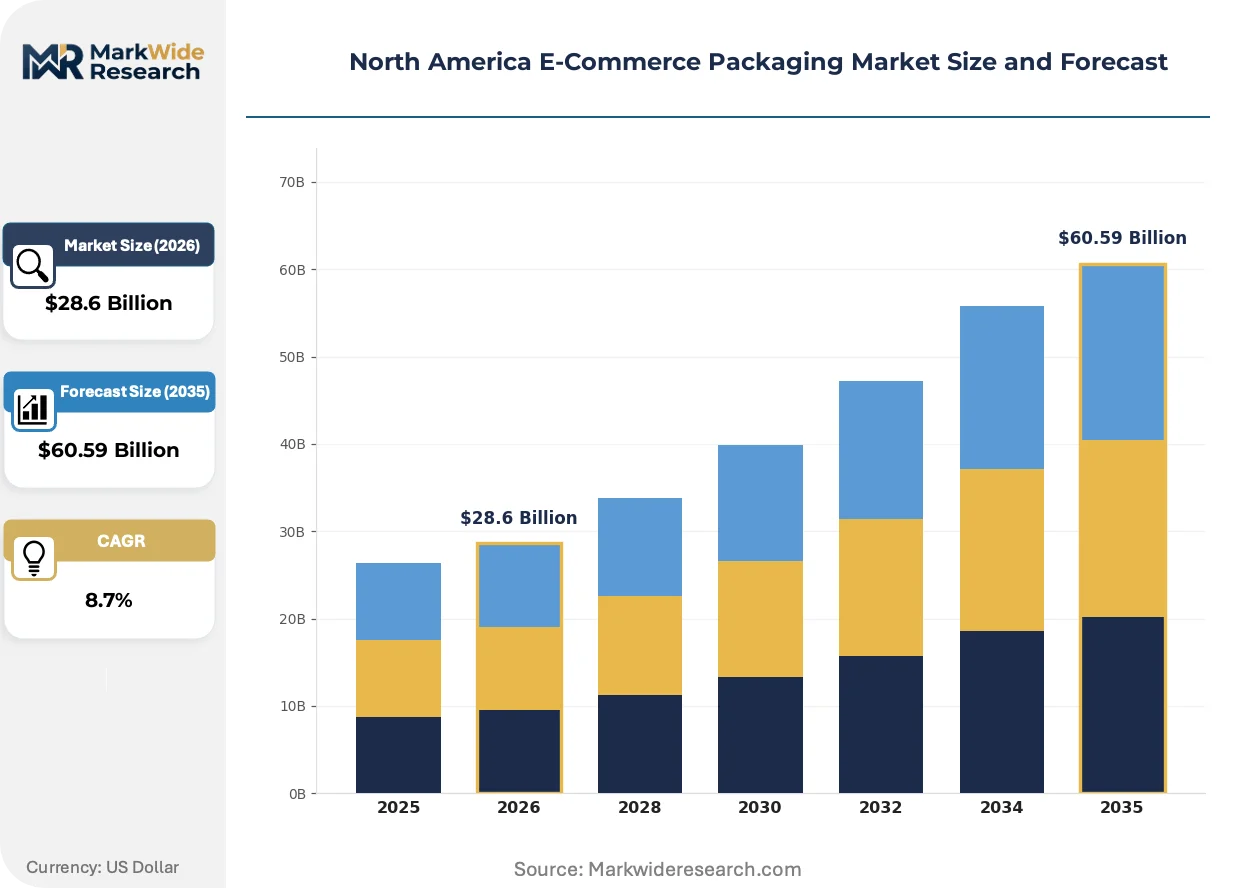
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Box, Envelope, Bubble Mailer, Crate Material: Cardboard, Polyethylene, Paper, Biodegradable Size: Small, Medium, Large, Custom End User: Retailers, Wholesalers, Manufacturers, E-Tailers |
| Companies Covered | Packaging Corporation of America, Graphic Packaging Holding, WestRock, International Paper, Sealed Air, Amcor, Georgia-Pacific, Sonoco Products Company, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America E-Commerce Packaging Market Evolving Landscape
Material science advances and regulatory enforcement patterns are fragmenting the protective packaging landscape into performance-optimized and sustainability-certified product tiers with diverging specification requirements.
Water-based barrier coatings for corrugated fiberboard are bifurcating the protective mailer category. Apparel and soft-goods e-tailers are specifying coated kraft envelopes at accelerating volume for outbound parcel streams. The technology is bifurcating procurement teams into sustainability-focused brand owners accepting modest moisture protection trade-offs versus electronics and health-product shippers retaining polyethylene bubble laminates for humidity resilience.
The FTC's Green Guides revision and state attorney general enforcement actions are tightening biodegradability and recyclability claim standards. California's Truth in Labeling law now mandates disclosure of non-recyclable components exceeding one percent by weight. Direct-to-consumer subscription brands are reformulating packaging portfolios to avoid class-action exposure, prioritizing How2Recycle-prequalified materials over unverified "eco-friendly" marketing.
Consolidated procurement by mega-fulfillment networks is compressing supplier bases and elevating performance-based contracting. Third-party logistics providers operating multi-tenant warehouses are specifying damage-rate guarantees and dimensional optimization clauses rather than unit-price agreements. This shift is most visible in the US Southeast, where Atlanta and Charlotte distribution corridors concentrate demand among four major parcel carriers and their captive packaging engineering teams.
North America E-Commerce Packaging Market Segmentation
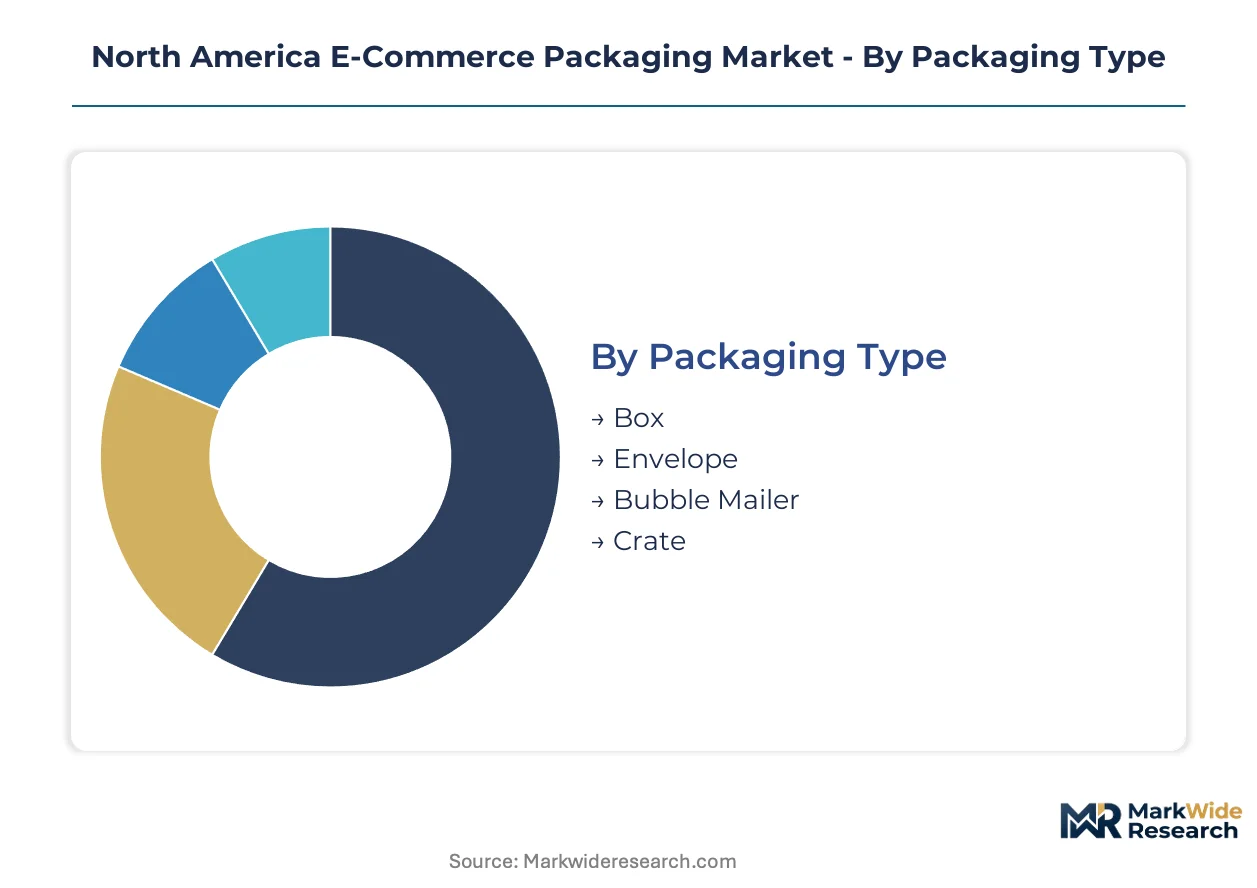
E-commerce packaging procurement in North America fragments across four dimensions that determine specification requirements, cost structures, and compliance obligations. Understanding where volume concentrates versus where margins expand allows suppliers to prioritize R&D and capacity investments.
Packaging Type:
Margin pools concentrate in protective formats that reduce damage liability and dimensional weight penalties for high-value shipments.
- Box:Corrugated fiberboard containers dominate volume across automated fulfillment networks, with burst strength and edge crush test ratings specified to survive robotic sortation in Atlanta and Charlotte distribution corridors. Major parcel carriers enforce dimensional weight algorithms that reward right-sized box specifications.
- Bubble Mailer:Polyethylene-lined envelopes are expanding most quickly among apparel and accessory e-tailers seeking to cut outbound postage costs while maintaining moisture protection through humid Gulf Coast transit lanes.
- Envelope:Kraft paper and lightweight poly mailers serve flat, non-fragile goods with minimal protective requirements, competing primarily on unit cost and printability for branded unboxing experiences.
- Crate:Heavy-duty corrugated or wood-reinforced formats handle oversized furniture and appliance shipments, with demand tied to home improvement and furniture e-commerce penetration.
Box holds installed capacity. Bubble Mailer is rotating up the share rankings.
Material:
Cost tier stratification separates virgin polyethylene producers from recycled-content fiberboard specialists facing divergent feedstock volatility profiles.
- Cardboard:Recycled-containerboard grades command specification share among retailers responding to California and New York post-consumer recycled-content mandates, though moisture absorption limits deployment in Florida summer transit.
- Polyethylene:Virgin and recycled-content films retain dominance in bubble mailer laminates and moisture-critical electronics packaging, with supply concentration along Gulf Coast petrochemical corridors exposing producers to hurricane interruption risk.
- Paper:Uncoated kraft and water-based barrier-coated variants serve sustainability-focused direct-to-consumer brands prioritizing How2Recycle-prequalified formats over performance-optimized plastics.
- Biodegradable:PLA and PHA polymer grades remain niche, commanding premium positioning among subscription box brands targeting FTC Green Guide-compliant environmental marketing with third-party certified compostable claims.
Polyethylene retains volume leadership. Paper is climbing the fastest among material conversions.
Size:
Application-specific dimensional requirements fragment procurement into standardized versus custom specification tiers with diverging tooling investments.
- Small:Standardized dimensions for jewelry, cosmetics, and accessory shipments align with carrier flat-rate pricing tiers, enabling high-volume converter economies.
- Medium:Mid-range apparel and electronics formats represent the most contested specification band, with dimensional optimization algorithms driving right-sizing investments among third-party logistics providers.
- Large:Bulk household goods and multi-item shipments require reinforced board grades and often custom structural design to prevent compression failure in stacked pallet loads.
- Custom:Bespoke dimensional specifications for irregular or high-value products carry premium pricing but extend new product development cycles by six to nine months due to recyclability testing protocols.
Medium holds installed capacity. Custom is gaining share fastest among premium positioning strategies.
End User:
Customer type determines contract structure, with consolidated procurement by mega-fulfillment networks compressing supplier bases versus fragmented e-tailer demand.
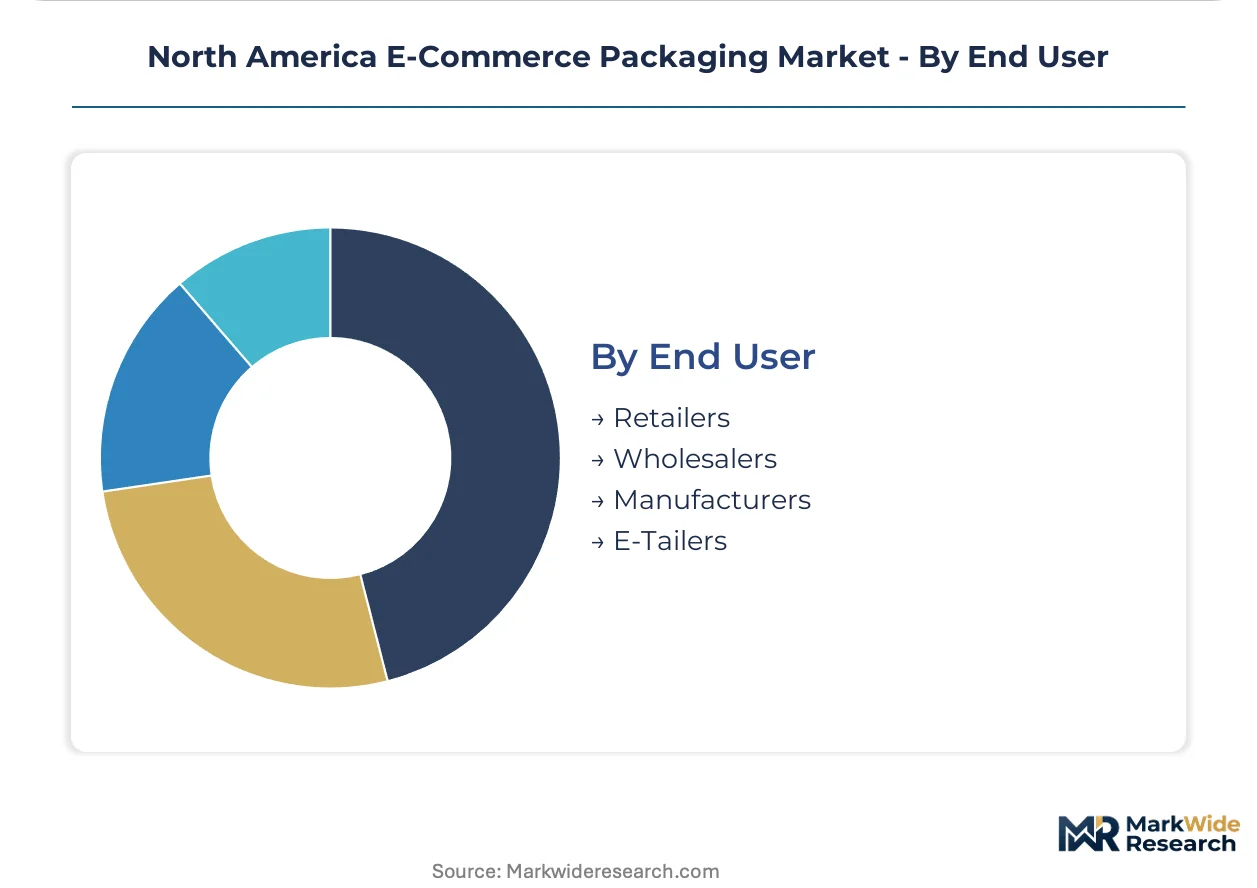
- E-Tailers:Direct-to-consumer brands prioritize unboxing experience and sustainability certification, driving specification of branded, How2Recycle-labeled formats with premium print quality and compostable claims.
- Retailers:Omnichannel operators balance in-store replenishment packaging with ship-from-store e-commerce formats, creating dual specification requirements that complicate inventory management.
- Manufacturers:Industrial and consumer goods producers specify protective packaging primarily for outbound finished goods distribution, with damage-rate guarantees replacing unit-price contracting in multi-tenant warehouse arrangements.
- Wholesalers:Bulk distributors emphasize total landed cost and pallet cube efficiency over individual package aesthetics, favoring standardized corrugated grades with minimal customization.
E-Tailers command specification influence. Retailers are rotating up the share rankings as ship-from-store volume expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across North America, with the United States prioritizing high-volume corrugated automation while Canada accelerates extended producer responsibility compliance and Mexico builds export-oriented assembly packaging capacity.
United States
The US Southeast dominates procurement volume, with Atlanta and Charlotte distribution corridors serving same-day fulfillment networks for major parcel carriers. The EPA's sustainable materials management priorities and California's SB 54 recycled-content mandates filter into national specifications. WestRock operates integrated pulp-to-box manufacturing across Georgia and the Carolinas to control margins on e-commerce grades.
Canada
British Columbia and Ontario extended producer responsibility frameworks outpace US federal action, creating first-mover demand for certified fiber-based alternatives. Health Canada and PMRA oversee packaging safety standards for cross-border e-commerce shipments. Toronto and Vancouver distribution hubs concentrate procurement among third-party logistics providers serving US market access.
Mexico
Export-oriented assembly operations near the US border drive demand for protective formats serving electronics and automotive parts e-commerce. The central bank and economy ministry coordinate industrial cluster development in Nuevo León and Baja California. Mexico City metro area distribution centers handle growing domestic e-commerce volume with corrugated specifications aligned to US carrier dimensional weight algorithms.
North America E-Commerce Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating among containerboard producers controlling pulp supply and regional sheet-feeder networks. The structure rewards backward integration into recycled fiber sourcing and high-speed converting automation. Three archetypes dominate: integrated paperboard manufacturers, protective packaging system specialists, and regional corrugated converters. Competitive moves center on M&A to secure Southeast US manufacturing clusters and strategic partnerships with parcel carriers to engineer damage-rate guarantees.
Among integrated North American paperboard producers, Packaging Corporation of America and WestRock exemplify the scale-driven tier with captive containerboard supply. Sealed Air occupies a position within the protective systems specialist archetype, differentiating through inflatable and foam-in-place technologies. These three represent contrasting strategic postures: fiber integration versus equipment-based protection, geographic manufacturing concentration versus global technology licensing.
| Leading Market Players |
|---|
| Packaging Corporation of America |
| Graphic Packaging Holding |
| WestRock |
| International Paper |
| Sealed Air |
| Amcor |
| Georgia-Pacific |
| Sonoco Products Company |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
Seventy-two-hour lead times from Charlotte and Atlanta sheet-feeder networks concentrate procurement leverage among Southeast distribution hubs, compressing spot-market premiums for corrugated grades while amplifying contract-based pricing power for integrated producers with captive containerboard supply.
Pricing Analysis
Long-term offtake agreements dominate volume procurement between major e-tailers and integrated corrugated producers, though spot-market transactions persist for specialty protective formats. Price differentiation hinges on recycled-content certification tiers and burst-strength performance grades, with California SB 54 compliance commanding modest premiums. Cost compression in standard corrugated runs through OCC feedstock volatility and resin price swings. Third-party logistics providers operating multi-tenant warehouses exhibit highest price sensitivity due to damage-rate guarantee clauses, while direct-to-consumer subscription brands prioritize sustainability certification over unit cost.
Supply Chain Analysis
Old corrugated container collection networks in the United States, Canada, and Mexico feed recycled-containerboard production, with Chinese import policy shifts periodically disrupting OCC pricing stability. Virgin polyethylene production draws from Gulf Coast petrochemical complexes, creating hurricane exposure for bubble mailer laminates. Single-source vulnerability concentrates in linerboard supply from integrated pulp-to-box manufacturers. Distribution runs through Atlanta and Charlotte regional sheet-feeder networks serving same-day fulfillment corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of high-speed flexo folder-gluer automation capability among legacy folding-carton operators is fragmenting competitive tiers, with capital access determining who captures e-commerce volume growth versus who faces margin compression.
For Market Incumbents: Secure backward integration into recycled fiber sourcing to buffer OCC price volatility, and expand Southeast US manufacturing clusters near Atlanta distribution corridors. Emerging automated converter entrants threaten regional sheet-feeder dominance. Certification investment in How2Recycle-prequalified formats defends positioning against FTC Green Guide enforcement. For New Entrants and Emerging Players: Anchor in Canadian provincial EPR frameworks ahead of US federal action, targeting British Columbia and Ontario compliance demand for certified fiber-based alternatives. Water-based barrier coating technology represents the most penetrable white-space for apparel e-tailer specifications. Pilot reusable container pooling programs with direct-to-consumer brands to bypass incumbent corrugated relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because automated converting equipment requirements are elevating capital barriers and compressing returns for sub-scale operators. Target regional corrugated converters with Southeast US footprint and captive sheet supply agreements. Watch California and New York EPR implementation pace as inflection indicator for national specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Fiber | OCC price volatility from Chinese import policies threatens margin stability for non-integrated converters. |
| High-Speed Converting Automation | Flexo folder-gluer throughput gaps separate competitive tiers in Atlanta and Charlotte corridors. |
| How2Recycle Certification Investment | FTC Green Guide enforcement elevates third-party prequalification above unverified sustainability claims. |
| Reusable Container Pooling Pilots | Apparel e-tailers seek reverse logistics solutions eliminating single-use corrugated from returns. |
| Provincial EPR Compliance Positioning | British Columbia and Ontario frameworks outpace US federal action, creating first-mover demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including corrugated plant managers, e-commerce fulfillment directors, third-party logistics procurement leads, and sustainability officers at direct-to-consumer brands. Secondary validation drew from EPA sustainable materials management reports, state EPR statute filings, FTC Green Guide enforcement records, and parcel carrier dimensional weight algorithm disclosures. Bottom-up volume modeling triangulated against top-down containerboard production capacity assessments.
Across the analysis window, forecasts applied segment-level CAGRs derived from historical e-commerce penetration rates and packaging intensity per shipment trends. Modeling incorporated packaging type, material grade, end-user archetype, and regional regulatory cluster dimensions. Edge crush test specification trajectories and recycled-content mandate compliance timelines served as industry-specific forecast inputs.
Material uncertainties — OCC import policy reversals, hurricane disruptions to Gulf Coast resin supply, and state EPR statute expansion — sit outside the modeled envelope. Forecasts reflect assumptions about sustained e-commerce volume growth and carrier dimensional weight algorithm stability. Revision becomes warranted when fiber-based moisture protection achieves performance parity with polyethylene in humid distribution corridors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Temperature Controlled Packaging Solutions Market
Packaging Solutions
Custom Packaging Market
Packaging Solutions
Cohesive Packaging Solutions Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Supplements and Nutrition Packaging Market
Packaging Solutions
Global Packaging Market
Packaging Solutions
Europe Modified Atmosphere Packaging Market
Packaging Solutions
FMCG Packaging Market