
 Sliding Injection Molding Machine Market | 2026-2036
Sliding Injection Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sliding Injection Molding Machine Market Insights
REACH compliance is restructuring the cost-of-entry calculus for European suppliers of sliding injection molding machines. KraussMaffei Group GmbH leverages its captive R&D infrastructure in Germany to anchor premium electric-hybrid system development. Arburg GmbH + Co KG competes through specialized medical-grade configurations that sustain margin pools in regulated end-use segments. Multiplas Enginery Co. Ltd dominates Taiwan-based supply for multi-component tooling systems across Asian automotive tier-ones.
A sliding injection molding machine employs a horizontally or vertically translatable clamping unit that shuttles molds between injection and ejection stations, typically achieving clamp forces from 50 to 5,000 kN and cycle times optimized for insert molding or overmolding operations. Its primary industrial purpose centers on producing complex geometries with integrated metal or polymer inserts in automotive lighting, medical connectors, and consumer electronics housings. Horizontal configurations lead unit shipments across automotive parts applications, while electric technology captures the fastest expansion as OEMs prioritize energy recovery systems and precision repeatability. Hybrid systems retain the largest installed base among packaging converters balancing throughput against capital constraints.
EMA medical device regulations and EU Green Deal industrial efficiency frameworks tighten performance verification for machines serving European medical device and automotive supply chains. China's MEE enforces GB standards on factory energy intensity that directly shape procurement criteria for domestic manufacturers. Japan's METI promotes JIS-certified machinery through subsidized upgrade programs for SME molders. Stakeholders must monitor how divergent certification timelines across Brussels, Beijing, and Tokyo reshape equipment replacement cycles and aftermarket service attach rates.
Market Dynamics
Electric sliding unit technology is displacing hydraulic systems across automotive and medical supply chains as energy efficiency mandates tighten procurement criteria in Germany, China, and Japan.
Growth Catalysts
- EU Green Deal industrial efficiency frameworks:Automotive parts manufacturers in Germany are expanding electric sliding unit adoption to meet emissions benchmarks, triggering replacement cycles for legacy hydraulic machines.
- China's Yangtze River Delta cluster concentration:Local MEE enforcement on industrial energy intensity is accelerating machine replacement cycles among domestic molders serving consumer electronics and automotive tier-ones.
- Insert molding process expansion:Medical connector producers are scaling multi-component tooling capacity to integrate metal-polymer geometries for minimally invasive device platforms.
Market Restraints
- High-voltage servo motor input costs:Rare earth magnet price volatility and semiconductor component shortages inflate electric system bill-of-materials by 15-25% versus comparable hydraulic configurations.
- Taiwan-based multi-component tooling supply concentration:Dependency on specialized slide table manufacturers creates lead time vulnerability for automotive lighting producers in European and North American supply chains.
- REACH substance restriction compliance:ECHA scrutiny of lubricant formulations and hydraulic fluid chemistry adds certification friction for European machine importers and retrofitters.
Strategic Opportunities
- India's PLI scheme for medical device manufacturing:Subsidized greenfield molding capacity creation offers first-mover positioning for electric-hybrid system suppliers targeting diagnostic consumable production.
- Overmolding for electric vehicle battery housings:Thermal management insert requirements in EV powertrain architectures are opening new specification windows for high-tonnage sliding clamp configurations.
- Japan's METI subsidized SME upgrade programs:JIS-certified machinery procurement incentives enable premium electric technology penetration among mid-tier automotive component molders.
Industry Challenges
- Multi-axis motion control programming expertise scarcity:Electric sliding unit commissioning and troubleshooting require specialized mechatronics competencies that outpace vocational training pipeline output in mature manufacturing regions.
- Legacy hydraulic system integration complexity:Retrofit electric drives onto existing press frames demands custom mechanical interface engineering that extends deployment timelines and inflates project risk.
- Cross-border GB-to-CE certification timeline compression:Chinese manufacturers exporting to European medical device supply chains face divergent verification protocols that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sliding Injection Molding Machine Market |
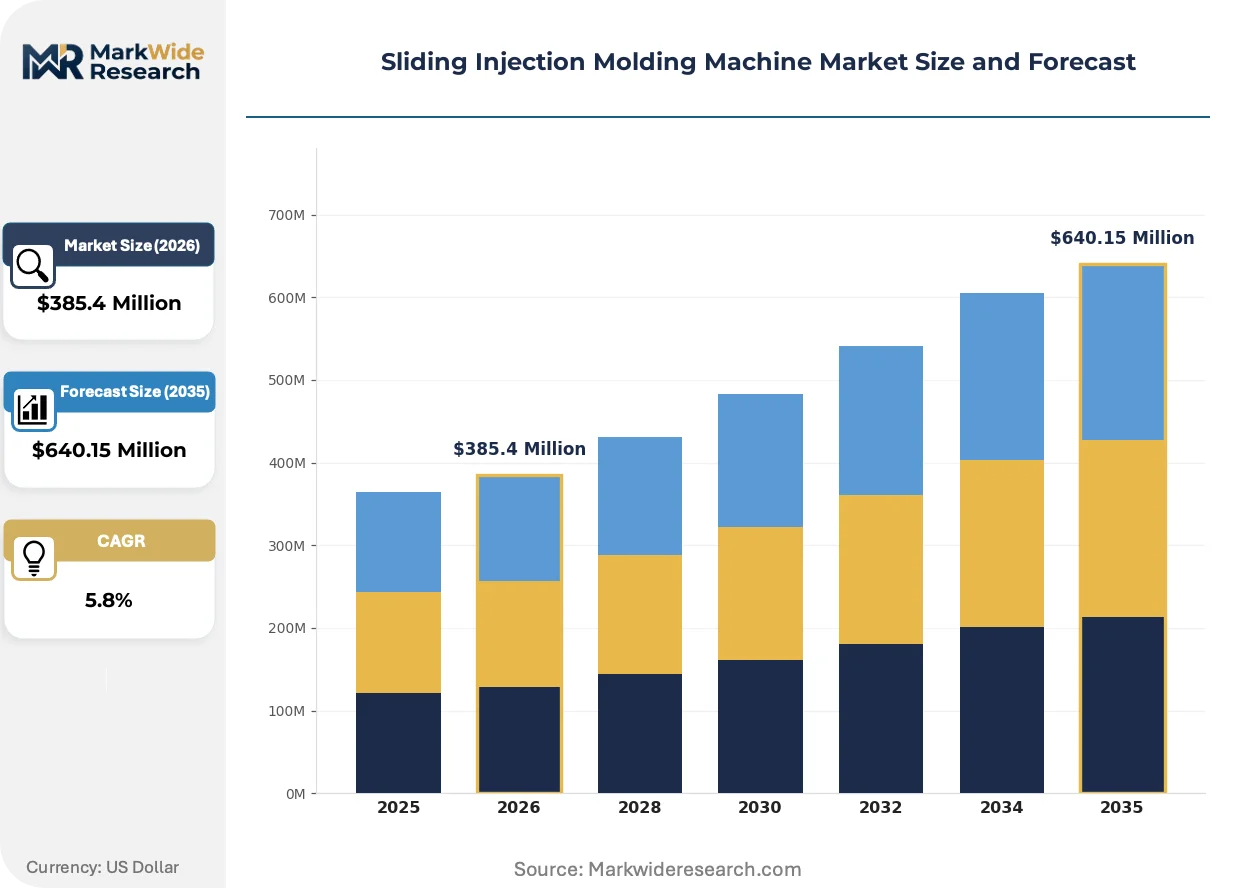
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal, Vertical, Multi-Component, Specialty Application: Automotive Parts, Consumer Goods, Medical Devices, Packaging End User: Manufacturers, OEMs, Suppliers, Distributors Technology: Electric, Hydraulic, Hybrid, Others |
| Companies Covered | Amrut Brothers Machinery Private Limited, Techno Machines India, Pratishna Engineers Ltd., APSX LLC, Multiplas Enginery Co. Ltd, KraussMaffei Group GmbH, Multitech Machinery Ltd., Woojin Plaimm GmbH, Arburg GmbH + Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sliding Injection Molding Machine Market Trends and Innovations
Digital twin simulation and predictive maintenance algorithms are rewriting equipment specification criteria as molders prioritize total cost-of-ownership metrics over upfront capital expenditure.
Closed-loop servo valve control systems are converging with real-time cavity pressure sensing to enable micro-shot precision in medical connector production. Tier-one automotive lighting suppliers in Germany and Japan are piloting these configurations for LED heat-sink overmolding. The technology is converging with cloud-based process fingerprinting to compress qualification timelines for multi-cavity tooling validation.
REACH substance restriction expansions are forcing lubricant formulation changes across European-installed machine bases. ECHA's candidate list updates now cover several hydraulic fluid additive chemistries previously grandfathered under legacy registrations. Medical device molders in Switzerland and Germany are accelerating electric system migration to eliminate fluid containment compliance exposure entirely.
Specification authority is consolidating among automotive OEM central engineering groups, displacing traditional tier-one molder autonomy in machine selection. Battery housing producers now face direct OEM audit of clamping unit energy consumption and cycle repeatability metrics. This concentration is most visible in South Korean and German EV supply chains, where platform standardization mandates are homogenizing equipment procurement across previously independent supplier networks.
Sliding Injection Molding Machine Market Segmentation
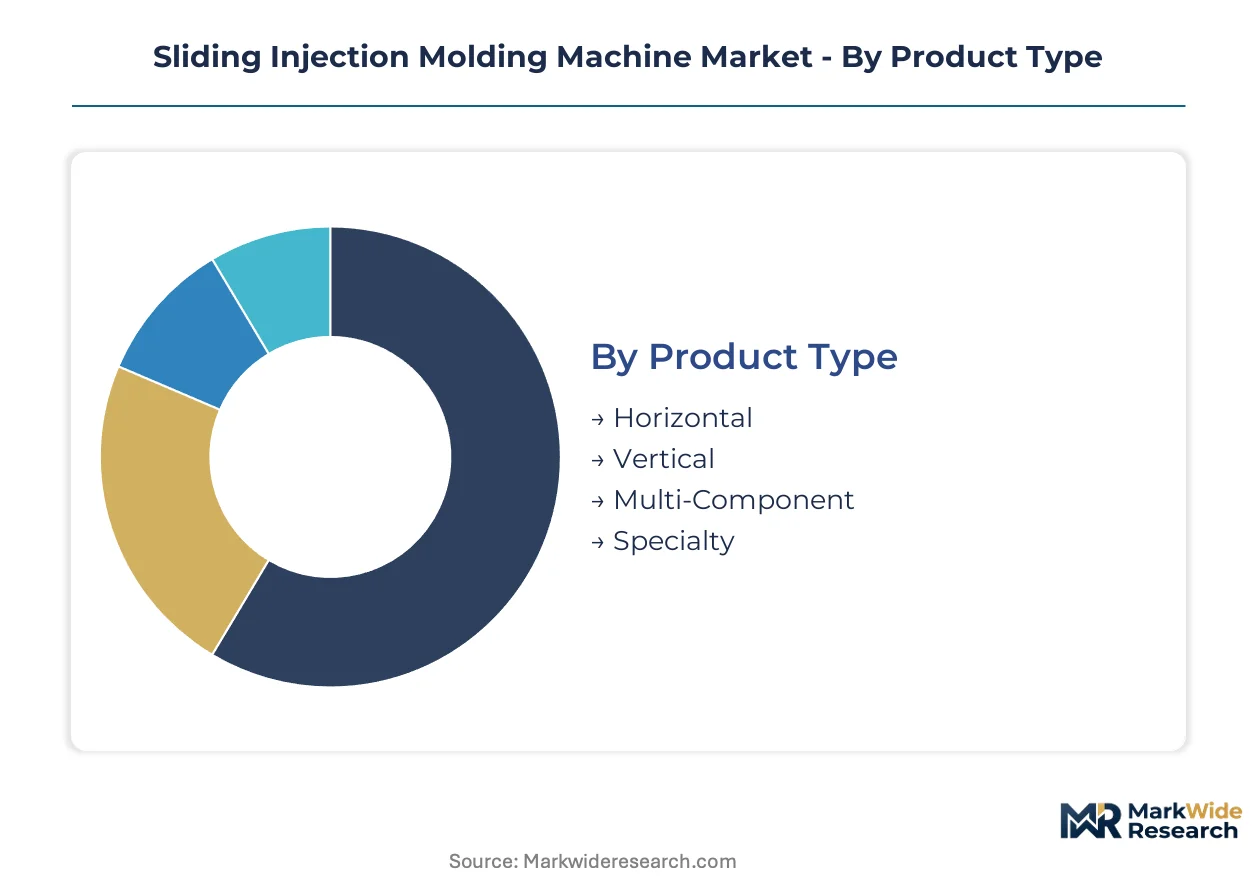
Sliding injection molding machine procurement patterns diverge sharply across product configurations and powertrain technologies, with upgrade cycles in automotive and medical supply chains driving specification fragmentation. End-users now weight energy recovery capabilities and insert molding precision more heavily than initial capital outlay.
Product Type:
Replacement cycles for legacy hydraulic presses are reshaping demand distribution across machine architectures, with automotive tier-ones prioritizing floor-space efficiency and multi-station throughput.
- Horizontal:Dominant configuration for automotive lighting and battery housing production, utilizing transverse clamp movement to accommodate large-part tooling. German and Japanese OEMs specify these units for LED heat-sink overmolding lines where floor-space optimization meets high-tonnage requirements.
- Vertical:Rotary table designs enable gravity-assisted insert placement for medical connector manufacturing. Swiss and German medical device molders favor these configurations for cleanroom compatibility and reduced particulate generation versus horizontal alternatives.
- Multi-Component:Specialized for soft-touch overmolding and hard-soft combinations in consumer electronics housings.
- Specialty:Custom slide table geometries for oversized automotive fascia and complex geometric undercuts.
Horizontal units sit at the top of the volume ranking, with multi-component configurations climbing the fastest on medical device tooling demand.
Application:
Margin structures vary substantially across end-use sectors, with regulatory intensity in medical and automotive segments supporting premium electric system pricing versus commodity packaging converters.
- Automotive Parts:LED lighting modules, battery housings, and interior trim components dominate throughput requirements. EU Green Deal compliance deadlines in Germany are forcing compressed replacement timelines for hydraulic equipment at tier-one suppliers.
- Medical Devices:Minimally invasive surgical platforms and diagnostic consumables demand cavity-pressure sensing integration. EMA device regulations and Swissmedic quality mandates require validated process fingerprinting that electric systems deliver more reliably than hydraulic alternatives.
- Consumer Goods:Personal care packaging and electronics housings balance cycle speed against capital constraints.
- Packaging:High-volume thin-wall containers and closures prioritize throughput over precision, sustaining hybrid system relevance.
Automotive parts generate the largest installed base, though medical devices are expanding most quickly on diagnostic platform growth.
End User:
Procurement authority concentration among central engineering groups is flattening traditional tier distinctions, with OEM direct audits now overriding molder equipment preferences.
- Manufacturers:Contract molders serving multiple end-use sectors face conflicting specification demands from automotive OEMs versus medical device sponsors.
- OEMs:Centralized platform standardization mandates in South Korean and German EV supply chains are homogenizing equipment selection across previously independent supplier networks.
- Suppliers:Tier-two component producers adapt to upstream equipment specifications dictated by OEM audit requirements.
- Distributors:Aftermarket service attach rates and spare parts logistics determine regional market penetration for machine builders.
Manufacturers retain the deepest installed base, while OEM direct procurement is gaining share fastest on platform consolidation.
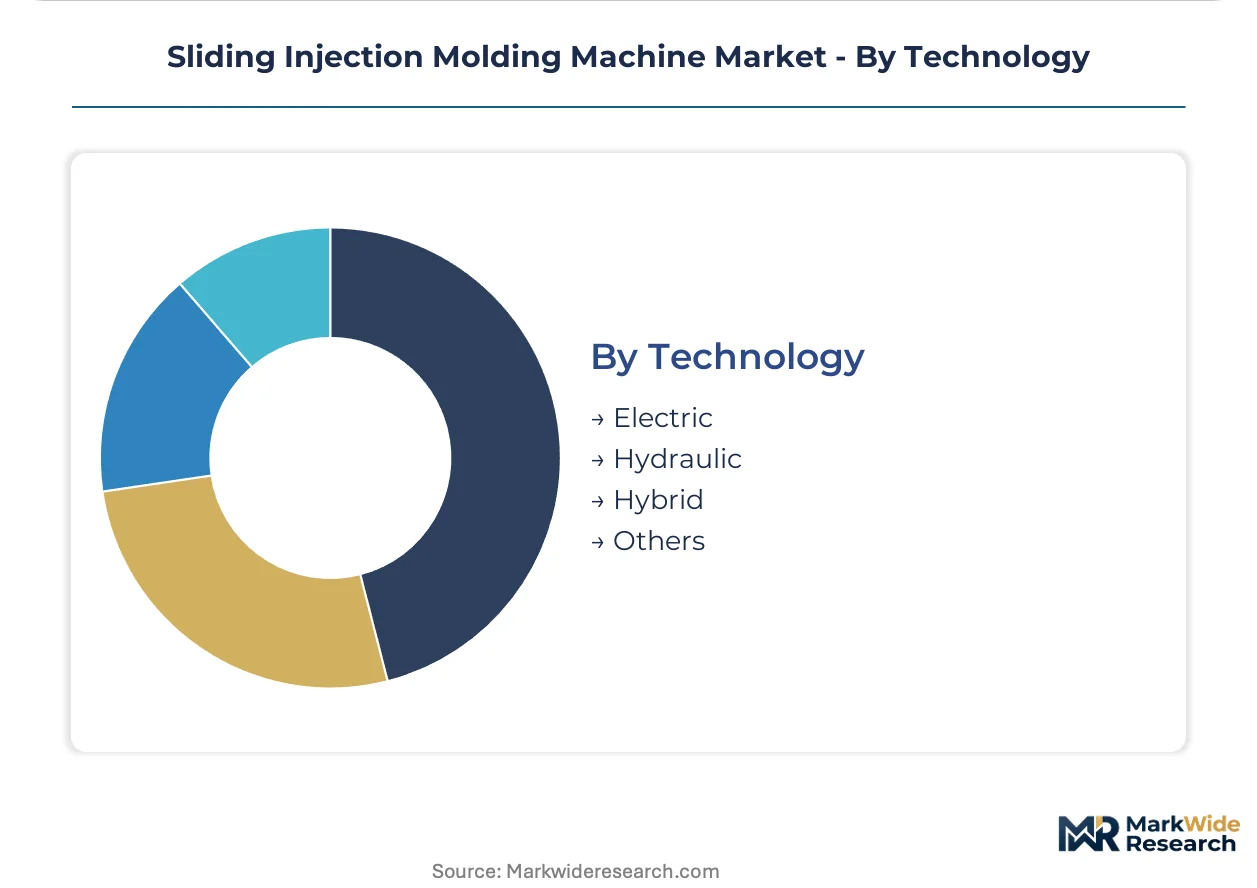
Technology:
Energy efficiency verification protocols in China, Germany, and Japan are segmenting the technology landscape, with electric systems capturing specification authority despite higher upfront capital requirements.
- Electric:Servo motor-driven clamp and injection units deliver precision repeatability and energy recovery capabilities. China's MEE enforcement on factory energy intensity is accelerating adoption among Yangtze River Delta molders serving consumer electronics and automotive export markets.
- Hydraulic:Legacy installed base remains substantial among packaging converters and commodity processors where capital constraints outweigh efficiency mandates.
- Hybrid:Electric screw drive with hydraulic clamping balances precision against tonnage requirements for mid-range automotive applications.
- Others:Pneumatic and mechanical alternatives for specialized low-volume insert molding operations.
Hybrid systems command the largest installed base, with electric technology ascending fastest on regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mechatronics engineers concentrate in Germany's precision machinery corridor, Japan's Nagoya industrial belt, and China's Yangtze River Delta manufacturing hubs, anchoring regional competitive advantages in electric sliding unit development and deployment.
Germany
Automotive tier-one suppliers in Bavaria and Baden-Württemberg drive specification authority for LED heat-sink overmolding lines. EU Green Deal industrial efficiency frameworks compress replacement timelines for legacy hydraulic equipment. Stuttgart and Munich clusters host central engineering groups mandating direct OEM audit of clamping unit energy metrics.
China
Domestic molders in the Yangtze River Delta serving consumer electronics and automotive export markets accelerate electric system procurement. MEE enforcement on factory energy intensity shapes procurement criteria through GB standards compliance windows. Shanghai and Suzhou industrial zones concentrate multi-component tooling capacity for medical connector platforms.
Japan
Mid-tier automotive component molders in Aichi and Shizuoka prefectures access subsidized upgrade pathways for precision machinery. METI promotes JIS-certified machinery through SME-targeted programs reducing capital barriers. Nagoya industrial belt maintains captive R&D infrastructure for electric-hybrid system iteration.
United States
Medical device contract manufacturers in Minnesota and Massachusetts scale diagnostic consumable molding capacity. FDA device regulations and state-level industrial efficiency incentives reshape equipment specification criteria. Twin Cities and Greater Boston clusters concentrate insert molding expertise for minimally invasive surgical platforms.
India
Greenfield medical device manufacturing capacity emerges in Maharashtra and Gujarat under subsidized production incentives. PLI scheme disbursements reduce effective capital costs for electric-hybrid system deployment. Pune and Ahmedabad industrial corridors attract first-mover equipment suppliers targeting diagnostic consumable export markets.
Sliding Injection Molding Machine Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale advantages clash with configurational agility. The vendor base clusters around three strategic archetypes: German precision machinery houses with captive R&D infrastructure, Taiwanese multi-component tooling specialists, and emerging Asian fabricators serving cost-sensitive packaging converters. Consolidation pressure intensifies as automotive OEM central engineering groups concentrate specification authority, while M&A activity targets electric drive competency acquisition and regional service network expansion.
Among German-based precision machinery houses, KraussMaffei Group GmbH and Arburg GmbH + Co KG occupy positions exemplifying premium-tier electric-hybrid development, while Multiplas Enginery Co. Ltd represents the Taiwanese specialist archetype in multi-component tooling systems. These three entities anchor distinct competitive vectors: German players leverage proximity to automotive OEM engineering headquarters, while the Taiwanese specialist captures Asian automotive tier-one supply chain relationships. Each exemplifies how geographic origin and organizational structure shape strategic positioning without guaranteeing segment dominance.
| Leading Market Players |
|---|
| Amrut Brothers Machinery Private Limited |
| Techno Machines India |
| Pratishna Engineers Ltd. |
| APSX LLC |
| Multiplas Enginery Co. Ltd |
| KraussMaffei Group GmbH |
| Multitech Machinery Ltd. |
| Woojin Plaimm GmbH |
| Arburg GmbH + Co KG |
| Others |
Pricing and Supply Chain Analysis
Rare earth magnet feedstocks for high-voltage servo motors trace a cost cascade from Chinese extraction through Taiwanese winding shops to German and Japanese machine builders, stratifying final equipment pricing across premium electric-hybrid, mid-tier hydraulic-electric blends, and legacy all-hydraulic configurations.
Pricing Analysis
Equipment-software bundling separates turnkey electric-hybrid systems with predictive maintenance subscriptions from bare-metal hydraulic presses sold through distributor networks. Certification grade—CE marking for European medical device supply chains versus GB standards for domestic Chinese molders—drives price differentiation between otherwise comparable tonnage ratings. Cost compression in economy-tier hydraulic configurations intensifies as Indian and Southeast Asian fabricators enter packaging converter segments. Medical device OEMs in Switzerland and Germany exhibit lowest price sensitivity, prioritizing cavity-pressure sensing precision and EMA compliance validation over capital outlay.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese slide table manufacturers serving multi-component tooling demand for automotive lighting producers in European and North American supply chains. Critical component sourcing concentrates in China for rare earth magnets, Japan for precision servo motors, and Germany for closed-loop valve control systems. Machine builders draw from these three geographies for electric drive assemblies, creating tariff exposure risk as trade policy shifts affect cross-border component flows. Distribution runs through authorized dealer networks with captive service capabilities rather than pure equipment resale, attaching aftermarket revenue streams to initial hardware placement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance deadlines in Germany compress replacement cycles faster than capital subsidy timelines in India, creating divergent pricing power across otherwise equivalent electric-hybrid specifications.
For Market Incumbents: Extend service attach rates by embedding predictive maintenance algorithms into installed electric units, countering emerging Asian fabricators competing on upfront capital cost alone. Backward integration into rare earth magnet sourcing through offtake agreements with Chinese suppliers mitigates semiconductor component shortage exposure inflating bill-of-materials. Prioritize JIS-certified machinery development for Japan's METI-subsidized SME upgrade pathways. For New Entrants and Emerging Players: Contract molders serving conflicting automotive OEM and medical device sponsor specifications present the most penetrable entry point, as these manufacturers lack unified platform standardization authority. India's PLI-subsidized greenfield medical device capacity in Maharashtra and Gujarat offers first-mover positioning for electric-hybrid system deployment. Partner with diagnostic consumable producers seeking validated process fingerprinting to bypass direct OEM audit barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where electric drive competency scarcity outpaces vocational training pipeline output in mature manufacturing regions. Mid-tier specialists with captive mechatronics programming expertise and established JIS or CE certification pathways represent priority acquisition targets. Watch for inflection when automotive OEM central engineering groups mandate direct supplier audit of clamping unit energy metrics, accelerating displacement of tier-one molder equipment autonomy.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Drive Competency Acquisition | Secures scarce mechatronics programming expertise as EU Green Deal deadlines compress replacement timelines. |
| Regional Service Network Expansion | Captures aftermarket attach rates in Yangtze River Delta clusters where MEE enforcement accelerates machine turnover. |
| JIS Certification Investment | Unlocks METI-subsidized procurement pathways among mid-tier automotive molders in Aichi and Shizuoka prefectures. |
| Predictive Maintenance Platform Launch | Shifts specification criteria toward total cost-of-ownership metrics favoring electric system precision. |
| Multi-Component Tooling Partnership | Mitigates single-source vulnerability to Taiwanese slide table suppliers serving automotive lighting supply chains. |
Research Methodology
Multiple input streams—structured interviews with plant engineers and OEM procurement teams, customs and trade flow databases, SEC and domestic exchange filings—were reconciled against bottom-up equipment shipment tallies and top-down industrial energy intensity benchmarks. Primary engagement captured specification authority shifts among automotive central engineering groups and medical device contract manufacturers. Secondary validation drew from MEE GB standard enforcement disclosures, METI subsidy program documentation, and ECHA REACH candidate list updates affecting lubricant formulation requirements.
Segment-level volume and value estimates across the projection horizon reflect reconciliation of equipment replacement cycle modeling with regulatory compliance deadline clustering. Segmentation dimensions span product architecture, powertrain technology, end-use application, and geographic regulatory framework. CAGR derivation incorporated energy efficiency verification protocol adoption curves, insert molding process expansion rates in minimally invasive surgical platforms, and platform standardization mandate propagation through South Korean and German EV supply chains.
Revisions become necessary when rare earth magnet price volatility exceeds historical bands, when semiconductor component availability constraints extend electric system lead times, or when automotive OEM central engineering groups accelerate direct audit requirements beyond modeled penetration rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Air Cushion Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Multi-Head Filling Machines Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Pallet Drum Filler Capper Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
North America Printing Machinery Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Candy Wrapping Machine Market
Packaging Machinery
Pouch Sealing Machine Market
Packaging Machinery
Sleeve Wrapping Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Tamper Evidence Machinery Market