
 Airless Bottles Market | 2026-2036
Airless Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Airless Bottles Market Outlook
Modular refill-pod configurations is shifting how cosmetic brands specify airless packaging, moving from single-use units toward reusable outer shells with replaceable inner cartridges. Albéa Group leverages its European manufacturing footprint to supply these hybrid systems to prestige skincare houses. AptarGroup anchors its position through pump-engine integration that reduces component count and assembly complexity. Lumson differentiates via in-house decoration capabilities that let beauty brands launch limited-edition finishes without secondary suppliers.
An airless bottle is a sealed dispensing container that isolates product from air exposure through a moving piston or collapsing bag mechanism, typically engineered to pump 98-99% of contents while maintaining vacuum integrity across temperature ranges of 5°C to 40°C. Its primary commercial purpose is extending shelf stability of oxygen-sensitive formulations in cosmetics and pharmaceuticals. Rigid plastic formats dominate current volume due to lower unit costs and established blow-fill-seal compatibility, though aluminum and composite constructions capture disproportionate margin pools in luxury segments where weight and tactile quality command premium positioning. Pump closures lead functional preference across all end-user categories, while twist mechanisms gain traction in travel-size and sampler applications where leak prevention overrides dispensing precision.
FDA stability-testing requirements for pharmaceutical packaging and EPA guidelines on recycled content thresholds shape material selection and validation protocols for airless systems sold in the United States. The EU Packaging and Packaging Waste Regulation, alongside ECHA REACH compliance for monomer migration limits, forces converters to document full material composition and recyclability pathways before market entry. Stakeholders must monitor how evolving extended producer responsibility frameworks in France and Germany reallocate compliance costs between packaging suppliers and brand owners.
Market Dynamics
Refillable mono-material airless systems are forcing converters to reconfigure production lines as premium skincare brands demand oxygen-free dispensing paired with circular packaging credentials.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates accelerate converter investment in post-consumer recycled plastics and aluminum alternatives for airless bottle construction.
- Retinol and vitamin C formulations:Cosmetic formulators in Germany, France, and the United States specify vacuum-dispensing systems to extend shelf stability of oxygen-sensitive actives.
- Modular refill-pod configurations:Prestige skincare houses shift procurement toward reusable outer shells with replaceable inner cartridges, reducing per-unit material intensity.
Market Restraints
- Post-consumer recycled resin supply concentration:Limited qualified PCR plastic supply in Europe creates input cost volatility for converters targeting ECHA REACH compliance.
- Extended producer responsibility frameworks:France and Germany reallocate compliance costs between packaging suppliers and brand owners, compressing margin pools.
- Pharmaceutical validation timelines:FDA stability-testing requirements for oxygen-free dispensing systems extend new product qualification cycles.
Strategic Opportunities
- Aluminum alternative penetration:Luxury segments where weight and tactile quality command premium positioning remain underpenetrated by metal-based airless constructions.
- Travel-size twist mechanisms:Leak-prevention-focused sampler applications represent an emerging functional preference distinct from pump-dominant standard formats.
- Digital printing convergence:In-house decoration capabilities enable beauty brands to launch limited-edition finishes without secondary supplier coordination.
Industry Challenges
- Material composition documentation:ECHA REACH monomer migration limits force converters to map full supply chain chemistry before EU market entry.
- Pump-engine integration complexity:Reducing component count while maintaining vacuum integrity across 5°C to 40°C temperature ranges demands specialized engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airless Bottles Market |
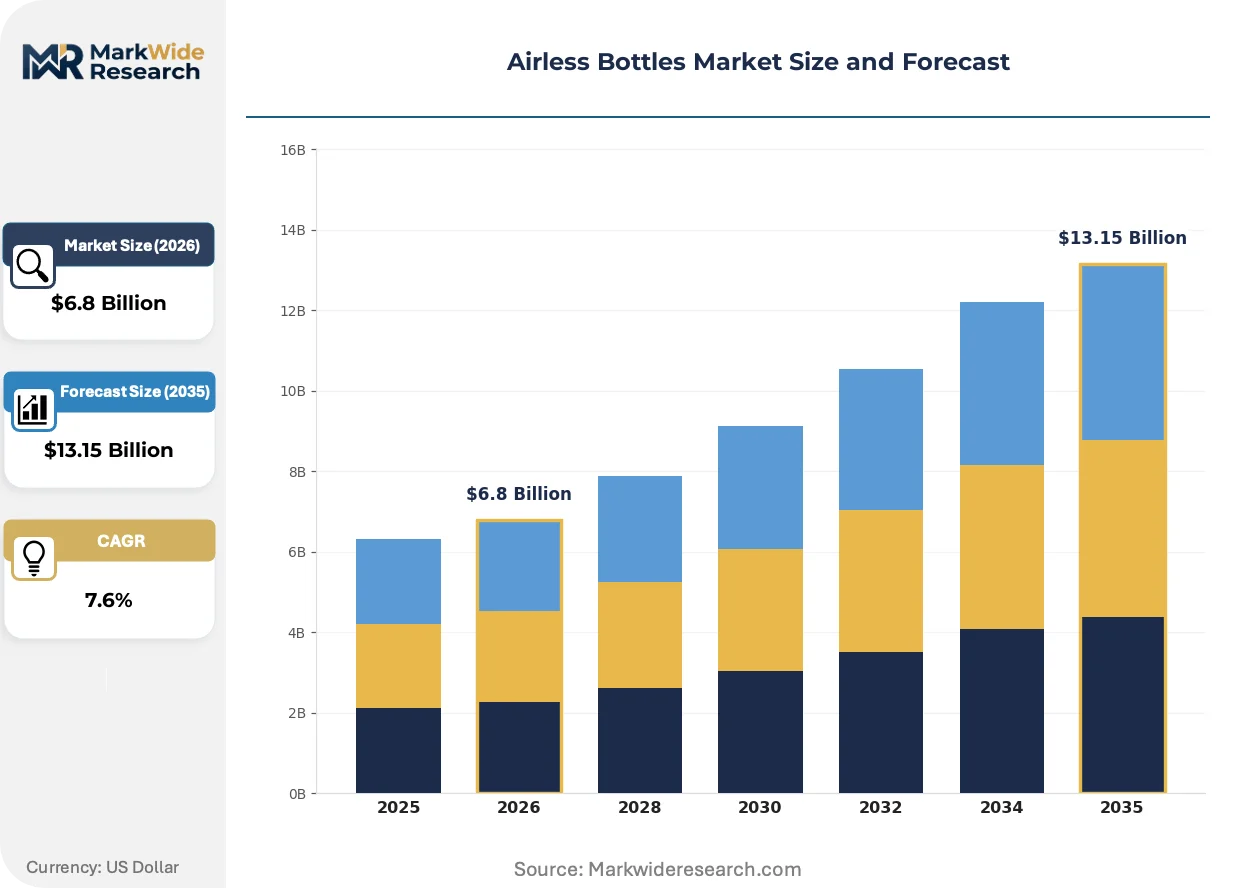
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid, Flexible, Semi-rigid, Customizable Closure Type: Pump, Twist, Snap, Dropper Material: Plastic, Glass, Aluminum, Composite End User: Cosmetic, Pharmaceutical, Personal Care, Food & Beverage |
| Companies Covered | Albéa Group, AptarGroup, Lumson, Silgan Dispensing, HCP Packaging, Quadpack, COSME Packaging, FusionPKG, Raepak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airless Bottles Market Strategic Shifts
Airless packaging technology is pivoting from single-use disposable formats toward closed-loop material systems as regulatory pressure and brand sustainability commitments converge.
Mono-material polypropylene airless bottles are consolidating market share among mass-market cosmetic brands seeking simplified recycling streams. European converters report accelerating qualification timelines for all-PP constructions as brands preempt EPR fee structures. This consolidation is compressing demand for multi-layer barrier films that complicate mechanical recycling.
REACH compliance documentation requirements now mandate full material disclosure for monomer migration limits across all cosmetic packaging entering EU markets. Converters must validate post-consumer recycled content thresholds against ECHA substance restrictions before commercialization. Pharmaceutical-grade airless systems face parallel scrutiny under FDA stability-testing protocols, with dual-registered suppliers absorbing disproportionate compliance overhead.
Beauty brand procurement teams are unbundling decoration from primary packaging supply, awarding separate contracts to converters with captive printing capabilities. This fragmentation disintermediates traditional label suppliers and compresses supplier bases toward vertically integrated manufacturers. Germany and France exhibit the most advanced procurement model evolution, with prestige houses specifying limited-edition finishes directly through primary packaging contracts.
Airless Bottles Market Segmentation
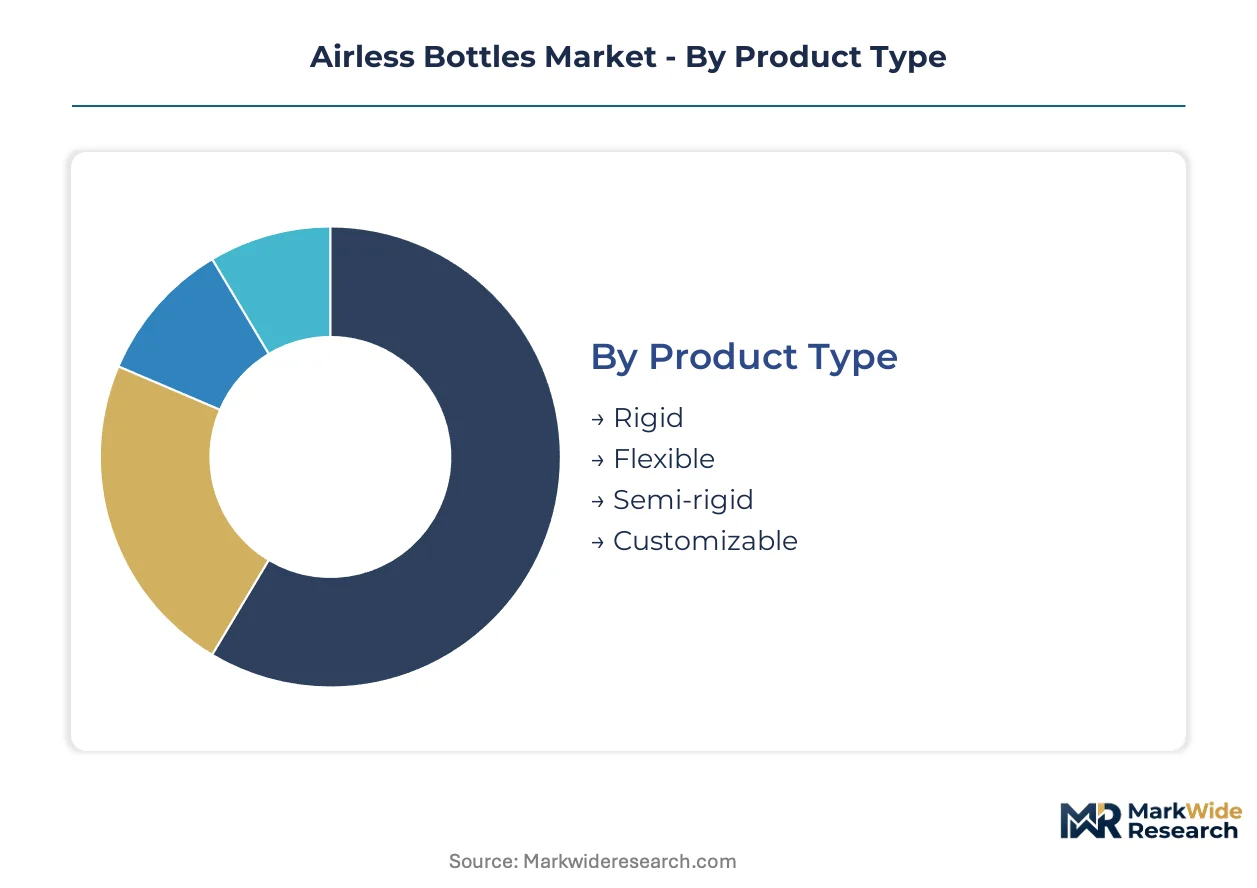
Airless bottle procurement decisions cascade through multiple technical dimensions, with material compatibility and dispensing precision determining qualification for oxygen-sensitive formulations. Brand owners map segment specifications against regulatory requirements and sustainability targets to optimize total cost of ownership across product lifecycles.
Product Type:
Upgrade cycles in airless packaging correlate directly with formulation stability requirements and shelf-life extension demands.
- Rigid:Blow-molded polypropylene or PET constructions maintain dimensional stability across 5°C to 40°C temperature ranges. Cosmetic formulators in Germany and France specify rigid formats for retinol and vitamin C products where vacuum integrity cannot degrade.
- Flexible:Collapsible bag-in-bottle systems eliminate piston friction and enable more complete product evacuation. Pharmaceutical applications in the United States favor flexible constructions for sterile ophthalmic and wound-care formulations where FDA stability-testing protocols apply.
- Semi-rigid:Hybrid constructions balance structural support with material efficiency for mid-tier skincare brands.
- Customizable:Modular architectures accommodate brand-specific geometries and decoration requirements.
Rigid formats sit at the top of the volume ranking, with flexible constructions climbing the fastest as pharmaceutical validation timelines compress.
Closure Type:
Cost tier differentiation separates premium pump mechanisms from economy twist alternatives.
- Pump:Precision-engineered piston or diaphragm actuators deliver metered dosing with 98-99% evacuation efficiency. Prestige skincare houses across North America and Europe anchor procurement specifications on pump-engine integration that reduces component count.
- Twist:Rotating collar mechanisms prioritize leak prevention over dosing precision. Travel-size and sampler applications in the United States specify twist closures where portability overrides dispensing accuracy.
- Snap:Single-use break-seal constructions serve diagnostic and clinical trial applications.
- Dropper:Pipette-style dispensing accommodates high-viscosity serums and oils.
Pump closures dominate the volume ranking, with twist mechanisms gaining share fastest in travel-format segments.
Material:
Application requirements dictate material selection, with oxygen barrier performance and recyclability credentials competing for priority.
- Plastic:Polypropylene and PET dominate mass-market volume due to blow-fill-seal compatibility and lower unit costs. EU Packaging and Packaging Waste Regulation recyclability mandates accelerate converter investment in post-consumer recycled plastic streams.
- Glass:Borosilicate and flint glass constructions deliver inert contact surfaces for pharmaceutical formulations. Luxury cosmetic segments in France specify glass for tactile quality and premium positioning.
- Aluminum:Lightweight metal alternatives capture disproportionate margin pools where weight and recyclability command premium positioning. ECHA REACH compliance documentation requirements complicate qualification timelines for aluminum constructions entering EU markets.
- Composite:Multi-layer barrier films complicate mechanical recycling but serve high-performance oxygen-sensitive applications.
Plastic sits at the top of the volume ranking, with aluminum climbing the fastest as circular packaging credentials reshape procurement criteria.
End User:
Customer type determines validation intensity, with pharmaceutical applications absorbing disproportionate compliance overhead.
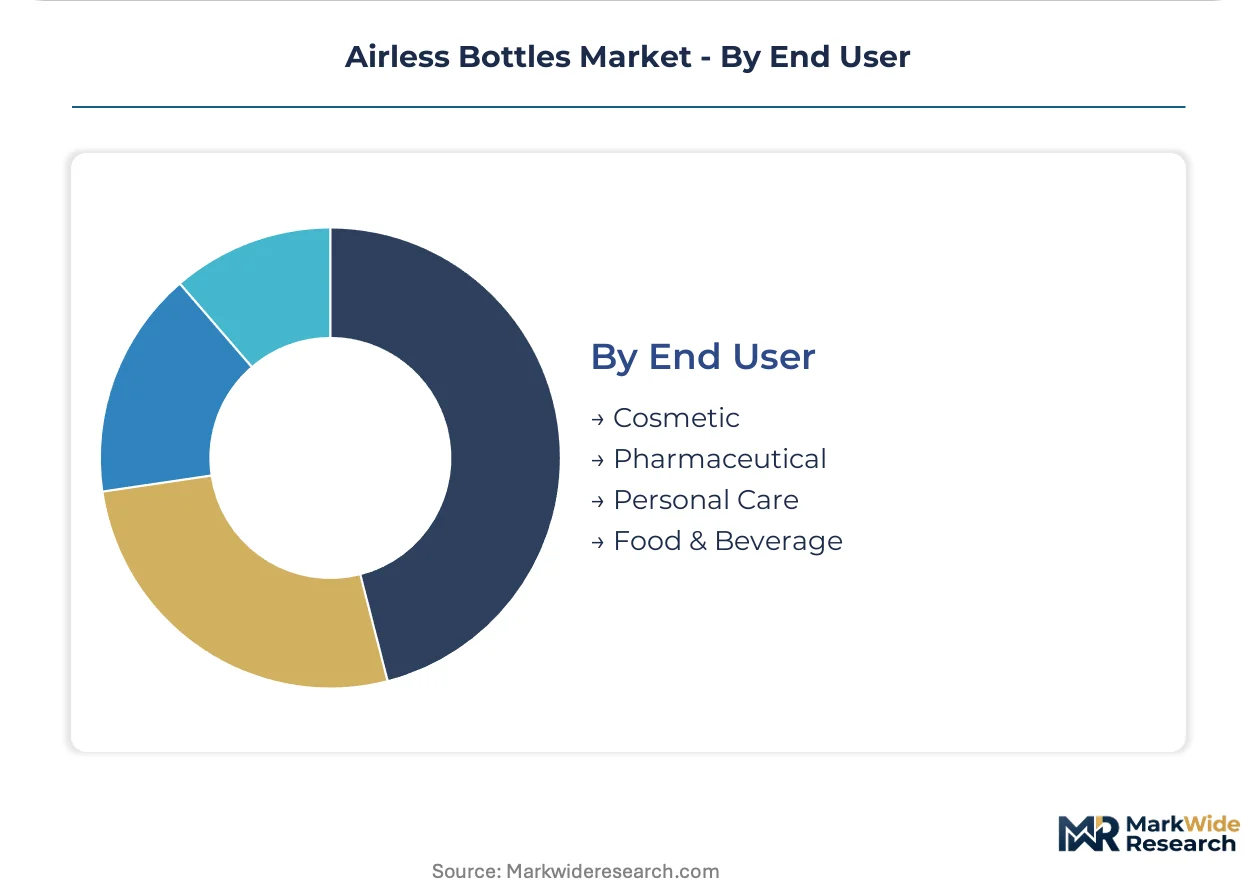
- Cosmetic:Skincare, color cosmetics, and fragrance applications prioritize shelf-life extension for oxygen-sensitive actives. Modular refill-pod configurations are shifting procurement toward reusable outer shells with replaceable inner cartridges.
- Pharmaceutical:Sterile and oxygen-sensitive drug delivery systems face FDA stability-testing requirements that extend new product qualification cycles. Ophthalmic and injectable applications in the United States demand the highest vacuum integrity specifications.
- Personal Care:Sun care, hair care, and oral care formulations balance cost efficiency with functional performance.
- Food & Beverage:Premium sauces, condiments, and nutritional supplements adopt airless technology for oxidation prevention.
Cosmetic applications sit at the top of the volume ranking, with pharmaceutical segments climbing the fastest as oxygen-free dispensing expands beyond traditional skincare boundaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airless bottle technology originated in European pharmaceutical and cosmetic laboratories during the 1980s, with Germany and France pioneering the first commercial vacuum-dispensing systems for oxygen-sensitive formulations. This heritage established technical standards that persist across today's global supply chains.
United States
FDA stability-testing requirements for pharmaceutical packaging drive converter investment in validated oxygen-free dispensing systems. Cosmetic formulators in New Jersey and California specify vacuum integrity for retinol and vitamin C products. Greater Boston hosts contract manufacturing clusters serving ophthalmic and sterile drug delivery applications.
Germany
Extended producer responsibility frameworks reallocate compliance costs between packaging suppliers and brand owners, compressing margin pools. ECHA REACH documentation mandates full material disclosure for monomer migration limits. The Rhine-Ruhr industrial corridor concentrates blow-molding capacity for post-consumer recycled polypropylene airless constructions.
France
Prestige skincare houses in Île-de-France specify modular refill-pod configurations with reusable outer shells. ANSM pharmaceutical packaging guidelines parallel FDA protocols for sterile formulations. The Provence-Alpes-Côte d'Azur region anchors luxury cosmetic manufacturing where aluminum airless alternatives command premium positioning.
China
SAMR cosmetic packaging regulations tighten documentation requirements for imported airless systems entering domestic markets. The Yangtze River Delta concentrates blow-fill-seal manufacturing for mass-market polypropylene formats. Zhejiang and Jiangsu provinces host decoration specialists serving beauty brands with captive printing capabilities.
South Korea
MFDS pharmaceutical packaging standards drive qualification timelines for oxygen-sensitive drug delivery systems. K-beauty export demand accelerates procurement of mono-material recyclable constructions. The Seoul Capital Area clusters formulation R&D facilities specifying vacuum integrity for fermented and active-rich skincare products.
Airless Bottles Market Competitive Environment
Premium-margin players sit above commodity-margin players across decoration capability and pump-engine integration depth, creating a tiered competitive structure. The vendor base organizes around three strategic archetypes: European converters with captive decoration and refill-system expertise, North American specialists in pharmaceutical-grade validation, and Asian fabricators scaling mono-material polypropylene production. Dominant competitive moves include backward integration into pump-engine manufacturing and geographic expansion through distributor partnerships in Southeast Asian beauty markets.
Within the European converter tier, Albéa Group and AptarGroup exemplify vertically integrated positioning, while Lumson occupies a specialist niche through in-house finishing capabilities. These three entities anchor the premium segment where brand-direct relationships and limited-edition production runs determine contract allocation.
| Leading Market Players |
|---|
| Albéa Group |
| AptarGroup |
| Lumson |
| Silgan Dispensing |
| HCP Packaging |
| Quadpack |
| COSME Packaging |
| FusionPKG |
| Raepak |
| Others |
Value Chain & Pricing Dynamics
Specialized polymer engineers in the Rhine-Ruhr corridor anchor European converter operations, with labor-cost differentials between German technical staff and Asian production workers driving 40-60 point spreads between premium and economy tier quotations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with FDA validation grade and decoration complexity serving as primary price differentiation drivers. Pricing pressure stems from EPR fee structures in France and Germany reallocating compliance costs downstream. Mass-market cosmetic brands exhibit highest price sensitivity, while pharmaceutical qualification requirements insulate premium tiers from negotiation intensity.
Supply Chain Analysis
Direct-to-brand channels handle prestige skincare house demand, while distributor networks serve mid-tier personal care manufacturers. Manufacturing concentrates in Germany, France, and China, with blow-molding capacity for polypropylene formats anchored in the Rhine-Ruhr and Yangtze River Delta. Raw material dependencies center on virgin and post-consumer recycled polypropylene resins, aluminum coil stock, and precision pump-engine components. Single-source vulnerability for qualified PCR plastic supply in Europe constitutes the dominant structural risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation operates as a regulatory compounder, with recyclability mandates accelerating converter investment cycles and reshaping procurement specifications across cosmetic and pharmaceutical end-uses.
For Market Incumbents: Lock in captive supply of post-consumer recycled resin streams through long-term offtake agreements with European chemical recyclers. Deepen backward integration into pump-engine manufacturing to reduce component count and defend margin position against modular refill-pod specialists entering from adjacent decoration markets.
For New Entrants and Emerging Players: The mid-tier price gap between aluminum luxury constructions and commodity polypropylene formats presents white-space opportunity. Target pharmaceutical contract manufacturing organizations in the United States seeking secondary qualified suppliers for ophthalmic applications. Enter through digital printing convergence capabilities that disintermediate traditional label suppliers.
For Investors and Strategic Acquirers: Beauty packaging conglomerates are the most active acquirer in this space, consolidating converters with captive decoration and refill-system expertise. Long-term viability hinges on circular packaging credential alignment with EPR framework evolution. Monitor ECHA REACH documentation mandate enforcement intensity as inflection indicator for compliance-cost reallocation between suppliers and brand owners.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material PP Qualification | Accelerates EPR fee optimization for mass-market cosmetic brands in Germany and France. |
| Pump-Engine Backward Integration | Reduces assembly complexity for AptarGroup and Albéa Group prestige skincare contracts. |
| Digital Printing Captive Investment | Enables Lumson to capture limited-edition finish contracts without secondary supplier coordination. |
| Aluminum Alternative Scale-Up | Captures premium positioning in Provence-Alpes-Côte d'Azur luxury cosmetic manufacturing clusters. |
| Pharmaceutical Dual Registration | Absorbs FDA stability-testing overhead for sterile ophthalmic applications in Greater Boston. |
Study Parameters
Bottom-up cosmetic and pharmaceutical formulation modeling reconciled against top-down converter capacity tracking forms the analytical core. Primary interviews with packaging procurement managers at prestige skincare houses, blow-molding plant engineers in the Rhine-Ruhr corridor, regulatory affairs specialists navigating ECHA REACH compliance, and pharmaceutical quality assurance directors shaped demand-side assumptions. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, FDA stability-testing guidance publications, ECHA substance restriction databases, and customs trade data for polypropylene resin flows.
Input-output matrices mapped end-use demand across product type, material composition, closure mechanism, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation against aggregate market boundary conditions. Forecast inputs incorporated EPR fee structure phase-in schedules, PCR plastic supply availability curves, and pharmaceutical validation timeline compression factors across the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for aluminum airless construction qualification would alter the outlook. Forecasts reflect base-case assumptions regarding regulatory enforcement intensity and resin supply chain normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Containers
Logistics Packaging Market
Packaging Containers
Trigger Spray Bottle Market
Packaging Containers
Gable Boxes Market
Packaging Containers
Double Seam Bowl Market
Packaging Containers
Inverted Squeeze Bottle Market
Packaging Containers
North America Food Cans Market
Packaging Containers
Correx Trays Market
Packaging Containers
Monobloc Aerosol Cans Market
Packaging Containers
Wide Mouth Bottles Market
Packaging Containers
Cluster Packaging Market
Packaging Containers
Eyewear Packaging Market
Packaging Containers
Hinged Food Containers Market
Packaging Containers
Latin America Aerosol Cans Market
Packaging Containers
Chalk Boxes Market
Packaging Containers
Bottles Market
Packaging Containers
Acrylic Boxes Market