
 Global Plastic Packaging Sacks Market | 2026-2036
Global Plastic Packaging Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Packaging Sacks Market Outlook
E-commerce fulfillment centers are rotating toward lightweight, puncture-resistant sack formats that reduce dimensional weight charges and last-mile damage rates. Berry Global Inc. leverages vertical integration across resin compounding and blown film extrusion to control cost volatility in polyethylene-based sacks. Mondi competes through specialty kraft-plastic hybrid constructions that target the premium industrial segment. Amcor plc anchors its position with pharmaceutical-grade barrier sacks that meet stringent extractables and leachables standards.
Plastic packaging sacks are flexible containers manufactured from extruded or woven thermoplastic films, typically ranging from 25 to 100 microns in thickness, designed for the containment, protection, and transport of dry bulk materials, powders, and semi-fluid goods across industrial and consumer supply chains. Gusseted bags dominate volume in agricultural produce handling due to their expanded cubic capacity and pallet-stacking stability, while biodegradable plastics represent the fastest-expanding material category as European retailers enforce single-use plastic reduction mandates under the EU Green Deal. Polypropylene woven sacks sustain margin pools in the chemicals sector where UN-certified dangerous-goods compliance commands price premiums over standard polyethylene constructions.
The U.S. FDA regulates food-contact substances under 21 CFR, while the EU REACH framework restricts Substances of Very High Concern in plastic formulations, and India's BIS mandates IS 6192 standards for woven polypropylene sacks used in food grain distribution. These overlapping compliance requirements are fragmenting supplier qualification processes and raising barriers for non-certified regional manufacturers. Stakeholders must monitor evolving extended producer responsibility schemes in Germany, France, and California to anticipate redesign obligations and recyclability targets that will reshape material selection and end-of-life economics.
Market Dynamics
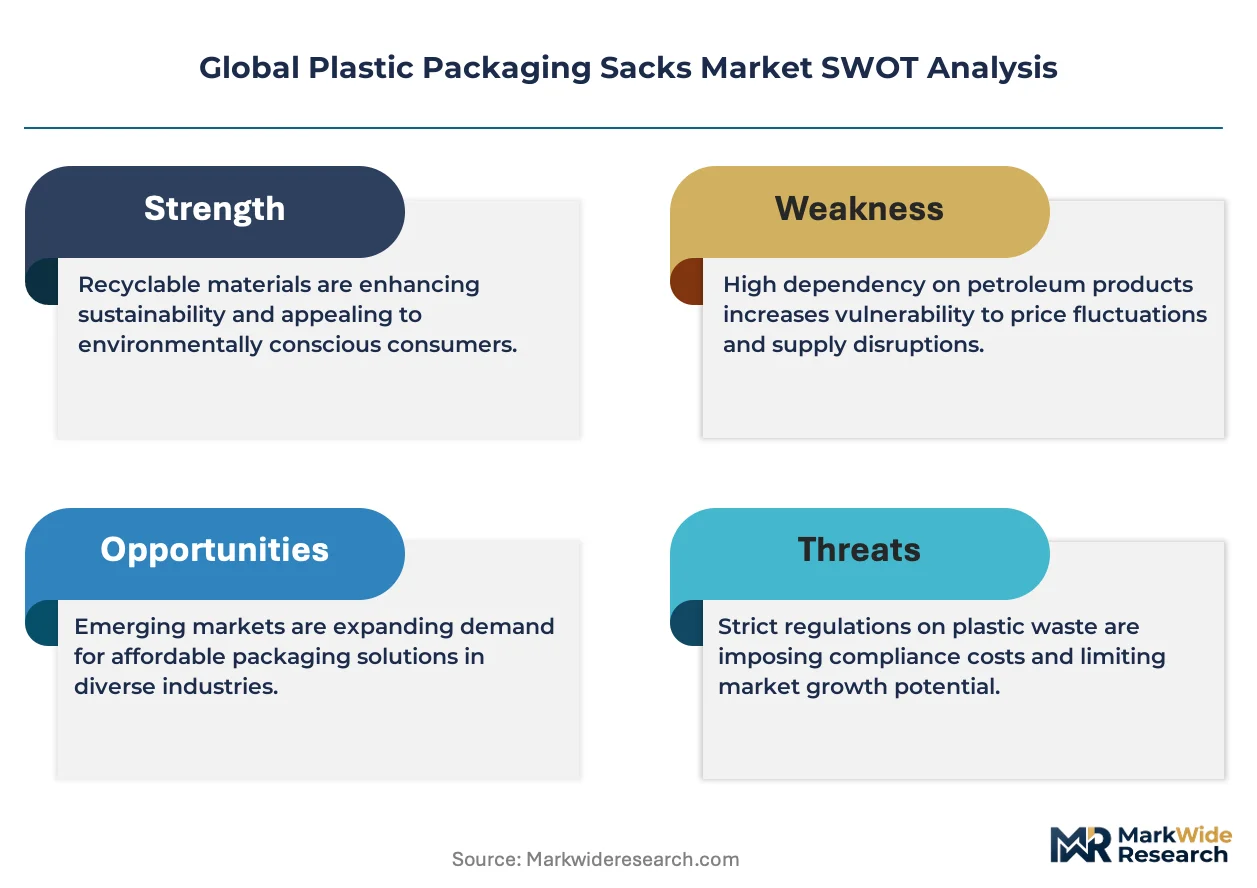
REACH compliance and FDA food-contact standards are compressing material specifications across the plastic packaging sacks value chain, forcing converters to migrate toward certified recyclable resins and documented supply chain traceability.
Growth Catalysts
- Agricultural modernization in India:The FSSAI and BIS standards for food grain distribution are accelerating bulk procurement of woven polypropylene sacks across the country's FMCG and agricultural sectors.
- EU Green Deal mandates:Single-use plastic reduction targets are creating certified demand for biodegradable sack formats in European retail and food service channels.
- E-commerce fulfillment optimization:Lightweight, puncture-resistant sack formats are reducing dimensional weight charges and last-mile damage rates for parcel carriers.
Market Restraints
- Resin price volatility:Polyethylene and polypropylene feedstock costs fluctuate with crude oil indices, squeezing converter margins and complicating long-term contract pricing.
- Supplier concentration in Middle East petrochemicals:A limited set of resin producers controls global polyethylene supply, creating vulnerability to regional production disruptions.
- Mechanical recycling contamination limits:Multi-layer barrier constructions and laminated woven sacks face technical barriers to closed-loop mechanical reprocessing.
Strategic Opportunities
- Pharmaceutical barrier compliance:Extractables and leachables testing protocols create premium positioning for sack converters with validated cleanroom production and documented polymer purity.
- Extended producer responsibility schemes:Germany's Verpackungsgesetz and France's AGEC law are mandating recyclability targets that favor suppliers with established take-back infrastructure.
- Hybrid kraft-plastic constructions:Specialty paper-polymer laminates address premium industrial segments seeking reduced plastic visibility without sacrificing moisture protection.
Industry Challenges
- Cross-jurisdictional certification complexity:Simultaneous compliance with FDA 21 CFR, EU REACH SVHC restrictions, and India's IS 6192 standards fragments supplier qualification processes and extends onboarding timelines.
- Recyclability testing and labeling standardization:Divergent protocols between APR, RecyClass, and national eco-labeling schemes create uncertainty in material selection and marketing claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Packaging Sacks Market |
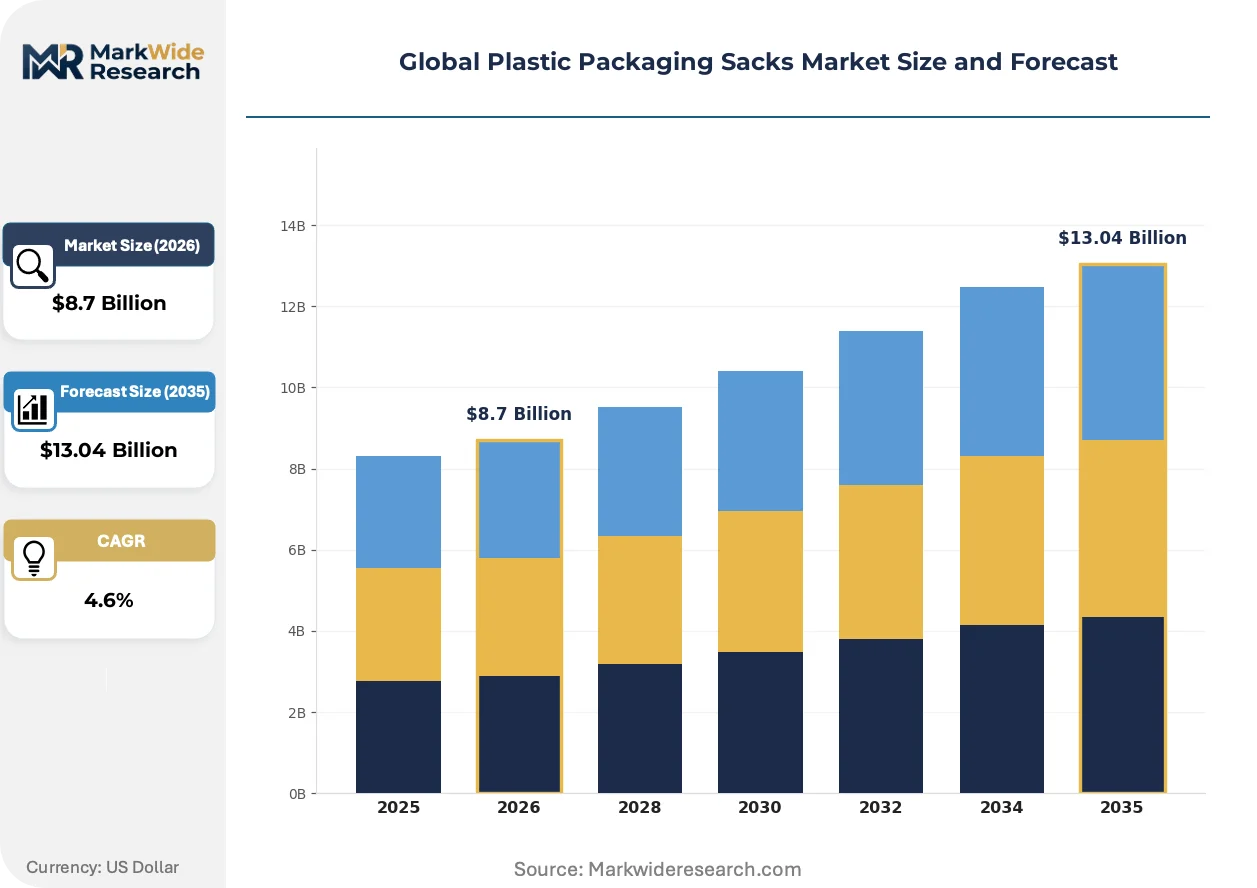
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Pouch Bags, Liner Bags End User: Food & Beverage, Chemicals, Agriculture, Pharmaceuticals Material: Polyethylene, Polypropylene, Polyester, Biodegradable Plastics Application: Retail, Industrial Packaging, Agricultural Produce, Waste Management |
| Companies Covered | Berry Global Inc., Mondi, Amcor plc, Inteplast Group, Smurfit Kappa, Novolex, Bischof+Klein SE & Co. KG, ProAmpac, Starlinger & Co Gesellschaft m.b.H., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Packaging Sacks Market Strategic Shifts
Material science advances and regulatory stringency are converging to reshape competitive positioning across sack formats, with sustainability credentials and barrier performance becoming inseparable purchase criteria.
Monomaterial polyethylene constructions with enhanced oxygen and moisture barriers are supplanting multi-layer laminated alternatives in frozen food and dry goods applications. Major European retailers are accelerating qualification timelines for these formats to meet 2025 recyclability commitments. The shift is compressing demand for conventional nylon-EVOH coextrusions while expanding resin compounding capabilities among integrated converters.
California's SB 54 extended producer responsibility framework is mandating 30% post-consumer recycled content thresholds for plastic packaging by 2028, with enforcement through CalRecycle certification. Food-contact sack manufacturers are responding by securing FDA letters of no objection for mechanically recycled polyethylene streams and redesigning formulations to accommodate PCR resin variability. The pharmaceutical and infant nutrition segments remain exempt but face parallel pressure through corporate ESG procurement policies.
Direct sourcing relationships between agricultural cooperatives and sack converters are displacing traditional distributor intermediaries in grain and produce supply chains. Large Indian farming collectives now negotiate specification-grade woven polypropylene contracts with integrated manufacturers, capturing cost advantages and quality consistency. This channel compression is most pronounced in Maharashtra and Punjab, where organized procurement accounts for expanding share of national food grain packaging volume.
Global Plastic Packaging Sacks Market Segmentation
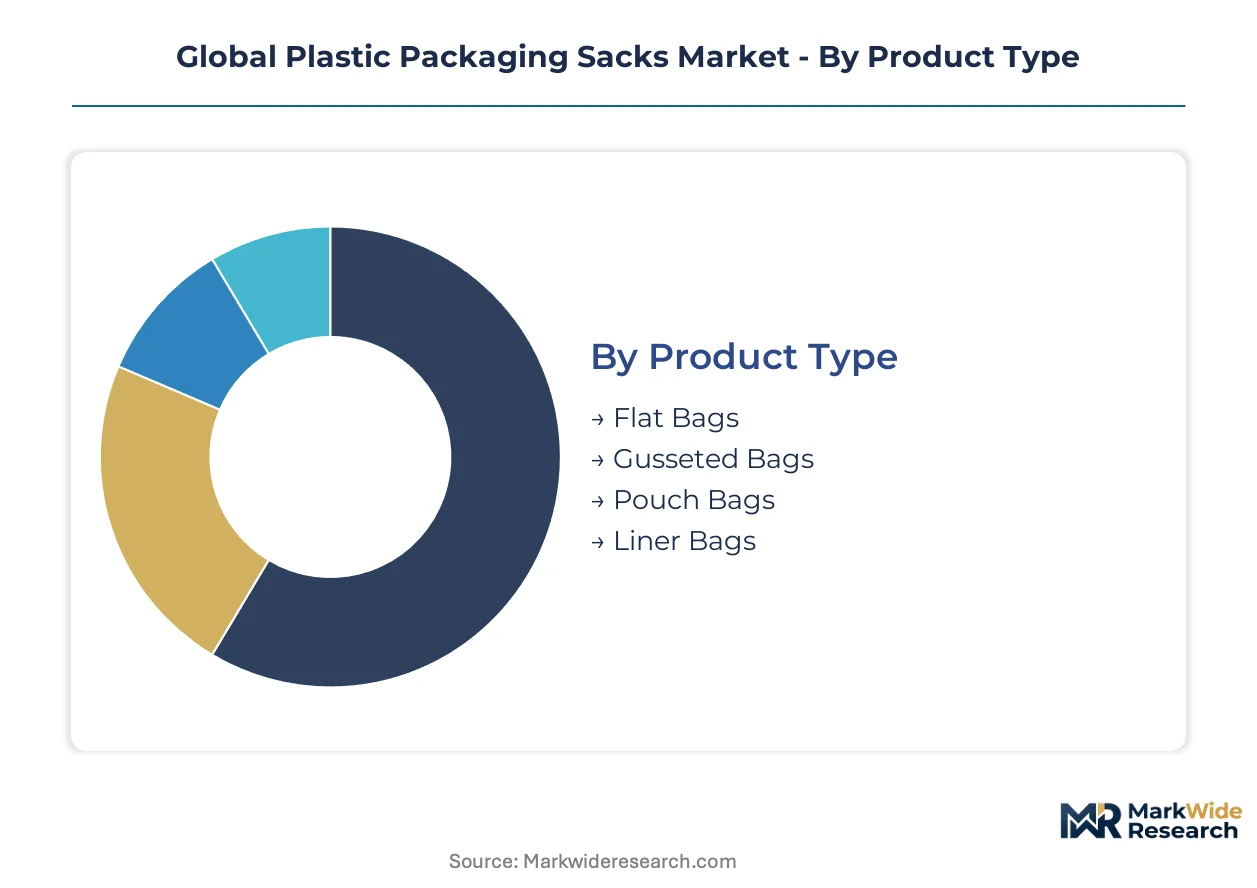
Segmentation in plastic packaging sacks reveals how functional requirements, regulatory pressures, and end-use specifications fragment demand across incompatible technical specifications. Understanding these divisions exposes where converters can defend margin pools and where commoditization erodes pricing power.
Product Type:
Domestic consumption dominates flat bag and liner bag segments in North American and European markets, while gusseted and pouch formats command substantial export volumes to agricultural economies in South Asia and sub-Saharan Africa.
- Flat Bags:Simple two-seam constructions from single-ply polyethylene or polypropylene film serve high-volume, low-specification applications. Demand concentrates in North American retail distribution for dry goods and hardware, where FDA 21 CFR compliance for food contact drives material selection toward certified virgin resins.
- Gusseted Bags:Side-folded designs expand cubic capacity and improve pallet stability for bulk agricultural handling. Maharashtra and Punjab farming collectives in India procure specification-grade woven polypropylene gusseted formats directly from integrated manufacturers, bypassing traditional distributor channels.
- Pouch Bags:Stand-up configurations with resealable closures target premium consumer goods. European retailers enforce EU Green Deal recyclability mandates that favor monomaterial polyethylene pouch constructions over multi-layer alternatives.
- Liner Bags:Form-fit inserts protect bulk containers and intermediate bulk containers from moisture and contamination. Chemical sector demand in Germany requires UN-certified dangerous-goods compliance that commands substantial price premiums over standard constructions.
Gusseted bags hold the largest share; momentum sits with pouch bags as European retail channels accelerate qualification timelines for recyclable formats.
End User:
Cost tier stratification separates pharmaceutical and food-grade specifications—where extractables testing and traceability documentation justify premium pricing—from agricultural and chemical segments where volume scale compresses unit economics.
- Food & Beverage:High-barrier sack formats for frozen products and dry goods require oxygen and moisture protection. FDA food-contact regulations and EU REACH SVHC restrictions are tightening material specifications and accelerating migration toward certified recyclable resins.
- Chemicals:UN-certified woven polypropylene sacks transport hazardous materials under strict dangerous-goods protocols. Middle East petrochemical suppliers concentrate global polyethylene supply, creating vulnerability to regional production disruptions that ripple through chemical sector procurement.
- Agriculture:India's BIS mandates IS 6192 standards for woven polypropylene sacks in food grain distribution. Rapid FMCG sector expansion and agricultural modernization are driving bulk procurement across the country's organized farming collectives.
- Pharmaceuticals:Barrier sacks must meet stringent extractables and leachables standards with validated cleanroom production. California's SB 54 extended producer responsibility framework mandates post-consumer recycled content thresholds that pharmaceutical manufacturers navigate through corporate ESG procurement policies.
Food & Beverage commands the greatest volume; Pharmaceuticals delivers the steepest expansion trajectory as barrier compliance requirements intensify.
Material:
Supply concentration in Middle East petrochemicals shapes polyethylene and polypropylene availability, while biodegradable alternatives depend on European compounding capacity and agricultural feedstock supply chains.
- Polyethylene:Blown film extrusions dominate flexible packaging with tunable density grades from LDPE to HDPE. E-commerce fulfillment centers specify lightweight, puncture-resistant polyethylene sacks to reduce dimensional weight charges and last-mile damage rates.
- Polypropylene:Woven constructions deliver tensile strength for agricultural and chemical bulk handling. India's FSSAI and BIS standards accelerate domestic procurement of specification-grade woven sacks for food grain distribution.
- Polyester:Higher melting point and dimensional stability serve specialized industrial applications. Limited adoption reflects cost positioning against commodity polyolefins in standard sack formats.
- Biodegradable Plastics:Starch-based and polylactic acid formulations address EU Green Deal single-use plastic reduction mandates. European retailers enforce certified demand for biodegradable sack formats in retail and food service channels.
Polyethylene retains dominant share; biodegradable plastics are gaining share fastest as regulatory mandates harden across European markets.
Application:
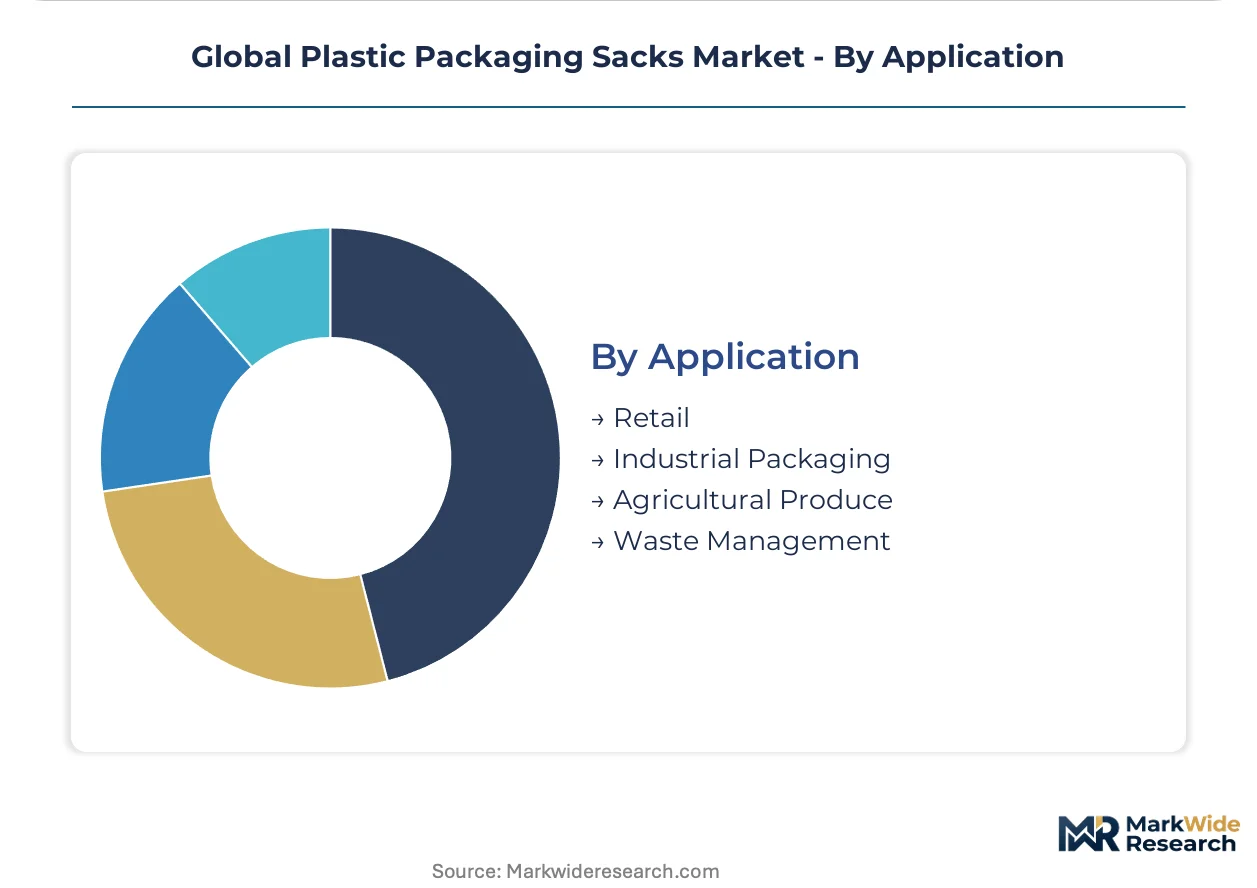
Customer type divergence separates industrial procurement—driven by total cost of ownership and compliance documentation—from retail and agricultural channels where visual presentation and handling efficiency shape purchasing decisions.
- Retail:Consumer-facing formats prioritize shelf appeal and resealability. Germany's Verpackungsgesetz and France's AGEC law mandate recyclability targets that favor suppliers with established take-back infrastructure.
- Industrial Packaging:Bulk containment for powders and semi-fluid goods demands consistent seal integrity and stack strength. California's SB 54 mandates 30% post-consumer recycled content thresholds that industrial users meet through mechanically recycled polyethylene streams with FDA letters of no objection.
- Agricultural Produce:Ventilated woven sacks preserve crop quality during extended storage. Direct sourcing relationships between Indian agricultural cooperatives and sack converters displace traditional distributor intermediaries in Maharashtra and Punjab.
- Waste Management:Heavy-duty constructions handle construction debris and municipal collection. Multi-layer barrier constructions face technical barriers to closed-loop mechanical reprocessing that complicate end-of-life economics under extended producer responsibility schemes.
Industrial Packaging captures the greatest revenue concentration; Agricultural Produce shows the strongest volume momentum as Indian modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock concentration in the Middle East and Gulf Coast shapes resin availability for sack converters worldwide. India, Germany, the United States, China, and Brazil each exhibit distinct demand drivers and regulatory pressures that fragment procurement patterns across the value chain.
United States
E-commerce fulfillment networks in California and Texas drive specification of lightweight polyethylene sacks that reduce dimensional weight charges. FDA 21 CFR food-contact standards and California's SB 54 extended producer responsibility framework mandate 30% post-consumer recycled content thresholds by 2028. The Gulf Coast petrochemical corridor supplies virgin polyethylene resin to domestic blown film extruders.
Germany
Industrial chemical packaging demands UN-certified dangerous-goods compliance for woven polypropylene sacks transporting hazardous materials. The Verpackungsgesetz extended producer responsibility scheme mandates recyclability targets and established take-back infrastructure obligations. The Rhine-Ruhr industrial cluster hosts integrated converters serving pharmaceutical and chemical sector procurement.
India
Rapid FMCG sector expansion and agricultural modernization in Maharashtra and Punjab drive bulk procurement of woven polypropylene sacks for food grain distribution. FSSAI and BIS IS 6192 standards regulate food-contact specifications and accelerate organized procurement through farming collectives. Direct sourcing relationships between agricultural cooperatives and integrated manufacturers displace traditional distributor channels.
China
Domestic e-commerce logistics and export manufacturing sustain high-volume demand for polyethylene flat bags and gusseted formats. GB standards and MIIT industrial policies shape material specifications for food-contact and industrial applications. The Yangtze River Delta concentration of blown film extruders supplies both domestic retail channels and export markets.
Brazil
Agricultural commodity exports and domestic food distribution networks consume woven polypropylene sacks for grain and produce handling. ANVISA pharmaceutical regulations and evolving packaging waste policies create compliance complexity for multinational converters. The São Paulo industrial corridor hosts thermoplastic film manufacturing serving South American agricultural and consumer goods sectors.
Global Plastic Packaging Sacks Market Competitive Environment
Concentration sits with integrated petrochemical-to-film converters and specialty barrier specialists that control resin compounding capabilities. The vendor base separates into three tiers: multinational integrated players with captive resin supply, regional specialists in certified food-contact or pharmaceutical formats, and commodity converters competing on volume scale. Strategic moves center on backward integration into resin compounding and geographic expansion through distributor acquisition in high-growth agricultural economies.
Within the integrated multinational tier, Berry Global Inc., Mondi, and Amcor plc exemplify archetypes that span resin compounding through finished sack production. Berry Global Inc. represents North American vertical integration models controlling polyethylene supply chains. Mondi occupies a position bridging European kraft-paper heritage with thermoplastic film capabilities. Amcor plc anchors pharmaceutical-grade barrier specialization with validated cleanroom production protocols. These three entities sit within distinct geographic and technical positioning vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Berry Global Inc. |
| Mondi |
| Amcor plc |
| Inteplast Group |
| Smurfit Kappa |
| Novolex |
| Bischof+Klein SE & Co. KG |
| ProAmpac |
| Starlinger & Co Gesellschaft m.b.H. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day resin inventory buffers among Gulf Coast converters amplify pricing leverage when Middle East supply disruptions compress spot polyethylene availability. This lead-time exposure concentrates margin pressure on non-integrated sack manufacturers who lack captive resin compounding capabilities.
Pricing Analysis
California's SB 54 dictates the pricing tier structure across food-contact sack segments, separating FDA-validated recyclable resin formulations from standard virgin polyethylene constructions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in standard-grade woven polypropylene is intensifying because Indian agricultural cooperatives consolidate procurement through direct sourcing contracts. Chemical sector buyers exhibit lowest price sensitivity due to UN-certified dangerous-goods compliance requirements, while retail distributors face acute margin pressure from e-commerce dimensional weight optimization mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate among European converters anticipating REACH SVHC restriction updates, while just-in-time resin procurement persists in North American e-commerce fulfillment channels. Feedstock supply concentrates in Saudi Arabia, Qatar, and the United States Gulf Coast, with blown film extrusion capacity clustering in Germany, China, and India. Manufacturing draws from polyethylene pellets, polypropylene resin, and calcium carbonate masterbatch inputs. Single-source vulnerability in Middle East petrochemical supply creates exposure to regional production disruptions. Distribution runs through integrated converter-direct relationships with agricultural cooperatives and pharmaceutical contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market exhibits cyclical recovery characteristics as resin price volatility moderates from peak crude oil index correlation and converter margins stabilize across the forecast window.
For Market Incumbents: Compound barrier technology advantages through validated cleanroom production expansion for pharmaceutical-grade extractables compliance. Accelerate backward integration into resin compounding capabilities to neutralize feedstock cost volatility. Secure BIS IS 6192 certification infrastructure ahead of Indian agricultural procurement consolidation.
For New Entrants and Emerging Players: Anchor in biodegradable sack formats for European retail channels where EU Green Deal mandates outpace incumbent qualification timelines. Target Maharashtra and Punjab farming collectives with specification-grade woven polypropylene direct contracts. Deploy hybrid kraft-plastic construction expertise as differentiated entry vector against commodity polyethylene competition.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-cap regional converters with established FDA food-contact validation and underutilized blown film extrusion capacity. Long-term viability hinges on recyclability infrastructure ownership and extended producer responsibility scheme participation. Monitor California CalRecycle certification thresholds as inflection indicator for post-consumer recycled content compliance economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Gulf Coast and European converters secure captive polyethylene supply against Middle East production volatility. |
| Pharmaceutical Cleanroom Validation Expansion | Extractables and leachables testing protocols command premium pricing from Amcor plc and specialized barrier manufacturers. |
| Biodegradable Format Qualification Acceleration | European retailers enforce EU Green Deal recyclability mandates favoring starch-based and polylactic acid sack constructions. |
| Direct Sourcing Relationship Development | Indian agricultural cooperatives in Maharashtra and Punjab displace distributor intermediaries for woven polypropylene procurement. |
| Post-Consumer Recycled Content Certification | California SB 54 mandates 30% PCR thresholds requiring FDA letters of no objection for mechanically recycled polyethylene streams. |
Study Parameters
The analysis maps polyethylene flat bags, gusseted woven sacks, pouch formats, and liner constructions, each validated through procurement managers at agricultural cooperatives, chemical logistics operators, pharmaceutical quality directors, and retail category buyers. Primary interviews with blown film extrusion plant managers and resin compounding technical leads combined with secondary validation from FDA 21 CFR filings, EU ECHA SVHC restriction updates, Indian BIS IS 6192 standards documentation, and customs trade data. Bottom-up volume modeling across end-use segments triangulated against top-down petrochemical feedstock consumption patterns.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from segment-level demand elasticity analysis and resin price trajectory assumptions. Forecast inputs incorporated e-commerce dimensional weight charge evolution, extended producer responsibility scheme implementation timelines, and agricultural modernization procurement patterns.
Material uncertainties — crude oil index volatility, REACH SVHC restriction expansion, and mechanical recycling contamination technical barriers — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement continuity and resin supply concentration stability. Revision becomes warranted when Middle East petrochemical production disruption frequency crosses thresholds sufficient to trigger sustained spot price divergence from contract benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
Packaging Industry in South Africa Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Cast Stretch Films Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
Plastic-Based Egg Packaging Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
North America PET Bottle Market
Plastic Packaging
Plastic Films Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Thailand Rigid Plastic Packaging Market
Plastic Packaging
Plastic T-Shirt Bags Market