
 Global Bespoke Packaging Market | 2026-2036
Global Bespoke Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bespoke Packaging Market Analysis
Direct-to-consumer subscription brands is bifurcating demand away from traditional retail-led procurement in the bespoke packaging space. DS Smith Plc leverages its fiber-based R&D pipeline to dominate sustainable luxury applications. WestRock anchors North American corrugated customization through integrated design-to-delivery infrastructure. Packhelp competes on digital-first tooling that collapses minimum order quantities for mid-tier cosmetics entrants.
Bespoke packaging denotes custom-engineered primary and secondary enclosures fabricated to dimensional, graphic, and structural specifications unique to a single brand or SKU, typically involving die-cut fiberboard, molded pulp, or thermoformed substrates with print embellishments such as foil stamping or soft-touch lamination. Its commercial purpose centers on unboxing experience differentiation, theft deterrence, and supply chain right-sizing for irregular product geometries. Paper-based substrates lead by volume across boxes and wraps, while plastic pouches represent the fastest-growing material-format intersection driven by barrier requirements in cosmetics and pharmaceuticals. Complex and custom design tiers concentrate margin pools due to extended creative development cycles and dedicated tooling amortization.
The EPA governs emissions from coating and adhesive operations in US-based converting facilities, while REACH and the EU Green Deal restrict certain plasticizers and mandate recyclability disclosures for packaging placed on European markets. China's MEE enforces wastewater and VOC standards at printing and lamination plants, raising compliance costs for export-oriented converters. Stakeholders must monitor evolving extended producer responsibility frameworks and material-specific bans to anticipate substrate substitution timelines and capital reallocation needs.
Market Dynamics
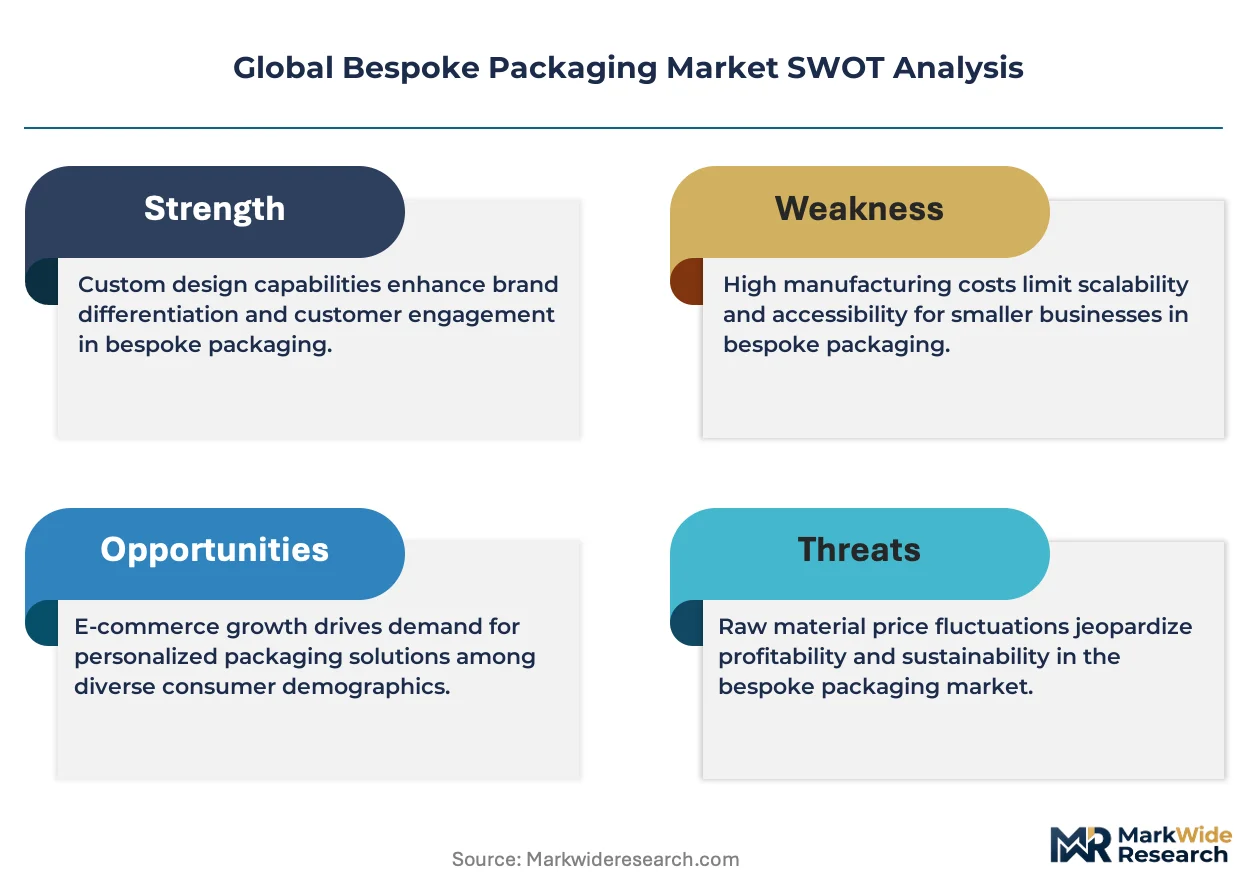
Direct-to-consumer subscription models are fragmenting procurement volumes across thousands of micro-orders, forcing converters to retool for batch-size-one economics while EU Green Deal mandates accelerate substrate transitions.
Growth Catalysts
- REACH plasticizer restrictions:European converters are pivoting to fiber-based mono-materials ahead of 2030 recyclability mandates, opening capacity for premium cosmetic applications.
- Luxury cosmetics clustering:Germany's Rhine-Ruhr and China's Yangtze River Delta concentration of prestige beauty brands generates localized demand for complex structural packaging with foil embellishments.
- Digital print embellishment:UV-cured inkjet systems now execute variable-data soft-touch coatings at production speeds, collapsing the cost gap between mass-customized and static print runs.
Market Restraints
- Pulp price volatility:Kraft linerboard input costs swing with Nordic softwood supply disruptions, compressing margins on fiber-based luxury boxes.
- Tooling amortization thresholds:Die-cut fiberboard molds require minimum runs that exclude emerging indie beauty brands from complex structural formats.
- China MEE VOC enforcement:Lamination and coating plants in Guangdong face wastewater discharge limits that extend lead times for export orders.
Strategic Opportunities
- India PLI scheme for packaging:Domestic manufacturing incentives for advanced materials could capture diverted volume from China-plus-one sourcing strategies.
- Pharmaceutical cold-chain bespoke:Temperature-validated molded pulp insulation for biologics shipments represents an underpenetrated application with high certification barriers.
- Reusable secondary packaging:Return-loop systems for DTC subscription boxes align with EU Green Deal circular economy targets while locking in multi-year brand relationships.
Industry Challenges
- Structural design talent scarcity:Die engineering expertise for complex fiberboard geometries concentrates in legacy German and Japanese tooling houses, limiting converter scaling.
- Multi-substrate certification timelines:FDA and EMA validation for pharmaceutical-grade bespoke formats extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bespoke Packaging Market |
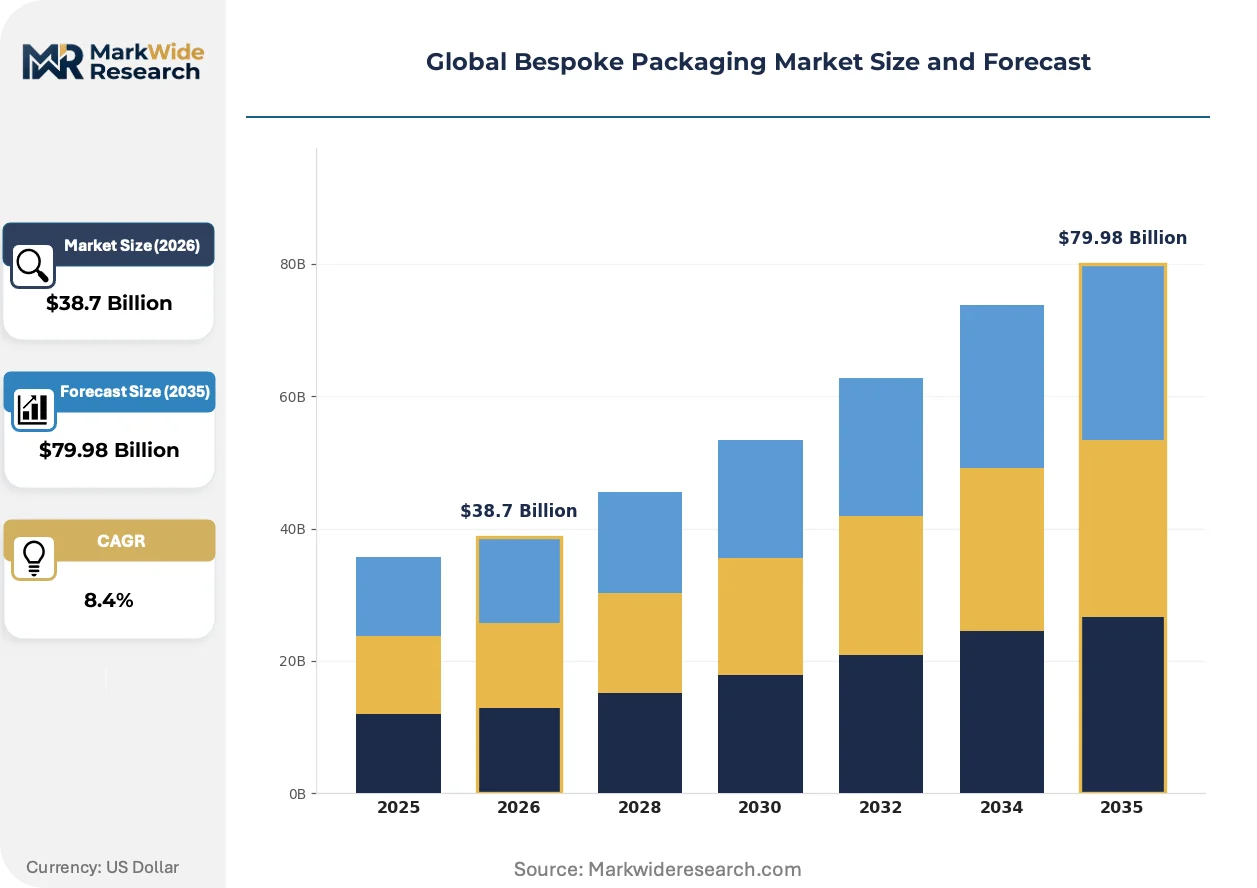
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Boxes, Bags, Wraps, Pouches Material: Paper, Plastic, Glass, Metal End User: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals Design Complexity: Simple, Moderate, Complex, Custom |
| Companies Covered | DS Smith Plc, WestRock, James Cropper Group, Lumi, Packlane, Packhelp, Smurfit Kappa Group, Huhtamaki, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bespoke Packaging Market Emerging Trajectories
Material science convergence with digital manufacturing is collapsing the traditional trade-off between customization depth and unit economics, enabling mass-luxury production models previously restricted to artisan scales.
Molded pulp with integrated barrier coatings is displacing thermoformed PET in premium cosmetic primary packaging. L'Oréal and Estée Lauder supply chains are qualifying cellulose-based formats for serum and cream applications at commercial volumes. This substrate shift is compressing petrochemical converter margins while expanding fiber equipment order backlogs.
REACH Article 33 disclosure requirements now mandate recyclability labeling for all packaging placed on EU markets. Converters must document mono-material content percentages or face market withdrawal. German luxury cosmetics brands are responding by eliminating mixed-substrate constructions entirely, driving specification changes that ripple through Asian supply chains.
Subscription box buyers now expect unboxing choreography engineered for social media capture. Birchbox and Glossier procurement teams specify hinge-lid reveals and magnetic closures as standard, not premium tiers. This aesthetic standardization is most visible in US DTC channels where unboxing content drives customer acquisition economics.
Global Bespoke Packaging Market Segmentation
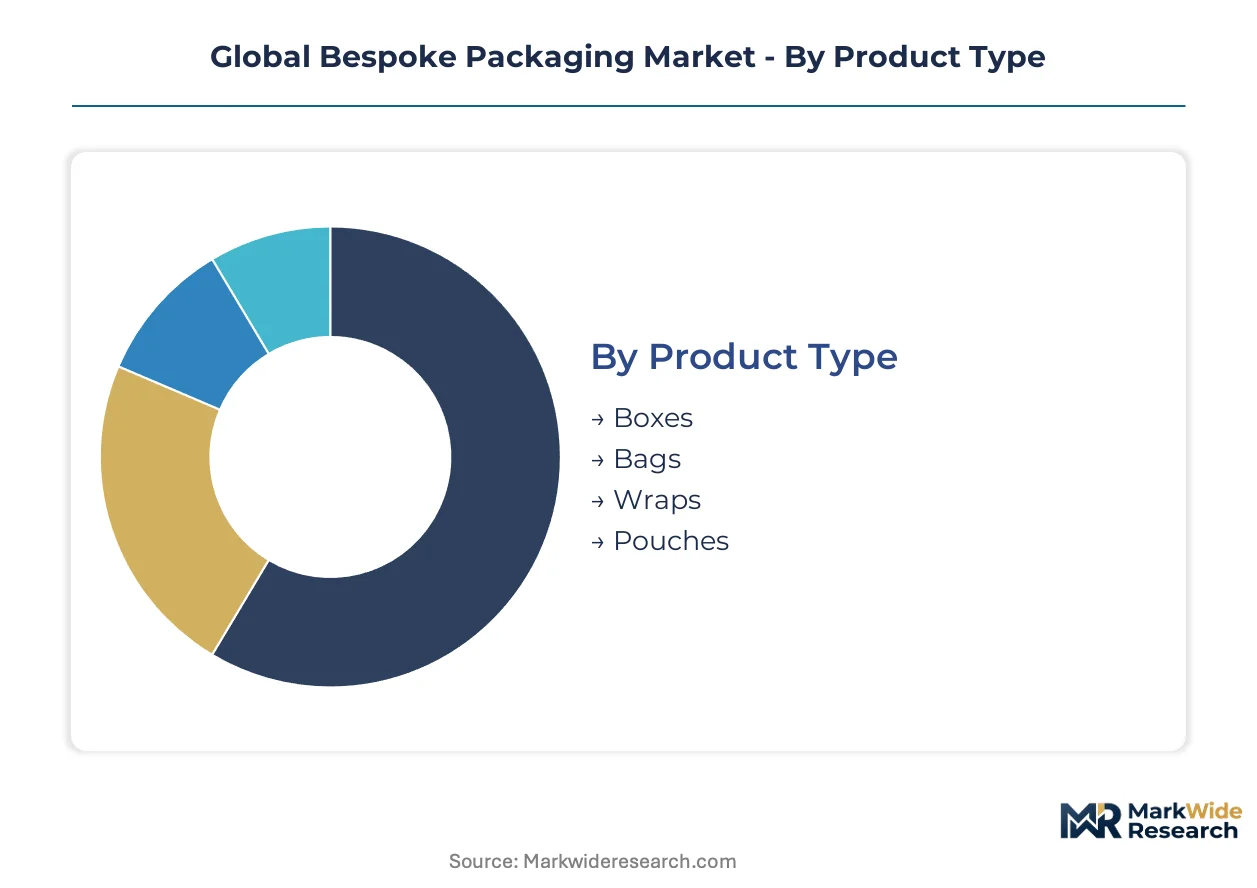
Bespoke packaging segmentation reveals how substrate choices and design tiers allocate margin pools across converting capacity. Procurement patterns in luxury cosmetics and pharmaceutical cold-chain applications are fragmenting volume concentration while elevating specification complexity.
Product Type:
Substitution pressure from flexible formats is reshaping rigid box demand as DTC brands prioritize dimensional efficiency in last-mile logistics.
- Boxes:Die-cut fiberboard constructions with magnetic closures and foil-stamped finishes dominate prestige cosmetics unboxing experiences. Rhine-Ruhr converters supply German luxury brands with complex hinge-lid formats requiring dedicated tooling amortization across 50,000-unit minimums.
- Pouches:Multi-layer barrier films with soft-touch matte finishes and resealable zippers are displacing glass for travel-size cosmetics. China's Yangtze River Delta flexible packaging clusters capture this specification shift through integrated gravure and digital print lines.
- Bags:Rope-handle paper and non-woven formats serve retail gift-with-purchase programs with rapid turnaround requirements.
- Wraps:Tissue and kraft paper with custom-printed patterns protect fragile items in subscription box fulfillment.
Boxes retain volume leadership; pouches hold the steepest expansion curve.
Material:
Cost tier stratification separates premium fiber-based formats from commodity thermoformed alternatives as EU Green Deal mandates accelerate substrate transitions.
- Paper:Molded pulp with integrated barrier coatings now qualifies for serum and cream primary packaging at L'Oréal and Estée Lauder volumes. Nordic kraft linerboard supply disruptions compress margins on luxury boxes while converters absorb pulp price volatility through long-term supply contracts.
- Plastic:Mono-material PET and PP formats face REACH plasticizer restrictions driving specification changes across European supply chains. Guangdong lamination plants encounter MEE wastewater discharge limits that extend lead times for export orders with soft-touch coatings.
- Glass:Heavy-wall bottles with custom-molded shoulders and silk-screened decoration retain fragrance and spirits applications where weight signals premium positioning.
- Metal:Tinplate and aluminum formats serve limited-edition collectible packaging with embossing and lithographic print capabilities.
Paper commands the premium tier by margin; plastic faces the steepest regulatory compression.
End User:
Application-specific certification requirements create divergent qualification timelines that segment converter capabilities across verticals.
- Cosmetics:Serum and cream primary packaging demands oxygen and UV barrier performance driving molded pulp qualification programs at major beauty houses. German prestige brands specify mono-material constructions ahead of EU recyclability mandates.
- Pharmaceuticals:Temperature-validated molded pulp insulation for biologics shipments represents underpenetrated demand with FDA and EMA validation cycles extending development by 18-24 months.
- Food & Beverage:Artisan chocolate and craft spirits producers adopt bespoke formats for gift and subscription channels with seasonal volume spikes.
- Electronics:Anti-static fiberboard and molded pulp corner protection for high-value device unboxing experiences.
Cosmetics concentrates specification innovation; pharmaceuticals present the longest commercialization runway.
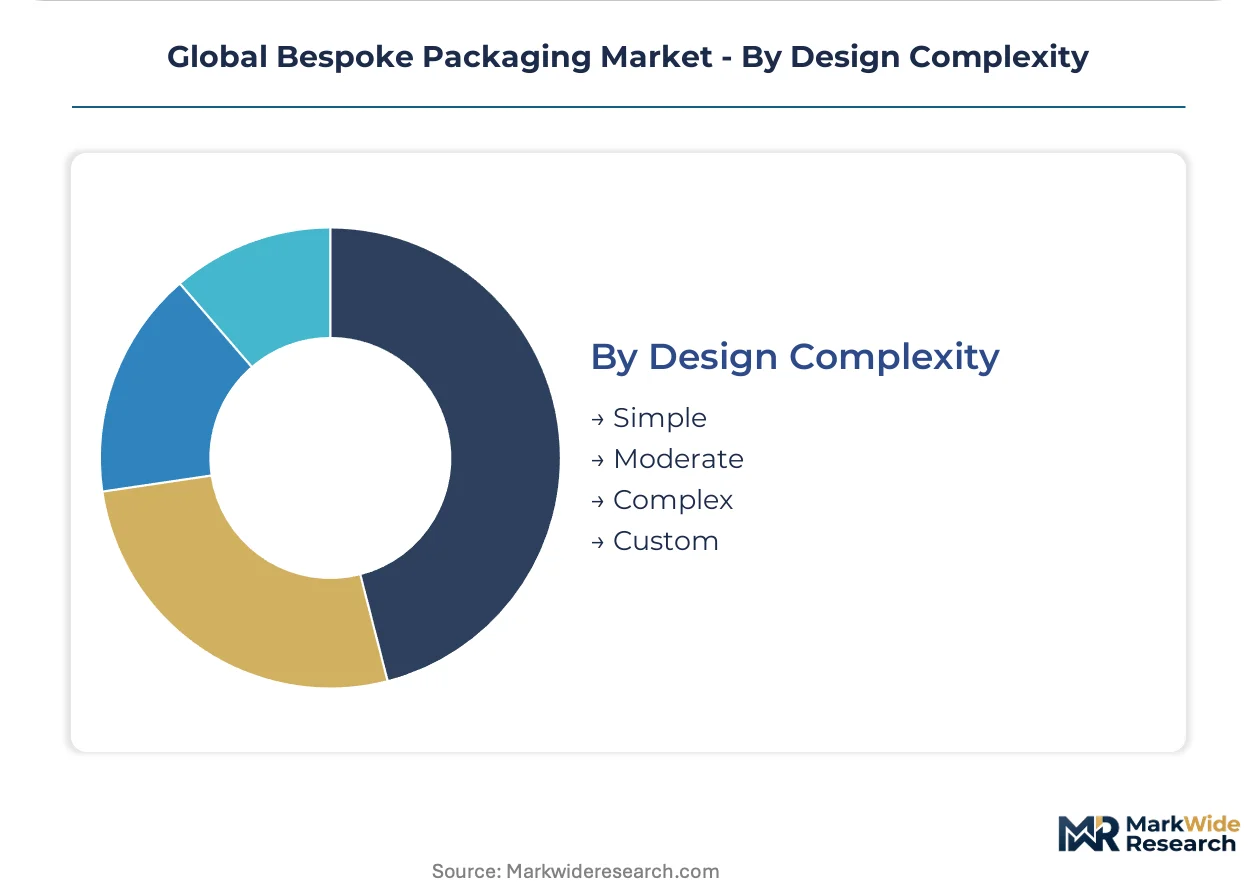
Design Complexity:
Customer type stratification separates enterprise procurement with dedicated tooling budgets from emerging brands constrained by minimum order economics.
- Complex:Multi-point glue structures with magnetic closures and ribbon pulls require die engineering expertise concentrated in legacy German and Japanese tooling houses. Birchbox and Glossier procurement teams specify hinge-lid reveals as standard DTC requirements.
- Custom:Batch-size-one digital print with variable-data soft-touch coatings collapses cost gaps between mass-customized and static runs through UV-cured inkjet systems.
- Moderate:Standard die-cut formats with spot UV and foil embellishments serve mid-tier brands with 10,000-50,000 unit annual volumes.
- Simple:Plain kraft boxes with single-color print for cost-conscious subscription and e-commerce fulfillment.
Complex formats capture margin concentration; custom tiers are climbing the fastest as digital manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites European bespoke packaging logistics, while the Yangtze River Delta's manufacturing density anchors Asian supply chains for premium cosmetic formats.
United States
Direct-to-consumer subscription brands in New York and Los Angeles fragment procurement into micro-orders, forcing batch-size-one economics. EPA emissions standards for coating operations raise compliance costs at converting facilities. The Pacific Northwest pulp supply disruption compresses margins on kraft linerboard boxes destined for prestige beauty brands.
Germany
Rhine-Ruhr prestige cosmetics clusters generate localized demand for complex hinge-lid formats with foil embellishments. REACH plasticizer restrictions accelerate mono-material transitions ahead of 2030 recyclability mandates. Bavarian tooling houses concentrate die engineering expertise for magnetic closure structures, limiting converter scaling outside legacy networks.
China
Yangtze River Delta flexible packaging clusters capture specification shifts toward multi-layer barrier pouches for travel-size cosmetics. MEE wastewater discharge limits at Guangdong lamination plants extend lead times for export orders with soft-touch coatings. Zhejiang digital print lines execute variable-data embellishment at production speeds previously restricted to static runs.
India
Domestic manufacturing incentives under the PLI scheme for advanced materials attract diverted volume from China-plus-one sourcing strategies. Maharashtra and Gujarat pharmaceutical clusters drive demand for temperature-validated molded pulp insulation with extended FDA validation cycles. Bangalore's design studios supply structural packaging talent to mid-tier cosmetics entrants constrained by tooling amortization thresholds.
United Kingdom
London-headquartered luxury brands specify unboxing choreography engineered for social media capture, elevating hinge-lid reveals to standard procurement tiers. CSRD disclosure requirements mandate supply chain emissions documentation for packaging converters. Manchester-based fiber R&D facilities qualify cellulose-based formats for serum applications at commercial beauty house volumes.
Global Bespoke Packaging Market Vendor Landscape
Concentration sits with integrated fiber-based converters and digital-first platforms serving fragmented DTC demand. The vendor base spans legacy European paperboard specialists, North American corrugated integrators, and agile software-enabled configurators. Two archetypes dominate: capital-intensive integrated producers with captive pulp supply, and asset-light digital platforms collapsing minimum order quantities. Competitive moves center on substrate R&D partnerships for barrier-coated molded pulp and geographic expansion into India PLI-subsidized manufacturing zones.
Within the integrated producer tier, DS Smith Plc and WestRock exemplify capital-intensive positioning with fiber-based R&D pipelines and design-to-delivery infrastructure. Packhelp occupies the digital-native archetype, competing on tooling that collapses minimum order thresholds for mid-tier cosmetics entrants. Smurfit Kappa Group and Huhtamaki represent European-headquartered specialists with corrugated and flexible format capabilities respectively. James Cropper Group anchors premium paperboard applications through specialized fiber expertise.
| Leading Market Players |
|---|
| DS Smith Plc |
| WestRock |
| James Cropper Group |
| Lumi |
| Packlane |
| Packhelp |
| Smurfit Kappa Group |
| Huhtamaki |
| ProAmpac |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for Nordic kraft linerboard lock in fiber supply visibility for Rhine-Ruhr converters serving German prestige cosmetics brands, insulating against pulp price swings while fixing input costs across multi-year procurement cycles. These arrangements concentrate pricing power with integrated producers holding captive pulp assets, forcing independent converters toward spot-market exposure or capacity reservation fees that compress margins on complex die-cut formats.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels based on customization depth and certification grade. Premium tiers command margin concentration through dedicated tooling amortization and FDA-grade barrier coatings for pharmaceutical applications, while economy tiers face price erosion from digital print commoditization. Birchbox-scale DTC buyers exhibit highest price sensitivity, whereas Estée Lauder procurement teams prioritize mono-material compliance over unit cost.
Supply Chain Analysis
Inventory buffers at Rotterdam port facilities extend lead times for German luxury brands sourcing hinge-lid formats from Asian component suppliers. Manufacturing gravity centers on Germany, China, and the United States, with Nordic softwood pulp and Guangdong lamination capacity serving as critical input dependencies. Tariff exposure on coated paperboard imports from China disrupts cost planning for US-based subscription brands. Distribution runs through integrated design-to-delivery networks anchored by WestRock's North American corrugated infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal substrate mandates and digital print convergence are accelerating a high-growth disruption that rewards fiber-based capability investments and punishes petrochemical-dependent converters. This inflection compresses commercialization timelines for barrier-coated molded pulp while elevating qualification barriers for mixed-substrate formats.
For Market Incumbents: Consolidate die engineering expertise through acquisition of Bavarian and Japanese tooling houses to defend structural design talent scarcity against digital-native entrants. Backward integration into Nordic kraft linerboard supply secures margin insulation from pulp volatility while locking out mid-tier competitors from complex format access. For New Entrants and Emerging Players: FDA fast-track certification for temperature-validated molded pulp insulation opens pharmaceutical cold-chain white space with 18-24 month incumbency barriers. Target India's Maharashtra pharmaceutical clusters through PLI-subsidized manufacturing partnerships, leveraging Bangalore design studios for structural talent without German tooling house premiums. For Investors and Strategic Acquirers: The market sits at a substrate-transition phase that favors fiber-specialist converters with captive R&D pipelines over diversified packaging conglomerates. Acquisition targets should demonstrate validated barrier-coating chemistry and established relationships with L'Oréal or Estée Lauder supply chains. Watch FDA and EMA validation timeline compression as the signal for molded pulp inflection acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating R&D Partnership | L'Oréal qualification programs validate cellulose-based serum packaging at commercial scale. |
| India PLI Manufacturing Footprint | Maharashtra subsidies capture China-plus-one diversion for pharmaceutical cold-chain formats. |
| Digital Print Platform Integration | UV-cured inkjet systems collapse minimum order quantities for mid-tier cosmetics entrants. |
| Mono-Material Certification Investment | REACH Article 33 compliance eliminates mixed-substrate constructions from EU supply chains. |
| Reusable Secondary Packaging Launch | Return-loop subscription boxes align with EU Green Deal circular economy targets. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade association filings, customs records, and regulatory disclosure databases. Converting plant managers, cosmetics brand procurement directors, pharmaceutical supply chain leads, and flexible packaging R&D heads contributed structured interviews across Germany, China, and the United States. Secondary validation drew from EPA emissions filings, REACH substance registrations, and EU Green Deal implementation guidance. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates.
Segmentation dimensions modeled include substrate type, design complexity tier, end-use vertical, and regional regulatory cluster across the analysis window. CAGRs derive from production capacity expansion schedules, brand qualification pipeline visibility, and substitution elasticity estimates for molded pulp displacing thermoformed PET. Forecast inputs incorporate Nordic pulp supply contract pricing, MEE enforcement intensity indices, and DTC subscription brand formation rates.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory stringency and stable pulp supply from Nordic softwood sources; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Global Noise Control Enclosures Packaging Market
Packaging Solutions
Airless Packaging Market
Packaging Solutions
Portable UV Sanitizing Boxes Market
Packaging Solutions
Sterilized Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
Middle East and Africa Contract Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
North America Secondary Packaging Market
Packaging Solutions
Transport Packaging Market