
 Global Coding and Marking Solutions Market | 2026-2036
Global Coding and Marking Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Coding and Marking Solutions Market Foresight
Aftermarket service revenue is narrowing as equipment manufacturers bundle predictive maintenance into subscription contracts. Domino Printing Sciences plc leverages its global service footprint to lock in multi-year agreements with beverage bottlers. Hitachi Ltd. anchors its position in East Asia through in-house production of laser source components, reducing third-party dependency. Paul Leibinger GmbH & Co. KG specializes in precision inkjet systems for pharmaceutical blister packs, occupying a defensible niche against broader-line competitors.
Coding and marking solutions encompass industrial systems that apply variable data—batch numbers, expiration dates, barcodes, and traceability codes—onto product packaging and substrates using non-contact deposition methods at speeds exceeding 1,000 prints per minute. These systems serve compliance, supply chain visibility, and anti-counterfeiting functions across regulated consumer industries. Continuous inkjet retains the largest installed base due to its versatility on porous and non-porous surfaces, though fiber laser coders represent the fastest-growing technology segment as manufacturers seek permanent, solvent-free marking on plastics and metals. Thermal transfer printers dominate in flexible film packaging where smudge resistance determines line clearance rates.
The US FDA enforces unit-level traceability under the Drug Supply Chain Security Act, compelling pharmaceutical packaging plants to upgrade legacy dot matrix systems to vision-verified inkjet or laser platforms. The EU Falsified Medicines Directive, administered by EMA-coordinated national regulators, mandates serialised 2D codes on prescription packs, reshaping procurement patterns across contract manufacturers in France, Germany, and Italy. China's NMPA and SAMR have tightened labeling requirements for domestic and imported food products, driving replacement demand in Shanghai and Guangzhou packaging clusters. Stakeholders must weigh capital intensity against regulatory non-compliance penalties when selecting between retrofit upgrades and greenfield laser installations.
Market Dynamics
Fiber laser systems are compressing replacement cycles across beverage and pharmaceutical packaging lines as manufacturers abandon solvent-based marking to meet tightening environmental compliance and permanence requirements.
Growth Catalysts
- Pharmaceutical serialization mandates:The US Drug Supply Chain Security Act and EU Falsified Medicines Directive compel packaging plants to deploy vision-verified track-and-trace systems on every prescription unit.
- China's labeling tightening:NMPA and SAMR enforcement on domestic and imported food products accelerates equipment replacement in Shanghai and Guangzhou packaging clusters.
- Fiber laser speed advantages:High-speed beverage lines in Germany, China, and the United States adopt laser coders exceeding 1,000 marks per minute without consumable downtime.
Market Restraints
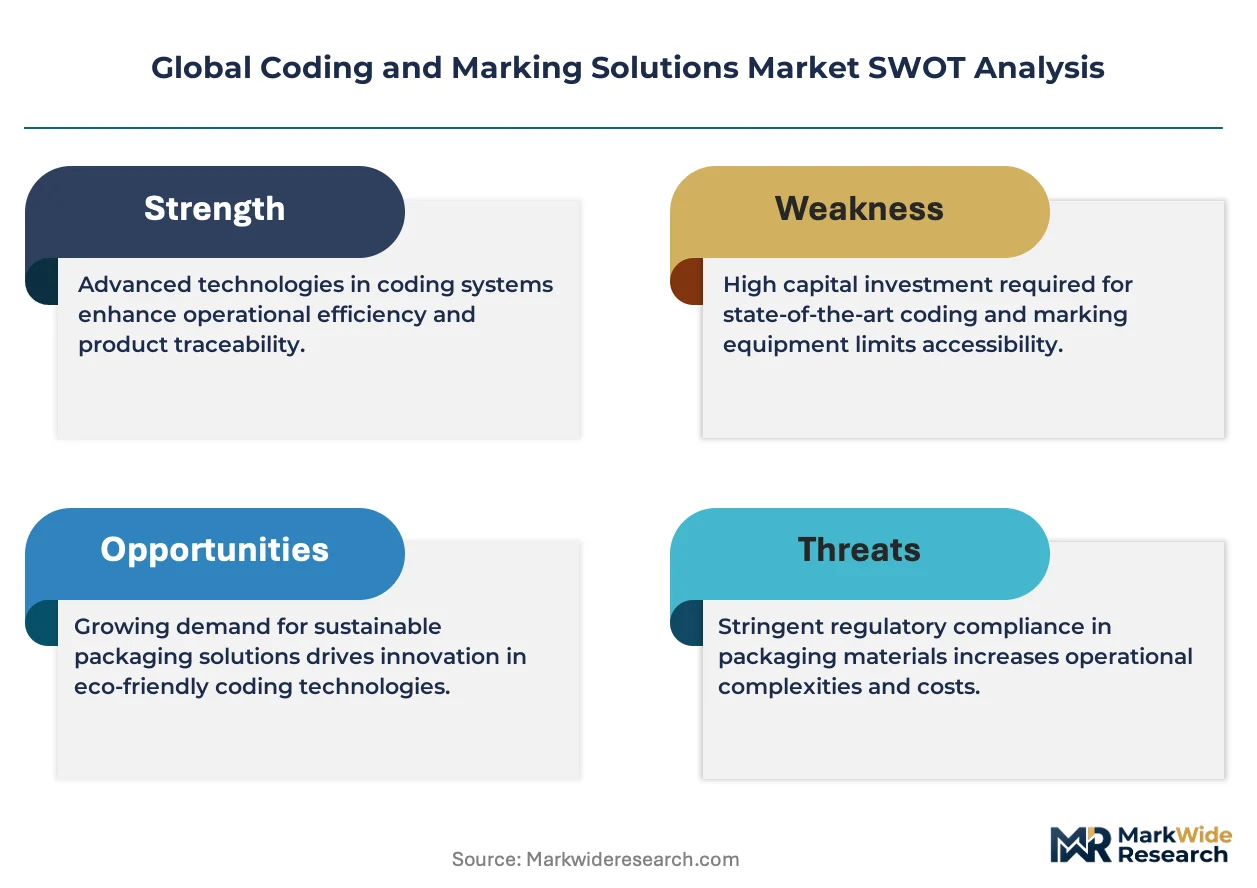
- Capital intensity barrier:Greenfield laser installations demand substantially higher upfront outlays than retrofit inkjet upgrades, freezing budget-constrained mid-tier packagers.
- Component supply concentration:Laser source production concentrates in East Asian manufacturing hubs, exposing lead time vulnerability to regional logistics disruptions.
- Legacy inkjet installed base:Continuous inkjet systems retain entrenched positions across porous substrates where fiber lasers deliver inferior marking quality.
Strategic Opportunities
- India contract packaging expansion:CDSCO serialization requirements and FSSAI labeling rules create greenfield demand among emerging pharmaceutical and food contract manufacturers.
- Predictive maintenance bundling:Equipment vendors lock in recurring revenue streams by embedding IoT-enabled uptime guarantees into multi-year subscription contracts.
- Thermal transfer film growth:Flexible packaging lines for snacks and confectionery present upgrade potential where smudge resistance determines automatic line clearance rates.
Industry Challenges
- Laser optics technician scarcity:Fiber laser maintenance demands specialized skills absent in traditional inkjet service workforces, inflating training costs and response times.
- Vision system integration complexity:Pharmaceutical plants struggle to synchronize new marking hardware with legacy warehouse management and ERP platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Coding and Marking Solutions Market |
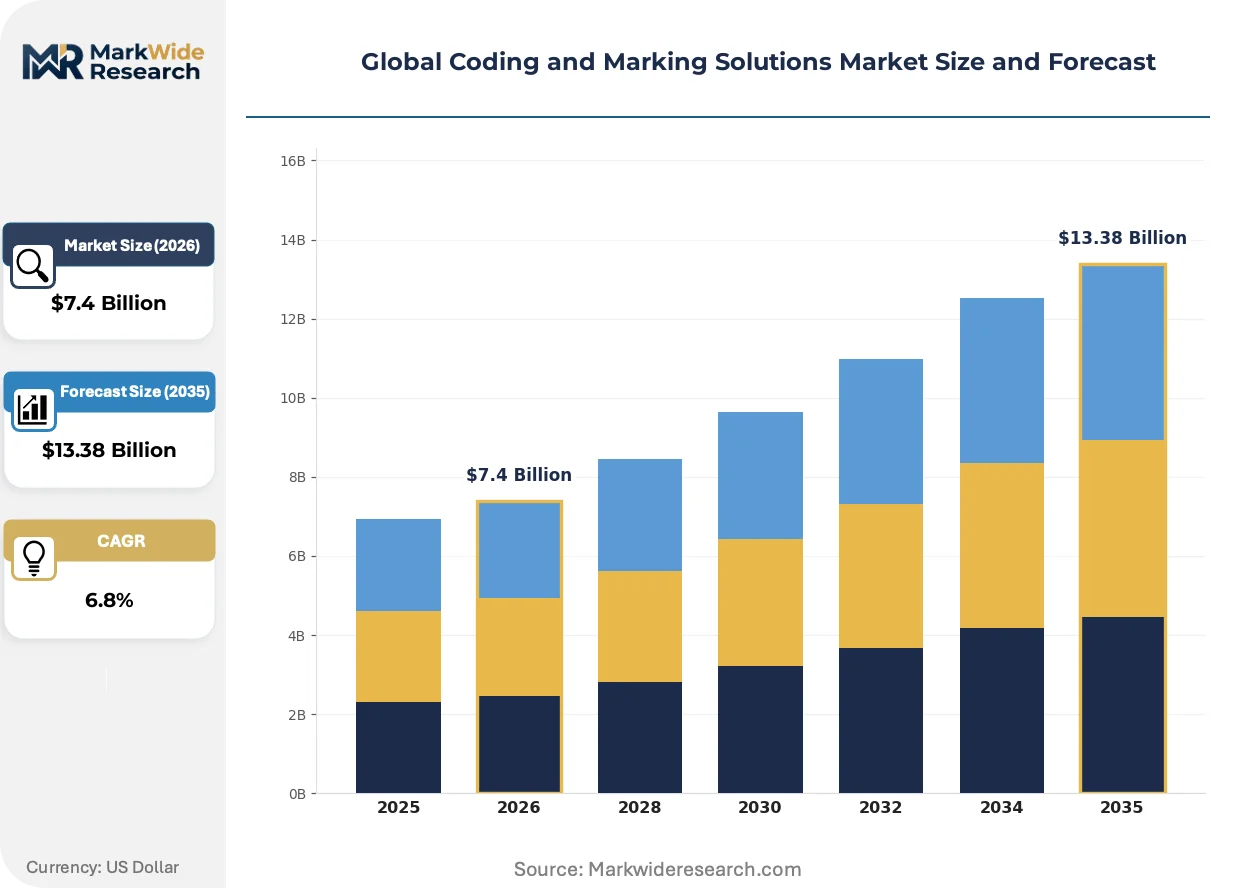
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Laser Coders, Thermal Transfer Printers, Dot Matrix Printers, Continuous Inkjet, Others Technology: Thermal Inkjet, Piezo Inkjet, CO2 Laser, Fiber Laser, UV Laser, Others Application: Food & Beverage, Pharmaceuticals, Personal Care, Electronics Manufacturing, Packaging Industry, Others End User: Contract Manufacturers, Packaging Plants, Brand Owners, Third-party Labelers, Retail Packaging Firms |
| Companies Covered | Videojet Technologies Inc., Domino Printing Sciences plc, Markem-Imaje Corporation, Hitachi Ltd., Linx Printing Technologies Ltd., Matthews International Corporation, REA Elektronik GmbH, Paul Leibinger GmbH & Co. KG, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Coding and Marking Solutions Market Shifts & Advancements
Equipment architecture is pivoting from standalone deposition hardware toward integrated production-line nodes that communicate directly with factory SCADA and MES layers.
Ultrafast picosecond fiber lasers are rendering obsolete legacy nanosecond systems in precision electronics marking. Semiconductor and medical device manufacturers in Japan and South Korea adopt these sources for heat-sensitive substrates. The technology is compressing capital equipment depreciation schedules as early adopters force competitive parity.
REACH solvent restrictions and EU Green Deal carbon accounting rules are eliminating volatile organic compound emissions from packaging operations. Manufacturers face compliance deadlines that invalidate wet-ink processes. German and Italian pharmaceutical contract packers accelerate laser and thermal transfer procurement to preempt enforcement actions.
Aftermarket service unbundling is reversing as beverage multinationals negotiate outcome-based uptime contracts. Domino Printing Sciences and comparable vendors absorb preventive maintenance risk in exchange for guaranteed availability fees. This restructuring concentrates in North American and Western European bottling operations where line stoppage costs exceed subscription premiums.
Global Coding and Marking Solutions Market Segmentation
Technology selection in coding and marking solutions determines compliance eligibility, line speed ceilings, and total cost of ownership across regulated packaging environments. Procurement patterns diverge sharply between mature inkjet installations and emerging laser platforms as environmental mandates reshape equipment replacement cycles.
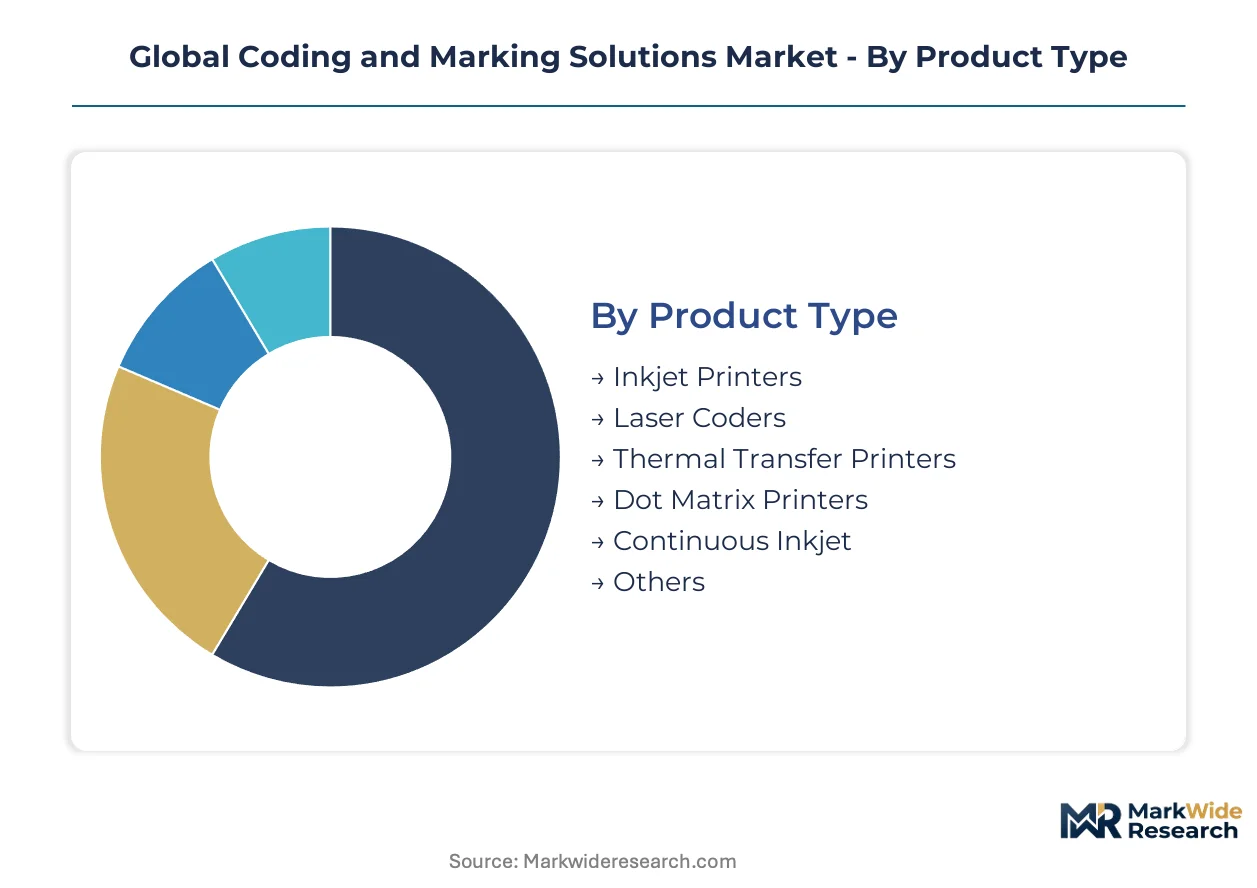
Product Type:
Mature continuous inkjet systems retain entrenched positions across high-volume beverage and food lines, while fiber laser coders represent the emerging technology disrupting replacement timelines.
- Inkjet Printers:Drop-on-demand systems deposit solvent-based or water-based inks onto porous and non-porous substrates without surface contact. Pharmaceutical contract manufacturers in Germany and Italy favor these units for blister pack serialization where substrate compatibility spans aluminum foil and PVC films.
- Laser Coders:Fiber and CO2 sources ablate substrate surfaces to create permanent, tamper-evident marks without consumables. Beverage bottlers in the United States and China deploy these systems to eliminate solvent handling costs and meet tightening EPA and MEE emissions enforcement.
- Thermal Transfer Printers:Ribbon-based melting transfer delivers smudge-resistant codes on flexible films.
- Dot Matrix Printers:Impact-based marking persists in legacy industrial applications with minimal regulatory exposure.
- Continuous Inkjet:Recirculating ink systems dominate high-speed lines exceeding 1,000 prints per minute.
- Others:Valve jet and hot foil stamping occupy niche applications in heavy industrial marking.
Continuous inkjet handles the majority of throughput across installed bases; laser coders are climbing the fastest on share as permanence requirements tighten.
Technology:
Cost tier separation between entry-level thermal inkjet and premium fiber laser systems drives divergent procurement strategies among budget-constrained mid-tier packagers and multinational brand owners.
- Fiber Laser:Solid-state sources at 1,064 nm wavelength deliver permanent marks on metals and opaque plastics with no thermal damage to heat-sensitive substrates. Semiconductor manufacturers in Japan and South Korea adopt picosecond variants for electronics marking where nanosecond systems previously dominated.
- Thermal Inkjet:Cartridge-based systems offer low capital entry points for short-run packaging operations. Contract labelers in India leverage these units for FSSAI-compliant food labeling where volume variability discourages fixed-asset deployment.
- Piezo Inkjet:Piezoelectric actuation enables precise droplet control for high-resolution pharmaceutical codes.
- CO2 Laser:Gas-based systems at 10.6 μm wavelength excel on organic materials including paper and wood.
- UV Laser:355 nm solid-state sources mark sensitive electronics and medical devices with minimal heat transfer.
- Others:Green laser and ultrafast variants address specialized substrate requirements.
Thermal inkjet captures the entry-level volume; fiber laser exhibits the steepest expansion trajectory as REACH solvent restrictions eliminate wet-ink alternatives.
Application:
Customer type concentration separates compliance-driven pharmaceutical serialization from throughput-optimized beverage marking, with divergent vendor selection criteria across each vertical.
- Pharmaceuticals:Track-and-trace mandates under the US Drug Supply Chain Security Act and EU Falsified Medicines Directive compel vision-verified 2D coding on every prescription unit. Packaging plants in France and Germany prioritize laser and thermal transfer systems that integrate with warehouse management platforms for EMA-coordinated compliance.
- Food & Beverage:High-speed production lines demand marking systems exceeding 1,000 units per minute with automatic line clearance protocols. Bottling operations in China and the United States favor fiber laser coders to eliminate solvent emissions under tightening NMPA and EPA enforcement.
- Personal Care:Cosmetic and hygiene products require smudge-resistant coding on curved and flexible containers.
- Electronics Manufacturing:PCB and component marking demands precision laser systems for miniaturized traceability.
- Packaging Industry:Contract converters serve multiple end-use verticals with flexible equipment configurations.
- Others:Automotive, aerospace, and industrial applications require specialized durability specifications.
Food and beverage commands the largest equipment volume; pharmaceuticals is gaining share fastest as serialization deadlines approach across multiple jurisdictions.
End User:
Geographic clustering of contract packaging capacity in India, China, and Eastern Europe concentrates demand among outsourced manufacturing specialists rather than captive brand owner facilities.
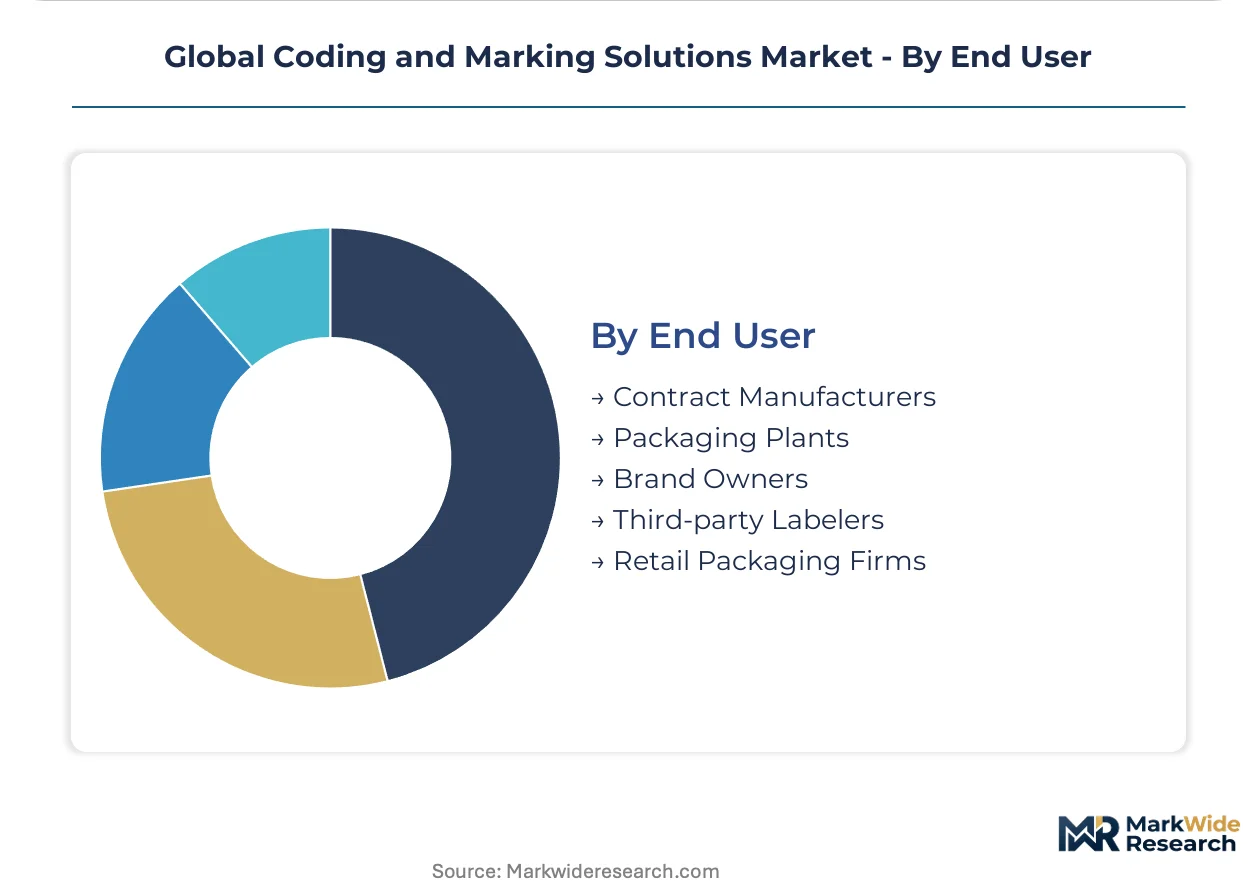
- Contract Manufacturers:Third-party packagers serving multinational pharmaceutical and food brands absorb compliance complexity across multiple regulatory jurisdictions. CDSCO serialization requirements and FSSAI labeling rules in India drive greenfield laser and inkjet procurement among emerging contract packaging clusters in Hyderabad and Mumbai.
- Packaging Plants:Captive facilities at beverage and consumer goods multinationals standardize equipment platforms across regional production networks. German and Italian pharmaceutical contract packers accelerate thermal transfer and laser adoption to preempt EU Green Deal enforcement actions.
- Brand Owners:Multinational consumer goods companies direct equipment specifications for co-packer networks.
- Third-party Labelers:Specialist converters apply variable data to pre-formed packaging materials.
- Retail Packaging Firms:Private label and store-brand packagers balance cost constraints against regulatory minimums.
Contract manufacturers represent the dominant procurement channel; packaging plants are expanding most quickly as brand owners repatriate quality control functions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical serialization mandates in Germany and the United States drive premium laser adoption, while cost-constrained packagers in India and China favor retrofit inkjet upgrades to meet evolving compliance deadlines.
United States
Beverage bottlers along the Gulf Coast and Midwest deploy fiber laser coders exceeding 1,000 marks per minute to eliminate solvent handling under tightening EPA enforcement. The FDA's Drug Supply Chain Security Act compels pharmaceutical packaging plants to upgrade legacy dot matrix systems to vision-verified platforms. Contract manufacturers in New Jersey and North Carolina concentrate procurement for track-and-trace compliance.
Germany
REACH solvent restrictions and EU Green Deal carbon accounting rules invalidate wet-ink processes across pharmaceutical and food packaging operations. The EMA-coordinated Falsified Medicines Directive mandates serialized 2D codes on every prescription unit. Contract packers in Bavaria and Baden-Württemberg accelerate thermal transfer and laser procurement to preempt enforcement actions.
China
NMPA and SAMR labeling enforcement on domestic and imported food products accelerates equipment replacement in Shanghai and Guangzhou packaging clusters. High-speed beverage lines favor fiber laser coders to meet MEE emissions standards without consumable downtime. Domestic laser source production concentrates in East Asian manufacturing hubs, reducing import dependency for regional system integrators.
India
CDSCO serialization requirements and FSSAI labeling rules create greenfield demand among emerging pharmaceutical and food contract manufacturers. Mid-tier packagers balance capital constraints against compliance deadlines through retrofit inkjet upgrades rather than greenfield laser installations. Hyderabad and Mumbai packaging clusters absorb multinational brand owner specifications for export-oriented production.
Japan
Semiconductor and medical device manufacturers adopt picosecond fiber lasers for heat-sensitive substrate marking, compressing capital equipment depreciation schedules. METI industrial policy supports precision manufacturing upgrade cycles. Kansai and Chubu regional production networks integrate ultrafast laser systems for electronics traceability.
Global Coding and Marking Solutions Market Competitive Landscape
Capability concentration sits with specialized component fabricators; scale advantage sits with diversified industrial equipment conglomerates. The vendor base stratifies across three tiers: integrated multinational platforms serving beverage and pharmaceutical multinationals, regional specialists anchoring national compliance ecosystems, and emerging Asian fabricators capturing replacement demand in cost-sensitive markets. Dominant competitive moves include predictive maintenance subscription bundling and in-house laser source production to reduce third-party dependency.
Among diversified Japanese industrial conglomerates, Hitachi Ltd. exemplifies upstream integration into laser source components. Domino Printing Sciences plc occupies a position within the integrated platform tier, leveraging global service footprints for multi-year agreements. Paul Leibinger GmbH & Co. KG represents the precision specialist archetype, anchoring defensible positioning in pharmaceutical serialization niches against broader-line competitors.
| Leading Market Players |
|---|
| Videojet Technologies Inc. |
| Domino Printing Sciences plc |
| Markem-Imaje Corporation |
| Hitachi Ltd. |
| Linx Printing Technologies Ltd. |
| Matthews International Corporation |
| REA Elektronik GmbH |
| Paul Leibinger GmbH & Co. KG |
| Keyence Corporation |
| Others |
Supply & Pricing Matrix
Shanghai and Guangzhou packaging clusters anchor East Asian laser source production, concentrating component supply in manufacturing hubs that feed downstream pricing power to system integrators serving multinational beverage and pharmaceutical brand owners. Contract manufacturers in these clusters negotiate volume discounts on fiber laser modules that compress pricing tiers for mid-tier packagers in India and Eastern Europe.
Pricing Analysis
Long-term subscription contracts dominate procurement as equipment manufacturers bundle predictive maintenance into multi-year offtake agreements. Three-tier pricing structure across premium, standard, and economy levels separates vision-integrated pharmaceutical systems from basic beverage coding units. Pricing pressure stems from REACH solvent restrictions eliminating wet-ink alternatives and forcing accelerated replacement cycles. Mid-tier contract packagers in India exhibit highest price sensitivity, while multinational beverage bottlers in Germany and the United States absorb premium laser installations without margin compression.
Supply Chain Analysis
Extended payment terms from East Asian laser source fabricators to European system integrators lubricate working capital through supply-chain finance facilities. Component production concentrates in China, Japan, and Germany, drawing from specialized optical fiber, rare-earth dopants, and precision motion control hardware. Single-source vulnerability around laser diode arrays exposes lead time risk to regional logistics disruptions. Distribution runs through authorized regional service partners that maintain spare parts inventory for pharmaceutical serialization uptime guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive maintenance subscriptions expand faster than hardware sales as beverage multinationals negotiate outcome-based uptime contracts, transforming equipment vendors into recurring-revenue service platforms.
For Market Incumbents: Harden defensive positioning through in-house production of laser source components to reduce third-party dependency on East Asian suppliers. Lock in multi-year subscription agreements with pharmaceutical contract manufacturers before serialization deadlines tighten. Absorb preventive maintenance risk in exchange for guaranteed availability fees that compound customer switching costs. For New Entrants and Emerging Players: Pursue white-space opportunities in India's emerging contract packaging clusters where CDSCO serialization requirements and FSSAI labeling rules create greenfield demand among mid-tier pharmaceutical and food manufacturers. Target retrofit inkjet upgrades as the most penetrable entry point for budget-constrained packagers balancing capital constraints against compliance deadlines. Lead with thermal transfer systems for flexible film applications where smudge resistance determines automatic line clearance rates. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because pharmaceutical serialization mandates under the US Drug Supply Chain Security Act and EU Falsified Medicines Directive embed structural demand for vision-verified track-and-trace infrastructure. Acquisition targets should display precision inkjet specialization in pharmaceutical blister packs or captive laser source production capability. Watch for REACH enforcement acceleration in Germany and Italy as the signal indicating replacement cycle compression beyond current baseline assumptions.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Bundling | Domino Printing Sciences locks in multi-year agreements with beverage bottlers through IoT-enabled uptime guarantees. |
| In-House Laser Source Production | Hitachi Ltd. reduces third-party dependency through captive manufacturing of fiber laser components in East Asia. |
| Precision Inkjet Specialization | Paul Leibinger GmbH occupies defensible pharmaceutical serialization niches against broader-line competitors. |
| Contract Packaging Expansion | Emerging clusters in Hyderabad and Mumbai absorb multinational specifications for export-oriented production. |
| Ultrafast Laser Adoption | Semiconductor manufacturers in Japan and South Korea compress depreciation schedules through picosecond system procurement. |
Research Methodology
Desk research of trade association filings, customs records, and regulatory databases preceded structured interviews with plant engineers at beverage bottlers, pharmaceutical packaging directors, aftermarket service heads, and procurement leads at contract manufacturers. Primary fieldwork combined telephone and video interviews with secondary validation against SEC filings, EMA compliance bulletins, and NMPA enforcement notices. Bottom-up equipment shipment data triangulated against top-down market sizing from industry associations.
Assumptions held fixed include current regulatory enforcement intensity under the FDA Drug Supply Chain Security Act, EU Falsified Medicines Directive, and REACH solvent restrictions, while technology substitution rates and contract manufacturer expansion trajectories were varied across sensitivity scenarios. Segmentation modeling spanned technology type, application vertical, end-user category, and regional production cluster. CAGRs derived from regression analysis of historical replacement cycles projected against compliance deadline schedules. Forecast inputs included pharmaceutical serialization mandate timelines and fiber laser speed benchmarks exceeding 1,000 marks per minute.
Macroeconomic conditions sit as an overlay; deviation in capital expenditure cycles at multinational brand owners or logistics cost volatility across East Asian manufacturing hubs would shift the trajectory. Forecasts reflect documented assumptions around regulatory enforcement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Advanced Packaging Market
Packaging Solutions
Single Dose Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Interior Packaging Market
Packaging Solutions
Anti-Counterfeiting Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Stretch Sleeves and Shrink Sleeves Market
Packaging Solutions
Halal Packaging Market
Packaging Solutions
Panel Level Packaging Market
Packaging Solutions
Europe Temperature Controlled Packaging Solutions Market
Packaging Solutions
Hermetic Packaging Market
Packaging Solutions
Strawless Lids Market
Packaging Solutions
Recycled Materials Packaging Solutions Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Australia Contract Packaging Market
Packaging Solutions
Package Drop Box Market