
 Panel Level Packaging Market | 2026-2036
Panel Level Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Panel Level Packaging Market Analysis
ISO 9001 qualification cycles for substrate-level packaging is collapsing from three-year windows to eighteen-month sprints, tightening supplier eligibility. Samsung Electronics leverages its captive memory and foundry divisions to internalize panel-level R&D. ASE Technology Holding Co., Ltd. anchors its position through heterogeneous integration roadmaps spanning multiple end markets. Deca Technologies specializes in fan-out panel-level flows that compete with conventional wafer-level formats on cost-per-die metrics.
Panel Level Packaging denotes semiconductor interconnect and redistribution processes performed on rectangular glass or organic panels rather than round silicon wafers, typically targeting panel dimensions of 510mm by 515mm or 600mm by 600mm to maximize area utilization for multi-die assemblies. The format serves industrial and commercial purposes by enabling higher throughput and lower per-unit costs for advanced packages requiring large body sizes or dense I/O counts. Fan-Out Wafer Level packaging dominates current revenue as the most mature panel-adaptable technology, while Embedded Die formats represent the fastest-growing structural segment due to their compatibility with automotive reliability specifications. Advanced Substrates technology captures concentrated margin pools as material suppliers and equipment makers extract value from low-alpha resin and laser-direct-imaging tooling requirements.
MIIT in China enforces GB standards for semiconductor packaging materials that restrict certain epoxy formulations, while the EU F-Gas Regulation limits fluorinated greenhouse gases used in plasma etching processes critical to panel-level via formation. The US CHIPS and Science Act directs funding toward domestic advanced packaging capacity, altering where stakeholders must qualify new supply sources. Buyers and vendors should monitor which regulatory frameworks achieve extraterritorial reach through customer audit requirements rather than direct jurisdiction.
Market Dynamics
The transition from round wafer processing to rectangular panel formats is compressing substrate costs per die while forcing equipment vendors to retool lithography and inspection systems for non-standard form factors.
Growth Catalysts
- High-performance computing demand:AI accelerators and data center processors require larger package bodies with dense redistribution layers that panel-level formats deliver more economically than wafer-level alternatives.
- EU F-Gas Regulation:Restrictions on fluorinated greenhouse gases in plasma etching are accelerating investment in alternative via-formation chemistries compatible with organic panel substrates.
- Taiwan ecosystem density:Concentrated advanced packaging engineering talent and equipment vendor proximity reduce qualification timelines for new panel-level process flows.
Market Restraints
- Low-alpha resin supply concentration:Three Japanese chemical suppliers control majority share of radiation-hardened epoxy formulations required for automotive-grade embedded die packages, creating input cost volatility.
- Equipment retrofit capex:Stepper and inspection tool vendors demand premium pricing for panel-format retrofits, extending payback periods for packaging houses below 5,000 wafer-equivalent monthly volumes.
- Wafer-level fan-out maturity:Established high-volume supply chains for 300mm round formats create switching friction even where panel economics prove superior on paper.
Strategic Opportunities
- Automotive embedded die penetration:Electric vehicle power modules and ADAS sensor packages represent underpenetrated volume pools where panel-level reliability testing protocols are gaining OEM qualification.
- US CHIPS Act packaging carve-out:Direct funding allocations for domestic advanced packaging capacity create first-mover advantages for substrate vendors qualifying new resin formulations with US-based OSATs.
- Glass-core substrate convergence:Intersection of panel-level processing with glass interposer technology enables thermal expansion matching for heterogeneous integration of chiplets from different foundry nodes.
Industry Challenges
- Warpage control engineering scarcity:Panel-level thermal management during molding and curing requires specialized finite-element modeling expertise concentrated at a handful of research institutes.
- ISO 9001 sprint qualification:Compressed eighteen-month certification cycles strain quality management system documentation capacity at mid-tier substrate suppliers.
- Die-shift compensation complexity:Larger panel formats amplify cumulative placement errors during fan-out embedding, demanding real-time feedback loops between pick-and-place and lithography stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panel Level Packaging Market |
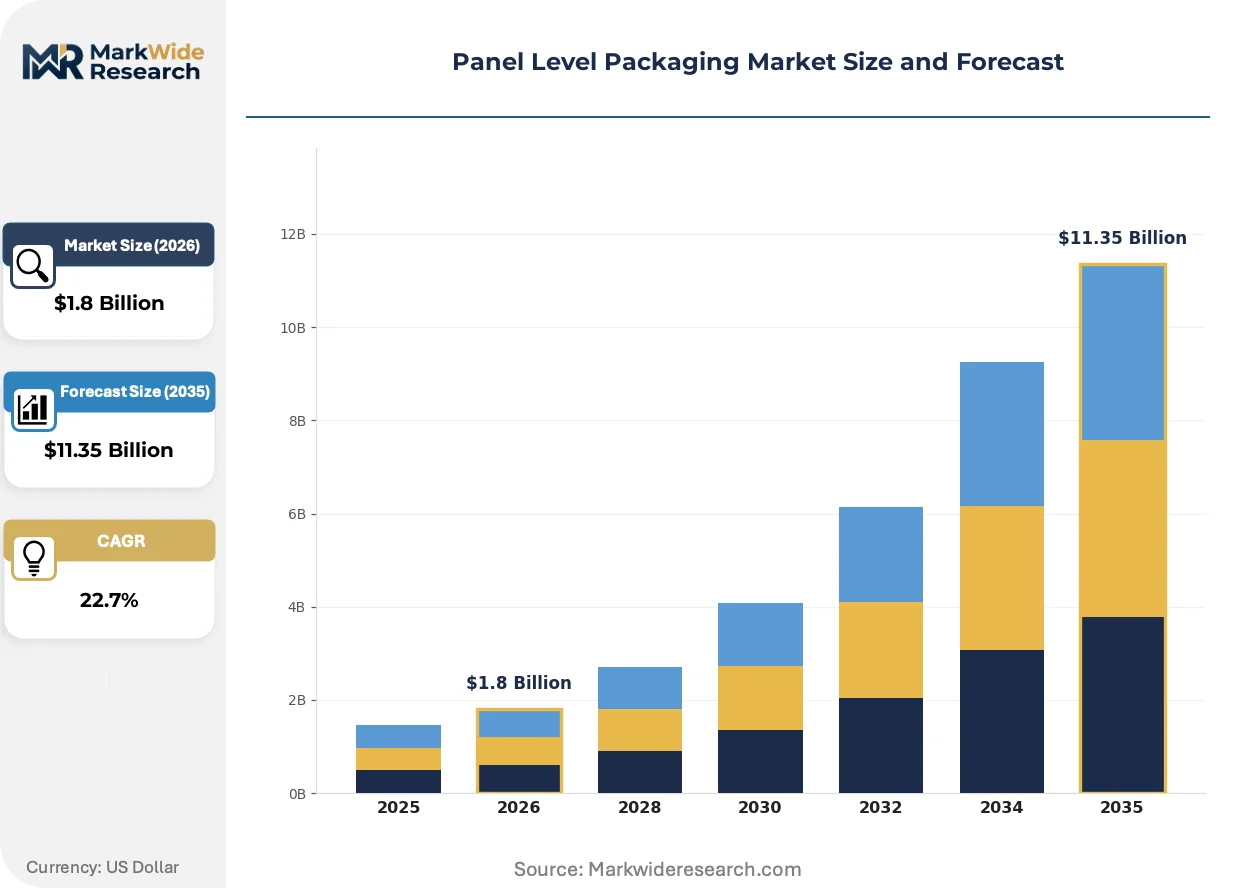
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $11.35 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
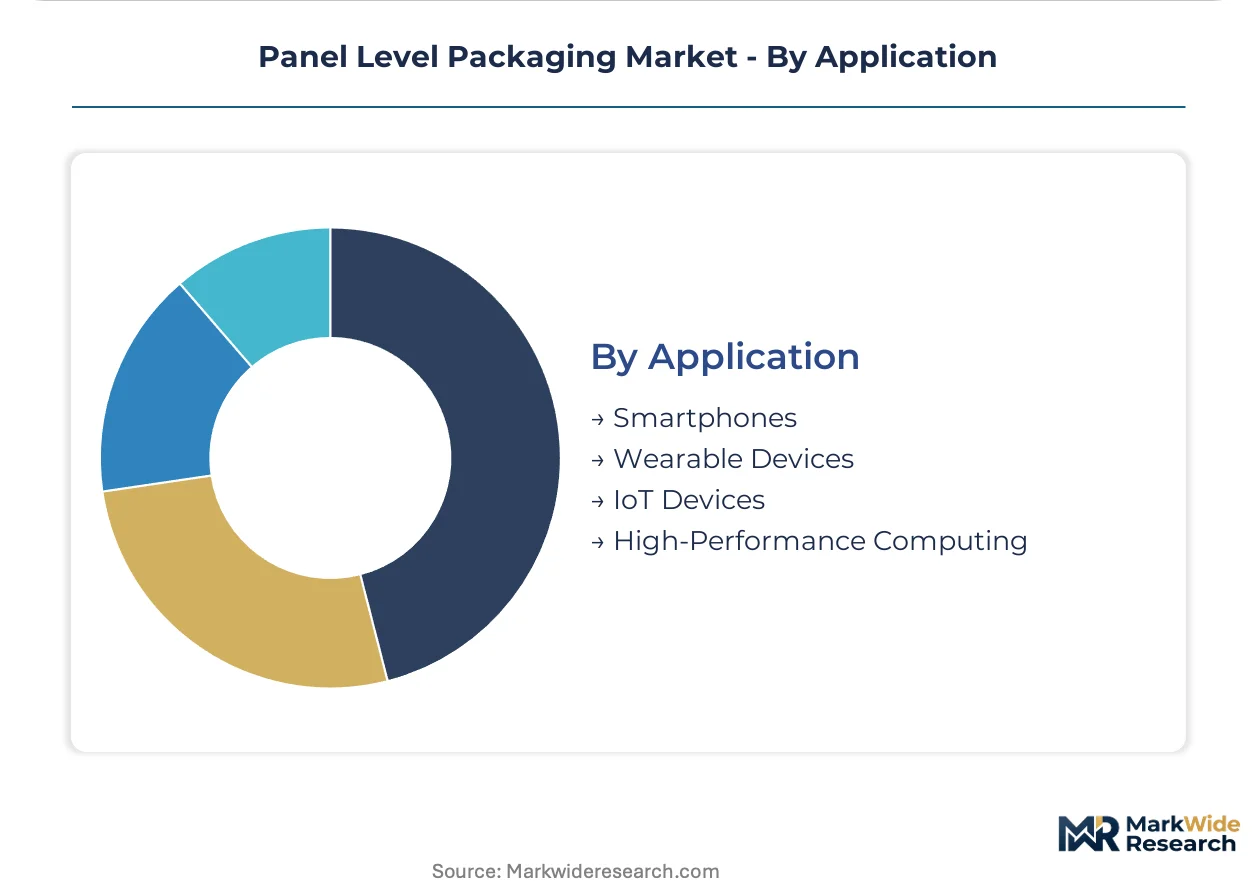
| Segmentation | Product Type: Fan-Out Wafer Level, Embedded Die, Thin Wafer, Flip Chip End User: Consumer Electronics, Automotive, Telecommunications, Industrial Technology: 3D Packaging, System-in-Package, Through-Silicon Via, Advanced Substrates Application: Smartphones, Wearable Devices, IoT Devices, High-Performance Computing |
| Companies Covered | Samsung Electronics Co., Ltd., Nepes Corporation, ASE Technology Holding Co., Ltd., Unimicron Technology Corp., Deca Technologies, Amkor Technology, Inc., JCET Group, Intel Corporation, TSMC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panel Level Packaging Market Emerging Trajectories
Active materials substitution and regulatory chemistry restrictions are reshaping process development priorities, while procurement patterns favor suppliers capable of spanning multiple packaging generations.
Laser-direct-imaging photoresist is supplanting traditional mask-based lithography for fine-pitch redistribution layer patterning on organic panels. Memory and logic packaging houses in South Korea are adopting the technology at pilot-line scale ahead of mass production ramps. The shift is compressing mask procurement lead times and enabling last-minute design revisions that rigid photomask workflows cannot accommodate.
China's MIIT enforcement of GB standards for semiconductor packaging materials is restricting certain brominated epoxy formulations previously dominant in consumer electronics applications. Domestic substrate vendors are reformulating resin systems to maintain compliance while preserving moisture resistance metrics. The regulation most acutely affects mid-range smartphone and tablet package categories where cost sensitivity limits premium material substitution.
Consolidated procurement contracts now bundle panel-level capacity with legacy wafer-level commitments, pressuring OSATs to maintain dual-format operational competence. Tier-one fabless semiconductor designers in Taiwan are leveraging volume guarantees to secure allocation priority during industry upturns. This behavior concentrates most visibly in AI accelerator supply chains where package size requirements are outpacing wafer-level area economics.
Panel Level Packaging Market Segmentation

Panel-level packaging formats serve divergent cost-performance requirements across semiconductor end markets. Segmentation reveals where rectangular-panel economics displace legacy wafer-level processing, and which application clusters drive equipment configuration decisions.
Product Type:
Fan-Out Wafer Level packaging dominates export-led demand from Taiwan and South Korea foundry complexes, while Embedded Die formats concentrate in domestic European automotive supply chains.
- Fan-Out Wafer Level:Redistribution-layer processing on reconstituted wafer or panel substrates enables dense I/O routing for multi-die assemblies. Memory and logic packaging houses in South Korea drive pilot-line adoption of laser-direct-imaging lithography for this format, compressing mask procurement cycles.
- Embedded Die:Active components are encapsulated within organic laminate substrates prior to surface mounting, delivering thermal cycling resilience for power electronics. German and French automotive tier-one suppliers qualify these packages for traction inverter modules under AEC-Q100 Grade 0 protocols.
- Thin Wafer:Sub-100µm silicon handling for backside interconnect requires specialized temporary bonding equipment.
- Flip Chip:Solder-bump interconnect remains cost-competitive for high-volume consumer applications with moderate I/O density.
Fan-Out Wafer Level commands the established base. The steepest expansion runs through Embedded Die.
End User:
Cost tier stratification separates premium-specification automotive and telecommunications segments from price-sensitive consumer electronics procurement.
- Automotive:Electric vehicle power modules and ADAS sensor fusion units demand panel-level formats for thermal dissipation and reliability under vibration loads. OEM qualification protocols in Germany and Japan extend development cycles but lock in multi-year supply agreements.
- Telecommunications:Baseband processors and mmWave antenna-in-package modules require low-loss organic substrates. 5G infrastructure buildouts in South Korea and the United States concentrate demand for 600mm panel-capable OSAT capacity.
- Consumer Electronics:Smartphone application processors and tablet chipsets prioritize die-cost minimization over package performance.
- Industrial:Motor drives and programmable logic controllers tolerate larger package footprints for extended temperature range operation.
Automotive absorbs the highest margin premiums. Consumer Electronics delivers the largest unit volumes.
Technology:
Supply concentration in advanced substrates and TSV equipment vendors shapes procurement leverage for packaging houses.
- Advanced Substrates:Low-alpha resin formulations and laser-direct-imaging tooling define material and equipment value capture. Japanese chemical suppliers control radiation-hardened epoxy supply, creating input cost volatility for automotive-grade embedded die production.
- Through-Silicon Via:Vertical interconnect through silicon die enables 3D memory stacking and heterogeneous logic integration. High-aspect-ratio via etching equipment vendors command premium pricing for panel-format retrofits.
- 3D Packaging:Die stacking with microbump or hybrid bonding interconnect targets high-bandwidth memory interfaces.
- System-in-Package:Integration of logic, memory, and passive components in single molded bodies serves space-constrained wearable applications.
Advanced Substrates concentrates supplier margins. Through-Silicon Via is climbing the fastest.
Application:
Maturity gradients separate volume-stable smartphone demand from nascent high-performance computing ramps.
- High-Performance Computing:AI accelerators and data center processors require package body sizes exceeding 300mm², where panel-level area utilization economics prove decisive. Cloud compute providers in the United States and China negotiate consolidated procurement contracts bundling panel-level with legacy wafer-level capacity.
- Smartphones:Application processor and modem integration drives fan-out wafer-level adoption for flagship tier devices. Assembly houses in Taiwan and Vietnam manage seasonal volume fluctuations through dual-format operational competence.
- Wearable Devices:Ultra-compact system-in-package formats prioritize thickness reduction over I/O density.
- IoT Devices:Cost-optimized flip chip and wirebond packages dominate sensor and connectivity module applications.
Smartphones anchor current revenue. High-Performance Computing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US CHIPS and Science Act directs funding toward domestic advanced packaging capacity, reshaping where panel-level substrate vendors must qualify new supply sources. Taiwan and South Korea retain engineering density advantages, while European automotive demand pulls embedded die formats into German and French supply chains.
United States
Cloud compute providers negotiate consolidated procurement contracts bundling panel-level with legacy wafer-level commitments. The CHIPS Act packaging carve-out creates first-mover advantages for substrate vendors qualifying resin formulations with domestic OSATs. Arizona and Texas host emerging advanced packaging clusters where equipment vendors retool lithography systems for rectangular panel formats.
Taiwan
Foundry complexes drive export-led demand for fan-out panel-level processing, with ASE Technology Holding anchoring heterogeneous integration roadmaps. Concentrated engineering talent reduces qualification timelines for new process flows. Hsinchu Science Park maintains equipment vendor proximity that accelerates pilot-line adoption of laser-direct-imaging photoresist.
South Korea
Memory and logic packaging houses adopt laser-direct-imaging lithography at pilot-line scale ahead of mass production ramps. Samsung Electronics leverages captive memory and foundry divisions to internalize panel-level R&D. Seoul Capital Area and Busan-Ulsan corridors concentrate 5G infrastructure demand for 600mm panel-capable capacity.
Germany
Automotive tier-one suppliers qualify embedded die packages for traction inverter modules under AEC-Q100 Grade 0 protocols. The EU F-Gas Regulation restricts fluorinated greenhouse gases in plasma etching, accelerating alternative via-formation chemistry investment. Bavaria and Baden-Württemberg host OEM qualification labs extending development cycles but locking in multi-year supply agreements.
China
MIIT enforcement of GB standards restricts brominated epoxy formulations, forcing domestic substrate vendors to reformulate resin systems. Yangtze River Delta packaging houses face compliance pressure while preserving moisture resistance metrics. Shanghai and Suzhou clusters manage mid-range consumer electronics categories where cost sensitivity limits premium material substitution.
Panel Level Packaging Market Vendor Landscape
Player mix skews toward diversified OSATs with captive foundry linkages and specialized fan-out panel-level specialists. Market structure concentrates around vertically integrated conglomerates controlling memory, logic, and packaging divisions alongside independent packaging houses competing on cost-per-die metrics. Two strategic archetypes dominate: diversified technology holding companies spanning multiple end markets, and focused specialists competing on panel-format process economics. Competitive moves center on internalized R&D pipelines and heterogeneous integration roadmaps that bundle legacy wafer-level with emerging panel-level capacity.
Within the diversified technology tier, Samsung Electronics Co., Ltd. and ASE Technology Holding Co., Ltd. exemplify conglomerate structures that internalize advanced packaging development across captive divisions. Deca Technologies occupies a specialist position focused on fan-out panel-level flows. Samsung Electronics represents Korean vertically integrated fabrication, ASE Technology Holding anchors Taiwanese OSAT diversification, and Deca Technologies exemplifies cost-competitive panel-format specialization against conventional wafer-level alternatives.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Nepes Corporation |
| ASE Technology Holding Co., Ltd. |
| Unimicron Technology Corp. |
| Deca Technologies |
| Amkor Technology, Inc. |
| JCET Group |
| Intel Corporation |
| TSMC |
| Others |
Supply Flow & Price Mechanics
Laser-direct-imaging photoresist substitution for mask-based lithography simultaneously relocates value capture toward South Korean and Taiwanese equipment vendors while compressing mask procurement economics across panel-level process flows. This chemistry transition rewards buyers with design flexibility but concentrates pricing power among photoresist formulators capable of ISO 9001 sprint qualification.
Pricing Analysis
Certification level under AEC-Q100 automotive protocols creates the primary spread between premium embedded die packages and standard consumer-grade fan-out formats. Three-tier pricing structure across automotive-grade, high-performance computing, and economy consumer tiers reflects material cost differentials in low-alpha resin formulations. Cost compression in mid-range smartphone packages is intensifying because MIIT GB standard compliance forces brominated epoxy substitution without full performance equivalence. Automotive OEMs show least price sensitivity due to multi-year supply agreement structures, while consumer electronics procurement teams negotiate hardest on per-die metrics.
Supply Chain Analysis
Inventory buffers for radiation-hardened epoxy formulations have compressed to twelve-week cycles, exposing packaging houses to Japanese chemical supplier allocation decisions. Raw material flows draw from Japan for low-alpha resins, Taiwan for ABF substrate laminates, and Germany for laser-direct-imaging exposure tools. Single-source vulnerability concentrates in high-aspect-ratio via etching equipment where panel-format retrofits require vendor-specific engineering. Distribution runs through consolidated procurement contracts that bundle panel-level capacity with legacy wafer-level commitments, pressuring OSATs to maintain dual-format operational competence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The panel-level packaging market represents a high-growth disruption as rectangular-format economics displace round-wafer processing for die sizes exceeding 300mm², accelerated by EU F-Gas Regulation restrictions on fluorinated etching chemistry.
For Market Incumbents: Compound heterogeneous integration roadmaps spanning automotive, telecommunications, and high-performance computing segments to defend against specialized fan-out panel-level specialists. Internalize warpage control engineering capabilities through captive finite-element modeling teams or exclusive research institute partnerships. Prioritize backward integration into low-alpha resin formulation to reduce Japanese chemical supplier dependency exposure. For New Entrants and Emerging Players: Mid-tier substrate supplier quality management system documentation gaps present service-layer entry points where ISO 9001 sprint qualification strains incumbent capacity. Target US-based OSATs qualifying new resin formulations under CHIPS Act packaging carve-out funding for first-mover positioning. Lead with glass-core substrate convergence expertise as thermal expansion matching becomes critical for chiplet heterogeneous integration. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed panel-level equipment retrofit specialists holding captive relationships with lithography and inspection tool vendors. Five-to-ten year viability hinges on qualification velocity with tier-one fabless designers in Taiwan and cloud compute providers in the United States. Watch die-shift compensation algorithm development as the inflection indicator separating scalable process flows from pilot-line limitations.| Strategic Initiative | Industry Significance |
|---|---|
| Glass-Core Substrate Convergence | Enables thermal expansion matching for chiplet integration from different foundry nodes. |
| Laser-Direct-Imaging Adoption | Compresses mask procurement lead times for South Korean memory packaging houses. |
| Low-Alpha Resin Backward Integration | Reduces input cost volatility from Japanese chemical supplier concentration. |
| US CHIPS Act Qualification | Creates first-mover advantages for substrate vendors with domestic OSAT partnerships. |
| Heterogeneous Integration Roadmaps | Bundles legacy wafer-level with panel-level capacity for Taiwan foundry complexes. |
Methodological Framework
A standing panel of advanced packaging engineering directors, substrate procurement leads at fabless semiconductor designers, equipment vendor application specialists, and automotive tier-one supplier quality managers provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC filings of diversified OSATs, MIIT GB standard enforcement notices, EU F-Gas Regulation implementation guidance, and equipment vendor order backlog disclosures. Bottom-up capacity buildout tallies triangulated against top-down end-market demand modeling.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product format, end-use application, technology tier, and regional regulatory cluster. CAGRs were derived from shipment trajectory analysis and capacity expansion announcement tracking. Forecast inputs incorporated ISO 9001 qualification cycle compression effects and laser-direct-imaging adoption curves.
Underlying assumptions cover sustained EU F-Gas Regulation enforcement and CHIPS Act funding disbursement velocity, with deviation risk concentrated in low-alpha resin supply disruption and equipment retrofit delivery delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Solutions
Global Peel and Reseal Packaging Market
Packaging Solutions
Vacuum Skin Packaging Market
Packaging Solutions
Global Coding and Marking Solutions Market
Packaging Solutions
Global E-Commerce Packaging Market
Packaging Solutions
Shelf Stable Packaging Market
Packaging Solutions
Global Lithium Ion Battery Packaging Solutions Market
Packaging Solutions
India Packaging Market
Packaging Solutions
Decoys and Dispensers Market
Packaging Solutions
Saudi Arabia Packaging Market
Packaging Solutions
United States Contract Packaging Market
Packaging Solutions
Corrugated Packaging Software Market
Packaging Solutions
Packaging Solutions Market
Packaging Solutions
Topical Dispenser Market
Packaging Solutions
Patisserie Packaging Market
Packaging Solutions
Global Bespoke Packaging Market
Packaging Solutions
United Kingdom Packaging Market