
 Aircraft Lightning Protection Market | 2026-2036
Aircraft Lightning Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Lightning Protection Market Analysis
Direct OEM procurement channels is tilting toward tier-1 system integrators as airframers consolidate vendor bases for strike-protection suites. PPG Industries leverages its conductive coatings portfolio to sustain long-term supply positions on Boeing and Airbus programs. BAE Systems anchors military lightning protection demand through classified platform work. Amphenol Aerospace competes on connector-level electromagnetic hardening for next-generation avionics bays.
Aircraft lightning protection encompasses conductive materials, grounding architectures, and transient suppression systems engineered to dissipate electrical strike energy exceeding 200,000 amperes without compromising airframe integrity or onboard electronics. Static dischargers and conductive surfaces dominate product-type revenue due to retrofit cycles on in-service fleets, while surge protection devices within the technology dimension command premium pricing from chip-scale integration in fly-by-wire systems. Civil aviation applications lead volume, though military aircraft segments carry higher specification margins driven by stealth-compatible mesh requirements.
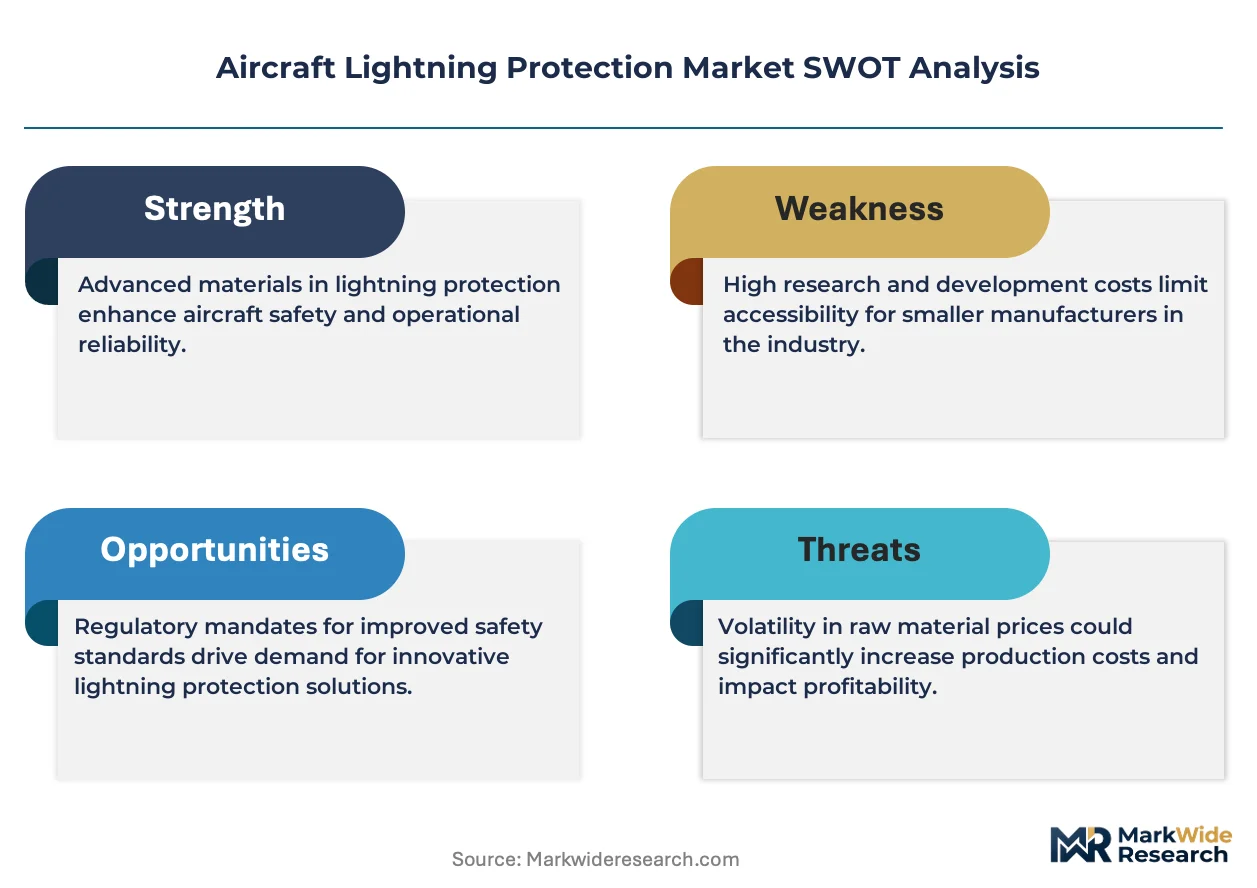
FAA airworthiness directives and EASA CS-25 certification standards mandate repeatable lightning test protocols that shape material selection and design validation costs for manufacturers. The EU Green Deal's sustainable aviation fuel push indirectly pressures lighter-weight conductive composites, altering grounding solution specifications. Stakeholders must monitor evolving DO-160 Section 22 test severity levels and corresponding supplier qualification timelines.
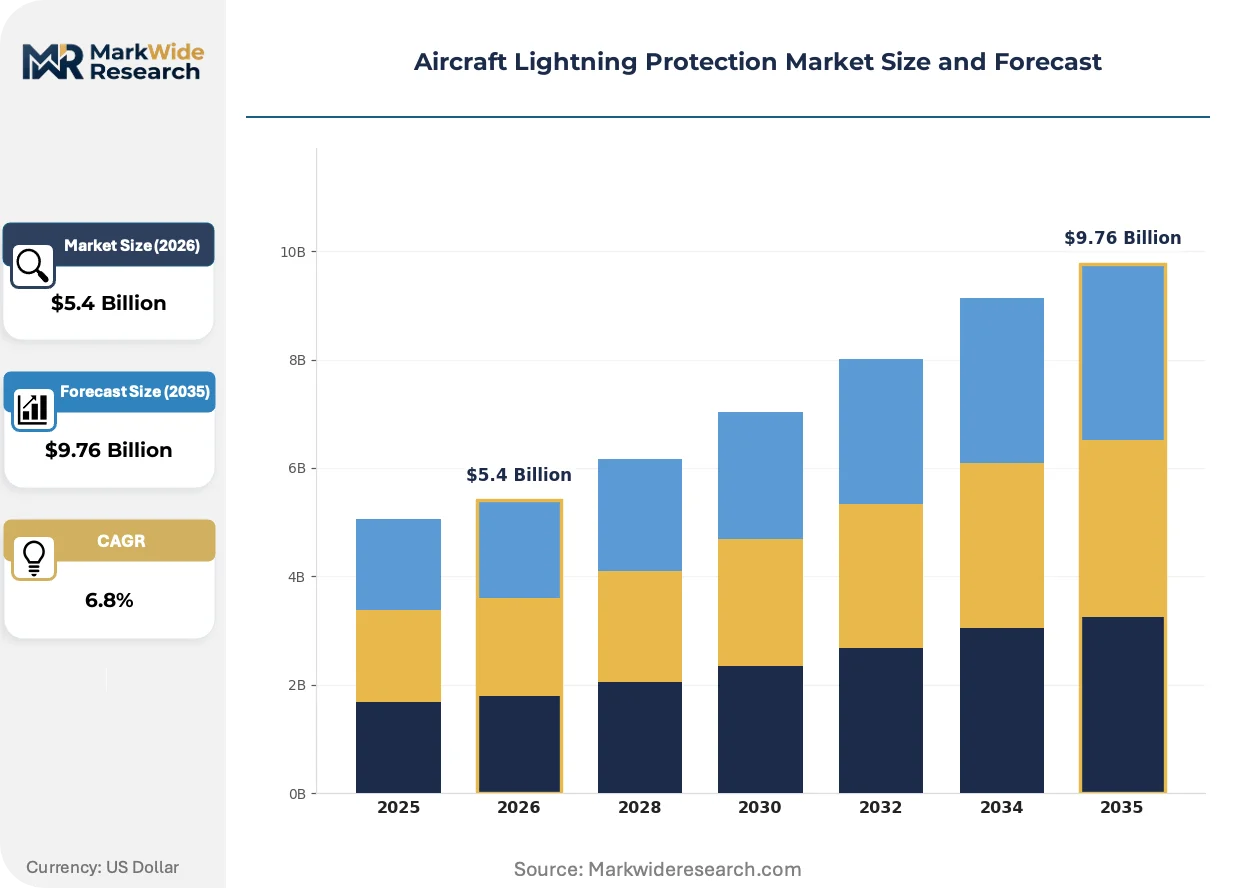
Market Dynamics
FAA airworthiness directives and EASA CS-25 certification standards are tightening material specifications and test protocols, forcing manufacturers to requalify conductive composites and grounding architectures across narrow-body retrofit programs and new OEM platforms.
Growth Catalysts
- Commercial Fleet Expansion:Narrow-body aircraft production rates at Boeing and Airbus facilities are accelerating demand for integrated lightning protection suites on new deliveries.
- CS-25 Certification Mandates:EASA's enhanced strike resilience requirements are compelling European MRO providers to upgrade aging conductive surface treatments on in-service fleets.
- Conductive Composite Advances:Lighter-weight carbon fiber reinforced polymers with embedded metallic mesh are displacing traditional aluminum grounding paths in next-generation wing structures.
Market Restraints
- Raw Material Concentration:Silver and copper supply volatility constrains conductive coating production, with refined metal sourcing concentrated in Chilean and Peruvian mining operations.
- Qualification Timeline Compression:DO-160 Section 22 test severity escalation extends supplier validation cycles by 18-24 months for new transient suppression devices.
- Technical Integration Limits:Legacy 28VDC electrical architectures on regional turboprops resist seamless integration of modern surge protection chipsets designed for 270VDC fly-by-wire systems.
Strategic Opportunities
- Urban Air Mobility Penetration:eVTOL manufacturers in Germany and the United States require miniaturized lightning protection for composite-intensive air taxi designs.
- Sustainable Aviation Fuel Alignment:EU Green Deal weight reduction targets are creating procurement preference for conductive thermoplastics that trim grounding system mass.
- Channel Digitization:Direct-to-MRO digital procurement platforms are bypassing traditional tier-2 distributors for standardized static discharger replacements.
Industry Challenges
- Electromagnetic Hardening Expertise Gap:Aerospace engineering programs produce insufficient specialists in high-intensity radiated field protection design for next-generation avionics bays.
- Multi-Standard Certification Burden:Simultaneous FAA, EASA, and Transport Canada validation requirements fragment testing resources for suppliers targeting transcontinental operator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Lightning Protection Market |
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Dischargers, Lightning Strikes Protection Systems, Conductive Surfaces, Lightning Protection Cables Technology: Surge Protection Devices, Lightning Rods, Electromagnetic Shielding, Grounding Solutions Application: Civil Aviation, Military Aircraft, Cargo Aircraft, General Aviation End User: Aerospace Manufacturers, Airlines, Defense Contractors, Maintenance Providers |
| Companies Covered | PPG Industries, Inc., 3M Company, BAE Systems plc, Dayton-Granger, Inc., Astroseal Products Manufacturing Corp., Honeywell International Inc., Amphenol Aerospace (Amphenol Corporation), Henkel Corporation, Collins Aerospace (Raytheon Technologies), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Lightning Protection Market Emerging Trajectories
Digital twin technology and additive manufacturing are compressing design-validation cycles for lightning protection components, while regulatory test severity escalation and shifting procurement models reshape competitive positioning across OEM and aftermarket channels.
Conductive nanocomposite coatings incorporating carbon nanotube dispersions are virtualizing traditional metallic mesh applications in wing leading edge protection. Tier-1 system integrators at Boeing's Everett and Charleston facilities are qualifying these formulations for 787 and 777X programs. This material transition is virtualizing established supply relationships between airframers and legacy aluminum mesh suppliers.
EASA's evolving CS-25 Amendment 26 provisions now mandate direct effects testing for fuel tank ignition source prevention, extending certification scope beyond historical airframe skin protection. European OEM procurement offices are rewriting supplier technical requirements to incorporate these expanded test matrices. Narrow-body platforms serving high-frequency routes across the Mediterranean and North Atlantic corridors face the most compressed requalification timelines.
Airline technical procurement departments are consolidating vendor bases for strike-protection suites, favoring tier-1 integrators with full airframe coverage over specialized component suppliers. This concentration pattern displaces historical multi-source strategies for static dischargers, conductive sealants, and grounding jumpers. US-based legacy carriers with substantial in-house MRO capabilities are driving this consolidation most aggressively.
Aircraft Lightning Protection Market Segmentation
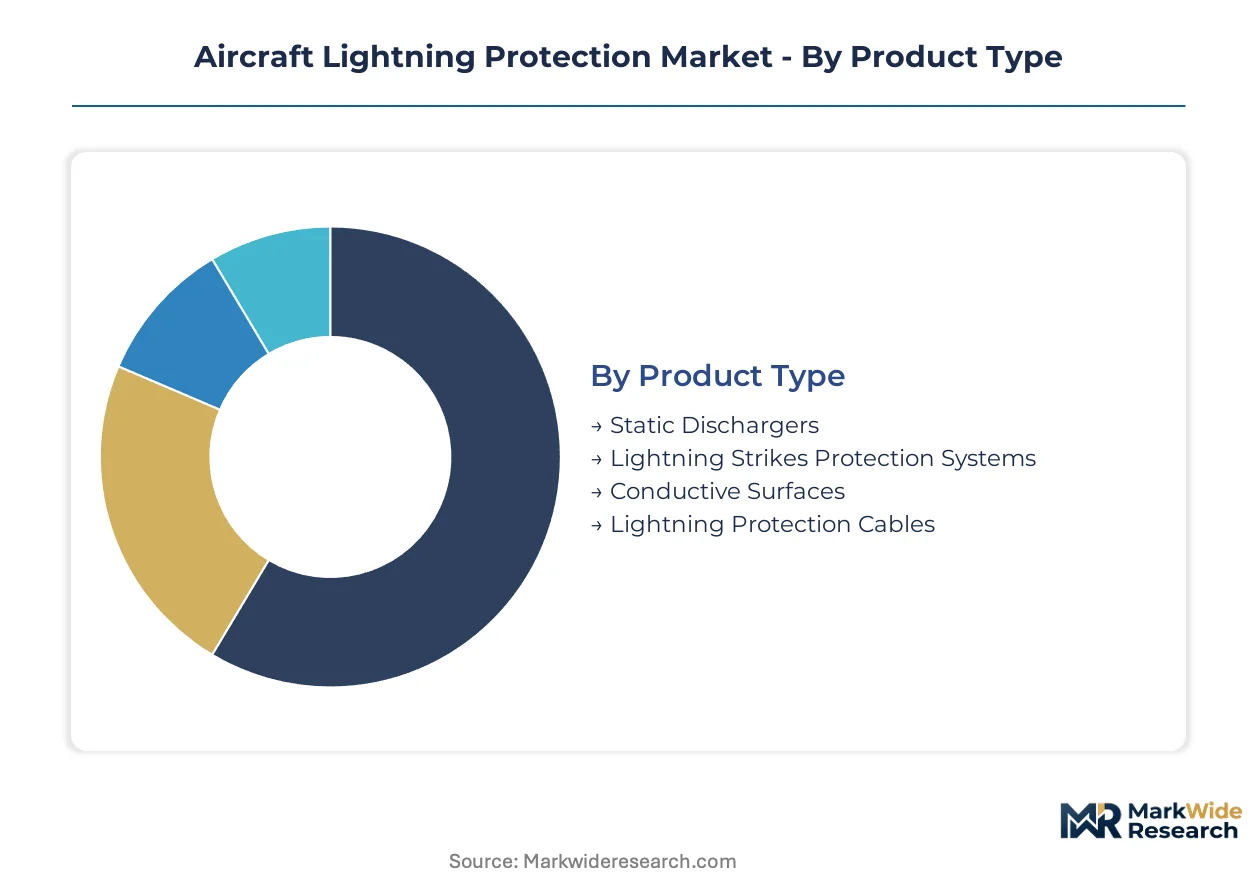
Lightning protection procurement patterns diverge sharply across replacement cycles and platform specifications. Static dischargers and conductive surfaces turn over every 18-24 months on high-utilization commercial fleets, while integrated strike-protection systems align with airframe production schedules spanning 5-7 years.
Product Type:
Replacement velocity varies from months for consumable wicks to decades for embedded structural systems, creating distinct aftermarket and OEM revenue profiles.
- Static Dischargers:Carbon composite wicks and metallic electrodes dissipate accumulated atmospheric static before lightning attachment. Airlines operating high-frequency routes across the Mediterranean and North Atlantic corridors drive replacement demand through accelerated wear cycles.
- Conductive Surfaces:Metallic mesh, conductive coatings, and expanded foil layers protect composite airframes from direct strike damage. Boeing 787 and Airbus A350 production lines concentrate procurement for embedded wing and fuselage applications.
- Lightning Strikes Protection Systems:Integrated architectures combining strike attachment points, current paths, and grounding networks for complete airframe coverage.
- Lightning Protection Cables:Specialized high-current conductors routing electrical energy between structural elements and grounding terminals.
Static dischargers anchor the volume base while conductive surfaces gain share at the steepest rate.
Technology:
Cost stratification separates commodity grounding hardware from premium electromagnetic hardening components commanding specification premiums.
- Surge Protection Devices:Transient voltage suppression circuits and chip-scale protectors shield avionics from induced currents. Fly-by-wire system integration at Boeing and Airbus facilities drives qualification timelines for 270VDC-rated components.
- Electromagnetic Shielding:Enclosures, gaskets, and barriers containing electromagnetic interference within avionics bays. Military stealth platform requirements sustain premium pricing for frequency-selective surface technologies.
- Grounding Solutions:Bonding jumpers, grounding straps, and equipotential networks maintaining electrical continuity across airframe structures.
- Lightning Rods:Discrete attachment points engineered to control strike entry locations on composite and metallic surfaces.
Grounding solutions anchor the volume base while surge protection devices gain share at the steepest rate.
Application:
Military specifications sustain margin premiums despite smaller unit volumes, while civil aviation drives aggregate revenue through fleet scale.
- Civil Aviation:Commercial airliners, regional jets, and business aircraft requiring CS-25 and FAA Part 25 certification compliance. Narrow-body retrofit programs across United States-based legacy carrier fleets concentrate aftermarket demand.
- Military Aircraft:Fighter, bomber, and surveillance platforms with stealth-compatible mesh and classified hardening requirements. BAE Systems and Northrop Grumman procurement offices specify enhanced electromagnetic resilience for next-generation platforms.
- Cargo Aircraft:Freighter conversions and dedicated cargo fleets operating high-cycle routes with accelerated maintenance intervals.
- General Aviation:Private aircraft, flight training fleets, and rotorcraft with lighter certification burdens and cost-sensitive procurement.
Civil aviation anchors the volume base while military applications gain share at the steepest rate.
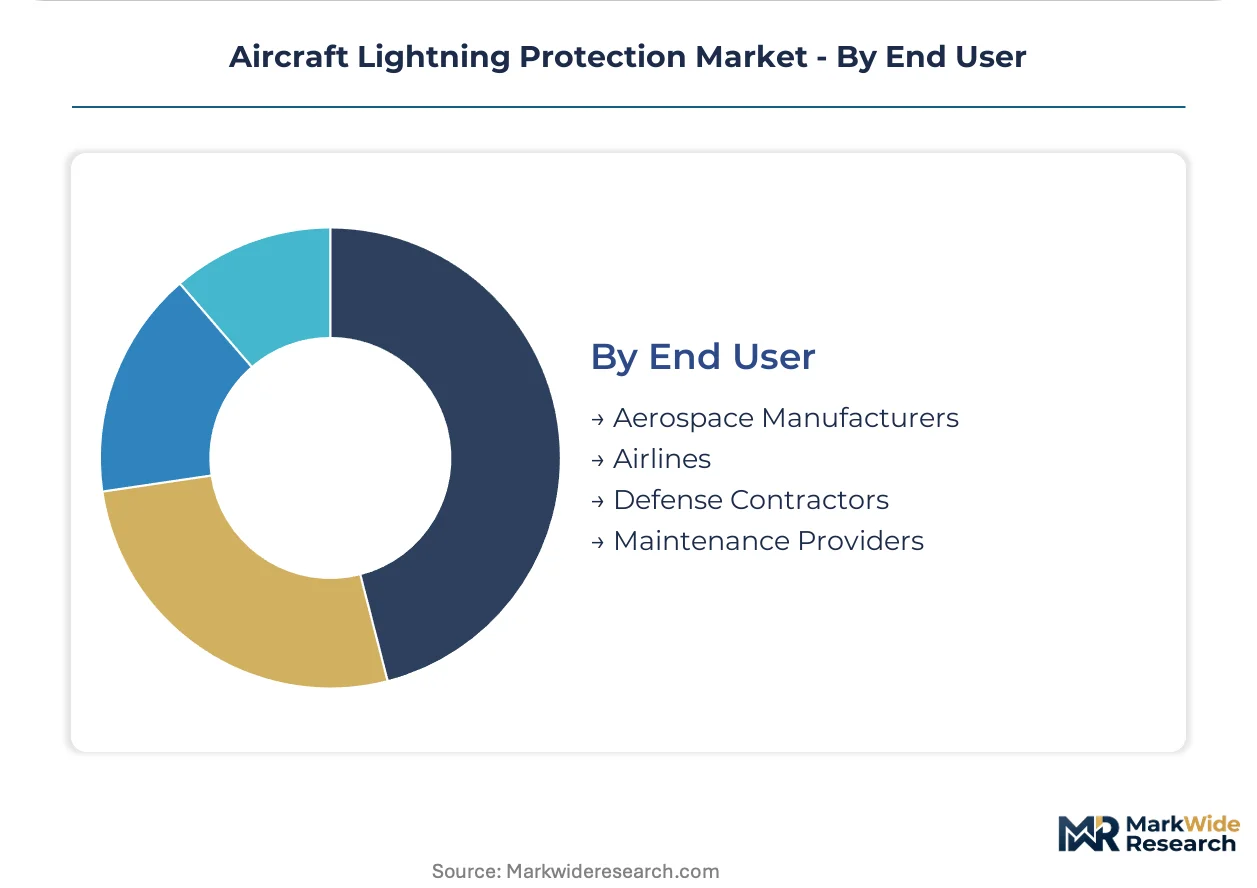
End User:
Procurement authority is consolidating toward tier-1 system integrators with full airframe coverage capabilities.
- Aerospace Manufacturers:Boeing, Airbus, and Bombardier facilities integrating strike protection at assembly stage. Everett and Charleston production lines specify conductive composite formulations for 787 and 777X wing structures.
- Defense Contractors:Lockheed Martin and Raytheon divisions embedding classified protection architectures into military platforms. Stealth-compatible mesh requirements sustain specialized supplier relationships.
- Airlines:Technical procurement departments managing fleet-wide retrofit programs and consumable replacement schedules.
- Maintenance Providers:MRO facilities performing damage repair and scheduled replacement of static dischargers and conductive sealants.
Aerospace manufacturers anchor the volume base while defense contractors gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States-based OEM procurement offices, while European MRO providers absorb compressed margins from EASA-mandated retrofit cycles. German and French tier-1 integrators leverage proximity to Airbus final assembly lines to defend specification influence.
United States
Boeing's Everett and Charleston production lines anchor OEM demand for conductive composite formulations on 787 and 777X programs. FAA airworthiness directives on narrow-body strike resilience tighten material specifications for in-service fleets. Wichita's aerostructure cluster houses specialized grounding architecture suppliers serving both commercial and defense programs.
Germany
Airbus Hamburg and Bremen facilities drive procurement for integrated lightning protection suites on A320 and A350 families. EASA CS-25 Amendment 26 provisions mandate expanded fuel tank ignition source testing, extending certification scope. Munich's aerospace engineering corridor concentrates electromagnetic hardening specialists for next-generation avionics integration.
France
Toulouse final assembly lines concentrate strike-protection specification authority for single-aisle and wide-body platforms. DGAC enforces EASA certification standards while national procurement preferences sustain domestic conductive mesh suppliers. Bordeaux's composite manufacturing cluster advances embedded metallic filament technologies for wing leading edge applications.
United Kingdom
BAE Systems' classified platform work sustains premium-tier demand for stealth-compatible protection architectures. UK Civil Aviation Authority aligns with EASA test protocols while retaining sovereign certification authority for military derivatives. Bristol's aerospace corridor hosts grounding system integrators serving both commercial and defense supply chains.
Japan
Mitsubishi Heavy Industries and Subaru Corporation procurement offices specify conductive coatings for regional jet and defense programs. METI's aerospace industrial policy channels R&D funding toward lightweight composite protection technologies. Nagoya's manufacturing cluster integrates lightning protection into carbon fiber wing structures for next-generation platforms.
Aircraft Lightning Protection Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in material and device supply. The vendor structure concentrates around tier-1 integrators with full airframe coverage capabilities, displacing historical multi-source strategies for discrete components. Three archetypes dominate: conductive materials suppliers, electromagnetic hardening specialists, and full-system integrators. Consolidation through vendor base reduction and strategic partnerships with OEM engineering offices represent the dominant competitive vectors.
Among United States-based diversified materials suppliers, PPG Industries and 3M Company exemplify the conductive coatings archetype, leveraging broad chemical formulation portfolios to sustain long-term supply positions. BAE Systems anchors the defense-specialist tier through classified platform work requiring stealth-compatible mesh specifications. These three entities occupy distinct competitive positions without overlapping core market segments.
| Leading Market Players |
|---|
| PPG Industries, Inc. |
| 3M Company |
| BAE Systems plc |
| Dayton-Granger, Inc. |
| Astroseal Products Manufacturing Corp. |
| Honeywell International Inc. |
| Amphenol Aerospace (Amphenol Corporation) |
| Henkel Corporation |
| Collins Aerospace (Raytheon Technologies) |
| Others |
Supply Flow & Price Mechanics
Wichita's aerostructure cluster concentrates specialized grounding architecture capacity, feeding Boeing's Everett and Charleston assembly lines with configured-to-order conductive composite formulations that command premium positioning over standardized static discharger replacements.
Pricing Analysis
Configured-to-order pricing for integrated strike-protection suites spreads 40-60% above catalog static discharger rates, with certification grade and airframe program scale as primary differentiation drivers. Three-tier pricing structure across OEM-integrated, MRO-contract, and spot-replacement levels is compressing at the bottom tier due to airline procurement consolidation. Defense contractors exhibit lowest price sensitivity, accepting specification premiums for stealth-compatible mesh and classified hardening protocols.
Supply Chain Analysis
Tier-1 electronics manufacturing services in Mexico and Malaysia hold surge protection device assembly capacity, drawing refined copper and silver feedstock from Chilean and Peruvian mining operations. Single-source vulnerability concentrates in conductive nanotube precursors sourced from Japanese chemical suppliers. Distribution runs through Boeing and Airbus certified vendor programs directly to final assembly lines, bypassing traditional tier-2 distributor networks for critical flight-safety components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft lightning protection market is entering a cyclical recovery phase as commercial narrow-body production rates at Boeing and Airbus facilities accelerate post-supply chain normalization, driving OEM procurement velocity for integrated protection suites.
For Market Incumbents: Pre-empt consolidation pressure from tier-1 system integrators by securing long-term formulation agreements for conductive composite wing structures at Airbus Hamburg and Boeing Charleston facilities. Deepen backward integration into silver and copper refining relationships to offset raw material volatility from Chilean supply concentration. Anchor certification investment in EASA CS-25 Amendment 26 fuel tank ignition source testing to capture expanded scope mandates. For New Entrants and Emerging Players: Establish a beachhead in urban air mobility lightning protection for German and United States-based eVTOL manufacturers, where miniaturized conductive thermoplastic demand outpaces established aerospace supplier capacity. Target digital procurement platforms serving United States legacy carrier MRO operations with standardized static discharger replacements. Lead with weight-optimized grounding solutions aligned to EU Green Deal sustainable aviation fuel targets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors conductive materials specialists with captive nanocomposite formulation capabilities over discrete component assemblers. Long-term viability hinges on qualification timelines for 270VDC fly-by-wire surge protection integration. Acquisition focus should center on electromagnetic hardening engineering teams with DO-160 Section 22 test severity escalation experience. Watch EASA fuel tank ignition source test matrix expansion as inflection signal for specification scope acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Conductive Nanocomposite Qualification | PPG Industries and 3M Company formulations at Boeing Everett displace legacy aluminum mesh suppliers. |
| EASA CS-25 Amendment 26 Certification Investment | European MRO providers must expand test matrices for fuel tank ignition source prevention. |
| Urban Air Mobility Lightning Protection Development | eVTOL manufacturers in Germany and United States require miniaturized composite-intensive solutions. |
| Digital Procurement Platform Integration | Direct-to-MRO channels bypass tier-2 distributors for standardized static discharger replacements. |
| Defense Platform Electromagnetic Hardening | BAE Systems classified work sustains premium-tier demand for stealth-compatible mesh architectures. |
Methodological Framework
A standing panel of Boeing and Airbus procurement officers, FAA certification engineers, MRO technical directors, and conductive materials R&D leads provided ongoing calibration throughout the study period. Primary interview data triangulated against secondary sources including FAA airworthiness directive filings, EASA CS-25 certification databases, OEM production rate disclosures, and United States Geological Survey mineral commodity summaries. Bottom-up segment sizing across product type, technology, and application dimensions validated through top-down OEM procurement budget analysis.
Scenario-bracketing framed low, baseline, and high cases across the projection horizon using production rate sensitivity at Boeing Everett and Charleston facilities, EASA regulatory timeline acceleration, and raw material price volatility assumptions. Segmentation modeling incorporated aircraft platform class, conductive material chemistry, certification tier, and end-user procurement authority. CAGRs derived from fitted growth curves against historical retrofit cycle data and new delivery schedules.
Sensitivities concentrate around Boeing and Airbus production rate revisions, EASA test severity escalation timelines, and Chilean copper supply disruptions. Forecasts embed assumptions regarding narrow-body fleet expansion and military platform electromagnetic hardening specifications. Quarterly review of FAA airworthiness directive issuance patterns and OEM supplier qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aviation Airbags Market