
 Airborne Lightning Detection System Market | 2026-2036
Airborne Lightning Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Lightning Detection System Market Outlook
Market Context
Defense procurement consolidation among NATO member air forces is recalibrating supplier relationships across the airborne lightning detection sector. Elbit Systems leverages its electromagnetic sensor integration expertise to sustain long-term contracts with Israeli and European military operators. Northrop Grumman anchors the high-altitude platform segment through specialized RF detection arrays designed for unmanned systems. BAE Systems competes on manufacturing scale, supplying modular lightning detection units for multi-role fighter programs.
Technical and Segment Structure
An airborne lightning detection system comprises electromagnetic field sensors, optical transient detectors, and RF pulse analyzers mounted on aircraft to identify and localize electrical discharge events within a operational radius, primarily enabling real-time flight hazard avoidance and meteorological data collection. Electromagnetic technology dominates current installations due to proven reliability in all-weather conditions, while optical detection represents the fastest-expanding category as solid-state photodiode arrays achieve microsecond response times. Defense applications concentrate the highest margin pools, whereas meteorology deployment through ground stations and satellite systems absorbs volume-driven procurement with thinner profitability.
Regulatory Environment
FAA airworthiness directives mandate minimum lightning detection performance for Part 121 commercial carriers, while EASA certification standards in Europe enforce equivalent electromagnetic compatibility thresholds for aircraft entering EU airspace. The EU AI Act introduces emerging compliance obligations for autonomous detection algorithms, prompting manufacturers to revalidate software architectures. Stakeholders must monitor divergence between FAA and EASA testing protocols for next-generation optical sensors, as regulatory misalignment threatens to fragment product certification timelines and inflate development overhead for dual-market suppliers.
Market Dynamics
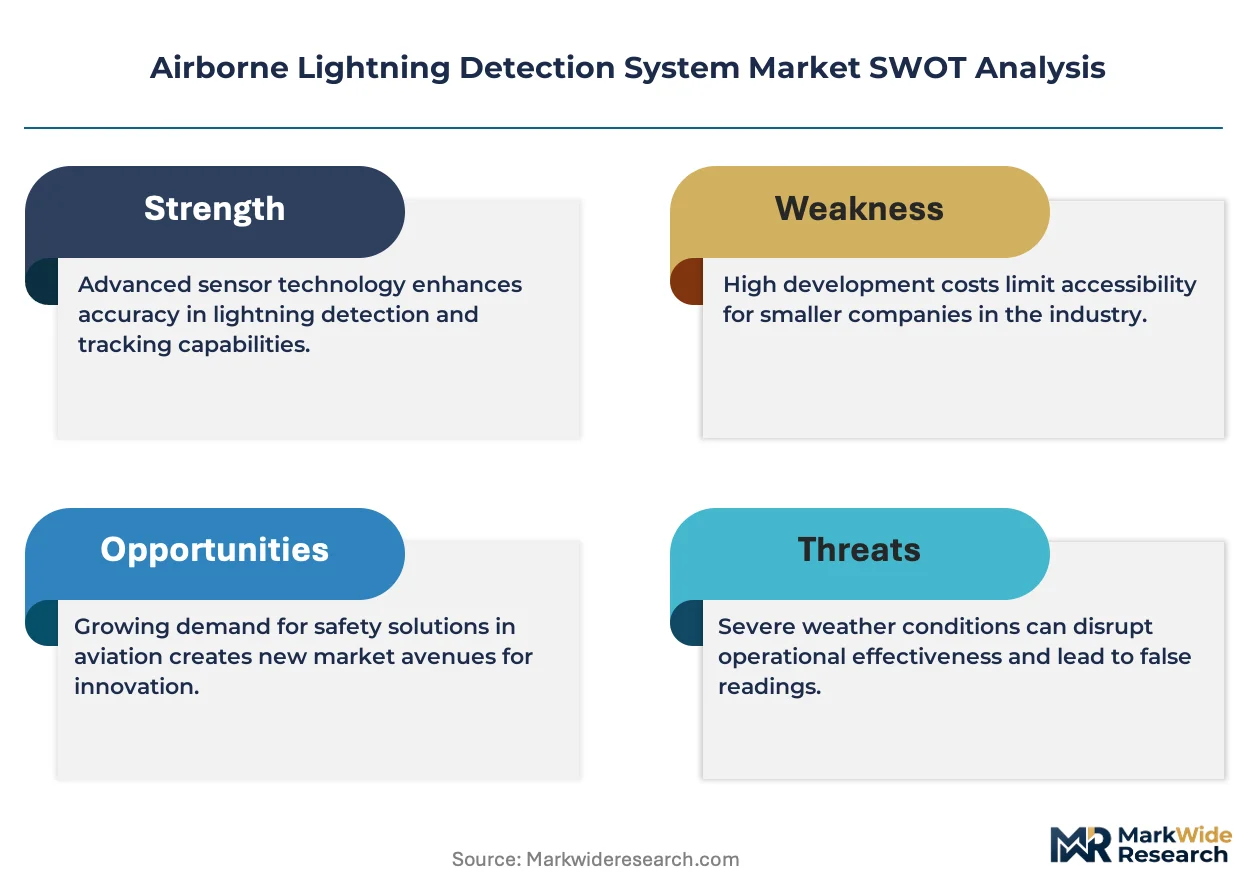
Defense procurement consolidation among NATO air forces is compressing supplier margins while accelerating electromagnetic sensor standardization across multi-role fighter platforms and unmanned systems.
Growth Catalysts
- FAA Certification Mandates:Part 121 commercial carriers must retrofit aging fleets with next-generation detection platforms, creating sustained replacement demand across United States domestic routes.
- Solid-State Photodiode Arrays:Microsecond response times in optical detection technology are opening new installation opportunities in meteorological ground stations and satellite systems.
- Flight Path Optimization:Commercial aviation fleets are integrating lightning detection sensors into unified avionics suites for real-time hazard avoidance and fuel efficiency gains.
Market Restraints
- Dual Certification Burden:Divergence between FAA and EASA testing protocols for optical sensors fragments product timelines and inflates development overhead for suppliers serving both markets.
- Electromagnetic Component Concentration:Specialized RF detection arrays for high-altitude unmanned systems depend on concentrated semiconductor foundry capacity in East Asia.
- Thin Meteorology Margins:Volume-driven procurement for ground station and satellite deployments absorbs capital without returning defense-equivalent profitability pools.
Strategic Opportunities
- EU AI Act Compliance:Autonomous detection algorithm mandates create first-mover advantages for manufacturers revalidating software architectures ahead of enforcement timelines.
- Electromagnetic-Optical Convergence:Hybrid sensor fusion combining field detection with photodiode arrays enables all-weather performance previously unattainable with single-technology systems.
- Unmanned Platform Integration:High-altitude long-endurance drones represent an underpenetrated installation base requiring miniaturized RF detection arrays with reduced power draw.
Industry Challenges
- Algorithm Validation Timelines:EU AI Act software revalidation requirements extend certification cycles for autonomous detection systems beyond traditional hardware-only approvals.
- Legacy Avionics Integration:Retrofit installations on aging commercial fleets face mechanical and electrical interface mismatches with existing flight management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Lightning Detection System Market |
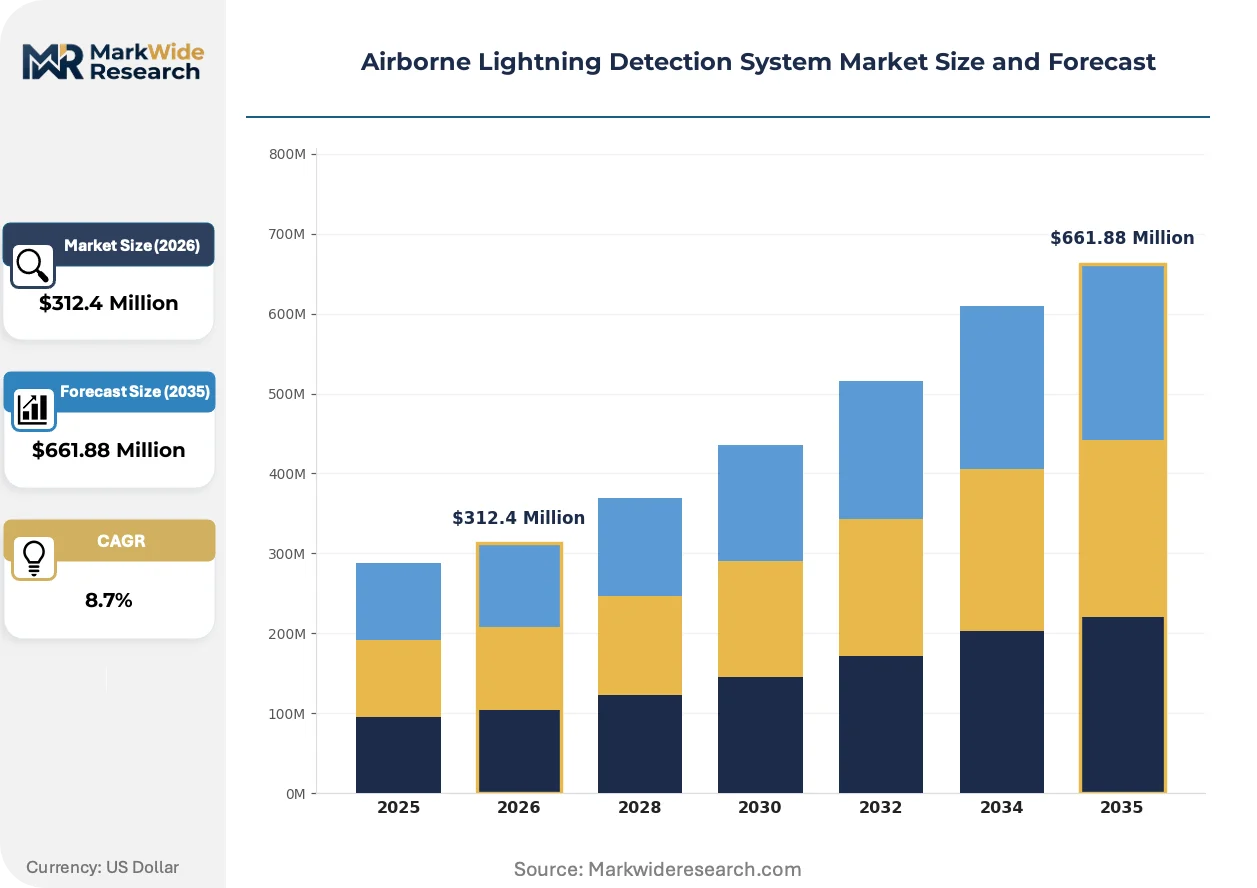
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromagnetic, Optical, Acoustic, RF Application: Aviation Safety, Meteorology, Research, Defense End User: Aerospace Companies, Research Institutions, Government Agencies, Private Sector Deployment: Onboard Systems, Ground Stations, Mobile Units, Satellite Systems |
| Companies Covered | Elbit Systems, Aselsan, L3 Technologies, Raytheon, Avidyne, Northrop Grumman, BAE Systems, Lockheed Martin Corporation, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Lightning Detection System Market Strategic Shifts
Sensor fusion architectures and autonomous software validation are compressing product development cycles while redefining competitive differentiation between electromagnetic and optical technology suppliers.
Solid-state photodiode arrays are consolidating optical detection as the fastest-expanding technology category. Meteorological ground stations and satellite operators are adopting these sensors for microsecond lightning localization. This consolidation is compressing the performance gap with electromagnetic systems in clear-weather conditions while forcing hybrid architecture investments from single-technology incumbents.
EASA electromagnetic compatibility thresholds are tightening certification requirements for aircraft entering EU airspace. Manufacturers must now demonstrate equivalent performance across broader frequency spectra before market entry. Commercial carriers operating transatlantic routes face the steepest compliance burden as they synchronize retrofit schedules with FAA Part 121 mandates.
Carrier procurement departments are bundling lightning detection into integrated avionics upgrade contracts rather than standalone sensor purchases. Tier-one system integrators are capturing value previously retained by specialized detection suppliers. This concentration is most visible among United States legacy carriers retrofitting narrow-body fleets under unified fleet management agreements.
Airborne Lightning Detection System Market Segmentation
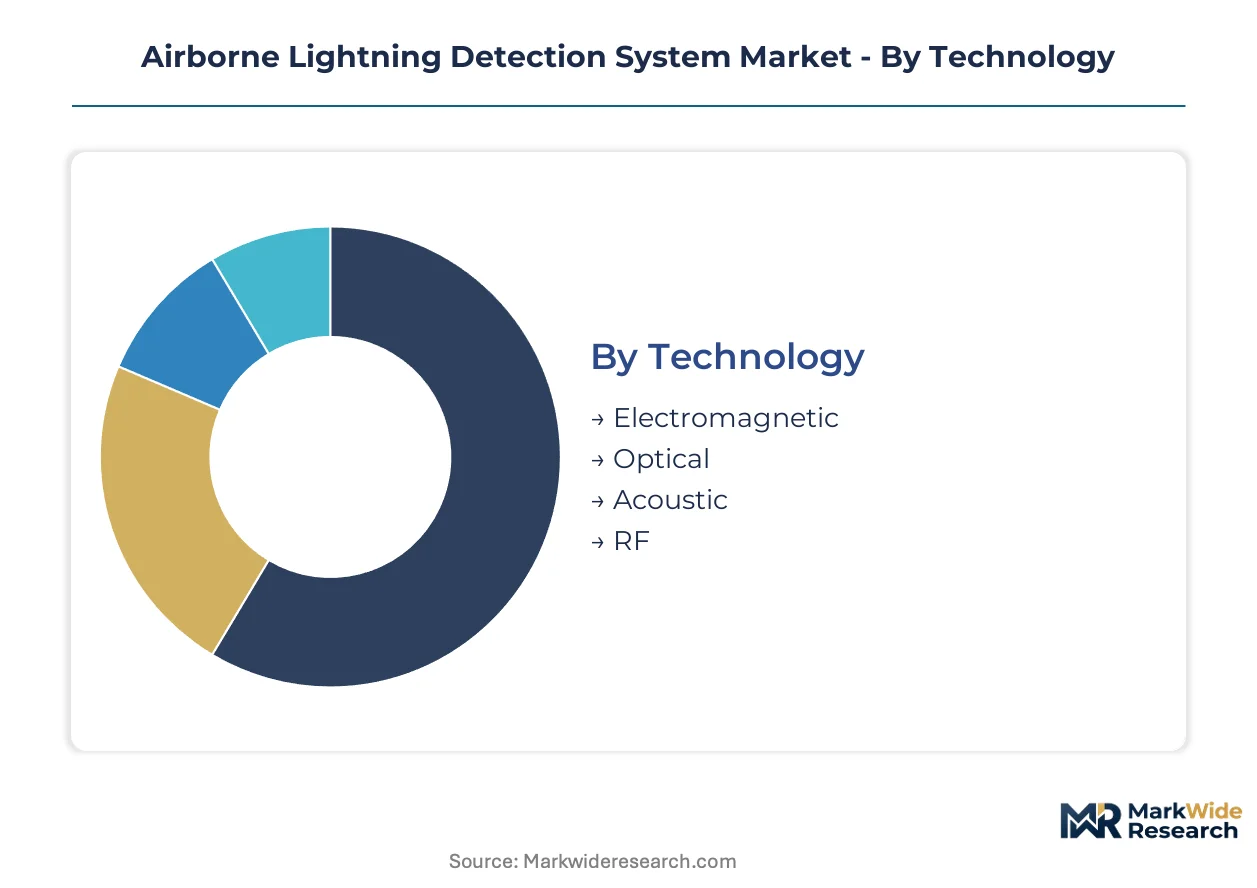
Technology heterogeneity across airborne lightning detection creates distinct supply chain configurations, with electromagnetic and optical sensor manufacturers competing for different installation profiles. Application-driven procurement patterns further fragment demand between defense-grade specifications and commercial aviation retrofit economics.
Technology:
Electromagnetic sensor suppliers concentrate manufacturing in specialized RF component foundries, while optical detection arrays depend on solid-state photodiode fabrication capacity.
- Electromagnetic:Field-based detection systems utilize antenna arrays and signal processing units to measure electrical discharge signatures across broad frequency spectra. FAA Part 121 carriers in the United States specify electromagnetic systems for all-weather reliability on transcontinental routes, though semiconductor foundry concentration in East Asia creates supply vulnerability for specialized RF components.
- Optical:Photodiode array systems capture lightning emission spectra through ultraviolet and infrared channels with microsecond temporal resolution. Meteorological ground station operators in Germany and France are consolidating procurement around solid-state optical platforms, driven by EASA electromagnetic compatibility thresholds that favor non-RF detection for certain EU airspace applications.
- Acoustic:Thunder signature analysis through airborne microphone arrays provides supplementary localization data in multi-sensor fusion architectures.
- RF:Radio frequency pulse analyzers detect lightning-generated electromagnetic emissions across aviation communication bands.
Electromagnetic technology absorbs the bulk of installed capacity; optical detection is expanding most quickly.
Application:
Defense procurement operates on cost-plus contracting with extended validation cycles, while commercial aviation demands rapid certification turnaround for fleet retrofit programs.
- Aviation Safety:Flight hazard avoidance systems integrate with flight management computers for real-time route optimization. United States domestic carriers facing FAA retrofit mandates concentrate demand in narrow-body fleet upgrades, with procurement bundled into unified avionics contracts rather than standalone sensor purchases.
- Defense:Multi-role fighter and unmanned platform programs require hardened electromagnetic detection arrays with military-grade environmental specifications. NATO air forces are consolidating supplier relationships around electromagnetic sensor standardization, compressing margins while extending contract durations for qualified vendors.
- Meteorology:Ground station and satellite deployment networks prioritize volume procurement with thinner profitability pools.
- Research:Atmospheric physics programs demand specialized calibration and data logging capabilities beyond operational aviation requirements.
Defense applications command the steepest specification requirements; aviation safety installations are climbing the fastest as fleet retrofit cycles accelerate.
End User:
Aerospace original equipment manufacturers capture value through integrated avionics bundling, while research institutions procure through specialized scientific instrumentation channels.
- Aerospace Companies:Tier-one system integrators dominate procurement decisions for new aircraft platforms and fleet retrofit programs.
- Research Institutions:University and government laboratory programs require extended calibration protocols and open data architectures.
- Government Agencies:National meteorological services and defense procurement offices operate on multi-year capital allocation cycles with stringent certification requirements.
- Private Sector:Commercial drone operators and regional aviation services represent emerging demand with cost-constrained procurement profiles.
Government agencies absorb the bulk of installed capacity; private sector adoption is gaining share fastest as unmanned platform regulations mature.
Deployment:
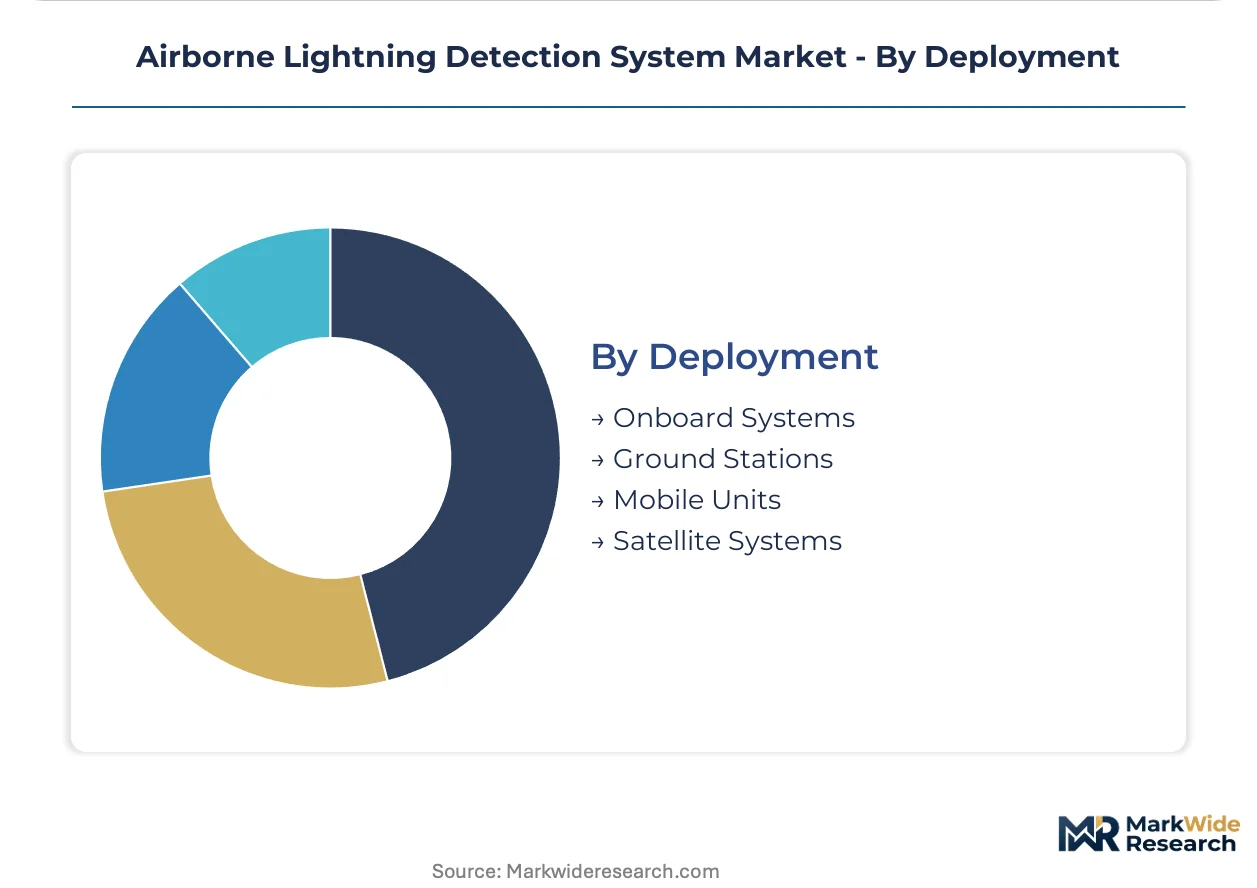
Onboard system integration demands miniaturization and electromagnetic compatibility certification, while ground station deployment prioritizes sensor density and network connectivity.
- Onboard Systems:Aircraft-mounted detection units must satisfy weight, power, and interference constraints for commercial and military airframes.
- Ground Stations:Fixed meteorological installations leverage optical photodiode arrays for regional lightning mapping with minimal atmospheric interference.
- Mobile Units:Rapidly deployable detection platforms serve temporary aviation operations and emergency response scenarios.
- Satellite Systems:Orbital lightning detection requires radiation-hardened components and specialized downlink bandwidth allocation.
Onboard systems absorb the bulk of installed capacity; satellite systems are expanding most quickly as constellation deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States domestic carriers concentrate retrofit demand as FAA Part 121 mandates drive narrow-body fleet upgrades. Defense procurement across NATO members and satellite constellation expansion in Asia-Pacific reshape regional supply priorities.
United States
FAA certification thresholds for Part 121 carriers compel systematic replacement of legacy detection hardware across domestic narrow-body fleets. The agency's tightened electromagnetic compatibility directives synchronize with airline fleet management agreements bundling lightning sensors into unified avionics contracts. Dallas-Fort Worth and Atlanta aerospace clusters host concentrated MRO capacity executing these retrofit programs.
Germany
EASA electromagnetic compatibility standards enforce equivalent detection performance across broader frequency spectra for EU airspace entry. The EU AI Act introduces autonomous algorithm validation obligations that extend software certification timelines beyond traditional hardware approvals. Munich and Hamburg defense electronics corridors concentrate NATO multi-role fighter integration work.
France
Meteorological ground station operators consolidate procurement around solid-state optical platforms for regional lightning mapping networks. EASA thresholds favor non-RF detection modalities for specific EU airspace applications, redirecting procurement toward photodiode array suppliers. Toulouse aerospace engineering clusters anchor cross-border fighter program sensor standardization efforts.
Israel
Defense procurement prioritizes hardened electromagnetic detection arrays for unmanned platform programs operating in contested electromagnetic environments. Israeli military specifications drive miniaturization requirements for high-altitude long-endurance drone integration. Haifa and Tel Aviv defense technology corridors concentrate electromagnetic sensor foundry and integration expertise.
Japan
METI aviation safety directives align domestic carrier retrofit schedules with international certification reciprocity agreements. Satellite constellation operators in the Asia-Pacific region source radiation-hardened components for orbital lightning detection networks. Nagoya and Tokyo aerospace manufacturing clusters produce integrated avionics suites incorporating detection subsystems for regional jet platforms.
Airborne Lightning Detection System Market Competitive Environment
United States producers anchor the high-specification defense tier; European specialists hold meteorological and commercial aviation retrofit segments. Market structure concentrates around electromagnetic sensor integration for military applications while fragmenting across optical photodiode suppliers serving ground station networks. Three archetypes dominate: defense-prime system integrators, specialized RF component fabricators, and solid-state optical sensor developers. Competitive moves center on electromagnetic-optical hybrid architecture development and unmanned platform miniaturization programs.
Within the defense-prime tier, Elbit Systems and Northrop Grumman exemplify electromagnetic sensor integration archetypes, while BAE Systems occupies a position representing manufacturing-scale modular supply. These three anchors illustrate how supplier relationships consolidate around NATO standardization mandates while diverging across unmanned versus manned platform specializations.
| Leading Market Players |
|---|
| Elbit Systems |
| Aselsan |
| L3 Technologies |
| Raytheon |
| Avidyne |
| Northrop Grumman |
| BAE Systems |
| Lockheed Martin Corporation |
| Honeywell International |
| Others |
Value Chain & Pricing Dynamics
RF engineering talent concentration in Israel and the United States creates labor-cost differentials that widen pricing-tier spreads between defense-grade electromagnetic arrays and commercial aviation retrofit units. Defense procurement absorbs premium pricing through cost-plus contracting while commercial carriers negotiate volume discounts on bundled avionics upgrades.
Pricing Analysis
Volume procurement in meteorology ground stations trades margin for market presence while defense applications retain pricing power through specification complexity. Three-tier pricing structure across FAA-certified, EASA-equivalent, and non-certified economy levels separates buyers by regulatory stringency and after-sales service bundling. Price differentiation hinges on electromagnetic compatibility certification tier and foundry-sourced component grade. Cost compression in commercial aviation retrofits is intensifying as fleet management agreements consolidate procurement leverage with tier-one system integrators. Regional aviation services exhibit highest price sensitivity; NATO defense offices demonstrate least.
Supply Chain Analysis
FAA and EASA certification gates restrict qualified supplier pools to electromagnetic sensor foundries with demonstrated airworthiness validation histories. Specialized RF component fabrication concentrates in Israel, the United States, and selected European defense corridors. Solid-state photodiode arrays draw from semiconductor foundry capacity in East Asia and Germany. Single-source vulnerability in radiation-hardened components for satellite systems threatens constellation deployment schedules. Distribution runs through tier-one aerospace system integrators capturing value previously retained by standalone detection specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around electromagnetic-optical hybrid architectures as dual-certification burdens force weaker players toward exit or acquisition. FAA-EASA regulatory divergence accelerates shakeout among single-technology suppliers lacking software validation capabilities.
For Market Incumbents: Extend electromagnetic sensor integration expertise into optical photodiode fusion architectures before EU AI Act enforcement timelines close. Lock in long-term NATO multi-role fighter contracts through electromagnetic standardization commitments. Invest in software architecture revalidation to preempt algorithm certification delays that threaten hardware-only suppliers.
For New Entrants and Emerging Players: Capture unmanned platform miniaturization demand in Israeli and Asia-Pacific defense corridors where incumbent presence remains thin. Target high-altitude long-endurance drone programs requiring reduced-power RF detection arrays. Lead with electromagnetic-optical hybrid prototypes offering all-weather performance previously unavailable from single-technology incumbents.
For Investors and Strategic Acquirers: Re-rating potential sits with electromagnetic-optical hybrid specialists given EU AI Act compliance mandates and unmanned platform integration demand. Long-term viability favors suppliers with dual-certification capabilities spanning FAA Part 121 and EASA electromagnetic compatibility thresholds. Signal to watch: NATO standardization directives consolidating supplier relationships around qualified electromagnetic sensor integrators.
| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic-Optical Hybrid Development | Fusion architectures satisfy EASA electromagnetic compatibility thresholds while retaining all-weather reliability. |
| EU AI Act Software Revalidation | Autonomous detection algorithm compliance creates first-mover certification advantages before enforcement. |
| Unmanned Platform Miniaturization | Reduced-power RF arrays open high-altitude long-endurance drone installations previously inaccessible. |
| NATO Supplier Consolidation | Standardization mandates compress margins while extending contract durations for qualified electromagnetic integrators. |
| Avionics Bundling Partnership | Tier-one system integrators capture procurement decisions previously held by standalone detection specialists. |
Study Parameters
Document review covered FAA airworthiness directives, EASA certification standards, EU AI Act implementation guidance, and NATO procurement announcements, complemented by interviews with electromagnetic sensor engineering directors, commercial aviation fleet procurement managers, defense procurement officers, and meteorological ground station operators. Secondary validation drew from SEC filings of listed aerospace suppliers, customs records of RF component trade flows, and satellite constellation deployment databases. Bottom-up installation forecasts triangulated against top-down defense and commercial aviation budget allocations.
Historical retrofit cycle patterns cross-referenced against panel input from MRO facility planners and avionics integration specialists shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application category, deployment platform, and regional regulatory cluster. CAGRs were derived from installation base expansion rates adjusted for fleet replacement cycles and satellite constellation deployment schedules. Industry-specific inputs incorporated FAA Part 121 mandate compliance timelines and EASA electromagnetic compatibility threshold evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to semiconductor foundry capacity allocation and EU AI Act enforcement timing. Forecasts reflect assumptions regarding NATO standardization continuity and transatlantic certification reciprocity. A model refresh is warranted upon material change in FAA-EASA regulatory alignment or unmanned platform procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Rescue Hoist System Market