
 Aircraft Evacuation Slide Market | 2026-2036
Aircraft Evacuation Slide Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Evacuation Slide Market Analysis
Market Context
FAA evacuation certification timelines are consolidating the supplier landscape around firms with full-cycle testing capabilities. Survitec Group leverages its integrated survival systems portfolio to anchor military and commercial contracts across NATO-aligned fleets. Safran Aerosystems sustains its position through co-development agreements with Airbus and Boeing production lines. Collins Aerospace differentiates via digital twin-enabled slide deployment verification that reduces recertification costs for airline operators.
Technical Definition and Segment Structure
Aircraft evacuation slides are pneumatically deployed descent devices constructed from coated fabric assemblies rated for temperature extremes and UV degradation, designed to evacuate occupants from door and over-wing exits within regulatory time limits. The product category spans passenger slides, crew slides, tactical slides, and inflatable slides, with passenger slides occupying the largest installed base due to mandatory dual-door configurations on commercial narrow-body aircraft. Military forces represent the fastest-growing end user as defense procurement shifts toward multi-role transport platforms requiring tactical slide variants for austere-field operations.
Regulatory Framework and Outlook
FAA Part 25 and EASA CS-25 airworthiness codes govern slide deployment force, inflation time, and load-bearing thresholds, while ISO 9100 quality standards shape supplier qualification protocols for tier-one aerostructures procurement. Military specification MIL-PRF-83388 implicates additional survival-grade requirements for tactical slide variants used in combat search and rescue. Stakeholders must monitor evolving fire-resistance mandates from the EU Green Deal chemicals framework, as flame-retardant coating reformulations threaten to disrupt established material supply chains and recertification schedules.
Market Dynamics
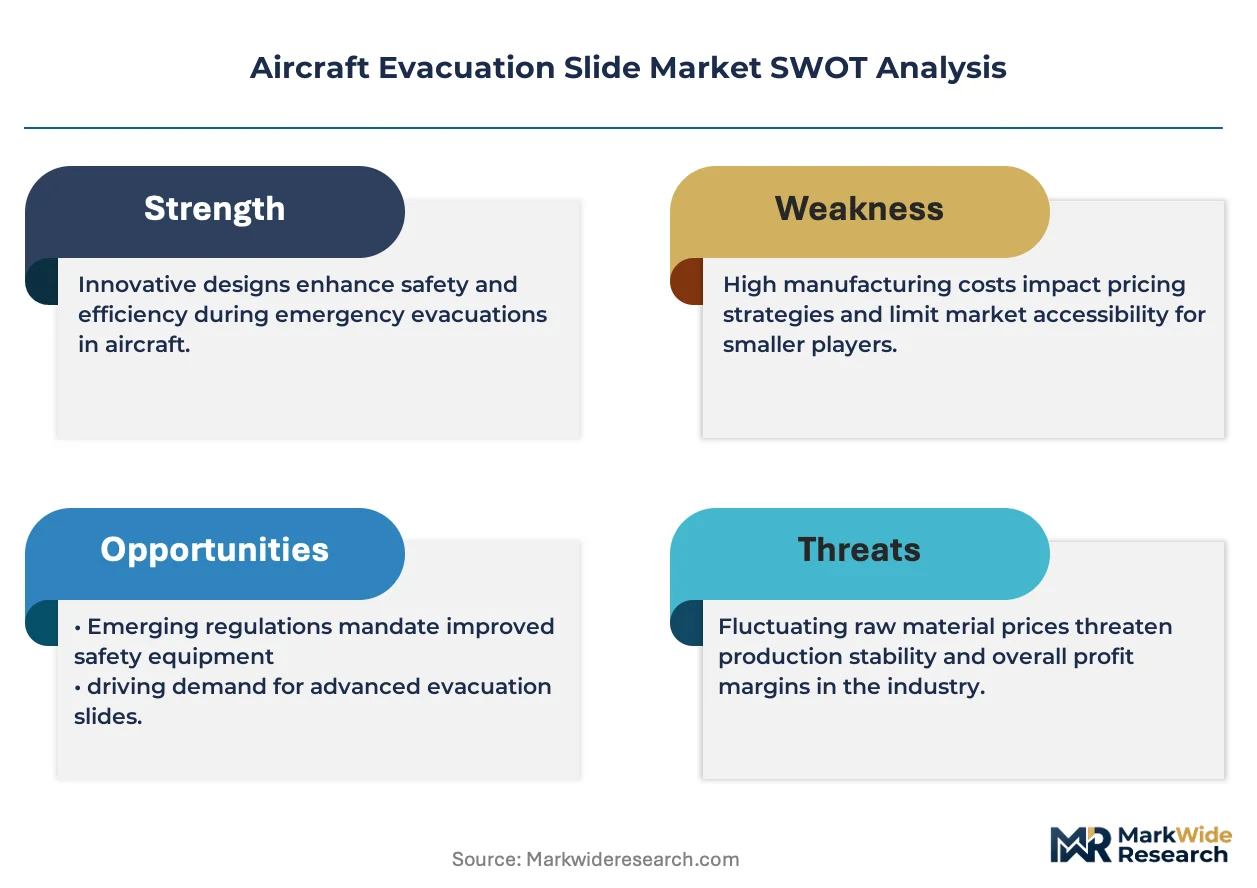
FAA Part 25 evacuation certification timelines are compressing supplier qualification cycles, forcing tier-two fabricators to exit as full-cycle testing capabilities become the minimum viable threshold for commercial aviation contracts.
Growth Catalysts
- FAA 90-Second Mandate:Stricter FAA Part 25 deployment timelines are forcing airlines to accelerate slide replacement schedules across narrow-body and wide-body fleets, sustaining aftermarket demand through mandatory compliance windows.
- Commercial Fleet Expansion:Boeing and Airbus delivery backlogs for single-aisle aircraft are embedding slide procurement into multi-year production contracts, locking in volume commitments from assembly line activation.
- Aramid Fiber Advances:Next-generation aramid-reinforced coated fabrics are extending service intervals and reducing weight penalties, enabling OEMs to bundle slide upgrades with cabin retrofit programs.
Market Restraints
- Specialized Polymer Concentration:Polyurethane coating supply chains concentrate among three European chemical suppliers, exposing slide manufacturers to input cost volatility and allocation risk during petrochemical disruptions.
- Certification Reciprocity Friction:Divergent FAA-EASA test protocols for cold-weather deployment validation force dual certification expenditures, raising effective barriers for mid-tier suppliers lacking transatlantic testing infrastructure.
- Extended Asset Lifecycles:Modern slide assemblies now exceed twelve-year certified intervals, compressing replacement frequency and elongating revenue recognition timelines for aftermarket providers.
Strategic Opportunities
- Urban Air Mobility Integration:eVTOL platform developers in the United States are specifying compact inflation systems for emergency egress, opening a nascent demand vertical outside traditional commercial aviation procurement channels.
- EU Green Deal Chemical Reform:Flame-retardant coating reformulation mandates are creating first-mover advantage for suppliers with bio-based polymer certification, potentially reshaping tier-one procurement qualification protocols.
- Digital Twin Verification:Virtual deployment simulation is enabling predictive maintenance contracts and remote recertification, allowing slide service providers to unbundle physical inspection from compliance documentation.
Industry Challenges
- Composite Repair Technician Scarcity:Qualified personnel for coated fabric damage assessment and field repair remain concentrated at OEM-affiliated MRO facilities, constraining turnaround capacity during peak fleet retrofit seasons.
- Legacy System Integration Complexity:Retrofit slide installations on aging regional jet platforms require structural modifications to door frames and inflation trigger mechanisms, extending downtime and complicating airline scheduling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Evacuation Slide Market |
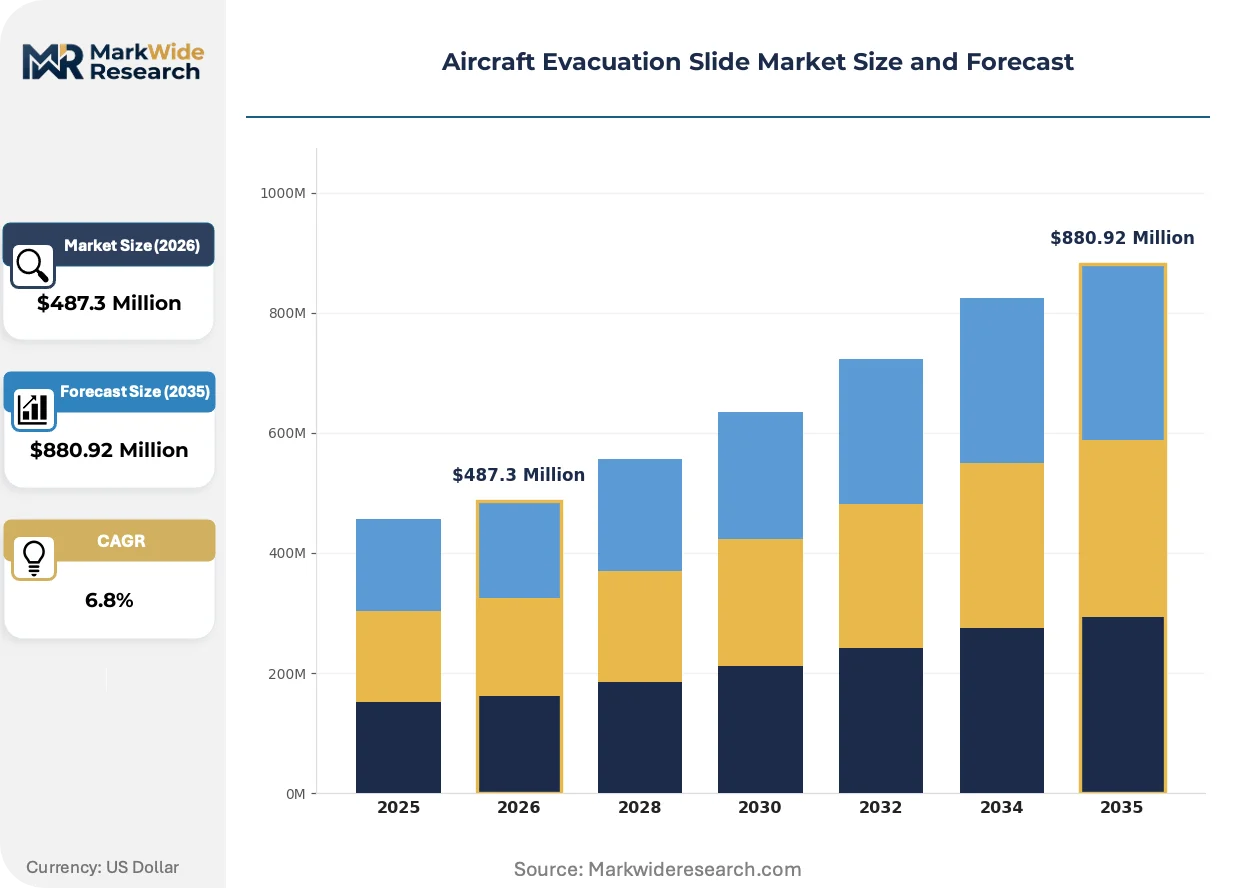
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger Slides, Crew Slides, Tactical Slides, Inflatable Slides End User: Commercial Airlines, Military Forces, Cargo Operators, Private Jets Deployment: Fixed Installation, Portable Solutions, Customizable Designs, Emergency Use Material: Fabric, Polymer, Composite, Metal |
| Companies Covered | Survitec Group, Astronics Corporation, Safran Aerosystems, Parker Hannifin, Diehl Aviation, Collins Aerospace, Trelleborg AB, AmSafe Bridport, Meggitt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Evacuation Slide Market Emerging Trajectories
Material science convergence with digital verification protocols is redefining how evacuation systems are specified, tested, and maintained across the commercial aviation value chain.
Self-healing polymer coatings are absorbing micro-abrasion damage during routine deployment exercises, extending certified service intervals. Regional carriers in the United States are piloting these formulations to reduce MRO touchpoints. The technology is absorbing maintenance volume that previously flowed to scheduled replacement programs, compressing aftermarket revenue predictability for traditional service providers.
REACH chemical restriction proposals under the EU Green Deal are compelling coating reformulations ahead of flame-retardant substance sunset dates. Manufacturers serving European-registered fleets are accelerating qualification timelines for halogen-free alternatives. Narrow-body operators with high cycle counts face the steepest compliance cost exposure, driving consolidation toward suppliers with pre-certified material portfolios.
Airline technical procurement teams are unbundling slide inspection from OEM service contracts, awarding standalone compliance verification to specialized MRO networks. This disintermediation is most visible among low-cost carriers in the United States seeking to arbitrage labor rate differentials between airline-affiliated and independent maintenance facilities. The shift is fragmenting vendor relationships and compressing pricing transparency across the aftermarket.
Aircraft Evacuation Slide Market Segmentation
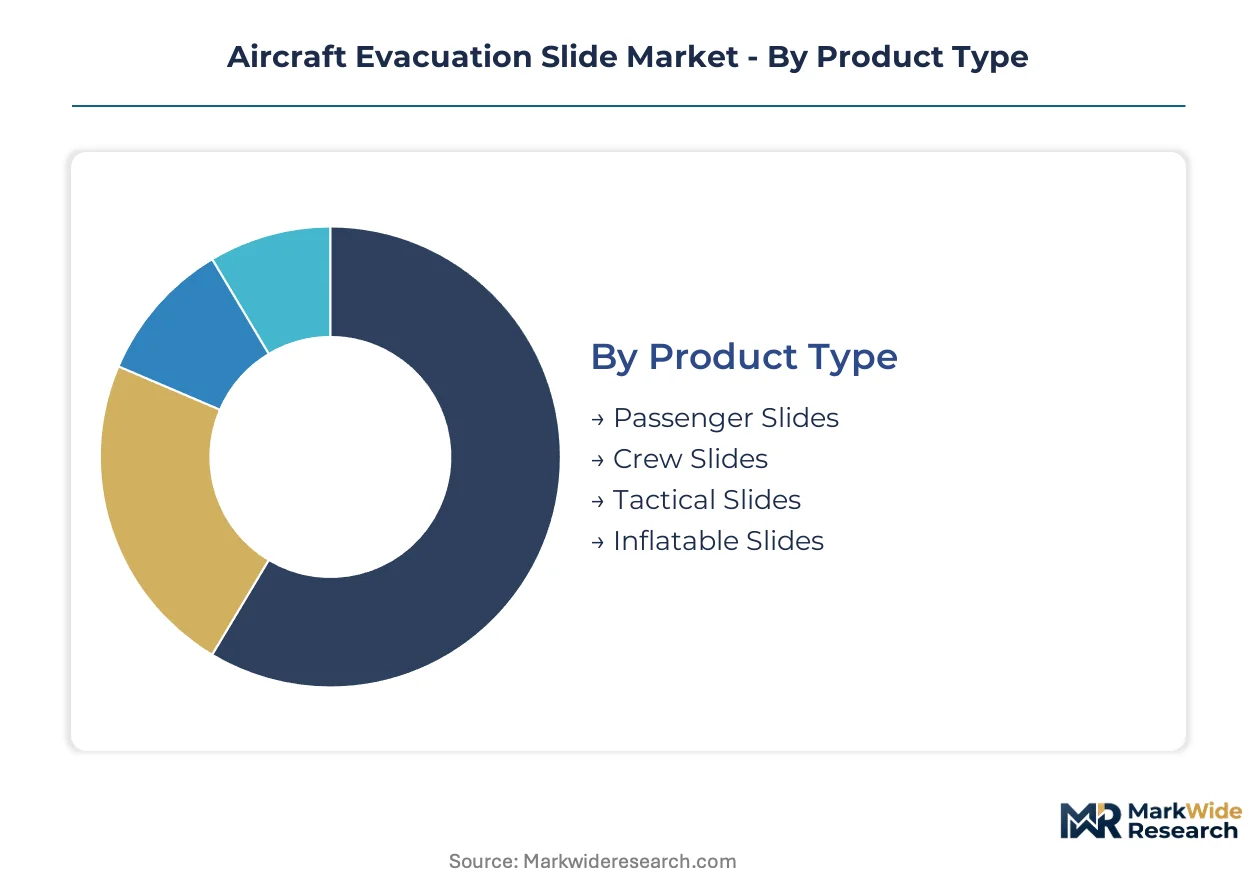
Segmentation in aircraft evacuation slides reflects divergent certification burdens and operational tempo across buyer types. Procurement specifications fragment sharply between commercial airlines chasing FAA compliance windows and military forces optimizing for austere-field deployability.
Product Type:
Airline technical procurement teams weight deployment reliability against recertification cost when specifying slide categories.
- Passenger Slides:Dual-door pneumatic assemblies constructed from aramid-reinforced coated fabrics rated for temperature extremes. United States narrow-body operators drive replacement volume through mandatory 90-second evacuation compliance retrofits.
- Crew Slides:Compact single-exit variants with integrated lighting and handrail systems for cockpit and galley egress points. Regional jet fleets in the United States concentrate demand as aging platforms require structural door modifications.
- Tactical Slides:Military-specification assemblies meeting MIL-PRF-83388 survival-grade requirements for combat search and rescue operations.
- Inflatable Slides:Auxiliary over-wing and emergency exit systems with rapid-inflation triggers for high-cycle commercial deployment.
Volume sits with Passenger Slides; growth tilts toward Tactical Slides.
End User:
Buyer procurement authority determines specification complexity and contract duration.
- Commercial Airlines:Fleet-wide slide replacement programs synchronized with FAA Part 25 recertification timelines. Low-cost carriers in the United States are unbundling inspection from OEM service contracts to arbitrage labor rate differentials.
- Military Forces:Multi-role transport platform procurement embedding tactical slide variants for austere-field operations. NATO-aligned fleets are expanding fastest.
- Cargo Operators:Converted freighter aircraft requiring slide reconfiguration for reduced crew complements and modified exit layouts.
- Private Jets:Custom cabin configurations with bespoke slide dimensions tied to luxury interior integration schedules.
Procurement volume clusters with Commercial Airlines; Military Forces are expanding most quickly.
Deployment:
Installation permanence shapes maintenance liability and asset ownership structures.
- Fixed Installation:Permanent door-mounted assemblies with integrated inflation canisters and girt bar mechanisms. Wide-body production lines at Boeing and Airbus embed these into multi-year supply contracts.
- Portable Solutions:Rapid-attach systems for temporary aircraft configurations and lease return standardization.
- Customizable Designs:Modular slide architectures accommodating non-standard exit geometries on VIP and head-of-state aircraft.
- Emergency Use:Standalone deployment systems for auxiliary exits and ditching scenarios with manual inflation triggers.
Fixed Installation dominates fleet economics; Portable Solutions are gaining share fastest.
Material:
Coating chemistry and substrate selection determine service intervals and regulatory compliance exposure.
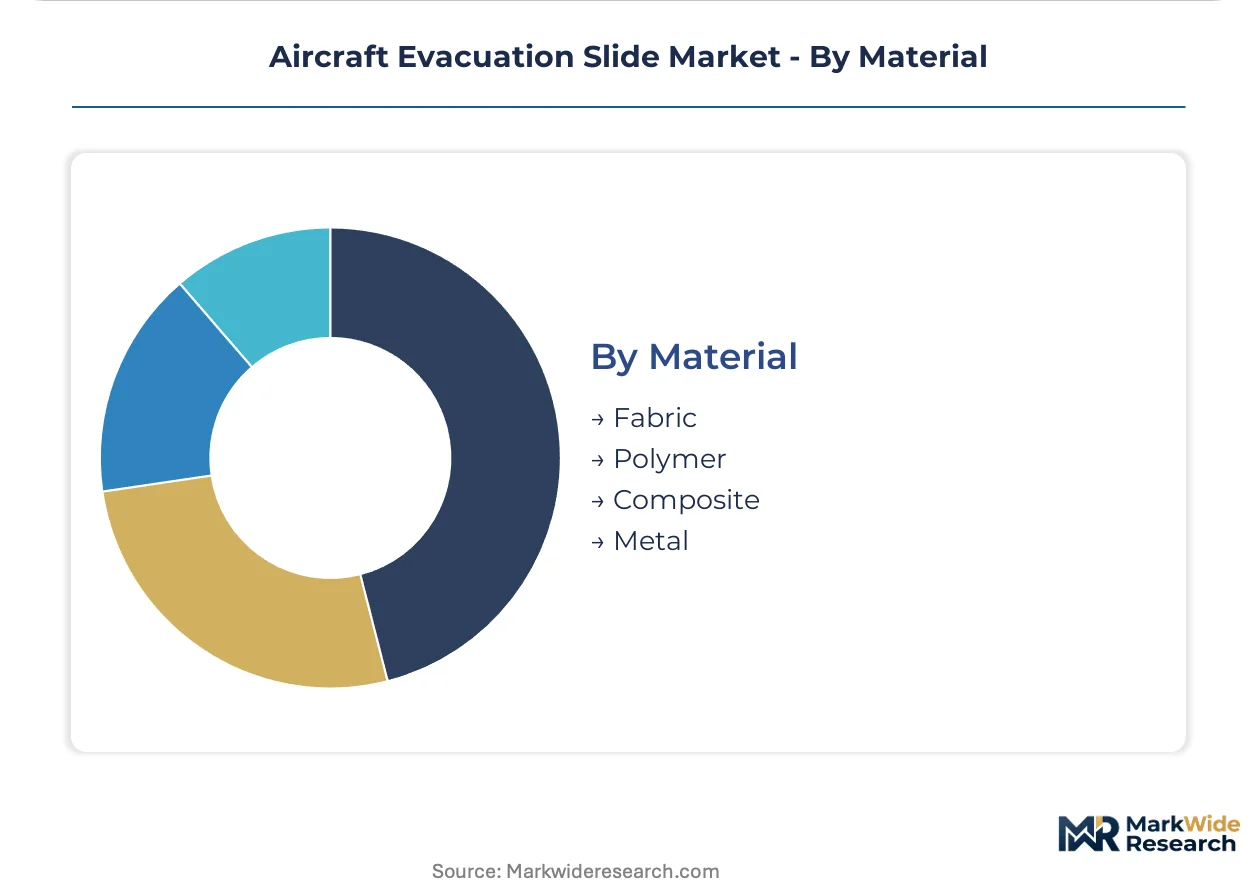
- Fabric:Aramid and polyester base cloths with polyurethane coatings for abrasion resistance and UV degradation protection. European chemical suppliers concentrate coating supply, exposing manufacturers to petrochemical disruption risk.
- Polymer:Advanced thermoplastic formulations for lightweight slide surfaces and self-healing micro-abrasion recovery. Regional carriers in the United States pilot these to reduce MRO touchpoints.
- Composite:Hybrid material stacks combining fabric substrates with polymer reinforcement layers for extended certified intervals exceeding twelve years.
- Metal:Structural girt bars, deployment brackets, and inflation trigger housings in aluminum and corrosion-resistant alloys.
Fabric commands installed base; Polymer shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign-trade zones in the United States concentrate aircraft evacuation slide manufacturing and MRO capacity, with bonded warehousing provisions reducing duty exposure on imported aramid fabrics and polymer coatings from European chemical suppliers.
United States
Boeing production lines in Washington and South Carolina embed slide procurement into multi-year supply contracts, while FAA Part 25 recertification timelines compress supplier qualification cycles. The FAA mandates 90-second evacuation compliance for all commercial fleet retrofits. Wichita, Kansas hosts a dense cluster of tier-one aerostructures fabricators serving both OEM assembly and aftermarket replacement demand.
Germany
Diehl Aviation maintains integrated production facilities for narrow-body and wide-body slide assemblies, serving Airbus final assembly lines in Hamburg and Toulouse. EASA CS-25 airworthiness codes govern deployment force and inflation time thresholds, with REACH chemical restrictions forcing coating reformulations ahead of flame-retardant substance sunset dates. The Bavarian aerospace corridor around Munich concentrates specialized polymer research and full-cycle testing infrastructure.
France
Safran Aerosystems anchors domestic supply through co-development agreements with Airbus production schedules, embedding slide systems into A320 and A350 delivery backlogs. The EU Green Deal chemicals framework implicates additional compliance burdens for halogen-free coating alternatives. The Toulouse-Blagnac aerospace cluster integrates slide manufacturing with adjacent survival systems and emergency equipment production.
United Kingdom
Survitec Group leverages its integrated survival systems portfolio to anchor military and commercial contracts across NATO-aligned fleets, with particular strength in tactical slide variants for multi-role transport platforms. UK Defence Equipment & Support procurement frameworks prioritize austere-field deployability specifications. The South West England aerospace cluster around Bristol and Yeovil concentrates defense-aerospace manufacturing and survival-grade testing capabilities.
China
Commercial Aircraft Corporation of China (COMAC) C919 production ramp-up is embedding domestic slide procurement into indigenous narrow-body programs, displacing some import dependency. The Civil Aviation Administration of China enforces parallel certification protocols to FAA Part 25, with additional cold-weather deployment validation for high-altitude operations. The Shanghai Pudong aerospace industrial zone concentrates foreign joint-venture facilities and tier-two fabricator networks.
Aircraft Evacuation Slide Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. Tier-one OEM-affiliated suppliers dominate production-line contracts through co-development agreements and captive supply relationships, while independent MRO networks fragment aftermarket service and recertification revenue. Three archetypes populate the vendor base: integrated survival systems conglomerates, aerostructures-focused engineering specialists, and polymer-coating material science firms. Competitive moves concentrate on strategic partnerships for digital twin verification capabilities and geographic expansion into emerging eVTOL platform specifications.
Within the integrated survival systems tier, Survitec Group exemplifies full-portfolio positioning across military and commercial segments. Among aerostructures specialists, Safran Aerosystems and Collins Aerospace occupy positions tied to major OEM production schedules, with the latter representing digital twin-enabled verification approaches. Diehl Aviation anchors European narrow-body supply through Airbus-aligned contract structures.
| Leading Market Players |
|---|
| Survitec Group |
| Astronics Corporation |
| Safran Aerosystems |
| Parker Hannifin |
| Diehl Aviation |
| Collins Aerospace |
| Trelleborg AB |
| AmSafe Bridport |
| Meggitt |
| Others |
Supply Flow & Price Mechanics
Aramid-reinforced coated fabric qualification is compressing supplier tiers while simultaneously elevating cost structures for commercial aviation contracts. FAA Part 25 full-cycle testing mandates are forcing tier-two fabricators to exit, concentrating pricing power among integrated survival systems conglomerates with captive polymer coating supply.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as airlines face compressed FAA recertification windows. Three-tier pricing structure across OEM-integrated, independent MRO, and spot procurement channels separates bundled service contracts from unbundled inspection awards. Cost compression in the independent MRO tier is intensifying because low-cost carriers arbitrage labor rate differentials between airline-affiliated and independent maintenance facilities. Cargo operators exhibit highest price sensitivity due to converted freighter reconfiguration economics, while head-of-state private jet buyers absorb premium customization margins.
Supply Chain Analysis
Composite repair technician scarcity in Wichita, Kansas and the Bavarian aerospace corridor is constraining turnaround capacity during peak fleet retrofit seasons. Polyurethane coating supply concentrates in Germany, France, and Belgium, drawing from European petrochemical feedstocks and aramid fiber substrates. Single-source vulnerability pervades the halogen-free flame-retardant coating transition as REACH sunset dates approach. Distribution runs through bonded warehousing provisions in United States foreign-trade zones, reducing duty exposure on imported fabric assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 25 certification timelines have erected a cost-of-compliance moat that protects qualified incumbents while excluding capital-constrained entrants. The 90-second evacuation mandate creates sustained replacement demand that rewards players with full-cycle testing infrastructure.
For Market Incumbents: Cement qualification advantages by accelerating halogen-free coating certification ahead of EU Green Deal enforcement. Expand captive polymer research capacity in the Bavarian aerospace corridor to offset European chemical supplier concentration. Digital twin-enabled remote recertification represents the priority capability investment to defend against MRO network disintermediation by low-cost carrier procurement teams.
For New Entrants and Emerging Players: Independent MRO networks present the most penetrable channel for aftermarket service contracts unbundled from OEM relationships. Target eVTOL platform developers in the United States urban air mobility segment, where compact inflation system specifications remain undefined and procurement channels are nascent. Pursue bio-based polymer certification as a first-mover qualification pathway for European-registered fleet compliance.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated survival systems conglomerates seeking full-portfolio positioning. Long-term viability hinges on certification asset durability rather than production scale. Acquisition targets should display pre-qualified material portfolios and established FAA-EASA dual certification infrastructure. Watch for divergence in FAA-EASA test protocol harmonization as the inflection signal for mid-tier supplier distress.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Verification Capability | Collins Aerospace deploys virtual deployment simulation to unbundle physical inspection from compliance documentation. |
| Backward Integration into Polymer Coating | Survitec Group secures supply continuity for aramid-reinforced fabric assemblies amid REACH chemical reformulation. |
| eVTOL Platform Specification Partnership | Safran Aerosystems embeds compact inflation systems into emerging urban air mobility procurement channels. |
| Halogen-Free Coating Pre-Certification | Diehl Aviation accelerates qualification timelines to capture narrow-body operator compliance cost exposure. |
| MRO Network Geographic Expansion | Independent maintenance facilities arbitrage labor rate differentials for low-cost carrier inspection contracts. |
Methodological Framework
Independent corroboration across OEM procurement executives, MRO operations directors, and polymer coating R&D leads underwrites the qualitative findings in this study. Primary interviews with FAA certification engineers, airline technical procurement managers, and defense aerospace program officers combined with secondary validation from FAA Part 25 airworthiness directives, EASA CS-25 certification databases, and EU Green Deal chemical restriction proposals. Bottom-up fleet retrofit demand modeling and top-down aerostructures procurement analysis triangulate volume estimates.
Rate-of-change decomposition across product type, end user, deployment configuration, and material chemistry dimensions structures the analytical framework. CAGRs derive from segment-level replacement cycle analysis and production line embedding rates across the projection horizon. Industry-specific forecast inputs include Boeing and Airbus delivery backlog schedules, FAA recertification timeline compression effects, and military multi-role transport platform procurement trajectories.
Caveats apply where REACH flame-retardant coating reformulation timelines or FAA-EASA test protocol harmonization efforts could materially shift the outlook. Forecasts reflect assumptions regarding certification reciprocity stability and petrochemical supply continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Airborne Lightning Detection System Market
Aircraft Safety Systems
Helicopter Emergency Flotation System Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Aircraft Braking System Market