
 Engineered Material Arresting System Market | 2026-2036
Engineered Material Arresting System Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered Material Arresting System Market Analysis
Project finance and long-term leasing arrangements for airport infrastructure is reconfiguring how arresting system vendors secure contracts and deploy capital. Runway Safe Group leverages its specialized manufacturing scale to dominate European EMAS installations. Curtiss-Wright Corporation sustains competitive positioning through backward integration into high-performance material substrates. QinetiQ Group plc anchors its presence in military base applications with technology leadership in active arresting mechanisms.
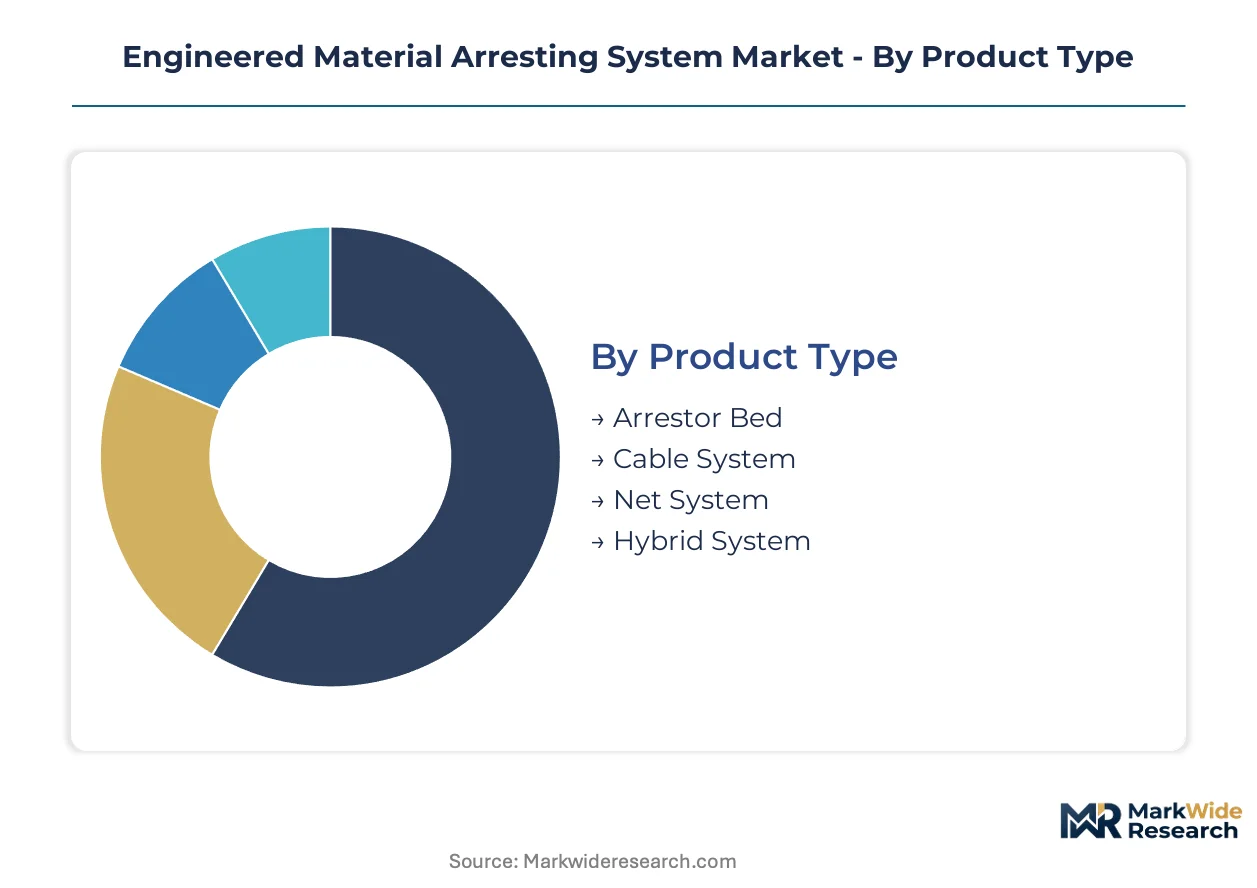
Engineered material arresting systems are deceleration structures composed of crushable cellular cement or lightweight aggregate blocks designed to absorb kinetic energy from overrunning aircraft, typically supporting aircraft weights up to and exceeding commercial narrow-body specifications. These systems function as passive safety barriers installed beyond runway thresholds, engineered to collapse predictably under wheel loading while preserving airframe integrity. Arrestor bed installations command the largest installed base among product types, though hybrid systems integrating mechanical and electromechanical elements represent the fastest-growing configuration as airports seek multi-threat capability. Military base end users sustain premium pricing for certified systems, while commercial aviation applications drive volume through regulatory retrofit mandates.
The FAA mandates EMAS installations at commercial airports with inadequate runway safety areas, while EASA enforces comparable overrun protection standards under its aerodrome certification framework. The EU Green Deal and national carbon accounting rules are pressuring manufacturers to reduce embodied emissions in cementitious arrestor materials. Stakeholders must monitor evolving certification reciprocity between FAA and EASA standards, as divergence would fragment product qualification pathways and complicate multinational airport operator procurement.
Market Dynamics
The engineered material arresting system market is being reshaped by regulatory retrofit mandates at aging commercial airports, where FAA and EASA safety area requirements are forcing systematic replacement of legacy gravel-based overrun protection with certified crushable concrete and composite arrestor beds.
Growth Catalysts
- FAA EMAS Program:The FAA's mandated installation schedule at commercial airports with inadequate runway safety areas creates predictable procurement cycles for certified arrestor bed systems.
- Crushable Cellular Cement:Advances in lightweight aggregate formulations enable arrestor beds to absorb higher kinetic energy loads from narrow-body and regional aircraft overruns.
- Metropolitan Airport Concentration:Dense air traffic corridors in the United States and Western Europe concentrate retrofit demand at facilities with constrained expansion footprints.
Market Restraints
- Cementitious Material Emissions:The EU Green Deal and national carbon accounting frameworks are pressuring manufacturers to reduce embodied emissions in concrete arrestor production.
- Specialized Installation Base:Deployment requires certified contractors with airside construction credentials, limiting vendor scalability and extending project timelines.
- Runway Occupancy Windows:Installation and maintenance access depends on limited nighttime closure periods, compressing revenue realization for system integrators.
Strategic Opportunities
- Hybrid System Convergence:Integration of passive crushable beds with active electromechanical arresting mechanisms addresses multi-threat capability at military and joint-use facilities.
- Performance-Based Leasing:Long-term infrastructure leasing arrangements allow vendors to capture recurring revenue through availability-guaranteed arrestor system contracts.
- Carbon-Neutral Material Certification:Low-emission arrestor substrates aligned with EU Green Deal criteria unlock preferential procurement at European aerodromes.
Industry Challenges
- FAA-EASA Certification Reciprocity:Diverging qualification pathways between United States and European regulators fragment product approval timelines and complicate multinational operator procurement.
- Airside Construction Labor Scarcity:Shortages of certified personnel capable of working in active movement areas constrain deployment velocity during mandated retrofit windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered Material Arresting System Market |
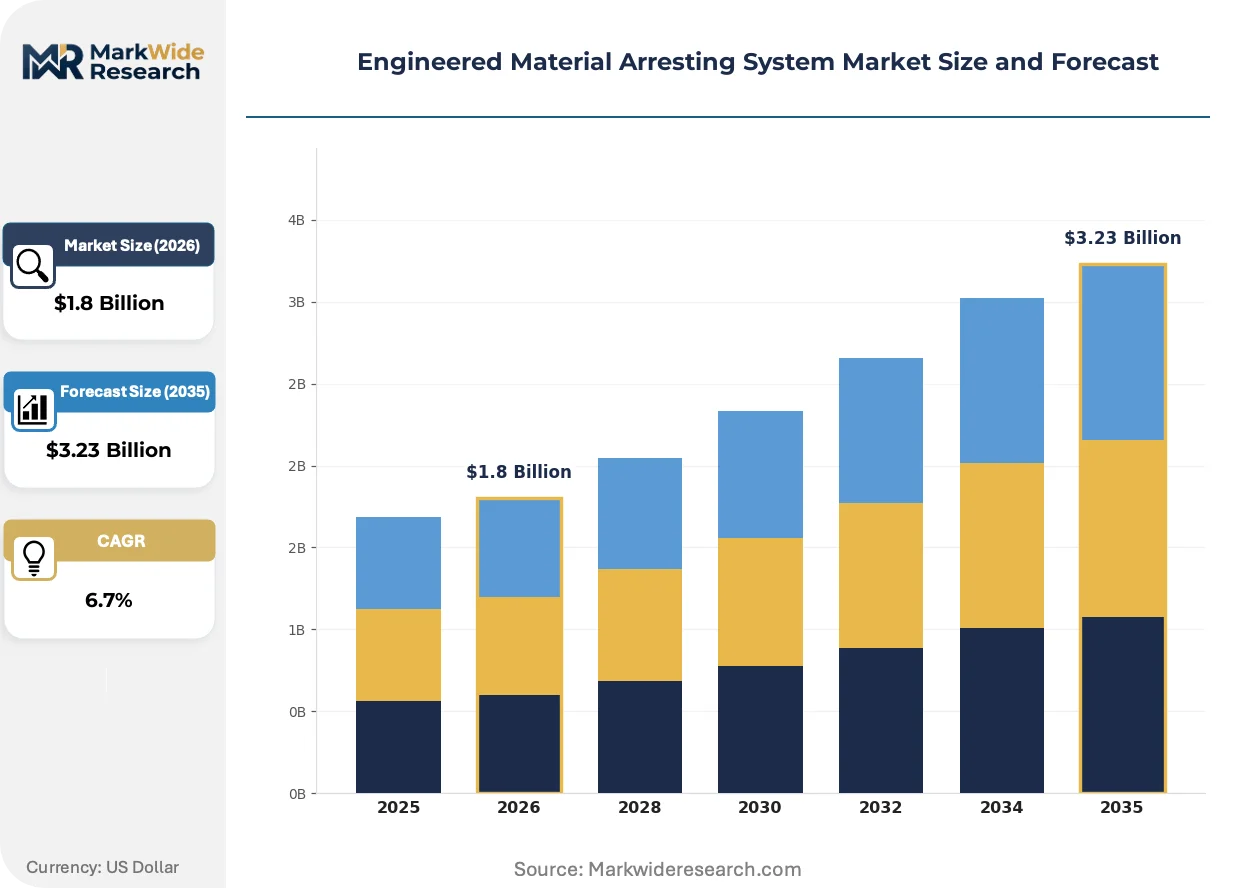
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arrestor Bed, Cable System, Net System, Hybrid System Application: Aerospace, Military, Commercial Aviation, Emergency Landings Technology: Mechanical, Electromechanical, Passive, Active End User: Airports, Military Bases, Commercial Airlines, Maintenance Providers |
| Companies Covered | A-Tech Inc., Wire Rope Industries, Runway Safe Group, Crawford, Murphy & Tilly, Inc., Scandinavian Manufacturing SCAMA AB, Curtiss-Wright Corporation, QinetiQ Group plc, Hangke Technology Development Co., Ltd., General Atomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered Material Arresting System Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are compressing traditional product lifecycles while opening new competitive vectors in arrestor system design and deployment.
Crushable cellular cement formulations with engineered porosity gradients are collapsing the performance gap between lightweight arrestor beds and traditional high-density concrete systems. Commercial airports in the United States are adopting these materials at accelerated replacement cycles to meet FAA EMAS energy absorption specifications. The shift is collapsing vendor margins on legacy gravel-based systems while rewarding manufacturers with in-house substrate engineering capabilities.
EASA aerodrome certification framework amendments are tightening overrun protection standards for commercial operators, mirroring FAA safety area mandates. The regulatory convergence is forcing European airports to accelerate arrestor bed installations beyond original capital improvement schedules. Military base operators in NATO member states are responding by procuring dual-certified systems acceptable to both regulatory regimes.
Airport authorities are unbundling arrestor system procurement from general runway construction contracts, creating dedicated vendor relationships with specialized EMAS integrators. This behavioral shift is displacing general civil engineering contractors from arrestor bed installation. The pattern is most visible at United States hub airports where FAA grant funding flows through separate safety infrastructure channels.
Engineered Material Arresting System Market Segmentation
Arresting system procurement patterns diverge sharply across operational environments, with regulatory mandates, threat profiles, and infrastructure ownership models dictating technology selection and deployment scale. Understanding these segment boundaries clarifies where vendor capabilities align with buyer requirements.
Product Type:
The use-case spectrum spans passive energy absorption for routine commercial overruns through active interception for military emergency scenarios, with hybrid architectures emerging at joint-use facilities requiring multi-threat coverage.
- Arrestor Bed:Crushable cellular cement or lightweight aggregate blocks engineered to collapse predictably under aircraft wheel loading. Commercial airports in the United States concentrate procurement here, driven by FAA EMAS retrofit mandates at aging metropolitan facilities with constrained runway safety areas.
- Hybrid System:Integrated architectures combining passive crushable substrates with active electromechanical arresting mechanisms. Military base operators and joint-use civil-military aerodromes in NATO member states are expanding procurement of these configurations to address both routine overruns and cable-capture emergencies.
- Cable System:Tensile energy absorption through hydraulic or friction-brake mechanisms, deployed primarily for military aircraft arrestment.
- Net System:Barrier interception systems for unmanned aerial vehicle containment and small-aircraft emergency capture.
The dominant share belongs to Arrestor Bed, while Hybrid System is closing the gap fastest.
Application:
Cost tier stratification separates military premium procurement from commercial volume deployment, with emergency landing infrastructure occupying a distinct capital planning channel.
- Commercial Aviation:Scheduled passenger and cargo operations at certificated aerodromes subject to FAA and EASA runway safety area mandates. Retrofit cycles concentrate at United States hub airports where grant funding flows through dedicated safety infrastructure channels.
- Military:Combat aircraft operations requiring certified arresting systems for both routine training and emergency scenarios. NATO base operators sustain premium pricing for dual-certified systems acceptable to both FAA and EASA regulatory regimes.
- Aerospace:Manufacturing and flight test facilities requiring specialized arresting configurations for prototype and developmental aircraft.
- Emergency Landings:Contingency infrastructure for non-routine diversion scenarios, typically procured through national aviation authority programs rather than airport capital budgets.
Commercial Aviation commands the largest installed base, though Military applications maintain the steepest expansion trajectory as joint-use facility requirements proliferate.
Technology:
Volume concentration favors passive architectures where deployment simplicity and maintenance predictability outweigh performance complexity.
- Passive:Systems relying on material deformation or friction without powered components, including crushable concrete beds and gravel-based legacy configurations. European aerodromes are accelerating replacement of these legacy systems under tightened EASA aerodrome certification amendments.
- Mechanical:Cable and friction-brake systems with purely mechanical energy absorption, dominant in military aircraft arrestment.
- Electromechanical:Powered control systems enabling variable resistance and real-time response adjustment, gaining adoption at facilities with diverse aircraft weight profiles.
- Active:Sensor-triggered interception mechanisms with dynamic engagement capabilities, procured primarily for high-value military asset protection.
Passive technology retains the dominant procurement volume, while Electromechanical is expanding most quickly as airports seek operational flexibility across mixed fleet operations.
End User:
Customer type determines contracting structure, with airport authorities unbundling arrestor procurement from general runway construction while military bases retain integrated system acquisition.
- Airports:Civil aerodrome operators subject to regulatory safety area mandates, increasingly establishing dedicated vendor relationships with specialized EMAS integrators rather than general civil engineering contractors.
- Military Bases:National defense installations procuring through military specification channels with distinct certification requirements and longer procurement cycles.
- Commercial Airlines:Carrier-operated maintenance and training facilities with specialized arresting needs outside certificated aerodrome infrastructure.
- Maintenance Providers:Third-party MRO facilities requiring temporary or portable arresting capabilities for hangar and test cell operations.
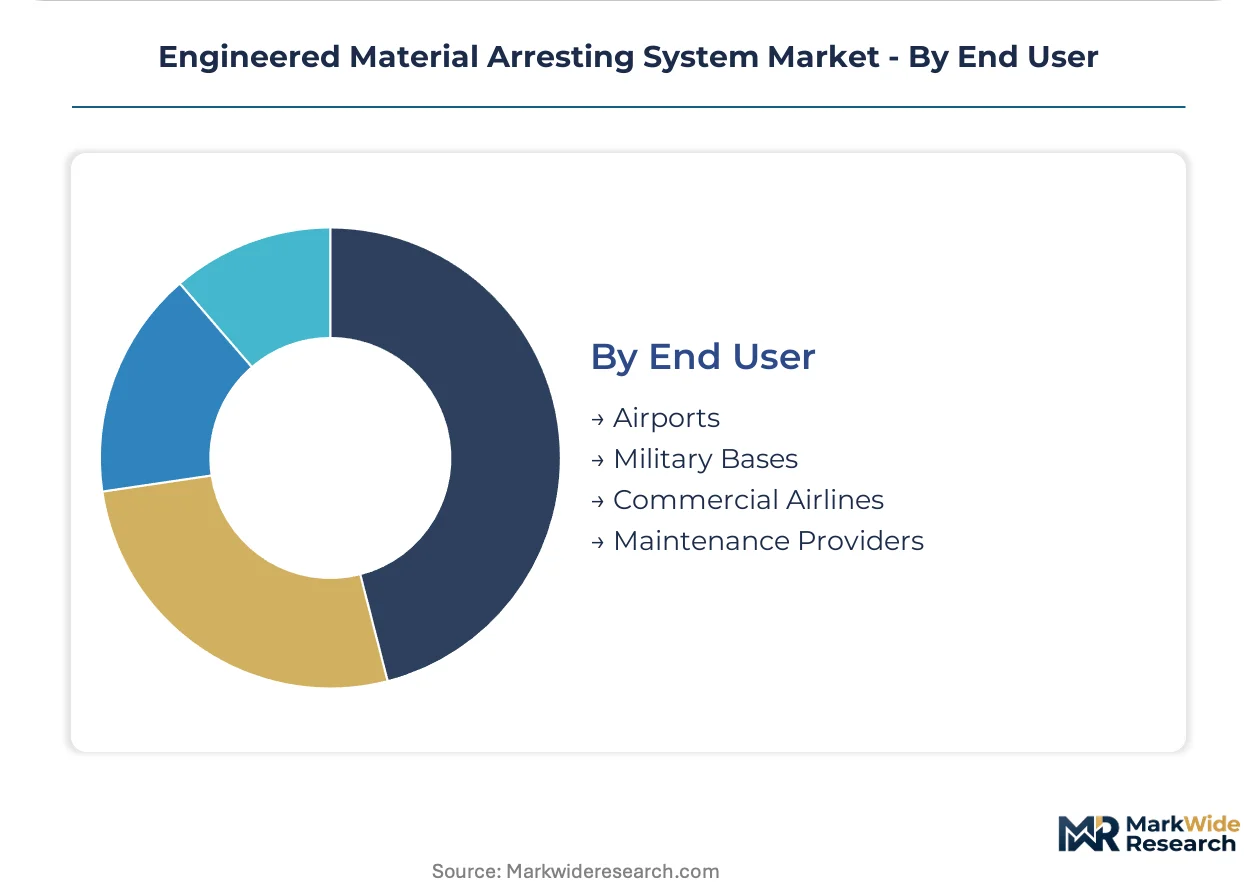
Airports represent the dominant procurement channel, while Military Bases are gaining share fastest as NATO infrastructure modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where FAA grant funding accelerates procurement cycles, while European vendors absorb carbon compliance costs that compress margins on cementitious arrestor systems.
United States
FAA EMAS retrofit mandates at aging metropolitan airports drive predictable procurement volumes through dedicated safety infrastructure grant channels. The FAA's installation schedule for commercial airports with inadequate runway safety areas creates concentrated demand windows. Chicago O'Hare, Los Angeles International, and Newark Liberty anchor the largest active replacement programs.
Germany
EASA aerodrome certification amendments are forcing accelerated replacement of legacy gravel-based systems at major commercial hubs. The EU Green Deal applies direct pressure on embodied emissions in concrete arrestor production, favoring low-carbon substrate suppliers. Frankfurt Airport and Munich Airport lead procurement activity for dual-certified systems acceptable to both FAA and EASA frameworks.
France
Military base operators in NATO member states sustain premium pricing for certified arresting systems with multi-threat capability. The country's national aviation regulator enforces tightened overrun protection standards mirroring FAA safety area mandates. Paris Charles de Gaulle and Lyon-Saint Exupéry concentrate commercial retrofit investment.
United Kingdom
Joint-use civil-military aerodromes are expanding procurement of hybrid arresting configurations addressing both routine overruns and cable-capture emergencies. The Civil Aviation Authority coordinates with military specification channels on dual-certification pathways. London Heathrow and RAF Brize Norton represent contrasting procurement profiles within the same regulatory jurisdiction.
Japan
Tokyo Narita and Osaka Kansai are accelerating arrestor bed installations under METI-coordinated infrastructure safety programs. The country's transport ministry aligns domestic certification with ICAO standards while maintaining distinct material testing protocols. Japanese manufacturers face procurement preferences for domestically sourced cellular cement formulations.
Engineered Material Arresting System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying crushable substrates and electromechanical actuation modules. The vendor base separates into three strategic archetypes: full-service EMAS integrators with airside construction credentials, specialized material substrate engineers, and hybrid system architects serving military-joint use facilities. Competitive dynamics center on backward integration into high-performance material production and long-term infrastructure leasing arrangements that convert capital sales into recurring revenue streams.
Among the named participants, Runway Safe Group exemplifies the European system integrator archetype, while Curtiss-Wright Corporation occupies a position reflecting material substrate engineering capabilities. QinetiQ Group plc represents the military-specialist tier with positioning in active arresting mechanisms. These three anchors illustrate how vendor capabilities align with divergent procurement channels across commercial aviation and defense infrastructure.
| Leading Market Players |
|---|
| A-Tech Inc. |
| Wire Rope Industries |
| Runway Safe Group |
| Crawford, Murphy & Tilly, Inc. |
| Scandinavian Manufacturing SCAMA AB |
| Curtiss-Wright Corporation |
| QinetiQ Group plc |
| Hangke Technology Development Co., Ltd. |
| General Atomics |
| Others |
Supply Flow & Price Mechanics
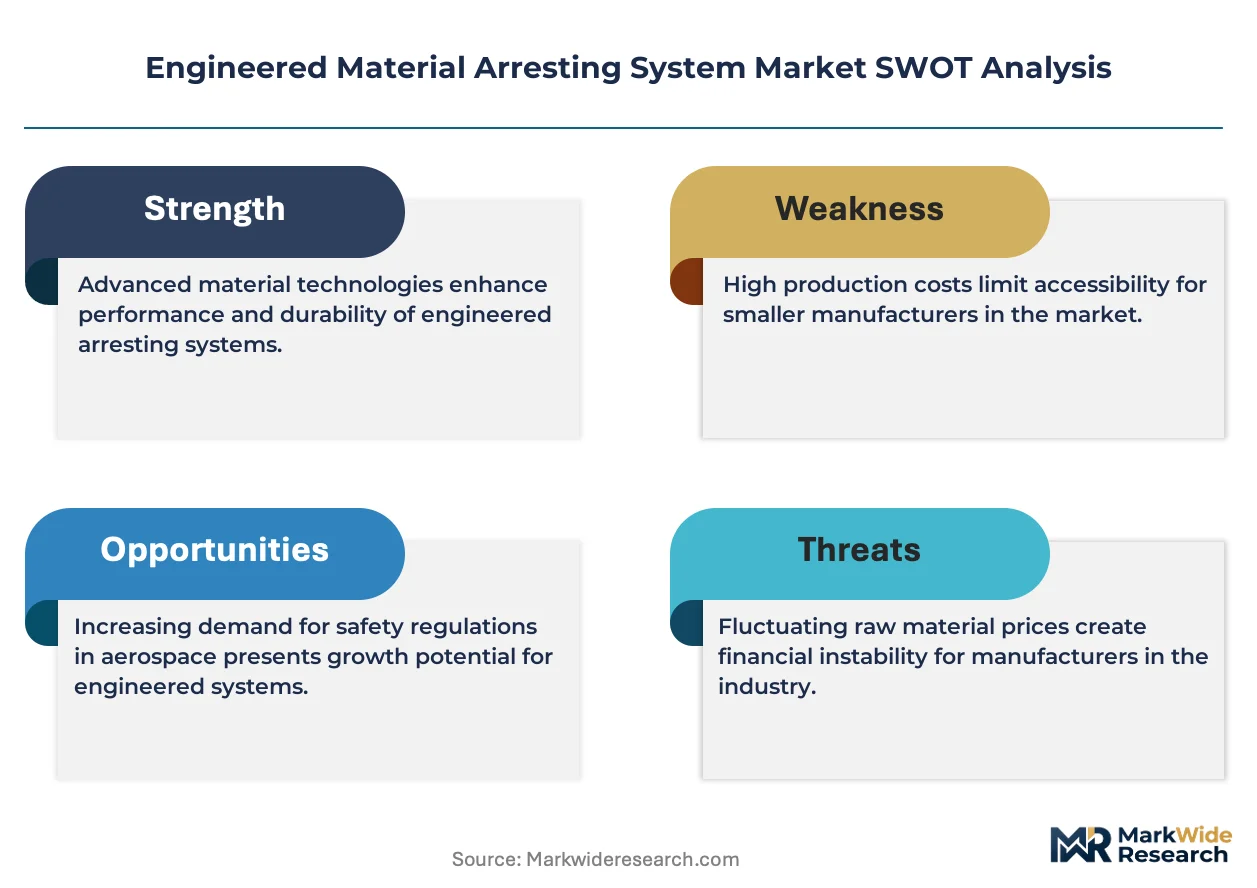
Cellular cement substrate production concentrates in the United States and Germany, anchoring margin pools with system integrators who control airside construction credentials and FAA-EASA dual certification pathways. This upstream concentration allows arrestor bed manufacturers to capture value through configured-to-order pricing while downstream airport authorities absorb installation complexity premiums.
Pricing Analysis
Configured-to-order arrestor bed installations command substantial premiums over standard gravel-replacement configurations, with FAA EMAS certification tier and airside construction bundling as the primary price differentiation drivers. Three-tier pricing structure across premium dual-certified, standard single-regulatory, and economy retrofit tiers stratifies the vendor base. Pricing pressure stems from EU Green Deal carbon accounting rules pressuring cementitious material suppliers to absorb compliance costs. Commercial aviation retrofit programs show highest price sensitivity due to grant-funded procurement cycles, while military base operators sustain lowest sensitivity given mission-critical specifications and longer procurement horizons.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk profiles for electromechanical actuation components used in hybrid arresting systems. Geographic supply concentration centers on the United States for crushable cellular cement formulations, Germany for precision-engineered composite substrates, and China for cable and friction-brake mechanisms. Raw material dependencies rest on lightweight aggregate supplies, high-performance polymer resins, and certified steel cabling. Single-source vulnerability characterizes FAA-approved substrate engineering capabilities, constraining vendor scalability. Distribution runs through specialized EMAS integrators with direct airside construction credentials rather than general civil engineering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat defense, where FAA and EASA certification entrenchment creates switching costs that lock airport authorities into established vendor relationships through multi-decade infrastructure lifecycles.
For Market Incumbents: Insulate certification assets by deepening backward integration into low-carbon cellular cement production ahead of EU Green Deal enforcement timelines. Prioritize dual FAA-EASA qualification pathways to capture NATO military base procurement migrating toward unified standards. Defend against emerging composite substrate specialists by locking long-term availability-guaranteed contracts with metropolitan hub airports.
For New Entrants and Emerging Players: Establish a beachhead in portable arresting configurations for third-party MRO facilities, where regulatory barriers are lower and procurement cycles are compressed. Target carbon-neutral material certification as a differentiation vector at European aerodromes facing EU Green Deal procurement preferences. Deploy performance-based leasing models to bypass incumbent lock-in at cash-constrained regional airports outside major metropolitan corridors.
For Investors and Strategic Acquirers: Capital is best deployed toward system integrators with captive substrate engineering capabilities and established airside construction credentials, as these assets compound regulatory moats across multi-decade infrastructure replacement cycles. Long-term viability hinges on positioning for hybrid system convergence at joint-use civil-military facilities. Monitor FAA-EASA certification reciprocity negotiations as the critical inflection signal for multinational vendor consolidation opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Substrates | EU Green Deal compliance secures preferential procurement at Frankfurt and Munich airports. |
| Dual FAA-EASA Certification Investment | Unified qualification pathways unlock NATO military base procurement expansion. |
| Performance-Based Leasing Arrangements | Recurring revenue models convert capital sales into availability-guaranteed contracts. |
| Hybrid System Architecture Development | Passive-active integration addresses multi-threat coverage at RAF Brize Norton-style joint-use facilities. |
| Airside Construction Credential Expansion | Certified contractor networks compress deployment timelines during mandated retrofit windows. |
Methodological Framework
A spread of perspectives from airport infrastructure directors, FAA certification engineers, EMAS system integrators, and military base procurement officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FAA EMAS program documentation, EASA aerodrome certification amendments, EU Green Deal regulatory filings, and airport capital improvement budget disclosures. Bottom-up segmentation modeling triangulated against top-down market sizing derived from procurement database tracking across the United States, Germany, France, the United Kingdom, and Japan.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with arrestor bed, hybrid system, cable system, and net system product categories modeled alongside commercial aviation, military, aerospace, and emergency landing applications. Technology segmentation spanned passive, mechanical, electromechanical, and active architectures, while end-user analysis distinguished airports, military bases, commercial airlines, and maintenance providers. CAGRs were derived from regression analysis of historical procurement cycles against regulatory mandate schedules, incorporating cementitious material cost trajectories and airside construction labor availability as industry-specific forecast inputs.
Stress conditions across EU carbon border adjustment implementation, FAA-EASA certification divergence scenarios, and airside construction labor scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory retrofit timelines, material science advancement curves, and infrastructure grant funding continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market