
 UK Space Electronics Market | 2026-2036
UK Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Space Electronics Market Insights
Market Context
A chronic shortfall of radiation-effects engineers and space-qualified PCB designers is unwinding across British aerospace supply chains. BAE Systems leverages its sovereign secure manufacturing footprint to sustain Ministry of Defence satellite programs. Cobham anchors high-reliability interconnect and microelectronics production for European launchers. Thales Alenia Space UK competes for Earth observation payload contracts through its Belfast and Bristol facilities.
Technical Definition and Segment Structure
UK space electronics encompasses radiation-hardened and high-reliability semiconductor devices, assemblies, and subsystems engineered to survive ionizing radiation, thermal cycling, and vacuum conditions across orbital and deep-space missions, typically qualified to ECSS-Q-ST-60-02C or MIL-STD-883 test regimes. These components manage power distribution, data processing, sensor interfacing, and RF communication in satellites and probes where terrestrial-grade devices would fail within hours of launch. Radiation-hardened microprocessors and power amplifiers occupy the dominant revenue positions owing to their irreplaceability in command-and-data handling chains. Mixed-signal technology and Earth observation applications are expanding fastest as synthetic-aperture radar and multispectral imaging constellations multiply.
Regulatory Framework and Outlook
The UK Space Agency governs payload licensing under the Space Industry Act 2018, while the Department for Science, Innovation and Technology administers export control classifications for space-grade technologies under UK Strategic Export Control Lists. ESA coordination requirements and emerging UKCA marking obligations for space components are tightening qualification documentation burdens on suppliers. Stakeholders must monitor whether post-Brexit alignment with EU Space Programme procurement rules preserves British contractor access to Copernicus and Galileo downstream markets.
Market Dynamics
Radiation-hardened component qualification bottlenecks are compressing procurement timelines for British satellite constellation operators, forcing domestic foundries to accelerate ECSS-Q-ST-60-02C certification pathways or lose contracts to European qualified suppliers.
Growth Catalysts
- Earth observation payload demand:Synthetic-aperture radar and multispectral imaging constellations are multiplying across southern England, concentrating procurement around the Harwell Space Cluster and Surrey manufacturing corridor.
- National Space Strategy acceleration:The UK Space Agency's domestic qualification pathways are reducing reliance on ESA-coordinated foreign foundries for radiation-hardened microprocessors.
- Ministry of Defence satellite programs:Sovereign secure manufacturing requirements are sustaining classified procurement volumes through BAE Systems and specialized British defense contractors.
Market Restraints
- Foundry concentration risk:Radiation-hardened wafer fabrication concentrates at single-source European facilities, exposing British fabless designers to allocation constraints during aerospace demand surges.
- Qualification cost structure:MIL-STD-883 test regime execution requires six-figure expenditure per device variant, excluding smaller satellite startups from space-grade component access.
- Engineering talent scarcity:British universities produce fewer than fifty radiation-effects engineering graduates annually, constraining domestic qualification team expansion.
Strategic Opportunities
- Scottish spaceport integration:SaxaVord and Sutherland launch facilities are creating captive demand for locally qualified electronics in vertical-launch small satellites.
- UKCA marking transition:Post-Brexit component marking obligations are incentivizing British suppliers to establish independent qualification laboratories.
- RF power amplifier convergence:Gallium nitride-on-silicon carbide technology is penetrating Earth observation downlink chains, opening foundry partnerships with compound semiconductor specialists.
Industry Challenges
- Radiation-effects simulation expertise:Heavy-ion accelerator access at Harwell and Daresbury is oversubscribed, delaying single-event upset characterization for new device architectures.
- ECSS-UKCA dual compliance:Parallel documentation requirements for European Space Agency coordination and domestic marking are stretching quality engineering teams across incompatible templates.
- Space-qualified PCB design capacity:Thermal cycling and outgassing analysis specialists are concentrated at Cobham and Thales Alenia Space UK, limiting subcontractor pool depth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Space Electronics Market |
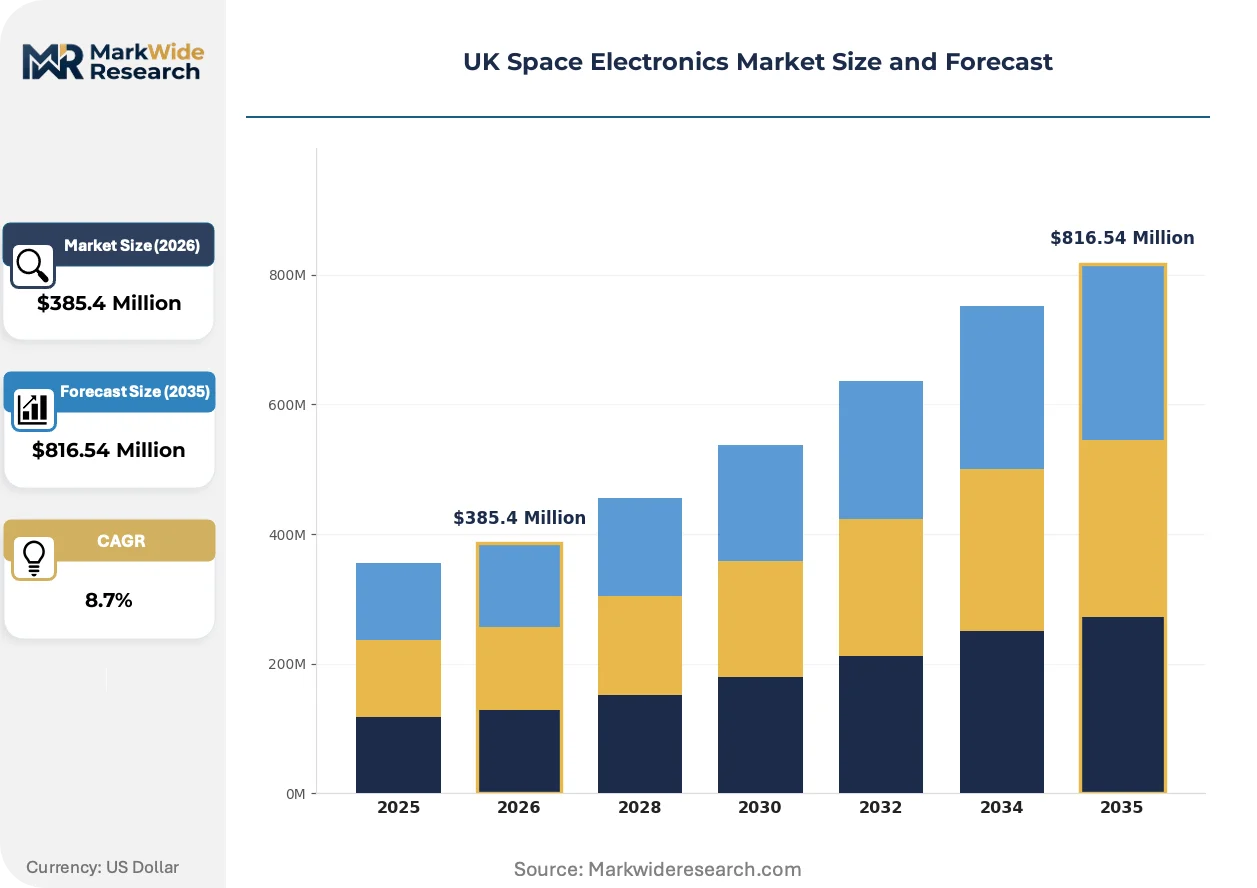
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microprocessors, Power Amplifiers, Sensors, Transmitters, Memory Devices, Voltage Regulators Technology: Radiation-Hardened, Cryogenic, Mixed Signal, Digital Signal Processing, Low Noise, High Frequency Application: Satellite Communication, Space Exploration Probes, Earth Observation, Navigation Systems, Space Research Instruments, Weather Monitoring End User Industry: Satellite Operators, Aerospace Contractors, Defense Agencies, Research Institutions, Space Launch Service Providers, Telco Companies |
| Companies Covered | BAE Systems, Parker Meggitt, Cobham, Teledyne e2v, Oxford Instruments, Micross, Thales Alenia Space UK, Reliance Precision, APC Technology Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Space Electronics Market Trends and Innovations
Commercial off-the-shelf component radiation tolerance screening is disrupting traditional hardened-device procurement, enabling constellation operators to compress satellite unit costs while accepting higher orbital replacement rates.
Commercial-grade field-programmable gate arrays with radiation-tolerant by design architectures are supplanting fully hardened application-specific integrated circuits in low-Earth orbit command-and-data handling chains. Surrey Satellite Technology and emerging constellation operators are adopting these screened COTS devices for three-year mission lifetimes. The substitution is collapsing procurement lead times from eighteen months to six weeks and forcing traditional hardened foundries to diversify into screening services.
The UK Space Agency's payload licensing enforcement under the Space Industry Act 2018 is tightening end-to-end traceability requirements for space-grade electronics. Suppliers must now document component provenance from wafer fabrication through satellite integration, extending quality management system audits. Small satellite manufacturers in Bristol and Belfast are consolidating supplier bases to reduce compliance documentation burden.
Constellation operators are consolidating procurement through long-term framework agreements with qualified component distributors, displacing spot-market purchasing for radiation-hardened devices. Harwell-based satellite ventures are locking three-year supply commitments with specialist distributors holding ECSS-certified inventory. The shift is visible most acutely in synthetic-aperture radar payload programs where component obsolescence risk demands supply continuity guarantees.
UK Space Electronics Market Segmentation
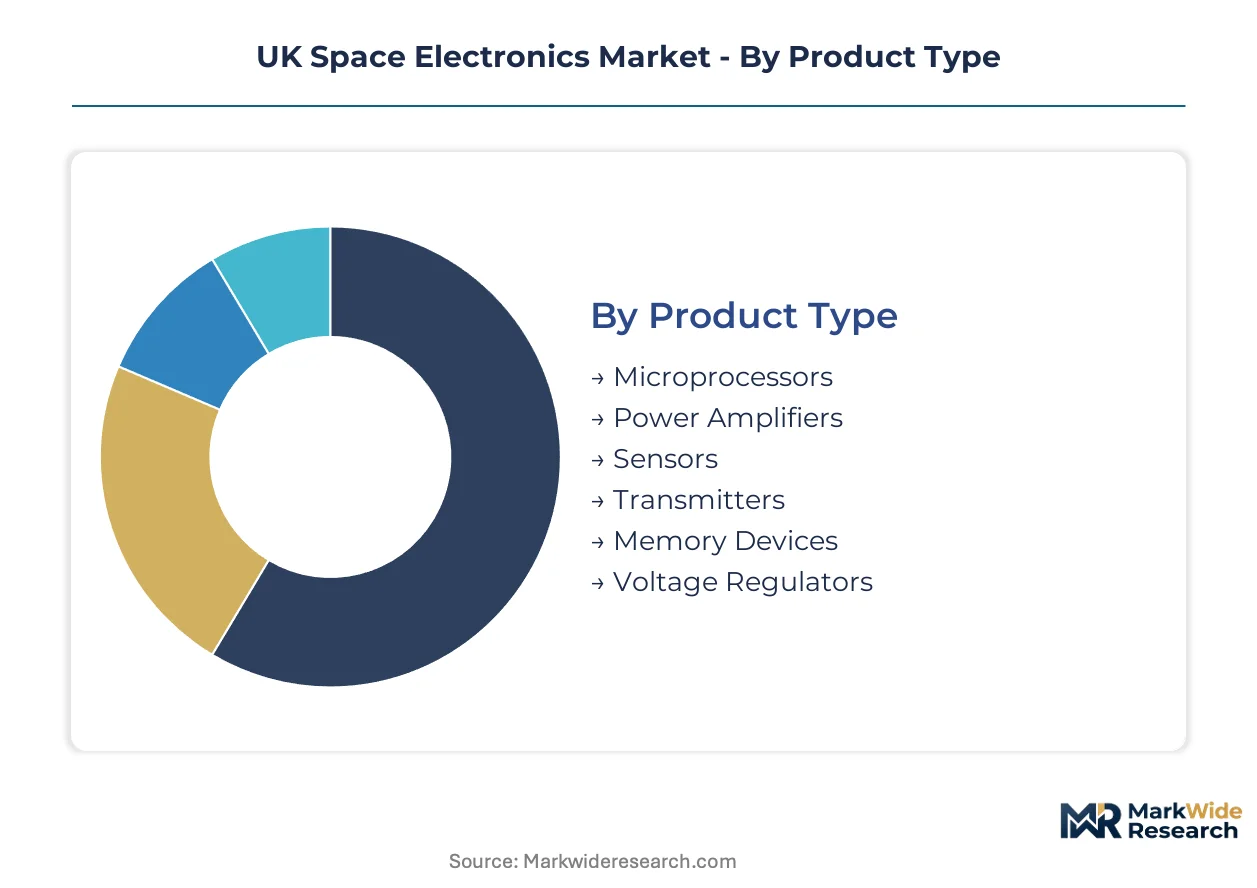
Segmentation reveals how procurement power concentrates across radiation-hardened component categories in the United Kingdom. British satellite manufacturers prioritize qualification status over unit cost when selecting suppliers for constellation programs.
Product Type:
Margin pools concentrate in devices commanding irreplaceable positions within satellite command-and-data handling architectures.
- Microprocessors:These radiation-hardened central processing units execute flight software under total ionizing dose conditions exceeding 100 krad(Si). Surrey Satellite Technology and Harwell-based ventures are expanding procurement of ARM-based hardened cores for synthetic-aperture radar payload control.
- Power Amplifiers:Gallium nitride and gallium arsenide devices generate RF output for downlink transmission across Ku- and Ka-bands. Earth observation operators in southern England are specifying these for high-data-rate imagery return from low-Earth orbit constellations.
- Sensors:Radiation-tolerant photodetectors and inertial measurement units support attitude determination.
- Transmitters:Solid-state and traveling-wave tube amplifiers handle telemetry and telecommand links.
- Memory Devices:Magnetoresistive and ferroelectric RAM retain data through single-event upset events.
- Voltage Regulators:Point-of-load converters distribute conditioned power across satellite bus subsystems.
The dominant share belongs to Microprocessors, while Power Amplifiers is closing the gap fastest.
Technology:
Qualification burden varies sharply across process nodes and architectural approaches.
- Radiation-Hardened:Foundry processes employ epitaxial layers, enclosed geometry layouts, and error-correction circuitry to achieve MIL-STD-883 compliance. BAE Systems maintains captive qualification teams at its Greater Manchester facilities for Ministry of Defence satellite programs.
- Mixed Signal:Analog-to-digital converters and precision references combine sensitive front-ends with digital calibration loops. Bristol-based payload houses are specifying these for multispectral imaging focal plane interfaces where noise floors determine commercial viability.
- Cryogenic:Components qualified for sub-100K operation support infrared astronomy missions.
- Digital Signal Processing:Radiation-tolerant FPGAs implement real-time filter banks and compression algorithms.
- Low Noise:Front-end amplifiers preserve signal integrity in deep-space telecommunications.
- High Frequency:Millimeter-wave devices enable inter-satellite laser communication terminals.
Radiation-Hardened commands the largest procurement volumes, though Mixed Signal is expanding most quickly as commercial imaging constellations proliferate.
Application:
Program funding stability determines component procurement visibility across mission categories.
- Earth Observation:Synthetic-aperture radar and electro-optical payloads demand high-reliability data converters, solid-state recorders, and X-band transmitters. The UK Space Agency's National Space Strategy is channeling investment toward Harwell Cluster companies building radar constellations for maritime surveillance.
- Satellite Communication:Geostationary and medium-Earth orbit relay platforms require hardened traveling-wave tube amplifiers and redundancy-managed switch matrices. OneWeb's constellation manufacturing through Airbus Defence and Space UK sustains procurement volumes for RF power components.
- Space Exploration Probes:Deep-space missions specify extreme-temperature electronics and fault-tolerant computing.
- Navigation Systems:Atomic clock interfaces and precise orbit determination electronics support positioning augmentation.
- Space Research Instruments:Particle detectors and plasma analyzers require specialized front-end electronics.
- Weather Monitoring:Sounding instruments and imagers for meteorological agencies demand calibrated radiometric performance.
Earth Observation holds the dominant position, while Satellite Communication is gaining share fastest through constellation replenishment cycles.
End User Industry:
Contracting mechanisms and security classification requirements segment procurement behavior.
- Satellite Operators:Commercial and government fleet managers specify components through long-term framework agreements with qualified distributors. Harwell-based ventures are consolidating supplier bases to reduce Space Industry Act 2018 compliance documentation burden.
- Aerospace Contractors:Prime integrators including Airbus Defence and Space UK and Thales Alenia Space UK maintain approved vendor lists for radiation-hardened procurement. These primes are pushing qualification cost absorption onto Tier 2 subsystem suppliers.
- Defense Agencies:Ministry of Defence satellite programs mandate UK sovereign secure manufacturing footprints through BAE Systems and specialized British contractors.
- Research Institutions:University-led CubeSat missions access screened COTS components through simplified procurement.
- Space Launch Service Providers:Scottish spaceport operators at SaxaVord and Sutherland are creating captive demand for locally qualified avionics.
- Telco Companies:Satellite-to-cellular service providers are emerging as specification authorities for user terminal electronics.
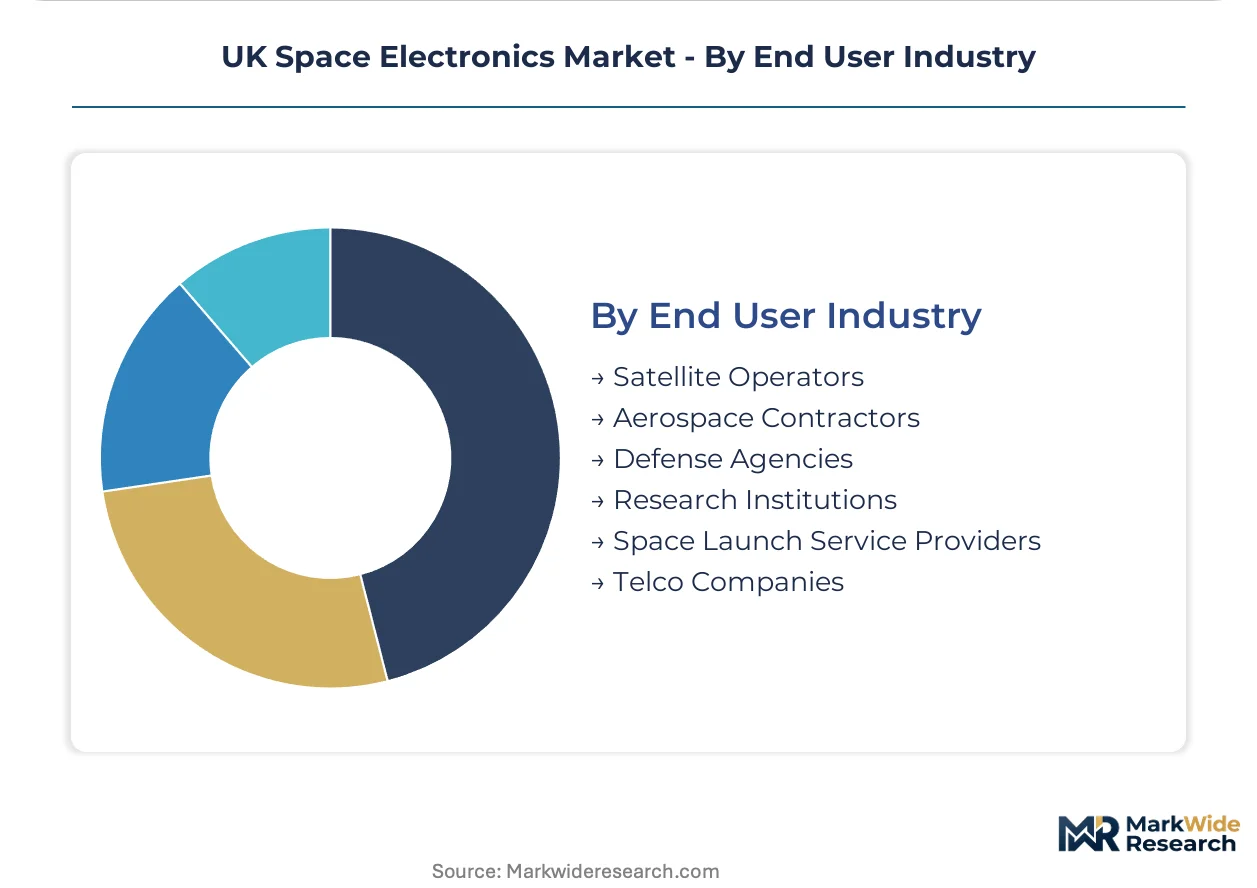
Satellite Operators represent the largest addressable base, though Defense Agencies are expanding procurement most rapidly through classified constellation programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK Space Agency anchors procurement governance across British space electronics demand. National qualification pathways and constellation manufacturing clusters concentrate activity in southern England and Scotland. Regional specialization follows launch facility geography and defense contractor footprints.
London and Southeast England
Synthetic-aperture radar constellation operators drive component procurement around the Harwell Space Cluster. The UK Space Agency's National Space Strategy channels investment toward Earth observation payload manufacturers. Oxfordshire and Surrey facilities concentrate radiation-hardened microprocessor qualification for maritime surveillance missions.
Southwest England
Bristol payload houses specify mixed-signal converters for multispectral imaging focal planes. The Space Industry Act 2018 licensing enforcement tightens traceability requirements for local satellite manufacturers. Gloucestershire and Somerset suppliers consolidate approved vendor lists to reduce compliance documentation burden.
Scotland
SaxaVord and Sutherland spaceports generate captive demand for vertical-launch small satellite avionics. Scottish Enterprise funding supports local qualification laboratory development for UKCA marking compliance. Highlands and Islands electronics subcontractors position for launch vehicle integration contracts.
Northern Ireland
Belfast facilities compete for Earth observation payload contracts through precision manufacturing capabilities. The Department for Science, Innovation and Technology administers export control classifications affecting local component shipments. Antrim and Down suppliers leverage aerospace heritage for satellite subsystem assembly.
Northwest England
Greater Manchester hosts sovereign secure manufacturing for Ministry of Defence satellite programs. BAE Systems maintains captive radiation-effects engineering teams for classified procurement. Lancashire and Cheshire supply chains anchor defense-grade electronics production outside commercial constellation flows.
UK Space Electronics Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in British space electronics procurement. Prime contractors and defense conglomerates occupy the upper tier through captive qualification capabilities and long-term government contracts. Mid-tier specialists concentrate in high-reliability interconnect, radiation-tolerant imaging sensors, and precision mechanical subsystems. Competitive positioning hinges on ECSS certification maintenance and UKCA marking transition readiness rather than price competition.
Among UK-based integrated defense-electronics conglomerates, BAE Systems and Cobham anchor sovereign secure manufacturing positions. Teledyne e2v represents the specialist tier through its focus on imaging and sensor technologies. Thales Alenia Space UK occupies a position bridging European prime contractor networks with British payload integration capabilities. These three exemplify how geographic footprint alignment with defense procurement and commercial constellation demand determines competitive viability.
| Leading Market Players |
|---|
| BAE Systems |
| Parker Meggitt |
| Cobham |
| Teledyne e2v |
| Oxford Instruments |
| Micross |
| Thales Alenia Space UK |
| Reliance Precision |
| APC Technology Group |
| Others |
Pricing and Supply Chain Analysis
Wafer-scale qualification economies at European radiation-hardened foundries concentrate pricing power among ECSS-certified suppliers, compressing margin buffers for British fabless designers while elevating price floors for constellation operators seeking domestic sourcing alternatives.
Pricing Analysis
Geographic price spreads between Harwell-based qualified distributors and continental European suppliers narrow as UKCA marking compliance costs equalize procurement premiums. Three-tier pricing structure across mission-critical, commercial-grade screened, and research-grade components differentiates on radiation-tolerance certification level and traceability documentation depth. Pricing pressure stems from constellation operators consolidating procurement through multi-year framework agreements. Research institutions and CubeSat ventures exhibit highest price sensitivity, while Ministry of Defence programs prioritize sovereign secure manufacturing over unit cost.
Supply Chain Analysis
Eighteen-month lead times for radiation-hardened microprocessors strain satellite constellation delivery schedules, forcing British operators to buffer inventory or accept screened COTS substitutes. Wafer fabrication concentrates in France, Belgium, and Germany, while compound semiconductor substrates for RF power amplifiers draw from Japan and the United States. Gallium nitride epitaxy, ceramic packaging substrates, and heavy-ion accelerator access represent critical input dependencies. Single-source vulnerability at European foundries exposing British designers to allocation constraints during aerospace demand surges constitutes the dominant structural risk. Distribution runs through specialist distributors holding ECSS-certified inventory rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK space electronics market rewards organizations that control scarce radiation-effects engineering capacity and captive qualification infrastructure, with fewer than fifty annual British graduates constraining domestic team expansion.
For Market Incumbents: Fortify qualification laboratory capabilities at Greater Manchester and Harwell facilities to absorb ECSS-UKCA dual compliance burdens before smaller competitors exhaust quality engineering bandwidth. Deepen backward integration into heavy-ion accelerator partnerships at Daresbury to secure single-event upset characterization slots. Lock three-year supply commitments with Scottish spaceport operators at SaxaVord and Sutherland to anchor vertical-launch avionics demand. For New Entrants and Emerging Players: Differentiate on rapid UKCA marking pathway completion for mixed-signal converters serving Bristol payload houses, where ECSS certification gaps among incumbent suppliers create procurement bottlenecks. Target synthetic-aperture radar focal plane interfaces as the most penetrable segment, given expanding maritime surveillance constellation procurement. Pursue qualification-as-a-service partnerships with Harwell Cluster ventures to bypass six-figure MIL-STD-883 test regime capital requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialist distributors holding ECSS-certified inventory and long-term framework agreements with constellation operators. Long-term viability across the projection horizon hinges on UK Space Agency payload licensing enforcement tightening traceability requirements that favor incumbent quality management systems. Acquisition target archetype: mid-tier imaging sensor specialists with captive radiation-tolerance screening capabilities. Watch for inflection signals in Scottish Enterprise funding disbursements for local qualification laboratory development.| Strategic Initiative | Industry Significance |
|---|---|
| Qualification Laboratory Expansion | ECSS-Q-ST-60-02C certification capacity at Harwell reduces reliance on European foundry queues. |
| UKCA Marking Pathway Investment | Independent domestic marking compliance opens procurement access to post-Brexit satellite programs. |
| Heavy-Ion Accelerator Partnership | Daresbury facility access secures single-event upset characterization for new device architectures. |
| Scottish Spaceport Integration | SaxaVord and Sutherland launch facilities generate captive demand for locally qualified avionics. |
| Screened COTS Service Diversification | Commercial-grade FPGA screening collapses procurement lead times for low-Earth orbit constellations. |
Research Methodology
The analysis maps radiation-hardened microprocessors, mixed-signal converters, RF power amplifiers, and memory devices, each validated through radiation-effects engineers, satellite procurement managers, qualification laboratory directors, and UK Space Agency licensing officers. Primary interview insights triangulate against UK Space Agency National Space Strategy documentation, ESA coordination requirements, Department for Science, Innovation and Technology export control classifications, and ECSS standard registries. Bottom-up component demand modeling reconciles with top-down constellation program funding allocations.
Consistency checks against ESA procurement databases and UK Space Agency investment disclosures validate volume and value outputs across the analysis window. Segmentation dimensions include product type, technology qualification tier, application mission category, and end-user contracting mechanism. CAGRs derive from satellite constellation deployment schedules and replacement cycle assumptions. Forecast inputs incorporate radiation-hardened foundry capacity utilization rates and British university graduate pipeline constraints.
Forecasts assume regulatory continuity in UK Space Agency payload licensing under the Space Industry Act 2018 and ESA coordination requirements; material policy shifts in post-Brexit EU Space Programme procurement alignment would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space Oscillator Market
Space
Space-Based Solar Power Market
Space
Carrier Rocket Market
Space
China Space Electronics Market
Space
US Space Launch Services Market
Space
Private Space Travel Market
Space
Space Ground System Market
Space
Space As a Service Market
Space
South Korea Space Electronics Market
Space
Space Tourism Market
Space
Space-Based C4ISR Market
Space
Space Management Solutions Market
Space
Space on Board Computing Platform Market
Space
Space Transportation Market
Space
India Space Electronics Market
Space
LAMEA Space As a Service Market