
 Aircraft Smoke Detection and Fire Extinguishing System Market | 2026-2036
Aircraft Smoke Detection and Fire Extinguishing System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Smoke Detection and Fire Extinguishing System Market Outlook
Halon 1301 is hardening as the reference point against which all next-generation suppressants must prove economic viability. Meggitt plc leverages its integrated sensor-to-extinguisher architecture to capture value across the fire suppression chain. Diehl Stiftung & Co. KG anchors its position through deep relationships with Airbus and European military platforms. UTC Aerospace Systems competes on the strength of its FAA-certified optical detection platforms installed across Boeing's narrow-body programs.
Aircraft smoke detection and fire extinguishing systems comprise networked sensor arrays, suppression agent delivery mechanisms, and centralized control interfaces designed to identify combustion events and deploy extinguishing agents within seconds. Optical detection technology dominates commercial installations due to its immunity to false triggers from dust and humidity, while photoelectric sensors gain share in cargo applications where smoldering fires present distinct spectral signatures. Military aircraft applications command premium pricing for hardened, EMI-resistant systems, whereas passenger aircraft volumes scale with OEM delivery cycles. Maintenance Repair Organizations represent a growing revenue pool as regulatory authorities mandate shorter inspection intervals for aging detector fleets.
FAA airworthiness directives and EASA certification standards shape product development timelines and retrofit obligations across the installed base. The EPA's Significant New Alternatives Policy program accelerates Halon-replacement chemistry validation, while ISO 2685 fire-resistance testing governs material selection for engine-nacelle applications. Stakeholders must monitor the divergence between European F-Gas Regulation thresholds and FAA alternative-agent approval pathways, as this regulatory friction will determine which suppression chemistries achieve cross-certification economics.
Market Dynamics
The phase-out of Halon 1301 under EPA Significant New Alternatives Policy mandates is forcing airframers and system integrators to validate fluoroketone and aerosol alternatives across FAA and EASA certification pathways simultaneously.
Growth Catalysts
- Fleet Modernization Mandates:FAA airworthiness directives require retrofit of aging detector arrays in Boeing 737NG and 757 fleets, creating sustained aftermarket demand through 2035.
- REACH Chemical Restrictions:European ECHA substance evaluations accelerate substitution of legacy suppressants, opening procurement windows for clean-agent alternatives in Airbus A320 family programs.
- Optical Detection Maturation:Dual-wavelength infrared sensors eliminate false alarms from condensation and dust, enabling cargo operators to reduce inspection downtime.
Market Restraints
- Certification Timeline Compression:FAA Part 25 Appendix F flammability testing and EASA CS-25 fire protection standards impose parallel validation costs that extend new product introduction cycles.
- Agent Supply Concentration:Three chemical manufacturers control Novec 1230 and FK-5-1-12 production, exposing system integrators to input price volatility.
- Technical Performance Gap:Halon replacements require 40-60% larger storage cylinders, imposing weight penalties that narrow-body OEMs resist.
Strategic Opportunities
- Urban Air Mobility Integration:eVTOL platforms lack fire suppression heritage, creating first-mover advantage for lightweight aerosol systems certified to RTCA DO-311A.
- India Defense Procurement:Hindustan Aeronautics Limited fighter and transport programs specify indigenous fire detection under Make in India defense offsets.
- Predictive Maintenance Convergence:IoT-enabled detector networks feeding fleet-wide analytics platforms unlock recurring software revenue from airline maintenance contracts.
Industry Challenges
- Cross-Certification Expertise Scarcity:Engineers fluent in both FAA Part 25 and EASA CS-25 fire protection interpretations command premium compensation, constraining program staffing.
- Legacy System Integration Friction:Retrofit of addressable detector loops into 1980s-vintage aircraft wiring harnesses requires custom interface modules that prolong installation downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Smoke Detection and Fire Extinguishing System Market |
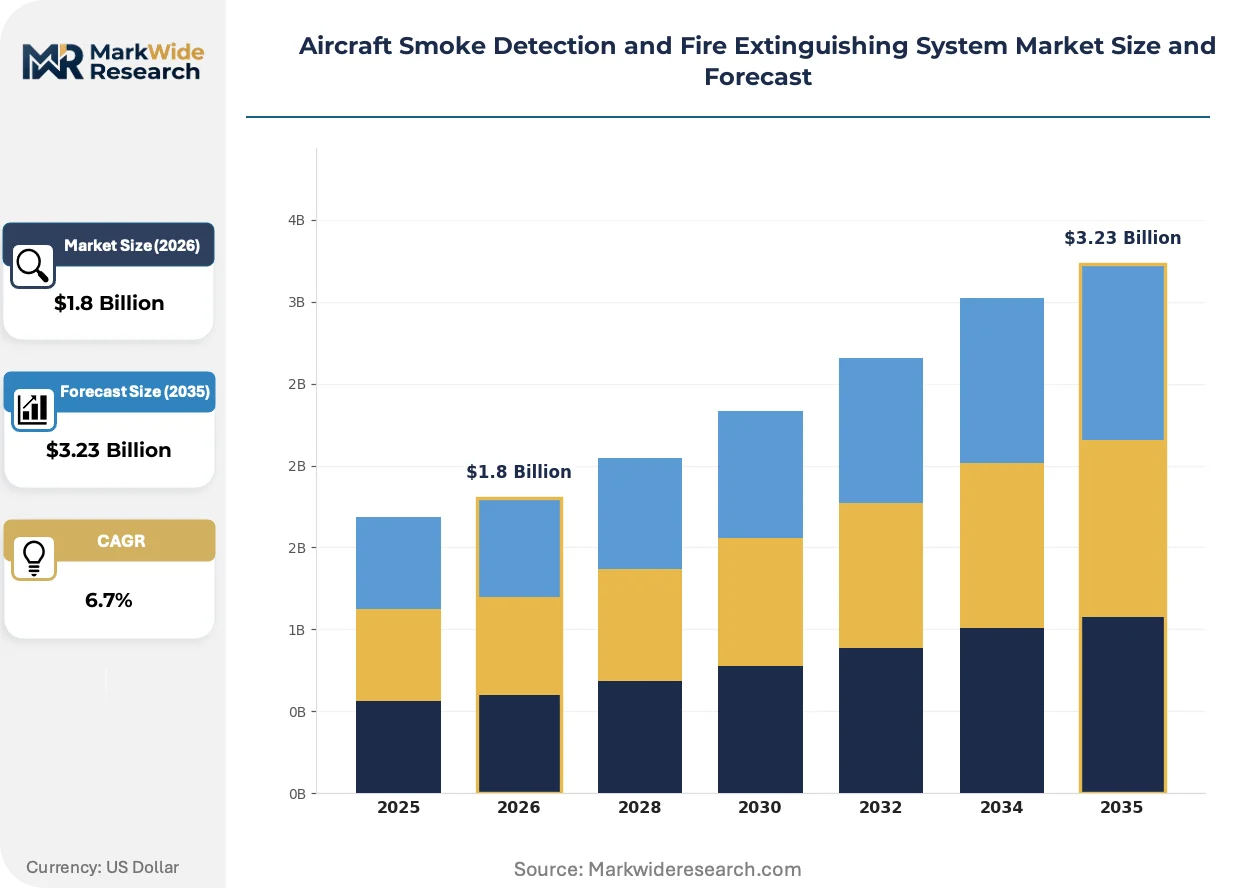
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical, Ionization, Laser, Photoelectric Application: Passenger Aircraft, Cargo Aircraft, Military Aircraft, Business Jets End User: Airlines, Aircraft Manufacturers, Maintenance Repair Organizations, Regulatory Authorities Component: Smoke Detectors, Fire Extinguishers, Control Panels, Sensors |
| Companies Covered | Meggitt plc, Siemens AG, Advanced Aircraft Extinguishers, Ltd, Diehl Stiftung & Co. KG, UTC Aerospace Systems, Gielle Industries, H3R Aviation Inc., Ventura Aerospace Inc., Fire Fighting Enterprises Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Smoke Detection and Fire Extinguishing System Market Strategic Shifts
Detection sensitivity and suppression agent chemistry are converging to redefine system architecture, with weight reduction and false-alarm elimination emerging as the primary design imperatives for next-generation platforms.
Photoelectric smoke detection paired with carbon monoxide sensing is rewriting cargo hold protection standards. FedEx and UPS freighter operators are retrofitting dual-sensor arrays to distinguish smoldering lithium battery events from benign dust accumulation. The structural consequence is collapsing demand for single-technology ionization detectors in dedicated freighter configurations.
EASA F-Gas Regulation threshold reductions for fluorinated gases are compressing the approval window for HFC-227ea in European-registered aircraft. System integrators must now validate FK-5-1-12 or water mist alternatives before 2027 fleet renewal deadlines. Narrow-body operators with high European route exposure are accelerating agent substitution ahead of mandate timelines.
Airline technical procurement teams are consolidating fire system sourcing under airframe OEM line-fit agreements rather than post-delivery specification. This behavior concentrates specification influence with Boeing and Airbus engineering groups, marginalizing independent system distributors. The shift is most visible among US ultra-low-cost carriers standardizing on factory-installed configurations to minimize certificate of airworthiness complexity.
Aircraft Smoke Detection and Fire Extinguishing System Market Segmentation
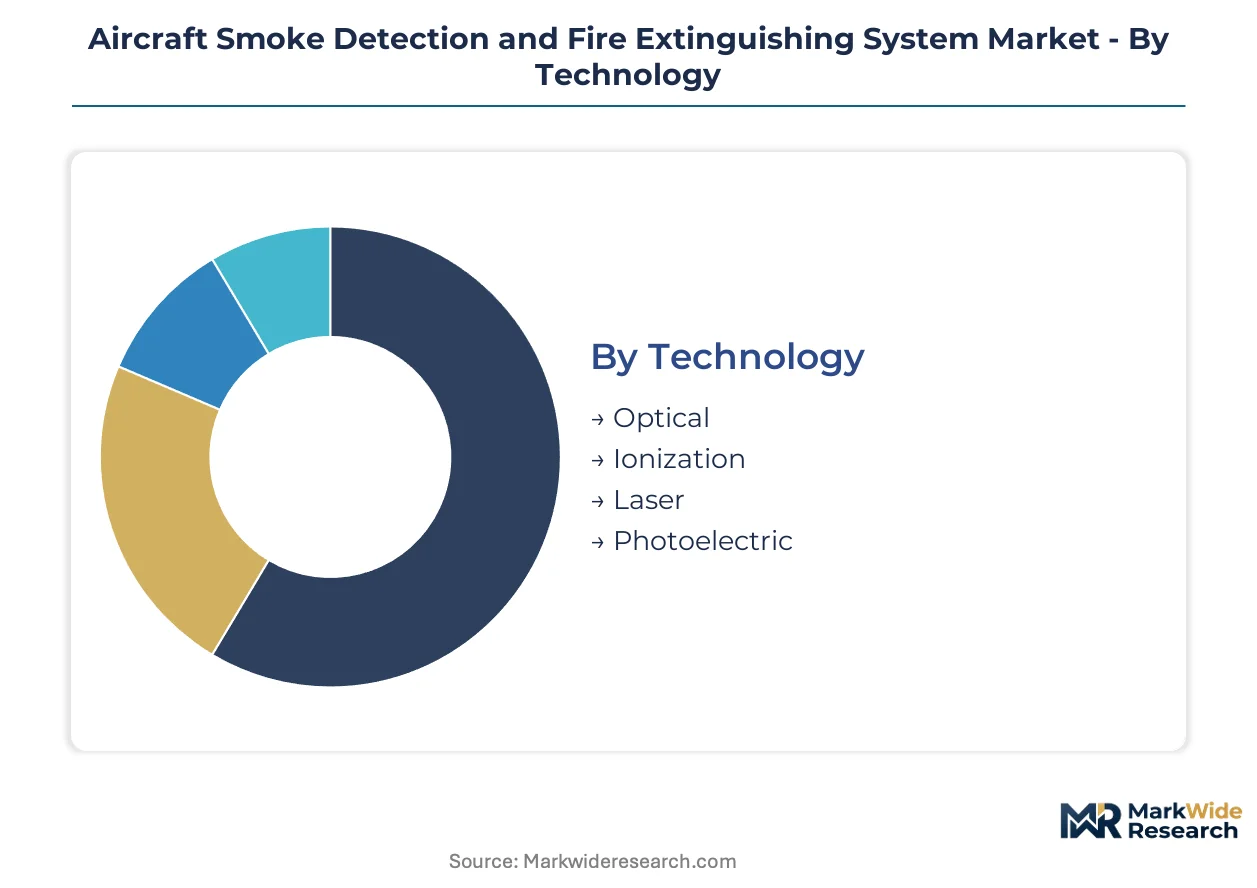
Segmentation in aircraft fire protection systems reveals how procurement authority, certification pathways, and platform-specific hazards reshape supplier economics. Buyers across segments prioritize fundamentally different performance trade-offs—weight versus sensitivity, retrofit compatibility versus factory integration, military hardening versus commercial cost efficiency.
Technology:
Optical detection platforms command premium positioning through their immunity to environmental false triggers, while legacy ionization systems retain installed-base retrofit demand.
- Optical:Dual-wavelength infrared arrays discriminate combustion particles from condensation and dust. FAA-certified installations dominate Boeing narrow-body programs where cargo hold false-alarm reduction drives specification.
- Ionization:Americium-241 based detectors respond fastest to flaming combustion events. Aging fleets in the United States sustain aftermarket demand despite EASA pressure to phase out radioactive components.
- Laser:High-sensitivity particulate detection for engine nacelle applications where rapid flame kernel identification prevents catastrophic failure.
- Photoelectric:Smoldering-fire spectral signature recognition gains share in dedicated freighter configurations serving lithium battery transport routes.
Volume sits with Optical; growth tilts toward Photoelectric.
Application:
Platform type determines suppression agent chemistry, detector redundancy requirements, and certification cost burden.
- Passenger Aircraft:Cabin and lavatory protection mandates optical detection with Halon-alternative clean agents. Airbus A320 family line-fit volumes concentrate procurement influence with Toulouse engineering specifications.
- Cargo Aircraft:Main deck and lower hold fire zones require dual-sensor arrays distinguishing battery thermal runaway from benign dust accumulation. FedEx and UPS retrofit programs validate photoelectric-carbon monoxide paired detection.
- Military Aircraft:Hardened EMI-resistant systems with battle damage tolerance command premium pricing through specialized FAA-EASA parallel certification pathways.
- Business Jets:Compact extinguisher cylinder design and reduced sensor count prioritize weight minimization for fractional ownership fleets.
Passenger Aircraft generate the largest revenue pool; Cargo Aircraft are expanding most quickly.
End User:
Procurement authority fragmentation across the value chain creates divergent specification priorities and contract structures.
- Airlines:Retrofit obligations under FAA airworthiness directives drive aftermarket demand for addressable detector loop upgrades in Boeing 737NG and 757 fleets.
- Aircraft Manufacturers:Boeing and Airbus engineering groups consolidate fire system sourcing under line-fit agreements, marginalizing independent distributors.
- Maintenance Repair Organizations:Shorter regulatory inspection intervals for aging detector fleets unlock recurring service revenue from predictive maintenance platform subscriptions.
- Regulatory Authorities:FAA Part 25 Appendix F and EASA CS-25 fire protection standards shape product development timelines through certification gatekeeping.
Procurement concentrates with Aircraft Manufacturers; technical influence is shifting toward Maintenance Repair Organizations.
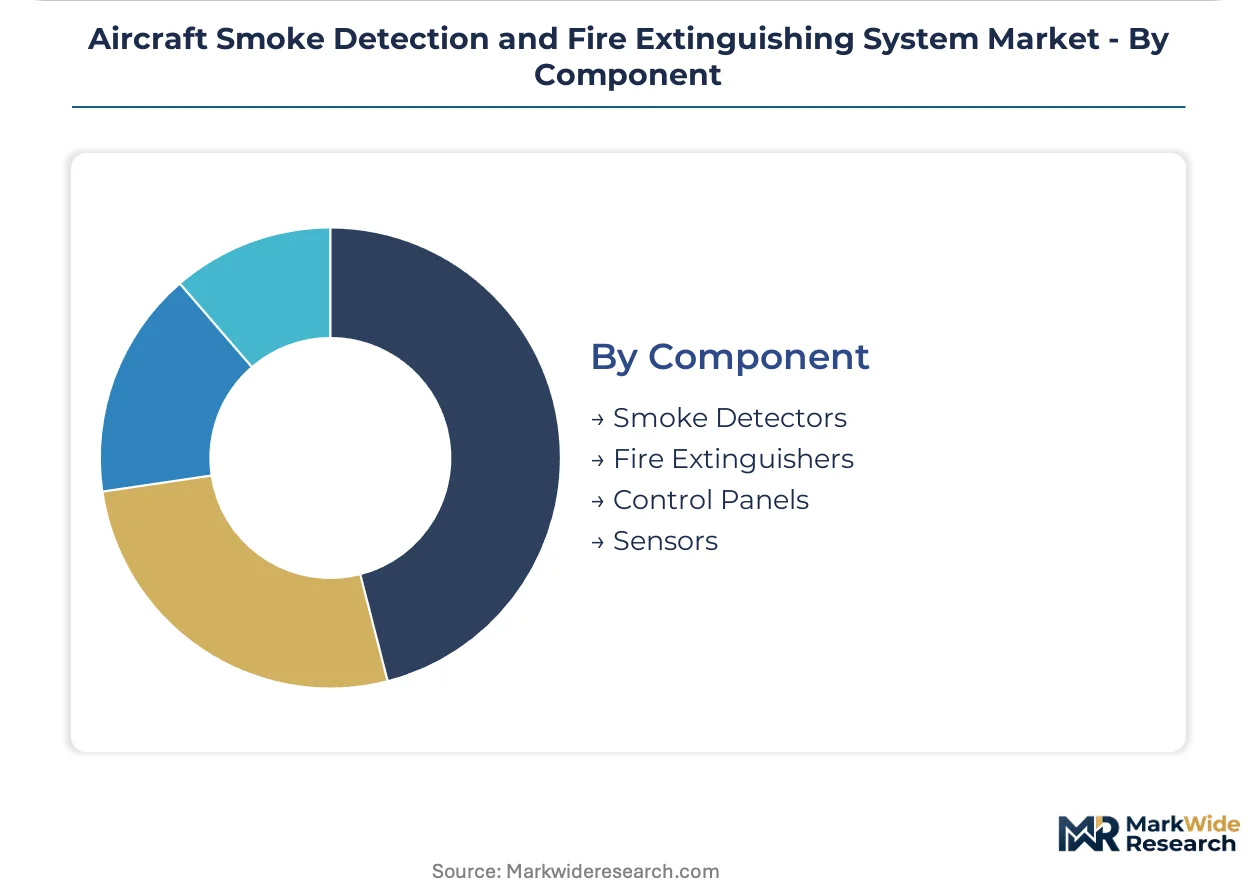
Component:
System architecture disaggregates into detection, suppression, and control subsystems with distinct margin profiles and supplier specialization.
- Smoke Detectors:Networked sensor arrays with addressable communication protocols enable centralized fault monitoring. Optical technology platforms dominate new installations.
- Fire Extinguishers:Stored-pressure agent delivery mechanisms face 40-60% cylinder volume expansion for Halon replacements, imposing weight penalties that narrow-body OEMs resist.
- Control Panels:Centralized interfaces integrating detection inputs with suppression agent release authorization require dual-channel redundancy for FAA certification.
- Sensors:Temperature, pressure, and gas composition monitoring elements support multi-criteria fire confirmation algorithms reducing false-alarm dispatch costs.
Smoke Detectors capture the highest unit volumes; Fire Extinguishers face the steepest technology transition pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial aviation procurement concentrates in the United States, where Boeing and major carriers drive retrofit volumes and new aircraft installations. Fleet modernization mandates and stricter FAA fire safety standards are reshaping regional demand patterns across major aerospace manufacturing clusters.
United States
Boeing's narrow-body delivery schedules and 737NG retrofit obligations sustain aftermarket demand for optical detection platforms. FAA airworthiness directives mandate shorter inspection intervals for aging detector fleets, concentrating technical procurement in Seattle and Charleston manufacturing corridors. Wichita's MRO ecosystem supports addressable detector loop upgrades for regional carrier fleets.
Germany
Airbus engineering specifications from Toulouse radiate procurement influence through Hamburg final assembly lines. EASA F-Gas Regulation threshold reductions for fluorinated gases compress approval windows for legacy suppressants, accelerating FK-5-1-12 validation. Bavaria's precision electronics clusters supply dual-wavelength infrared sensor components to system integrators.
France
Airbus A320 family line-fit volumes concentrate specification authority with Toulouse engineering groups. REACH chemical restrictions accelerate substitution of legacy suppressants in European-registered aircraft. Paris-region certification consultancies manage parallel FAA-EASA validation pathways for Halon-replacement chemistries.
United Kingdom
Rolls-Royce engine programs drive fire protection requirements for nacelle applications. CAA alignment with EASA standards shapes product development timelines for UK-based system distributors. Southwest England's aerospace supply chain feeds detector assembly operations serving business jet OEMs.
China
COMAC C919 delivery ramp-up creates procurement windows for fire suppression system suppliers qualifying to CAAC standards. Shanghai and Xi'an manufacturing clusters incubate domestic detector production capabilities. MIIT industrial policy prioritizes indigenous fire detection technology for civil aviation programs.
Aircraft Smoke Detection and Fire Extinguishing System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated system architects capturing premium positioning in OEM line-fit agreements. The vendor base organizes around three strategic archetypes: sensor-to-extinguisher integrated suppliers, component specialists focused on detection or suppression alone, and aerospace conglomerates leveraging airframe relationships. Consolidation pressure intensifies as Boeing and Airbus engineering groups concentrate procurement authority. Dominant competitive moves include backward integration into agent chemistry production and technology licensing partnerships spanning FAA-EASA dual certification pathways.
Within the integrated-system tier, Meggitt plc and Diehl Stiftung & Co. KG exemplify architectures spanning detection through suppression deployment. UTC Aerospace Systems anchors the aerospace-conglomerate vector with established narrow-body program positions. Siemens AG represents the industrial-electronics crossover archetype applying automation expertise to centralized control interfaces. These three occupy positions shaped by airframe OEM relationships rather than independent aftermarket distribution channels.
| Leading Market Players |
|---|
| Meggitt plc |
| Siemens AG |
| Advanced Aircraft Extinguishers, Ltd |
| Diehl Stiftung & Co. KG |
| UTC Aerospace Systems |
| Gielle Industries |
| H3R Aviation Inc. |
| Ventura Aerospace Inc. |
| Fire Fighting Enterprises Limited |
| Others |
Value Chain & Pricing Dynamics
FK-5-1-12 fluoroketone feedstock price volatility cascades through three distinct pricing tiers, with cylinder volume penalties for Halon-replacement agents compressing margins at the standard tier while premium optical detection platforms retain pricing power through FAA-certified dual-wavelength architectures.
Pricing Analysis
Volume concentrates in line-fit agreements with Boeing and Airbus engineering groups, while aftermarket retrofit commands margin premiums through addressable detector loop upgrades and shorter FAA-mandated inspection intervals. Price differentiation hinges on EASA-FAA dual-certification status and agent chemistry validation completeness, with narrow-body OEMs exhibiting acute price sensitivity to cylinder weight penalties. Pricing pressure intensifies in the standard tier as three chemical manufacturers control Novec 1230 and FK-5-1-12 production, exposing system integrators to input cost pass-through demands.
Supply Chain Analysis
Refurbishment flows for aging Boeing 737NG and 757 detector arrays create reverse-logistics revenue pools for Wichita-based MRO clusters, with addressable loop upgrades requiring custom interface modules that prolong installation downtime. Supply concentration centers on the United States for Boeing line-fit procurement, Germany for Airbus engineering specifications, and China for emerging COMAC C919 qualification programs. Critical dependencies include americium-241 for ionization detectors, dual-wavelength infrared sensor components from Bavarian precision electronics clusters, and fluoroketone agent chemistry from concentrated chemical manufacturing. Single-source vulnerability in agent production exposes integrators to supply disruption. Distribution runs through airframe OEM line-fit agreements rather than independent aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under supply-constrained conditions where Halon-replacement chemistry validation bottlenecks prop pricing premiums for certified alternatives, with only three manufacturers controlling FK-5-1-12 production capacity.
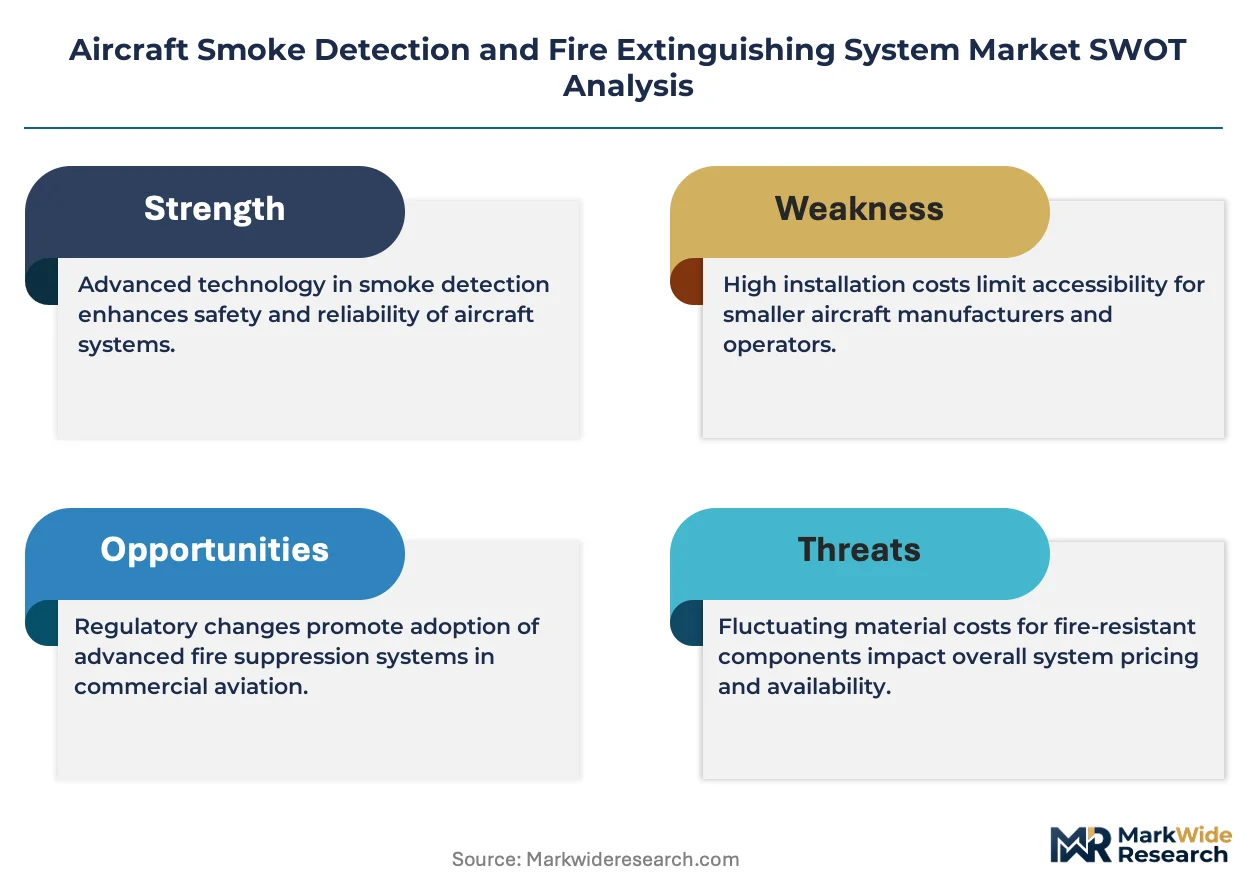
For Market Incumbents: To counter EASA-FAA regulatory divergence compressing certification timelines, Meggitt plc and Diehl Stiftung should deepen backward integration into agent chemistry production while accelerating parallel validation pathways for fluoroketone alternatives. Securing captive supply of FK-5-1-12 feedstock insulates margin pressure from input volatility. For New Entrants and Emerging Players: The premium-to-economy pricing gap in military EMI-resistant systems offers entry traction, with hardened battle-damage-tolerant architectures commanding 40-60% pricing premiums over commercial equivalents. Urban air mobility platforms lack fire suppression heritage, creating first-mover positioning for lightweight aerosol systems certified to RTCA DO-311A. Target eVTOL OEMs through direct engineering partnerships rather than distributor channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor component specialists with EASA-FAA dual-certification expertise in France and Germany, where regulatory consulting capabilities anchor valuation premiums. Long-term viability rests on IoT-enabled detector networks feeding predictive maintenance platforms. Watch for CAAC qualification completion by COMAC C919 suppliers as inflection signal for China procurement access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agent Chemistry | Captive supply of FK-5-1-12 insulates margins from three-manufacturer concentration risk. |
| EASA-FAA Dual Certification Investment | Parallel validation pathways unlock cross-Atlantic procurement economics for Halon alternatives. |
| IoT-Enabled Predictive Maintenance Platform | Recurring software revenue from airline maintenance contracts displaces transactional hardware sales. |
| Urban Air Mobility System Certification | RTCA DO-311A compliance creates first-mover advantage in eVTOL fire protection specification. |
| CAAC Qualification for COMAC Programs | Domestic certification access positions suppliers for C919 delivery ramp-up procurement windows. |
Study Parameters
Multi-period observation of FAA airworthiness directive issuance patterns, EASA CS-25 amendment timelines, and EPA Significant New Alternatives Policy program milestones anchored the trend analysis, supplemented by interviews with fire protection system engineering directors, airline technical procurement managers, MRO maintenance planners, and CAAC certification consultants. Secondary validation drew from FAA Part 25 Appendix F flammability testing records, EASA F-Gas Regulation threshold documentation, ISO 2685 fire-resistance testing protocols, and SEC filings from publicly traded aerospace suppliers. Bottom-up segment sizing triangulated against top-down OEM delivery projections.
Input-output matrices modeled suppression agent demand against aircraft delivery schedules, retrofit fleet age distributions, and regulatory mandate compliance deadlines across the projection horizon. Segmentation dimensions included detection technology platform, application platform type, end-user procurement authority, and component subsystem. CAGRs derived from regression analysis of historical certification timeline compression and fleet modernization cycle correlation. Industry-specific forecast inputs incorporated Boeing 737NG and 757 retrofit obligation schedules and Airbus A320 family line-fit specification trends.
Inputs from FAA airworthiness directive databases and EASA certification registries were available through the study window; gaps in emerging CAAC qualification completion timelines introduce uncertainty bands for China demand projections. Forecasts embed assumptions regarding Halon-replacement chemistry validation pace and cross-certification regulatory alignment. Material deviation in EPA alternative-agent approval timelines or EASA F-Gas Regulation threshold acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Aircraft Evacuation System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Global Aircraft Brake System Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Rescue Hoist System Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Door Dampers Market