
 Aviation Airbags Market | 2026-2036
Aviation Airbags Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Airbags Market Analysis
Subscription-based lifecycle maintenance for airbag inflation systems is restructuring how airlines procure cabin safety equipment. AmSafe Inc. leverages its installed base across Boeing and Airbus platforms to secure long-term service contracts. Collins Aerospace anchors its position through integrated avionics-to-safety-system architectures. Safran SA competes via its expertise in pyrotechnic initiators and controlled gas generation technologies.
Aviation airbags are deployable restraint systems engineered from coated fabric envelopes and solid-propellant gas generators, designed to absorb occupant kinetic energy during rapid deceleration events exceeding specified g-force thresholds. Primary airbags dominate retrofit budgets across aging narrow-body fleets, while seatbelt-integrated designs capture the fastest expansion as OEMs embed inflation modules directly into shoulder harness assemblies. Electronic sensor architectures now outpace mechanical trigger systems in new installations, concentrating margin pools among suppliers with firmware-certification capabilities.
FAA Technical Standard Orders and EASA Certification Specifications govern airbag performance thresholds, deployment latency, and environmental durability testing. The EU AI Act and CSRD reporting requirements are beginning to shape supplier disclosure obligations on algorithmic sensor logic and supply chain emissions. Stakeholders must monitor how emerging rulemakings on autonomous cabin safety systems redefine the boundary between hardware compliance and software validation.
Market Dynamics
Retrofit mandates for narrow-body fleets are compressing installation timelines, forcing suppliers to balance certification velocity with pyrotechnic reliability standards.
Growth Catalysts
- FAA Technical Standard Order TSO-C114b:Updated crashworthiness thresholds mandate faster deployment latencies, compelling fleet operators to upgrade legacy mechanical trigger systems.
- Seatbelt-integrated inflation modules:OEMs embed shoulder harness airbags directly into restraint assemblies, eliminating separate module housing and reducing cabin weight.
- Pyrotechnic initiator supply clusters:Concentrated manufacturing expertise in France and the United States accelerates prototyping cycles for next-generation gas generators.
Market Restraints
- Coated fabric input volatility:Specialized aramid and silicone-coated textiles face price instability from aerospace-grade polymer supply constraints.
- Dual-source certification requirements:FAA and EASA demand redundant supplier qualification, extending qualification timelines for single-source pyrotechnic vendors.
- Electronic sensor firmware liability:Algorithmic deployment logic creates exposure to product liability claims exceeding historical mechanical trigger risk profiles.
Strategic Opportunities
- India narrow-body fleet expansion:IndiGo and Air India procurement programs create first-mover advantage for airbag suppliers establishing local technical support.
- EU CSRD emissions disclosure:Mandated supply chain carbon reporting favors suppliers with verified low-emission gas generator chemistries.
- Avionics-safety convergence:Integration of cabin pressure sensors with restraint deployment algorithms enables predictive inflation before impact detection.
Industry Challenges
- Firmware certification expertise scarcity:Qualified engineers capable of DO-178C software validation for airborne electronic hardware command premium compensation.
- Legacy fleet wiring incompatibility:Aging 737 Classic and A320ceo electrical architectures require costly harness modifications to support electronic trigger systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Airbags Market |
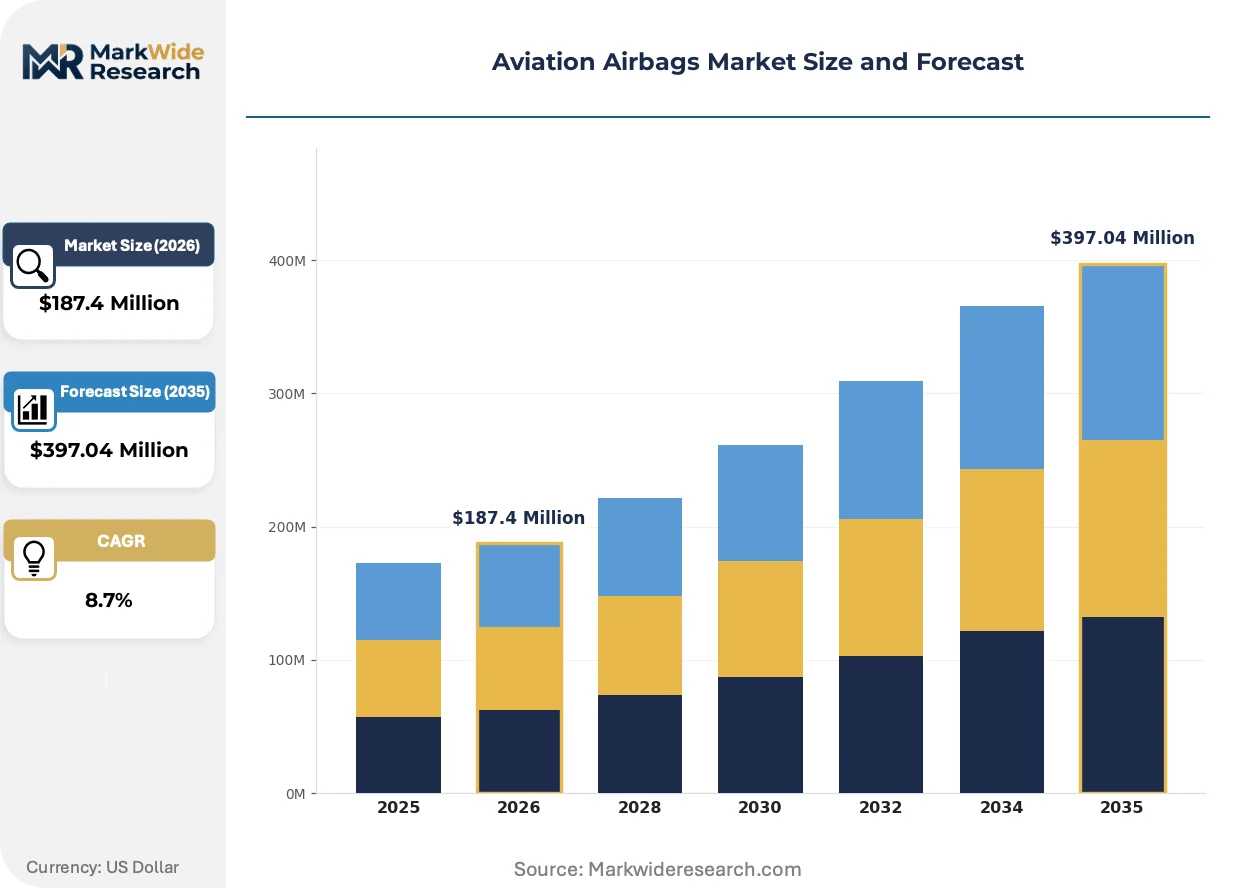
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Airbags, Secondary Airbags, Side Airbags, Seatbelt Airbags Technology: Mechanical, Electronic, Hybrid, Inflatable End User: Commercial Aviation, Military Aviation, Business Aviation, Private Aviation Application: Passenger Safety, Cargo Protection, Ground Handling, Emergency Situations |
| Companies Covered | AmSafe Inc., PRONAL S.A., Collins Aerospace, IDEX Corporation, RESQTEC Zumro B.V., Safran SA, SCHROTH Safety Products GmbH, Musthane S.A., TransDigm Group Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Airbags Market Emerging Trajectories
Aviation airbag technology is pivoting from standalone hardware toward integrated cabin safety architectures, with sensor fusion and predictive algorithms redefining deployment timing.
Smart fabric sensors woven directly into seat upholstery are expanding into real-time occupant position detection, enabling variable inflation force based on passenger size and posture. Narrow-body OEMs adopt these systems fastest, driven by single-aisle certification cycles that are shorter than wide-body programs. The technology is expanding into aftermarket retrofit channels previously dominated by mechanical upgrades.
EASA Certification Specification CS-25 amendments on dynamic seating tests are tightening g-force thresholds for head injury criteria, forcing suppliers to redesign gas generator output curves. Airlines operating European routes face compressed compliance deadlines compared to other jurisdictions. Seatbelt-integrated designs absorb disproportionate engineering resources as manufacturers race to meet the revised specifications.
Airlines now unbundle lifecycle maintenance from initial equipment purchase, signing separate service agreements for inflation system inspection and cartridge replacement. This fragments the traditional single-source procurement relationship between OEMs and safety suppliers. The shift is most visible in United States-based carrier fleets, where operational leasing structures accelerate component-level contract innovation.
Aviation Airbags Market Segmentation
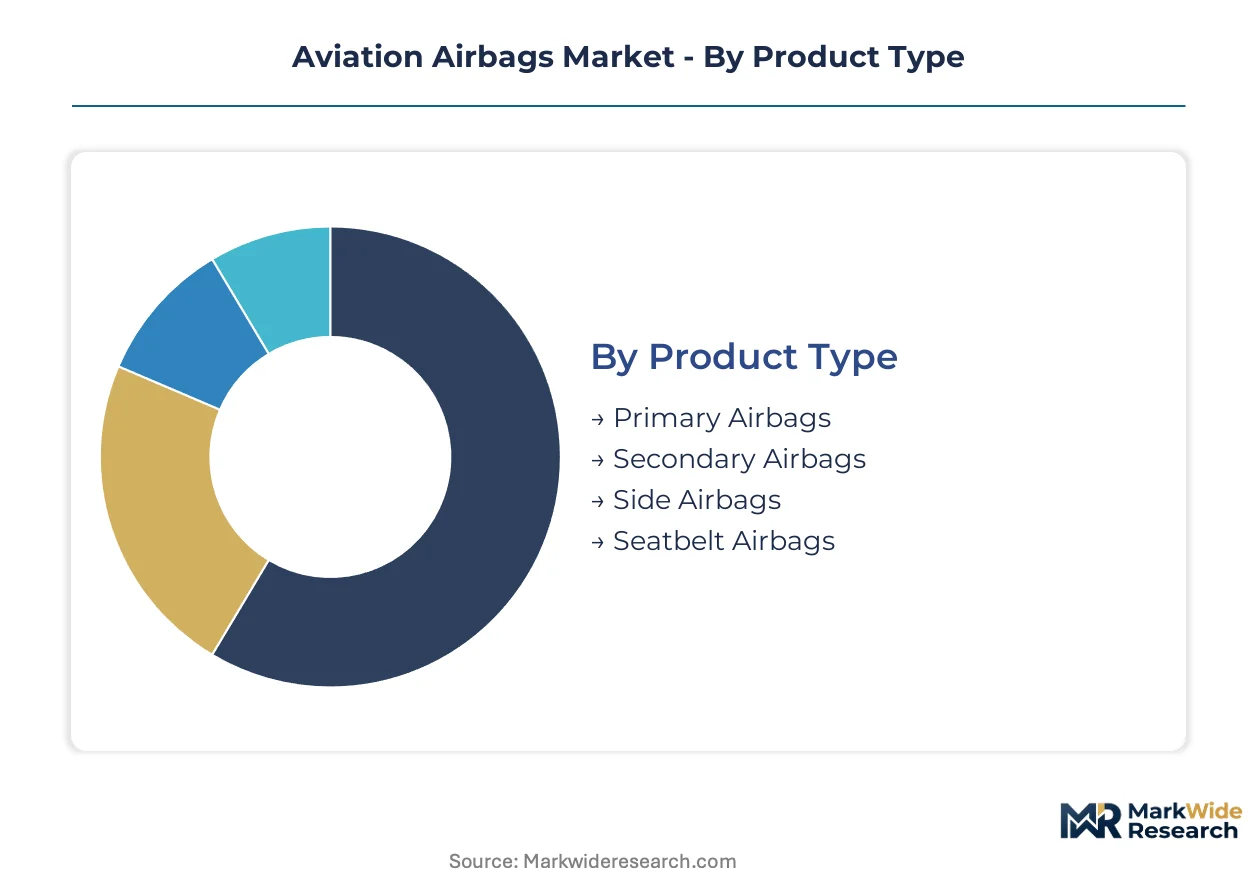
Airbag procurement patterns diverge sharply across aircraft programs, with retrofit timelines and OEM integration cycles creating distinct demand profiles for each segment category. Suppliers must align certification resources against these structural differences to capture recurring revenue streams.
Product Type:
Airline fleet strategies separate buyers into weight-sensitive narrow-body operators versus feature-focused wide-body carriers, with retrofit urgency varying by aircraft age profile.
- Primary Airbags:These forward-facing torso protection systems utilize coated aramid fabric envelopes with solid-propellant gas generators sized for 16g deceleration events. Narrow-body retrofit programs in the United States concentrate procurement volumes here, driven by FAA TSO-C114b compliance deadlines for aging 737 and A320 fleets.
- Seatbelt Airbags:Inflation modules embedded directly into shoulder harness assemblies eliminate separate housing structures and reduce per-passenger weight by approximately 0.8 kilograms. OEM new-build contracts for single-aisle platforms favor this architecture, with Airbus A321XLR and Boeing 737 MAX programs specifying integrated designs from initial certification.
- Secondary Airbags:Supplementary knee and lower-leg protection systems address revised EASA head injury criteria for dynamic seating tests.
- Side Airbags:Lateral impact protection for premium cabin configurations and business jet interiors.
Volume sits with Primary Airbags; growth tilts toward Seatbelt Airbags.
Technology:
Certification velocity and liability exposure divide procurement decisions, with firmware-capable suppliers commanding premium positioning against mechanical legacy vendors.
- Electronic:Sensor-fusion architectures combining accelerometer data with cabin pressure monitoring enable predictive deployment algorithms. United States-based carriers lead adoption, motivated by operational leasing structures that favor predictive maintenance and cartridge-life monitoring through connected diagnostics.
- Mechanical:Spring-mass trigger systems with fixed g-force thresholds persist in cargo applications and military platforms where electromagnetic hardening requirements complicate electronic validation. Budget-constrained retrofit programs for 737 Classic and A320ceo fleets extend procurement timelines for this mature technology.
- Hybrid:Dual-path triggering with mechanical backup for electronic primary activation.
- Inflatable:Non-pyrotechnic cold gas systems for specialized cargo restraint and ground handling equipment.
Mechanical retains volume in cargo and military channels; Electronic gains share fastest in passenger applications.
End User:
Procurement scale and contract structure vary dramatically, from high-volume line-fit programs to fragmented aftermarket decisions by individual operators.
- Commercial Aviation:Scheduled carriers and low-cost operators generate the largest equipment volumes through fleet-wide retrofit mandates and new-aircraft line-fit specifications. IndiGo and Air India narrow-body expansion programs in India create concentrated demand windows for suppliers establishing local technical support capabilities.
- Business Aviation:Fractional ownership fleets and corporate flight departments prioritize customization and premium cabin integration over unit cost, accepting longer lead times for bespoke seatbelt-integrated configurations in Gulfstream and Dassault platforms.
- Military Aviation:Crew restraint systems for tactical transport and rotary-wing platforms with electromagnetic compatibility requirements.
- Private Aviation:Owner-operated aircraft with sporadic aftermarket upgrade decisions.
Commercial Aviation dominates absolute volume; Business Aviation offers the steepest expansion trajectory.
Application:
Regulatory scope and certification pathway determine supplier qualification requirements, with passenger-facing systems subject to stricter ongoing airworthiness oversight.
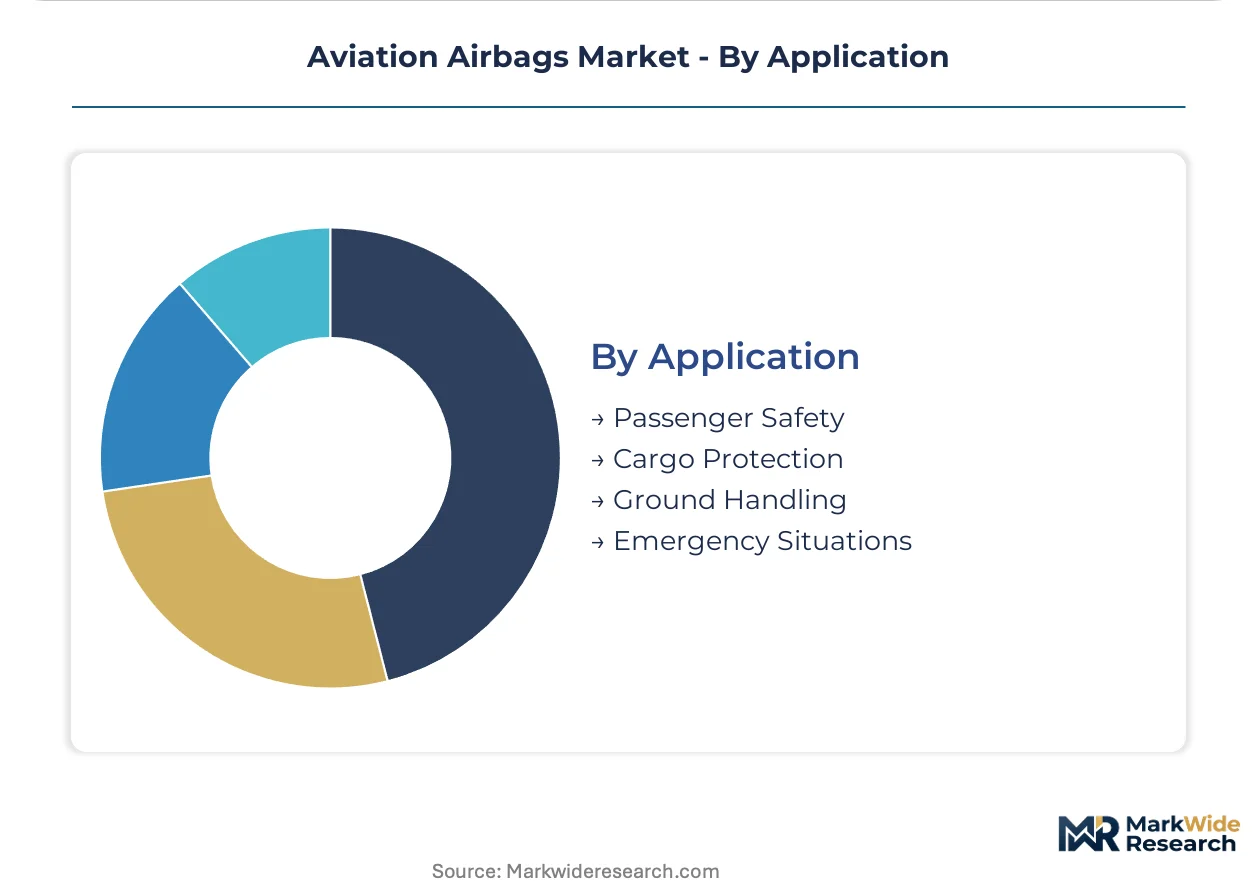
- Passenger Safety:FAA and EASA crashworthiness mandates govern occupant restraint deployment latency and head injury criteria for all transport-category aircraft. European route operators face compressed compliance schedules under EASA CS-25 amendment timelines compared to other jurisdictions.
- Cargo Protection:Unit load device restraint and main-deck cargo barrier systems address freighter-specific deceleration scenarios, with reduced firmware liability exposure versus passenger applications.
- Ground Handling:Aircraft towbar and jack protection for maintenance operations.
- Emergency Situations:Evacuation slide and raft inflation systems with overlapping pyrotechnic supply chains.
Passenger Safety commands regulatory attention and R&D investment; Cargo Protection offers faster qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of pyrotechnic initiators and gas generator assemblies clusters in France and the United States, while fleet expansion and retrofit demand concentrate in India and European route networks. This production-consumption divide shapes supplier location strategies and technical support investments.
United States
FAA Technical Standard Order TSO-C114b compliance deadlines drive narrow-body retrofit programs for aging 737 and A320 fleets. The FAA mandates updated crashworthiness thresholds with faster deployment latencies. Seattle and Wichita host major airframe manufacturer engineering centers where safety system integration occurs.
France
Safran SA anchors pyrotechnic expertise in controlled gas generation technologies for aviation applications. EASA Certification Specification CS-25 amendments on dynamic seating tests tighten g-force thresholds for European route operators. Toulouse and Paris-Saclay concentrate aerospace supply chain engineering and regulatory liaison functions.
India
IndiGo and Air India narrow-body fleet expansion programs create concentrated demand windows for cabin safety equipment. The country's national aviation regulator aligns with ICAO standards while developing indigenous certification capacity. Mumbai and Delhi-NCR emerge as technical support hubs for suppliers establishing local service presence.
Germany
EU CSRD emissions disclosure requirements favor suppliers with verified low-emission gas generator chemistries serving European carriers. The KBA participates in EASA rulemaking on autonomous cabin safety systems. Hamburg and Munich house business aviation completion centers specifying bespoke seatbelt-integrated configurations.
United Kingdom
Collins Aerospace leverages integrated avionics-to-safety-system architectures through British engineering operations. The UK Civil Aviation Authority implements EASA-aligned crashworthiness standards with compressed compliance schedules. London and Southwest England clusters concentrate aftermarket service provider procurement decision-making.
Aviation Airbags Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the aviation airbags market, with integrated aerospace conglomerates holding pyrotechnic manufacturing assets while specialized safety firms focus on certification and integration engineering. The structure tilts toward consolidated supply given FAA and EASA dual-source requirements, yet firmware-certification capabilities create differentiation tiers. Three archetypes dominate: full-system integrators with airframe OEM relationships, pyrotechnic component specialists with initiator chemistry expertise, and avionics convergence players bridging sensor and deployment logic. Competitive moves center on long-term service contract capture and avionics-safety architecture integration.
Among full-system integrators, AmSafe Inc. and Collins Aerospace occupy positions defined by installed base scale and platform coverage breadth. Safran SA exemplifies the pyrotechnic specialist archetype through its concentration in initiator and gas generator technologies. These three companies anchor the competitive structure, with their respective strengths in service contract retention, avionics integration, and controlled gas generation representing the primary vectors of rivalry.
| Leading Market Players |
|---|
| AmSafe Inc. |
| PRONAL S.A. |
| Collins Aerospace |
| IDEX Corporation |
| RESQTEC Zumro B.V. |
| Safran SA |
| SCHROTH Safety Products GmbH |
| Musthane S.A. |
| TransDigm Group Incorporated |
| Others |
Supply Flow & Price Mechanics
Pyrotechnic chemist clusters in France and the United States create labor-cost differentials that widen pricing-tier spreads between premium electronic sensor systems and commodity mechanical triggers. Firmware-certification engineers command premium compensation in Toulouse and Wichita, forcing suppliers to pass these specialized labor costs through to tier-one OEM contracts while mechanical legacy products compete on volume economics.
Pricing Analysis
Cost-down pressure on mechanical trigger tiers accelerates because budget-constrained retrofit programs for aging narrow-body fleets extend procurement timelines and compress supplier margins. Three-tier pricing structure across premium electronic, standard hybrid, and economy mechanical levels separates buyers by certification velocity requirements. Price differentiation traces to DO-178C firmware validation tier and pyrotechnic initiator chemistry grade. Commercial aviation carriers exhibit highest price sensitivity due to fleet-scale procurement volumes, while business aviation operators accept premium positioning for bespoke seatbelt-integrated configurations.
Supply Chain Analysis
Cartridge return flows for refurbishment and remanufacturing concentrate aftermarket service revenue among suppliers with established technical support networks in Mumbai and Dallas-Fort Worth. Solid-propellant gas generator manufacturing clusters in France, the United States, and Germany, drawing from aramid fiber feedstocks and specialized silicone-coated textile inputs. Single-source vulnerability in pyrotechnic initiator chemistry creates exposure to EASA dual-source certification delays. Distribution runs through airframe OEM line-fit channels and MRO service providers with direct airline contracting authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where qualified DO-178C firmware engineers represent the binding capacity bottleneck, propping pricing power for certificated suppliers against uncertificated competitors.
For Market Incumbents: Acquire firmware-certification engineering teams in Toulouse and Wichita to secure DO-178C validation capacity against emerging avionics convergence players. Consolidate pyrotechnic initiator supply positions through backward integration into gas generator chemistry to defend margin structure against dual-source certification requirements. For New Entrants and Emerging Players: Cargo operators with electromagnetic hardening requirements represent an underserved buyer archetype bypassed by passenger-focused electronic sensor suppliers. Military aviation platforms and freighter-specific restraint applications offer penetrable segments with reduced firmware liability exposure. Establish technical partnerships with MRO networks in India to capture IndiGo and Air India narrow-body fleet expansion demand. For Investors and Strategic Acquirers: Re-rating potential sits with pyrotechnic component specialists given EASA CS-25 amendment compliance deadlines tightening across European route networks. Long-term viability favors suppliers with captive gas generator chemistry and established airframe OEM line-fit relationships. Monitor FAA TSO-C114b retrofit program acceleration as early signal for capacity utilization inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware Certification Investment | DO-178C validation capability unlocks premium electronic sensor contracts with Boeing and Airbus platforms. |
| Pyrotechnic Chemistry Backward Integration | In-house gas generator production secures margin control against aramid fiber input volatility. |
| India Technical Support Expansion | Local engineering presence captures IndiGo and Air India narrow-body procurement windows. |
| Subscription Service Contract Conversion | Lifecycle maintenance unbundling fragments traditional OEM procurement relationships toward recurring revenue. |
| Avionics-Safety Architecture Convergence | Cabin pressure sensor integration enables predictive inflation algorithms before impact detection. |
Methodological Framework
Document review covered FAA TSO-C114b filings, EASA CS-25 amendment records, and airframe OEM safety system specifications, complemented by interviews with fleet engineering directors, MRO procurement managers, pyrotechnic R&D leads, and regulatory certification specialists. Secondary validation drew from customs trade data, SEC aerospace supplier filings, and ICAO safety incident databases. Bottom-up equipment unit estimates and top-down fleet expansion projections were triangulated against retrofit program announcements.
Segment-level outputs across the analysis window reflect modeled deployment by product type, technology architecture, end-user category, and application scope. CAGRs were derived from regression analysis of historical fleet retrofit cycles and new-aircraft delivery schedules, with inputs including narrow-body fleet age profiles, EASA compliance deadline clustering, and electronic sensor adoption curves in United States-based carrier fleets.
Revisions become necessary when FAA or EASA rulemakings on autonomous cabin safety systems materialize, or when pyrotechnic initiator supply disruptions alter qualification timelines. Forecasts reflect assumptions on certification velocity and firmware liability exposure. Practitioners should monitor EASA CS-25 amendment implementation schedules and India narrow-body delivery ramps for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Aircraft Carbon Brakes Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Aircraft Arresting System Market
Aircraft Safety Systems
Aircraft Lightning Protection Market
Aircraft Safety Systems
Aircraft Door Dampers Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market