
 Aircraft Docking Systems Market | 2026-2036
Aircraft Docking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Docking Systems Market Analysis
Aftermarket service revenue is reconfiguring margin distribution between original equipment fabrication and lifecycle maintenance contracts. Kern Steel Fabrication leverages its structural steel expertise to dominate heavy-duty fixed docking installations across North American military bases. CTI Systems S.à r.l. anchors European supply chains through electromechanical platform specialization. NIJL Aircraft Docking competes on retrofit engineering, converting legacy hangar infrastructure for next-generation wide-body compatibility.
Aircraft docking systems comprise precision-engineered elevated platforms, nose docks, and wing stands that position maintenance personnel at optimal working height relative to fuselage geometry, typically supporting loads exceeding 45 tons with deflection tolerances below 3 millimeters. These structures enable safe access for airframe inspection, engine replacement, and livery refurbishment in confined hangar environments. Mobile docking systems command expanding share as airlines prioritize fleet flexibility and reduced hangar downtime, while automated docking solutions represent the fastest-growing technology category despite higher capital thresholds. Fixed docking systems retain maturity in dedicated military and heavy maintenance facilities where aircraft types remain standardized over decades.
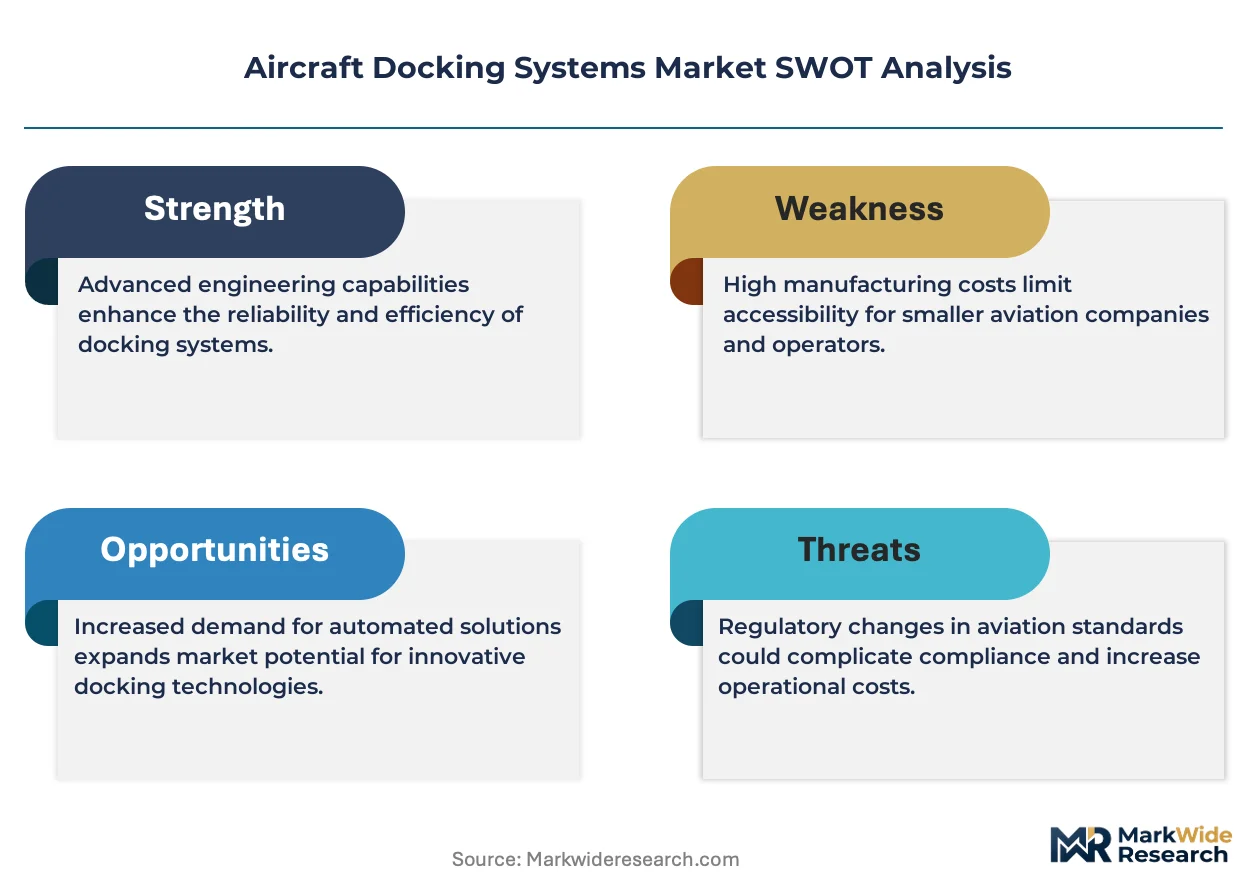
FAA airworthiness standards and EASA CS-25 certification requirements govern structural integrity and electromagnetic compatibility for all docking equipment interfacing with commercial aircraft. OSHA fall protection mandates and ISO 9001 quality management frameworks further shape manufacturer design protocols and operator training obligations. Stakeholders must monitor evolving hybrid technology standards that integrate electromechanical precision with hydraulic power density for next-generation docking platforms.
Market Dynamics
Automated docking solutions are compressing fleet turnaround windows while FAA airworthiness directives and EASA certification standards force structural recertification cycles that reshape procurement timelines across commercial aviation maintenance networks.
Growth Catalysts
- FAA Airworthiness Directives:Mandated structural integrity assessments for aging commercial fleets drive replacement demand for precision-engineered docking platforms that meet updated load-bearing specifications.
- Wide-body fleet expansion:Airlines operating Airbus A350 and Boeing 787 variants require nose docks and wing stands reconfigured for composite fuselage geometries and extended wingspans.
- Mobile electromechanical platforms:German manufacturing clusters advance servo-driven positioning systems that reduce hangar reconfiguration time between aircraft type changes.
Market Restraints
- High-grade structural steel volatility:Fluctuations in specialized alloy prices compress fabrication margins for fixed docking installations requiring 45-ton load ratings.
- Electromechanical component supply concentration:Precision servo motors and linear actuators concentrate in East Asian supply chains, exposing lead time risks for European and North American system integrators.
- Hangar dimensional constraints:Legacy maintenance facilities built for narrow-body aircraft lack ceiling height and floor loading capacity for next-generation wide-body docking configurations.
Strategic Opportunities
- India MRO infrastructure buildout:The country's PLI scheme for aviation manufacturing creates demand for modular docking systems as domestic maintenance capacity expands to serve Southeast Asian carriers.
- Hybrid hydraulic-electromechanical convergence:Platforms combining hydraulic power density with electromechanical precision address load requirements exceeding 60 tons while enabling programmable positioning.
- Retrofit engineering services:Conversion of legacy fixed installations for multi-aircraft compatibility opens recurring revenue streams as airlines diversify fleet compositions.
Industry Challenges
- Certification timeline compression:EASA CS-25 structural approval cycles for modified docking configurations extend 14-18 months, delaying revenue recognition for system upgrades.
- Electromechanical-hydraulic integration complexity:Maintenance technicians require cross-trained expertise in both drive systems, creating workforce development gaps at regional MRO facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Docking Systems Market |
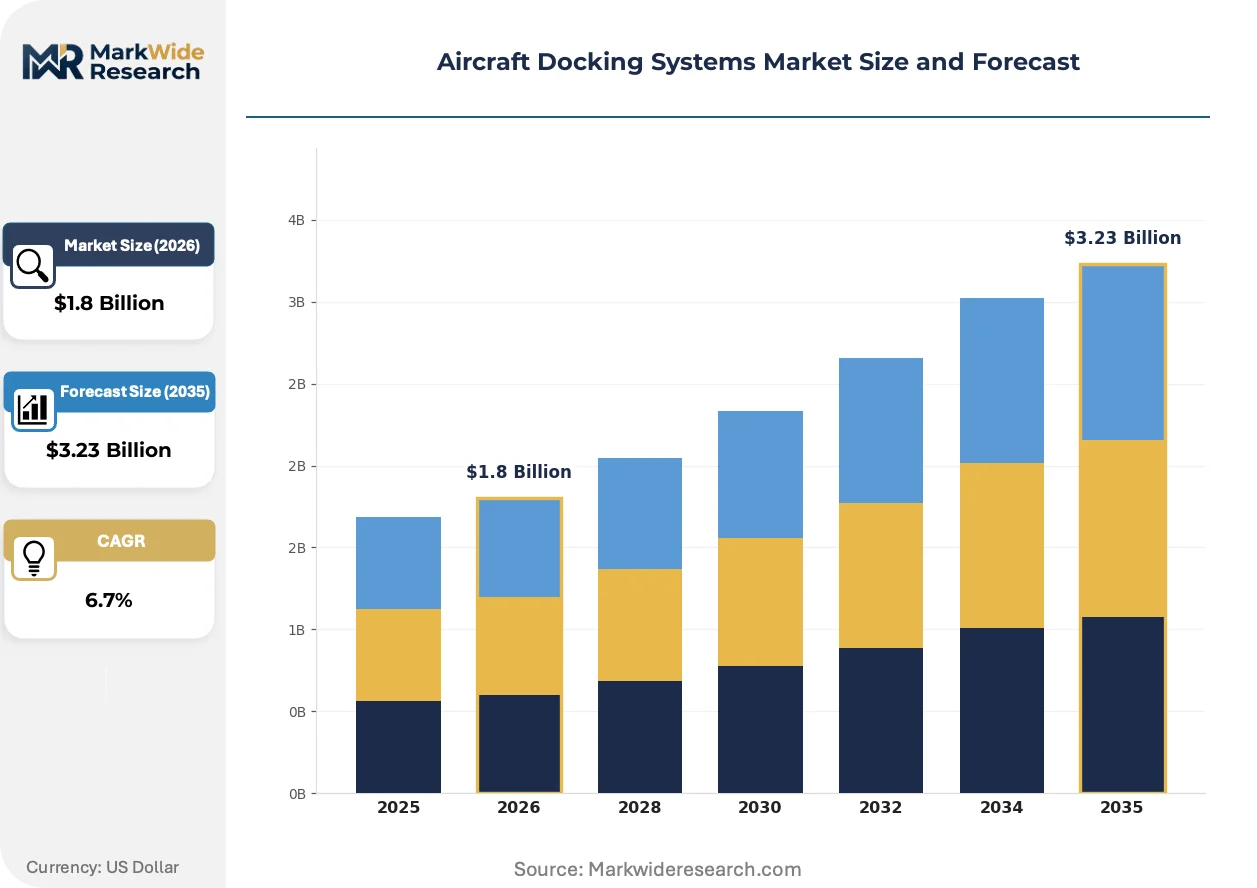
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Docking Systems, Mobile Docking Systems, Portable Docking Systems, Automated Docking Solutions Technology: Electromechanical, Hydraulic, Pneumatic, Hybrid Systems End User: Airports, Maintenance Facilities, Military Bases, Airlines Installation Type: Permanent Installation, Temporary Installation, Retrofit Solutions, Custom Installations |
| Companies Covered | Kern Steel Fabrication, Inc., SEMMCO, CTI Systems S.à r.l., SICK AG, Metaltech, NIJL Aircraft Docking, Altech, ZARGES GMBH, KAWASAKI HEAVY INDUSTRIES, LTD., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Docking Systems Market Emerging Trajectories
Docking technology is migrating toward programmable automation while regulatory frameworks harden electromagnetic compatibility requirements. These forces compress the viable technology lifecycle for equipment manufacturers.
Laser-guided positioning systems are migrating from military maintenance facilities into commercial airline operations. Lufthansa Technik and Delta TechOps deploy these systems for sub-millimeter fuselage alignment during heavy checks. The technology is migrating from fixed-installation heritage toward mobile platform configurations that enable same-day aircraft type changes.
EASA F-Gas Regulation restrictions on hydraulic fluids with high global warming potential are forcing refrigerant and lubricant substitutions in docking system power units. German and French manufacturers reformulate hydraulic circuits to accommodate lower-viscosity biodegradable alternatives. MRO providers in the European Union face compliance deadlines that accelerate capital replacement cycles for aging fixed installations.
Airline procurement departments unbundle after-sales service contracts from initial equipment purchases. Maintenance agreements now price separately from platform fabrication, with third-party service providers capturing lifecycle revenue previously retained by original manufacturers. This restructuring concentrates in North American carrier procurement, where fleet management subsidiaries negotiate direct maintenance contracts independent of equipment sourcing.
Aircraft Docking Systems Market Segmentation
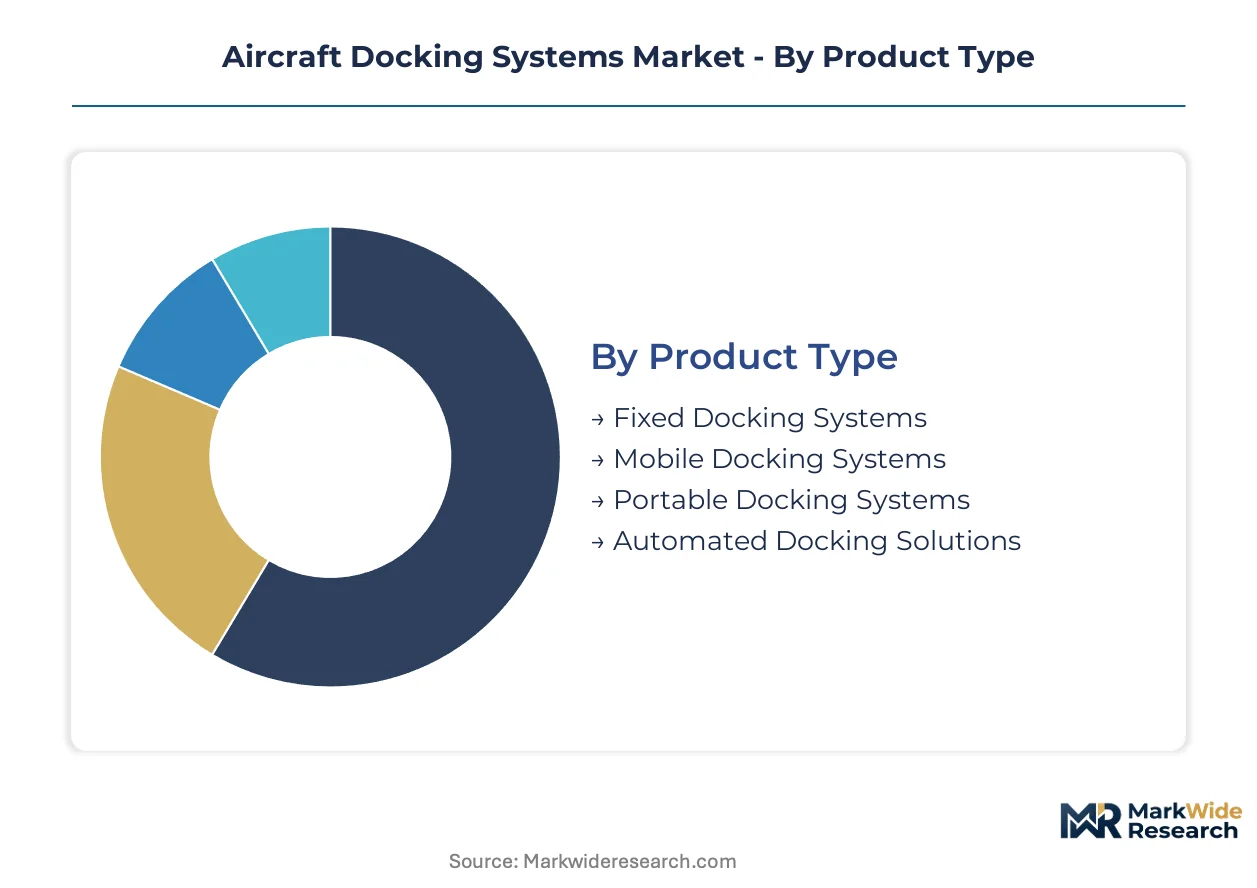
Segmentation in aircraft docking systems determines procurement pathways, certification requirements, and lifecycle revenue distribution. After-sales service intensity varies dramatically across product configurations, reshaping manufacturer margin structures and customer lock-in duration.
Product Type:
After-sales service contracts concentrate most heavily on automated and mobile platforms, where electromechanical complexity drives recurring maintenance revenue.
- Fixed Docking Systems:Heavy-duty steel structures permanently anchored to hangar foundations, typically supporting 45-ton load ratings with deflection tolerances below 3 millimeters. Demand clusters at military bases and dedicated heavy maintenance facilities in Germany and the United States, where standardized aircraft types justify capital-intensive permanent installations. FAA airworthiness directives and EASA certification standards govern structural recertification cycles that extend equipment lifespans across decades.
- Mobile Docking Systems:Rail-mounted or free-moving platforms enabling rapid hangar reconfiguration between aircraft types. Airlines prioritize these configurations for fleet flexibility, particularly at Delta TechOps and Lufthansa Technik facilities where same-day aircraft type changes compress turnaround windows.
- Portable Docking Systems:Modular components assembled on-site for temporary maintenance campaigns, common at regional MRO facilities with limited capital budgets.
- Automated Docking Solutions:Servo-driven positioning systems with programmable fuselage alignment, commanding premium pricing despite higher capital thresholds.
Fixed installations hold the largest share; momentum sits with automated solutions gaining share fastest.
Technology:
Cost tier stratification separates premium electromechanical precision from commodity hydraulic power density, with hybrid configurations emerging at the intersection.
- Electromechanical:Servo motors and linear actuators deliver programmable positioning with sub-millimeter accuracy. German manufacturing clusters in Bavaria and Baden-Württemberg concentrate production of precision drive components, though East Asian supply chains dominate servo motor fabrication.
- Hydraulic:Power-dense actuation systems handling loads exceeding 60 tons, prevalent in legacy fixed installations. EASA F-Gas Regulation restrictions on high-global-warming-potential hydraulic fluids force lubricant substitutions that accelerate replacement cycles across European Union maintenance facilities.
- Pneumatic:Compressed-air systems for lightweight access platforms and emergency deployment scenarios.
- Hybrid Systems:Converged hydraulic-electromechanical architectures combining power density with precision programmability.
Hydraulic technology retains installed base dominance; hybrid configurations are climbing the fastest.
End User:
Application-specific load profiles and certification requirements fragment procurement specifications across operator types.
- Airports:Ground handling operators require rapid-deployment docking for overnight maintenance windows, prioritizing mobile configurations that minimize hangar footprint.
- Maintenance Facilities:Independent MRO providers and airline technical divisions drive demand for multi-aircraft compatibility and retrofit engineering services.
- Military Bases:Fixed installations dominate at United States Air Force and Bundeswehr facilities, where standardized fleet compositions justify permanent infrastructure.
- Airlines:Fleet management subsidiaries unbundle equipment procurement from maintenance contracts, reshaping vendor relationships toward lifecycle service partnerships.
Maintenance facilities hold the largest share; momentum sits with airline direct procurement expanding most quickly.
Installation Type:
Maturity gradients separate established permanent infrastructure from emerging retrofit opportunities that convert legacy assets.
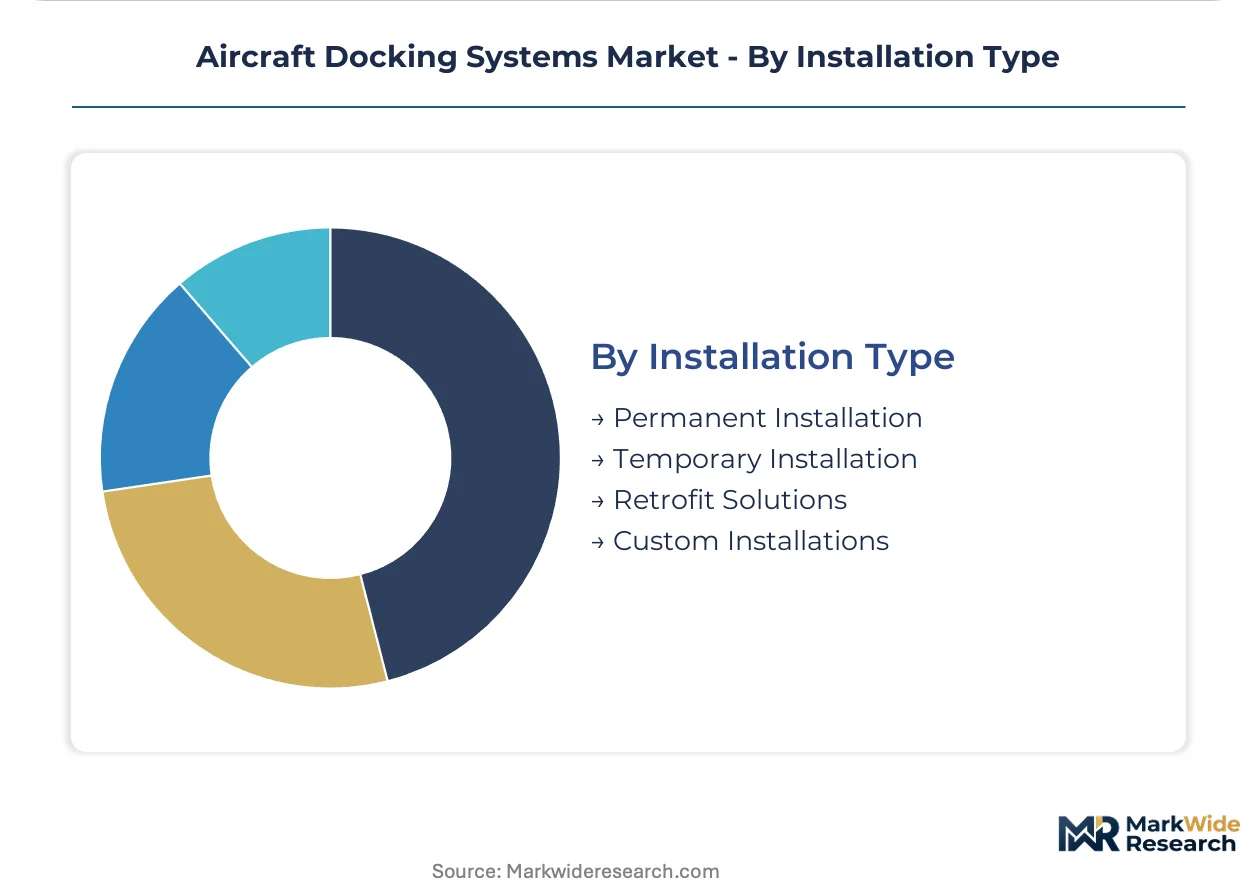
- Permanent Installation:Foundation-anchored structures requiring 12-18 month deployment timelines and extensive civil engineering coordination.
- Temporary Installation:Rapid-assembly configurations for surge maintenance capacity or emergency airworthiness directive compliance campaigns.
- Retrofit Solutions:Engineering services converting fixed installations for next-generation wide-body compatibility, opening recurring revenue streams as airlines diversify fleet compositions toward Airbus A350 and Boeing 787 variants.
- Custom Installations:Purpose-engineered platforms for non-standard fuselage geometries or constrained hangar dimensions.
Permanent installations hold the largest share; retrofit solutions are gaining share fastest as fleet diversification accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German MRO facilities favor electromechanical precision platforms, while US military bases anchor fixed steel installations. Indian carriers prioritize mobile configurations for fleet flexibility. Japanese manufacturers integrate automated positioning into narrow-body hangars. UAE infrastructure investments target wide-body compatibility for superjumbo maintenance.
United States
US Air Force bases and commercial MRO networks drive demand for 45-ton load-rated fixed installations. FAA airworthiness directives mandate structural recertification cycles that compress replacement timelines for aging steel platforms. Kern Steel Fabrication anchors heavy-duty fabrication clusters across military maintenance corridors in Texas and California.
Germany
Lufthansa Technik facilities deploy servo-driven mobile platforms for same-day aircraft type changes. EASA F-Gas Regulation restrictions force hydraulic fluid substitutions that accelerate capital replacement across Bavarian maintenance hubs. CTI Systems S.à r.l. concentrates electromechanical specialization in Baden-Württemberg manufacturing corridors.
India
Domestic carriers expanding A320 and 737 fleets require modular docking for overnight maintenance windows. The PLI scheme for aviation manufacturing subsidizes MRO infrastructure buildout in Maharashtra and Karnataka. Independent maintenance providers in Delhi-NCR prioritize portable configurations for limited capital budgets.
Japan
ANA and JAL technical divisions automate narrow-body hangar operations with laser-guided positioning systems. METI industrial standards govern electromagnetic compatibility for electromechanical platforms interfacing with composite fuselages. Kawasaki Heavy Industries integrates docking fabrication with existing aerospace manufacturing in the Kansai region.
United Arab Emirates
Emirates and Etihad wide-body fleets drive demand for nose docks reconfigured for A380 and 777X geometries. The country's aviation regulator mandates load-bearing certifications for equipment supporting superjumbo maintenance. Dubai South maintenance clusters import German electromechanical platforms for hangar automation.
Aircraft Docking Systems Market Vendor Landscape
Capability concentration sits with electromechanical specialists; scale advantage sits with structural steel fabricators. The vendor base separates into three tiers: integrated aerospace conglomerates with captive docking divisions, dedicated platform manufacturers with certification expertise, and regional fabrication shops serving military contracts. Strategic archetypes include precision automation specialists, heavy-structure steel fabricators, and retrofit engineering service providers. Competitive moves center on vertical integration into after-sales service contracts and geographic expansion through certification reciprocity agreements.
Among North American steel fabricators, Kern Steel Fabrication, Inc. exemplifies the heavy-structure archetype for military-grade fixed installations. CTI Systems S.à r.l. and NIJL Aircraft Docking occupy positions within the European precision tier, with the former representing electromechanical platform specialization and the latter anchoring retrofit engineering capabilities for legacy hangar conversions.
| Leading Market Players |
|---|
| Kern Steel Fabrication, Inc. |
| SEMMCO |
| CTI Systems S.à r.l. |
| SICK AG |
| Metaltech |
| NIJL Aircraft Docking |
| Altech |
| ZARGES GMBH |
| KAWASAKI HEAVY INDUSTRIES, LTD. |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp freight corridors govern landed costs for German electromechanical components entering North American MRO facilities, concentrating pricing power among Bavarian servo-drive manufacturers while forcing US-based steel fabricators to absorb volatile alloy surcharges through fixed military contracts.
Pricing Analysis
Long-term offtake agreements dominate procurement for fixed military installations, while spot purchasing prevails for mobile platform retrofits. Price differentiation rests on EASA CS-25 certification tier and after-sales service bundling intensity. Cost compression in electromechanical subsystems intensifies as airlines unbundle maintenance contracts from hardware procurement. Regional MRO providers exhibit highest price sensitivity; Lufthansa Technik and Delta TechOps accept premium positioning for programmable automation.
Supply Chain Analysis
Tariff exposure between Germany and the United States dominates supply chain risk planning for precision servo motors and linear actuators. Manufacturing concentrates in Germany, China, and Japan, with East Asian supply chains anchoring critical drive component fabrication. Raw material dependencies span high-grade structural steel, specialized hydraulic fluids, and rare-earth magnet alloys. Distribution runs through OEM-direct channels for military contracts and third-party MRO integrators for commercial airline procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts now expand faster than original equipment fabrication, with lifecycle maintenance agreements capturing recurring revenue streams previously retained by platform manufacturers.
For Market Incumbents: Harden certification reciprocity across FAA-EASA jurisdictions to defend against emerging Asian automation specialists. Anchor backward integration into servo motor supply through captive Bavarian manufacturing corridors. Deepen vertical control over retrofit engineering capabilities as airlines accelerate fleet diversification toward composite wide-bodies. For New Entrants and Emerging Players: India's PLI-subsidized MRO infrastructure buildout represents the most penetrable entry point for modular mobile platform specialists. Regional maintenance facilities in Delhi-NCR and Bangalore seek portable configurations compatible with A320 and 737 overnight turnaround windows. Partner with domestic steel fabricators to bypass established German supply chain gatekeepers. For Investors and Strategic Acquirers: EASA F-Gas Regulation compliance deadlines reshape the acquisition landscape toward hydraulic-electromechanical hybrid specialists with biodegradable fluid certification. Long-term viability favors platform manufacturers with captive after-sales service networks. Monitor FAA airworthiness directive issuance frequency as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Unbundling | Separates maintenance pricing from hardware procurement, concentrating recurring revenue with third-party providers at Delta TechOps and Lufthansa Technik. |
| Hybrid Platform Development | Combines hydraulic power density with electromechanical precision to address 60-ton load thresholds for A350 and 787 maintenance. |
| Retrofit Engineering Expansion | Converts legacy fixed installations for multi-aircraft compatibility, opening recurring revenue as airlines diversify fleet compositions. |
| Certification Reciprocity Investment | Accelerates FAA-EASA dual approval timelines, compressing 14-18 month structural recertification cycles for system upgrades. |
| Biodegradable Fluid Transition | Reformulates hydraulic circuits to meet EASA F-Gas restrictions, forcing capital replacement across European Union maintenance facilities. |
Methodological Framework
The analysis maps fixed, mobile, portable, and automated platform sub-sectors, each validated through maintenance directors, MRO procurement leads, aftermarket service heads, and regulatory compliance officers at FAA and EASA. Primary interviews triangulate against customs trade data, SEC filings from aerospace conglomerates, EASA certification databases, and military procurement disclosures. Bottom-up equipment unit analysis and top-down MRO spending allocation confirm value estimates.
Assumptions held fixed include FAA-EASA regulatory reciprocity frameworks and structural steel alloy availability; variables tested include airline fleet diversification rates and electromechanical component lead time volatility. The projection horizon spans product type, technology, end user, and installation type dimensions, with CAGRs derived from equipment replacement cycle analysis and MRO infrastructure investment patterns. Forecast inputs incorporate airworthiness directive issuance rates and PLI scheme subsidy trajectories.
Stress conditions across hydraulic fluid regulatory bans, rare-earth supply disruptions, and military procurement budget shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions without guarantee of realization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aircraft Braking System Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Commercial Parachute Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market