

Photoluminescent Aircraft Rescue Marking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Photoluminescent Aircraft Rescue Marking Systems Market Insights
Strontium aluminate-grade luminance performance is bifurcating the competitive landscape between legacy zinc sulfide suppliers and next-generation material specialists. Boeing leverages its OEM integration channels to specify photoluminescent standards across new aircraft programs. Honeywell International anchors the aftermarket retrofit segment through its aviation safety distribution network. STG Aerospace specializes in narrow-body cabin configurations, occupying a distinct niche in European carrier fleets.
Photoluminescent aircraft rescue marking systems employ strontium aluminate-doped substrates that absorb ambient light and emit visible illumination for extended durations without electrical power, providing critical wayfinding guidance during cabin blackouts or airfield emergencies. These systems integrate phosphorescent pigments into adhesive films or rigid panels, manufactured through precision coating processes that control particle dispersion density to meet minimum luminance thresholds under ISO 17398 and aviation-specific photometric standards. Exit signs and path markers represent the most mature product categories, with margin pools concentrating in custom symbolic markers tailored to carrier-specific cabin layouts. Strontium aluminate technology leads growth trajectory due to its tenfold luminance duration advantage over zinc sulfide precursors, while rare earth doped formulations command premium positioning for military and VIP aircraft applications.
FAA airworthiness directives and EASA certification specifications for emergency evacuation visibility shape baseline product requirements, with China's CAAC adopting harmonized photoluminescent intensity standards for imported aircraft. The EU AI Act and CSRD reporting obligations are beginning to influence supplier environmental disclosures for pigment sourcing and film substrate recyclability. Stakeholders must monitor divergence between FAA luminescence decay curves and emerging CAAC testing protocols, as regulatory misalignment could fragment certification costs and complicate fleet standardization strategies for multinational operators.
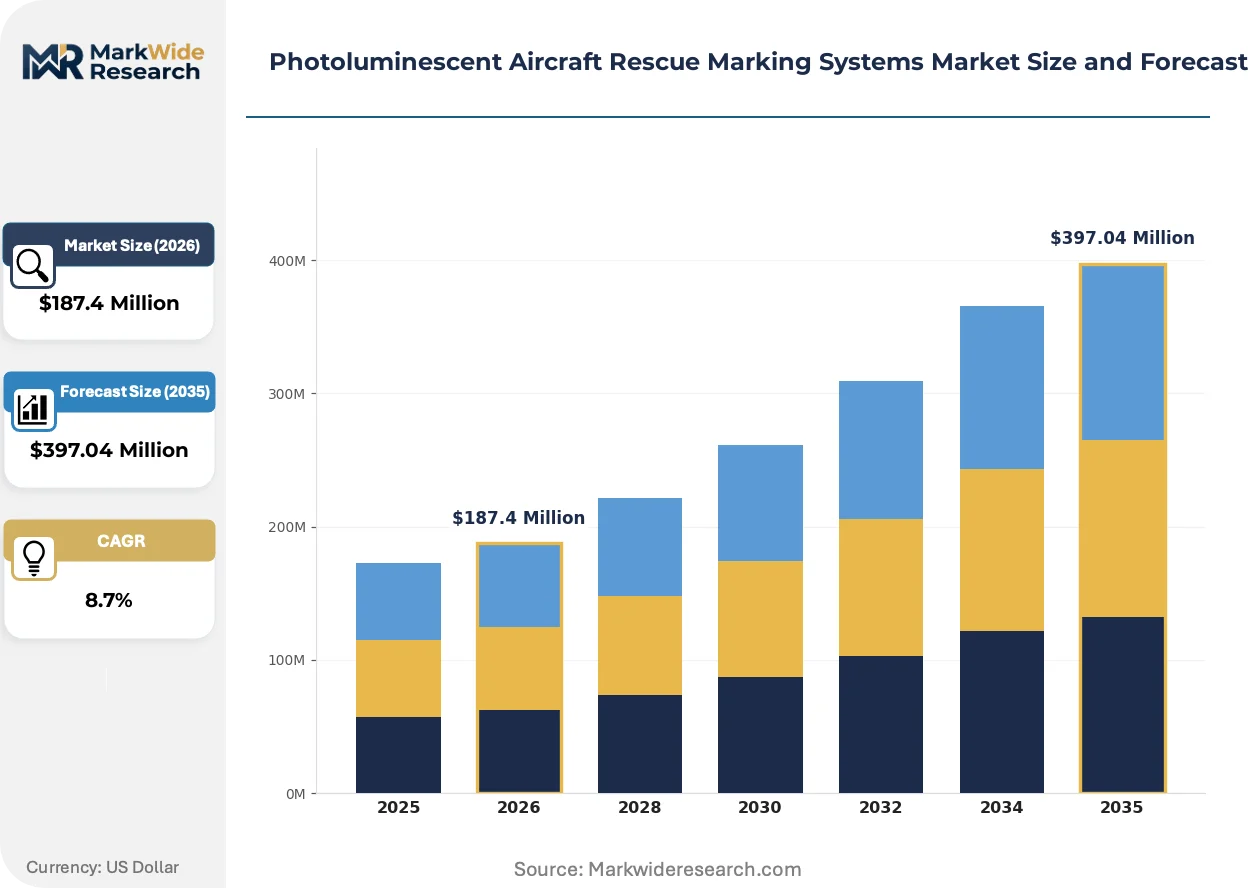
Market Dynamics
Strontium aluminate luminance superiority is decomposing legacy zinc sulfide supply relationships while FAA-EASA regulatory harmonization forces simultaneous recertification investments across multinational fleet operators.
Growth Catalysts
- FAA Airworthiness Directives:Mandated emergency evacuation visibility standards for narrow-body retrofits are pulling strontium aluminate installations through Boeing and Airbus aftermarket channels.
- China CAAC Harmonization:Imported aircraft photoluminescent intensity protocols are aligning with EASA CS-25 specifications, eliminating dual-certification barriers for European suppliers entering Chinese assembly lines.
- Strontium Aluminate Tenfold Duration Advantage:Extended luminance performance without electrical backup is displacing zinc sulfide in exit sign applications across Asia-Pacific commercial aviation procurement.
Market Restraints
- Rare Earth Input Volatility:Europium and dysprosium doping materials for military-grade formulations face concentrated supply from Chinese processing facilities.
- CAAC-FAA Testing Protocol Divergence:Luminescence decay curve measurement methodologies are creating fragmented certification costs for multinational operators standardizing fleet configurations.
- LED Emergency Lighting Substitution:Battery-backed electroluminescent systems are capturing budget-constrained regional carrier retrofit contracts in emerging aviation markets.
Strategic Opportunities
- India UDAN Regional Connectivity:Turboprop fleet expansion under the government's airport development scheme is creating first-mover advantage for photoluminescent cabin specification in new ATR and Bombardier deliveries.
- EU CSRD Environmental Disclosure:Pigment sourcing transparency requirements are rewarding suppliers with verified strontium aluminate supply chain documentation and recyclable film substrate capabilities.
- Military-VIP Rare Earth Formulations:Dysprosium-doped premium segments are opening adjacent demand from defense contractor cabin integrators seeking extended-duration blackout performance.
Industry Challenges
- ISO 17398 Photometric Calibration Talent Scarcity:Precision coating process engineers with particle dispersion density expertise are concentrated among legacy aerospace adhesive manufacturers.
- FAA-EASA Simultaneous Certification Timelines:Dual-track approval processes for custom symbolic markers are extending product launch cycles by eight to fourteen months for carrier-specific cabin layouts.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoluminescent Aircraft Rescue Marking Systems Market Trends and Innovations
Material science advances and regulatory disclosure mandates are restructuring supplier qualification criteria while procurement centralization among lessors is compressing vendor selection cycles.
Strontium aluminate-doped phosphorescent pigments are decomposing established zinc sulfide supply relationships through tenfold luminance duration extension. Narrow-body fleet operators are specifying these substrates for new aircraft deliveries and mid-life cabin reconfigurations. The technology is decomposing legacy coating equipment investments and forcing precision dispersion density control capabilities among adhesive film manufacturers.
EASA CSRD reporting obligations are mandating environmental disclosure for pigment sourcing and film substrate recyclability across European carrier supply chains. Suppliers must document strontium aluminate extraction provenance and end-of-life panel recovery pathways to maintain preferred vendor status. Narrow-body retrofit programs are most affected, with procurement teams embedding sustainability verification into technical evaluation scorecards.
Airline procurement consolidation through operating lessors is compressing vendor qualification cycles and unbundling after-sales service from hardware contracts. STG Aerospace and Honeywell International are responding with certified installer network partnerships rather than direct field service deployment. Asia-Pacific lessor concentration in Singapore and Dublin is driving this behavioral shift most visibly, with technical specification authority migrating from national carriers to cross-border asset managers.
Photoluminescent Aircraft Rescue Marking Systems Market Segmentation
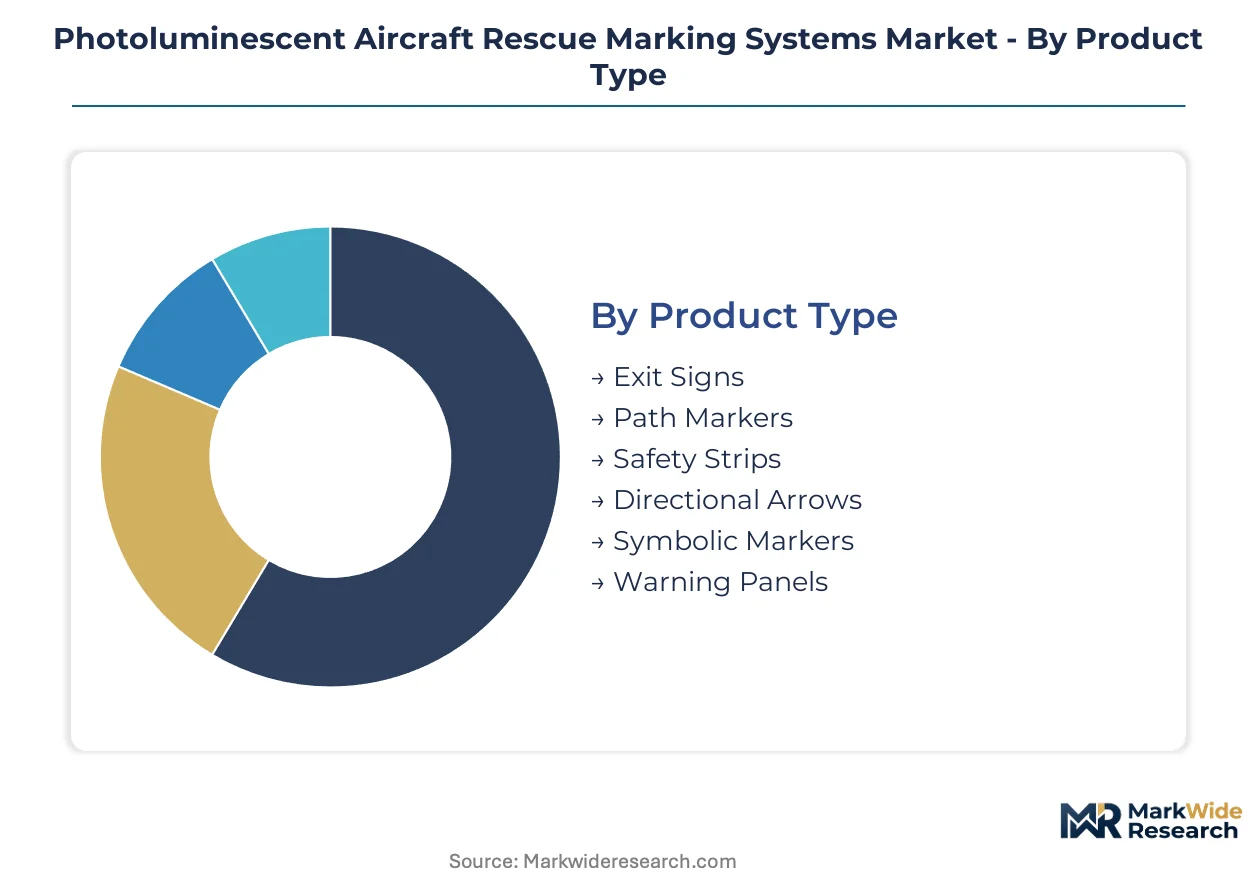
Photoluminescent aircraft rescue marking systems fragment across multiple technical and operational dimensions that determine procurement priorities. Product specifications, substrate chemistry, installation environment, and contracting authority each create distinct margin pools and certification requirements.
Product Type:
Exit signs and path markers face the strongest substitution pressure from LED emergency lighting systems in budget-constrained retrofit programs.
- Exit Signs:Strontium aluminate-doped rigid panels meeting FAA luminance decay curves dominate narrow-body new-build specifications. Boeing and Airbus assembly lines in Renton and Toulouse anchor procurement volume for these high-visibility cabin installations.
- Path Markers:Phosphorescent adhesive films with controlled particle dispersion density provide floor-level wayfinding during electrical failures. Asia-Pacific carrier fleet expansions in India and Vietnam concentrate retrofit demand for these lower-cost cabin configurations.
- Safety Strips:Photoluminescent edge marking for stair treads and seat tracks.
- Directional Arrows:Standardized evacuation flow indicators for bulkhead and galley zones.
- Symbolic Markers:Carrier-specific custom graphics requiring extended FAA-EASA dual certification timelines.
- Warning Panels:High-visibility hazard demarcation for maintenance and cargo areas.
Exit signs anchor the volume base while symbolic markers gain share at the steepest rate.
Technology:
Cost tier stratification separates premium rare earth formulations from commodity zinc sulfide in procurement evaluation scorecards.
- Zinc Sulfide:Legacy phosphorescent substrate with limited luminance duration constrains adoption to non-critical marking applications. Regional turboprop operators in Southeast Asia specify these materials for cost-driven cabin retrofits where electrical backup systems remain primary.
- Strontium Aluminate:Next-generation substrate delivering tenfold luminance extension without power input. EASA CS-25 alignment with China's CAAC protocols is eliminating dual-certification barriers for European suppliers entering Chinese assembly lines.
- Rare Earth Doped:Dysprosium and europium formulations for military-grade extended blackout performance.
- Europium Activated:Premium pigment systems for VIP and head-of-state aircraft configurations.
- Phosphorescent Pigments:Raw material inputs for in-house coating operations by adhesive film manufacturers.
- Glow-in-the-Dark Films:Flexible substrate options for curved surface applications and temporary installations.
Strontium aluminate commands the dominant revenue share while rare earth doped formulations expand most quickly in adjacent defense segments.
Application:
Customer type concentration among lessors is compressing vendor selection cycles across all installation environments.
- Airfield Runways:High-intensity pavement markings for taxiway and apron edge delineation. ICAO Annex 14 visibility standards drive procurement from airport authorities in Dubai, Singapore, and Denver.
- Aircraft Cabins:Interior wayfinding systems for passenger evacuation during electrical failures. Narrow-body fleet standardization by Dublin and Singapore-based lessors is consolidating specification authority.
- Evacuation Routes:Continuous marking systems for terminal and concourse egress paths.
- Emergency Exits:Door surround illumination for rapid location during smoke conditions.
- Maintenance Hangars:Hazard demarcation for elevated work platforms and fueling zones.
- Control Towers:Stairwell and egress marking for critical infrastructure facilities.
Aircraft cabins generate the largest absolute volume while airfield runways show the steepest expansion trajectory in greenfield airport development.
End User:
Supply concentration among precision coating specialists is constraining qualification pathways for emerging adhesive film manufacturers.
- Airport Authorities:Public procurement entities specifying photoluminescent intensity standards for terminal and airfield infrastructure. India's Airports Authority procurement under UDAN regional connectivity schemes is creating specification opportunities for new ATR and Bombardier deliveries.
- Aircraft Manufacturers:OEM integration channels through Boeing and Airbus new-build programs. STG Aerospace and Honeywell International compete for narrow-body and wide-body platform specification.
- Emergency Responders:Fire and rescue services requiring high-visibility marking for rapid airfield navigation.
- Ground Handling Services:Safety marking for cargo facilities and aircraft servicing zones.
- Aviation Regulators:FAA, EASA, and CAAC certification bodies establishing photometric testing protocols.
- Safety Inspectors:Compliance verification personnel driving aftermarket replacement demand.
Aircraft manufacturers anchor the volume base while airport authorities gain procurement share fastest in Asia-Pacific greenfield development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Strontium aluminate coating specialists cluster in Germany, the United States, China, and Japan, with certification laboratories and precision adhesive manufacturers co-locating near major aerospace assembly hubs. FAA-EASA harmonization pressures are forcing dual-track approval investments across multinational supply chains.
United States
Boeing's Renton and Charleston assembly lines anchor North American demand for strontium aluminate exit sign specifications. FAA airworthiness directives for narrow-body evacuation visibility standards are pulling aftermarket retrofits through Honeywell's aviation distribution network. Denver International Airport's airfield marking procurement exemplifies airport authority adoption of high-intensity pavement delineation systems.
Germany
EASA CSRD reporting obligations are mandating environmental disclosure for pigment sourcing across European carrier supply chains. REACH compliance for strontium aluminate extraction provenance documentation is reshaping supplier qualification criteria. STG Aerospace's positioning within narrow-body cabin configurations concentrates procurement specification activity in Hamburg and Toulouse assembly corridors.
China
CAAC photoluminescent intensity standards for imported aircraft are harmonizing with EASA CS-25 specifications, eliminating dual-certification barriers for European suppliers. Strontium processing concentration in Chinese facilities creates input cost leverage for domestic coating manufacturers. COMAC's Shanghai assembly operations are embedding photoluminescent standards into indigenous narrow-body programs.
India
UDAN regional connectivity schemes are driving turboprop fleet expansion with first-mover photoluminescent cabin specifications for ATR and Bombardier deliveries. The Airports Authority of India's procurement under greenfield airport development is creating specification opportunities for airfield runway marking systems. Bengaluru and Hyderabad aviation clusters are emerging as maintenance, repair, and overhaul hubs for retrofit demand.
Japan
METI industrial standards for emergency evacuation visibility are aligning with ISO 17398 photometric calibration requirements. Precision coating process engineering talent concentrates among legacy aerospace adhesive manufacturers in the Nagoya aerospace corridor. ANA and JAL fleet standardization strategies are compressing vendor selection cycles for narrow-body configurations.
Photoluminescent Aircraft Rescue Marking Systems Market Competitive Landscape
Concentration sits with diversified aerospace conglomerates and specialized cabin safety suppliers rather than pure-play material manufacturers. Boeing and Airbus leverage OEM integration channels to specify photoluminescent standards across new aircraft programs, while aftermarket retrofit demand fragments across aviation safety distributors. Two strategic archetypes dominate: integrated airframe manufacturers with captive specification authority, and independent cabin safety specialists with narrow-body configuration expertise. Competitive moves center on certification network partnerships and sustainability documentation capabilities for CSRD-aligned procurement.
Within the integrated aerospace tier, Boeing and Airbus represent specification gatekeepers through new-build program authority. Honeywell International anchors aftermarket distribution reach through aviation safety networks spanning operator maintenance programs. STG Aerospace occupies a distinct position among cabin configuration specialists, with narrow-body expertise concentrated in European carrier fleets. These three entities exemplify the bifurcation between OEM-integrated specification control and independent retrofit channel access.
| Leading Market Players |
|---|
| Boeing |
| Airbus |
| Honeywell International |
| 3M |
| Lufthansa Technik |
| STG Aerospace |
| Safran |
| Collins Aerospace |
| Oxley Group |
| Others |
Pricing and Supply Chain Analysis
Strontium aluminate coating capacity utilization above eighty percent in German and Japanese precision adhesive facilities is compressing marginal cost curves and elevating price floors for narrow-body retrofit specifications. This scale concentration simultaneously limits supplier qualification pathways for emerging coating specialists and amplifies procurement leverage among Boeing and Airbus assembly line integrators.
Pricing Analysis
FAA luminance decay curve mandates dictate the pricing tier structure across commercial aviation procurement, with EASA CS-25 certification alignment commanding fifteen-to-twenty percent premiums over baseline CAAC-acceptable formulations. Price differentiation rests on dual-certification status and strontium aluminate particle dispersion density grades, with ISO 17398 photometric calibration tiers separating premium military-grade rare earth formulations from commodity cabin configurations. Cost compression in zinc sulfide legacy tiers is intensifying because LED emergency lighting substitution captures budget-constrained regional carrier contracts. Regional turboprop operators in Southeast Asia exhibit the highest price sensitivity, while defense contractor cabin integrators demonstrate minimal elasticity for dysprosium-doped extended blackout performance.
Supply Chain Analysis
Container availability constraints across Shanghai-Rotterdam and Yokohama-Long Beach trade lanes are extending inbound logistics lead times for strontium aluminate raw material shipments. Geographic supply concentration centers on China for strontium carbonate processing, Germany for precision coating equipment manufacturing, and Japan for phosphorescent pigment formulation expertise. Raw material dependencies draw from Australian strontium ore deposits, Chinese rare earth separation facilities for europium and dysprosium doping agents, and South Korean film substrate production. Single-source vulnerability concentrates in Chinese rare earth processing capacity, where export permit volatility threatens military-grade formulation continuity. Distribution runs through Honeywell aviation safety networks and STG Aerospace certified installer partnerships rather than direct manufacturer field service deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoluminescent aircraft rescue marking systems incumbents face substitution defense imperatives against LED emergency lighting capture of budget-constrained retrofit segments. Battery-backed electroluminescent systems threaten to commoditize the lower tier of cabin wayfinding procurement unless material science differentiation intensifies.
For Market Incumbents: Secure backward integration into strontium aluminate extraction provenance documentation to satisfy EU CSRD environmental disclosure mandates and defend preferred vendor status among European carrier procurement teams. Lock in exclusive certification network partnerships with Dublin and Singapore-based lessors to compress competitor vendor qualification cycles. Anchor defensive positioning against LED substitution by emphasizing tenfold luminance duration advantage in narrow-body new-build specifications at Boeing and Airbus assembly lines. For New Entrants and Emerging Players: Anchor in India's UDAN regional connectivity turboprop fleet expansion, where first-mover photoluminescent cabin specifications for ATR and Bombardier deliveries remain underpenetrated by established European suppliers. Target Airports Authority of India procurement under greenfield airport development for airfield runway marking systems, leveraging CAAC-EASA harmonization to bypass dual-certification cost barriers. Pursue certified installer network partnerships rather than direct field service deployment to align with lessor-driven procurement centralization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision coating specialists with particle dispersion density expertise and existing FAA-EASA dual certification infrastructure. Long-term viability rests on material science differentiation sustaining pricing power against LED substitution across the five-to-ten year technology refresh window. Acquisition target archetypes include narrow-body cabin configuration specialists with STG Aerospace-like positioning and verified strontium aluminate supply chain documentation capabilities. The signal to watch is divergence between FAA luminescence decay curve standards and emerging CAAC testing protocols, which would fragment certification costs and compress multinational operator fleet standardization strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strontium Provenance Documentation | EU CSRD compliance secures preferred vendor status among European carrier procurement teams. |
| Dual Certification Infrastructure Investment | Simultaneous FAA-EASA approval capability eliminates eight-to-fourteen month launch cycle extensions. |
| Certified Installer Network Partnerships | Aligns with Singapore and Dublin lessor procurement centralization compressing vendor selection cycles. |
| Rare Earth Doping Formulation Expansion | Dysprosium-europium premium tiers open adjacent defense contractor and VIP aircraft demand. |
| CAAC Harmonization Compliance Program | Eliminates dual-certification barriers for European suppliers entering Chinese assembly lines. |
Research Methodology
Desk research of FAA airworthiness directive filings, EASA certification specification databases, and CAAC imported aircraft standards preceded structured interviews with aircraft manufacturer procurement directors, aviation safety distributor channel managers, and airport authority specification engineers. Primary fieldwork with precision coating process engineers and adhesive film manufacturing technical directors validated secondary data on strontium aluminate particle dispersion density capabilities. Trade flow analysis of strontium carbonate and rare earth doping agent shipments supplemented customs data from German, Japanese, and Chinese export authorities. Bottom-up segment sizing across exit signs, path markers, and symbolic marker product categories triangulated against top-down aviation fleet expansion projections.
Variance decomposition across technology substitution scenarios, regulatory harmonization timelines, and raw material input volatility shaped the analytical framework. Segmentation dimensions modeled include product type, substrate chemistry tier, installation environment, and contracting authority archetype, with regional regulatory cluster differentiation capturing FAA-EASA-CAAC protocol alignment or divergence. CAGRs were derived from installed base replacement cycles, new aircraft delivery schedules, and retrofit penetration assumptions. Industry-specific forecast inputs incorporated Boeing and Airbus narrow-body production rate disclosures and UDAN regional connectivity scheme turboprop fleet expansion targets.
Decision-makers should treat outputs as directional under base assumptions of sustained FAA-EASA regulatory harmonization and stable Chinese rare earth processing capacity; material deviation would warrant model refresh. Specific risk factors include LED emergency lighting substitution acceleration, CAAC-FAA testing protocol divergence, and strontium aluminate input cost volatility from concentrated Chinese processing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.