
 Aircraft Ejection Seats Market | 2026-2036
Aircraft Ejection Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Ejection Seats Market Intelligence
Aerospace metallurgy and pyrotechnics expertise is redrawing competitive boundaries in the aircraft ejection seats sector. Martin-Baker Aircraft Company Limited leverages decades of British engineering heritage to dominate Western military procurement channels. NPP Zvezda anchors Eastern military supply chains with Russian-designed systems optimized for extreme-climate operations. Collins Aerospace sustains its position through integrated avionics-seat architectures that reduce platform integration cycles for prime contractors.
Aircraft ejection seats are pilot-survivability systems combining ballistic catapults, rocket motors, and parachute deployment mechanisms engineered to extract aircrew from disabled platforms at altitudes ranging from ground level to 50,000 feet and speeds exceeding 600 knots. These systems serve exclusively life-preservation functions across military and select experimental aviation applications. Rocket-powered configurations command premium positioning due to their zero-zero capability envelope, while fixed-wing deployment categories generate the dominant revenue share given fighter and trainer fleet densities. Hybrid technology segments are gaining structural traction as platforms demand multi-mode extraction sequencing adaptable to rotary-wing and high-speed jet profiles.
FAA airworthiness directives and EASA certification standards shape product development timelines and testing expenditure burdens for manufacturers seeking platform integration contracts. MIL-STD-810 environmental testing protocols and ISO 9001 quality management requirements further constrain supplier qualification, filtering out smaller competitors lacking capital-intensive validation infrastructure. Stakeholders must monitor evolving automatic ejection technology standards and next-generation aircraft platform specifications to align R&D roadmaps with procurement cycles.
Market Dynamics
The aircraft ejection seats sector is undergoing a fundamental recalibration as zero-zero capability requirements and automatic ejection sequencing redefine platform integration standards across next-generation combat aircraft programs.
Growth Catalysts
- Zero-Zero Technology Mandates:Fighter modernization programs in the United States and United Kingdom are mandating rocket-powered extraction systems capable of ground-level ejection at zero airspeed, expanding upgrade cycles across legacy fleets.
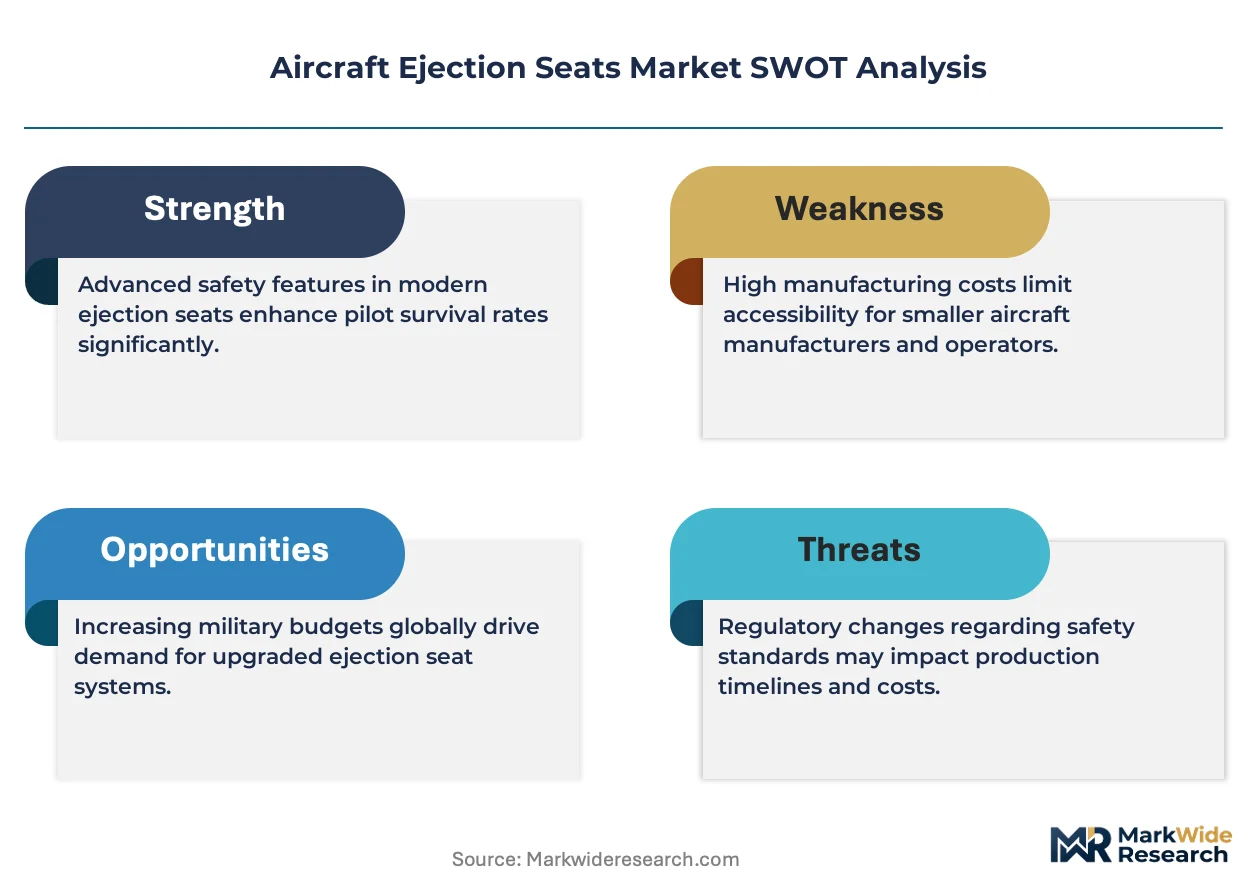
- FAA Airworthiness Directives:Stricter certification protocols for experimental and trainer aircraft categories are elevating minimum safety thresholds and forcing platform integrators toward certified seat architectures.
- NATO Procurement Consolidation:Coordinated multi-national fighter acquisition frameworks are standardizing ejection seat specifications across member air forces, reducing qualification duplication and accelerating volume commitments.
Market Restraints
- Pyrotechnic Input Volatility:Solid rocket propellant precursor chemicals face concentrated supply from limited specialty chemical producers, exposing seat manufacturers to input cost swings and allocation risk.
- Eastern Supply Chain Concentration:NPP Zvezda's dominance across Russian and allied military aviation creates parallel procurement blocs that fragment interoperability standards and limit cross-platform seat exchangeability.
- MIL-STD-810 Testing Burden:Environmental validation protocols require multi-million-dollar climatic chamber infrastructure that filters smaller competitors from prime contractor qualification pools.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme and domestic procurement preferences are creating openings for joint-venture seat production to serve indigenous fighter programs and regional export markets.
- Automatic Ejection Convergence:Integration of sensor-fused aircraft health monitoring with seat firing logic is enabling hands-free extraction protocols for unmanned wingman and loyalist wingman platforms.
- Rotary-Wing Adaptation:Hybrid rocket-catapult architectures are penetrating helicopter crew survivability applications previously served by passive restraint systems alone.
Industry Challenges
- Aerospace Pyrotechnics Talent Scarcity:The specialized knowledge base combining ballistic engineering, ordnance safety, and avionics integration is contracting as experienced cohorts retire without sufficient pipeline replacement.
- Platform-Specific Certification Timelines:Each aircraft integration requires unique seat-track geometry validation, delaying revenue recognition across multi-year development cycles and compressing program margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Ejection Seats Market |
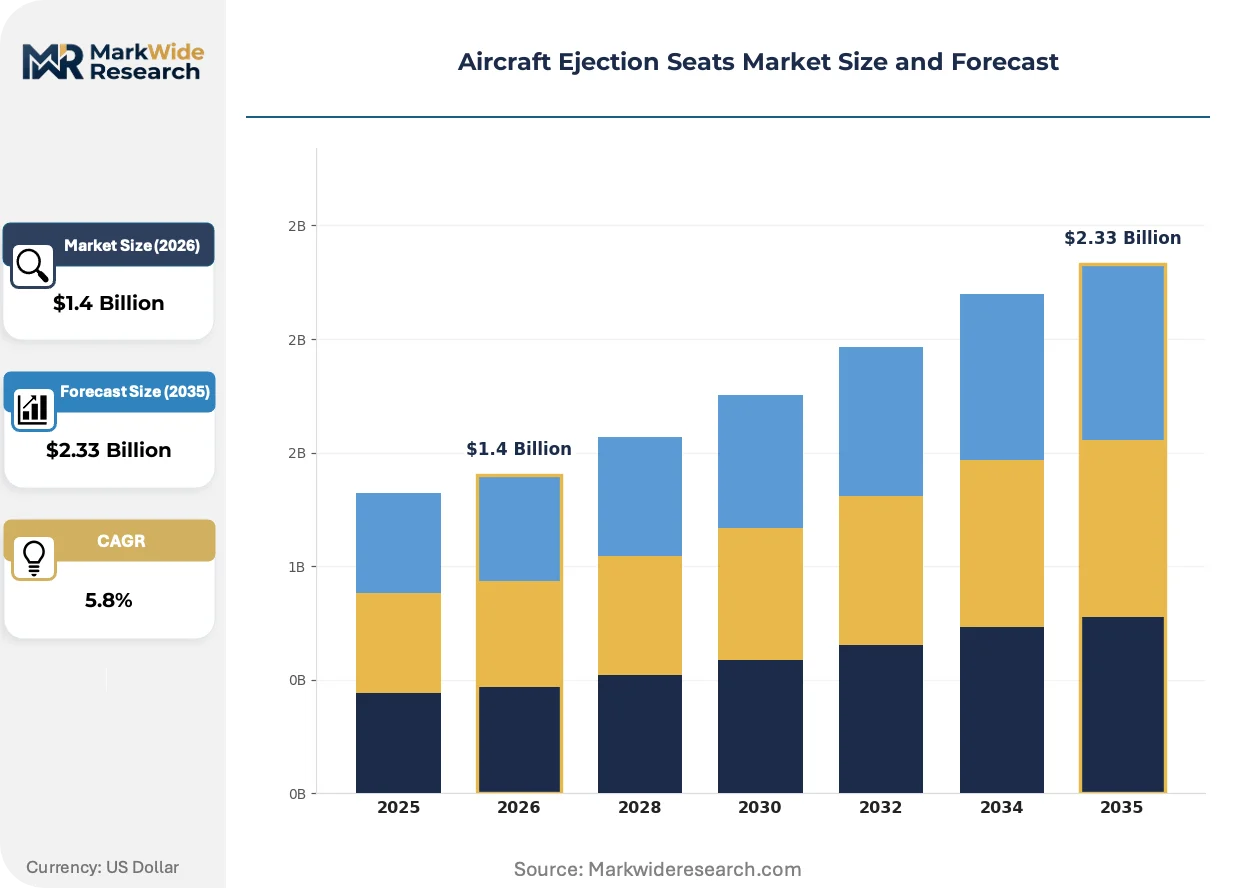
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Pneumatic, Rocket-Powered, Hybrid End User: Military, Commercial Aviation, Private Aviation, Aerospace Research Deployment: Fixed-Wing Aircraft, Rotary-Wing Aircraft, Experimental Aircraft, Trainer Aircraft Technology: Zero-Zero Ejection, Manual Ejection, Automatic Ejection, Vertical Ejection |
| Companies Covered | Martin-Baker Aircraft Company Limited, Collins Aerospace, NPP Zvezda, AVIC, PacSci EMC, RUAG Aviation, Safran SA, EDM Limited, RLC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Ejection Seats Market Strategic Shifts & Innovations
Active developments across propulsion architecture, regulatory harmonization, and procurement methodology are compressing product lifecycles and reshaping vendor-customer relationships in pilot-survivability systems.
Smart ejection sequencing technology is fragmenting traditional single-mode extraction paradigms. Multi-axis accelerometer arrays now modulate rocket thrust profiles in real-time, adapting seat trajectory to aircraft attitude and airspeed. Fighter programs in Sweden and South Korea are embedding these architectures into their next-generation platforms. The technology is fragmenting procurement patterns as air forces abandon legacy seat categories in favor of modular, software-defined extraction systems.
REACH chemical substance restrictions are forcing reformulation of heritage pyrotechnic compositions across European supply chains. The regulation's Substances of Very High Concern list now captures several legacy initiator compounds, compelling manufacturers to validate alternative energetic materials through full recertification protocols. German and French airworthiness authorities are coordinating accelerated approval pathways, though testing backlogs are extending platform integration timelines by eighteen to twenty-four months.
Life-cycle service contracting is displacing transactional seat procurement across NATO operator budgets. Danish and Norwegian defense ministries now contract for guaranteed availability per flight-hour rather than capital equipment purchase, transferring obsolescence risk and upgrade responsibility to seat manufacturers. This model concentrates vendor relationships around incumbents with established logistics networks and compresses opportunities for new market entrants lacking integrated support infrastructure.
Aircraft Ejection Seats Market Segmentation
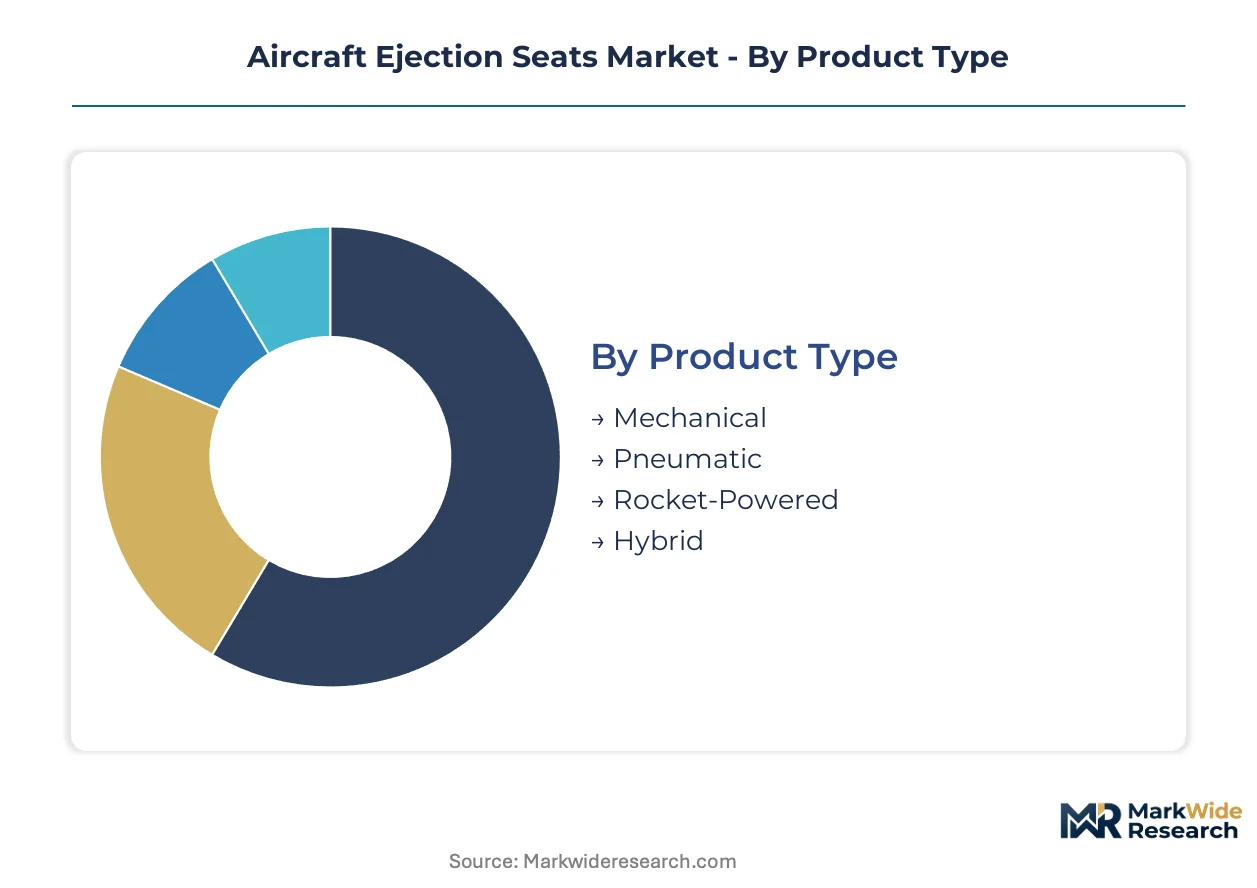
Ejection seat procurement decisions pivot on platform-specific extraction envelopes and certification requirements. Manufacturers configure product portfolios across four intersecting dimensions that determine qualification timelines and contract values.
Product Type:
Rocket-powered configurations command premium positioning due to zero-zero capability requirements in modern fighter programs, while mechanical systems retain cost-sensitive trainer applications.
- Rocket-Powered:Solid-fuel rocket motors generate thrust profiles enabling ground-level ejection at zero airspeed. United States F-35 and United Kingdom Tempest programs mandate these systems, driving upgrade cycles across NATO legacy fleets.
- Hybrid:Dual-mode architectures combine ballistic catapults with variable-thrust rockets for multi-platform adaptability. South Korea KF-21 and Sweden Gripen E integrations favor this flexibility for rotary-wing and high-speed jet profiles.
- Mechanical:Spring-loaded or compressed-gas systems serve basic trainer aircraft with limited altitude-speed envelopes.
- Pneumatic:Compressed-air extraction mechanisms occupy niche experimental aviation applications with moderate ejection frequency requirements.
The dominant share belongs to Rocket-Powered, while Hybrid is closing the gap fastest.
End User:
Military procurement channels generate nearly all revenue volume through sovereign defense budgets and alliance framework agreements.
- Military:Fighter, bomber, and trainer fleets across United States Air Force, Royal Air Force, and allied services drive specification standards. Department of Defense modernization budgets prioritize pilot survivability systems with automatic ejection sequencing for next-generation platforms.
- Aerospace Research:Experimental test programs at NASA Armstrong Flight Research Center and similar facilities require specialized seats for envelope-expansion flights. High-profile incidents accelerate replacement cycles and technology validation budgets.
- Commercial Aviation:No current civil certification pathway exists for passenger ejection systems.
- Private Aviation:Experimental and homebuilt aircraft categories occasionally incorporate seats under FAA Special Airworthiness Certificate limitations.
Military procurement maintains overwhelming volume concentration, though Aerospace Research contracts carry disproportionate margin contribution.
Deployment:
Fixed-wing platforms absorb the majority of engineering qualification hours due to diverse airframe geometries and seat-track configurations.
- Fixed-Wing Aircraft:Fighter and trainer fleet densities across United States, United Kingdom, and allied air forces generate structural demand. Each platform integration requires unique seat-track geometry validation, compressing program margins across multi-year development cycles.
- Rotary-Wing Aircraft:Helicopter crew survivability applications are penetrating previously passive-restraint segments. Hybrid rocket-catapult architectures address autorotation and low-altitude extraction scenarios that defeat traditional ballistic systems.
- Trainer Aircraft:High-volume, lower-specification seats for pilot instruction fleets emphasize cost containment over advanced capability envelopes.
- Experimental Aircraft:One-off integrations for prototype platforms demand extensive custom engineering with limited production scale.
Fixed-Wing Aircraft retains the dominant procurement volume, while Rotary-Wing Aircraft is expanding most quickly as helicopter operators adopt crew extraction capabilities.
Technology:
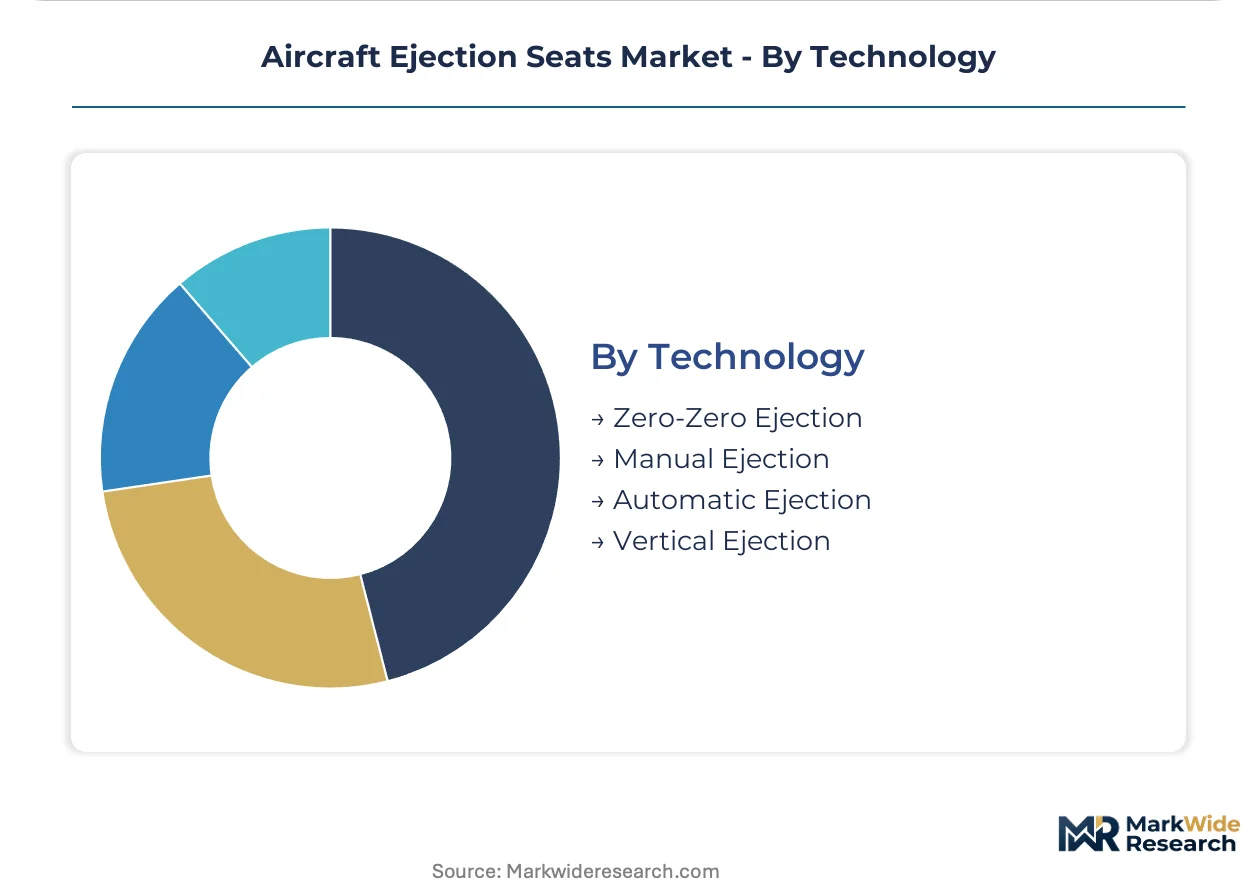
Automatic ejection sequencing is fragmenting traditional manual-firing paradigms through sensor-fused aircraft health monitoring integration.
- Zero-Zero Ejection:Ground-level, zero-airspeed capability has become mandatory for United States and United Kingdom fighter modernization programs. Rocket-powered propulsion architectures enable this envelope, elevating minimum safety thresholds across NATO procurement specifications.
- Automatic Ejection:Hands-free extraction protocols integrate airframe sensor arrays with seat firing logic. Unmanned wingman and loyalist wingman platforms require this technology for crew preservation without pilot intervention.
- Manual Ejection:Pilot-initiated firing handles retain dominance in trainer and legacy fighter fleets with established human-factors certification.
- Vertical Ejection:Upward-only trajectory systems serve specific helicopter and VTOL applications with constrained lateral clearance envelopes.
Zero-Zero Ejection holds the established standard position, while Automatic Ejection is gaining structural traction fastest through next-generation platform specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procurement channels favor zero-zero rocket-powered systems for next-generation fighter programs, while United Kingdom and Indian operators prioritize hybrid architectures for multi-platform fleet commonality, creating divergent specification standards across NATO and non-aligned defense frameworks.
United States
Department of Defense modernization budgets channel sustained investment into pilot survivability systems across F-35 and trainer fleets. FAA airworthiness directives for experimental aircraft categories elevate minimum safety thresholds for seat integration contracts. The aerospace industrial cluster around Fort Worth, Texas concentrates platform integration activity for next-generation combat aircraft programs.
United Kingdom
Royal Air Force Tempest program specifications mandate zero-zero capability envelopes for future fighter procurement. EASA certification standards shape product development timelines for manufacturers seeking platform integration contracts. The engineering heritage concentrated around London and the South East sustains specialized pyrotechnics and metallurgy capabilities for seat production.
Germany
Luftwaffe fighter modernization drives demand for automatic ejection sequencing in next-generation platform specifications. REACH chemical substance restrictions force reformulation of heritage pyrotechnic compositions through full recertification protocols. The Baden-Württemberg aerospace cluster around Munich and Stuttgart hosts climatic chamber infrastructure for MIL-STD-810 environmental validation.
India
Indigenous fighter programs under the country's PLI scheme create openings for joint-venture seat production to serve domestic and regional export markets. DGFT domestic procurement preferences channel defense spending toward local manufacturing partnerships. The Bangalore-Hyderabad aerospace corridor concentrates platform development activity for indigenous combat aircraft integration.
South Korea
KF-21 fighter program specifications favor hybrid rocket-catapult architectures for multi-role adaptability. The country's national defense procurement agency coordinates accelerated qualification pathways for indigenous platform integration. The Sacheon aerospace cluster in the South Gyeongsang region concentrates final assembly and seat-track geometry validation for domestic fighter production.
Aircraft Ejection Seats Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the aircraft ejection seats sector. British and American engineering groups dominate Western military procurement channels through decades of platform integration heritage. Russian-designed systems anchor Eastern supply chains with specialized extreme-climate capabilities. Competitive positioning concentrates around automatic ejection technology licensing and life-cycle service contracting models that transfer obsolescence risk to manufacturers.
Within the integrated tier, Martin-Baker Aircraft Company Limited and Collins Aerospace occupy positions exemplifying heritage British and American engineering approaches to pilot-survivability systems. NPP Zvezda represents the Eastern bloc archetype with specialized supply chain concentration across Russian and allied military aviation. These three anchors illustrate how geographic procurement blocs fragment interoperability standards and limit cross-platform seat exchangeability despite NATO consolidation pressures.
| Leading Market Players |
|---|
| Martin-Baker Aircraft Company Limited |
| Collins Aerospace |
| NPP Zvezda |
| AVIC |
| PacSci EMC |
| RUAG Aviation |
| Safran SA |
| EDM Limited |
| RLC Group |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four-month qualification backlogs for alternative energetic materials concentrate pricing power among incumbent seat manufacturers with established MIL-STD-810 climatic chamber infrastructure, while pyrotechnic input volatility compresses margins for second-tier suppliers lacking long-term offtake agreements with solid rocket propellant precursor producers.
Pricing Analysis
Long-term offtake agreements dominate procurement between prime seat manufacturers and defense ministries, with life-cycle service contracts per flight-hour displacing transactional capital equipment purchases across NATO operator budgets. Price differentiation hinges on certification grade—FAA and EASA airworthiness tiers command substantial premiums over baseline MIL-STD configurations—and vertical integration depth in pyrotechnics manufacturing. Cost compression in mechanical trainer seat segments is intensifying as Eastern European operators prioritize affordability over zero-zero capability envelopes. Aerospace research facilities exhibit lowest price sensitivity due to incident-driven replacement cycles and technology validation mandates.
Supply Chain Analysis
United Kingdom and United States anchor Western ejection seat production through concentrated metallurgy and pyrotechnics expertise around London and Fort Worth industrial clusters. Solid-fuel rocket motors draw from specialty chemical producers in Germany and France, while titanium alloy seat structures source from aerospace forging operations across the transatlantic defense industrial base. Single-source vulnerability in solid rocket propellant precursor chemicals—concentrated among limited specialty chemical producers—creates allocation risk during surge procurement cycles. Distribution runs through prime contractor platform integration channels rather than direct OEM sales, with seat-track geometry validation occurring at final assembly sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense procurement cyclicality—driven by fighter modernization program cadences across NATO member states—positions the market for recovery as multi-year platform specifications crystallize and qualification timelines compress.
For Market Incumbents: Fortify automatic ejection technology licensing positions through patent portfolio expansion in sensor-fused aircraft health monitoring integration, while deepening captive supply of solid rocket propellant precursors to offset Eastern supply chain concentration and pyrotechnic input volatility. Lock in life-cycle service contracting incumbency with guaranteed availability per flight-hour offerings that transfer obsolescence risk from operator budgets. For New Entrants and Emerging Players: Anchor in India's PLI scheme joint-venture opportunities for indigenous fighter program seat production, where DGFT domestic procurement preferences create structural openings absent from saturated Western defense channels. Target rotary-wing adaptation segments—hybrid rocket-catapult architectures for helicopter crew survivability—where penetration remains below fixed-wing saturation levels and qualification pathways are less encumbered by legacy platform integration heritage. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified aerospace conglomerates with underoptimized pilot-survivability divisions lacking standalone automatic ejection technology portfolios. Long-term viability centers on software-defined extraction system architectures with recurring upgrade revenue streams rather than hardware transactional models. Watch for inflection in unmanned wingman platform procurement specifications mandating hands-free ejection protocols as the signal for technology valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Automatic Ejection Technology Licensing | Sensor-fused integration with F-35 and Tempest platform specifications creates recurring royalty streams. |
| Life-Cycle Service Contracting | Per-flight-hour availability models transfer obsolescence risk while locking out competitor substitution. |
| Pyrotechnics Backward Integration | In-house solid rocket propellant production insulates margin from specialty chemical allocation volatility. |
| Rotary-Wing Hybrid Architecture Development | Helicopter crew survivability applications penetrate passive-restraint segments with limited incumbent competition. |
| India Joint-Venture Manufacturing | PLI scheme alignment with DGFT preferences opens indigenous fighter program integration pathways. |
Research Approach
Desk research of FAA airworthiness directive filings, EASA certification standards documentation, and NATO procurement framework agreements preceded structured interviews with platform integration engineers at prime contractors, military procurement officers at defense ministries, pyrotechnics R&D directors, and climatic chamber validation specialists. Primary fieldwork combined with secondary validation through MIL-STD-810 environmental test reports, ISO 9001 quality management audits, and customs trade data for aerospace pyrotechnics components. Bottom-up seat production volume estimates triangulated against top-down defense budget allocation analysis.
Variance decomposition across product type, end user, deployment platform, and technology segmentation dimensions anchored the analytical framework over the projection horizon. CAGRs derived from platform delivery schedules, fleet modernization cycles, and upgrade penetration assumptions. Industry-specific forecast inputs incorporated REACH chemical substance restriction implementation timelines and automatic ejection technology standardization progress across next-generation combat aircraft programs.
Material uncertainties—supply chain disruption in solid rocket propellant precursors, REACH regulatory expansion to additional initiator compounds, and fighter program cancellation or delay—sit outside the modeled envelope. Forecasts reflect assumptions about procurement continuity through NATO consolidation frameworks and qualification pathway stability. Recalibration cycles align with material shifts in defense modernization budget appropriations and airworthiness certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
HUD Helmet Market
Aircraft Safety Systems
Helicopter Ice Protection Systems Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aerospace Lightning Strike Protection Market
Aircraft Safety Systems
Military Airborne Collision Avoidance Systems (ACAS) Market
Aircraft Safety Systems
Identification Friend or Foe Systems Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Cloud-Connected Aircraft Safety Data Management Platforms Market
Aircraft Safety Systems
Instrument Landing System (ILS) Market
Aircraft Safety Systems
Aviation Airbags Market
Aircraft Safety Systems
Aircraft Docking Systems Market
Aircraft Safety Systems
Aircraft Lightning Protection Market