
 Heat Shield Market | 2026-2036
Heat Shield Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shield Market Outlook
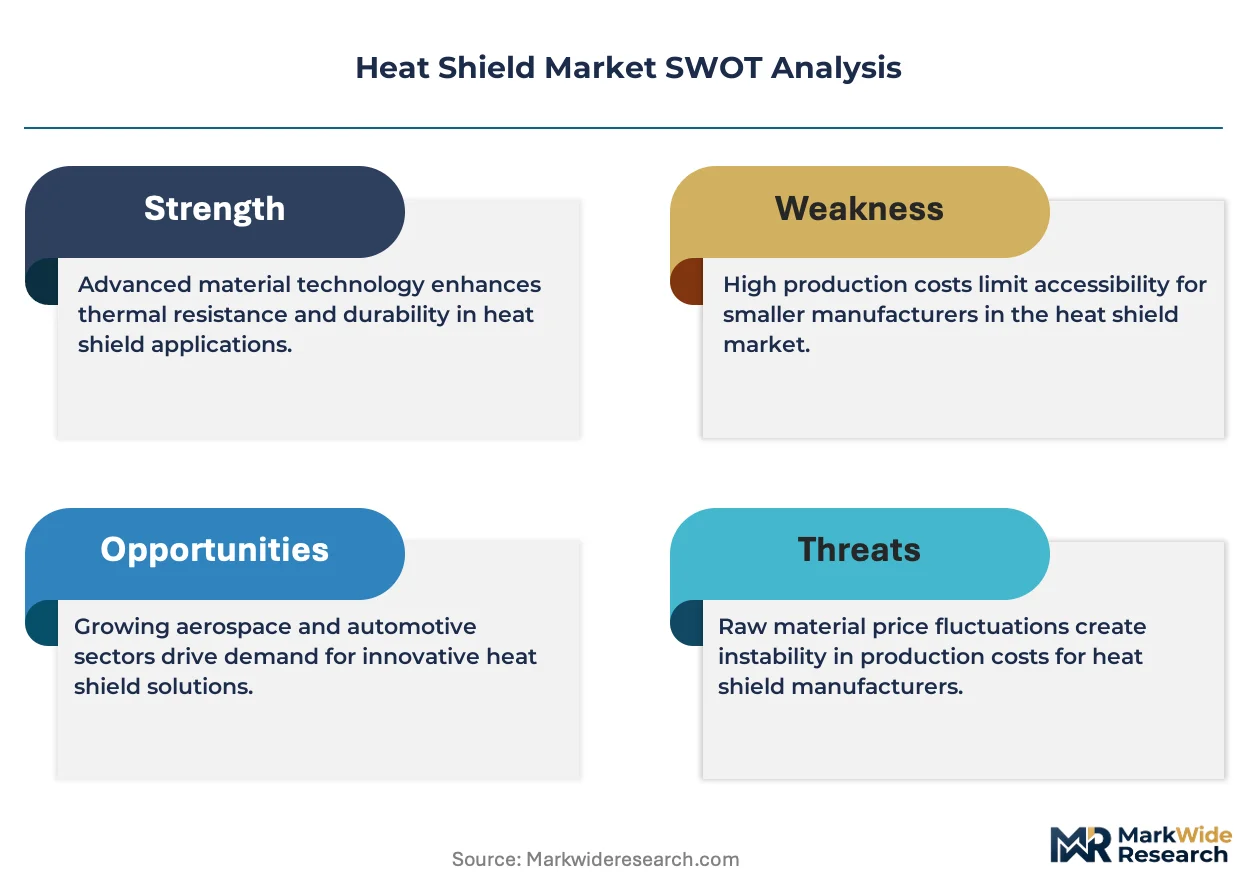
Advanced ceramic matrix composites is tilting heat shield fabrication away from traditional stamped metals toward engineered, fiber-reinforced architectures. Tenneco Inc. leverages its exhaust systems integration expertise to bundle thermal management with emissions hardware. Morgan Advanced Materials anchors European supply through its specialized ceramic formulations for aerospace turbines. ElringKlinger AG competes in automotive underbody shields with polymer-composite hybrids that cut mass versus aluminum alternatives.
Heat shields are engineered thermal barriers, typically fabricated from aluminized steel, ceramic fibers, silica aerogels, or carbon-polymer composites, designed to maintain operational temperatures below critical thresholds in adjacent components or compartments. Their primary purpose is to protect structural elements, electronic systems, and personnel from radiative and convective heat flux in high-temperature operational environments. Metallic shields retain dominance in cost-sensitive automotive exhaust applications, while ceramic and composite variants command premium positioning in aerospace engine protection and spacecraft thermal management where weight-specific performance drives procurement. Electronics cooling represents the fastest-growing application segment as power-dense EV inverters and 5G base stations multiply heat flux densities beyond passive dissipation limits.
FAA airworthiness directives and EPA heavy-duty emissions standards jointly elevate testing rigor and material traceability requirements across North American supply chains. REACH substance restrictions in Europe and China's GB standards for automotive components further fragment compliance architectures, forcing multi-site manufacturers to maintain parallel certification portfolios. Stakeholders must monitor evolving thermal efficiency mandates in defense procurement and commercial space access regimes, as these specifications typically propagate into adjacent industrial segments within two to three regulatory cycles.
Market Dynamics
Ceramic matrix composites are displacing stamped metal architectures across aerospace turbine procurement, compressing qualification timelines while elevating material traceability requirements throughout tiered supply chains.
Growth Catalysts
- EPA heavy-duty emissions standards:Thermal management retrofit demand accelerates as fleet operators upgrade exhaust systems to meet stricter NOx and particulate thresholds. Aftermarket installation volumes concentrate in California and Texas corridors.
- Silica aerogel integration:EV battery pack manufacturers specify ultra-low-density barriers to manage thermal runaway propagation between cell modules. Pack architects value the 90% air fraction that preserves energy density.
- China:Commercial aviation cluster expansion in Xi'an and Chengdu drives specification intensity for next-generation narrowbody programs. Domestic foundries scale ceramic fiber preform capacity to serve COMAC supply chains.
Market Restraints
- Raw material concentration:High-purity alumina feedstock for ceramic matrices concentrates among Chinese state-owned refiners, exposing aerospace fabricators to export quota volatility and dual-use licensing delays.
- REACH substance restrictions:ECHA candidate list expansion for refractory ceramic fibers forces European manufacturers to reformulate insulation blankets, extending R&D cycles by 18-24 months for equivalent thermal performance.
- Aluminum-silicate substitution:Cost-sensitive automotive exhaust suppliers retain stamped aluminized steel for mass-market segments, capping ceramic penetration below premium vehicle lines despite weight advantages.
Strategic Opportunities
- India:Defense indigenization mandates under the PLI scheme create captive demand for domestically fabricated turbine shields. Hindustan Aeronautics and private tier-1s seek technology transfer partnerships for CMC weaving.
- 5G base station thermal management:Power-dense MIMO arrays exceed passive dissipation limits in tropical climates, opening specification channels for composite heat spreaders with integrated phase-change materials.
- FAA airworthiness directive harmonization:Streamlined certification pathways for ceramic matrix components across Part 25 and Part 33 applications reduce duplicate testing burdens for multi-platform engine suppliers.
Industry Challenges
- Specialized braiding technicians:3D woven preform manufacturing requires skills absent from conventional textile or metalworking labor pools. Technical institutes in Germany and the United States pilot apprenticeship tracks with 24-month qualification horizons.
- Pyrolysis furnace capacity:Polymer infiltration and pyrolysis cycles demand continuous high-temperature infrastructure with 10-year depreciation schedules. Mid-tier suppliers face capital allocation constraints against aerospace customer volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shield Market |
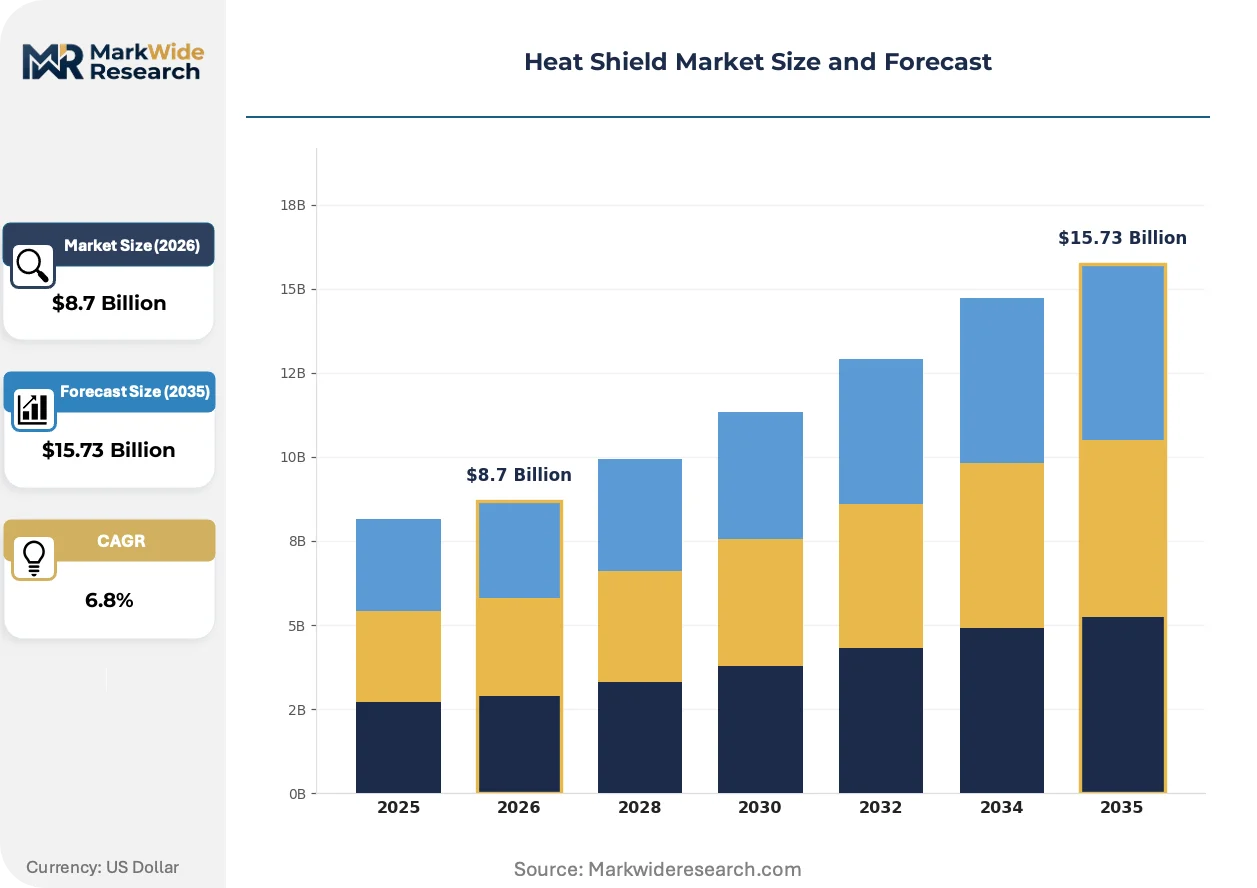
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Shields, Ceramic Shields, Composite Shields, Thermal Barriers End User: Aerospace, Automotive, Industrial, Marine Application: Engine Protection, Exhaust Systems, Spacecraft Thermal Management, Electronics Cooling Installation Type: OEM, Aftermarket, Retrofit, Custom Fit |
| Companies Covered | Tenneco Inc., Morgan Advanced Materials, ElringKlinger AG, UGN Inc., Lydall Inc., Dana Incorporated, Sumitomo Riko Co. Ltd., Progress-Werk Oberkirch AG, Autoneum Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shield Market Strategic Shifts
Digital thread integration across design-to-certification workflows is compressing development cycles while fragmenting supplier tiers between data-capable specialists and legacy fabricators.
Additive manufacturing of ceramic matrix composite preforms is digitizing qualification protocols for complex-curved turbine vanes. GE Aerospace and Rolls-Royce deploy topology-optimized lattice structures that integrate cooling channels monolithically. This capability collapses the traditional forged-billet-to-machined-component pipeline into single-build geometries, digitizing supply chain documentation for FAA traceability requirements.
REACH authorization procedures for refractory ceramic fibers are tightening raw material sourcing across European aerospace supply chains. ECHA's 2023 sunset date extension for certain fiber categories forced inventory requalification at French and German insulation fabricators. Tier-2 suppliers now maintain parallel formulations—one REACH-compliant for EU deliveries, one conventional for export markets—diverging cost structures by geography.
Buyer consolidation among mega-OEMs is compressing supplier negotiation leverage while elevating performance-guarantee terms. Pratt & Whitney and Safran now specify thermal barrier life-cycle cost models rather than unit pricing, transferring operational risk to shield fabricators. This shift concentrates contract awards among vertically integrated material suppliers capable of warranting 25,000-hour service intervals, marginalizing component specialists without captive fiber production.
Heat Shield Market Segmentation
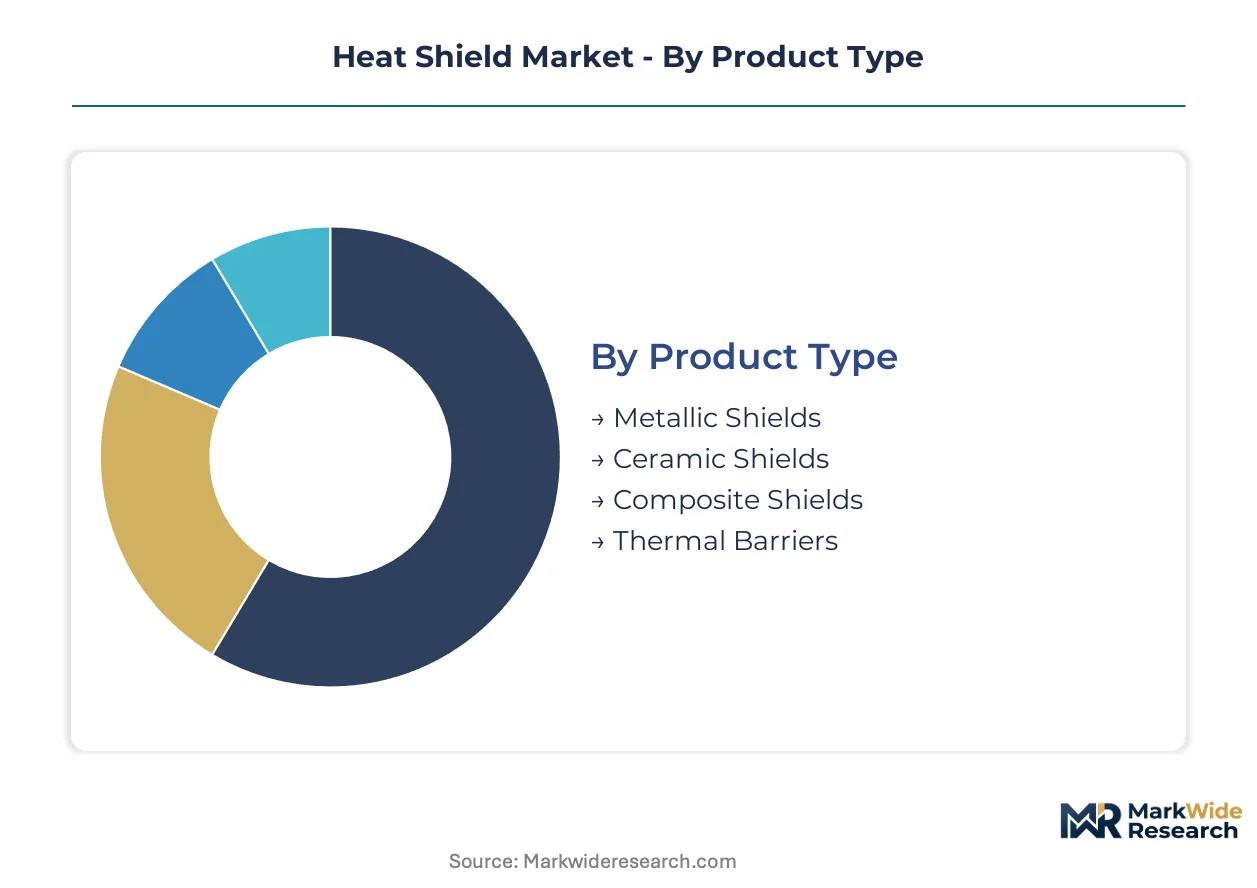
Heat shield procurement splits across multiple axes that dictate service intensity, material specification, and certification burden. Engineers must match thermal performance requirements against weight constraints, regulatory exposure, and lifecycle cost models. The report examines four primary segmentation dimensions that structure vendor-customer relationships and pricing architectures.
Product Type:
After-sales service intensity varies sharply by material family, with ceramic matrix composites demanding specialized inspection protocols and metallic shields supporting routine exhaust shop maintenance.
- Metallic Shields:Stamped aluminized steel or stainless steel architectures dominate automotive exhaust applications where cost sensitivity overrides weight penalties. Fleet operators in Texas and California corridors drive aftermarket replacement volumes as EPA heavy-duty emissions standards tighten thermal management requirements.
- Ceramic Shields:High-purity alumina and silica-based matrices command premium positioning in aerospace turbine engines where 25,000-hour service intervals are contractually warranted. REACH substance restrictions on refractory ceramic fibers force European fabricators to maintain parallel formulations for EU and export markets.
- Composite Shields:Carbon-fiber-reinforced polymer hybrids cut mass versus aluminum alternatives in automotive underbody applications. Tier-1 suppliers integrate these with structural components to reduce assembly complexity.
- Thermal Barriers:Silica aerogel blankets with 90% air fraction preserve energy density in EV battery pack architectures. Pack architects specify these ultra-low-density barriers to manage thermal runaway propagation between cell modules.
By volume, metallic shields lead. By growth pace, ceramic shields are climbing the fastest.
End User:
Cost tier stratification separates defense-aerospace procurement with multi-year qualification cycles from automotive volume contracts with annual price-down targets.
- Aerospace:Commercial aviation clusters in Xi'an, Chengdu, and Toulouse drive specification intensity for next-generation narrowbody programs. FAA airworthiness directives and EASA certification requirements elevate material traceability throughout tiered supply chains.
- Automotive:Heavy-duty fleet retrofit demand accelerates as operators upgrade exhaust systems to meet stricter NOx thresholds. OEM integration with emissions hardware bundles thermal management into system-level procurement.
- Industrial:Process equipment and power generation applications specify standardized insulation blankets with shorter qualification horizons than aerospace counterparts.
- Marine:IMO emissions regulations for vessel engines create specification channels for corrosion-resistant metallic shields in salt-air environments.
Defense indigenization mandates under India's PLI scheme are expanding the addressable base for domestic turbine shield fabrication.
Application:
Volume concentration in mature engine protection segments contrasts with electronics cooling, where power density trends are opening new specification channels.
- Engine Protection:Turbine vanes and combustor liners require 3D woven ceramic matrix composite preforms with integrated cooling channels. GE Aerospace and Rolls-Royce deploy topology-optimized lattice structures that collapse traditional forged-billet-to-machined-component pipelines.
- Exhaust Systems:Thermal management retrofit volumes concentrate in California and Texas corridors where fleet operators face EPA compliance deadlines. Stamped metal architectures retain dominance in cost-sensitive mass-market segments.
- Spacecraft Thermal Management:Reentry vehicle heat shields demand ablative or reusable ceramic tiles with extreme temperature gradients. Commercial space access regimes propagate thermal efficiency specifications into adjacent industrial segments.
- Electronics Cooling:Power-dense EV inverters and 5G MIMO arrays in tropical climates exceed passive dissipation limits. Composite heat spreaders with integrated phase-change materials represent the steepest expansion trajectory across all application categories.
Application-level procurement is shifting toward life-cycle cost models rather than unit pricing, transferring operational risk to shield fabricators.
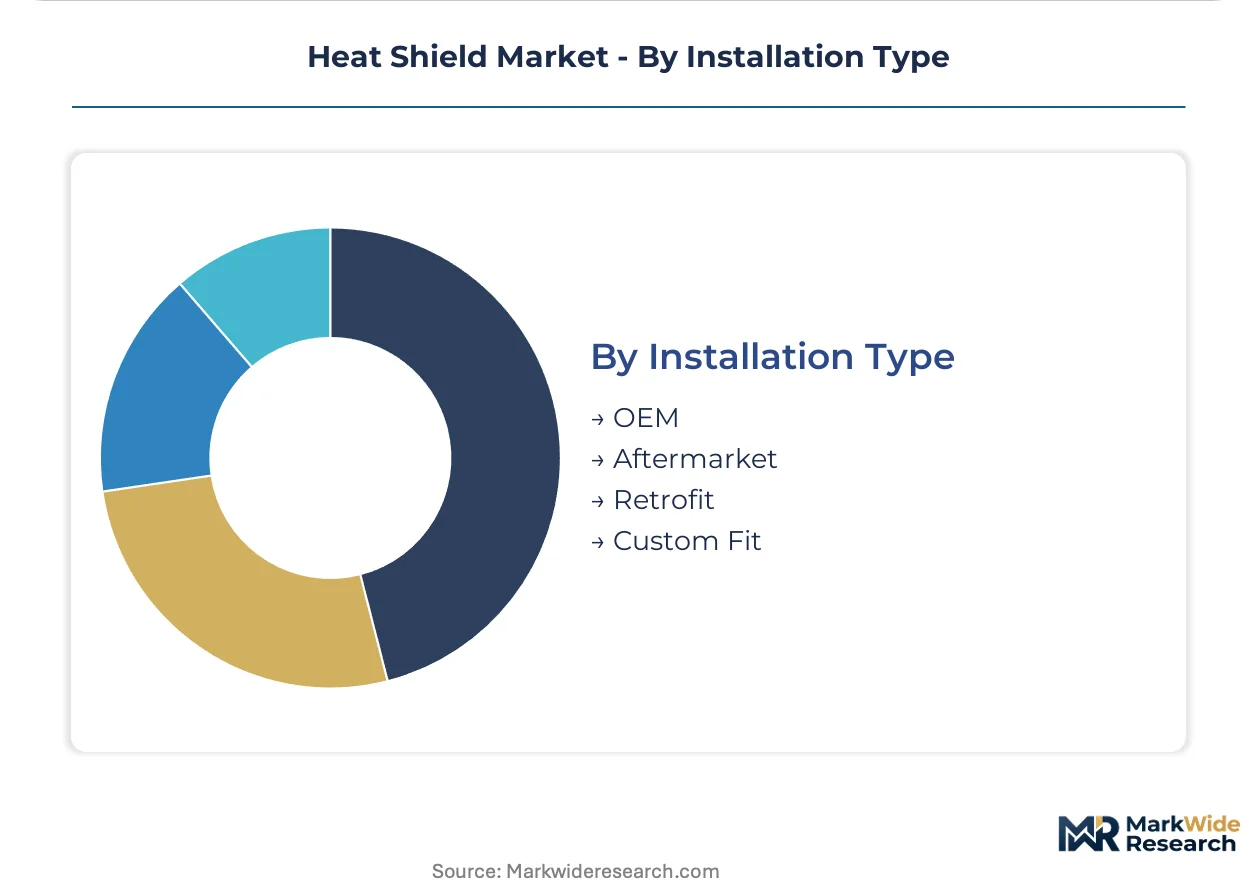
Installation Type:
Customer type determines margin structure, with OEM contracts capturing volume and aftermarket channels preserving pricing power through emergency replacement demand.
- OEM:Long-term supply agreements with Pratt & Whitney and Safran specify thermal barrier performance guarantees across 25,000-hour service intervals. Mega-OEM consolidation compresses supplier negotiation leverage while elevating warranty terms.
- Aftermarket:Independent service networks for heavy-duty trucks and marine engines stock metallic shield inventories for rapid turnaround. Distribution runs through specialized thermal management distributors rather than general automotive parts channels.
- Retrofit:EPA-driven exhaust system upgrades require engineering validation for legacy vehicle architectures. Fleet operators seek bundled solutions combining emissions hardware with thermal barriers.
- Custom Fit:Defense and specialty aerospace applications demand application-specific preform weaving with 24-month technician qualification horizons. Technical institutes in Germany and the United States pilot apprenticeship tracks to address specialized braiding skills scarcity.
Installation type selection depends on regulatory exposure timing and fleet replacement cycles rather than pure cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace fabricators export ceramic matrix composite preforms to Toulouse and Seattle assembly lines, while Chinese state-owned refiners dominate high-purity alumina feedstock shipments serving global turbine shield production.
United States
Defense procurement from Pratt & Whitney and GE Aerospace drives specification intensity for next-generation turbine engines. FAA airworthiness directives elevate material traceability requirements throughout tiered supply chains. Commercial aviation clusters in the Pacific Northwest and Southeast concentrate ceramic fiber weaving capacity for narrowbody programs.
Germany
Automotive OEMs specify polymer-composite underbody shields to meet mass reduction targets in premium vehicle lines. REACH substance restrictions on refractory ceramic fibers force insulation fabricators to maintain parallel formulations for EU and export markets. Technical institutes in Bavaria and Baden-Württemberg pilot apprenticeship tracks addressing specialized braiding technician scarcity.
China
COMAC supply chain expansion in Xi'an and Chengdu accelerates domestic ceramic fiber preform capacity scaling. GB standards for automotive components fragment compliance architectures for multi-site manufacturers. State-owned refiners concentrate high-purity alumina feedstock, exposing aerospace fabricators to export quota volatility.
India
Defense indigenization mandates under the PLI scheme create captive demand for domestically fabricated turbine shields. Hindustan Aeronautics and private tier-1s seek technology transfer partnerships for CMC weaving. Foundry investments in Maharashtra and Karnataka target captive ceramic fiber production for indigenous combat aircraft programs.
Japan
Sumitomo Riko and domestic tier-1s supply composite heat spreaders for power-dense EV inverters exceeding passive dissipation limits. METI efficiency mandates propagate thermal management specifications into industrial equipment segments. Automotive clusters in Aichi and Kanagawa prefectures integrate lightweight shielding into hybrid powertrain architectures.
Heat Shield Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated material suppliers capable of warranting extended service intervals, while mid-tier fabricators face capital allocation constraints against aerospace customer volume commitments. Three archetypes dominate: exhaust systems integrators bundling thermal management with emissions hardware, specialized ceramic formulators serving aerospace turbine specifications, and polymer-composite hybrid suppliers targeting automotive mass reduction. Competitive moves concentrate on backward integration into fiber production and geographic expansion through technology licensing partnerships.
Among North American fabricators, Tenneco Inc. and Dana Incorporated occupy positions within the exhaust systems integration archetype, leveraging aftermarket distribution networks for heavy-duty fleet retrofit demand. Morgan Advanced Materials anchors the specialized ceramic formulation tier, exemplifying European supply concentration for aerospace turbine applications. ElringKlinger AG represents the polymer-composite hybrid segment, competing in automotive underbody shielding where mass reduction specifications drive procurement decisions.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Morgan Advanced Materials |
| ElringKlinger AG |
| UGN Inc. |
| Lydall Inc. |
| Dana Incorporated |
| Sumitomo Riko Co. Ltd. |
| Progress-Werk Oberkirch AG |
| Autoneum Holding AG |
| Others |
Value Chain & Pricing Dynamics
Export quota volatility on Chinese high-purity alumina feedstock compresses pricing tier spreads between aerospace-grade ceramic matrix composites and stamped metallic shields while forcing tier-2 fabricators toward dual-sourcing architectures. This raw material concentration risk simultaneously elevates premium-tier pricing power for vertically integrated suppliers and squeezes margins at mid-tier stampers lacking captive fiber production.
Pricing Analysis
Current-generation ceramic matrix composite shields command substantial premiums over prior-generation stamped aluminized steel, while next-generation additive-manufactured preforms with integrated cooling channels widen the technology gap further. Three-tier pricing structure across premium aerospace certification, standard automotive OEM, and economy aftermarket replacement levels separates procurement by performance guarantee duration and material traceability depth. Cost compression in metallic exhaust shields intensifies because fleet operators bundle thermal management with emissions hardware upgrades. Automotive mass-market segments exhibit highest price sensitivity, whereas aerospace turbine contracts with Pratt & Whitney and Safran tolerate premium positioning for 25,000-hour service interval warranties.
Supply Chain Analysis
Extended payment terms from mega-OEMs strain working capital at mid-tier preform weavers, pushing suppliers toward supply-chain finance facilities backed by aerospace prime contractors. High-purity alumina feedstock concentrates in China, ceramic fiber preform weaving anchors in Germany and the United States, and polymer-composite hybrid fabrication clusters in Japan. Pyrolysis furnace capacity for polymer infiltration cycles draws from specialized high-temperature infrastructure with decade-long depreciation schedules. Single-source vulnerability on Chinese state-owned alumina refiners exposes fabricators to dual-use licensing delays. Distribution runs through specialized thermal management distributors serving heavy-duty fleet retrofit corridors rather than general automotive parts channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as silica aerogel integration into EV battery packs and 5G base station thermal management opens specification channels beyond traditional engine protection applications.
For Market Incumbents: Pre-empt ceramic matrix composite displacement of metallic architectures by accelerating backward integration into high-purity alumina feedstock or securing long-term offtake agreements with Chinese state-owned refiners. Invest in pyrolysis furnace capacity additions in the United States or Germany to capture volume commitments from Pratt & Whitney and GE Aerospace as REACH restrictions fragment European supply. Certification investment for FAA Part 25 and Part 33 harmonization creates defensive moats against emerging additive manufacturing specialists.
For New Entrants and Emerging Players: Build out silica aerogel blanket production capacity targeting EV battery pack architects in Japan and South Korea, where power-dense inverters exceed passive dissipation limits. Target India's defense indigenization mandates under the PLI scheme for technology transfer partnerships with Hindustan Aeronautics. A go-to-market angle centered on thermal runaway propagation containment offers faster qualification timelines than aerospace turbine entry.
For Investors and Strategic Acquirers: Specialized braiding technicians with 24-month qualification horizons represent the scarcest acquisition target archetype, as technical institutes in Bavaria and Baden-Württemberg struggle to replenish labor pools. Long-term viability across the projection horizon rests on capturing ceramic fiber preform capacity ahead of COMAC supply chain expansion in Xi'an and Chengdu. Watch for FAA airworthiness directive streamlining as the inflection signal that collapses duplicate testing burdens and concentrates contract awards among data-capable specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Feedstock | Captive supply of high-purity alumina insulates against Chinese export quota volatility and dual-use licensing delays. |
| Pyrolysis Furnace Capacity Expansion | Continuous high-temperature infrastructure captures aerospace customer volume commitments with decade-long depreciation schedules. |
| Digital Thread Integration | Design-to-certification workflow compression fragments supplier tiers between data-capable specialists and legacy fabricators. |
| Silica Aerogel Production Scale-Up | Ultra-low-density barriers with 90% air fraction penetrate EV battery pack and 5G base station specification channels. |
| Technology Transfer Partnerships in India | Defense indigenization mandates under PLI scheme create captive demand for domestically fabricated turbine shields. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with ceramic matrix composite engineers, aerospace procurement managers at tier-1 suppliers, pyrolysis furnace operators, and specialized braiding technicians; and secondary validation through FAA airworthiness directive filings, EPA heavy-duty emissions standard updates, ECHA REACH substance restriction notifications, customs trade data on high-purity alumina shipments, and SEC 10-K disclosures from exhaust systems integrators. Bottom-up and top-down triangulation cross-checked preform weaving capacity estimates against OEM thermal barrier procurement volumes.
Forecast inputs considered material substitution rates from stamped metals to ceramic matrix composites, regulatory compliance cost escalations under REACH and GB standards, and capacity expansion announcements from Chinese state-owned refiners. Segmentation dimensions modeled include material family, end-use industry, application type, and installation channel across the analysis window. CAGRs were derived from volume-weighted average growth trajectories calibrated to aerospace engine production schedules and automotive fleet replacement cycles. Silica aerogel adoption curves in EV battery packs and 5G infrastructure deployment timelines served as industry-specific demand drivers.
Stress conditions across alumina export quota restrictions, pyrolysis furnace capacity constraints, and specialized technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory harmonization timelines and OEM consolidation trajectories. Macroeconomic contraction, accelerated REACH sunset dates, or breakthroughs in metallic additive manufacturing would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Rotary Wing Aircraft Rivets Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Aviation Electro Optical Systems Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Germany Aerospace and Defense Market
Aircraft and Aerospace Components
Europe Military Aviation Market
Aircraft and Aerospace Components
Europe Drone Motor Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Air Taxi Exterior Component Systems Market
Aircraft and Aerospace Components
Aerospace Couplers Market
Aircraft and Aerospace Components
Thrust Vector Control Market
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market