
 Helicopter Emergency Flotation System Market | 2026-2036
Helicopter Emergency Flotation System Market Size, Share, and Industry Trends Forecast 2026-2036
Helicopter Emergency Flotation System Market Insights
North American manufacturing capacity for aviation safety systems is reshaping supplier dynamics across the helicopter emergency flotation system value chain. Survitec Group Limited leverages its marine survival heritage to anchor certification pipelines for offshore rotorcraft operators. DART Aerospace competes through specialized quick-release mounting hardware designed for harsh maritime environments. Safran Aerosystems sustains engineering integration with major OEM helicopter platforms.
A helicopter emergency flotation system comprises inflatable buoyancy assemblies, gas inflation mechanisms, and structural attachment hardware engineered to deploy within seconds of water contact, maintaining cabin upright stability for occupant egress during controlled ditching or unplanned water entry. Systems typically incorporate multi-chamber floats fabricated from coated fabric rated for saltwater corrosion and UV degradation, with activation triggered by hydrostatic sensors or manual pull-cables depending on operational profile. Inflatable floats dominate product type demand due to their proven deployment reliability and established recertification intervals across military and commercial fleets. Search and rescue applications are expanding fastest among application segments as coastal agencies replace legacy platforms with modern rotorcraft equipped for extended over-water missions. Oil and gas operators remain the most concentrated end-user pool, with procurement decisions tied directly to leaseholder insurance requirements and offshore worker safety mandates.
The FAA governs rotorcraft ditchworthiness under Part 29 airworthiness standards, while EASA enforces comparable CS 29 requirements across European jurisdictions, both mandating flotation system performance for Category A operations over water. The US Coast Guard integrates emergency flotation specifications into its rotary-wing acquisition contracts, creating a captive demand channel distinct from commercial aftermarket flows. Stakeholders must monitor evolving hydrostatic sensor reliability standards and composite float material qualification timelines as regulatory bodies tighten deployment-success thresholds.

Market Dynamics
Offshore leaseholder insurance mandates are tightening flotation system compliance timelines faster than manufacturing capacity can expand, compressing retrofit windows for aging helicopter fleets across the Gulf of Mexico and North Sea corridors.
Growth Catalysts
- FAA Part 29 ditchworthiness updates:The FAA's revised rotorcraft ditching standards mandate Category A flotation performance for extended over-water operations, forcing fleet-wide system upgrades among commercial operators.
- Offshore worker safety mandates:Oil and gas leaseholders in the United States Gulf Coast corridor now require emergency flotation compliance as a condition of crew transport contracts, embedding safety systems into procurement specifications.
- Coated fabric durability advances:Multi-chamber float designs using saltwater-corrosion-resistant materials are extending recertification intervals, reducing total cost of ownership for military and commercial fleets.
Market Restraints
- Specialized coated fabric supply concentration:Production of aviation-grade inflatable materials clusters among a limited supplier base, creating input bottlenecks during fleet-wide retrofit surges.
- Composite float material qualification timelines:New lightweight composite buoyancy assemblies face extended airworthiness certification cycles under EASA CS 29 and FAA Part 29 frameworks, delaying product entry.
- Fixed-wing offshore transport substitution:Short-haul fixed-wing aircraft with ditching-capable hull designs are capturing select offshore personnel transport routes from rotorcraft platforms.
Strategic Opportunities
- Search and rescue fleet modernization:Coastal agencies in Norway and the United Kingdom are replacing legacy rotorcraft with extended-range platforms, creating demand for integrated emergency flotation systems.
- Hydrostatic sensor reliability standards:Regulatory bodies are tightening deployment-success thresholds, opening specification windows for next-generation activation mechanisms with redundant triggering architectures.
- Extended over-water mission profiles:Emergency medical services operators in Australia are expanding inter-island helicopter routes, requiring flotation systems for missions previously confined to coastal corridors.
Industry Challenges
- Aviation safety systems engineering talent scarcity:Specialized expertise in rotorcraft ditchworthiness certification and marine survival system integration remains concentrated among a narrow practitioner pool, constraining program velocity.
- Legacy platform structural attachment complexity:Retrofit mounting hardware for aging helicopter airframes requires custom engineering to accommodate non-standard frame geometries, extending installation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Helicopter Emergency Flotation System Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Floats, Emergency Buoyancy Devices, Self-Activating Systems, Manual Deployment Units, Multi-Chamber Floats Application: Search and Rescue, Offshore Transport, Military Operations, Medical Evacuation, Firefighting Missions End User: Oil & Gas Operators, Coast Guard Units, Naval Forces, Search and Rescue Organizations, Air Ambulance Services Deployment Method: Helicopter Cabin Installation, External Mounting, Quick-Release Mounts, Integrated Floatation Systems, Modular Attachments |
| Companies Covered | Survitec Group Limited, Airborne Systems, DART Aerospace, GKN Aerospace, Leonardo S.p.A., UTC Aerospace Systems, L3Harris Technologies, Aero Sekur, Safran Aerosystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Helicopter Emergency Flotation System Market Trends and Innovations
Activation mechanism architectures are pivoting from manual pull-cable dependencies toward sensor-triggered autonomous deployment, reshaping system reliability expectations and maintenance protocols across military and commercial fleets.
Electro-mechanical hydrostatic sensors with redundant triggering circuits are rendering obsolete single-point manual activation systems in high-risk offshore environments. Oil and gas transport operators in the Gulf of Mexico are specifying these architectures for new-build helicopter acquisitions. The shift is compressing supplier differentiation around sensor mean-time-between-failure metrics rather than hardware durability alone.
EASA's tightened CS 29 ditchworthiness interpretation is accelerating compliance-driven retrofit cycles among European offshore operators. The regulatory friction is forcing fleet managers to prioritize flotation system upgrades ahead of other avionics modernization programs. North Sea helicopter service providers are responding by consolidating maintenance contracts with certified installation centers capable of handling compressed turnaround windows.
Buyer preference is hardening around integrated life-cycle service agreements that bundle flotation system installation, recertification, and emergency response training. Traditional component-only supply relationships are losing share to full-service contracts among major offshore oil and gas leaseholders. This pattern is most pronounced in Brazil, where ANVISA-aligned safety mandates are embedding training compliance into procurement evaluation criteria.
Helicopter Emergency Flotation System Market Segmentation
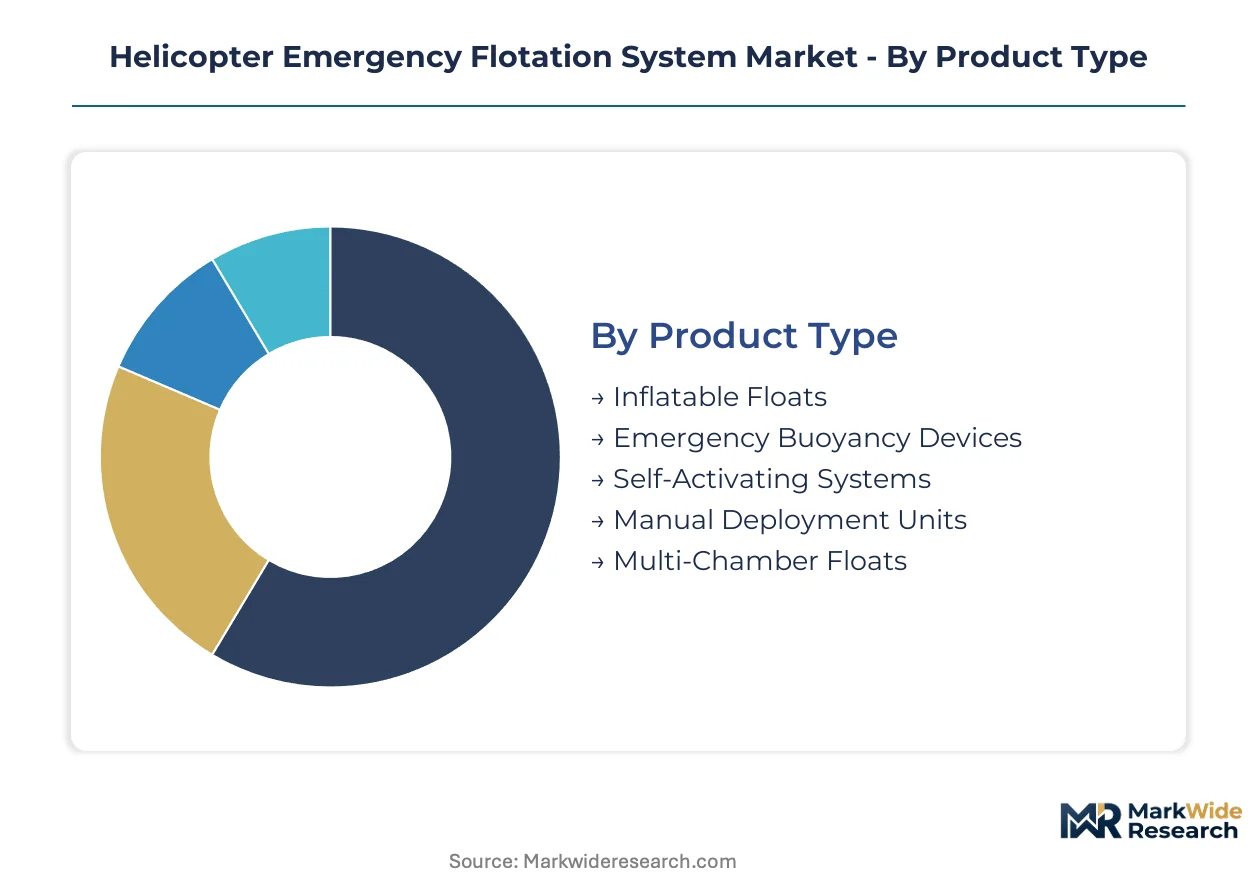
Helicopter emergency flotation systems serve radically different operational profiles across offshore oil transport, military search and rescue, and medical evacuation missions. Each use-case imposes distinct buoyancy requirements, deployment speed thresholds, and recertification protocols that fragment procurement specifications across the value chain.
Product Type:
Cost tiers separate legacy manual systems from sensor-integrated autonomous architectures with redundant activation circuits.
- Inflatable Floats:Multi-chamber designs fabricated from saltwater-corrosion-resistant coated fabric dominate commercial and military retrofit programs. Oil and gas operators in the United States Gulf Coast corridor specify these for extended over-water transport contracts tied to leaseholder insurance mandates.
- Multi-Chamber Floats:Segmented buoyancy cells maintain cabin upright stability even with partial chamber damage during unplanned water entry. Search and rescue organizations in Norway and the United Kingdom are specifying these for extended-range rotorcraft modernization programs.
- Emergency Buoyancy Devices:Compact supplemental flotation for skid-mounted helicopters operating coastal corridors.
- Self-Activating Systems:Hydrostatic sensor-triggered deployment eliminates manual pull-cable dependencies in high-risk offshore environments.
- Manual Deployment Units:Single-point activation systems retain niche presence in legacy military platforms with established maintenance protocols.
The dominant share belongs to Inflatable Floats, while Self-Activating Systems is closing the gap fastest.
Application:
Volume concentrates in offshore transport, though mission profile diversity creates specification fragmentation across the install base.
- Offshore Transport:Crew rotation flights between Gulf of Mexico platforms and coastal heliports drive fleet-wide retrofit surges. FAA Part 29 Category A ditchworthiness compliance compresses installation timelines for aging helicopter fleets serving oil and gas leaseholders.
- Search and Rescue:Coastal agencies are replacing legacy platforms with modern rotorcraft equipped for extended over-water missions. EASA CS 29 tightened interpretations accelerate compliance-driven procurement cycles among European helicopter service providers.
- Military Operations:Naval rotary-wing acquisition contracts embed emergency flotation specifications distinct from commercial aftermarket flows.
- Medical Evacuation:Inter-island helicopter routes in Australia require flotation systems for missions previously confined to coastal corridors.
- Firefighting Missions:Amphibious rotorcraft operating reservoir and coastal water sources specify rapid-deployment flotation for water scooping operations.
Offshore Transport commands the largest installed base, though Search and Rescue shows the steepest expansion trajectory.
End User:
Customer type determines procurement authority structure and life-cycle service agreement preferences.
- Oil & Gas Operators:Leaseholder safety mandates embed flotation compliance into crew transport contract specifications. Procurement decisions tie directly to insurance requirements and offshore worker protection protocols across the North Sea and Gulf of Mexico corridors.
- Coast Guard Units:Government acquisition contracts integrate emergency flotation into rotary-wing platform specifications with captive demand channels.
- Search and Rescue Organizations:Coastal agencies in the United Kingdom consolidate maintenance contracts with certified installation centers.
- Naval Forces:Military specifications prioritize deployment reliability under combat damage conditions.
- Air Ambulance Services:Emergency medical operators in Australia expand inter-island route networks requiring over-water certification.
Oil & Gas Operators retain the dominant procurement volume, while Coast Guard Units are gaining share fastest through fleet modernization programs.
Deployment Method:
Supply concentration clusters around integrated architectures versus modular retrofit hardware for aging airframes.
- Quick-Release Mounts:Specialized attachment hardware designed for harsh maritime environments enables rapid installation and maintenance access. DART Aerospace competes through proprietary designs targeting Gulf of Mexico offshore operators with compressed turnaround requirements.
- Integrated Floatation Systems:Factory-installed architectures engineered for major OEM helicopter platforms streamline airworthiness certification. Safran Aerosystems sustains engineering integration partnerships with airframe manufacturers.
- Helicopter Cabin Installation:Internal mounting preserves external aerodynamic profiles for high-speed offshore transport configurations.
- External Mounting:Skid and fuselage attachments accommodate legacy platforms without structural cabin modifications.
- Modular Attachments:Field-replaceable components reduce maintenance downtime for dispersed fleet operations.
Integrated Floatation Systems hold the dominant position, though Quick-Release Mounts are climbing the fastest as retrofit demand surges.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation-grade inflatable material suppliers cluster in the United States, United Kingdom, and France, creating geographic chokepoints for helicopter emergency flotation system manufacturing. Fleet retrofit demand concentrates along offshore oil corridors where leaseholder safety mandates compress installation timelines.
United States
The Gulf Coast corridor between Houston and New Orleans hosts the densest concentration of offshore helicopter activity worldwide. FAA Part 29 ditchworthiness updates mandate Category A flotation performance for extended over-water operations, forcing fleet-wide system upgrades. Louisiana-based installation centers handle compressed turnaround windows for aging Sikorsky and Bell platforms serving Gulf of Mexico oil platforms.
Norway
North Sea helicopter service providers face EASA CS 29 tightened interpretations that accelerate compliance-driven procurement cycles. Coastal agencies in Stavanger and Bergen are replacing legacy rotorcraft with extended-range platforms equipped for search and rescue missions. Norwegian operators consolidate maintenance contracts with certified centers capable of handling multi-chamber float installations under compressed regulatory deadlines.
United Kingdom
Aberdeen anchors European offshore oil and gas transport demand, with helicopter operators retrofitting fleets to meet tightened leaseholder insurance mandates. The UK Coast Guard integrates emergency flotation specifications into rotary-wing acquisition contracts, creating captive demand distinct from commercial aftermarket flows. Scottish installation facilities specialize in quick-release mounting hardware for harsh North Sea maritime environments.
Brazil
ANVISA-aligned safety mandates embed training compliance into procurement evaluation criteria for offshore operators in the Campos Basin. Air ambulance services expanding inter-island routes require flotation systems for missions previously confined to coastal corridors. Rio de Janeiro-based helicopter service providers bundle life-cycle service agreements covering installation, recertification, and emergency response training.
Australia
Emergency medical services operators in Queensland and Western Australia are extending helicopter routes across Torres Strait and Bass Strait corridors. The country's Civil Aviation Safety Authority mandates flotation equipment for rotorcraft operating beyond autorotational distance from shore. Perth and Brisbane maintenance centers report surging demand for self-activating hydrostatic sensor systems on medical evacuation platforms.
Helicopter Emergency Flotation System Market Competitive Landscape
Integrated system architects and specialized component fabricators split the market along engineering depth versus installation velocity lines. Consolidation pressures concentrate among aviation-grade coated fabric suppliers, where limited production capacity creates input bottlenecks during fleet-wide retrofit surges. Three strategic archetypes dominate: marine survival heritage conglomerates with certification pipeline control, aerospace-integrated platform specialists, and quick-release hardware boutiques targeting compressed turnaround environments. Competitive moves center on capacity expansion in sensor-triggered activation architectures and geographic consolidation of certified installation center networks.
Within the marine survival tier, Survitec Group Limited anchors certification pipelines leveraging its heritage in offshore safety systems. DART Aerospace and Safran Aerosystems occupy complementary positions, with the former exemplifying specialized quick-release mounting hardware design and the latter representing engineering integration partnerships with major OEM helicopter platforms. These three companies collectively illustrate the market's segmentation between installation-velocity specialists and platform-integrated system architects.
| Leading Market Players |
|---|
| Survitec Group Limited |
| Airborne Systems |
| DART Aerospace |
| GKN Aerospace |
| Leonardo S.p.A. |
| UTC Aerospace Systems |
| L3Harris Technologies |
| Aero Sekur |
| Safran Aerosystems |
| Others |
Pricing and Supply Chain Analysis
Aviation-grade coated fabric production clusters in the United States Gulf Coast corridor, where limited supplier capacity for saltwater-corrosion-resistant materials creates asymmetric pricing power during fleet-wide retrofit surges. This geographic concentration allows input producers to command premium terms when oil and gas leaseholders compress compliance timelines.
Pricing Analysis
FAA Part 29 ditchworthiness standards dictate the pricing tier structure across the helicopter emergency flotation system market. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated autonomous architectures with redundant activation circuits from legacy manual deployment units. Cost compression in the standard tier is intensifying because coated fabric suppliers face capacity constraints during North Sea and Gulf of Mexico retrofit waves. Oil and gas operators show the least price sensitivity due to embedded insurance mandates, while air ambulance services in emerging route networks exhibit the highest elasticity.
Supply Chain Analysis
Export control regimes governing aviation safety systems limit technology flows to certain end-users, constraining supplier expansion into restricted defense channels. Manufacturing capacity concentrates in the United States, United Kingdom, and France, with production anchored in specialized coated fabric mills and precision sensor fabrication facilities. Raw material dependencies include aviation-grade elastomer coatings, hydrostatic sensor components, and high-tensile attachment hardware. Single-source vulnerability runs through the limited base of certified coated fabric suppliers capable of meeting EASA CS 29 and FAA qualification standards. Distribution runs through OEM-integrated channels for new-build platforms and certified installation centers for retrofit programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The helicopter emergency flotation system market sits in a cyclical recovery phase driven by offshore oil and gas fleet renewal cycles. Regulatory compliance deadlines are compressing procurement windows and reshaping competitive positioning.
For Market Incumbents: Build certification pipeline moats by expanding accredited installation center networks across the Gulf of Mexico and North Sea corridors. Secure captive supply agreements with aviation-grade coated fabric producers to defend against input bottlenecks during retrofit surges. Invest in redundant hydrostatic sensor architectures ahead of tightened FAA deployment-success thresholds. For New Entrants and Emerging Players: Pursue white-space opportunities in quick-release mounting hardware for aging Sikorsky and Bell platforms requiring custom structural attachments. Target the Australian emergency medical services segment where inter-island route expansion outpaces established supplier presence. Lead with bundled life-cycle service agreements covering installation, recertification, and emergency response training to differentiate from component-only incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because aviation safety mandates embed recurring retrofit demand independent of cyclical offshore activity. Acquisition candidates should display certified installation center networks and established relationships with major oil and gas leaseholders. Watch for EASA CS 29 interpretation tightening as the signal indicating accelerated European procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installation Center Expansion | Compresses turnaround windows for Gulf of Mexico operators facing FAA compliance deadlines. |
| Coated Fabric Supplier Integration | Secures captive supply of saltwater-corrosion-resistant materials during retrofit surges. |
| Redundant Sensor Architecture Development | Anticipates tightened FAA Part 29 deployment-success thresholds for Category A operations. |
| Life-Cycle Service Agreement Bundling | Aligns with Brazilian ANVISA-aligned mandates embedding training compliance into procurement. |
| Search and Rescue Platform Partnership | Captures Norwegian and UK coastal agency modernization programs for extended-range rotorcraft. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FAA airworthiness directives, EASA certification databases, and offshore leaseholder safety mandate documentation. Primary interviews engaged rotorcraft ditchworthiness certification engineers, marine survival system integration specialists, oil and gas transport fleet managers, and certified installation center operations directors. Secondary validation drew from SEC filings of aviation safety system suppliers, US Coast Guard rotary-wing acquisition contract disclosures, and customs records of aviation-grade inflatable material trade flows. Bottom-up segmentation modeling triangulated against top-down market sizing across the analysis window.
Forecast inputs include retrofit program timelines tied to FAA Part 29 compliance deadlines, oil and gas leaseholder insurance mandate adoption curves, and search and rescue fleet modernization budgets. Segmentation dimensions span product type architecture, application mission profile, end-user procurement authority structure, and deployment method integration level. CAGRs were derived from regression analysis of historical fleet data against regulatory implementation schedules. Industry-specific inputs incorporate hydrostatic sensor reliability standard evolution and composite float material qualification pipeline status.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by coated fabric suppliers or accelerated composite material certification would shift outcomes. Material shifts in FAA or EASA ditchworthiness interpretation stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Safety Systems
Commercial Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Survival Equipment Market
Aircraft Safety Systems
Aircraft Smoke Detection and Fire Extinguishing System Market
Aircraft Safety Systems
Aerospace & Aircraft Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Fire Protection Systems Market
Aircraft Safety Systems
Aviation Life Rafts Market
Aircraft Safety Systems
Military Aircraft Collision Avoidance Systems Market
Aircraft Safety Systems
Aircraft Ejection Seats Market
Aircraft Safety Systems
Free Fall Sensor Market
Aircraft Safety Systems
Aircraft Ice Protection System Market
Aircraft Safety Systems
Airborne Collision Avoidance System Market
Aircraft Safety Systems
Aircraft Evacuation Systems Market
Aircraft Safety Systems
Global Aircraft Brakes Market
Aircraft Safety Systems
South Korea Aircraft Windshield Wiper and Washer System Market
Aircraft Safety Systems
Aircraft Survivability Equipment Market
Aircraft Safety Systems
Aircraft Braking System Market