
 Airborne Molecular Contamination Control Services Market | 2026-2036
Airborne Molecular Contamination Control Services Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne Molecular Contamination Control Services Market Insights
South Korea is fragmenting its AMC control services landscape as Samsung and SK Hynix expand domestic cleanroom infrastructure. Entegris leverages its materials science portfolio to anchor filtration solutions across semiconductor fabs. Camfil competes through geographic dominance in European pharmaceutical cleanroom installations. MKS Instruments differentiates by integrating gas analysis hardware with real-time monitoring software.
Airborne molecular contamination control services encompass engineered systems and protocols that detect, filter, and neutralize gaseous and particulate contaminants at concentrations measured in parts per trillion, using chemisorptive media and catalytic oxidation to protect sensitive manufacturing environments. These services prevent yield loss in lithography and deposition processes where molecular acids, bases, and condensables can destroy billion-dollar wafer batches. Contamination monitoring and analytical testing command premium pricing due to the specialized instrumentation and certified protocols required for semiconductor qualification. Gas phase filtration and photocatalytic oxidation represent the fastest-growing technology categories as fabs transition to EUV lithography with stricter AMC thresholds.
The EPA regulates hazardous air pollutant emissions from semiconductor manufacturing under the National Emission Standards for Hazardous Air Pollutants, while the EU F-Gas Regulation phases down hydrofluorocarbon use in etching and chamber cleaning. ISO 14644-8 provides cleanroom classification standards for molecular contamination that fabs must meet for customer qualification. Stakeholders must monitor how tightening fluorinated gas restrictions reshape service contract structures and equipment upgrade cycles.
Market Dynamics
Advanced node migration below 3nm is compressing AMC thresholds by orders of magnitude, forcing fabs to upgrade filtration infrastructure ahead of depreciation cycles and rewiring service contract economics around guaranteed yield outcomes rather than equipment uptime.
Growth Catalysts
- EUV Lithography Penetration:Scanner manufacturers now require sub-ppt molecular contamination levels for optical component protection, mandating chemisorptive media replacement cycles that triple service contract values.
- EU F-Gas Regulation Phase-Down:Tightening hydrofluorocarbon quotas for etching and chamber cleaning are accelerating abatement system deployments that require continuous AMC monitoring to verify destruction efficiency.
- Taiwan Semiconductor Cluster Expansion:Foundry capital expenditure in Hsinchu and Tainan Science Parks is concentrating demand for turnkey contamination control services within a 50-kilometer radius.
Market Restraints
- Specialized Media Supply Concentration:Activated carbon and zeolite substrates for chemisorptive filtration originate from a narrow supplier base in East Asia, exposing service providers to input cost volatility and allocation risk.
- Capital Intensity of Analytical Instrumentation:Real-time AMC detection requires proton transfer reaction mass spectrometry units costing several million dollars per installation, limiting independent service provider entry.
- Regulatory Friction from EPA NESHAP:Hazardous air pollutant reporting requirements for semiconductor manufacturing create compliance overhead that extends service contract negotiation timelines by quarters.
Strategic Opportunities
- India Semiconductor Mission Incentives:Production-linked incentive schemes for domestic fab construction are creating first-mover advantage for AMC control service providers establishing local calibration and maintenance capabilities.
- Photocatalytic Oxidation Convergence:Integration of UV-activated titanium dioxide systems with existing gas phase filtration infrastructure enables retrofit revenue streams in mature fabs.
- Pharmaceutical Cleanroom Crossover:Cell and gene therapy manufacturing under ISO 14644-8 is adopting semiconductor-grade AMC protocols, opening adjacent verticals with less cyclical capital spending.
Industry Challenges
- Certified Technician Scarcity:Operation of proton transfer reaction mass spectrometry and ion mobility spectrometry equipment requires specialized training programs that lag fab construction timelines.
- Legacy System Integration Complexity:Brownfield facilities with 1990s-era HVAC infrastructure face prohibitive ductwork modification costs to accommodate modern gas phase filtration banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne Molecular Contamination Control Services Market |
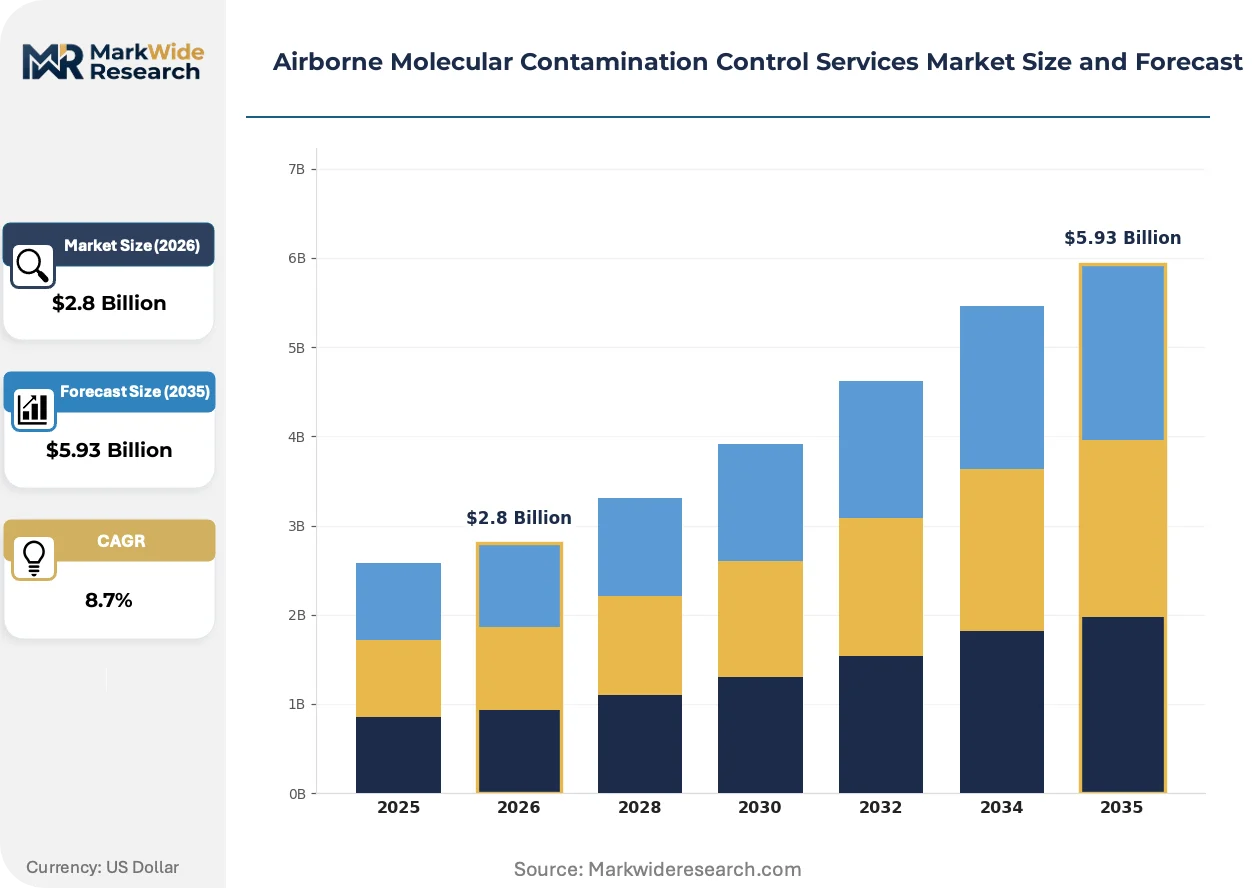
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Contamination Monitoring, Air Purification, Surface Cleaning, Analytical Testing, Preventive Maintenance Technology: Photocatalytic Oxidation, Ultraviolet Light, Activated Carbon Filtration, Ionic Purification, Gas Phase Filtration Application: Semiconductor Fabrication, Pharmaceutical Manufacturing, Aerospace Assembly, Food Processing End User: Microelectronics Manufacturers, Biopharmaceutical Firms, Aerospace Integrators, Food Production Facilities |
| Companies Covered | Entegris, Camfil, Particle Measuring Systems, HORIBA, KLA, MKS Instruments, Teledyne API, Picarro, Process Insights, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne Molecular Contamination Control Services Market Trends and Innovations
Service delivery models are pivoting from scheduled maintenance to continuous contamination intelligence, with real-time data streams rewiring how fabs manage yield risk and how providers structure performance guarantees.
Photocatalytic oxidation technology is hybridizing with traditional chemisorptive filtration to address volatile organic compounds that evade activated carbon capture. Memory and logic fabs in South Korea are piloting these hybrid systems for EUV resist outgassing control. The convergence is compressing equipment footprints while raising the technical bar for service providers who must now optimize catalyst replacement cycles alongside media changeouts.
REACH authorization requirements for per- and polyfluoroalkyl substances are restricting fluoropolymer membrane availability for cleanroom construction and filtration components. European pharmaceutical and semiconductor manufacturers are accelerating qualification of alternative membrane chemistries ahead of sunset dates. German chemical suppliers are responding with expanded production of non-fluorinated barrier materials, though performance parity gaps persist in ultrapure water applications.
Foundries are unbundling AMC monitoring from equipment maintenance, creating standalone analytical service contracts with penalty clauses tied to excursion detection response times. This purchasing pattern shift concentrates spending with providers owning proprietary sensor networks and certified reference materials. Taiwan-based integrated device manufacturers are most advanced in this transition, with contract structures now specifying maximum allowable time-to-detection for molecular acid and base events.
Airborne Molecular Contamination Control Services Market Segmentation
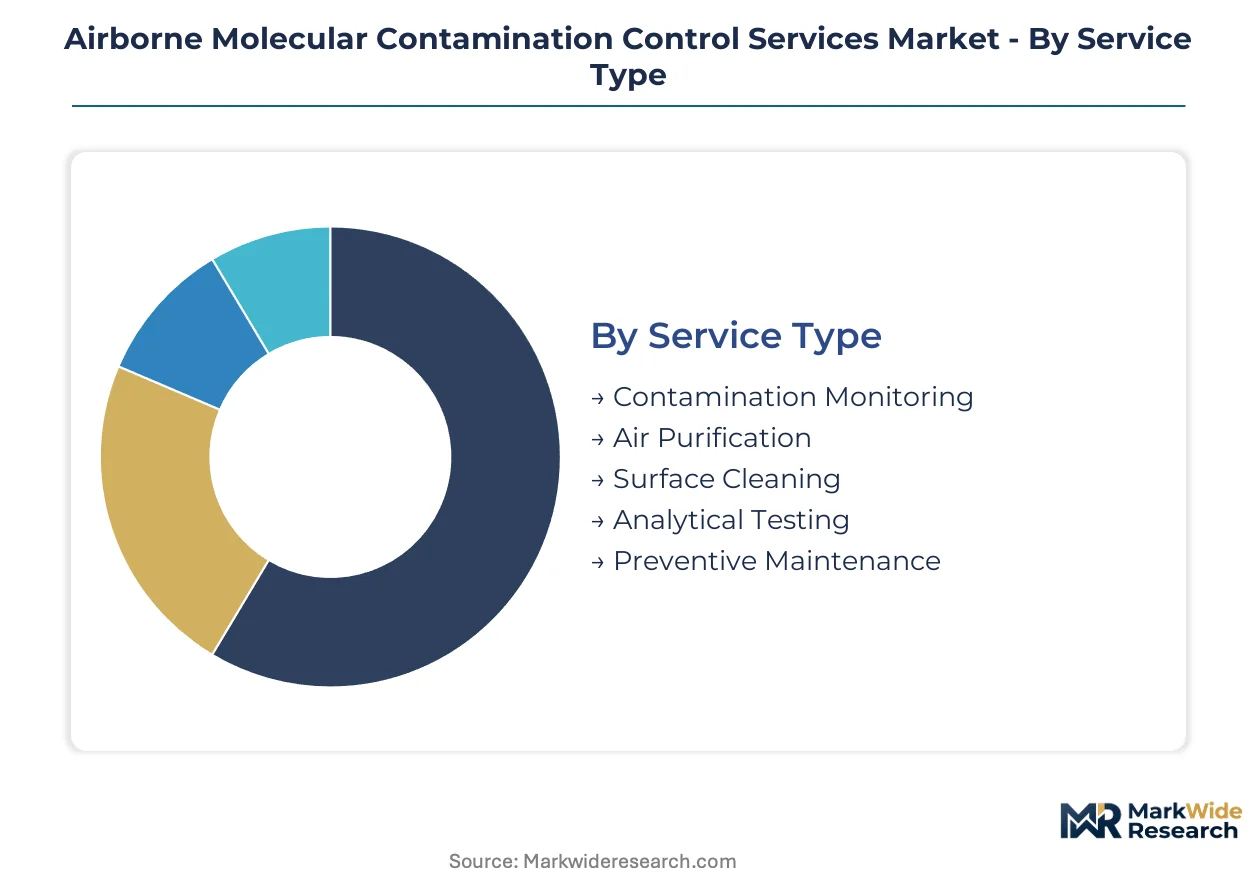
AMC control services fragment across distinct technical competencies and regulatory compliance layers. Each segment commands different capital intensity and recurring revenue profiles. Procurement patterns vary sharply between semiconductor fabs requiring sub-ppt detection and pharmaceutical cleanrooms operating at higher contamination thresholds.
Service Type:
Service portfolios span reactive remediation through predictive intelligence, with contract economics diverging by technical sophistication and certification requirements.
- Contamination Monitoring:Continuous sensor networks using proton transfer reaction mass spectrometry and ion mobility spectrometry track molecular acids, bases, and condensables in real time. Taiwan foundries now specify maximum time-to-detection clauses in standalone analytical contracts, unbundling this service from equipment maintenance agreements.
- Analytical Testing:Certified laboratories perform grab sampling and chromatographic analysis for customer qualification audits under ISO 14644-8 protocols. Demand concentrates in Hsinchu and Tainan Science Parks where foundry capital expenditure is accelerating.
- Air Purification:Turnkey gas phase filtration system design and commissioning for new fab construction.
- Surface Cleaning:Protocol development and execution for cleanroom materials and equipment decontamination.
- Preventive Maintenance:Scheduled media replacement and equipment calibration to sustain filtration performance.
The dominant share belongs to Contamination Monitoring, while Analytical Testing is closing the gap fastest.
Technology:
Technology selection hinges on contaminant chemistry, with hybrid architectures gaining traction as EUV lithography tightens thresholds.
- Photocatalytic Oxidation:UV-activated titanium dioxide systems mineralize volatile organic compounds through radical oxidation. Samsung and SK Hynix fabs in South Korea pilot hybrid configurations combining photocatalytic stages with downstream chemisorptive polishing for EUV resist outgassing control.
- Gas Phase Filtration:Deep-bed chemisorptive media using activated carbon and zeolite substrates remove molecular contaminants through adsorption and chemical reaction. Media supply concentration in East Asia exposes service providers to allocation risk and input cost volatility.
- Activated Carbon Filtration:Standard impregnated carbon systems for general acid and base removal.
- Ultraviolet Light:Standalone UV sterilization for biological contamination control.
- Ionic Purification:Electrostatic precipitation systems for charged particulate and aerosol removal.
Gas Phase Filtration retains the largest installed base, though Photocatalytic Oxidation is expanding most quickly through retrofit revenue in mature fabs.
Application:
Application demand clusters around yield-critical manufacturing where contamination excursions destroy high-value work-in-process.
- Semiconductor Fabrication:Lithography and deposition processes require sub-ppt AMC levels to protect optical components and prevent wafer defects. EUV scanner manufacturers now mandate chemisorptive media replacement cycles that triple service contract values.
- Pharmaceutical Manufacturing:Cell and gene therapy production under ISO 14644-8 is adopting semiconductor-grade protocols. This vertical offers less cyclical capital spending and opens adjacent revenue streams for established service providers.
- Aerospace Assembly:Precision instrument and satellite component manufacturing requiring controlled environments.
- Food Processing:High-care zone contamination control for extended shelf-life products.
Semiconductor Fabrication commands the premium pricing tier, while Pharmaceutical Manufacturing is gaining share fastest through regulatory convergence.
End User:
End user procurement sophistication varies by industry maturity and internal technical capabilities.
- Microelectronics Manufacturers:Integrated device manufacturers and foundries operate captive cleanroom infrastructure with dedicated AMC control staff. These buyers unbundle monitoring from maintenance and negotiate penalty clauses tied to excursion response times.
- Biopharmaceutical Firms:Contract development and manufacturing organizations outsource contamination control to qualified service providers under quality agreements. REACH authorization restrictions on fluoropolymer membranes are accelerating qualification of alternative barrier materials.
- Aerospace Integrators:Prime contractors and tier suppliers with specialized contamination control requirements.
- Food Production Facilities:Processors implementing hygienic zone segregation for pathogen control.
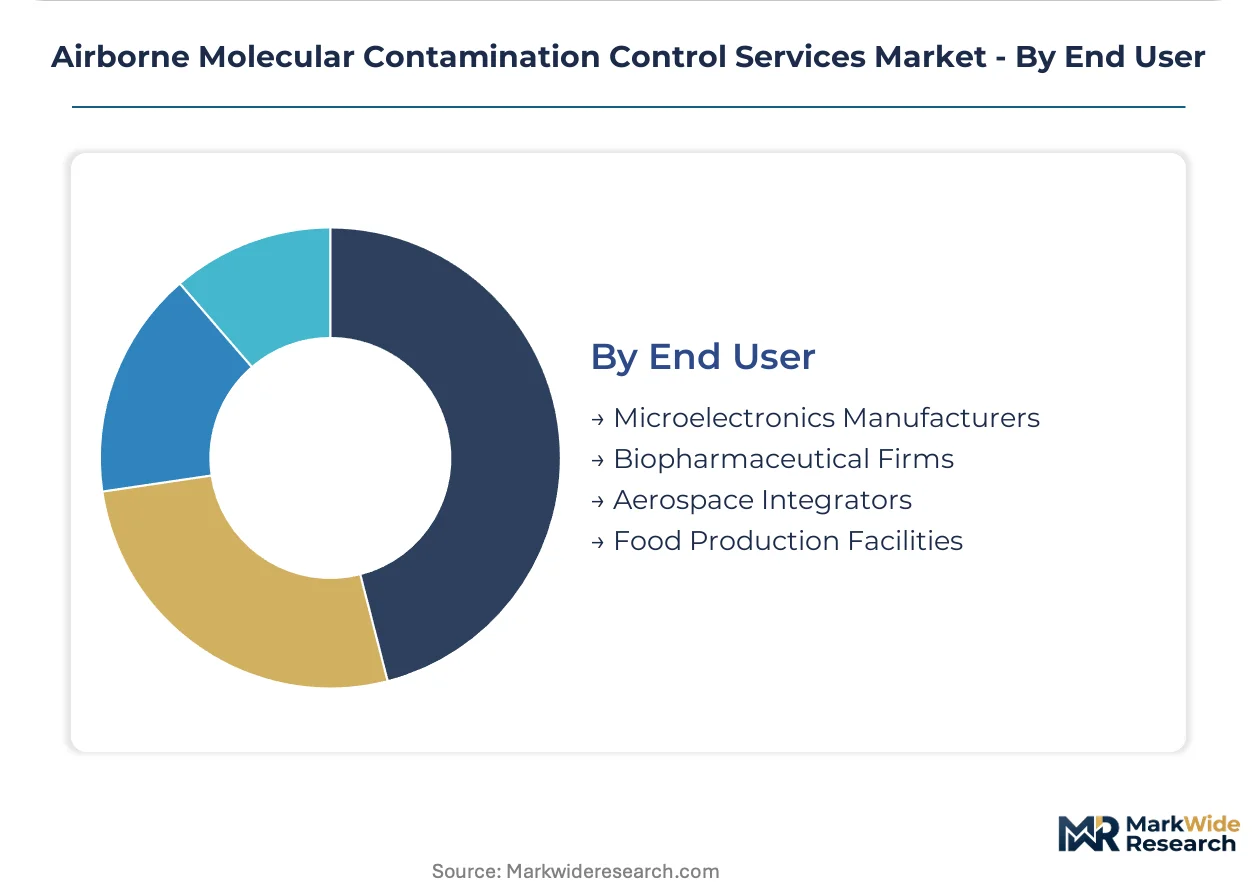
Microelectronics Manufacturers dominate contract value, while Biopharmaceutical Firms are climbing the fastest as cell therapy capacity expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized media supply chains concentrate in East Asian manufacturing corridors, creating regional dependencies that shape service provider footprints and contract negotiation leverage.
Taiwan
Foundry capital expenditure in Hsinchu and Tainan Science Parks drives concentrated demand for turnkey contamination control services within a 50-kilometer radius. The EPA Taiwan enforces semiconductor manufacturing emission standards that align with international fab qualification requirements. EUV lithography deployment at advanced nodes mandates chemisorptive media replacement cycles that triple service contract values.
South Korea
Samsung and SK Hynix are expanding domestic cleanroom infrastructure, fragmenting the AMC control services landscape across memory and logic fabrication. The MFDS regulates pharmaceutical cleanroom standards that increasingly adopt semiconductor-grade protocols. Pilot programs in Busan-Ulsan and Seoul Capital Area fabs are testing hybrid photocatalytic oxidation systems for EUV resist outgassing control.
United States
The EPA regulates hazardous air pollutant emissions from semiconductor manufacturing under National Emission Standards for Hazardous Air Pollutants, creating compliance overhead that extends service contract timelines. Arizona and Texas fab construction is accelerating demand for real-time AMC monitoring infrastructure. Intel and TSMC projects in Greater Phoenix and Austin metro areas are specifying standalone analytical contracts with penalty clauses tied to excursion response times.
Germany
The EU F-Gas Regulation phases down hydrofluorocarbon use in etching and chamber cleaning, accelerating abatement system deployments that require continuous AMC monitoring. German chemical suppliers are expanding production of non-fluorinated barrier materials ahead of REACH authorization sunset dates for per- and polyfluoroalkyl substances. Bavaria and Baden-Württemberg host precision manufacturing clusters where ISO 14644-8 compliance drives pharmaceutical cleanroom crossover demand.
Japan
METI industrial policy supports domestic semiconductor reshoring initiatives that require upgraded contamination control infrastructure. Tokyo Electron and Shin-Etsu supply chain proximity in Chubu and Kanto regions creates integrated service ecosystems. Yokohama and Osaka-based fabs are adopting unbundled AMC monitoring contracts that separate analytical services from equipment maintenance.
Airborne Molecular Contamination Control Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in filtration media and sensor hardware. The market structure consolidates around three to five full-service providers capable of delivering guaranteed yield outcomes, while numerous regional specialists compete on geographic proximity and rapid response. Two strategic archetypes dominate: integrated materials-science platforms spanning chemisorptive media through real-time analytics, and instrumentation-focused specialists with proprietary sensor networks. Competitive moves concentrate on strategic partnerships for media supply security and technology licensing for photocatalytic oxidation convergence.
Among North American instrumentation specialists, MKS Instruments and Teledyne API exemplify the hardware-software integration archetype, anchoring positions where real-time monitoring software differentiates beyond standalone sensor sales. Entegris represents the integrated materials-science platform model, leveraging filtration chemistry expertise across semiconductor fab service contracts. Camfil occupies a position within European pharmaceutical cleanroom installations where geographic proximity to regulated manufacturing clusters builds recurring maintenance relationships.
| Leading Market Players |
|---|
| Entegris |
| Camfil |
| Particle Measuring Systems |
| HORIBA |
| KLA |
| MKS Instruments |
| Teledyne API |
| Picarro |
| Process Insights |
| Others |
Pricing and Supply Chain Analysis
Activated carbon and zeolite substrate production concentrates in East Asian manufacturing corridors, anchoring margin pools in chemisorptive media replacement cycles and locking service providers into long-term supply agreements with Japanese and South Korean chemical suppliers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across the European market, with REACH authorization requirements for fluoropolymer membranes compressing margins on legacy filtration components. Pricing stratifies across premium, standard, and economy tiers based on ISO 14644-8 certification grade and real-time monitoring integration depth. Cost compression in standard-tier preventive maintenance is intensifying because foundries are unbundling monitoring from equipment service contracts. Contract development and manufacturing organizations in biopharmaceuticals exhibit highest price sensitivity, while Taiwan integrated device manufacturers prioritize excursion response guarantees over unit cost.
Supply Chain Analysis
Export control regimes on proton transfer reaction mass spectrometry hardware limit flows of analytical instrumentation from US and European manufacturers to certain end markets, fragmenting equipment availability across regional service provider networks. Taiwan, South Korea, and Japan anchor the supply base for chemisorptive media substrates and advanced filtration membranes. Service delivery draws from activated carbon impregnation facilities, zeolite synthesis plants, and UV-activated titanium dioxide catalyst production lines. Single-source vulnerability concentrates in East Asian substrate suppliers, exposing providers to allocation risk during foundry construction surges. Distribution runs through direct fab service contracts with captive technical teams and regional specialist distributors for aftermarket consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EUV lithography penetration below 3nm nodes is disrupting service contract economics, with sub-ppt contamination thresholds forcing a fundamental rewiring of how providers structure performance guarantees and capture recurring revenue.
For Market Incumbents: Build certification moats around proton transfer reaction mass spectrometry operation and ISO 14644-8 audit protocols to defend against independent analytical laboratories. Entrench through backward integration into chemisorptive media formulation, securing substrate allocation priority during supply crunches. Expand calibration and maintenance capabilities in India ahead of domestic fab construction timelines to preempt emerging competitor footholds. For New Entrants and Emerging Players: Mature fabs in Southeast Asia with 1990s-era HVAC infrastructure represent the most penetrable entry point for photocatalytic oxidation retrofit services, as brownfield modification complexity deters full-service incumbents. Pharmaceutical cleanroom crossover applications under ISO 14644-8 offer less cyclical capital spending with lower technical barriers to entry. Lead with hybrid UV-activated titanium dioxide system pilots that demonstrate volatile organic compound mineralization alongside existing gas phase filtration banks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated materials-science platforms spanning chemisorptive media through real-time analytics, as unbundling trends concentrate value in end-to-end yield guarantee providers. Long-term viability hinges on exposure to EUV lithography deployment curves and pharmaceutical regulatory convergence. Watch for foundry specification of maximum time-to-detection clauses in standalone analytical contracts as the inflection signal for monitoring service premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Photocatalytic Oxidation Convergence | Hybrid UV-activated titanium dioxide systems address EUV resist outgassing in Samsung and SK Hynix fabs. |
| Media Supply Security Partnerships | Long-term substrate agreements with East Asian chemical suppliers mitigate allocation risk during foundry expansions. |
| Real-Time Monitoring Platform Integration | Software-anchored sensor networks enable standalone analytical contracts with penalty clauses in Taiwan. |
| Pharmaceutical Cleanroom Crossover | ISO 14644-8 compliance opens adjacent revenue streams with less cyclical capital spending patterns. |
| India Semiconductor Mission Positioning | Early calibration and maintenance capability builds first-mover advantage in domestic fab construction. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fab operations directors, contamination control engineers, procurement leads at foundries, and regulatory compliance officers; and secondary validation through SEMI industry reports, EPA NESHAP filings, EU F-Gas Regulation implementation documents, and ISO 14644-8 certification databases. Bottom-up triangulation across service contract value pools and top-down cross-check against capital expenditure disclosures anchored market sizing.
Forecast inputs span technology adoption curves for EUV lithography, regulatory phase-down schedules for hydrofluorocarbons, and foundry construction pipelines across East Asian science parks. Segmentation modeling covers service type, technology category, application vertical, and end-user procurement sophistication. CAGRs were derived from weighted scenario analysis across baseline, accelerated EUV penetration, and delayed abatement deployment cases.
Practitioners should monitor REACH authorization timelines for per- and polyfluoroalkyl substances and East Asian substrate supplier capacity announcements for early signals of supply constraint. Forecasts reflect assumptions on EUV scanner installation rates and EU F-Gas quota allocation methodologies. Material shifts in fluorinated compound regulatory stringency or chemisorptive media supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Environment Control
HUD-Compatible Low-Haze Windshield Defogging Coating Systems Market
Aircraft Environment Control
Aircraft Waste Tank Market
Aircraft Environment Control
Aircraft Air Conditioning Unit Market
Aircraft Environment Control
Commercial Aircraft Air Management System Market
Aircraft Environment Control
Turbine Air Filtration Market
Aircraft Environment Control
Gas Turbine Air Filtration Market
Aircraft Environment Control
Aerospace Flight Control System Market
Aircraft Environment Control
Ice Protection Systems Market