
 Next-Generation Assault Rifles Market | 2026-2036
Next-Generation Assault Rifles Market Size, Share, and Industry Trends Forecast 2026-2036
Next-Generation Assault Rifles Market Foresight
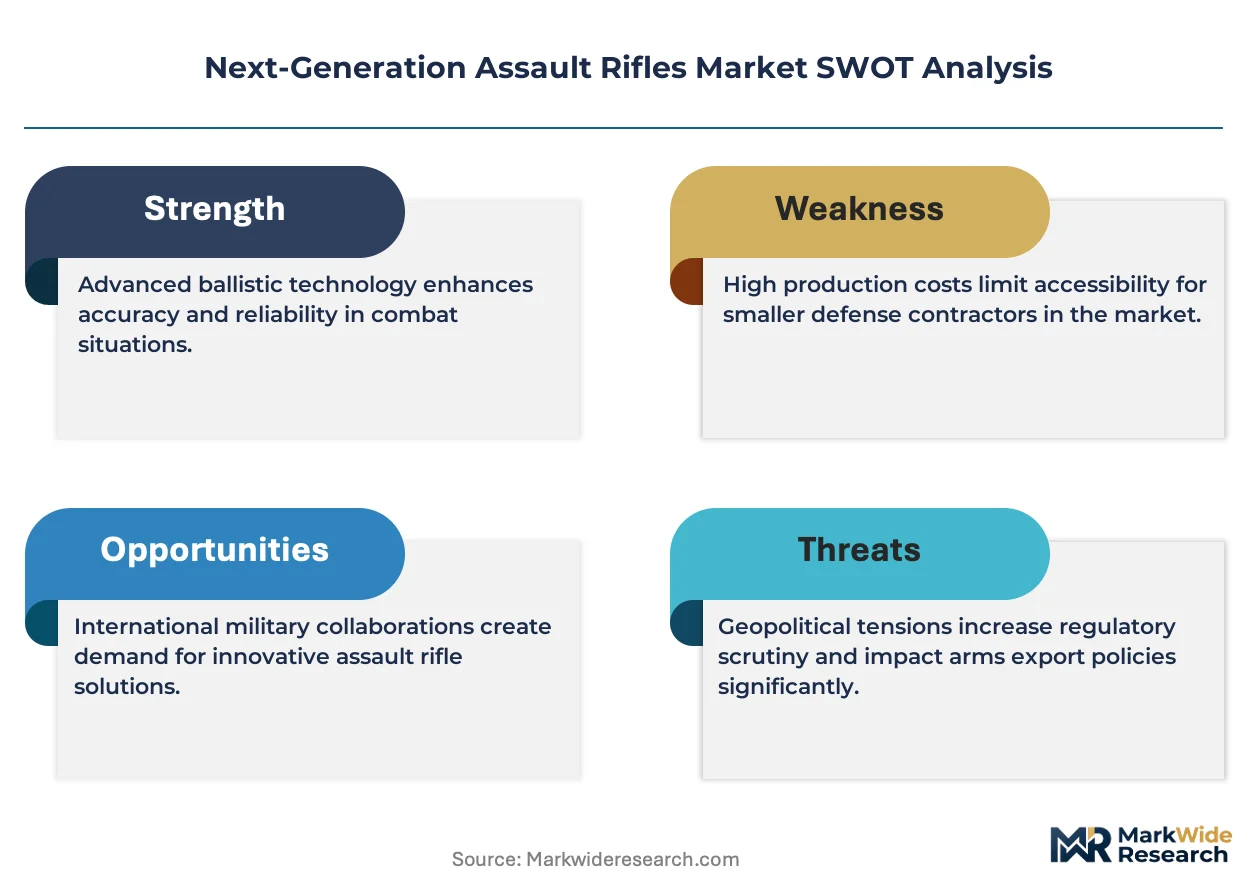
The EU Green Deal's embodied carbon tracking requirements for defense procurement is expanding compliance burdens across European suppliers. SIG Sauer leverages its vertically integrated US-German manufacturing footprint to navigate dual-jurisdiction standards. Heckler & Koch sustains R&D intensity through dedicated ballistics laboratories in Oberndorf. FN Herstal anchors NATO standardization efforts through its dominance of 5.56mm and 7.62mm platform supply chains.
Next-generation assault rifles integrate modular receiver architectures, advanced metallurgy such as nitride-treated barrels, and ambidextrous controls to accommodate diverse operational environments and ammunition types including intermediate and full-power cartridges. Their primary purpose centers on delivering sustained suppressive fire with improved reliability across extreme climates while reducing soldier load through weight-optimized materials. Modular product configurations command the widest addressable demand as militaries prioritize mission-tailorable systems over fixed-form platforms. Gas-operated technology leads installed volume though hybrid operating systems represent the fastest-growing category as manufacturers combine short-stroke pistons with adjustable gas regulation for suppressed and unsuppressed firing. Military end users absorb the dominant share of procurement value, with law enforcement representing a concentrated but lower-volume segment focused on counter-terror and specialized response units.
The US Army's NGSW program, Germany's KBA technical requirements, and Israel's Ministry of Defense tender specifications collectively dictate caliber transitions, optic integration mandates, and barrel-life benchmarks that determine market access eligibility. NATO standardization agreements and national offset rules fragment procurement pathways, forcing suppliers to maintain parallel certification tracks across jurisdictions. Stakeholders must monitor how ammunition commonality clauses and local-content thresholds in US, German, and Israeli tenders reshape manufacturing location decisions and partnership structures.
Market Dynamics
Modular weapon architectures are compressing platform replacement cycles as NATO special operations forces demand caliber-interchangeable systems for multi-mission flexibility. The US Army's Next Generation Squad Weapon program and Germany's KBA technical specifications are forcing suppliers to engineer dual-jurisdiction compliance into single product lines.
Growth Catalysts
- Intermediate Cartridge Mandates:The US Army's NGSW program is accelerating adoption of 6.8mm ammunition standards. Special operations units across NATO member states are issuing requirements for ammunition commonality clauses in tender specifications.
- EU Green Deal Embodied Carbon Tracking:Defense procurement compliance burdens are expanding across European suppliers. Manufacturers with vertically integrated US-German production footprints are navigating dual-jurisdiction environmental standards more efficiently than single-site competitors.
- Gas-Regulation Technology Maturation:Hybrid operating systems combining short-stroke pistons with adjustable gas regulation are enabling suppressed and unsuppressed firing from identical platforms. Law enforcement counter-terror units are driving initial procurement of these configurations.
Market Restraints
- Nitride-Treated Barrel Input Concentration:Advanced metallurgy supply chains concentrate among specialized Austrian and Swiss thermal processing facilities. Disruption to these inputs would cascade through European and Israeli manufacturing schedules.
- Offset Rule Fragmentation:National local-content thresholds in US, German, and Israeli tenders force suppliers to maintain parallel certification tracks. This structural friction elevates fixed compliance costs for mid-scale manufacturers.
- Optic Integration Mandate Complexity:KBA and Israeli Ministry of Defense tender specifications dictate proprietary rail interfaces and electronic sighting system protocols. Non-compliant platforms face automatic disqualification regardless of ballistic performance.
Strategic Opportunities
- Law Enforcement Channel Expansion:Specialized response units in France, Belgium, and the Netherlands are emerging as concentrated buyers for compact modular configurations. These units prioritize mission-tailorable systems over standard-issue military platforms.
- REACH-Compliant Surface Treatment Innovation:European suppliers developing hexavalent chromium alternatives for barrel finishing are positioning for preferential procurement status. The EU Green Deal's defense procurement extensions create first-mover advantages in sustainable metallurgy.
- Ambidextrous Control Retrofit Kits:Legacy platform upgrade demand from NATO reserve forces represents underpenetrated aftermarket volume. Manufacturers with modular receiver architectures can capture this without full-system replacement cycles.
Industry Challenges
- Ballistics Laboratory Talent Scarcity:Specialized R&D functions requiring combined materials science and terminal ballistics expertise concentrate in Oberndorf and southern Germany. Recruitment competition among Heckler & Koch, SIG Sauer, and emerging competitors is compressing salary structures.
- Multi-Jurisdiction Certification Timeline Compression:Simultaneous US Army, KBA, and Israeli Ministry of Defense qualification tracks require dedicated regulatory affairs teams. Smaller manufacturers face 18-24 month delays between prototype completion and tender eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next-Generation Assault Rifles Market |
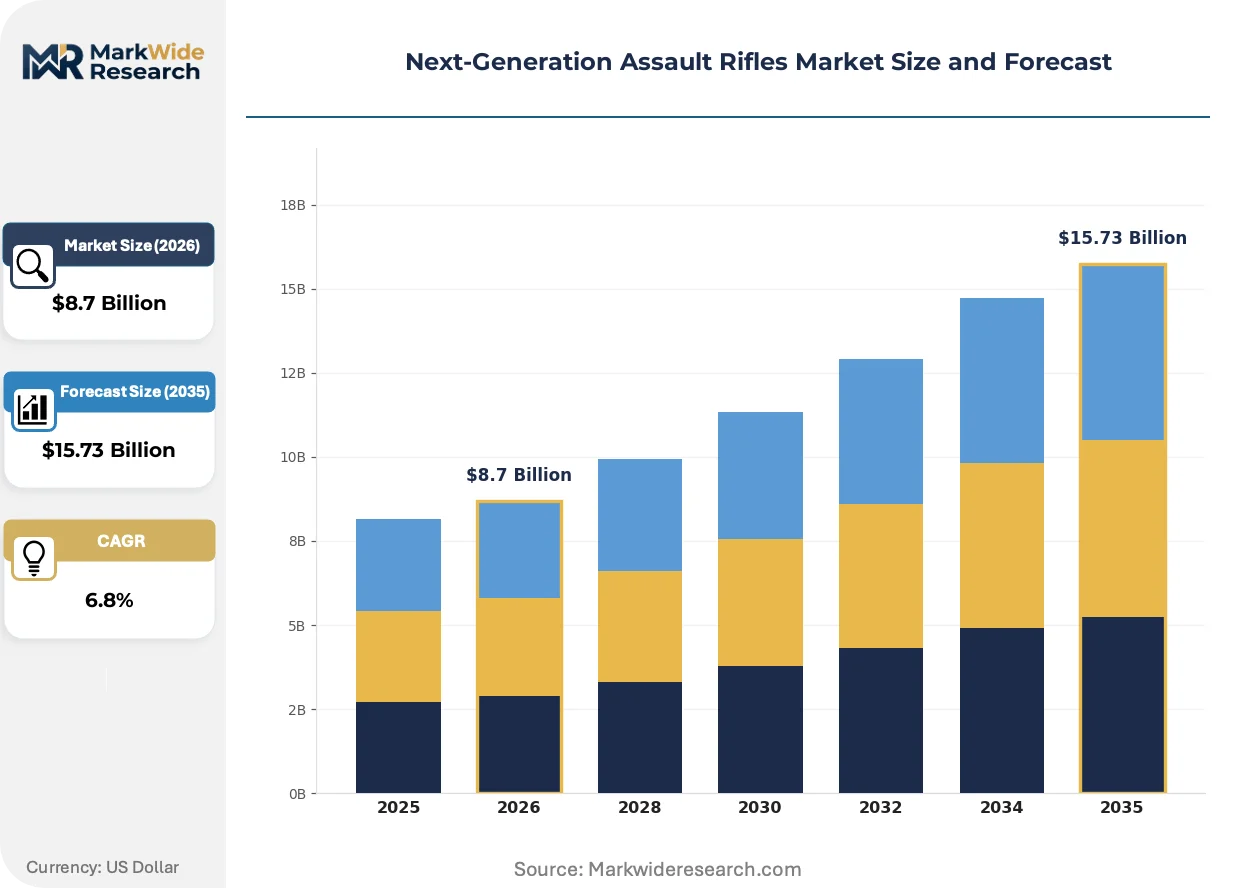
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Bullpup, Conventional, DMR Technology: Gas-Operated, Blowback, Recoil-Operated, Hybrid End User: Military, Law Enforcement, Private Security, Civilian Accessory Type: Sights, Grips, Suppressors, Magazines |
| Companies Covered | SIG Sauer, General Dynamics Ordnance and Tactical Systems, Textron Systems, Heckler & Koch, FN Herstal, Kalashnikov Concern, Israel Weapon Industries, Colt Manufacturing, Norinco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next-Generation Assault Rifles Market Shifts & Advancements
Additive manufacturing of titanium receiver components is converging with traditional forging methods to reshape production economics. Defense procurement officers are rewriting technical specifications to accommodate hybrid-manufactured platforms without compromising fatigue-life benchmarks.
Hybrid operating systems are converging with suppressor-integrated barrel designs to eliminate gas-blowback in close-quarters configurations. Special operations forces in Germany and Israel are field-testing these combinations for counter-terror applications. The structural consequence is collapsing demand for separate suppressed and unsuppressed weapon assignments within single units.
The EU Green Deal's embodied carbon tracking requirements are extending into defense procurement frameworks. European suppliers must now document cradle-to-gate emissions for nitride-treated barrels and polymer furniture components. German and Belgian manufacturers with captive thermal processing facilities are responding faster than competitors dependent on outsourced surface treatment.
Buyer concentration among NATO special operations procurement cells is compressing vendor evaluation cycles. Traditional multi-year trials are contracting to 12-18 month competitive shoots. Israeli and US special mission units are driving this acceleration through emergency operational requirements that bypass standard acquisition timelines.
Next-Generation Assault Rifles Market Segmentation
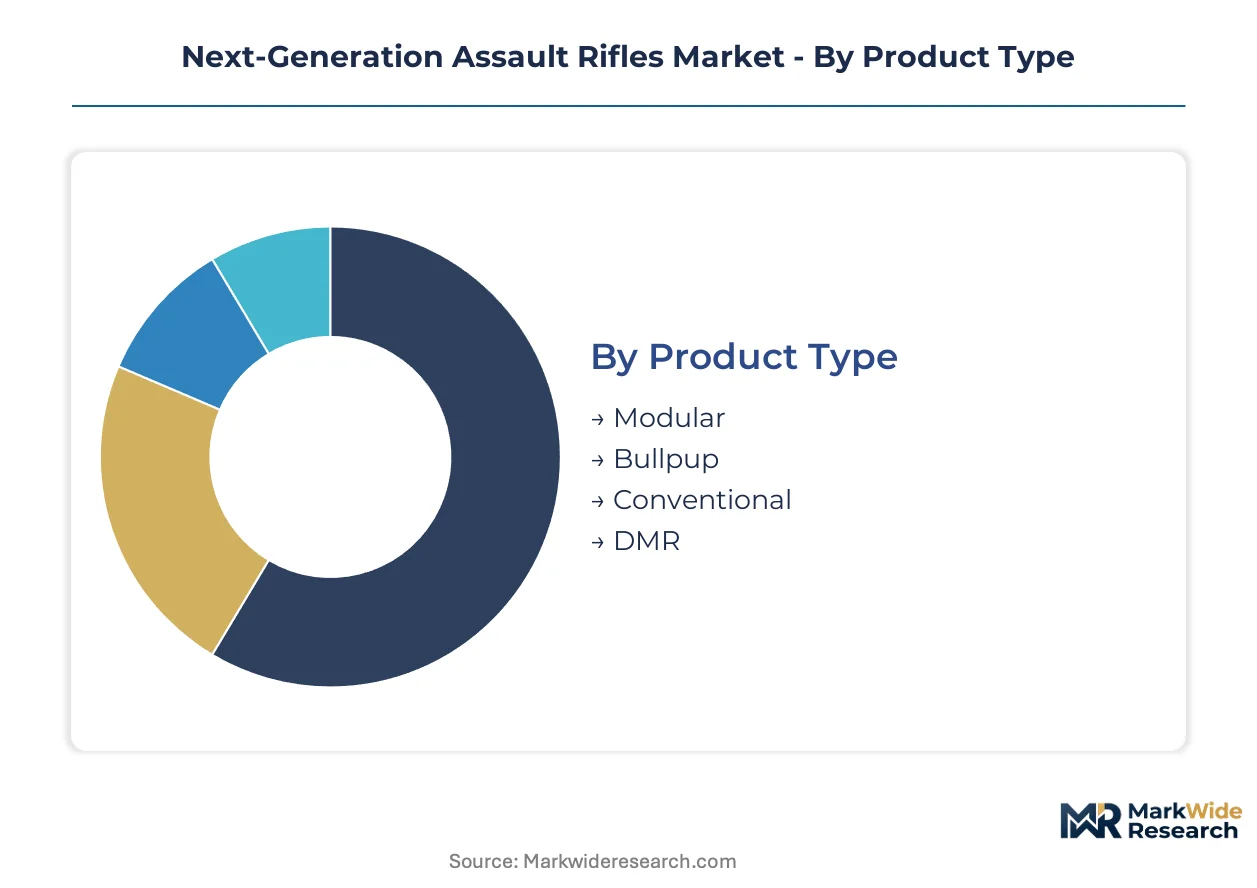
Segmentation in next-generation assault rifles determines which procurement channels manufacturers can access. NATO standardization agreements and national certification tracks create divergent compliance pathways for each product configuration.
Product Type:
KBA technical specifications and Israeli Ministry of Defense tender requirements impose distinct barrel-life benchmarks and rail interface standards on each configuration.
- Modular:Interchangeable receiver architectures accommodate multiple calibers through barrel and bolt carrier swaps. US Army NGSW program specifications and German special operations procurement cells are concentrating demand here for multi-mission flexibility.
- Conventional:Fixed-form platforms with traditional buffer tube assemblies dominate NATO reserve force inventories. These systems face replacement pressure from modular alternatives in frontline units across the United States and Israel.
- Bullpup:Compact configurations with rear-mounted action reduce overall weapon length for vehicle crews.
- DMR:Designated marksman rifles bridge assault rifle portability with precision engagement capability.
Modular sits at the top of the volume ranking, with DMR climbing the fastest.
Technology:
Operating system selection directly impacts suppressor compatibility and maintenance intervals in field conditions.
- Gas-Operated:Short-stroke piston and direct impingement variants deliver proven reliability across extreme climates. Military end users in Germany and the United States absorb dominant procurement volume for these established configurations.
- Hybrid:Adjustable gas regulation combined with short-stroke pistons enables seamless transition between suppressed and unsuppressed firing. Law enforcement counter-terror units in France and Belgium are driving initial adoption of these systems.
- Blowback:Simple operating mechanism suits compact submachine gun derivatives and training platforms.
- Recoil-Operated:Delayed blowback and roller-locking systems persist in legacy platform support.
Gas-Operated retains the largest installed base, though Hybrid is gaining share fastest among new procurements.
End User:
Customer type dictates pricing tolerance, certification stringency, and accessory integration mandates.
- Military:National defense ministries impose the most rigorous ballistics laboratory testing and environmental qualification protocols. Procurement concentrates in the United States, Germany, and Israel with indigenous manufacturing preferences.
- Law Enforcement:Specialized response units prioritize compact modular configurations for counter-terror applications. French RAID and Belgian DSU units represent concentrated demand clusters within this segment.
- Private Security:Executive protection details and maritime security contractors operate under less restrictive procurement frameworks.
- Civilian:Sporting and collector markets face jurisdiction-specific restrictions on barrel length and selective-fire capability.
Military accounts for the dominant procurement value, with Law Enforcement expanding most quickly in absolute terms.
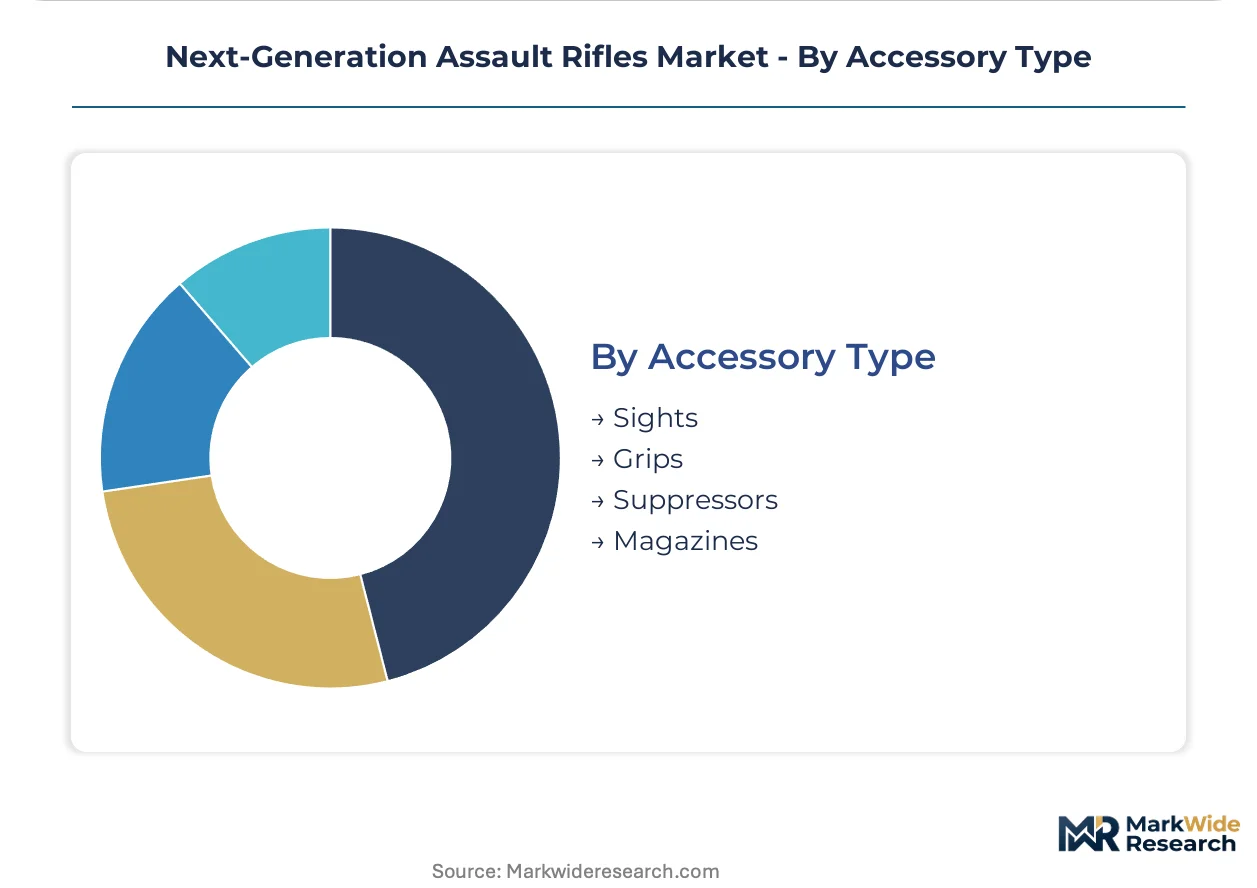
Accessory Type:
Integration standards vary sharply between NATO STANAG agreements and national proprietary specifications.
- Sights:Electronic optical systems and magnified optics require alignment with KBA rail interface mandates and Israeli Ministry of Defense electronic sighting protocols. Non-compliant mounting systems trigger automatic tender disqualification regardless of ballistic performance.
- Suppressors:Quick-detach mounting systems and flow-through designs are collapsing demand for separate suppressed weapon assignments in German and Israeli special operations units.
- Grips:Ergonomic furniture with ambidextrous control accommodation supports modular platform retrofit demand.
- Magazines:Polymer and steel feed devices must satisfy ammunition commonality clauses in multi-national tender specifications.
Sights command the highest unit value, with Suppressors showing the steepest expansion trajectory as integrated designs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ballistics laboratory talent concentrates in southern Germany, anchoring European small arms innovation. Israeli special operations procurement cells and US Army acquisition commands shape dual-hemisphere demand patterns. Industrial clusters in Oberndorf, Oberland, and Hartford sustain specialized manufacturing capabilities.
United States
The US Army's Next Generation Squad Weapon program drives intermediate cartridge standardization at Picatinny Arsenal. Pentagon acquisition reform accelerates vendor evaluation cycles from multi-year trials to 12-18 month competitive shoots. Connecticut's Precision Valley cluster around Hartford sustains legacy machining expertise alongside additive manufacturing adoption.
Germany
KBA technical specifications dictate barrel-life benchmarks and rail interface standards for NATO-aligned procurements. The EU Green Deal's embodied carbon tracking extends compliance burdens to defense procurement frameworks. Oberndorf am Neckar hosts concentrated ballistics R&D functions requiring combined materials science and terminal ballistics expertise.
Israel
Israeli Ministry of Defense tender specifications mandate proprietary optic integration protocols and electronic sighting system standards. Emergency operational requirements from special mission units bypass standard acquisition timelines. Tel Aviv-area defense contractors specialize in compact modular configurations for counter-terror applications.
Belgium
DSU specialized response units drive concentrated demand for hybrid operating systems with adjustable gas regulation. NATO standardization agreements position Belgian manufacturers as 5.56mm and 7.62mm platform supply chain anchors. Herstal maintains dedicated regulatory affairs teams navigating simultaneous US, German, and Israeli qualification tracks.
Switzerland
Thermal processing facilities in specialized Austrian and Swiss locations concentrate nitride-treated barrel supply chains. REACH-compliant surface treatment innovation creates first-mover positioning for hexavalent chromium alternatives. Swiss-German border regions sustain captive metallurgy capabilities responding faster than outsourced competitors.
Next-Generation Assault Rifles Market Competitive Landscape
Capital-heavy producers with captive forging and thermal processing facilities compete with asset-light designers dependent on outsourced precision manufacturing. The vendor base concentrates around vertically integrated specialists maintaining dual-jurisdiction US-European production footprints. Three archetypes dominate: integrated transatlantic manufacturers, regional champions with national offset compliance, and state-affiliated conglomerates with captive demand. Competitive moves center on backward integration into metallurgy supply and parallel certification track maintenance across US Army, KBA, and Israeli Ministry of Defense qualification protocols.
Within the transatlantic integrated tier, SIG Sauer exemplifies dual-jurisdiction manufacturing architecture spanning US and German facilities. Heckler & Koch anchors the regional specialist archetype through Oberndorf-based ballistics laboratory concentration. FN Herstal occupies a position as NATO standardization infrastructure, leveraging Belgian location for 5.56mm and 7.62mm platform supply chain dominance.
| Leading Market Players |
|---|
| SIG Sauer |
| General Dynamics Ordnance and Tactical Systems |
| Textron Systems |
| Heckler & Koch |
| FN Herstal |
| Kalashnikov Concern |
| Israel Weapon Industries |
| Colt Manufacturing |
| Norinco |
| Others |
Supply & Pricing Matrix
Sovereign-backed producers with state-captive demand and family-owned mid-caps with Oberndorf heritage anchor supply discipline across the next-generation assault rifles market. Their divergent financing structures generate distinct pricing behaviors: state-affiliated manufacturers absorb qualification cost amortization through offset guarantees, while private specialists extract premiums through dual-jurisdiction certification maintenance.
Pricing Analysis
Bundled platform-plus-optic configurations command substantial premiums over unbundled weapon-only procurement. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified systems with proprietary rail interfaces from NATO STANAG-compliant alternatives and legacy reserve-force refits. Pricing pressure stems from compressed vendor evaluation cycles at US Army acquisition commands, which compress 18-24 month qualification timelines into 12-18 month competitive shoots. Military end users exhibit lowest price sensitivity due to indigenous manufacturing mandates, while law enforcement counter-terror units in France and Belgium demonstrate acute cost consciousness for compact modular configurations.
Supply Chain Analysis
Dual-sourcing requirements embedded in US Army, KBA, and Israeli Ministry of Defense tender specifications force buyers to qualify secondary metallurgy suppliers for nitride-treated barrel inputs. Geographic supply concentration centers on Austria and Switzerland for thermal processing capabilities, Germany for ballistics laboratory R&D functions, and the United States for additive manufacturing of titanium receiver components. Raw material dependencies encompass specialized alloy steels for barrel blanks, polymer compounds for furniture, and rare-earth elements for electronic sighting systems. Single-source vulnerability concentrates in Oberndorf-area thermal processing facilities, where disruption would cascade through European and Israeli manufacturing schedules. Distribution runs through national defense procurement cells with direct-to-military contracting, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in next-generation assault rifles rests on REACH-compliant surface treatment innovation, where first-movers in hexavalent chromium alternatives capture preferential procurement status under EU Green Deal defense extensions.
For Market Incumbents: Deepen captive metallurgy capabilities through backward integration into nitride-treatment facilities, mirroring SIG Sauer's US-German vertical footprint. Defend against asset-light designers by accelerating parallel certification track maintenance across US Army NGSW, KBA, and Israeli Ministry of Defense protocols. Prioritize ambidextrous control retrofit kits for NATO reserve force aftermarket capture without full-system replacement cycles. For New Entrants and Emerging Players: Begin with law enforcement channel expansion in French RAID and Belgian DSU specialized response units, where compact modular configurations face less stringent ballistics laboratory qualification than military tenders. Target REACH-compliant surface treatment innovation as regulatory arbitrage against established competitors dependent on hexavalent chromium finishing. Pursue partnership structures with Israeli Tel Aviv-area contractors for compact counter-terror platform co-development. For Investors and Strategic Acquirers: Valuations sit cheapest among regional champions with single-jurisdiction certification exposure facing 18-24 month delays to tender eligibility. Long-term viability favors integrated transatlantic manufacturers with dual US-European production footprints capable of navigating offset rule fragmentation. Monitor ammunition commonality clause adoption across NATO special operations procurement cells as inflection indicator for caliber-transition winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Processing | Captive nitride-treatment facilities at Oberndorf and Swiss-German border regions eliminate Austrian-Swiss input concentration risk. |
| Parallel Certification Track Investment | Simultaneous US Army NGSW, KBA, and Israeli Ministry of Defense qualification compresses time-to-tender from 24 months to 12-18 months. |
| REACH-Compliant Surface Treatment Development | Hexavalent chromium alternatives position suppliers for EU Green Deal preferential procurement status in defense tenders. |
| Law Enforcement Channel Expansion | French RAID and Belgian DSU units represent concentrated demand clusters with faster procurement cycles than military ministries. |
| Ambidextrous Retrofit Kit Commercialization | Modular receiver architectures capture NATO reserve force aftermarket volume without full platform replacement investment. |
Research Methodology
Direct dialogue with defense procurement officers at national ministries, ballistics laboratory directors in southern Germany, regulatory affairs leads navigating KBA and Israeli Ministry of Defense protocols, and specialized response unit commanders in France and Belgium grounded qualitative findings. Secondary validation drew from NATO standardization agreement documentation, EU Green Deal defense procurement extension filings, US Army NGSW program specifications at Picatinny Arsenal, and tender databases tracking ammunition commonality clause adoption. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis across the analysis window.
Bottom-up modeling aggregated procurement volume by product type, technology, end user, and accessory configuration, with cross-validation against national defense expenditure patterns. Segmentation dimensions encompassed modular versus conventional versus bullpup versus DMR architectures, gas-operated versus hybrid versus blowback operating systems, and military versus law enforcement versus private security demand channels. CAGRs derived from slope-intercept analysis of disclosed procurement timelines and announced program acceleration schedules, with sensitivity testing around barrel-life benchmark revisions and optic integration mandate complexity.
Caveats apply where intermediate cartridge standardization delays, nitride-treated barrel input disruption, or REACH compliance timeline extensions could materially shift the outlook. Deviation in US Army NGSW program fielding schedules or KBA technical specification revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Asia-Pacific Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ammunition Belt Market
Weapons and Ammunition
Enclosed Smokeless Flares Market
Weapons and Ammunition
Middle East and North Africa Perforating Gun Market
Weapons and Ammunition
Artillery Ammunition Market
Weapons and Ammunition
Europe Medium and Large Caliber Ammunition Market
Weapons and Ammunition
NIJ III Ballistic Bullet Resistant Panel Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Military Airborne Laser Market
Weapons and Ammunition
North America Nuclear Bombs and Missiles Market
Weapons and Ammunition
Ballistic Protection Market
Weapons and Ammunition
Global Shoulder-Fired Weapons Market
Weapons and Ammunition
Detonator Market
Weapons and Ammunition
Weapons Release System Market
Weapons and Ammunition
Americas Medium and Large Caliber Ammunition Market
Weapons and Ammunition
Mortar Ammunition Market