
 Crashworthy Aircraft Seats Market | 2026-2036
Crashworthy Aircraft Seats Market Size, Share, and Industry Trends Forecast 2026-2036
Crashworthy Aircraft Seats Market Analysis
EASA's updated CS-25.561 dynamic injury criteria is shifting procurement specifications toward advanced energy-absorbing designs. Collins Aerospace leverages its integrated avionics-to-seating platform to sustain long-term military contracts. Martin-Baker Aircraft Co. Ltd anchors its position through specialized ejection and crashworthy seat heritage spanning fixed-wing and rotorcraft applications. RTX Corporation differentiates via backward integration into composite energy-absorption structures for next-generation combat platforms.
Crashworthy aircraft seats are engineered occupant protection systems designed to limit spinal loading and pelvic acceleration during controlled and uncontrolled impact events, typically incorporating stroking mechanisms, composite crush structures, and multi-point restraint architectures rated to 14-16g dynamic pulses. Their primary purpose is to reduce fatal and serious injuries in survivable crashes across military, commercial, and emergency aviation operations. Aluminum and composite material segments dominate current procurement volumes, with composite formulations representing the fastest-growing category as specific strength targets tighten under updated military specification MIL-S-58095. Military aircraft type applications command the deepest margin pools due to extended qualification cycles and sole-source contracting patterns, while commercial jet retrofits remain volume-constrained by fleet replacement timing.
FAA Part 25.561 and 25.562, EASA CS-25, and ISO 9529 establish the regulatory baseline for seat dynamic performance, flammability, and occupant restraint integration, with each framework periodically tightening g-load thresholds and head injury criteria. Military buyers reference MIL-STD-1290 and specific platform technical requirements that exceed civil thresholds, creating a bifurcated compliance landscape. Stakeholders must monitor evolving rotorcraft crash resistance mandates from the US Army Aviation and Missile Command and parallel European defense procurement directives that will reshape qualification investments and supplier eligibility.
Market Dynamics
The collision between tightening FAA and EASA dynamic injury thresholds and the military's push for lighter composite energy-absorption structures is compressing supplier qualification timelines while fragmenting procurement specifications across defense and commercial channels.
Growth Catalysts
- MIL-S-58095 Composite Adoption:Updated military specifications for specific strength targets are pulling aluminum-to-composite substitutions in next-generation rotorcraft seat platforms.
- NATO Helicopter Modernization:Multi-year procurement cycles across member defense ministries are sustaining replacement demand for energy-absorbing crew and troop seat systems.
- CS-25.561 Amendment:EASA's tightened dynamic injury criteria is forcing commercial retrofit specifications toward advanced stroking mechanisms and multi-point restraint architectures.
Market Restraints
- Titanium and Carbon Fiber Cost Volatility:Raw material price swings for aerospace-grade composites compress margin predictability during multi-year military contract periods.
- Extended Qualification Cycles:FAA Part 25.562 and MIL-STD-1290 testing protocols create 18-36 month certification barriers that freeze out new entrants.
- Legacy Fleet Replacement Timing:Commercial jet seat retrofits remain tethered to airframe heavy maintenance intervals, decoupling demand from standalone safety upgrades.
Strategic Opportunities
- Unmanned Aerial System Integration:Crewed-uncrewed teaming architectures in US Army Aviation Command programs are opening specifications for crashworthy remote operator stations.
- Urban Air Mobility Certification:Emerging eVTOL platforms under FAA Special Class airworthiness rules present first-mover positioning for 16g-rated seat suppliers.
- ISO 9529 Harmonization:Convergence between civil and military dynamic testing standards is reducing dual-certification overhead for cross-sector suppliers.
Industry Challenges
- Spinal Biomechanics Modeling Talent Scarcity:Finite element analysis expertise for occupant injury prediction remains concentrated among a handful of specialized engineering consultancies.
- Legacy Airframe Integration Friction:Retrofitting energy-absorbing stroking mechanisms into existing seat rails requires structural modification approvals that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crashworthy Aircraft Seats Market |
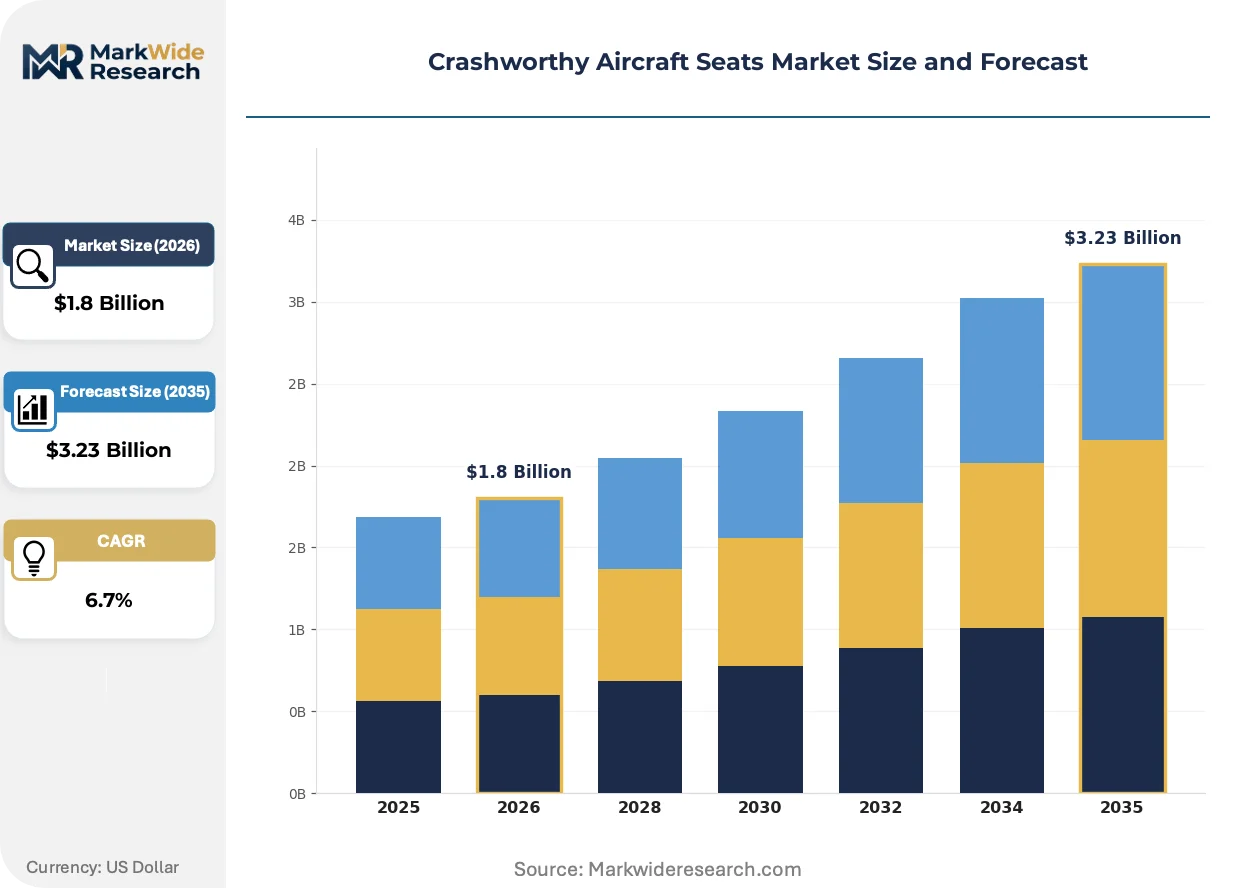
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seat Type: Standard Seats, Reclining Seats, Lounge Seats, Pilot Seats Material: Aluminum, Composite, Steel, Fabric Aircraft Type: Commercial Jets, Military Aircraft, Private Jets, Helicopters Safety Features: Crash Cushions, Restraint Systems, Energy-Absorbing Frames, Fire-Resistant Materials |
| Companies Covered | RTX Corporation, AUTOFLUG GmbH, Martin-Baker Aircraft Co. Ltd, East/West Industries, Inc., MBA S.A., Collins Aerospace, Israel Aerospace Industries Ltd., Safe, Inc., BAE Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crashworthy Aircraft Seats Market Emerging Trajectories
Active research into magnetorheological and electrorheological damping fluids is collapsing the trade-off between seat weight and energy absorption capacity, while digital thread integration is compressing design-to-test cycles across military and civil programs.
Modular composite crush structures with tunable stroke characteristics are modularizing the traditional monolithic seat frame architecture. US Army rotorcraft program offices are piloting these configurations in Black Hawk and Chinook modernization tranches. The approach is modularizing supplier ecosystems by decoupling energy-absorption module vendors from final seat assembly integrators.
REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent alternatives and plasma electrolytic oxidation for seat frame corrosion protection. European suppliers face 12-18 month requalification cycles for affected military contracts. The commercial retrofit segment is absorbing compliance costs faster than defense channels due to shorter procurement decision chains.
Performance-based sustainment contracts are displacing traditional spares-and-repair purchasing in NATO defense aviation. Military buyers now contract for fleet availability metrics rather than discrete seat unit volumes. This shift is most pronounced in UK Ministry of Defence helicopter support frameworks and parallel US Navy rotorcraft logistics contracts.
Crashworthy Aircraft Seats Market Segmentation
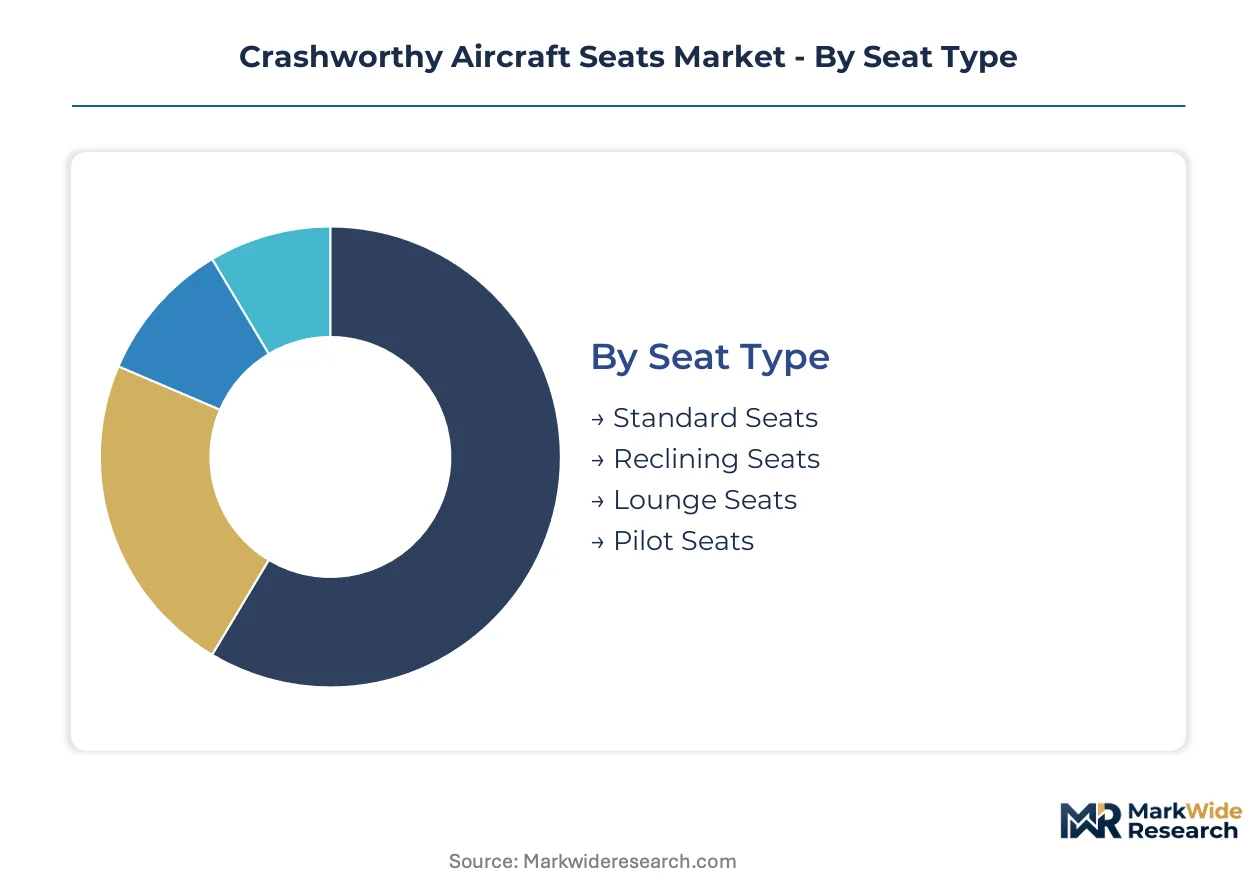
Procurement specifications for crashworthy aircraft seats fragment across defense and commercial channels, with material chemistry and aircraft platform requirements driving divergent qualification investments. Suppliers must navigate distinct regulatory baselines while managing composite material qualification costs against aluminum legacy volumes.
Seat Type:
Supply concentrates with specialized military contractors for high-performance pilot configurations, while commercial retrofits sustain standardized seating volumes through fleet maintenance cycles.
- Standard Seats:Fixed-back configurations dominate troop transport and commercial economy cabins, with procurement tied to FAA Part 25.562 16g dynamic testing protocols. US Army rotorcraft programs absorb the majority of military standard seat volumes through Black Hawk and Chinook modernization.
- Pilot Seats:Energy-absorbing stroking mechanisms with integrated restraint architectures command extended qualification cycles under MIL-STD-1290. NATO helicopter procurement across Germany, France, and the United Kingdom prioritizes these configurations for crew protection.
- Reclining Seats:Mechanisms must balance occupant comfort against crashworthiness integrity during longitudinal deceleration events.
- Lounge Seats:Premium cabin configurations face EASA CS-25.561 head injury criteria compliance challenges for non-forward-facing orientations.
Pilot seats absorb the bulk of installed capacity; standard seats are expanding most quickly across commercial retrofit programs.
Material:
Cost tiers separate aerospace-grade aluminum legacy supply from emerging composite formulations targeting specific strength thresholds under updated military specifications.
- Composite:Carbon fiber reinforced polymer crush structures achieve weight reductions critical for next-generation combat platforms. US Navy rotorcraft programs and UK Ministry of Defence procurement frameworks are accelerating aluminum-to-composite substitutions.
- Aluminum:7075-T6 and 2024-T3 alloys retain cost advantages for high-volume commercial retrofits and legacy military spares. REACH restrictions on hexavalent chromium surface treatments are forcing European suppliers into 12-18 month requalification cycles.
- Steel:High-strength alloy frames persist in ejection seat applications requiring extreme g-load tolerance.
- Fabric:Fire-blocking layer assemblies must meet FAA flammability standards while managing wear resistance in high-cycle operations.
Aluminum retains the deepest volume base; composite formulations are climbing the fastest as specific strength targets tighten.
Aircraft Type:
Application requirements diverge sharply between civil certification timelines and military sole-source contracting patterns that freeze out new entrants.
- Military Aircraft:Fixed-wing and rotorcraft platforms reference MIL-S-58095 for energy-absorption performance, with procurement concentrated in US Army Aviation and Missile Command programs. Performance-based sustainment contracts now displace discrete unit purchasing across NATO defense ministries.
- Helicopters:Vertical flight dynamics impose unique spinal loading profiles addressed through stroking seat mechanisms. US Black Hawk and Chinook fleets, plus European NH90 programs, sustain replacement demand for crew and troop seat systems.
- Commercial Jets:Retrofit timing remains tethered to airframe heavy maintenance intervals rather than standalone safety upgrades.
- Private Jets:Custom configurations face compressed qualification timelines under FAA Special Class airworthiness rules for emerging eVTOL platforms.
Military aircraft anchor supplier revenue; helicopters are gaining share fastest through NATO modernization cycles.
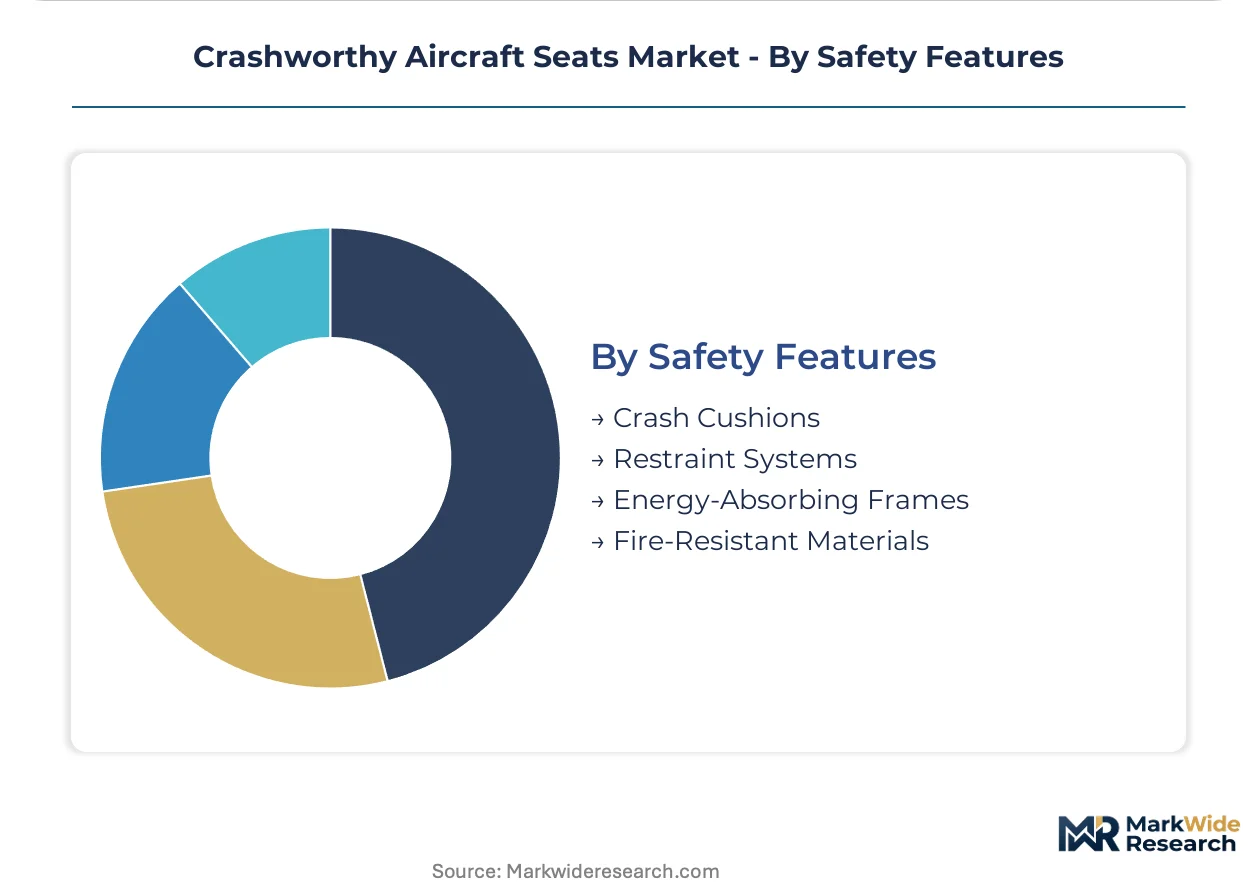
Safety Features:
Customer type separates defense buyers demanding integrated multi-point restraints from commercial operators prioritizing fire-blocking compliance.
- Energy-Absorbing Frames:Composite crush structures with tunable stroke characteristics are modularizing traditional monolithic seat architectures. US Army rotorcraft program offices are piloting these configurations to decouple energy-absorption module vendors from final assembly integrators.
- Restraint Systems:Four-point and five-point harness architectures rated to 14-16g dynamic pulses are mandatory for military crew positions. EASA's tightened CS-25.561 injury criteria are forcing commercial specifications toward advanced multi-point configurations.
- Crash Cushions:Foam and inflatable systems supplement primary stroking mechanisms in troop transport applications.
- Fire-Resistant Materials:Fire-blocking fabric layers and thermal barriers must meet FAA Part 25.853 flammability requirements while managing toxicity emission profiles.
Energy-absorbing frames command the deepest engineering investment; restraint systems are seeing the steepest specification upgrades across civil and military channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of crashworthy aircraft seats concentrates in defense aerospace clusters across the United States, Germany, and the United Kingdom, while consumption patterns track NATO helicopter modernization cycles and FAA-mandated commercial retrofit timelines.
United States
US Army Aviation and Missile Command programs drive sustained demand for Black Hawk and Chinook crew seat replacements. FAA Part 25.562 and MIL-STD-1290 testing protocols anchor qualification requirements for domestic suppliers. The Dallas-Fort Worth aerospace corridor hosts integrated seating-to-avionics manufacturing operations serving both military and commercial channels.
Germany
Bundeswehr NH90 helicopter procurement and Eurofighter sustainment contracts sustain energy-absorbing seat volumes. EASA CS-25.561 amendments impose tightened dynamic injury criteria on German-registered commercial fleets. The Bavarian aerospace cluster around Munich anchors composite energy-absorption structure development for next-generation combat platforms.
United Kingdom
UK Ministry of Defence performance-based sustainment contracts displace discrete seat purchasing across helicopter support frameworks. REACH restrictions on hexavalent chromium surface treatments force 12-18 month requalification cycles for domestic suppliers. The South West England aerospace corridor around Bristol concentrates ejection seat heritage manufacturing and specialized military seating integration.
France
DGA procurement directives for Rafale and Caracal platforms maintain demand for high-g-rated pilot configurations. ANSM and EASA jointly oversee civil-military dual-use certification pathways for seat suppliers. The Toulouse aerospace cluster houses integrated seating development programs tied to Airbus commercial and military rotorcraft divisions.
Israel
Israel Defense Forces rotorcraft modernization and fixed-wing platform upgrades sustain specialized crashworthy seat demand. Israeli national aviation regulator mandates exceed baseline FAA thresholds for occupant protection in military applications. The Haifa metropolitan area concentrates defense electronics-to-seating integration capabilities serving domestic and export markets.
Crashworthy Aircraft Seats Market Vendor Landscape
The competitive structure tilts toward integrated defense contractors with multi-decade platform relationships. Consolidation around sole-source military contracting patterns has frozen out new entrants, while commercial retrofit channels sustain standardized seating volumes through fleet maintenance cycles. Two strategic archetypes dominate: vertically integrated avionics-to-seating platforms and specialized ejection seat heritage manufacturers. Competitive moves center on backward integration into composite energy-absorption structures and performance-based sustainment contract capture.
Among defense-integrated conglomerates, RTX Corporation and BAE Systems exemplify the avionics-to-seating platform archetype, leveraging captive supply chains for composite structures. AUTOFLUG GmbH represents the specialized European tier, occupying a position within German-centric NATO procurement frameworks. Martin-Baker Aircraft Co. Ltd anchors the ejection seat heritage segment, with its UK-based operations exemplifying decades-long military qualification continuity across fixed-wing and rotorcraft applications.
| Leading Market Players |
|---|
| RTX Corporation |
| AUTOFLUG GmbH |
| Martin-Baker Aircraft Co. Ltd |
| East/West Industries, Inc. |
| MBA S.A. |
| Collins Aerospace |
| Israel Aerospace Industries Ltd. |
| Safe, Inc. |
| BAE Systems |
| Others |
Supply Flow & Price Mechanics
Finite element analysis expertise concentrated in the Dallas-Fort Worth aerospace corridor and South West England propels labor-cost differentials that widen pricing spreads between MIL-STD-1290 certified pilot configurations and commercial retrofit standard seats.
Pricing Analysis
Margin tightening in commercial retrofit tiers traces to fleet maintenance interval timing that decouples demand from standalone safety upgrades. Three-tier pricing structure across premium, standard, and economy levels separates MIL-S-58095 composite platforms from aluminum legacy configurations and fire-blocking fabric assemblies. Price differentiation hinges on certification grade under FAA Part 25.562 versus MIL-STD-1290 and volume scale tied to NATO helicopter procurement cycles. Commercial operators exhibit acute price sensitivity; defense buyers prioritize performance-based sustainment metrics over unit cost.
Supply Chain Analysis
Domestic-content mandates in US Army Aviation and Missile Command programs and UK Ministry of Defence frameworks are reshaping sourcing toward captive composite energy-absorption production. Supply concentrates in the United States, Germany, and the United Kingdom for integrated seating-to-avionics manufacturing. Aerospace-grade carbon fiber and titanium feed from specialized tier-2 converters. Single-source vulnerability persists in magnetorheological damping fluid formulations. Distribution runs through sole-source military contracting channels and commercial fleet maintenance integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA Part 25.562 and EASA CS-25.561 dynamic testing protocols erect a cost-of-compliance barrier that entrenches qualified incumbents against unqualified challengers.
For Market Incumbents: Anticipate raw material cost volatility in titanium and carbon fiber by securing long-term offtake agreements with composite converters. Deepen backward integration into energy-absorption module production to defend margins against modular supplier ecosystems decoupling from final assembly integrators. For New Entrants and Emerging Players: Magnetorheological damping fluid architectures offer a technology-first wedge into urban air mobility certification under FAA Special Class airworthiness rules. Target eVTOL platforms and remote operator stations for crewed-uncrewed teaming architectures as the most penetrable white space, deploying qualification partnerships with established test laboratories as the primary go-to-market angle. For Investors and Strategic Acquirers: Re-rating potential sits with composite energy-absorption specialists given MIL-S-58095 aluminum-to-composite substitution mandates. Long-term viability favors suppliers with dual civil-military certification pathways under converging ISO 9529 harmonization. Monitor US Army rotorcraft program office pilot configurations as the signal for modular architecture adoption inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Structures | Captive supply of carbon fiber crush structures locks in margin control under tightening MIL-S-58095 specifications. |
| Performance-Based Sustainment Contract Capture | Fleet availability metrics displace discrete unit purchasing across UK Ministry of Defence and US Navy rotorcraft logistics frameworks. |
| Modular Energy-Absorption Architecture Development | Tunable stroke characteristics decouple module vendors from final seat assembly integrators in Black Hawk modernization tranches. |
| Urban Air Mobility Certification Investment | First-mover positioning for 16g-rated seat suppliers under FAA Special Class rules for emerging eVTOL platforms. |
| REACH Compliance Conversion Program | Trivalent chromium and plasma electrolytic oxidation requalification secures European defense contract eligibility against 12-18 month cycle risk. |
Methodological Framework
Independent corroboration across program managers at US Army Aviation and Missile Command, procurement leads at UK Ministry of Defence, composite manufacturing engineers in the Bavarian aerospace cluster, and regulatory affairs specialists at EASA underwrites the qualitative findings. Primary fieldwork with FAA certification engineers and MIL-STD-1290 test laboratory directors combined with secondary validation from FAA Part 25.562 amendment dockets, EASA CS-25.561 regulatory filings, NATO helicopter procurement announcements, and defense contract award databases. Bottom-up segment sizing across seat type, material, aircraft platform, and safety feature dimensions triangulated against top-down market envelope checks.
Comparable-period anchoring to historical military procurement cycles and commercial retrofit maintenance intervals structured the projection horizon. The analytical framework modeled segmentation across seat configuration, material chemistry, aircraft platform type, and safety feature integration. CAGRs derived from platform-specific replacement timelines and regulatory amendment implementation schedules. Forecast inputs incorporated NATO helicopter modernization program trajectories and REACH restriction compliance conversion timelines.
Several conditions sit outside the modeled scope, including unannounced platform cancellations, abrupt titanium or carbon fiber supply disruptions, and retroactive regulatory reinterpretations. Forecasts reflect documented assumptions regarding qualification cycle durations and procurement decision-chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aeronautical Wind Tunnel Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Sailplane Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
Global Business Jets Market
Aircraft
Australia Aviation Market
Aircraft
North America Helicopters Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Japan Aerospace and Defense Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
Europe Commercial Aircraft Market
Aircraft
US Military Aviation Market