
 Aerospace Fluid Conveyance System Market | 2026-2036
Aerospace Fluid Conveyance System Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Fluid Conveyance System Market Analysis
Aerospace fluid systems engineering talent is redrawing competitive boundaries as OEMs and Tier-1 suppliers compete for specialists in titanium forming and composite overwrap manufacturing. Parker Hannifin Corporation leverages its vertically integrated hose and fitting portfolio to sustain long-term contracts with major airframers. GKN Aerospace Services Limited anchors European supply chains through its precision tube fabrication capabilities for engine and airframe programs. Senior PLC specializes in lightweight ducting solutions that differentiate its offerings in fuel and environmental control systems.
An aerospace fluid conveyance system comprises the network of hoses, tubes, fittings, and connectors that transport fuel, hydraulic fluid, air, and coolant throughout an aircraft, typically operating at pressures from 3,000 to 8,000 psi in hydraulic circuits and enduring temperature swings from minus 65 to plus 450 degrees Fahrenheit. Hoses and tubes constitute the core product categories, with metallic and composite technologies commanding premium positions due to weight reduction mandates, while rubber and thermoplastic variants serve secondary and legacy applications where cost sensitivity dominates. Fuel systems and hydraulic systems represent the largest application segments, though cooling systems for thermal management in electric and hybrid-electric architectures are gaining engineering attention.
FAA airworthiness directives and EASA certification standards govern material flammability, fatigue life, and pressure cycling requirements, compelling manufacturers to maintain dual-approval testing protocols for transatlantic program participation. The EPA and REACH frameworks additionally restrict certain elastomer chemistries and surface treatments, redirecting R&D investment toward compliant polymer formulations and aqueous cleaning processes. Stakeholders must monitor evolving sustainability-linked procurement criteria from OEMs and defense agencies, as lifecycle emissions accounting begins penetrating supplier qualification scorecards.
Market Dynamics
Weight reduction mandates from airframers are compressing material selection cycles, forcing suppliers to validate titanium aluminide and thermoplastic composites under accelerated FAA fatigue protocols before traditional qualification timelines expire.
Growth Catalysts
- Single-aisle production ramp:Boeing and Airbus narrowbody backlogs exceeding 13,000 units are pulling demand for lightweight hydraulic lines and fuel tubing across their supplier networks.
- REACH-compliant elastomer development:ECHA restrictions on halogenated flame retardants are redirecting R&D budgets toward bio-based polymer formulations that maintain 3000 psi pressure ratings.
- Urban air mobility certification:FAA Special Class airworthiness criteria for eVTOL platforms are creating first-mover advantages for fluid system vendors with existing Part 23/25 approval track records.
Market Restraints
- Titanium sponge supply concentration:Russian and Chinese smelters control 60% of aerospace-grade titanium feedstock, exposing Western fabricators to geopolitical supply interruptions.
- Dual-approval testing burden:Simultaneous FAA and EASA validation protocols add 18-24 months to qualification timelines for new hose architectures.
- Composite overwrap equipment costs:Automated fiber placement systems for pressure vessels require capital commitments exceeding $15 million per production cell.
Strategic Opportunities
- India defense localization:Indigenization mandates under the country's Defense Acquisition Procedure are opening captive demand for hydraulic actuation lines in combat aircraft programs.
- Thermal management for hybrid-electric propulsion:Liquid cooling circuits for megawatt-class electric motors represent undeveloped specification territory with no incumbent supplier lock-in.
- ISO 14001-linked procurement criteria:Lifecycle carbon accounting requirements from European OEMs are creating preference premiums for suppliers with verified Scope 3 emissions data.
Industry Challenges
- Titanium forming skill scarcity:Aerospace tube bending and thin-wall welding expertise is concentrating among retiring technician cohorts with limited apprenticeship pipeline replacement.
- Legacy system integration friction:New lightweight hose technologies must interface with 1970s-era airframe plumbing architectures without triggering full recertification cascades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Fluid Conveyance System Market |
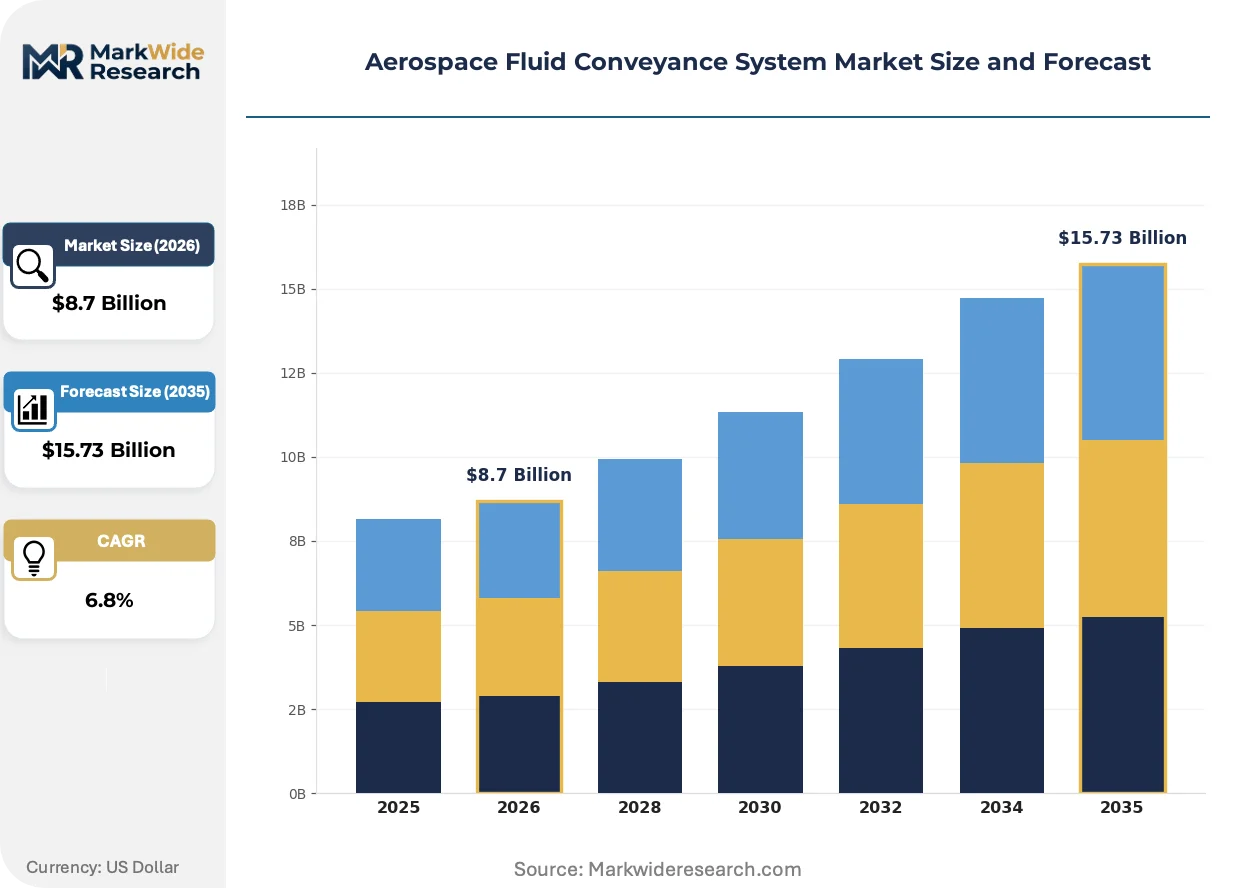
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hoses, Fittings, Connectors, Tubes Technology: Metallic, Composite, Rubber, Thermoplastic Application: Fuel Systems, Hydraulic Systems, Pneumatic Systems, Cooling Systems End User: OEMs, MROs, Airlines, Defense Contractors |
| Companies Covered | GKN Aerospace Services Limited, Senior PLC, Parker Hannifin Corporation, Flexfab Horizons International, Inc., Triumph Group, Inc., Eaton Corporation, ITT Inc., Zodiac Aerospace, Safran Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Fluid Conveyance System Market Emerging Trajectories
Material science advances and certification protocol evolution are compressing product lifecycles while opening specification territory previously dominated by metallic legacy systems.
Smart sensor-embedded tubing is miniaturizing condition monitoring capabilities directly into hydraulic and fuel lines. Gulfstream and Dassault business jet programs are specifying these architectures for predictive maintenance contracts. The technology is miniaturizing the aftermarket service model from scheduled replacement to condition-based intervention, compressing MRO revenue cycles.
EPA restrictions on per- and polyfluoroalkyl substances are eliminating PTFE-lined hose options for fuel vent and drain applications. Manufacturers are pivoting toward FEP and PFA alternatives with equivalent chemical resistance profiles. Commercial narrowbody platforms are absorbing the qualification costs fastest due to production volume amortization.
Airframer direct sourcing is consolidating Tier-2 and Tier-3 fluid component vendors into approved supplier lists with exclusive long-term agreements. Regional jet programs in Brazil and Canada are experiencing the most aggressive supplier rationalization. This concentration is eliminating distributor intermediaries and compressing pricing negotiation leverage for smaller fabricators.
Aerospace Fluid Conveyance System Market Segmentation
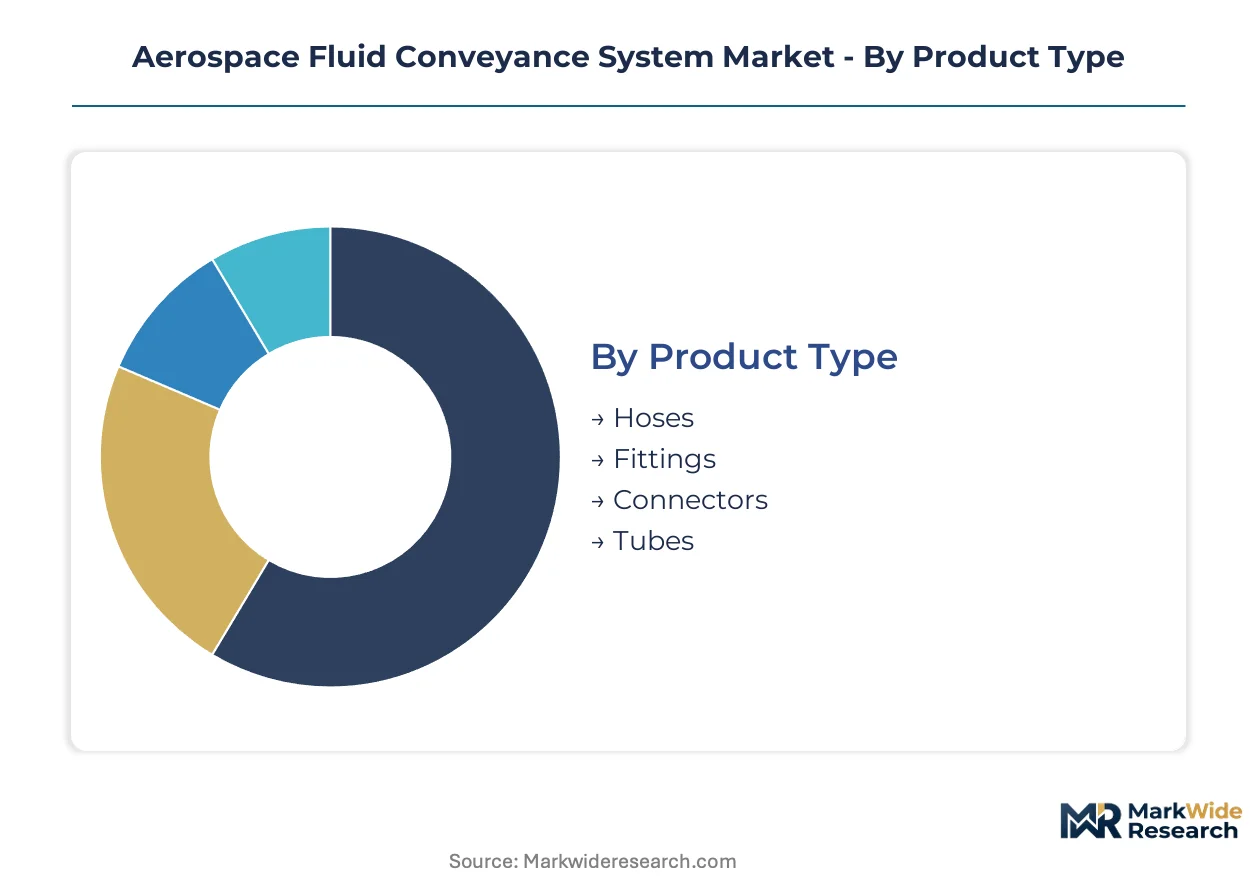
Segmentation in aerospace fluid conveyance systems reveals how material substitution pressures and certification complexity fragment procurement strategies across airframe programs. Understanding these divisions exposes where incumbent technologies defend position and where emerging architectures disrupt established supply relationships.
Product Type:
Tube and hose architectures face divergent substitution threats as composite overwrap technologies challenge metallic legacy systems in high-pressure circuits.
- Hoses:Flexible pressure-bearing lines constructed from elastomer inner tubes reinforced with braided metallic or synthetic fiber layers, rated typically to 5,000 psi operating pressure. Demand concentrates in hydraulic actuation circuits for Boeing and Airbus narrowbody landing gear systems, where fatigue cycling requirements under FAA AC 20-107C drive specification toward aramid-reinforced fluoropolymer constructions.
- Tubes:Rigid seamless or welded metallic conduits, predominantly titanium Ti-3Al-2.5V or corrosion-resistant steel alloys, handling 3,000-8,000 psi in fuel distribution and engine bleed air networks. Procurement from Safran and Rolls-Royce engine programs in France and the United Kingdom prioritizes thin-wall titanium forming for weight-critical pylon and nacelle routing.
- Fittings:Precision-machined connection elements including flared, flareless, and quick-disconnect configurations that terminate hose and tube assemblies. Fleet retrofit programs for aging Boeing 737NG and Airbus A320ceo platforms sustain aftermarket demand for standard AN/MS fitting inventories.
- Connectors:Multi-port manifold assemblies and swivel joints enabling complex routing geometries in confined airframe compartments. Gulfstream G700 and Dassault Falcon 10X business jet specifications favor compact titanium connector blocks for integrated hydraulic power distribution.
Hoses retain volume leadership across commercial aviation production rates; tubes hold the steepest expansion curve as next-generation propulsion thermal management demands proliferate.
Technology:
Cost tier stratification separates premium material systems from commodity elastomer alternatives, with qualification burden determining viable supplier participation.
- Metallic:Titanium, stainless steel, and aluminum alloy constructions dominating legacy airframe specifications and high-temperature engine zones. Boeing 787 and Airbus A350 programs in the United States and France specify titanium hydraulic lines for corrosion resistance in humid operational environments.
- Composite:Carbon fiber or glass fiber reinforced polymer overwraps on metallic liners, achieving 25-40% weight reduction versus all-metal equivalents. NASA and FAA research programs in the United States are qualifying thermoset composite fuel lines for pressurized wing tank applications under revised flammability protocols.
- Rubber:Nitrile, neoprene, and ethylene propylene diene monomer (EPDM) elastomer hoses for low-pressure pneumatic and drain applications. REACH-compliant formulations from German and French compounders are displacing legacy halogenated flame-retardant grades in European-registered aircraft.
- Thermoplastic:Nylon, polyethylene, and polyvinylidene fluoride (PVDF) extrusions for lightweight secondary systems and electric aircraft cooling loops. Joby Aviation and Archer Aviation eVTOL development programs in California specify thermoplastic ducting for battery thermal management in their FAA certification campaigns.
Metallic technology commands the highest revenue per kilogram; thermoplastic formulations are climbing the fastest as urban air mobility platforms scale pre-production volumes.
Application:
Application maturity varies sharply, with established fuel and hydraulic domains defending against emerging thermal management categories lacking incumbent supplier lock-in.
- Fuel Systems:Pressurized and non-pressurized lines, vents, and inerting distribution networks handling Jet-A and sustainable aviation fuel blends. Airbus A321XLR extended-range programs in France drive demand for titanium fuel tubing resistant to thermal expansion cycling during long-haul operations.
- Hydraulic Systems:Power transfer lines for flight control surfaces, landing gear, and thrust reversers operating at 3,000-5,000 psi. Boeing's final assembly operations in Washington state and South Carolina anchor North American procurement for 737 MAX and 777X hydraulic line kits.
- Pneumatic Systems:Bleed air and environmental control distribution at moderate pressures, typically 50-150 psi. De Havilland Canada Dash 8-400 regional turboprop production sustains demand for lightweight pneumatic ducting in Ontario manufacturing facilities.
- Cooling Systems:Liquid and air-cooled circuits for avionics, electric motors, and battery packs in hybrid-electric and all-electric architectures. MagniX and Rolls-Royce electrical propulsion programs in Australia and the United Kingdom are defining first-generation specifications for megawatt-class motor cooling lines.
Fuel systems retain volume leadership; cooling systems hold the steepest expansion curve as electrification penetrates commercial and defense platforms.
End User:
Customer type determines contract structure, with OEM direct sourcing consolidating supplier bases while MRO channels preserve fragmented distributor relationships.
- OEMs:Original equipment manufacturers including Boeing, Airbus, Bombardier, and Embraer procuring fluid systems for new aircraft production. Long-term agreement frameworks with Parker Hannifin and Eaton Corporation span 10-15 year program lifecycles for single-aisle platforms.
- MROs:Maintenance, repair, and overhaul providers managing scheduled replacement and airworthiness directive compliance for in-service fleets. Lufthansa Technik and ST Engineering facilities in Germany and Singapore stock broad hose and fitting inventories for turnaround-critical AOG support.
- Airlines:Carrier direct procurement for consumable spares and fleet standardization initiatives. Delta Air Lines and United Airlines technical operations in Atlanta and Chicago specify common hydraulic line configurations across mixed Boeing and Airbus fleets to simplify inventory.
- Defense Contractors:Lockheed Martin, Northrop Grumman, and BAE Systems programs for military aircraft, rotorcraft, and unmanned systems. F-35 Joint Strike Fighter production in Texas and Italy drives classified-specification fluid line demand with ITAR-controlled supply chains.
OEMs retain volume leadership; defense contractors hold the steepest expansion curve as Indo-Pacific military modernization accelerates platform procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States supplier networks where Boeing's final assembly operations command volume discounts, while European fabricators absorb REACH compliance premiums that inflate delivered costs by 8-12%.
United States
Boeing's 737 MAX and 777X production lines in Washington state and South Carolina pull titanium hydraulic line demand from Parker Hannifin and Eaton Corporation. FAA AC 20-107C fatigue protocols govern qualification timelines for new hose architectures. Wichita's precision tube fabrication cluster supplies engine bleed air systems for Textron Aviation and Bombardier business jet programs.
France
Airbus A321XLR extended-range fuel systems drive titanium tubing procurement for thermal expansion resistance during long-haul cycles. EASA certification standards for fire-resistant fluid lines tighten material specifications across Safran and Rolls-Royce engine supply chains. Toulouse's aerospace corridor concentrates composite overwrap manufacturing for next-generation wing tank applications.
United Kingdom
Rolls-Royce electrical propulsion programs in Derby define first-generation specifications for megawatt-class motor cooling lines. REACH restrictions on halogenated flame retardants redirect GKN Aerospace toward bio-based polymer formulations. Bristol's precision engineering cluster specializes in thin-wall titanium forming for engine pylon routing on Airbus widebody platforms.
Germany
Lufthansa Technik's Hamburg MRO facilities stock broad hose inventories for AOG support across European-registered fleets. ECHA compliance mandates displace legacy elastomer chemistries in hydraulic actuation circuits. Munich's supplier ecosystem concentrates on quick-disconnect fittings for Bombardier and Embraer regional jet retrofits.
India
Indigenization mandates under the Defense Acquisition Procedure open captive demand for hydraulic lines in Tejas combat aircraft and Dhruv helicopter programs. BIS certification requirements for aerospace materials accelerate local testing infrastructure buildout. Bangalore's defense aerospace cluster attracts Tier-2 fabricators seeking offset partnerships with Hindustan Aeronautics Limited.
Aerospace Fluid Conveyance System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated conglomerates commanding premium-tier contracts while regional specialists compete on qualification speed. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive material supply, precision engineering specialists with FAA/EASA dual-approval track records, and emerging fabricators targeting urban air mobility qualification. Consolidation pressure intensifies as airframer direct sourcing eliminates distributor intermediaries, while strategic partnerships between tube formers and composite overwrap technology licensors accelerate product development cycles.
Among diversified industrial conglomerates, Parker Hannifin Corporation and Eaton Corporation occupy positions exemplifying vertically integrated hose and fitting portfolios that sustain decade-long program agreements. GKN Aerospace Services Limited anchors European supply relationships through precision tube fabrication capabilities. These three entities represent the archetype of suppliers capable of spanning metallic legacy systems and emerging composite architectures without triggering full recertification cascades.
| Leading Market Players |
|---|
| GKN Aerospace Services Limited |
| Senior PLC |
| Parker Hannifin Corporation |
| Flexfab Horizons International, Inc. |
| Triumph Group, Inc. |
| Eaton Corporation |
| ITT Inc. |
| Zodiac Aerospace |
| Safran Group |
| Others |
Supply Flow & Price Mechanics
FAA AC 20-107C fatigue protocols and EASA fire-resistance certification standards gate both supplier qualification and price differentiation simultaneously, compressing margins for uncertified fabricators while awarding premium positioning to dual-approved incumbents with established airframer relationships.
Pricing Analysis
United States suppliers command 8-12% price premiums over European counterparts due to REACH compliance cost absorption by French and German fabricators. Pricing stratifies across FAA-EASA dual-certified premium tiers, single-jurisdiction standard tiers, and uncertified economy alternatives for aftermarket applications. Cost compression in standard-tier metallic tubing is intensifying because Boeing and Airbus narrowbody production ramps extract volume discounts from captive suppliers. Regional airlines and MRO distributors exhibit highest price sensitivity; defense contractors and business jet OEMs demonstrate lowest sensitivity due to performance-specification priority.
Supply Chain Analysis
Russia and China control 60% of aerospace-grade titanium sponge feedstock, exposing Western tube fabricators to geopolitical supply interruption risk. United States, France, and United Kingdom concentrate precision forming and composite overwrap manufacturing, drawing from titanium ingot, aramid fiber, and fluoropolymer resin inputs. Single-source vulnerability concentrates in Russian smelter dependency for Ti-6Al-4V and Ti-3Al-2.5V alloys. Distribution runs through airframer direct-sourcing agreements that eliminate Tier-2 intermediaries, consolidating procurement leverage with Boeing, Airbus, and Safran.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite overwrap technologies and thermoplastic formulations threaten metallic legacy systems, forcing incumbents to defend substitution-prone positions through certification speed and material science investment.
For Market Incumbents: Secure dual-approval testing capacity expansion to compress 18-24 month FAA-EASA qualification timelines before composite alternatives achieve equivalent pressure ratings. Anchor backward integration into titanium sponge sourcing through non-Russian supply agreements to mitigate geopolitical disruption exposure. Prioritize aramid-reinforced fluoropolymer R&D to defend hydraulic circuit positions against thermoplastic displacement in narrowbody landing gear systems. For New Entrants and Emerging Players: FAA Special Class airworthiness criteria for eVTOL platforms offer accelerated certification pathways for fluid system vendors with existing Part 23 track records. Urban air mobility thermal management applications represent undeveloped specification territory with no incumbent lock-in. Target liquid cooling circuit development for megawatt-class electric motors through partnership with MagniX and Rolls-Royce electrical propulsion programs. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated fiber placement systems for composite pressure vessels, exceeding $15 million per production cell. Long-term viability favors precision engineering specialists with FAA-EASA dual-approval track records and established airframer relationships over undifferentiated commodity fabricators. Watch titanium sponge supply diversification progress as inflection indicator for Western fabricator margin stability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Approval Testing Investment | FAA-EASA simultaneous qualification compresses time-to-revenue for new hose architectures. |
| Non-Russian Titanium Sourcing | Supply agreements with Japanese and Saudi smelters reduce geopolitical concentration risk. |
| Composite Overwrap Licensing | Technology partnerships with NASA research programs accelerate thermoset fuel line qualification. |
| eVTOL Certification Fast-Track | FAA Special Class criteria create first-mover advantages in urban air mobility fluid systems. |
| Thermal Management R&D Partnership | Collaboration with Rolls-Royce electrical propulsion defines megawatt-class cooling specifications. |
Methodological Framework
The analysis maps fluid conveyance product categories, each validated through procurement executives at Boeing and Airbus, Tier-1 supplier engineering directors, MRO inventory managers at Lufthansa Technik, and defense contractor supply chain leads. Primary interview insights triangulate against FAA airworthiness directives, EASA certification standards, SEC 10-K filings from Parker Hannifin and Eaton Corporation, and customs trade data for titanium sponge imports. Bottom-up segment sizing and top-down market reconciliation ensure consistency across metallic, composite, rubber, and thermoplastic technology tiers.
Volume and value outputs were validated against external benchmarks including airframer production rate disclosures, engine program delivery schedules, and fleet retrofit cycle documentation. The analytical framework models product type, technology, application, and end-user dimensions across the projection horizon. CAGRs derive from production backlog analysis, material substitution elasticity, and certification timeline compression. Forecast inputs incorporate narrowbody delivery schedules, REACH-compliant elastomer development trajectories, and urban air mobility platform certification progressions.
Underlying assumptions cover sustained narrowbody production rates, stable titanium sponge supply chains, and incremental eVTOL certification advancement, with deviation risk concentrated in geopolitical supply interruption and accelerated composite technology adoption. Recalibration cycles align with material shifts in airframer procurement criteria, regulatory protocol revisions, and electrification platform entry into service.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Fuel Systems
Fuel Tank Inerting Systems Market
Aircraft Fuel Systems
Asia-Pacific Aviation Fuel Market
Aircraft Fuel Systems
Jet Fuel Market
Aircraft Fuel Systems
Air-To-Air Refueling Market
Aircraft Fuel Systems
Aviation Gasoline (Avgas) Market
Aircraft Fuel Systems
Global Aircraft Pumps Market
Aircraft Fuel Systems
Aircraft Exhaust System Market
Aircraft Fuel Systems
Aerospace and Defense Fuel Market
Aircraft Fuel Systems
Aircraft Refueling Hose Market
Aircraft Fuel Systems
North America Renewable Aviation Fuel Market
Aircraft Fuel Systems
Middle-East and Africa Aviation Fuel Market
Aircraft Fuel Systems
Aerospace and Defense Fluid Conveyance Systems Market
Aircraft Fuel Systems
Global Aircraft Fuel Tanks Market
Aircraft Fuel Systems
Aviation Fluid Market
Aircraft Fuel Systems
Aircraft Fuel Nozzle Market
Aircraft Fuel Systems
Aircraft Fuel System Market