
 Aircraft Electrical Systems Market | 2026-2036
Aircraft Electrical Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Electrical Systems Market Intelligence
The industry-wide commitment to net-zero aviation goals, reinforced by initiatives like the EU Green Deal, is restructuring the design philosophy for onboard power architectures. This fundamental shift prioritizes electrification to reduce aircraft weight and fuel consumption. Safran S.A. leverages its expertise in integrated power generation and distribution systems for new airframes. Collins Aerospace, a unit of RTX Corporation, competes by offering a broad portfolio of electrical power components and systems.
Aircraft electrical systems are the integrated networks that generate, distribute, convert, and manage electrical power onboard an aircraft. These systems operate on specific standards, such as 28V DC or 115V AC at 400 Hz, to power all equipment. The primary purpose is ensuring the safe and continuous operation of mission-critical flight and cabin systems. Power Distribution Systems and Generators form the core value segments, while advanced, lightweight Wiring Harnesses for Commercial Aviation are a key growth area.
Regulatory bodies including the FAA in the United States and EASA in Europe enforce strict certification standards for electrical system reliability and safety. These regulations, particularly standards like DO-160, dictate stringent design, testing, and redundancy requirements for every component. The central strategic decision for suppliers involves balancing investment between mature AC systems and next-generation high-voltage DC architectures for future aircraft platforms.
Market Dynamics
The fundamental transition toward more-electric aircraft (MEA) architectures, driven by industry-wide commitments to net-zero emissions, is the central force shaping the market. This shift necessitates a complete redesign of onboard power systems, moving from legacy standards to high-voltage DC architectures.
Growth Catalysts
- More-Electric Aircraft Programs:The development of next-generation commercial airframes and military platforms requires advanced power generation and distribution systems capable of handling significantly higher electrical loads for flight controls and subsystems.
- Emission Reduction Mandates:Regulatory frameworks, including the EU Green Deal, compel aircraft operators and manufacturers to adopt lighter, more efficient electrical systems to reduce overall aircraft weight and fuel consumption.
- Advanced Air Mobility (AAM) Sector:The emergence of electric vertical takeoff and landing (eVTOL) aircraft creates an entirely new demand segment for compact, high-power-density electrical systems tailored for urban and regional transport.
Market Restraints
- Stringent Certification Cycles:The lengthy and capital-intensive certification processes mandated by the FAA and EASA, particularly for novel high-voltage DC systems, create significant barriers to entry and slow the pace of innovation deployment.
- Thermal Management Complexity:Increased power density in MEA systems generates substantial waste heat, requiring sophisticated and often heavy thermal management solutions that can partially negate the weight savings from electrification.
- Supply Chain Bottlenecks:A constrained supply base for aerospace-grade, high-voltage components like specialized semiconductors, contactors, and connectors creates production risks and cost volatility for system integrators.
Strategic Opportunities
- High-Voltage DC Architectures:Developing standardized, modular high-voltage DC power distribution units and components represents a significant opportunity as the industry moves beyond traditional 115V AC and 28V DC systems.
- Solid-State Power Control:The replacement of electromechanical relays with lighter, more reliable solid-state power controllers offers a clear path to improve system diagnostics, reduce maintenance, and enable more intelligent load management.
- Retrofit for Fuel Efficiency:Supplying lightweight wiring harnesses and upgraded generator control units to the existing global fleet of commercial aircraft provides a stable revenue stream tied directly to airline fuel-saving initiatives.
Industry Challenges
- Systems Integration with Legacy Platforms:Integrating new high-voltage electrical systems into existing aircraft designs presents major engineering hurdles, including managing electromagnetic interference (EMI) with sensitive avionics and flight control systems.
- Specialized Talent Shortages:A deficit of power electronics engineers with expertise in high-voltage aerospace applications and familiarity with rigorous certification standards like DO-160 impedes development and program execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Electrical Systems Market |
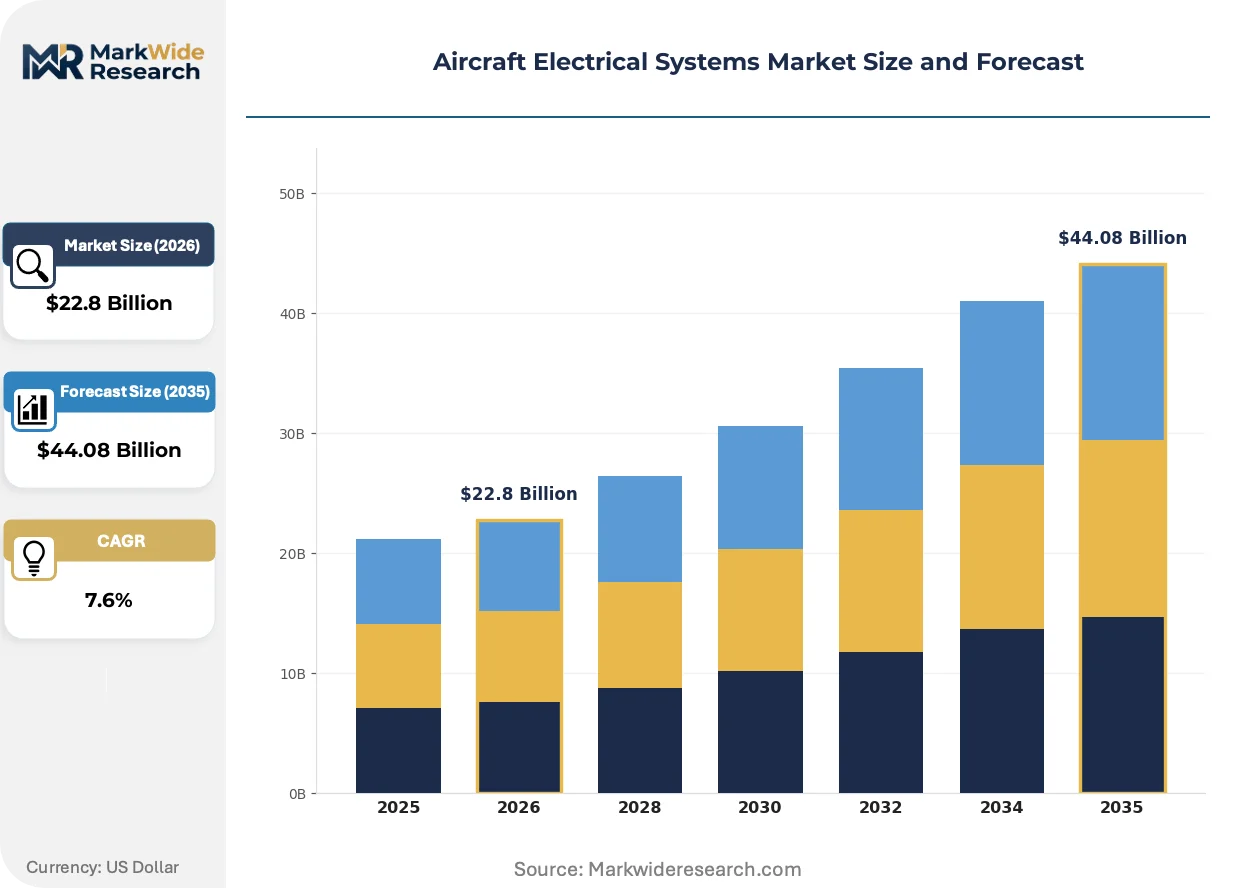
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $44.08 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Distribution Systems, Wiring Harnesses, Circuit Protectors, Generators Technology: Fly-by-Wire, Avionics Systems, Flight Control Systems, Monitoring Systems End User: Commercial Aviation, Military Aviation, Cargo Operators, General Aviation Application: Flight Control, Electrical Power Generation, Cabin Systems, Emergency Systems |
| Companies Covered | Safran S.A., Collins Aerospace, RTX Corporation, AMETEK, Inc., Parker-Hannifin Corporation, Honeywell International Inc., Thales Group, Meggitt PLC, General Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Electrical Systems Market Strategic Shifts & Innovations
The evolution from federated, single-function electrical components toward deeply integrated power systems defines the market's current trajectory. This change prioritizes system-level efficiency and weight reduction over the optimization of individual line-replaceable units, altering supplier relationships and design philosophies.
High-voltage DC (HVDC) power distribution serves as the backbone for next-generation aircraft. Commercial and military aircraft programs are adopting these architectures to transmit more power using smaller, lighter-gauge wiring compared to traditional systems. The HVDC architecture is absorbing functions previously managed by separate hydraulic and pneumatic networks, including flight control actuation and environmental systems.
Harmonization of certification standards for electric and hybrid propulsion by EASA and the FAA is a critical regulatory development. This provides a clearer, though still rigorous, pathway for manufacturers to validate and commercialize novel electrical architectures and components. The power generation and distribution segments are most affected, facing substantial investment requirements for compliance testing against these new high-voltage safety standards.
Aircraft original equipment manufacturers (OEMs) are altering their procurement models for electrical systems. The practice is shifting away from sourcing individual components toward acquiring complete, pre-validated power systems from a single Tier-1 supplier. This trend, most visible in new airframe programs based in the United States and France, disrupts the market for smaller component specialists.
Aircraft Electrical Systems Market Segmentation
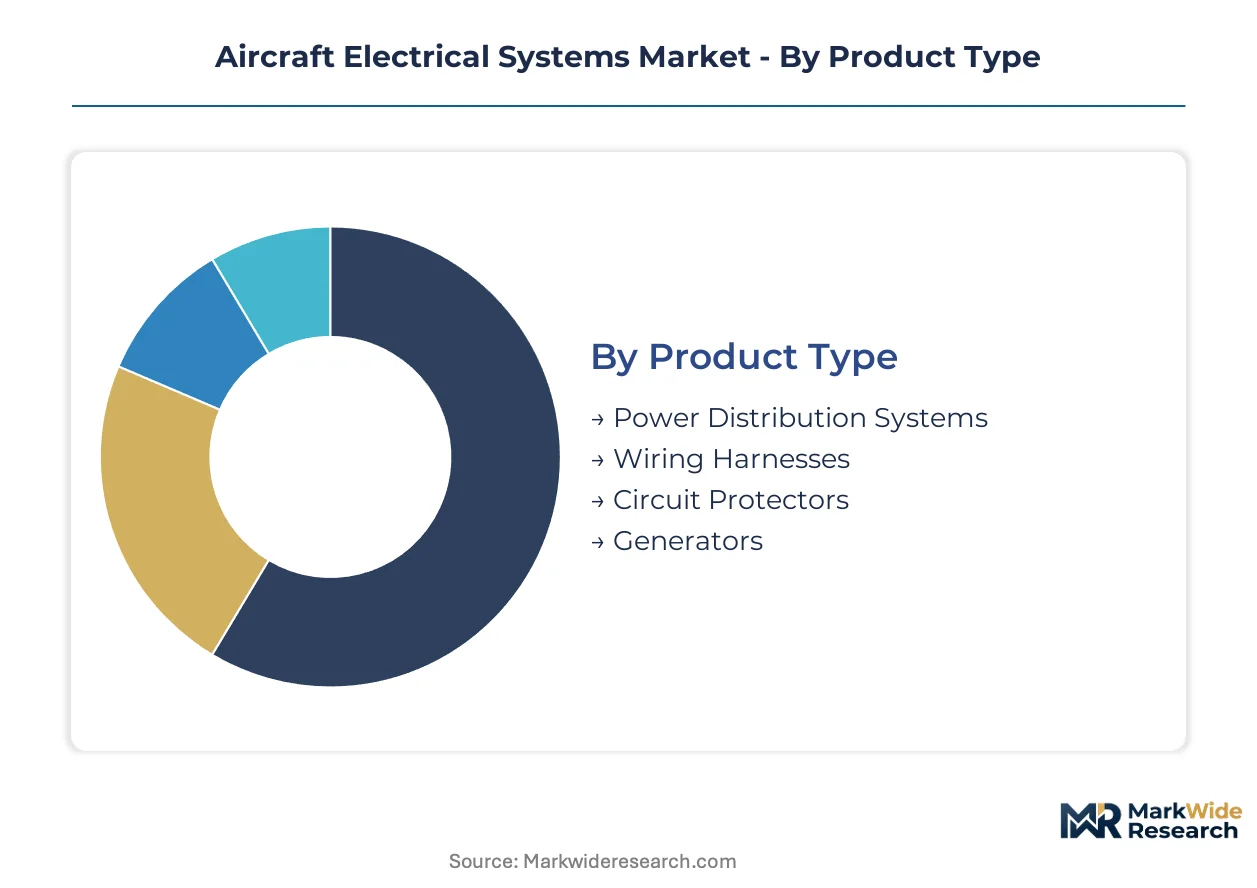
The aircraft electrical systems market is segmented by critical operational and design considerations, reflecting the diverse requirements of modern aviation. Understanding these segments helps stakeholders identify specific demand drivers and technological priorities within this evolving industry.
Product Type:
Aircraft manufacturers prioritize system reliability and weight reduction when selecting electrical product types for new airframes.
- Power Distribution Systems:These integrated networks manage and route electrical power throughout the aircraft, converting voltages and frequencies for various loads. Demand concentrates in new more-electric aircraft programs in the United States, requiring high-voltage DC capabilities.
- Wiring Harnesses:Comprising bundles of wires, connectors, and protective coverings, these components transmit electrical signals and power across the aircraft. Demand is concentrating in commercial aviation for lightweight, high-temperature solutions to reduce fuel consumption.
- Circuit Protectors:Devices like circuit breakers and fuses safeguard electrical systems from overcurrents and short circuits, ensuring system integrity.
- Generators:These convert mechanical energy from the engine into electrical power, forming the primary source for onboard systems.
Volume sits with Generators; growth tilts toward Wiring Harnesses.
Technology:
Technological advancements in aircraft electrical systems focus on enhancing flight safety and operational efficiency across diverse platforms.
- Fly-by-Wire:This advanced control system replaces mechanical linkages with electronic interfaces, transmitting pilot commands via electrical signals to flight control surfaces. Demand concentrates in next-generation military aircraft for enhanced maneuverability and precision.
- Avionics Systems:These electronic systems encompass communication, navigation, flight management, and display functions, integrating critical data for crew operation. Demand is concentrating in commercial aviation for highly integrated, software-defined solutions to optimize operational costs.
- Flight Control Systems:These integrated systems manage aircraft movement and stability, translating pilot inputs into physical responses.
- Monitoring Systems:These electrical components continuously track aircraft parameters, providing real-time data for diagnostics and preventive maintenance.
Innovation in Fly-by-Wire technology drives fundamental transformation, while Avionics Systems continue to expand capabilities.
End User:
Mission criticality and operational requirements dictate the specific electrical system configurations for different aircraft end users.
- Commercial Aviation:This segment includes passenger and cargo aircraft operated by airlines, prioritizing reliability, fuel efficiency, and passenger comfort. Demand concentrates in the United States and Europe for more-electric architectures to meet stringent emission reduction targets.
- Military Aviation:Encompassing fighter jets, transport aircraft, and surveillance platforms, this segment demands robust, high-power-density systems capable of operating in extreme conditions. Demand concentrates in advanced airframes for enhanced mission capabilities and stealth technology.
- Cargo Operators:These entities utilize aircraft primarily for freight transport, emphasizing operational uptime and payload capacity in their electrical system choices.
- General Aviation:This diverse segment includes private planes, corporate jets, and small utility aircraft, requiring cost-effective and reliable electrical solutions.
Commercial Aviation holds the largest market share, with Military Aviation demonstrating consistent investment in advanced systems.
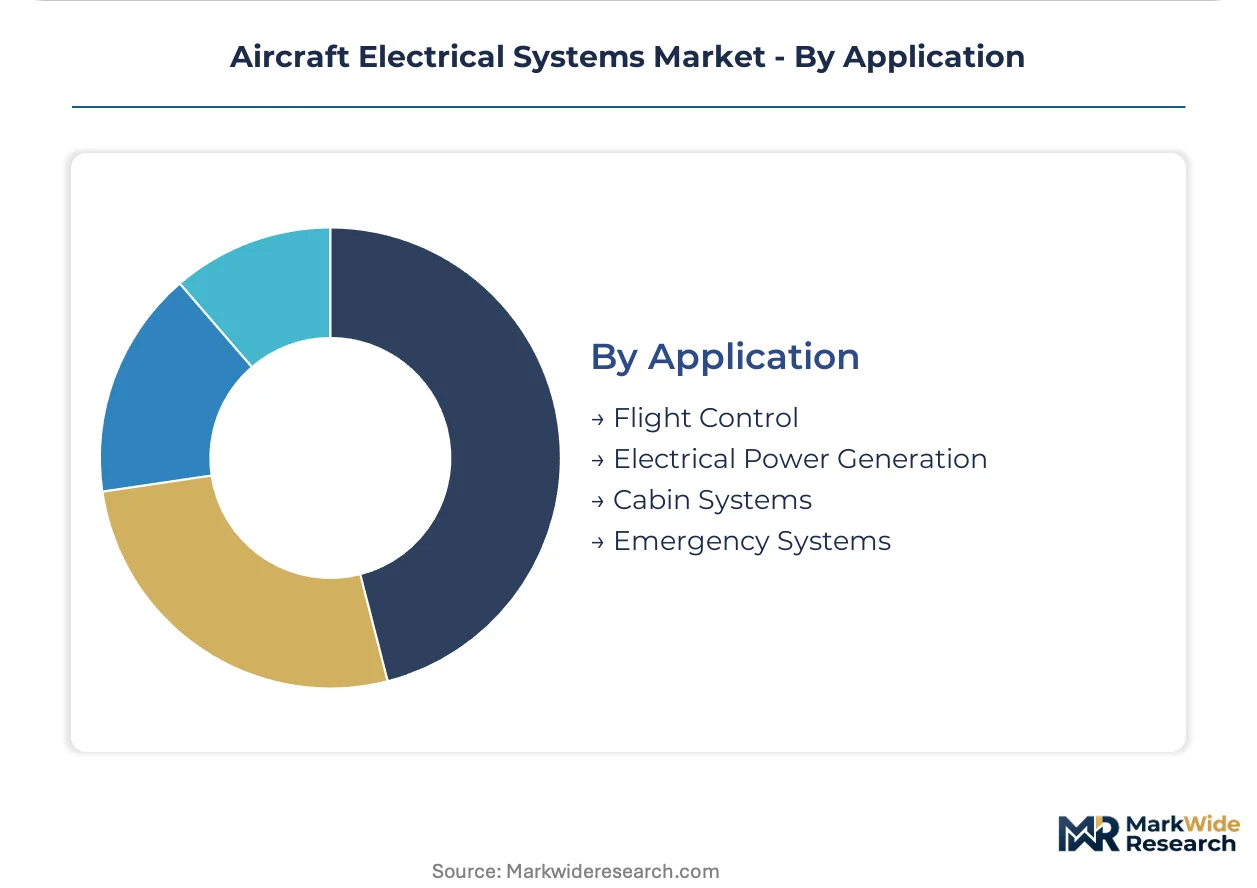
Application:
The functional imperative of each application area shapes the design and integration of aircraft electrical systems.
- Electrical Power Generation:This application involves the primary creation of electrical energy from aircraft engines or auxiliary power units to supply all onboard systems. Demand concentrates in new aircraft designs in France, which require high-voltage DC systems for increased power loads.
- Flight Control:This application ensures the precise and reliable manipulation of aircraft movement, integrating sensors, actuators, and control surfaces. Demand is concentrating in advanced air mobility platforms for highly responsive and fail-safe electrical actuation.
- Cabin Systems:These applications encompass passenger comfort and entertainment, including lighting, environmental controls, and in-flight connectivity.
- Emergency Systems:These critical applications include backup power, escape slide deployment, and fire suppression, ensuring aircraft safety during abnormal operations.
Strategic emphasis remains on Electrical Power Generation, while Flight Control applications drive critical system innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The market for aircraft electrical systems exhibits a distinct divide between nations leading in aerospace manufacturing and those primarily focusing on fleet modernization. Key aerospace manufacturing hubs concentrate both the production and significant consumption for advanced electrical systems. This dynamic shapes investment priorities and technological development across different geographies.
United States
Demand for more-electric aircraft programs and military platforms drives significant investment in advanced power systems. The FAA enforces stringent certification standards, particularly for novel high-voltage DC architectures. Aerospace clusters in Seattle, Wichita, and Southern California are centers for both development and integration of these complex systems.
France
New aircraft designs and the push for high-voltage DC systems generate substantial demand for advanced electrical components. Regulations stemming from the EU Green Deal and EASA compel manufacturers to adopt more efficient power architectures. The Toulouse and Bordeaux regions anchor European aerospace manufacturing and research activities.
Germany
Investment in advanced air mobility (AAM) and electric vertical takeoff and landing (eVTOL) aircraft creates a new demand segment for compact electrical systems. EASA certification processes influence design choices, supported by national R&D funding for electrification. Munich and Hamburg serve as critical aerospace centers for both traditional and emerging aviation technologies.
Japan
Modernization of defense platforms and investment in next-generation aerospace technologies underpin demand for high-performance electrical systems. Initiatives from METI support domestic aerospace R&D and component manufacturing capabilities. The Nagoya region remains a primary hub for aircraft component production and assembly.
United Kingdom
A strong focus on fuel-efficient retrofits and upgraded power management solutions for existing fleets drives market activity. Compliance with EASA standards, alongside UK CAA requirements, guides product development and certification. Bristol and Derby function as established aerospace engineering and manufacturing hubs.
Aircraft Electrical Systems Market Key Industry Players
The competitive structure tilts toward large, diversified aerospace and defense contractors that can offer integrated electrical system solutions. These companies leverage extensive engineering capabilities and established relationships with aircraft OEMs. Strategic partnerships and technology licensing agreements represent dominant competitive moves in this capital-intensive industry.
Within the integrated systems provider tier, Safran S.A. and Collins Aerospace exemplify companies offering broad portfolios across power generation and distribution. Honeywell International Inc. also occupies a significant position, providing a wide array of electrical components and systems for both commercial and military platforms. These entities anchor the market for complex, certified electrical architectures.
| Leading Market Players |
|---|
| Safran S.A. |
| Collins Aerospace |
| RTX Corporation |
| AMETEK, Inc. |
| Parker-Hannifin Corporation |
| Honeywell International Inc. |
| Thales Group |
| Meggitt PLC |
| General Electric Company |
| Others |
Cost & Logistics Intelligence
The rigorous aerospace certification ladder for electrical systems establishes a clear divergence, dictating premium pricing for certified components and concentrating supply within a limited pool of qualified manufacturers. This framework directly influences both system costs and procurement strategies.
Pricing Analysis
Cost-down pressure on electrical system suppliers accelerates as commercial aviation OEMs demand lighter, more efficient components to meet fuel economy targets. The dominant pricing model for integrated electrical systems remains project-based, often incorporating long-term support contracts. Price differentiation stems from the stringent DO-160 certification level and the degree of customization required for specific airframes. Commercial Aviation buyers exhibit high price sensitivity, while Military Aviation prioritizes performance and reliability over cost.
Supply Chain Analysis
Supply of aerospace-grade electrical components largely rests on established manufacturing hubs in the United States and France, alongside specialized producers in Germany and Japan. Key dependencies include specialized semiconductors, high-power contactors, and lightweight, high-temperature wiring. A structural risk involves single-source vulnerability for certain high-voltage components due to stringent certification and limited qualified suppliers. Distribution primarily occurs directly to aircraft OEMs and through large Tier-1 system integrators like Safran S.A. and Collins Aerospace.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
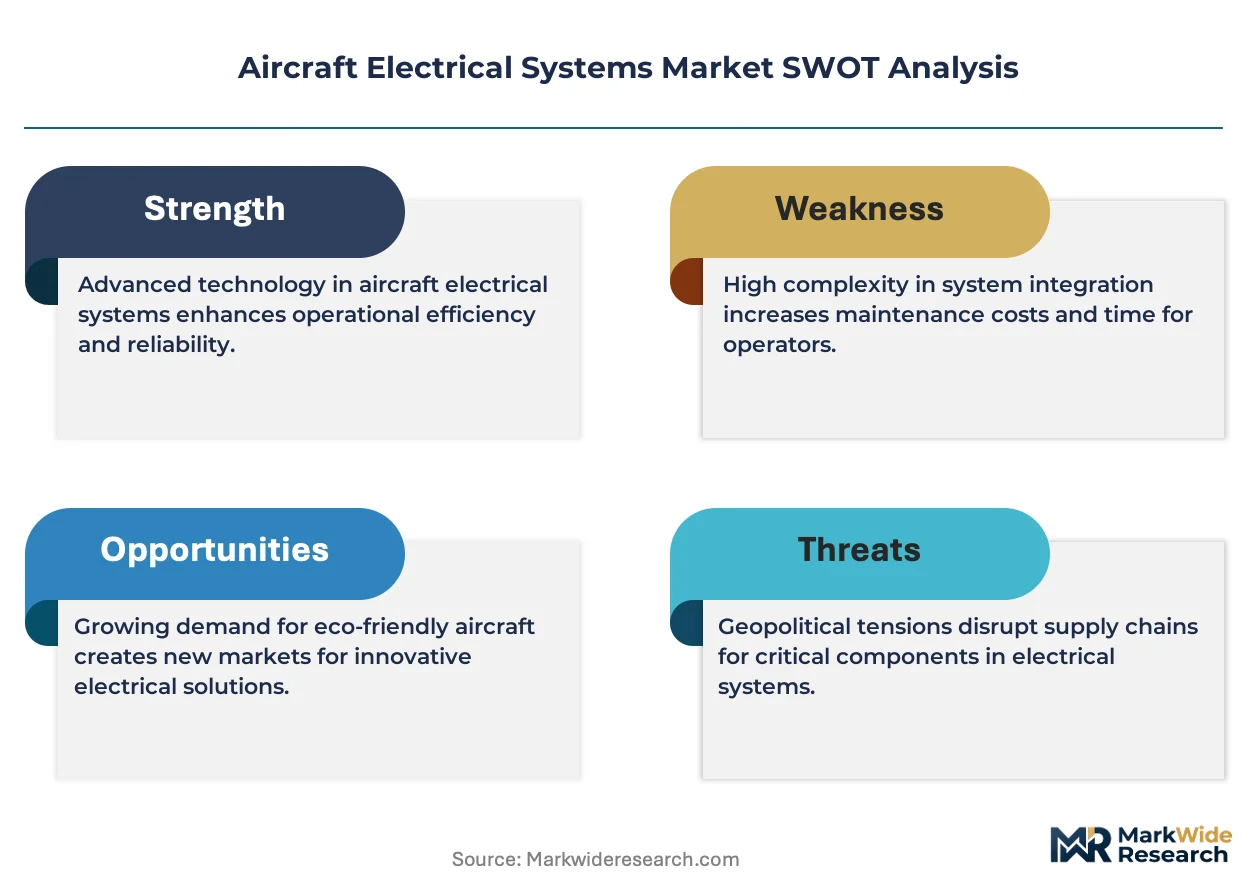
The aircraft electrical systems market is characterized by a vertical-integration race, as major players like Collins Aerospace pursue deeper control over specialized high-voltage component manufacturing. This strategy aims to secure critical supply and enhance system performance.
For Market Incumbents: Anticipate the increasing demand for high-voltage DC architectures by accelerating internal R&D into solid-state power control and advanced thermal management solutions. Secure long-term supply agreements for specialized semiconductors to mitigate supply chain bottlenecks, a threat to program execution. Strategic partnerships with aircraft OEMs, coupled with significant investment in DO-160 certification for next-generation systems, will reinforce market leadership.
For New Entrants and Emerging Players: Enter via niche segments like Advanced Air Mobility (AAM), which requires compact, high-power-density electrical systems for eVTOL aircraft. Focus on developing modular high-voltage DC power distribution units that offer superior weight savings and integration flexibility. A go-to-market angle emphasizing rapid prototyping and agile certification pathways for emerging platforms can disrupt established players.
For Investors and Strategic Acquirers: Re-rating potential sits with agile power electronics specialists given the irreversible trend towards aircraft electrification and net-zero aviation goals. Focus on acquisition targets possessing expertise in high-voltage DC architectures or lightweight wiring harnesses, crucial for future aircraft platforms. A key signal to watch is the continued harmonization of EASA and FAA certification standards for electric propulsion, indicating market maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in HVDC Architecture R&D | Safran S.A. can solidify its leadership in next-generation power systems for more-electric aircraft platforms. |
| Acquire Power Electronics Specialists | Collins Aerospace can expand its portfolio of high-density components for advanced air mobility applications. |
| Secure Long-term Semiconductor Supply | Honeywell International Inc. ensures stable production amidst global supply chain volatility for critical aerospace components. |
| Develop Lightweight Wiring Harnesses | Manufacturers can capture growing demand from commercial aviation for fuel-efficient retrofit solutions across existing fleets. |
| Pursue eVTOL System Integration | Emerging players can establish early market share in the rapidly expanding Advanced Air Mobility sector. |
Research Approach
Document review covered FAA and EASA certification documents, aerospace OEM financial reports, and industry association publications, complemented by interviews with aerospace engineers and procurement leads. Primary fieldwork involved discussions with regulatory affairs specialists and power electronics R&D directors to gather qualitative insights. This approach facilitated bottom-up and top-down triangulation, ensuring data consistency and market understanding.
The quantitative model produced volume and value projections across the analysis window, segmented by product type, technology, end user, application, and voltage architecture. Compound annual growth rates were derived from historical data and projected shifts in more-electric aircraft adoption. Key forecast inputs included anticipated aircraft delivery schedules and evolving regulatory emission targets from bodies like the EU Green Deal.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological shifts or unforeseen regulatory changes. These forecasts reflect current market assumptions regarding the pace of HVDC system certification and supply chain stability for specialized components. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Electrified Aircraft Propulsion Market
Aircraft Power Systems
Commercial Aircraft Propeller Systems Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Hydraulic System Market
Aircraft Power Systems
Global Aircraft Micro Turbine Market
Aircraft Power Systems
Commercial Aviation Electrical Wiring Interconnection System (EWIS) Market
Aircraft Power Systems
More Electric Aircraft Market
Aircraft Power Systems
Military Power Solutions Market
Aircraft Power Systems
Aviation High Speed Motor Market
Aircraft Power Systems
Aerospace and Military Auxiliary Power Unit (APU) Market
Aircraft Power Systems
Thrust Vector Control (TVC) Systems Market