
 Aircraft Turbocharger Market | 2026-2036
Aircraft Turbocharger Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Turbocharger Market Analysis
Modular turbocharger kits are decoupling engine upgrades from full powerplant replacements, giving general aviation owners more granular spending control. Hartzell Engine Technologies leverages its vertically integrated casting and machining operations to dominate the piston-engine aftermarket. Garrett Motion Inc. competes through advanced variable-geometry designs optimized for sustainable aviation fuel combustion profiles.
An aircraft turbocharger is a centrifugal or axial-flow compressor driven by exhaust gas energy, typically operating at shaft speeds exceeding 80,000 RPM to boost manifold pressure and restore sea-level power density at altitude; its primary purpose is to compensate for atmospheric density loss during climb and cruise operations in reciprocating and turboprop engines. Twin-spool architectures now anchor the commercial aviation segment due to superior thermal efficiency and part-load performance, while variable-geometry systems represent the fastest-growing product category as operators seek altitude-agnostic fuel economy. The MRO services end-user channel occupies disproportionate margin pools because overhaul intervals compress under higher boost pressures and lean-of-peak operating regimes.
FAA Part 33 airworthiness standards govern turbocharger durability and containment requirements in the United States, while EASA CS-E certification in Europe imposes additional blade-out and vibration test protocols that extend development timelines. The EU Green Deal's escalating SAF blending mandates are forcing turbocharger manufacturers to redesign compressor maps and materials for alternative fuel combustion chemistry. Stakeholders must monitor how dual-certification strategies and fuel-flexible architectures reshape competitive positioning across regulatory jurisdictions.
Market Dynamics
FAA Part 33 certification timelines and sustainable aviation fuel compatibility mandates are compressing product development cycles while forcing simultaneous hardware and materials redesigns across the piston-engine aftermarket.
Growth Catalysts
- SAF Blending Mandates:The EU Green Deal's escalating sustainable aviation fuel requirements are forcing turbocharger manufacturers to redesign compressor maps and combustion chamber geometries for alternative fuel chemistry.
- Flight Training Expansion:United States-based flight schools are accelerating fleet renewals with turbocharged piston aircraft to improve high-altitude training capabilities and reduce weather cancellations.
- Modular Retrofit Kits:Granular engine upgrade solutions are decoupling turbocharger replacements from full powerplant overhauls, lowering capital barriers for private owner-operators.
Market Restraints
- Inconel and Titanium Input Costs:Superalloy price volatility for turbine wheels and compressor housings compresses margin pools at the OEM tier.
- Dual-Certification Burden:EASA CS-E blade-out and vibration protocols extend development timelines beyond FAA Part 33 baselines, freezing capital in regulatory limbo.
- Electric Propulsion Substitution:Battery-electric and hydrogen fuel cell architectures in sub-19-seat segments threaten long-term piston-engine turbocharger addressable demand.
Strategic Opportunities
- Unmanned Aerial Systems:Turbocharged heavy-fuel engines for military drones and cargo UAVs represent a greenfield application segment with minimal incumbent competition.
- India's UDAN Regional Connectivity Scheme:Subsidized turboprop routes are stimulating demand for altitude-capable engines in Himalayan and Northeastern corridor operations.
- Digital Twin Integration:Convergence of physics-based modeling and IoT sensor streams enables predictive MRO scheduling, capturing aftermarket margin from unscheduled downtime avoidance.
Industry Challenges
- Aerothermal Simulation Talent Scarcity:CFD and combustion modeling expertise for high-RPM rotating machinery concentrates in legacy aerospace hubs, constraining R&D scaling.
- Legacy Fleet Integration Complexity:Retrofitting variable-geometry systems onto 1960s-1980s airframe architectures requires custom exhaust manifold engineering and STC approvals.
- Containment Test Capex Intensity:FAA Part 33 blade-out certification requires dedicated spin-pit facilities costing eight figures, favoring incumbents with captive test infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Turbocharger Market |
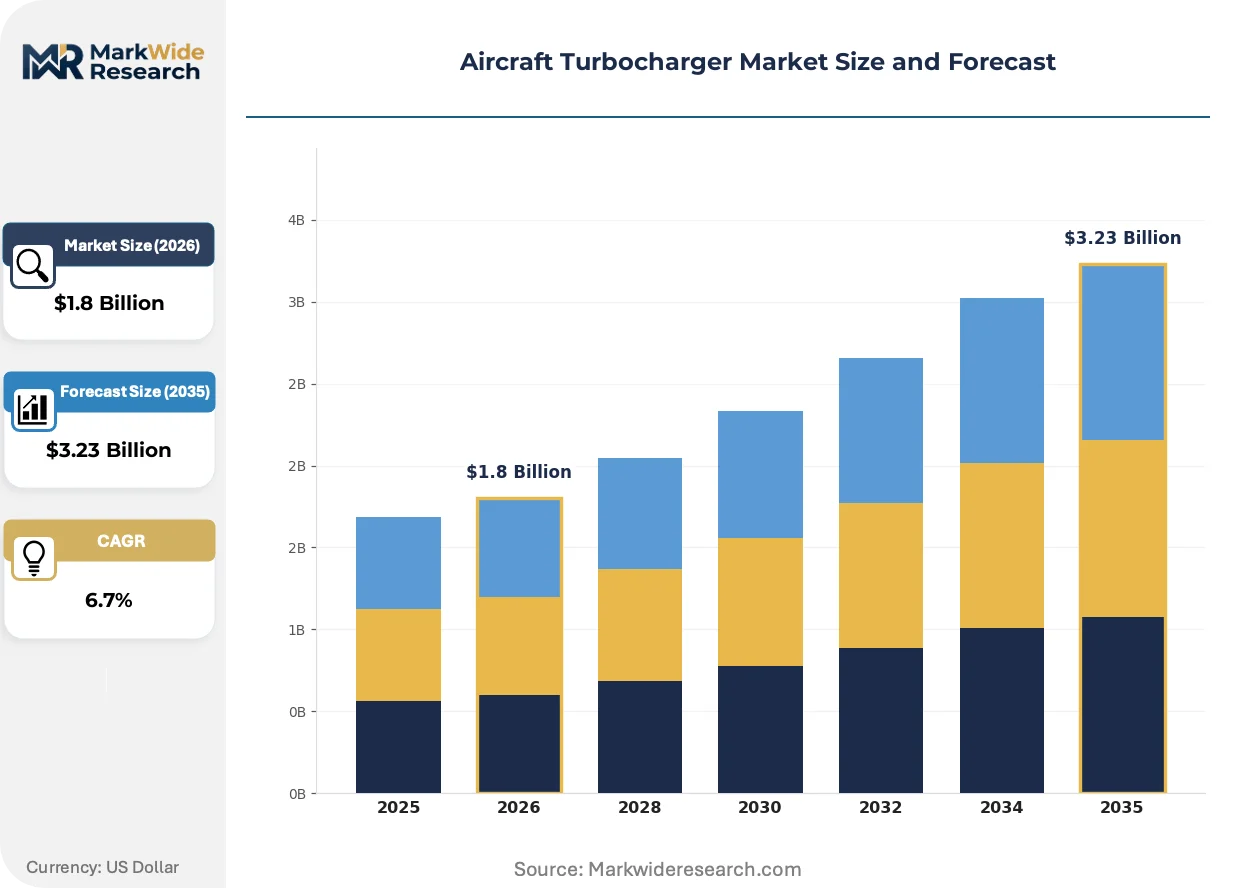
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Spool, Twin-Spool, Variable Geometry, Axial-Flow End User: Commercial Aviation, Military Aviation, General Aviation, MRO Services Installation Type: OEM, Aftermarket, Retrofit, Remanufactured Fuel Type: Jet A, Avgas, Sustainable Aviation Fuel, Biofuel |
| Companies Covered | Hartzell Engine Technologies LLC, Mitsubishi Heavy Industries Engine & Turbocharger Ltd., General Electric Company, IHI Corporation, ABB Ltd., Honeywell International Inc., Kawasaki Heavy Industries, Ltd., Garrett Motion Inc., BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Turbocharger Market Emerging Trajectories
Twin-spool variable-geometry architectures are displacing fixed-geometry designs as the dominant technical platform, while digitalization of MRO workflows and SAF-driven materials science are rewriting competitive differentiation criteria.
Variable-geometry turbochargers with sliding nozzle rings and electronically actuated wastegates are overtaking fixed-geometry units in new piston-engine platforms. Flight training operators in the United States are specifying these systems for altitude-agnostic fuel economy. The technology is compressing the performance gap between naturally aspirated and turbocharged powerplants at mid-altitude cruise regimes.
The EU Green Deal's sustainable aviation fuel blending mandates are forcing compressor map redesigns for broader fuel flexibility. Manufacturers must validate hardware across Jet-A, SAF blends, and potential future e-fuels without hardware swaps. European OEMs are responding with nickel-based superalloy turbine wheels and revised bearing cooling circuits to manage alternative fuel combustion temperatures.
Aftermarket procurement is fragmenting from bundled engine overhauls toward component-level turbocharger replacement decisions. Independent MRO shops in the United States are capturing margin from owner-operators seeking granular cost control. This unbundling is most visible in the Cirrus and Cessna single-engine piston fleets where TBO extensions have compressed traditional overhaul cycles.
Aircraft Turbocharger Market Segmentation
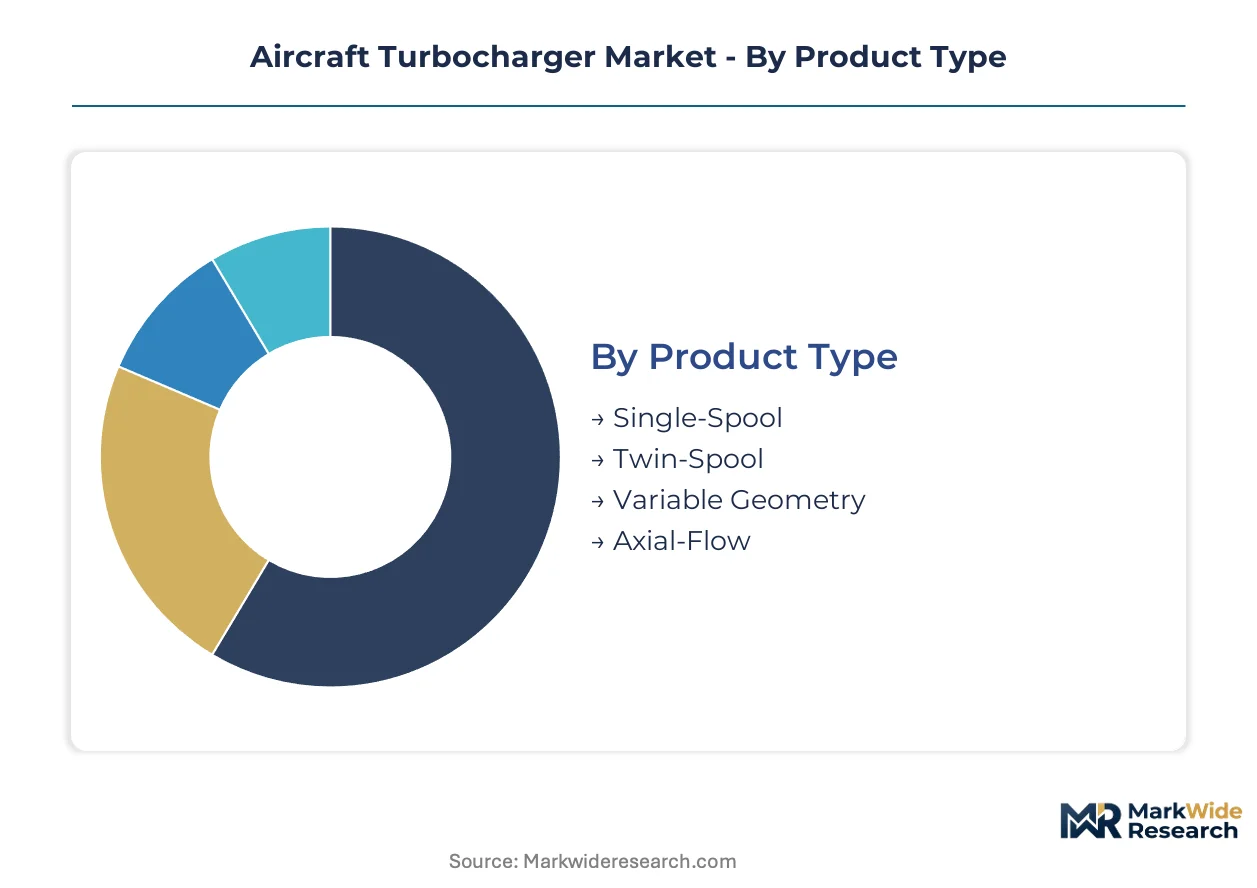
Turbocharger procurement decisions fragment across four distinct axes: technical architecture dictates performance ceilings, end-use application determines certification burden, installation channel controls margin capture, and fuel chemistry shapes materials selection. Each segmentation layer carries independent pricing logic and competitive dynamics.
Product Type:
Altitude requirements and thermal efficiency targets drive architecture selection more than unit cost considerations.
- Twin-Spool:Dual-shaft configurations separate compressor and turbine speed regimes, enabling broader operating maps without surge margin compromise. Commercial turboprop operators in the United States specify these for high-altitude cargo routes where part-load efficiency determines fuel economics.
- Variable Geometry:Sliding nozzle rings and electronically actuated wastegates adjust turbine swallowing capacity in real-time. Flight training schools favor these systems for altitude-agnostic power delivery that reduces weather-related cancellations during high-density-altitude operations.
- Single-Spool:Fixed-shaft designs dominate legacy piston-engine retrofits where simplicity outweighs efficiency gains.
- Axial-Flow:Compact multi-stage compressors serve auxiliary power units and small turboprops with severe weight constraints.
Volume sits with Twin-Spool; growth tilts toward Variable Geometry.
End User:
Certification pathway and overhaul interval economics segment buyer behavior more sharply than fleet size or procurement volume.
- MRO Services:Independent overhaul facilities capture disproportionate margin from unscheduled turbocharger replacements and TBO extensions. Lean-of-peak operating regimes in the United States general aviation fleet have compressed traditional overhaul cycles, accelerating aftermarket parts velocity.
- General Aviation:Owner-operators and flight schools drive modular retrofit demand, decoupling turbocharger upgrades from full engine overhauls. FAA Part 33 certification standards govern replacement part eligibility, creating regulatory stickiness for PMA-approved alternatives.
- Commercial Aviation:Scheduled line maintenance and power-by-the-hour contracts concentrate procurement authority with airframe OEMs and tier-one engine suppliers.
- Military Aviation:Heavy-fuel compatibility and sand ingestion tolerance specifications diverge from civil requirements, insulating this segment from commercial pricing pressure.
Procurement authority concentrates with Commercial Aviation; margin expansion favors MRO Services.
Installation Type:
Channel selection determines warranty coverage, technical support depth, and regulatory documentation burden.
- Aftermarket:Component-level replacement decisions unbundle from bundled engine overhauls, giving United States-based independent shops entry into Cirrus and Cessna single-engine fleets. Granular spending control appeals to private owner-operators facing compressed TBO intervals.
- Retrofit:STC-approved variable-geometry conversions onto 1960s-1980s airframes require custom exhaust manifold engineering. The segment climbs fastest where legacy fleet renewal lags behind new aircraft deliveries.
- OEM:Factory installation locks in long-term spare parts revenue through proprietary part numbers and warranty conditions.
- Remanufactured:FAA-approved core recovery programs offer cost alternatives for non-critical training aircraft operations.
Revenue weight rests with OEM; aftermarket velocity is accelerating most quickly.
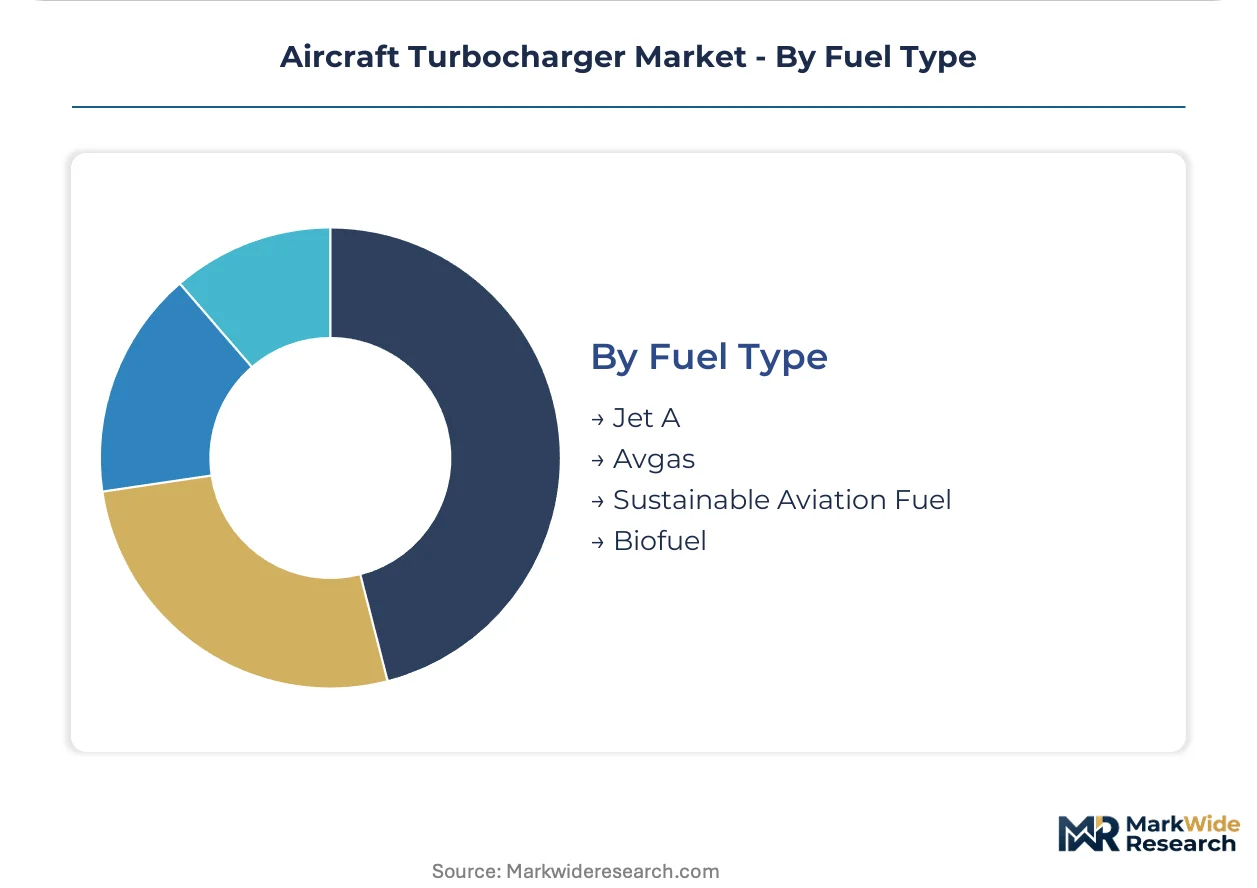
Fuel Type:
Combustion chemistry and thermal profiles now dominate materials selection and compressor map design priorities.
- Sustainable Aviation Fuel:Blending mandates under the EU Green Deal force validation across aromatic content variations without hardware swaps. Nickel-based superalloy turbine wheels and revised bearing cooling circuits manage alternative fuel combustion temperatures.
- Jet A:Kerosene-grade specifications anchor commercial turboprop and auxiliary power unit requirements, with established supply chains and predictable thermal profiles.
- Avgas:100LL and unleaded formulations serve piston-engine general aviation where lead content and octane sensitivity constrain combustion chamber design.
- Biofuel:FAME and HVO pathways face cold-flow and oxidation stability challenges that limit high-altitude deployment without additive packages.
Installed base clusters around Jet A; development investment is shifting most aggressively toward Sustainable Aviation Fuel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Japan and Germany where precision casting and superalloy machining clusters serve OEM supply chains, while consumption tilts toward the United States where general aviation fleet density and flight training expansion drive aftermarket velocity.
United States
Flight schools in Florida and Arizona are accelerating turbocharged piston renewals to reduce weather cancellations during high-density-altitude training. FAA Part 33 certification standards govern replacement part eligibility, creating regulatory stickiness for PMA-approved alternatives. Wichita, Kansas anchors the general aviation manufacturing corridor where Cessna and Cirrus production lines source factory-installed systems.
Germany
Commercial turboprop operators serving Alpine cargo routes specify twin-spool architectures for part-load efficiency above 10,000 feet. EASA CS-E blade-out and vibration protocols extend development timelines beyond FAA baselines, freezing capital in regulatory certification. Munich-Stuttgart industrial corridor houses specialized foundries producing Inconel turbine wheels for European engine programs.
Japan
Precision machining clusters in Aichi Prefecture supply compressor housings and shaft assemblies to global engine OEMs. METI industrial standards govern materials traceability and quality documentation for aerospace exports. Nagoya manufacturing belt concentrates rotational machinery expertise that supports both civil aviation and defense applications.
United Kingdom
Specialized MRO facilities at Cranfield and around London Gatwick capture margin from European general aviation operators seeking component-level turbocharger overhauls. CAA airworthiness requirements align with EASA frameworks but retain distinct approval pathways for legacy piston-engine retrofits. Southwest England maintains remnant casting capacity serving niche military and heritage aircraft programs.
India
UDAN regional connectivity subsidies are stimulating turboprop demand for Himalayan and Northeastern corridor operations above 8,000 feet. DGFT import licensing frameworks govern aviation component procurement, creating localization incentives for assembly operations. Bangalore-Hyderabad aerospace cluster is emerging as a maintenance hub for Southeast Asian operators seeking cost-advantaged overhaul services.
Aircraft Turbocharger Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct tiers. Tier-one players leverage captive casting infrastructure and FAA-certified spin-pit facilities to defend OEM installation share. Tier-two independents capture aftermarket margin through PMA-approved alternatives and STC engineering for legacy retrofits. Tier-three regional fabricators serve military drone and auxiliary power unit niches with minimal certification burden. Consolidation pressures intensify as EASA-FAA dual-certification requirements raise capital barriers, while technology licensing agreements proliferate for SAF-compatible compressor designs.
Within the vertically integrated tier, Hartzell Engine Technologies LLC and Garrett Motion Inc. exemplify divergent strategic postures. Hartzell anchors the piston-engine aftermarket through in-house superalloy casting and machining operations spanning its Ohio manufacturing base. Garrett Motion occupies a position at the technology frontier, with its corporate structure reflecting automotive-aerospace convergence. Mitsubishi Heavy Industries Engine & Turbocharger Ltd. represents the diversified industrial conglomerate archetype, leveraging shared precision manufacturing platforms across power generation and aviation applications.
| Leading Market Players |
|---|
| Hartzell Engine Technologies LLC |
| Mitsubishi Heavy Industries Engine & Turbocharger Ltd. |
| General Electric Company |
| IHI Corporation |
| ABB Ltd. |
| Honeywell International Inc. |
| Kawasaki Heavy Industries, Ltd. |
| Garrett Motion Inc. |
| BorgWarner Inc. |
| Others |
Supply Flow & Price Mechanics
Variable-geometry turbocharger adoption is compressing fixed-geometry cost structures while concentrating procurement authority with OEMs possessing captive spin-pit certification infrastructure. This technology transition simultaneously elevates R&D amortization burdens and locks out price-competitive challengers lacking FAA Part 33 approved test facilities.
Pricing Analysis
Margin tightening in the aftermarket tier reflects superalloy input volatility and compressed TBO intervals under lean-of-peak operating regimes. Three-tier pricing structure across PMA-approved alternatives, OEM factory-new units, and remanufactured cores segments buyer archetypes by certification tolerance and technical risk appetite. Flight schools exhibit acute price sensitivity due to high-cycle utilization economics, while commercial turboprop operators prioritize power-by-the-hour predictability over unit acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Japanese precision machining clusters for compressor housings and German foundry capacity for Inconel turbine wheels. The supply chain draws from Aichi Prefecture rotational machinery expertise, Munich-Stuttgart superalloy casting, and Ohio-based integrated manufacturing for piston-engine aftermarket dominance. Tariff exposure on aerospace-grade titanium concentrates risk at the turbine wheel tier. Distribution runs through airframe OEM captive channels, independent MRO procurement networks, and military drone systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where FAA Part 33 spin-pit certification infrastructure scarcity props pricing power for incumbent OEMs. Capacity bottlenecks in aerothermal simulation talent and superalloy precision casting defend margin pools against commoditization pressure.
For Market Incumbents: Acquire captive aerothermal simulation capability to compress development cycles for SAF-compatible compressor maps. Defend aftermarket share through backward integration into core recovery programs and exclusive PMA distribution agreements with flight school networks. Electric propulsion substitution in sub-19-seat segments threatens long-term piston-engine addressable demand, requiring dual-certification investment as defensive moat. For New Entrants and Emerging Players: Enter via unmanned aerial systems heavy-fuel engine applications where military procurement tolerates higher unit costs and minimal incumbent competition exists. India's UDAN-subsidized turboprop routes present penetrable white space for altitude-capable variable-geometry systems. License SAF-validated compressor designs from European OEMs to shortcut EASA CS-E certification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking aerospace exposure. Five-to-ten year viability hinges on electric-hybrid architecture substitution rates in general aviation. Monitor FAA Part 33 certification backlog duration as inflection indicator for incumbent pricing power durability.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Hardware Validation | EU Green Deal mandates force compressor map redesigns without hardware swap flexibility for operators. |
| Digital Twin Integration | Physics-based modeling convergence with IoT sensor streams enables predictive MRO scheduling for flight schools. |
| Dual-Certification Investment | EASA CS-E blade-out protocols extend development timelines, freezing capital and favoring incumbents with captive infrastructure. |
| Modular Retrofit Kit Development | Granular engine upgrades decouple turbocharger replacements from full powerplant overhauls for Cirrus and Cessna fleets. |
| Unmanned Aerial Systems Entry | Military drone heavy-fuel compatibility specifications diverge from civil requirements, insulating margins from commercial pricing pressure. |
Methodological Framework
Multi-period observation of fleet renewal cycles, TBO interval compression, and SAF blending mandate escalation anchored the trend analysis, supplemented by interviews with MRO facility directors, general aviation owner-operators, flight school fleet managers, and FAA certification engineers. Secondary validation drew from FAA Part 33 type certificate databases, EASA CS-E certification timelines, EU Green Deal regulatory filings, and METI industrial standards documentation. Bottom-up triangulation of component-level procurement velocity converged with top-down powerplant production forecasts.
Input-output matrices modeled unit shipments and value flows across twin-spool, variable-geometry, single-spool, and axial-flow architectures through the projection horizon. Segmentation dimensions encompassed product type, end-user channel, installation pathway, and fuel chemistry compatibility. CAGRs were derived from regression analysis of historical fleet renewal patterns and forward projection of regulatory mandate implementation curves. Industry-specific inputs included flight training expansion rates in the United States and UDAN route subsidy allocation trajectories in India.
Revisions become necessary when electric propulsion substitution accelerates beyond current technology readiness levels, superalloy price volatility exceeds historical bands, or EASA-FAA regulatory divergence widens certification burden asymmetries. Deviation in SAF blending mandate enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Battery Market
Aircraft Power Systems
Aircraft Fluid Power Components Market
Aircraft Power Systems
UAV Propulsion System Market
Aircraft Power Systems
Aircraft Thrust Reverser Actuation Systems Market
Aircraft Power Systems
Aircraft Drive Shaft and Couplings Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market
Aircraft Power Systems
Aircraft Turboprop Propeller System Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Circuit Breakers Market