
 Aircraft Battery Market | 2026-2036
Aircraft Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Battery Market Intelligence
DO-160G qualification standards is redrawing procurement criteria across the supply base. Saft leverages its European manufacturing footprint to sustain long-term contracts with Airbus and Dassault. EnerSys anchors North American aftermarket channels through EaglePicher Technologies, which specializes in military-grade silver-zinc systems. MarathonNorco Aerospace competes on price in the regional turboprop segment.
An aircraft battery is an electrochemical energy storage device engineered to deliver specified cold-cranking amperage at temperatures as low as minus 40 degrees Celsius, with nickel-cadmium cells employing a potassium hydroxide electrolyte and lithium-ion variants using cobalt-oxide or iron-phosphate cathode architectures. Its primary function is to provide engine starting power, emergency backup for flight-critical avionics, and auxiliary power unit ignition when main generators are offline. Lithium-ion chemistry captures the fastest expansion as operators trade energy density gains against thermal management complexity, while nickel-cadmium retains dominance in military platforms where NATO standardization and deep-cycle resilience override weight penalties. Emergency Power applications generate premium pricing relative to Ground Power units due to airworthiness certification burdens.
The FAA mandates RTCA DO-311A testing for rechargeable lithium aircraft batteries, while EASA enforces ED-79A compliance and China's CAAC aligns with GB standards for aviation equipment import. These frameworks elevate R&D barriers and consolidate procurement around certified suppliers. Military Aviation end users face additional MIL-PRF-8565J specifications that extend qualification timelines. Stakeholders must monitor solid-state electrolyte maturation and sulfur-based cathode research as pathways to displace incumbent chemistries without sacrificing safety margins.
Market Dynamics
Fleet electrification programs across commercial aviation are forcing a chemistry transition from nickel-cadmium to lithium-ion systems, while thermal runaway containment standards from the FAA and EASA compress supplier qualification timelines and consolidate procurement around certified manufacturers.
Growth Catalysts
- ED-79A Compliance Mandate:EASA's tightened certification requirements for lithium-based aircraft batteries are filtering out uncertified suppliers and concentrating contract awards among qualified European manufacturers serving Airbus and Dassault programs.
- Commercial Fleet Electrification:Airlines are retrofitting auxiliary power units with higher-density lithium-ion packs to reduce fuel burn during ground operations, creating pull-through demand for replacement battery systems.
- Silver-Zinc Chemistry:Military platforms requiring NATO-standardized deep-cycle resilience continue specifying silver-zinc architectures for emergency power applications, sustaining specialized production lines at EaglePicher Technologies and similar defense-focused suppliers.
Market Restraints
- Cobalt Supply Concentration:Lithium-ion cathode production depends on cobalt oxide feedstocks concentrated in Central African mining operations, exposing cell manufacturers to price volatility and ethical sourcing audit burdens.
- MIL-PRF-8565J Qualification Burden:Military aviation procurement requires extended testing timelines for rechargeable systems, stretching working capital cycles and deterring commercial suppliers from entering defense contracts.
- Potassium Hydroxide Electrolyte Handling:Nickel-cadmium maintenance infrastructure at MRO facilities requires specialized hazmat protocols that operators are reluctant to sustain as fleet transitions accelerate toward lithium chemistries.
Strategic Opportunities
- China CAAC GB Standards Alignment:Domestic certification pathways for aviation equipment import are creating openings for foreign suppliers to establish local assembly partnerships serving COMAC and regional airline expansion.
- Solid-State Electrolyte Maturation:Sulfur-based cathode research combined with ceramic electrolyte development offers a pathway to displace incumbent cobalt-oxide architectures without sacrificing the safety margins required by DO-311A testing protocols.
- Emergency Power Premium Positioning:Airworthiness certification burdens for flight-critical backup systems sustain pricing power relative to ground power units, rewarding suppliers who maintain dual-chemistry qualification portfolios.
Industry Challenges
- Thermal Management Engineering Scarcity:Lithium-ion system integration requires specialized expertise in cell balancing and runaway containment that outpaces current aerospace electrical engineering pipeline output.
- DO-160G Environmental Qualification:Vibration and altitude testing protocols for new battery designs extend development cycles, compressing window for return on R&D investment before chemistry obsolescence.
- Legacy Nickel-Cadmium Fleet Support:Operators maintaining mixed fleets face dual inventory and technician certification requirements during transition periods, creating operational friction and supplier switching costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Battery Market |
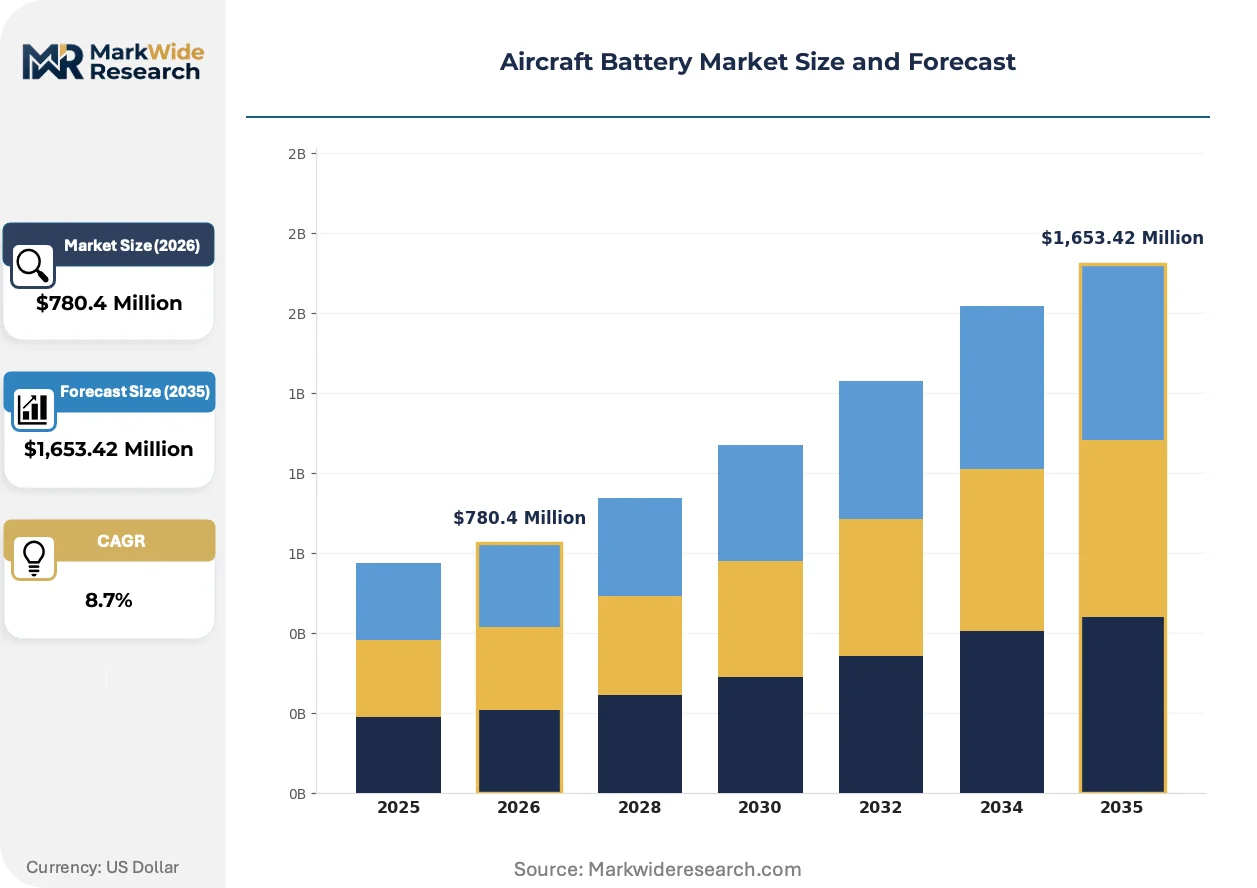
| Market Size in 2026 | $780.4 Million |
| Market Size in 2035 | $1,653.42 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Type: Nickel-Cadmium, Lithium-ion, Lead-Acid, Silver-Zinc, Lithium Polymer Application: Emergency Power, Auxiliary Power Unit, Ground Power, Passenger Systems, Communication Equipment End User: Commercial Airlines, Military Aviation, Business Jets, Helicopter Operators, Cargo Carriers Deployment: Original Equipment Manufacturer, Aftermarket Replacement, Maintenance & Repair, Retrofit Installations, Leasing |
| Companies Covered | GS Yuasa International Ltd., MarathonNorco Aerospace, Saft, Amprius Technologies, Teledyne Technologies, EnerSys, EaglePicher Technologies, Mid-Continent Instrument Co. Inc., Concorde Battery Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Battery Market Strategic Shifts & Innovations
Lithium-ion architectures are fragmenting the installed base as operators trade energy density against thermal complexity, while regulatory pressure on containment standards accelerates supplier consolidation and chemistry specialization.
Solid-state electrolyte development is bifurcating the advanced battery segment. Ceramic and polymer-ceramic hybrid electrolytes promise higher ionic conductivity with reduced flammability risk compared to liquid organic systems. Boeing and Airbus supplier qualification teams are screening solid-state prototypes for narrow-body platform integration, though manufacturing scalability remains constrained. This technology is bifurcating the R&D allocation between incumbent liquid-electrolyte optimization and next-generation solid-state platform development.
RTCA DO-311A testing protocols are tightening entry barriers for rechargeable lithium aircraft batteries in the United States. The FAA mandate requires multi-cell abuse testing and propagation resistance validation that adds eighteen to twenty-four months to qualification timelines. Commercial aviation OEMs are responding by consolidating supplier panels and requiring long-term chemistry roadmaps before contract award, compressing opportunities for new market entrants.
Aftermarket channel consolidation is reshaping battery procurement patterns across North American MRO networks. EaglePicher Technologies and Saft have established direct distribution agreements with major maintenance facilities, bypassing traditional aerospace distributors. This disintermediation is most visible in the United States, where regional airlines operating turboprop fleets now source nickel-cadmium replacements through manufacturer-authorized service centers rather than independent parts brokers.
Aircraft Battery Market Segmentation
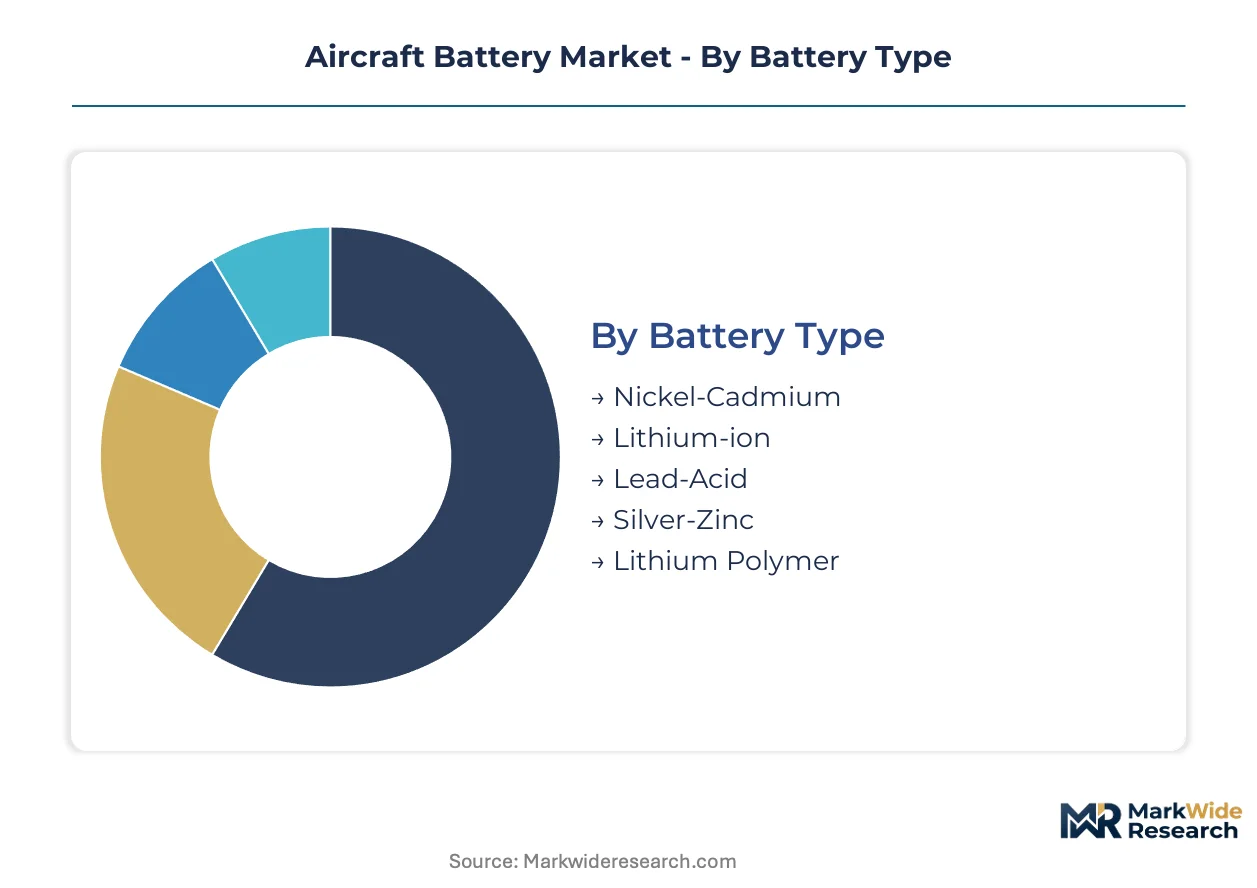
Segmentation in aircraft batteries reflects divergent certification burdens and chemistry trade-offs across operational profiles. Procurement patterns split between OEM line-fit programs demanding multi-year supply commitments and aftermarket channels serving mixed-fleet operators navigating transition timelines between nickel-cadmium and lithium-ion systems.
Battery Type:
Domestic production clusters around established chemistries with regional qualification advantages, while export-led segments concentrate where certification reciprocity agreements reduce re-qualification costs for foreign suppliers.
- Lithium-ion:Cobalt-oxide and iron-phosphate cathode architectures deliver energy density gains for auxiliary power unit electrification. Demand concentrates at Airbus and Boeing final assembly lines in Toulouse, Hamburg, and Charleston as fleet retrofit programs accelerate. FAA DO-311A and EASA ED-79A testing protocols compress supplier panels to qualified manufacturers with proven thermal runaway containment.
- Nickel-Cadmium:Potassium hydroxide electrolyte systems maintain NATO-standardized deep-cycle resilience for military platforms. Procurement centers on defense procurement agencies in the United States, France, and Germany where MIL-PRF-8565J specifications extend qualification timelines and deter commercial crossover.
- Lead-Acid:Legacy chemistry persists in ground power units and training aircraft where weight penalties matter less than acquisition cost.
- Silver-Zinc:Specialized military emergency power applications at EaglePicher and Saft sustain low-volume production with premium pricing.
- Lithium Polymer:Emerging solid-state electrolyte research targets narrow-body platform integration, though manufacturing scalability remains constrained.
Nickel-Cadmium commands the established base. The steepest expansion runs through Lithium-ion.
Application:
Cost tier stratification separates flight-critical systems with airworthiness certification burdens from ground support equipment with lighter regulatory oversight.
- Emergency Power:Flight-critical backup for avionics and control surfaces demands RTCA DO-160G environmental qualification plus propagation resistance validation. Pricing premiums reflect eighteen to twenty-four month certification timelines and limited supplier pools in the United States and Germany.
- Auxiliary Power Unit:Higher-density lithium-ion packs reduce fuel burn during ground operations at United, Delta, and Lufthansa hubs. EASA ED-79A compliance filters procurement toward Saft and qualified European manufacturers.
- Ground Power:External cart and hangar systems face lighter FAA oversight, enabling price competition from regional suppliers.
- Passenger Systems:In-seat power and galley loads drive lower-tier battery specifications with faster replacement cycles.
- Communication Equipment:Military platforms specify silver-zinc for NATO interoperability in emergency transponder applications.
Ground Power captures volume through fleet standardization. Emergency Power sustains margin through certification scarcity.
End User:
Customer type determines procurement rhythm, with scheduled carriers negotiating multi-year framework agreements while military buyers extend qualification cycles through specification volatility.
- Commercial Airlines:Fleet electrification programs at American, Air France-KLM, and China Southern drive lithium-ion transition with line-fit commitments to Airbus and Boeing. DO-311A testing requirements consolidate supplier relationships around chemistry roadmaps.
- Military Aviation:Pentagon, DGA France, and BAAINBw procurement maintains nickel-cadmium and silver-zinc specifications for deep-cycle resilience under combat conditions.
- Business Jets:Gulfstream and Dassault Falcon operators prioritize weight reduction, pulling lithium-ion into retrofit installations.
- Helicopter Operators:Sikorsky and Airbus Helicopter platforms sustain mixed chemistry demand across civil and defense variants.
- Cargo Carriers:FedEx and UPS fleet standardization creates concentrated aftermarket demand for replacement batteries at Memphis and Louisville hubs.
Military Aviation anchors legacy chemistry demand. Commercial Airlines are expanding most quickly through electrification mandates.
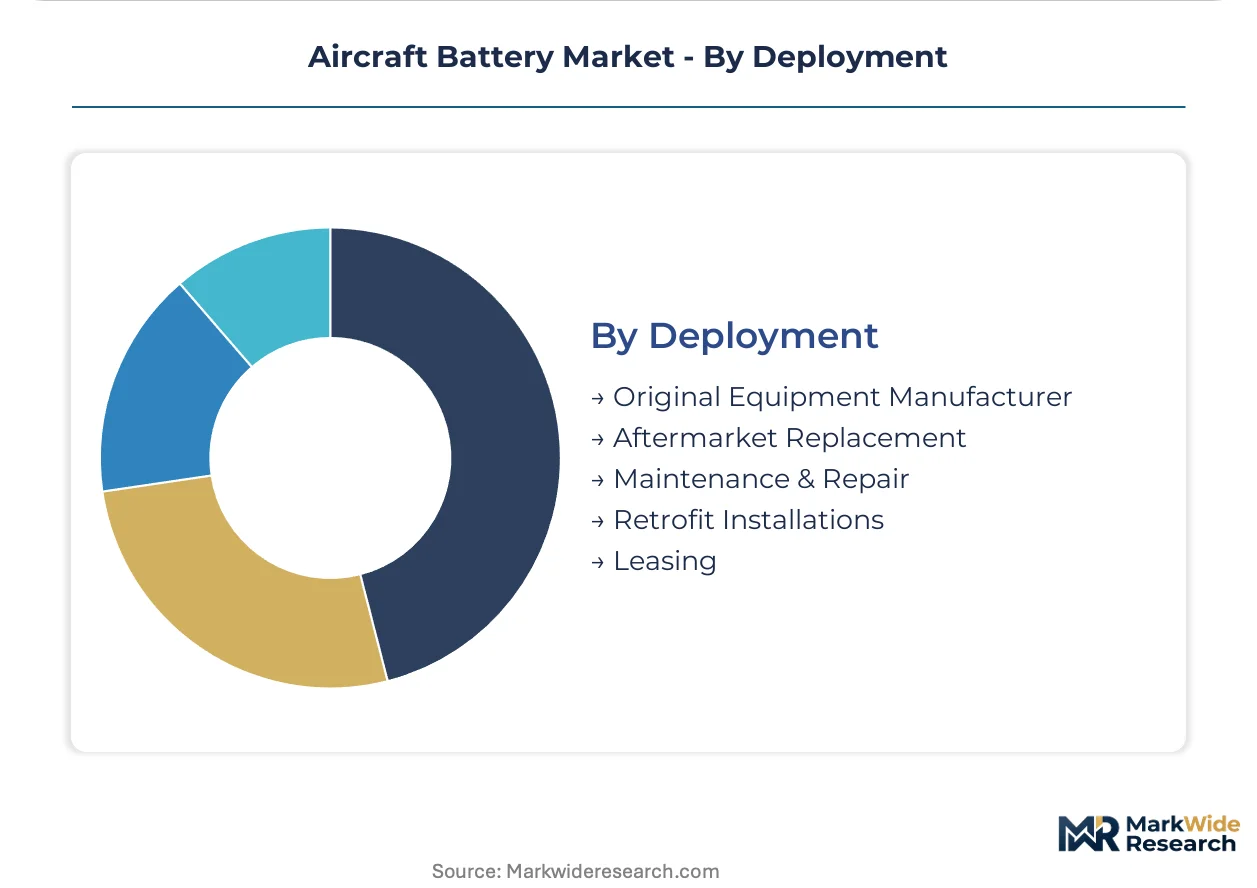
Deployment:
Supply concentration varies sharply across deployment modes, with OEM line-fit controlled by airframers and aftermarket channels consolidating through manufacturer-direct distribution.
- Original Equipment Manufacturer:Airbus, Boeing, and COMAC battery specifications are locked years before first flight, requiring suppliers to commit chemistry roadmaps for program duration. Saft's European manufacturing footprint secures long-term Dassault and Airbus contracts.
- Aftermarket Replacement:EaglePicher and MarathonNorco have established direct distribution with major MRO facilities, bypassing traditional aerospace distributors in the United States.
- Maintenance & Repair:Specialized hazmat protocols for potassium hydroxide handling compress nickel-cadmium service capacity as technicians retrain for lithium systems.
- Retrofit Installations:STC pathways for lithium-ion conversion face FAA field approval bottlenecks, stretching project timelines.
- Leasing:Lessors like AerCap and GECAS specify battery condition standards in return conditions, creating pooled replacement demand.
Original Equipment Manufacturer locks in long-term supply relationships. Aftermarket Replacement is gaining share fastest through channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in aircraft batteries track certification reciprocity agreements, with surplus capacity in qualified manufacturing zones shipping to emerging fleet operators. Trade patterns concentrate where FAA, EASA, and CAAC alignment reduces re-qualification burdens for cross-border suppliers.
United States
Commercial fleet electrification at American, Delta, and United hubs drives lithium-ion procurement for auxiliary power unit retrofits. FAA DO-311A testing mandates filter supplier panels to domestic-qualified manufacturers. Charleston and Wichita clusters anchor Boeing supplier networks with dedicated battery integration facilities.
Germany
Lufthansa Group fleet standardization creates concentrated aftermarket demand at Hamburg and Frankfurt MRO hubs. EASA ED-79A compliance requirements sustain procurement relationships with European-qualified cell manufacturers. Bavaria hosts specialized testing laboratories serving Airbus supplier qualification programs.
China
COMAC C919 production ramp and regional airline expansion pull imported battery systems through CAAC GB standards alignment pathways. Domestic certification reciprocity negotiations are reshaping supplier entry strategies. Shanghai and Tianjin aerospace clusters concentrate MRO infrastructure for mixed fleet operators.
France
Airbus final assembly lines at Toulouse and Hamburg-bound component flows sustain long-term supply contracts with European battery manufacturers. DGA France military procurement maintains nickel-cadmium specifications for combat aircraft platforms. Bordeaux region hosts specialized silver-zinc production for defense applications.
United Kingdom
Rolls-Royce electrical system integration programs at Derby drive qualification partnerships for next-generation propulsion architectures. CAA alignment with EASA standards reduces friction for continental supplier participation. Southwest England clusters maintain legacy military platform support infrastructure.
Aircraft Battery Market Key Industry Players
Listed leaders compete with private specialists across qualification-intensive segments, with public companies leveraging capital market access for certification timeline funding while private operators exploit niche military specifications. The supplier base stratifies around chemistry roadmaps and regulatory alignment rather than scale alone. Three archetypes dominate: European-qualified lithium-ion specialists, North American military-grade producers, and emerging solid-state researchers. Consolidation pressure manifests through long-term OEM framework agreements and direct MRO distribution bypassing traditional aerospace parts brokers.
Within the defense-specialist tier, EaglePicher Technologies and MarathonNorco Aerospace exemplify private operators sustaining premium positioning through MIL-PRF-8565J qualification holdings. Saft represents the European-qualified archetype with manufacturing footprint advantages for EASA-compliant programs. These three anchors illustrate how regulatory alignment and chemistry specialization supersede scale in procurement decisions.
| Leading Market Players |
|---|
| GS Yuasa International Ltd. |
| MarathonNorco Aerospace |
| Saft |
| Amprius Technologies |
| Teledyne Technologies |
| EnerSys |
| EaglePicher Technologies |
| Mid-Continent Instrument Co. Inc. |
| Concorde Battery Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Airbus and Saft lock in cobalt-oxide cell supply for A320 family programs while freezing unit pricing visibility across the forecast window. These contracts insulate European OEM line-fit procurement from spot volatility in Central African mining operations.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels. Premium tiers attach to DO-311A-qualified emergency power systems with eighteen-month certification timelines, while ground power units trade at standard tiers with lighter FAA oversight. Price erosion runs through nickel-cadmium replacement contracts as operators accelerate fleet transitions. Regional turboprop operators exhibit highest price sensitivity, whereas military procurement shows lowest elasticity under MIL-PRF-8565J specifications.
Supply Chain Analysis
Container availability constraints on the Shanghai-Rotterdam trade lane compress inbound logistics capacity for cobalt hydroxide feedstocks. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode active material production anchored in Chinese chemical processing hubs. The supply chain rests on single-source vulnerability for aerospace-grade electrolyte solvents. Distribution runs through manufacturer-direct agreements with MRO facilities, bypassing traditional aerospace parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet electrification mandates and solid-state electrolyte maturation are reshaping competitive positioning across chemistry roadmaps. Incumbents and challengers face divergent capability requirements.
For Market Incumbents: Secure EASA ED-79A qualification renewals ahead of 2025 regulatory review cycles to defend against emerging solid-state specialists. Extend backward integration into cobalt refining partnerships to offset Central African supply concentration. Channel control through direct MRO distribution agreements locks out independent parts brokers. For New Entrants and Emerging Players: Lead with CAAC GB standards alignment for COMAC C919 supplier qualification, the most penetrable entry vector for foreign cell manufacturers. Target silver-zinc emergency power retrofits for NATO legacy platforms where incumbents face capacity constraints. Position around ceramic electrolyte prototypes for narrow-body platform integration. For Investors and Strategic Acquirers: Defense-qualified specialists with MIL-PRF-8565J holdings and proprietary silver-zinc formulations represent the most defensible acquisition archetype. Long-term viability hinges on chemistry roadmap credibility across the next decade. Monitor solid-state manufacturing yield rates as the critical inflection signal for displacement timing.| Strategic Initiative | Industry Significance |
|---|---|
| DO-311A Qualification Investment | Eighteen-month certification timelines filter supplier panels to domestic-qualified manufacturers serving Boeing and Airbus. |
| Cobalt Supply Partnership | Long-term offtake agreements with Central African mining operations reduce price volatility exposure for cathode production. |
| Solid-State R&D Scale-Up | Ceramic electrolyte manufacturing yield improvements unlock narrow-body platform integration at Boeing supplier qualification teams. |
| MRO Distribution Bypass | Direct agreements with Memphis and Louisville cargo hub facilities disintermediate traditional aerospace parts brokers. |
| CAAC Local Assembly Partnership | Domestic certification pathways enable foreign supplier entry for COMAC C919 production ramp and regional airline expansion. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FAA certification databases, EASA ED-79A compliance filings, and customs trade records for cobalt hydroxide imports. Primary interviews covered cell engineering directors at tier-one suppliers, MRO procurement managers at Lufthansa Technik and Delta TechOps, and regulatory affairs leads navigating DO-311A testing protocols. Secondary sources included RTCA documentation, MIL-PRF-8565J specification sheets, and COMAC supplier qualification guidelines. Bottom-up cell shipment data triangulates against top-down OEM production forecasts.
Segmentation dimensions modeled span battery chemistry, application criticality, end-user procurement rhythm, and deployment mode across the projection horizon. Chemistry splits capture lithium-ion, nickel-cadmium, silver-zinc, and emerging solid-state architectures. Application stratification separates emergency power certification burdens from ground power commercial terms. CAGRs derive from installed base turnover rates and fleet electrification program commitments. Forecast inputs incorporate Boeing and Airbus delivery schedules, COMAC production targets, and military platform life-extension timelines.
Forecasts assume regulatory continuity in FAA DO-311A, EASA ED-79A, and CAAC GB standards regimes; material policy shifts would require re-modeling qualification timeline assumptions. Solid-state electrolyte manufacturing scalability and cobalt supply chain disruptions represent specific revision triggers. Practitioners should keep alternative scenarios live as thermal runaway containment standards and chemistry roadmaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Circuit Breakers Market
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Space Power System Hardware-in-the-Loop Test Platforms Market
Aircraft Power Systems
Asia-Pacific Aircraft Circuit Breakers Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Aerospace Electrical Inserts Market
Aircraft Power Systems
Aircraft Actuator Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Generators Market
Aircraft Power Systems
Aircraft Hydraulic Seat Actuation Systems Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Aircraft Electric Motor Market
Aircraft Power Systems
Aircraft Propulsion System Market
Aircraft Power Systems
Air Independent Propulsion Systems (AIP) Market