
 Global Airborne Surveillance Market | 2026-2036
Global Airborne Surveillance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airborne Surveillance Market Intelligence
Buyer concentration among defense forces is hardening as sovereign governments consolidate procurement under national security frameworks. Lockheed Martin leverages its integrated command-and-control architectures to anchor multi-year platform contracts. BAE Systems sustains competitive positioning through specialized electronic warfare payloads for manned surveillance fleets.
Airborne surveillance encompasses persistent detection, tracking, and reconnaissance operations conducted from aerial platforms equipped with multi-spectral sensor suites operating across radar, electro-optical, and infrared bands. These systems serve military, law enforcement, and civilian authorities requiring real-time situational awareness over expansive or inaccessible terrain. Fixed-wing UAVs dominate procurement volume due to endurance advantages, while signal intelligence capabilities represent the fastest-expanding sensor category as electronic warfare requirements intensify. Manned aircraft segments retain concentrated margin pools in strategic defense programs where payload flexibility and human-in-the-loop decision-making remain non-negotiable.
FAA regulations govern domestic airspace integration of unmanned surveillance platforms in the United States, while EASA frameworks across European member states mandate certifiable detect-and-avoid systems for beyond-visual-line-of-sight operations. NATO standardization agreements further shape cross-border procurement compatibility for allied defense operators. Stakeholders must monitor evolving certification pathways for autonomous sensor fusion architectures as regulatory divergence between jurisdictions creates fragmented market access conditions.
Market Dynamics
Sovereign defense procurement consolidation is hardening buyer concentration, with national security frameworks mandating domestic supply chains and NATO interoperability standards forcing cross-border system integration at the platform level.
Growth Catalysts
- EU Defense Procurement Directives:Cross-border tender harmonization accelerates multinational fleet modernization programs across allied European air forces.
- Signal Intelligence Payloads:Electronic warfare requirements intensify demand for multi-spectral sensor suites operating across radar, electro-optical, and infrared bands.
- Israeli Sovereign Capability Investment:Persistent wide-area monitoring programs drive indigenous platform development and export-oriented subsystem specialization.
Market Restraints
- Gallium Nitride Supply Concentration:Critical radar component sourcing depends on limited semiconductor foundry capacity concentrated in East Asian manufacturing clusters.
- FAA Beyond-Visual-Line-of-Sight Certification:Detect-and-avoid system mandates create multi-year approval timelines for unmanned platform operators.
- Manned Aircraft Cost Structure:Human-in-the-loop payload flexibility requirements sustain concentrated margin pools that resist cost compression.
Strategic Opportunities
- Indian Border Surveillance Modernization:Himalayan and maritime perimeter monitoring requirements create demand for high-altitude long-endurance unmanned platforms.
- Artificial Intelligence-Sensor Fusion Convergence:Autonomous target recognition algorithms integrated with multi-source data streams enable reduced crew complements.
- UK Integrated Review Refresh:Strategic defense posture realignments prioritize airborne early warning and electronic intelligence collection capabilities.
Industry Challenges
- Airworthiness Certification Timeline:EASA certifiable autonomy standards for civil-military dual-use platforms extend development cycles by 18-36 months.
- Legacy Platform Integration Complexity:NATO STANAG compatibility requirements force expensive retrofit engineering for national proprietary command architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airborne Surveillance Market |
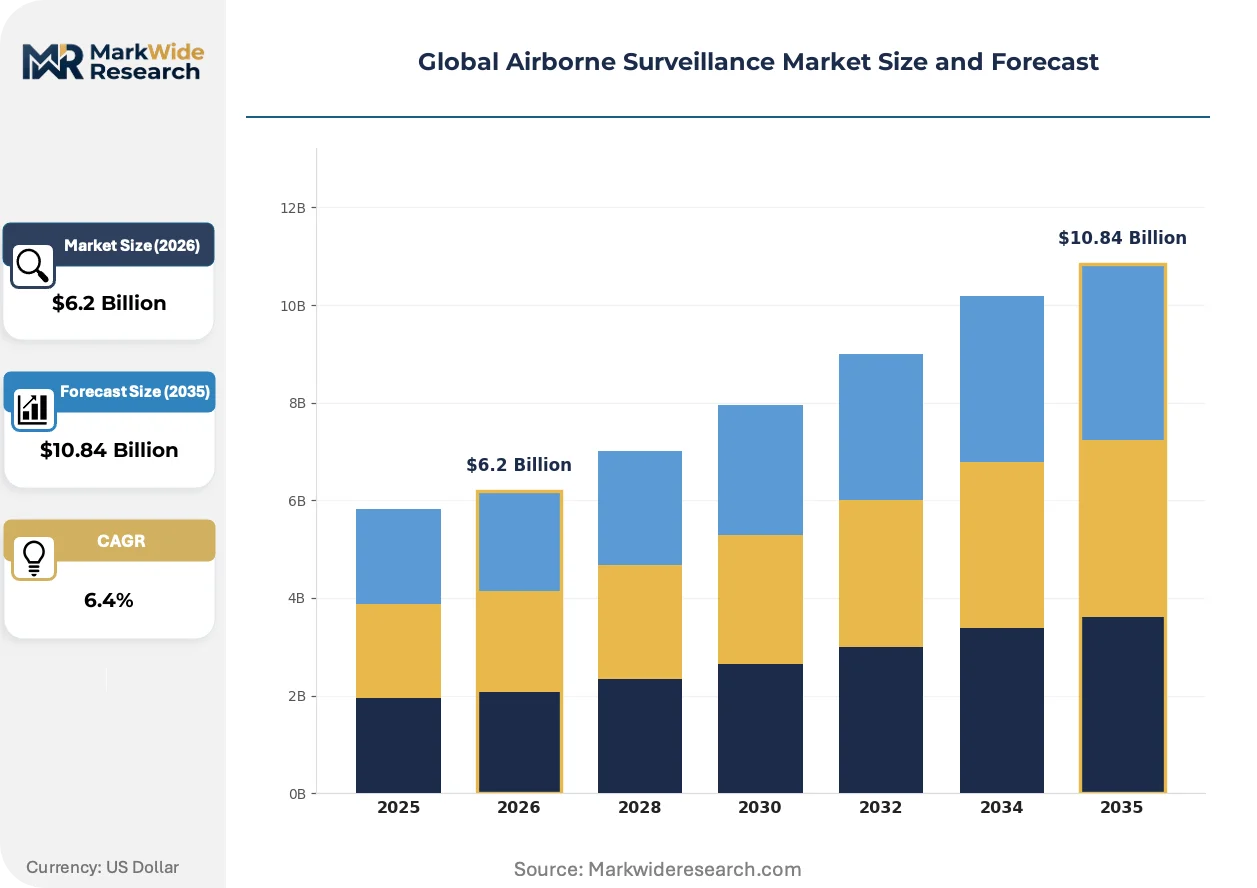
| Market Size in 2026 | $6.2 Billion |
| Market Size in 2035 | $10.84 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Fixed-Wing UAVs, Rotary-Wing UAVs, Manned Aircraft, Balloons, Aerostats Sensor Technology: Radar, Electro-Optical, Infrared, Lidar, Signal Intelligence Application: Border Security, Maritime Surveillance, Disaster Management, Search & Rescue, Infrastructure Monitoring End User: Defense Forces, Law Enforcement Agencies, Disaster Response Teams, Environmental Agencies, Aviation Authorities |
| Companies Covered | Raytheon Technologies, BAE Systems, Lockheed Martin, Leonardo, Saab, Northrop Grumman, Thales Group, Airbus, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airborne Surveillance Market Strategic Shifts & Innovations
Synthetic aperture radar payloads paired with artificial intelligence-driven analytics are compressing the sensor-to-decision timeline, reshaping how defense operators prioritize platform investments.
Solid-state active electronically scanned array radar is overtaking mechanically scanned systems in new procurement awards. Royal Air Force and Israeli Air Force programs now specify fixed-array architectures exclusively. This transition is compressing supplier margins for legacy subsystem manufacturers while elevating semiconductor packaging specialists.
EASA detect-and-avoid mandates for beyond-visual-line-of-sight operations are forcing unmanned platform developers to integrate certified sense-and-avoid architectures before market access. German and French procurement offices now require civil-type certification for military derivative platforms. This regulatory friction advantages established aerospace primes with dedicated certification engineering divisions.
Defense ministries are consolidating multi-year platform contracts under national security frameworks that mandate domestic work-share minimums. British and Australian operators now specify sovereign industrial participation clauses as non-negotiable evaluation criteria. This procurement centralization disadvantages foreign suppliers lacking local joint-venture structures.
Global Airborne Surveillance Market Segmentation
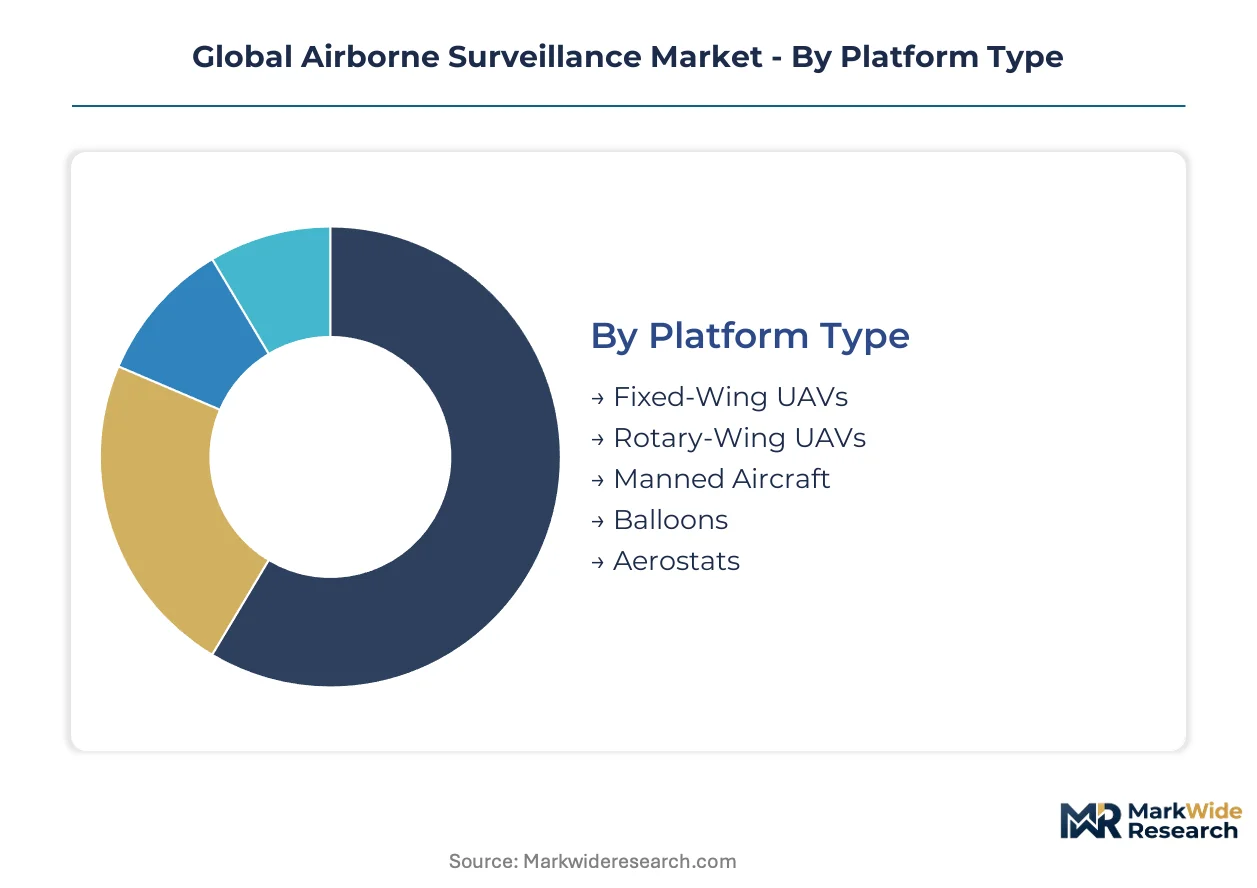
Platform architecture determines operational endurance and payload capacity, while sensor modality selection shapes mission utility across defense and civilian applications. Procurement patterns diverge sharply between sovereign military programs requiring NATO interoperability and civilian operators governed by FAA or EASA certification pathways.
Platform Type:
Integration depth varies from fully autonomous unmanned systems to crewed platforms requiring human-in-the-loop decision architectures for contested airspace operations.
- Fixed-Wing UAVs:High-aspect-ratio airframes with turbine or heavy-fuel propulsion deliver 24-40 hour endurance for persistent wide-area coverage. Demand concentrates in United States border security programs and Israeli perimeter monitoring, driven by sovereign capability investments requiring domestic supply chains.
- Manned Aircraft:Modified business jets and specialized surveillance platforms accommodate flexible payload reconfiguration and real-time analyst teams. United Kingdom Royal Air Force and Australian defense programs specify these for electronic intelligence missions where human judgment remains non-negotiable.
- Rotary-Wing UAVs:Vertical takeoff capability suits shipboard deployment and urban canyon operations without runway dependency.
- Balloons:Stratospheric platforms offer month-long station-keeping for communications relay and wide-area radar.
- Aerostats:Tethered helium systems provide cost-effective persistent coverage for fixed-site border monitoring.
Volume placements concentrate in Fixed-Wing UAVs; the faster expansion belongs to Manned Aircraft as electronic warfare payload requirements intensify.
Sensor Technology:
Cost tiers separate legacy mechanically scanned systems from solid-state active electronically scanned arrays with semiconductor packaging complexity.
- Signal Intelligence:Electronic support measures and communications intelligence suites intercept, geolocate, and classify electromagnetic emissions across radar, radio, and data-link frequencies. Israeli Air Force and German procurement offices prioritize these payloads for contested electromagnetic environments.
- Radar:Synthetic aperture radar and ground-moving target indication enable all-weather, day-night detection through cloud cover and foliage. Royal Air Force programs now specify fixed-array architectures exclusively, displacing mechanically scanned legacy suppliers.
- Electro-Optical:High-definition visible-spectrum cameras with stabilized gimbals provide positive identification at extended standoff ranges.
- Infrared:Cooled and uncooled thermal imagers detect heat signatures for personnel tracking and vehicle identification.
- Lidar:Laser ranging and 3D mapping support terrain characterization and infrastructure assessment.
Procurement volume clusters in Radar; Signal Intelligence climbs fastest as electronic warfare requirements reshape platform specifications.
Application:
Customer type determines mission profile complexity, from scheduled infrastructure inspection to emergency response with compressed deployment timelines.
- Border Security:Persistent linear monitoring of land and maritime boundaries requires multi-sensor fusion for target tracking across radar, electro-optical, and infrared bands. United States Customs and Border Protection and Indian paramilitary forces drive procurement for Himalayan and desert perimeter coverage.
- Maritime Surveillance:Exclusive economic zone patrol, anti-submarine warfare, and search-and-rescue coordination demand maritime radar and automatic identification system integration. United Kingdom and Australian naval aviation programs specify these capabilities for Indo-Pacific operational requirements.
- Disaster Management:Rapid damage assessment and communications relay support coordinated response to natural catastrophes.
- Search & Rescue:Thermal detection and beacon localization accelerate victim recovery in remote terrain.
- Infrastructure Monitoring:Pipeline, power grid, and transportation corridor inspection serves civilian regulatory compliance.
Contract awards concentrate in Border Security; Maritime Surveillance gains share fastest as Indo-Pacific strategic competition intensifies.
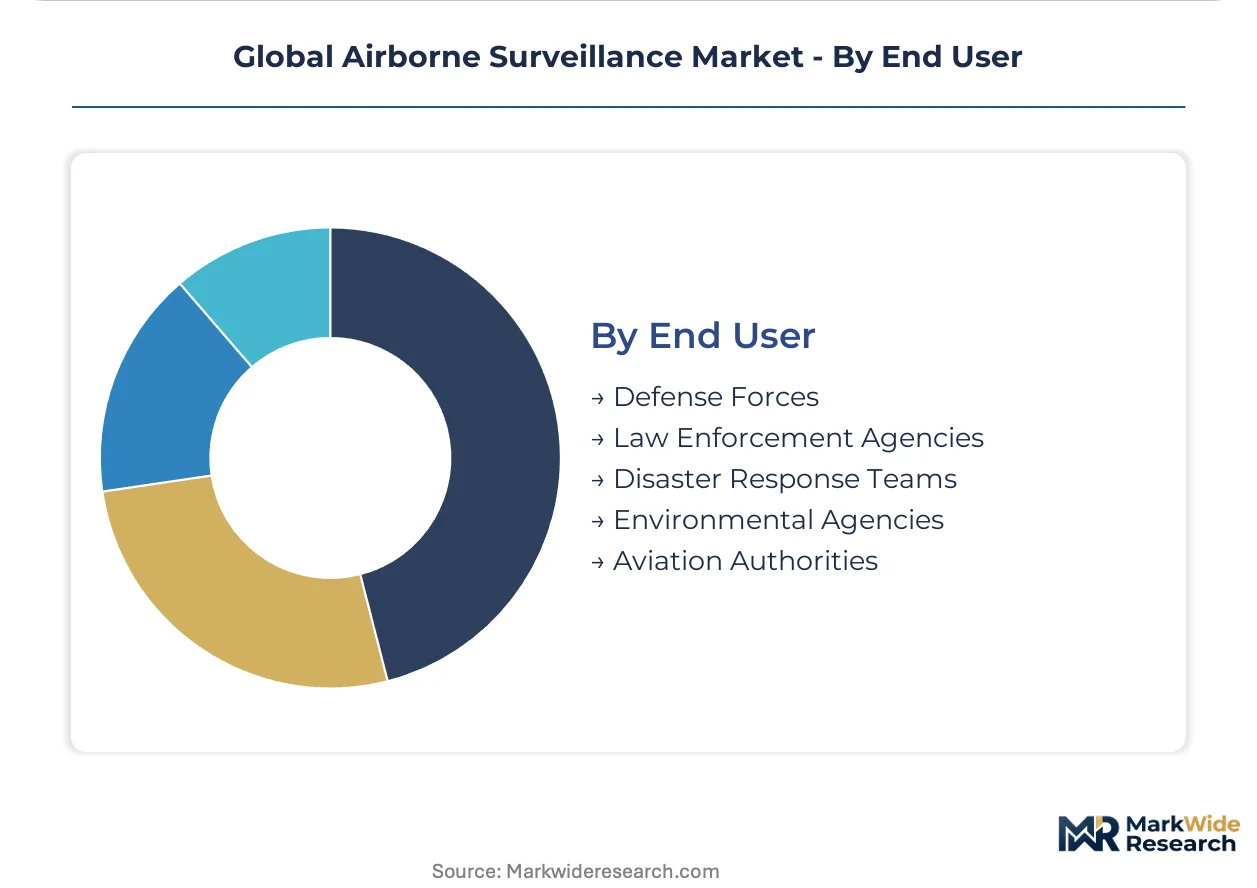
End User:
Maturity gradients separate established defense procurement frameworks from emerging civilian regulatory regimes with evolving certification standards.
- Defense Forces:Military operators specify multi-domain integration with command-and-control architectures and NATO STANAG interoperability. United States, United Kingdom, and Israeli defense ministries consolidate multi-year platform contracts under national security frameworks mandating domestic work-share minimums.
- Law Enforcement Agencies:Police and paramilitary units require civil-type certification for urban operations with detect-and-avoid systems. German and French procurement offices now mandate EASA-compatible architectures for military-derivative platforms.
- Disaster Response Teams:Emergency management authorities prioritize rapid deployment and interoperability with civilian communications networks.
- Environmental Agencies:Conservation and pollution monitoring programs utilize lighter payloads with extended endurance.
- Aviation Authorities:Air navigation service providers employ surveillance for traffic management and airspace security.
Program value aggregates in Defense Forces; Law Enforcement Agencies expand most quickly as civil certification pathways mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium nitride foundry capacity concentrates in East Asian manufacturing clusters, yet sovereign defense procurement drives platform assembly and system integration across distinct national industrial bases.
United States
Border security programs and military fleet modernization sustain demand for high-endurance unmanned platforms. FAA beyond-visual-line-of-sight certification mandates shape procurement timelines for domestic operators. Defense primes cluster around Washington DC metropolitan corridor and California aerospace corridors, anchoring multi-year platform contracts with integrated command-and-control architectures.
United Kingdom
Royal Air Force electronic intelligence missions and airborne early warning capabilities drive manned aircraft specifications. Ministry of Defence procurement frameworks mandate sovereign industrial participation clauses as non-negotiable evaluation criteria. BAE Systems and specialized subsystem suppliers concentrate in Lancashire and Bristol aerospace clusters, executing NATO STANAG-compatible retrofit programs.
Israel
Persistent wide-area monitoring requirements and contested electromagnetic environment operations accelerate indigenous platform development. Israeli Air Force programs prioritize signal intelligence payloads for electronic warfare applications. Defense technology firms cluster in Tel Aviv metropolitan area and Haifa Bay industrial zone, specializing in export-oriented subsystem integration for allied operators.
Germany
Federal procurement offices mandate EASA-compatible detect-and-avoid architectures for military-derivative unmanned platforms. Luftwaffe modernization programs specify fixed-array radar architectures displacing mechanically scanned legacy systems. Aerospace engineering capabilities concentrate in Bavaria and Hamburg metropolitan regions, where certification engineering divisions manage extended airworthiness timelines.
India
Himalayan border surveillance and maritime perimeter monitoring requirements create demand for high-altitude long-endurance unmanned platforms. Paramilitary forces drive procurement for desert and mountain terrain coverage applications. Defense public sector undertakings and private platform developers cluster in Bangalore and Hyderabad technology corridors, integrating multi-sensor fusion architectures for indigenous programs.
Global Airborne Surveillance Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized payload integration and sovereign supply chain carve-outs. Market structure reflects consolidated prime contractor dominance alongside tiered supplier networks for semiconductor packaging and sensor subsystem fabrication. Three archetypes prevail: integrated platform-system houses, specialized electronic warfare payload developers, and certifiable autonomy engineering specialists. Competitive dynamics center on multi-year national security framework contracts and cross-border joint-venture structures for local work-share compliance.
Within the integrated platform-system tier, Lockheed Martin and Northrop Grumman represent archetypal prime contractors anchoring sovereign defense procurement, while BAE Systems exemplifies specialized electronic warfare payload positioning for manned surveillance fleets. Thales Group and Leonardo occupy intermediate positions spanning platform integration and sensor subsystem supply, reflecting European defense industrial consolidation patterns. These five entities collectively illustrate competitive positioning across NATO interoperability mandates and national security framework requirements.
| Leading Market Players |
|---|
| Raytheon Technologies |
| BAE Systems |
| Lockheed Martin |
| Leonardo |
| Saab |
| Northrop Grumman |
| Thales Group |
| Airbus |
| Boeing |
| Others |
Cost & Logistics Intelligence
Gallium nitride wafer pricing indices cascade through airborne surveillance supply chains, compressing margins for legacy mechanically scanned radar suppliers while elevating semiconductor packaging specialists commanding fixed-array architecture premiums.
Pricing Analysis
Extended warranty and field service bundling separate premium platform contracts from unbundled subsystem procurement. Three-tier pricing structure across NATO-interoperable, sovereign-certified, and export-restricted levels reflects certification grade and domestic work-share minimums. Pricing pressure stems from EASA detect-and-avoid certification mandates extending development timelines. Defense forces show lowest price sensitivity; civilian law enforcement agencies exhibit highest.
Supply Chain Analysis
Refurbishment flows for active electronically scanned array radar modules create secondary supply streams for legacy platform retrofits. Gallium nitride foundry capacity concentrates in Taiwan, South Korea, and Japan; synthetic aperture radar subsystems draw from Israeli and United Kingdom sensor specialists. Single-source vulnerability in East Asian semiconductor packaging feeds tariff exposure through defense procurement frameworks. Distribution runs through national security framework contracts mandating domestic integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
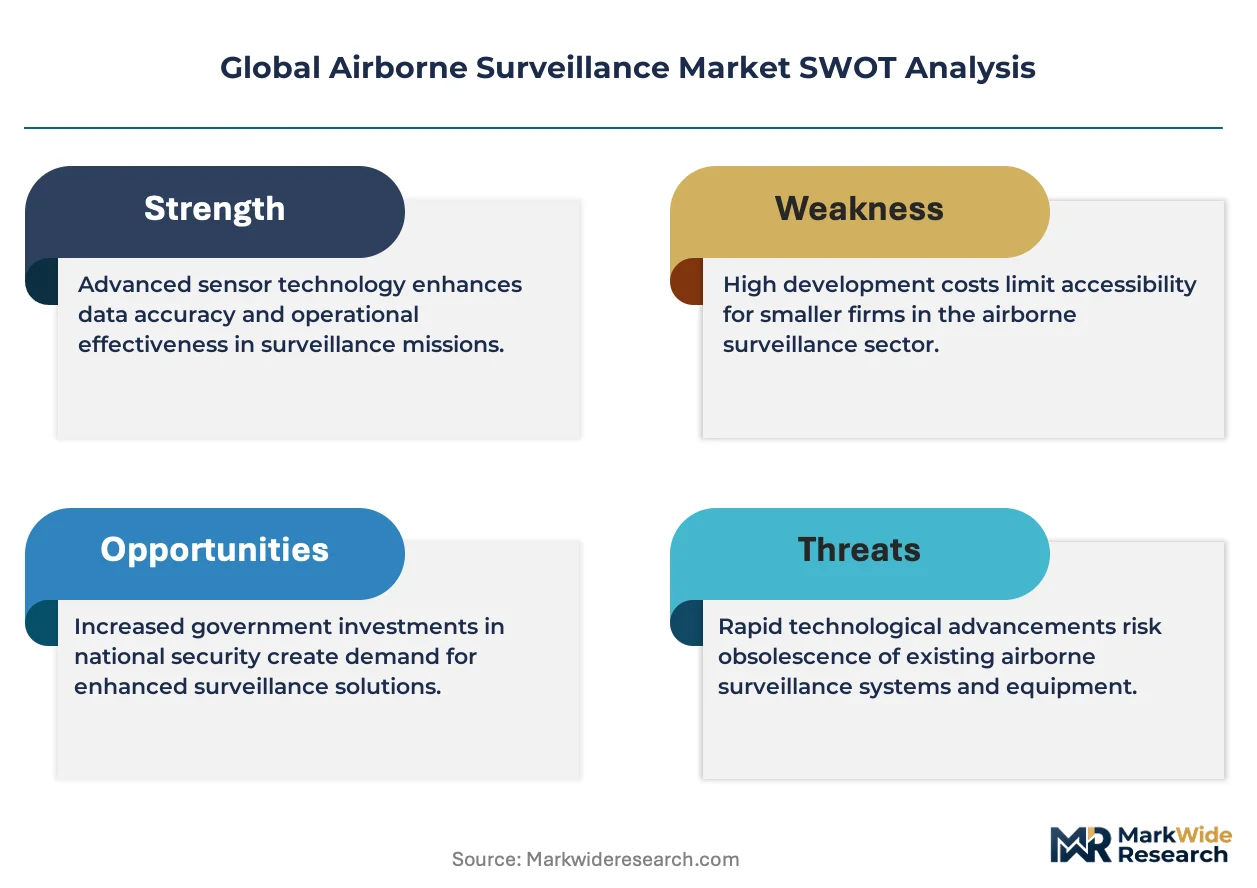
Sovereign defense procurement consolidation functions as a consolidation play, with national security frameworks mandating domestic supply chains that marginalize foreign competitors lacking local joint-venture structures.
For Market Incumbents: Deepen backward integration into gallium nitride semiconductor packaging to secure radar subsystem supply against East Asian foundry concentration. Anchor multi-year platform contracts through integrated command-and-control architectures that embed switching costs. Lockheed Martin's positioning exemplifies this defensive lever against emerging autonomy engineering specialists.
For New Entrants and Emerging Players: The mid-tier price gap between BAE Systems electronic warfare payloads and uncrewed platform economy tiers offers white-space entry. Target Indian border surveillance modernization with high-altitude long-endurance platforms integrating indigenous sensor fusion. Pursue civil-type certification partnerships with German and French procurement offices as the go-to-market angle.
For Investors and Strategic Acquirers: Distressed-cycle entries favor certifiable autonomy engineering specialists in Germany and the United Kingdom facing extended EASA airworthiness timelines. Long-term viability hinges on five-to-ten year regulatory pathway resolution. Monitor FAA beyond-visual-line-of-sight certification acceleration as the inflection signal for unmanned platform valuation recovery.
| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Backward Integration | Captive wafer supply secures radar subsystem margins against East Asian foundry bottlenecks. |
| EASA Certification Engineering Division | Dedicated autonomy teams compress detect-and-avoid approval timelines for German operators. |
| Indian Joint-Vehicle Structure | Domestic work-share compliance unlocks Himalayan border surveillance procurement awards. |
| NATO STANAG Retrofit Program | Legacy platform integration commands premium engineering fees from United Kingdom operators. |
| Signal Intelligence Payload Specialization | Electronic warfare focus captures Israeli Air Force and German Luftwaffe modernization budgets. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with platform program managers, radar subsystem engineers, certification specialists at EASA and FAA, defense procurement officers, and semiconductor packaging directors combined with NATO standardization agreement databases, SEC 10-K aerospace disclosures, and national defense budget appropriations documents. Bottom-up platform deployment estimates triangulated against top-down sovereign spending projections.
Granularity extended to individual sensor modality, platform endurance tier, and national procurement framework across the analysis window. Segmentation dimensions encompassed fixed-wing versus manned architecture, signal intelligence versus radar payload priority, border security versus maritime application, and defense force versus law enforcement end user. CAGRs derived from polynomial trend fitting against historical fleet replacement cycles, with gallium nitride foundry capacity expansion and FAA certification pathway evolution as industry-specific forecast inputs.
Inputs from defense ministry budget documents and trade customs records were available through the study window; gaps in proprietary subsystem pricing introduce uncertainty bands around margin estimates. Forecasts reflect documented assumptions regarding NATO interoperability timeline adherence and EASA detect-and-avoid standard finalization. Practitioners should monitor gallium nitride foundry utilization rates and FAA certification backlog clearance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Maritime Surveillance and Intervention Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
North America Hydrographic Survey Equipment Market