
 Aircraft Hydraulic System Market | 2026-2036
Aircraft Hydraulic System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Hydraulic System Market Analysis
North American aerospace suppliers is expanding production capacity for next-generation narrowbody programs. Parker Hannifin Corporation leverages integrated flight control packages to sustain long-term OEM relationships. Eaton Corporation anchors its position through advanced electro-hydraulic architectures for landing gear applications. Moog Inc. specializes in high-reliability actuation systems that dominate military rotorcraft niches.
Aircraft hydraulic systems transmit power through pressurized fluid—typically phosphate ester-based hydraulic fluid operating at pressures up to 5,000 psi—to actuate flight surfaces, landing gear, and braking mechanisms with precise mechanical advantage. These systems remain indispensable where electrical alternatives cannot yet match power density requirements for primary flight controls. Hydraulic pumps and actuators command the largest value share within product categories, reflecting their critical path role in every flight phase. Fail-safe systems technology is gaining fastest traction as OEMs redesign architectures around degraded-mode operational requirements.
FAA Part 25 airworthiness standards and EASA CS-25 certification frameworks mandate redundant hydraulic channels for transport category aircraft, directly shaping component count and system architecture decisions. EPA regulations on phosphate ester fluid handling and disposal add compliance layers to aftermarket service economics. Stakeholders must monitor the pace of electro-hydrostatic actuator substitution in flight control domains, as this technology trajectory will reshape supplier relevance and aftermarket revenue pools.
Market Dynamics
Electro-hydrostatic actuation is electrifying primary flight control architectures, forcing hydraulic suppliers to defend their remaining strongholds in landing gear and braking systems where power density requirements still favor fluid power.
Growth Catalysts
- Commercial Fleet Renewal:Narrowbody production ramps at Boeing and Airbus facilities in Washington State and Toulouse are pulling hydraulic component orders from tier-one suppliers. OEMs require redundant hydraulic channels for each new airframe.
- FAA Part 25 Mandates:Airworthiness standards for transport category aircraft mandate triple-redundant hydraulic systems, directly increasing actuator and pump counts per platform. This regulatory floor creates baseline demand regardless of fuel price cycles.
- Phosphate Ester Formulation Advances:Next-generation fire-resistant hydraulic fluids extend service intervals, reducing airline operating costs and sustaining aftermarket attachment rates for fluid suppliers.
Market Restraints
- Raw Material Concentration:Specialty steel forgings for high-pressure hydraulic manifolds concentrate in Japanese and German mill networks, exposing suppliers to alloy price volatility and geopolitical sourcing risk.
- Electromechanical Substitution:Electro-hydrostatic actuators are displacing conventional hydraulic circuits in spoiler and aileron controls, compressing addressable market for traditional pump and valve manufacturers.
- EPA Fluid Handling Rules:Phosphate ester disposal regulations add compliance costs to MRO operations, eroding service margins and pushing smaller independent shops toward consolidation.
Strategic Opportunities
- Indian MRO Expansion:Maintenance clusters in Hyderabad and Bengaluru are upgrading capabilities to handle widebody hydraulic overhauls, creating captive demand for component suppliers establishing local technical support.
- More Electric Aircraft Convergence:Integration of electro-hydraulic power packs with distributed electric architectures opens design contracts for suppliers bridging both technology domains.
- Defense Procurement Tailwinds:Pentagon modernization programs for rotorcraft and tactical airlifters specify upgraded hydraulic reliability standards, generating sole-source opportunities for qualified military suppliers.
Industry Challenges
- Specialized Welding Talent Scarcity:Precision TIG welding of titanium hydraulic lines requires certification levels that exceed current vocational pipeline output, constraining production scaling.
- EASA CS-25 Certification Timelines:European validation cycles for new hydraulic component designs now average 18-24 months, delaying revenue recognition for development programs.
- Legacy System Integration Complexity:Retrofit of fail-safe hydraulic architectures into existing platforms demands custom manifold designs that fragment engineering resources and compress project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Hydraulic System Market |
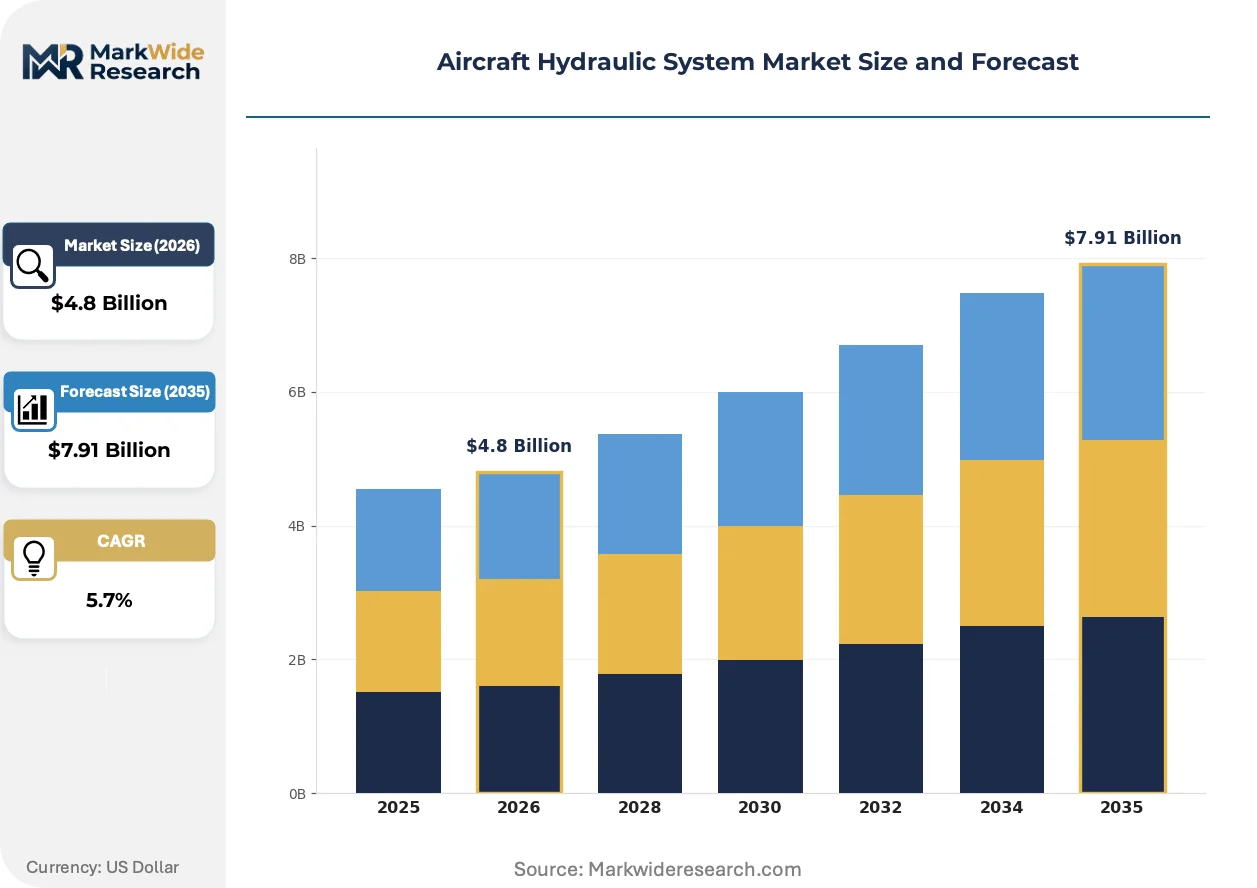
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Actuators, Valves, Reservoirs End User: Aerospace Manufacturers, Airlines, Maintenance Facilities, Government Agencies Application: Landing Gear, Flight Control, Brake Systems, Engine Controls Technology: Electro-Hydraulic, Open-Center, Closed-Center, Fail-Safe Systems |
| Companies Covered | Eaton Corporation, Moog Inc., Parker Hannifin Corporation, Triumph Group Inc., Woodward Inc., Raytheon Technologies Corporation, Liebherr-International AG, Honeywell International Inc., Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Hydraulic System Market Emerging Trajectories
Fluid power architectures face simultaneous pressure from electrification mandates and reliability requirements, pushing suppliers toward hybrid electro-hydraulic designs that preserve mechanical advantage while reducing parasitic losses.
Electro-hydrostatic actuation is electrifying flight control surface actuation, replacing centralized hydraulic distribution with self-contained electrical motor-pump units at each control point. Boeing 787 and Airbus A350 programs have adopted this approach for secondary surfaces, and narrowbody follow-ons are expanding adoption. This shift is compressing demand for traditional engine-driven pumps and complex hydraulic plumbing runs.
REACH SVHC restrictions on chromium(VI) compounds are forcing coating suppliers to reformulate hydraulic component surface treatments. Hard chrome alternatives including HVOF tungsten carbide and electroless nickel composites now dominate new qualification programs. European suppliers and their export customers must certify these coatings meet salt-spray and wear specifications previously satisfied by hexavalent chrome.
Power-by-the-hour contracts are consolidating hydraulic component procurement decisions into airframe OEM and tier-one system integrator channels. Airlines increasingly bundle hydraulic maintenance into fleet-wide service agreements, displacing independent component sourcing. This channel compression is most visible in North American and Western European carrier fleets, where major lessors now mandate integrated supplier accountability for hydraulic system availability.
Aircraft Hydraulic System Market Segmentation
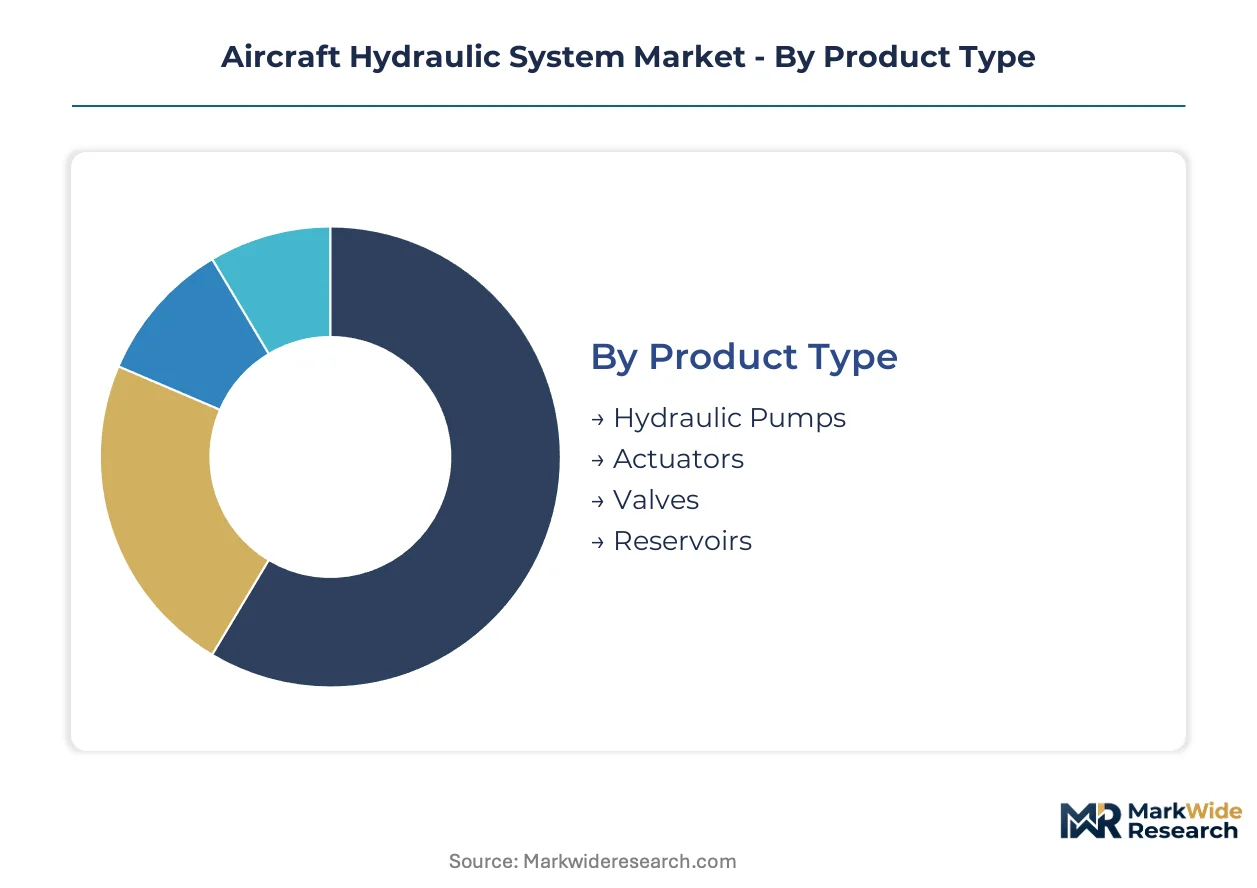
Aircraft hydraulic system segmentation reveals distinct procurement patterns across product architectures and operational domains. Each category carries unique certification burdens and supplier concentration dynamics that reshape competitive positioning.
Product Type:
Standalone hydraulic components dominate aftermarket procurement, while embedded integrated systems anchor OEM production contracts.
- Hydraulic Pumps:Engine-driven and electric-motor pumps generate primary power for 5,000 psi distribution networks. Boeing 737 MAX and Airbus A320neo production lines in Washington State and Toulouse pull multi-channel pump orders from tier-one suppliers. FAA Part 25 triple-redundancy mandates ensure three independent pumps per transport airframe.
- Actuators:Linear and rotary actuators convert fluid pressure into mechanical force for flight surface movement. Landing gear extension and retraction systems in commercial narrowbodies concentrate demand for high-load hydraulic actuators with integrated position feedback.
- Valves:Directional and pressure-control valves regulate flow distribution across hydraulic circuits. Military rotorcraft programs specify fail-safe valve architectures with manual override capabilities for degraded-flight modes.
- Reservoirs:Pressurized fluid storage units incorporate thermal management and air separation functions. Widebody platforms require larger reservoir volumes to accommodate extended hydraulic lines to outboard flight surfaces.
Volume placements concentrate in Hydraulic Pumps; the faster expansion belongs to Fail-Safe Systems technology integration across actuator and valve categories.
End User:
Cost tier stratification separates capital-intensive OEM procurement from price-sensitive aftermarket maintenance.
- Aerospace Manufacturers:Boeing, Airbus, and Embraer facilities specify integrated hydraulic packages with 25-year service life guarantees. Original equipment procurement emphasizes traceable alloy sourcing and EASA CS-25 certification documentation.
- Airlines:Delta, United, and Lufthansa procurement teams negotiate power-by-the-hour contracts that bundle hydraulic component availability into fleet-wide service agreements. Unit-level component sourcing is declining as integrated supplier accountability expands.
- Maintenance Facilities:Independent MRO shops in Oklahoma and Texas face margin compression from EPA phosphate ester handling regulations. Consolidation is accelerating as smaller operators cannot absorb compliance infrastructure costs.
- Government Agencies:Pentagon rotorcraft modernization programs specify upgraded reliability standards for tactical airlifter hydraulic systems. Sole-source qualification requirements limit supplier pools to established military contractors.
Procurement volumes cluster with Aerospace Manufacturers; the steepest expansion trajectory is emerging among consolidated Maintenance Facilities capturing airline outsourcing contracts.
Application:
Power density requirements determine where hydraulic architectures defend against electromechanical substitution.
- Landing Gear:High-force retraction and extension mechanisms remain hydraulic-dependent due to weight and packaging constraints. Boeing 787 and Airbus A350 programs specify integrated landing gear hydraulic power packs with electro-hydraulic backup.
- Flight Control:Primary surfaces on transport aircraft retain centralized hydraulic distribution, though spoilers and ailerons on newer platforms adopt electro-hydrostatic actuation. FAA Part 25 mandates redundant channels regardless of technology mix.
- Brake Systems:Anti-skid and autobrake functions rely on hydraulic pressure modulation with steel-carbon brake stack interfaces. Aftermarket brake system overhaul demand concentrates in Atlanta and Phoenix MRO clusters.
- Engine Controls:Thrust reverser actuation and variable geometry systems use dedicated hydraulic circuits isolated from flight control networks. GE and Pratt & Whitney engine programs specify custom manifold designs.
Deployment volumes concentrate in Landing Gear; the fastest technology shift is occurring in Flight Control as electro-hydrostatic architectures gain certification traction.
Technology:
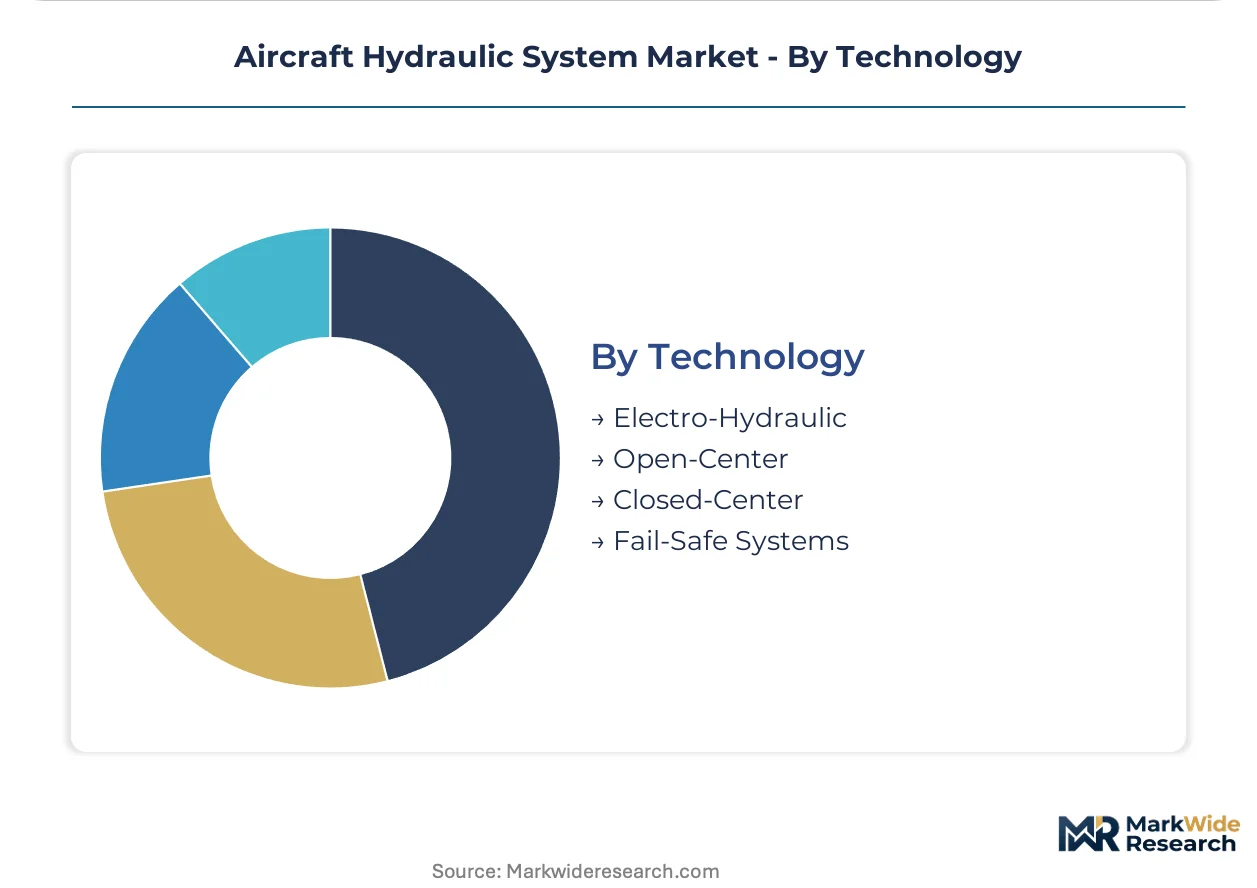
Maturity gradients separate legacy open-center architectures from emerging fail-safe designs required for next-generation airframes.
- Electro-Hydraulic:Integrated motor-pump units enable distributed power generation without centralized engine-driven pumps. Boeing 787 secondary flight surfaces and A350 follow-on programs specify self-contained electro-hydraulic actuators.
- Open-Center:Traditional constant-flow systems with unloading valves persist in regional turboprops and legacy narrowbody retrofits. Lower acquisition cost sustains demand in price-sensitive operator segments.
- Closed-Center:Pressure-compensated pump systems reduce parasitic losses by matching output to instantaneous demand. Fuel efficiency gains are driving adoption in new-generation single-aisle programs.
- Fail-Safe Systems:Degraded-mode architectures maintain limited functionality after primary hydraulic loss. EASA CS-25 and FAA Part 25 updates are mandating these capabilities for transport category certification.
Installation volumes concentrate in Open-Center legacy fleets; the steepest adoption curve belongs to Fail-Safe Systems as regulatory mandates tighten across certification jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty steel forgings for high-pressure hydraulic manifolds concentrate in Japanese and German mill networks, anchoring procurement geography for tier-one aerospace suppliers. Boeing and Airbus production lines pull component orders through distinct regional channel structures.
United States
Narrowbody production ramps at Boeing facilities in Washington State drive hydraulic pump and actuator procurement volumes. FAA Part 25 airworthiness standards mandate triple-redundant hydraulic systems for every transport airframe certified. MRO clusters in Oklahoma and Texas handle legacy fleet overhauls while absorbing EPA phosphate ester handling compliance costs.
France
Airbus assembly lines in Toulouse anchor European demand for integrated hydraulic packages with EASA CS-25 certification documentation. REACH SVHC restrictions on chromium(VI) compounds force coating suppliers to reformulate surface treatments for hydraulic components. The Occitanie aerospace cluster hosts specialized valve manufacturers serving both commercial and military rotorcraft programs.
Germany
Precision forging networks in North Rhine-Westphalia supply high-pressure hydraulic manifolds to global tier-one integrators. EASA CS-25 validation cycles for new hydraulic component designs now average 18-24 months, delaying revenue recognition. Bavaria-based system integrators specialize in fail-safe architectures for next-generation narrowbody programs.
Japan
Specialty alloy mills in the Chubu region dominate titanium hydraulic line feedstock for commercial and defense applications. METI industrial standards govern precision TIG welding certification levels that exceed current vocational pipeline output. Nagoya-area suppliers concentrate on engine control hydraulic circuits for GE and Pratt & Whitney programs.
India
Maintenance clusters in Hyderabad and Bengaluru upgrade capabilities to handle widebody hydraulic overhauls, creating captive demand for component suppliers. BIS certification requirements for imported aerospace components add regulatory layers to local procurement decisions. Delhi-NCR-based distributors are establishing technical support infrastructure to serve expanding airline MRO outsourcing contracts.
Aircraft Hydraulic System Market Vendor Landscape
Global majors compete with regional champions across certification jurisdiction boundaries, with EASA-qualified European suppliers and FAA-certified American fabricators occupying distinct procurement channels. The vendor base stratifies into three tiers: integrated system houses delivering complete hydraulic packages, component specialists dominating narrow product categories, and regional MRO service providers capturing aftermarket overhaul contracts. Dominant competitive moves include strategic partnerships bridging electro-hydraulic and electromechanical technology domains, plus capacity expansion into Indian and Southeast Asian maintenance clusters.
Among diversified industrial conglomerates, Eaton Corporation and Parker Hannifin Corporation exemplify the integrated system house archetype, anchoring long-term OEM relationships through bundled flight control and landing gear packages. Moog Inc. occupies a position within the high-reliability actuation specialist tier, with its military rotorcraft focus representing a defensible niche against commercial-market commoditization pressures. These three American corporations illustrate how geographic proximity to Boeing production lines reinforces competitive positioning in narrowbody procurement decisions.
| Leading Market Players |
|---|
| Eaton Corporation |
| Moog Inc. |
| Parker Hannifin Corporation |
| Triumph Group Inc. |
| Woodward Inc. |
| Raytheon Technologies Corporation |
| Liebherr-International AG |
| Honeywell International Inc. |
| Safran S.A. |
| Others |
Supply Flow & Price Mechanics
FAA Part 25 triple-redundancy mandates for transport category aircraft are forcing hydraulic component suppliers to absorb certification documentation costs that OEMs refuse to shoulder, compressing margins on standard catalog items while creating pricing power for integrated system houses that bundle design liability with hardware.
Pricing Analysis
Power-by-the-hour contract bundling now dominates commercial aviation procurement, with hydraulic component availability folded into fleet-wide service agreements rather than priced as discrete transactions. Three-tier pricing structure across premium, standard, and economy levels separates EASA CS-25 certified components from FAA-only qualified alternatives and uncertified aftermarket substitutes. Pricing pressure stems from airline procurement consolidation around mega-carrier and lessor accounts with standardized fleet specifications. Independent MRO shops exhibit highest price sensitivity due to EPA phosphate ester handling compliance cost absorption.
Supply Chain Analysis
Specialty titanium alloy feedstock for high-pressure hydraulic lines rests on Japanese mills in the Chubu region and German precision forging networks in North Rhine-Westphalia. Critical inputs include phosphate ester hydraulic fluids, high-strength steel forgings for manifolds, and REACH-compliant HVOF tungsten carbide coatings replacing hexavalent chrome. Single-source vulnerability concentrates in specialty alloy supply, where geopolitical disruption to Japanese or German mill output would cascade through tier-one integrator production schedules. Distribution runs through Boeing and Airbus tier-one system integrators with captive technical support infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EPA phosphate ester handling regulations is eliminating smaller independent MRO shops, concentrating aftermarket revenue among scaled operators with compliance infrastructure.
For Market Incumbents: Deploy backward integration into specialty alloy supply to secure titanium hydraulic line feedstock against Japanese mill network disruption. Capture Indian MRO expansion through technical support infrastructure in Hyderabad and Bengaluru before local competitors achieve BIS certification. Electro-hydrostatic actuator substitution in flight control domains threatens traditional pump manufacturers; defend landing gear and braking system strongholds where power density requirements still favor fluid power architectures. For New Entrants and Emerging Players: Enter via Indian MRO technical support contracts, where airline outsourcing is consolidating hydraulic overhaul demand among facilities upgrading to widebody capabilities. Target fail-safe system architecture qualification for next-generation narrowbody programs, where EASA CS-25 and FAA Part 25 mandates are tightening degraded-mode operational requirements. Pursue sole-source military rotorcraft opportunities through Pentagon modernization specifications that limit supplier pools to established contractors with upgraded reliability credentials. For Investors and Strategic Acquirers: The window for entry favors scaled MRO operators with EPA phosphate ester handling compliance infrastructure and established airline power-by-the-hour relationships. Acquisition candidates include regional hydraulic component distributors with captive relationships to Boeing or Airbus tier-one integrators. Monitor electro-hydrostatic actuator certification traction in spoiler and aileron applications as inflection indicator for traditional hydraulic circuit demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Secures titanium feedstock from Japanese Chubu region mills against geopolitical sourcing risk. |
| Indian MRO Technical Support Infrastructure | Captures widebody hydraulic overhaul demand from Hyderabad and Bengaluru airline outsourcing clusters. |
| Fail-Safe System Architecture Qualification | Addresses EASA CS-25 degraded-mode mandates for next-generation narrowbody certification. |
| Electro-Hydraulic Power Pack Integration | Bridges fluid power and distributed electric architectures for Boeing 787 and A350 follow-on programs. |
| REACH-Compliant Coating Reformulation | Replaces hexavalent chrome with HVOF tungsten carbide for European supplier export qualification. |
Methodological Framework
Independent corroboration across hydraulic system engineering directors, airline fleet procurement managers, MRO facility operations heads, and tier-one integrator supply chain leads underwrites the qualitative findings. Secondary validation draws from FAA airworthiness directive filings, EASA CS-25 certification documentation, EPA phosphate ester handling regulation records, and customs trade data for specialty alloy imports. Bottom-up component demand modeling and top-down fleet expansion projections triangulate volume estimates across product categories.
Comparable-period anchoring to historical narrowbody production rates at Boeing Washington State and Airbus Toulouse facilities establishes baseline demand coefficients across the projection horizon. Segmentation dimensions span product architecture, end-user procurement tier, application power density requirements, and technology maturity gradient. CAGRs derive from installed base expansion, replacement cycle timing, and regulatory-mandated component count increases. Industry-specific inputs include fleet retirement schedules, MRO outsourcing contract structures, and electro-hydrostatic actuator substitution trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under supply disruption to Japanese or German specialty alloy mills and accelerated electro-mechanical substitution in flight control domains. Forecasts reflect assumptions regarding regulatory mandate implementation timing and airline fleet renewal commitment durability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Power Systems
Aerospace Battery Technology Market
Aircraft Power Systems
Military Aircraft Actuation System Market
Aircraft Power Systems
Global Aircraft Electrification Market
Aircraft Power Systems
Low-Carbon Propulsion Market
Aircraft Power Systems
Liquid Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Fly-By-Wire System Market
Aircraft Power Systems
Aircraft Turbocharger Market
Aircraft Power Systems
Hydrogen-Powered Aircraft Market
Aircraft Power Systems
Aircraft Thrust Reverser Market
Aircraft Power Systems
Aircraft Electrical Systems Market
Aircraft Power Systems
Americas Aircraft Lighting Market
Aircraft Power Systems
Aircraft Hydraulic Actuators Market
Aircraft Power Systems
Commercial Aircraft Actuation System Market
Aircraft Power Systems
Aircraft Propeller System Market
Aircraft Power Systems
Aircraft Electrical Power Distribution Systems Market
Aircraft Power Systems
Aircraft Circuit Breakers Market